
 North America SGLT2 Inhibitors Market | 2026-2036
North America SGLT2 Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
North America SGLT2 Inhibitors Market Insights
The North America SGLT2 inhibitors market is rebalancing between premium branded formulations and commodity-priced generic alternatives as patent cliffs reshape prescribing economics. AstraZeneca leverages its cardiovascular outcomes data to sustain formulary positioning in integrated health networks. Boehringer Ingelheim International GmbH anchors its presence through deep endocrinology channel relationships and continued investment in combination therapy development. Johnson & Johnson Services, Inc. differentiates through its established primary care infrastructure and payer contracting scale.
SGLT2 inhibitors constitute a class of oral antihyperglycemic agents that selectively block sodium-glucose cotransporter 2 in renal proximal tubules to reduce blood glucose through urinary glucose excretion, with molecular specificity varying across canagliflozin, dapagliflozin, empagliflozin, and ertugliflozin scaffolds. Empagliflozin and dapagliflozin now command the largest revenue pools as label expansions into heart failure and chronic kidney disease indications have outpaced traditional diabetes-only prescribing. Oral tablets dominate delivery mode volumes, though combination therapy formats are capturing disproportionate attention from payers seeking to simplify multi-drug regimens for comorbid patients.
FDA cardiovascular and renal outcome trial requirements, alongside Health Canada bioequivalence standards for generic entrants, structure product differentiation and market access timelines across the region. The IRA Medicare price negotiation provisions are reshaping revenue forecasting for manufacturers with substantial Part D exposure. Stakeholders must monitor how indication-based pricing and outcomes-based contracts evolve as cardiology and nephrology prescribing displace traditional endocrinology-centric demand patterns.
Market Dynamics
The North America SGLT2 inhibitors market is restructuring around indication-based reimbursement as cardiology and nephrology prescribing displace traditional diabetes-centric demand patterns. FDA label expansions for heart failure and chronic kidney disease are rewiring prescriber eligibility and payer coverage criteria across integrated delivery networks.
Growth Catalysts
- IRA Medicare Price Negotiation:The Inflation Reduction Act's drug pricing provisions are accelerating manufacturer investment in outcomes-based contracts to preserve formulary access ahead of 2026 implementation timelines.
- Cardiology Department Expansion:Hospital systems are building dedicated heart failure protocols that embed SGLT2 inhibitors as first-line therapy, creating new prescriber cohorts beyond endocrinology.
- Chronic Kidney Disease Labeling:FDA approvals for renal indication expansions are unlocking nephrology channel access and broadening patient eligibility criteria across Medicare Part D plans.
Market Restraints
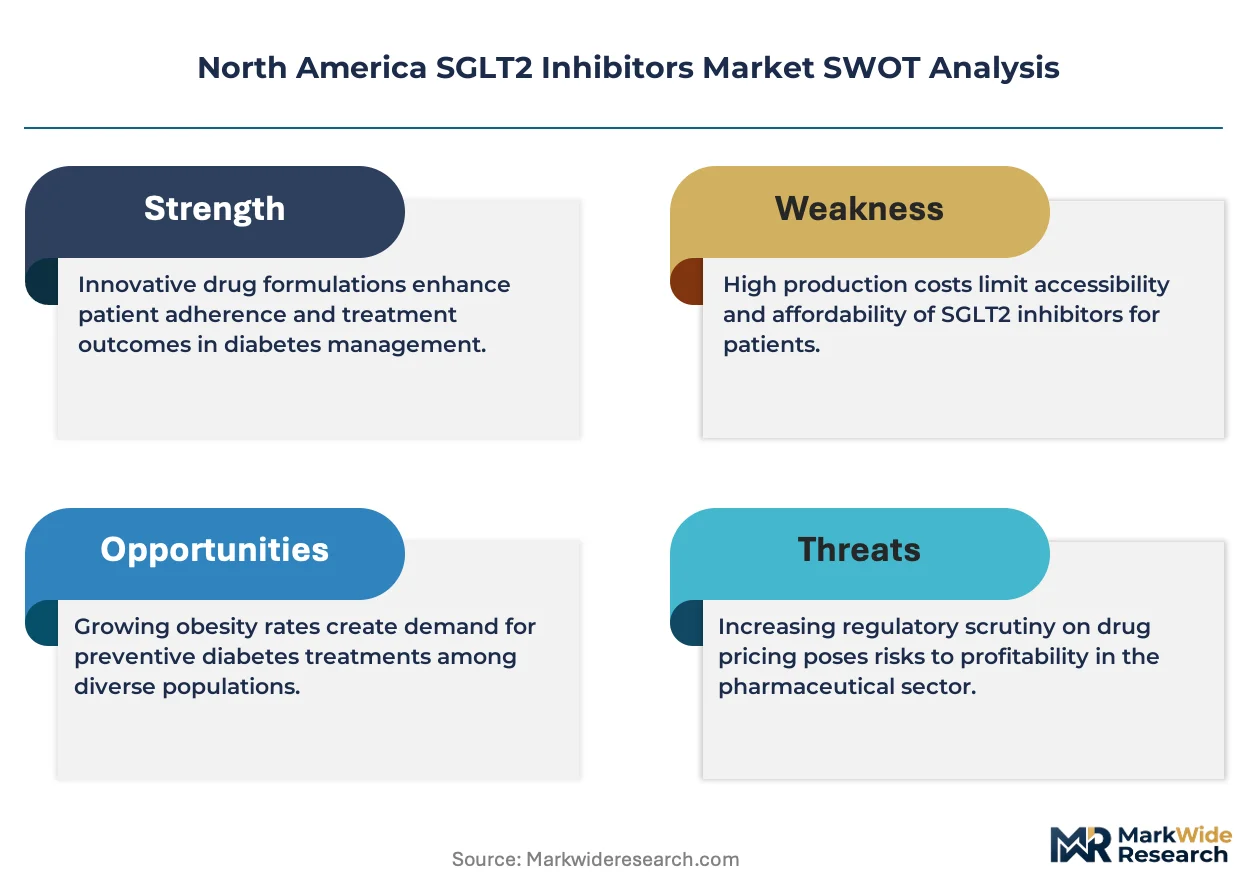
- Generic Erosion Pressure:Patent cliffs for canagliflozin and empagliflozin are compressing branded pricing power as Health Canada and FDA bioequivalence pathways accelerate commodity substitution.
- Reimbursement Concentration Risk:Medicare Part D and Medicaid programs account for disproportionate volume exposure, creating payer concentration vulnerability for manufacturers.
- Fixed-Dose Combination Limits:Technical constraints on triple-therapy formulation stability are restricting product development pipelines and limiting differentiation opportunities.
Strategic Opportunities
- Integrated Delivery Network Penetration:United States health systems with captive specialty pharmacy operations present concentrated contracting opportunities for outcomes-based agreements.
- Dual SGLT1/SGLT2 Inhibition:Next-generation molecular platforms targeting both transporters offer potential glycemic and weight-loss advantages over selective agents.
- Remote Patient Monitoring Integration:Partnerships with digital therapeutics vendors enable real-world evidence generation that supports value-based reimbursement negotiations with CMS.
Industry Challenges
- Cross-Functional Medical Affairs Scaling:Manufacturers must build cardiology and nephrology field forces while maintaining endocrinology relationships, straining commercial infrastructure.
- Real-World Evidence Infrastructure:Investment in data partnerships and patient registries is required to satisfy FDA post-market study commitments and payer evidence demands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America SGLT2 Inhibitors Market |
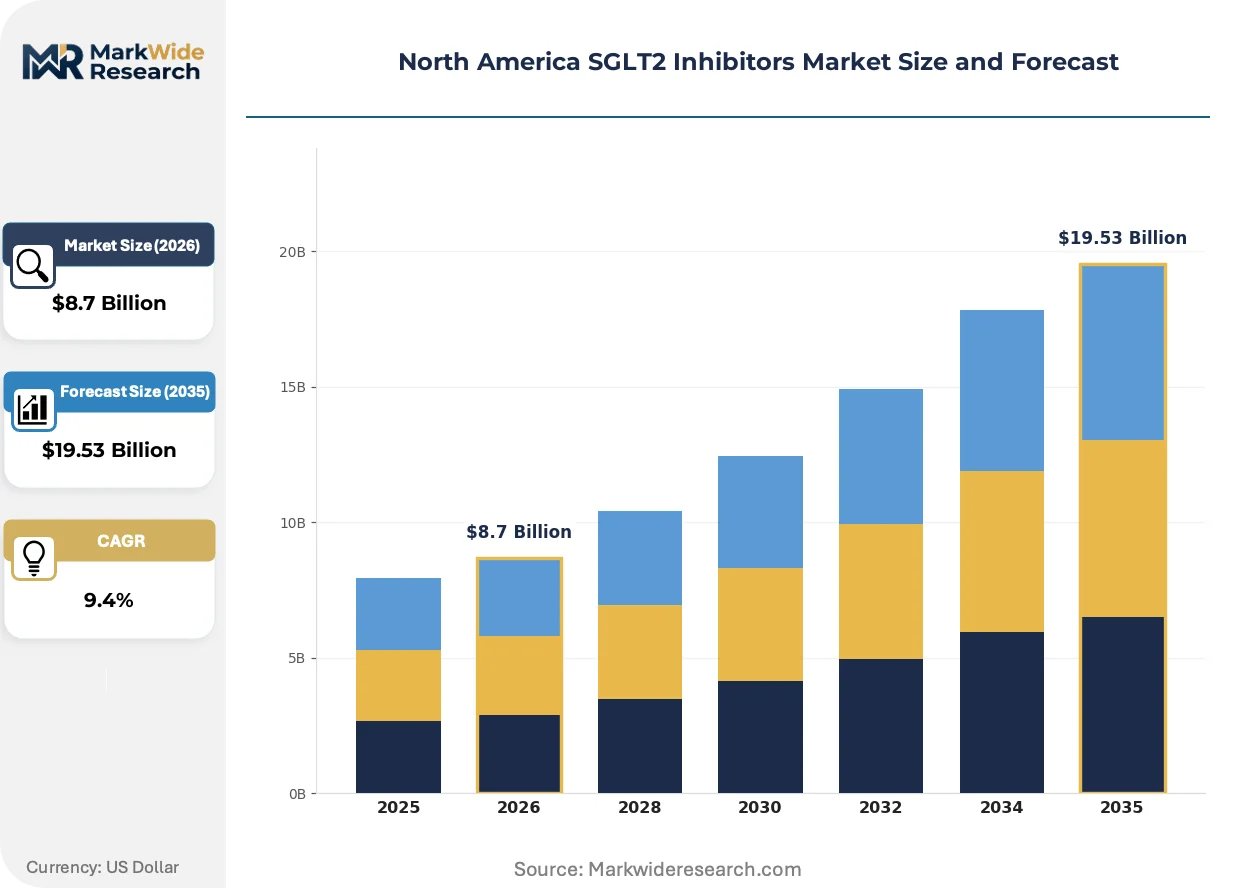
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canagliflozin, Dapagliflozin, Empagliflozin, Ertugliflozin End User: Hospitals, Clinics, Homecare Settings, Pharmacies Delivery Mode: Oral Tablets, Injectable Solutions, Combination Therapy, Others Indication: Type 2 Diabetes, Heart Failure, Chronic Kidney Disease, Obesity |
| Companies Covered | AstraZeneca, Boehringer Ingelheim International GmbH, Johnson & Johnson Services, Inc., Eli Lilly and Company, Merck & Co., Inc., Bristol-Myers Squibb Company, Lexicon Pharmaceuticals, Inc., TheracosBio, LLC, Glenmark Pharmaceuticals Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America SGLT2 Inhibitors Market Trends and Innovations
Prescribing economics in North America are pivoting from volume-based to value-based frameworks as indication expansions complicate traditional therapeutic positioning. Technology convergence and regulatory adaptation are reshaping how manufacturers demonstrate and capture clinical value.
Digital biomarker integration is automating patient identification for SGLT2 inhibitor initiation by flagging heart failure and chronic kidney disease risk through electronic health record algorithms. Cardiology departments at Cleveland Clinic and Mayo Clinic are deploying these tools to compress time-to-therapy for eligible patients. This automation is reducing reliance on specialist referral bottlenecks and expanding addressable patient pools beyond traditional diabetes management.
Health Canada and FDA are harmonizing cardiovascular outcomes trial requirements for chronic kidney disease indications, streamlining cross-border development programs for sponsors. The regulatory alignment is compressing submission timelines and reducing redundant clinical investment. Canadian provinces with centralized formularies are moving faster on renal indication coverage as trial design standards converge with US precedent.
Specialty pharmacy channels are consolidating SGLT2 inhibitor dispensing as integrated delivery networks seek to capture drug margin and improve adherence monitoring. CVS Caremark and OptumRx are building dedicated heart failure medication management programs that bundle SGLT2 inhibitors with remote monitoring services. This channel shift is most visible in Medicare Advantage plans with vertical integration between payer and pharmacy operations.
North America SGLT2 Inhibitors Market Segmentation
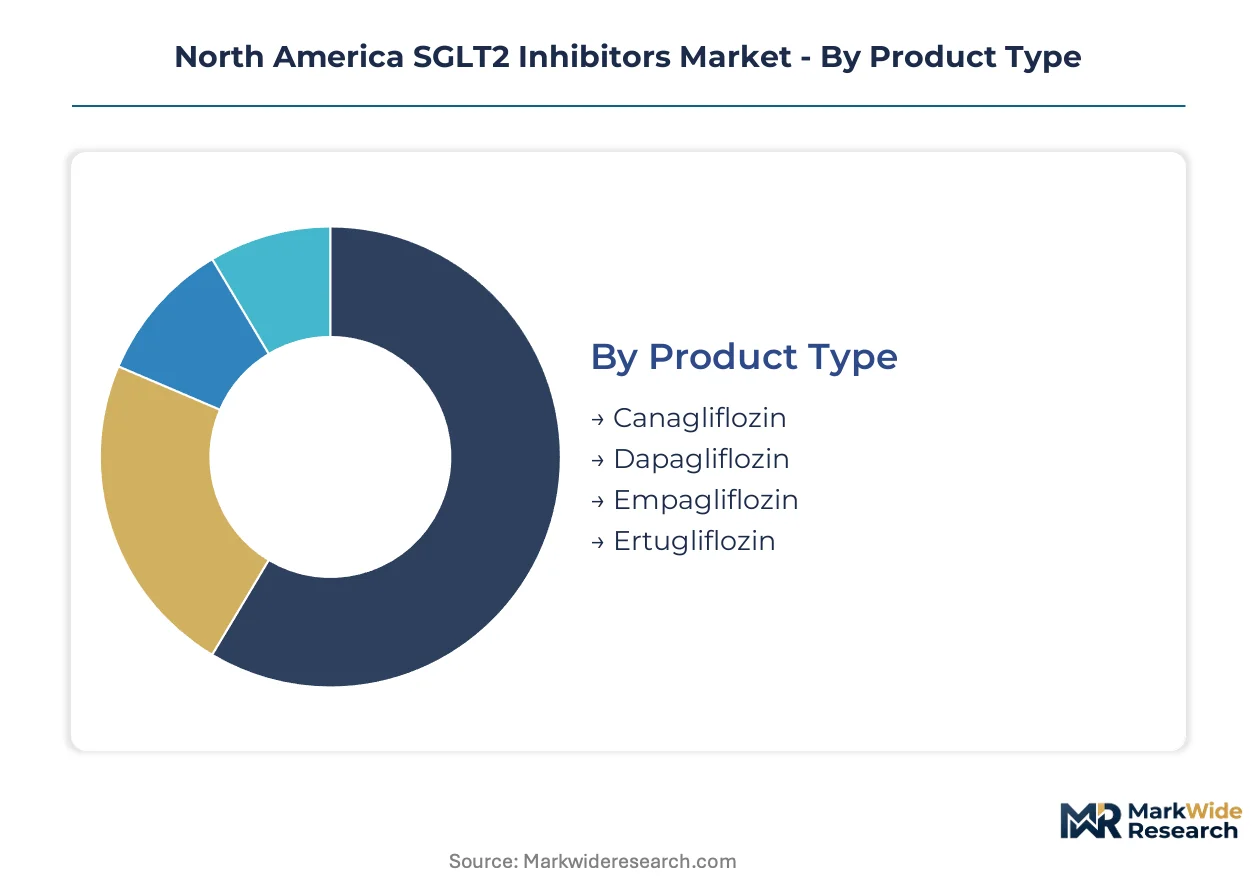
SGLT2 inhibitor segmentation reveals how capital allocation priorities diverge across molecular platforms, care settings, and therapeutic applications. Manufacturers deploy R&D budgets unevenly across these dimensions based on regulatory pathway complexity and reimbursement concentration.
Product Type:
Capital intensity varies sharply across molecular scaffolds, with cardiovascular outcome trial requirements driving divergent clinical investment profiles.
- Dapagliflozin:A propanediol derivative with demonstrated heart failure and chronic kidney disease efficacy in the DAPA-HF and DAPA-CKD trials. Demand concentrates in United States integrated delivery networks where AstraZeneca has secured preferred formulary status through outcomes-based contracts with Medicare Advantage plans.
- Empagliflozin:A benzyl-glucoside derivative distinguished by EMPEROR-Reduced and EMPEROR-Preserved cardiovascular outcomes data. Boehringer Ingelheim has concentrated United States investment in endocrinology-to-cardiology prescriber conversion programs as FDA label expansions broaden eligibility.
- Canagliflozin:A thiophene-containing C-glucoside facing generic erosion as FDA bioequivalence pathways accelerate commoditization.
- Ertugliflozin:A structurally differentiated SGLT2 inhibitor with more limited cardiovascular outcomes data relative to dapagliflozin and empagliflozin.
Most installed capacity flows through dapagliflozin. Expansion is steepest in empagliflozin.
End User:
Channel economics favor settings with captive specialty pharmacy operations and integrated electronic health record infrastructure.
- Hospitals:Academic medical centers and community hospital systems with heart failure protocols embed SGLT2 inhibitors in order sets. Cleveland Clinic and Mayo Clinic have automated patient identification through EHR algorithms that flag reduced ejection fraction and elevated NT-proBNP levels.
- Clinics:Cardiology and nephrology outpatient practices represent the fastest-expanding prescriber base as indication expansions displace traditional endocrinology-centric demand.
- Homecare Settings:Remote patient monitoring partnerships enable adherence tracking for Medicare beneficiaries with multiple comorbidities.
- Pharmacies:CVS Caremark and OptumRx bundle SGLT2 inhibitors with medication therapy management services in vertically integrated Medicare Advantage plans.
Volume concentrates in hospital outpatient departments. Homecare settings are climbing the fastest.
Delivery Mode:
Formulation stability requirements and manufacturing complexity create divergent margin structures across delivery formats.
- Oral Tablets:Immediate-release and extended-release formulations dominate prescription volumes. FDA bioequivalence standards for generic entrants have compressed branded pricing power as patent cliffs approach for established molecules.
- Combination Therapy:Fixed-dose combinations with metformin or DPP-4 inhibitors capture disproportionate payer attention for simplifying multi-drug regimens in comorbid patients.
- Injectable Solutions:Limited commercial presence due to SGLT2 inhibitor pharmacokinetics favoring oral administration.
- Others:Novel delivery platforms including orally disintegrating tablets for dysphagic patients remain developmental.
Most prescriptions flow through oral tablets. Combination therapy formats are gaining share fastest.
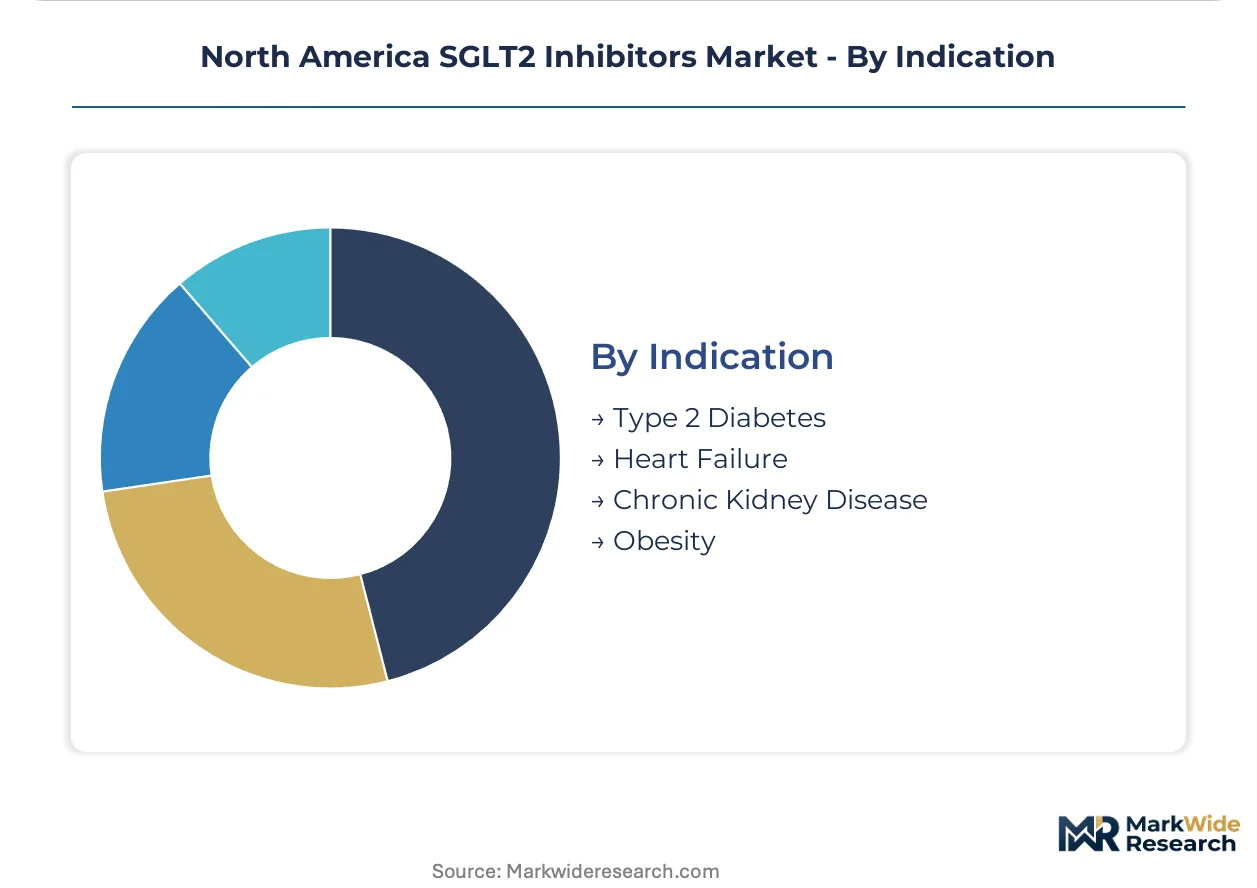
Indication:
Reimbursement concentration and prescriber training requirements reshape competitive dynamics as label expansions broaden addressable populations.
- Type 2 Diabetes:The original approved indication with established endocrinology prescribing patterns. United States demand is plateauing as cardiology and nephrology indications capture incremental volume.
- Heart Failure:FDA approvals for reduced and preserved ejection fraction indications have rewired hospital formulary placement. United States health systems with dedicated heart failure clinics prioritize SGLT2 inhibitors in protocol-driven care pathways.
- Chronic Kidney Disease:Renal indication expansions unlock nephrology channel access and Medicare Part D coverage with broader patient eligibility criteria.
- Obesity:Off-label utilization and clinical trial investment targeting weight-loss effects as differentiated from GLP-1 receptor agonists.
Most treated patients carry type 2 diabetes diagnoses. Heart failure applications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cardiology and nephrology specialists cluster in major academic medical centers across North America, driving demand concentration in integrated health systems with captive specialty pharmacy operations.
United States
Medicare Advantage plans with vertical pharmacy integration dominate volume uptake. FDA label expansions for heart failure with preserved ejection fraction have rewired hospital formulary placement. The Cleveland Clinic and Mayo Clinic anchor automated patient identification through EHR algorithms flagging reduced ejection fraction.
Canada
Provincial centralized formularies accelerate renal indication coverage as trial design standards converge with US precedent. Health Canada bioequivalence pathways for generic entrants compress branded pricing timelines. Ontario and Quebec health systems lead heart failure protocol adoption in academic medical centers.
Mexico
Private hospital chains in Mexico City and Monterrey drive branded product demand as public sector procurement favors cost-minimized alternatives. COFEPRIS regulatory alignment with FDA standards streamlines multinational sponsor submissions. Guadalajara's pharmaceutical manufacturing corridor supplies regional generic production.
North America SGLT2 Inhibitors Market Competitive Landscape
Top-tier vendors anchor cardiovascular outcomes data positioning, while mid-tier players compete on price as patent cliffs accelerate. The vendor base concentrates around three strategic archetypes: large-cap pharmaceutical conglomerates with integrated payer contracting infrastructure, mid-cap biotech specialists with single-molecule focus, and emerging generic manufacturers with cost-optimized production. Competitive moves center on outcomes-based contract negotiation with Medicare Advantage plans and nephrology field force expansion.
Within the large-cap pharmaceutical tier, AstraZeneca and Boehringer Ingelheim International GmbH exemplify divergent channel strategies. AstraZeneca occupies a position emphasizing integrated delivery network penetration through outcomes-based agreements, while Boehringer Ingelheim International GmbH anchors endocrinology-to-cardiology prescriber conversion programs. Johnson & Johnson Services, Inc. represents the diversified healthcare conglomerate archetype with primary care infrastructure scale.
| Leading Market Players |
|---|
| AstraZeneca |
| Boehringer Ingelheim International GmbH |
| Johnson & Johnson Services, Inc. |
| Eli Lilly and Company |
| Merck & Co., Inc. |
| Bristol-Myers Squibb Company |
| Lexicon Pharmaceuticals, Inc. |
| TheracosBio, LLC |
| Glenmark Pharmaceuticals Ltd. |
| Others |
Pricing and Supply Chain Analysis
Medicare Advantage plans with captive specialty pharmacy operations dictate pricing structures through bundled medication management contracts that compress branded margins while expanding volume commitments. This buyer concentration forces manufacturers toward outcomes-based agreements that tie reimbursement to hospitalization reduction metrics rather than per-unit transactional pricing.
Pricing Analysis
Bundled service contracts with remote patient monitoring dominate over unbundled per-prescription pricing in vertically integrated health systems. Three-tier pricing structure across premium branded formulations, authorized generics, and commodity bioequivalents reflects FDA approval status and cardiovascular outcomes data depth. Cost compression in the generic tier is intensifying as Health Canada bioequivalence pathways accelerate substitution. Medicare Part D plans exhibit highest price sensitivity due to IRA negotiation exposure, while employer-sponsored commercial plans retain modest brand premium tolerance.
Supply Chain Analysis
Dual-sourcing requirements from integrated delivery networks mandate multi-manufacturer formulary placement, preventing single-supplier dependence even for preferred molecules. Active pharmaceutical ingredient production draws from India, China, and the United States, with finished dose manufacturing concentrated in Puerto Rico and Ireland. Supply chain risk centers on tariff exposure for imported APIs as trade policy shifts threaten cost predictability. Distribution runs through captive specialty pharmacy operations at CVS Caremark and OptumRx, bypassing traditional wholesale channels for Medicare Advantage populations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America SGLT2 inhibitors market functions as a regulatory compounder where FDA label expansions for heart failure and chronic kidney disease continuously broaden prescriber eligibility and payer coverage criteria.
For Market Incumbents: Anticipate generic erosion pressure by accelerating outcomes-based contract penetration with Medicare Advantage plans before patent cliffs materialize. Deepen cardiology field force presence to defend formulary positioning against mid-tier competitors lacking cardiovascular outcomes data. Prioritize nephrology channel investment as renal indications displace diabetes-centric demand patterns. For New Entrants and Emerging Players: Launch via white-label generic partnerships with established specialty pharmacy distributors to bypass direct payer contracting barriers. Target Mexican private hospital chains where COFEPRIS alignment with FDA standards streamlines market entry without outcomes data requirements. Emphasize cost-minimized positioning against branded portfolios in provincial Canadian formularies. For Investors and Strategic Acquirers: Large-cap pharmaceutical conglomerates with integrated payer infrastructure represent the most active acquirer category in this space, seeking cardiovascular outcomes data assets to complement existing metabolic portfolios. Over the intermediate horizon, acquisition value concentrates in firms with nephrology field forces and Medicare Advantage contracting scale. Monitor FDA renal indication approval velocity as the critical inflection signal for valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Outcomes-Based Contracting | Aligns manufacturer reimbursement with Cleveland Clinic hospitalization reduction metrics. |
| Nephrology Field Force Expansion | Captures prescriber relationships as chronic kidney disease indications broaden eligibility. |
| Specialty Pharmacy Integration | Enables adherence monitoring through CVS Caremark bundled medication management programs. |
| Generic Bioequivalence Pathway | Accelerates Health Canada and FDA commoditization timelines for patent-expired molecules. |
| Digital Biomarker Partnership | Automates patient identification via Mayo Clinic EHR algorithms flagging reduced ejection fraction. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists with secondary validation against FDA filings, ClinicalTrials.gov records, CMS Medicare data, and hospital procurement databases. Bottom-up prescription volume modeling and top-down revenue reconciliation anchored market size estimation.
Segment-weighting approaches distributed analytical emphasis across molecular platform, prescriber specialty, delivery mode, and indication dimensions throughout the projection horizon. CAGRs derived from indication-specific adoption curves and payer coverage expansion timelines, incorporating IRA Medicare price negotiation implementation effects and patent cliff erosion assumptions as primary forecast inputs.
Several conditions sit outside the modeled scope, including unforeseen FDA safety actions, disruptive combination therapy approvals, and macroeconomic shocks to Medicare funding. Deviation in cardiology protocol adoption velocity or nephrology prescriber conversion rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Prescription Transdermal Patches Market
Pharmaceuticals
Systemic Lupus Erythematous SLE Drugs Market
Pharmaceuticals
Oral Solid Dosage Contract Manufacturing Market
Pharmaceuticals
Complement-Targeted Therapeutics Market
Pharmaceuticals
Osteoarthritis Drugs Market
Pharmaceuticals
Leflunomide Market
Pharmaceuticals
Global Pharmaceutical Contract Manufacturing Market
Pharmaceuticals
Dextromethorphan Market
Pharmaceuticals
Global Anti-Retroviral Drugs Market
Pharmaceuticals
Global Doxorubicin Market
Pharmaceuticals
Budesonide Market
Pharmaceuticals
Bulbospinal Muscular Atrophy Drugs Market
Pharmaceuticals
Europe Meglitinide Market
Pharmaceuticals
Global Primary Biliary Cirrhosis Drug Market
Pharmaceuticals
Critical Care Therapeutics Market
Pharmaceuticals
Calcium Channel Blocker Market