
 Chaple Syndrome Market | 2026-2036
Chaple Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Chaple Syndrome Market Analysis
Buyer concentration among academic medical centers and specialized complement clinics is recalibrating procurement patterns for Chaple Syndrome diagnostics and therapeutics. Alexion Pharmaceuticals leverages its established rare disease infrastructure to sustain commercial reach across these concentrated accounts. Apellis Pharmaceuticals anchors its competitive position through deep specialization in complement pathway modulation. Alnylam Pharmaceuticals differentiates via RNA interference technology leadership directed at genetic complement disorders.
Chaple Syndrome denotes a rare autosomal recessive condition marked by CD55 deficiency, uncontrolled complement activation, and thrombotic microangiopathy, requiring precise molecular confirmation through next-generation sequencing of the CD55 gene. Therapeutic development targets terminal complement inhibition to prevent systemic TMA and preserve organ function. Molecular diagnostics leads clinical decision-making as the gateway to definitive CD55 genotyping and treatment eligibility, while biologics capture expanding margin pools through long-acting C5 inhibitors and emerging subcutaneous formulations. Digital health solutions represent the fastest-growing technology segment as remote monitoring platforms track complement biomarkers and thrombotic risk between specialist visits.
The FDA's orphan drug program shapes development economics through tax credits, market exclusivity, and waived regulatory fees for Chaple Syndrome therapeutics. EMA's parallel designation under comparable rare disease frameworks enables synchronized European market access for complement-targeted therapies. Stakeholders must monitor evolving payer evidence requirements for ultra-rare indications, where traditional health technology assessment methodologies struggle to capture clinical value across heterogeneous patient populations.
Market Dynamics
FDA's orphan drug designation framework compresses development timelines for Chaple Syndrome therapeutics while concentrating procurement power among specialized complement disorder clinics clustered at major academic medical centers.
Growth Catalysts
- Orphan Drug Tax Credits:The FDA's program provides development cost offsets and market exclusivity that accelerate C5 inhibitor pipelines toward commercialization.
- Next-Generation Sequencing:Pediatric hematology centers deploy CD55 gene testing to shorten diagnostic odysseys and identify treatment-eligible patients earlier in disease progression.
- Academic Medical Center Clustering:Concentrated specialist infrastructure in the United States creates referral networks that aggregate sufficient patient volumes for clinical trial recruitment.
Market Restraints
- Plasma-Derived Protein Supply:Terminal complement inhibitors depend on biologic manufacturing capacity that concentrates at limited FDA-inspected facilities.
- Diagnostic Access Inequality:Molecular confirmation requires specialized laboratories that cluster in urban academic centers, leaving rural and underserved populations undiagnosed.
- Health Technology Assessment Limitations:Traditional cost-effectiveness methodologies struggle to value ultra-rare disease interventions across heterogeneous pediatric presentations.
Strategic Opportunities
- Subcutaneous Formulation Development:Long-acting C5 inhibitors enabling home administration would expand addressable populations beyond infusion center catchment areas.
- Remote Biomarker Monitoring:Digital health platforms tracking complement activation markers between specialist visits create new recurring revenue streams.
- EMA Synchronized Access:Parallel orphan designation pathways enable coordinated European launch strategies that leverage FDA approval data packages.
Industry Challenges
- Genetic Counselor Workforce Scarcity:CD55 variant interpretation requires specialized expertise that outpaces training program output.
- Multi-Site Trial Coordination:Pediatric rare disease studies demand complex international protocols across dispersed patient populations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chaple Syndrome Market |
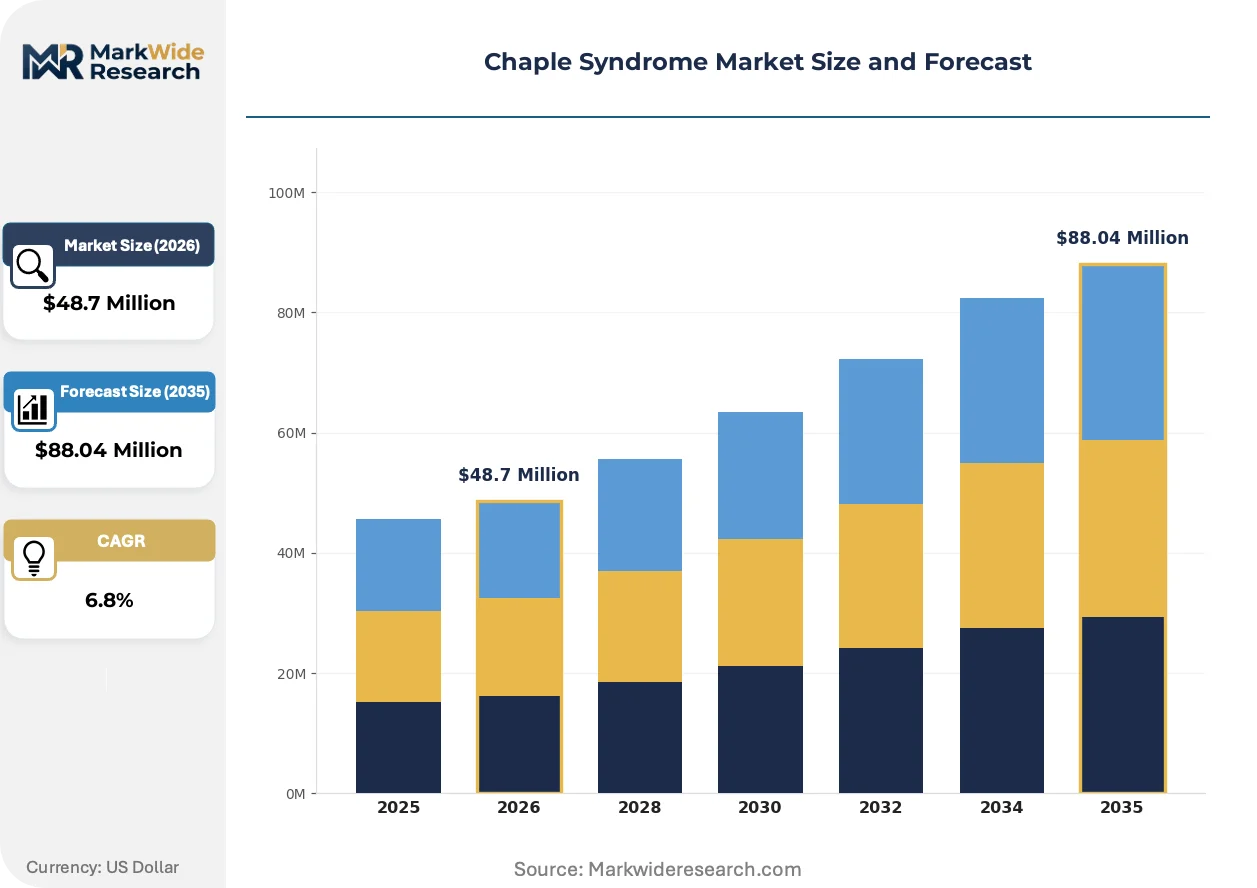
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $88.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Tests, Therapeutics, Monitoring Devices, Supportive Care Products Application: Clinical Research, Home Healthcare, Hospitals, Rehabilitation Centers End User: Healthcare Professionals, Patients, Caregivers, Research Institutions Technology: Molecular Diagnostics, Biologics, Wearable Tech, Digital Health Solutions |
| Companies Covered | Alexion Pharmaceuticals, Akari Therapeutics, Apellis Pharmaceuticals, Amgen, CinnaGen Co., Ra Pharmaceuticals, Alnylam Pharmaceuticals, Novartis AG, F. Hoffmann-La Roche Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chaple Syndrome Market Emerging Trajectories
RNA interference platforms are advancing toward clinical validation for genetic complement disorders, while regulatory frameworks adapt to accommodate single-arm trials in ultra-rare indications.
Subcutaneous C5 inhibitor delivery systems are integrating extended-release polymer technologies to sustain therapeutic concentrations between quarterly injections. Pediatric hematology centers in the United States are piloting these formulations to reduce infusion center dependency. The technology is integrating home-based administration models that decompress specialist clinic capacity.
EMA's parallel orphan designation framework is streamlining European market access for complement-targeted therapies through centralized assessment procedures. Manufacturers now synchronize FDA and EMA submission timelines to compress regulatory lag. Ultra-rare disease sponsors are responding with integrated transatlantic development strategies.
Specialist procurement committees at academic medical centers are consolidating purchasing authority for Chaple Syndrome diagnostics and therapeutics into centralized pharmacy and therapeutics boards. Traditional distributor relationships are yielding to direct manufacturer contracts with price transparency mandates. This concentration is most visible in the United States, where integrated delivery networks negotiate outcomes-based agreements for C5 inhibitors.
Chaple Syndrome Market Segmentation
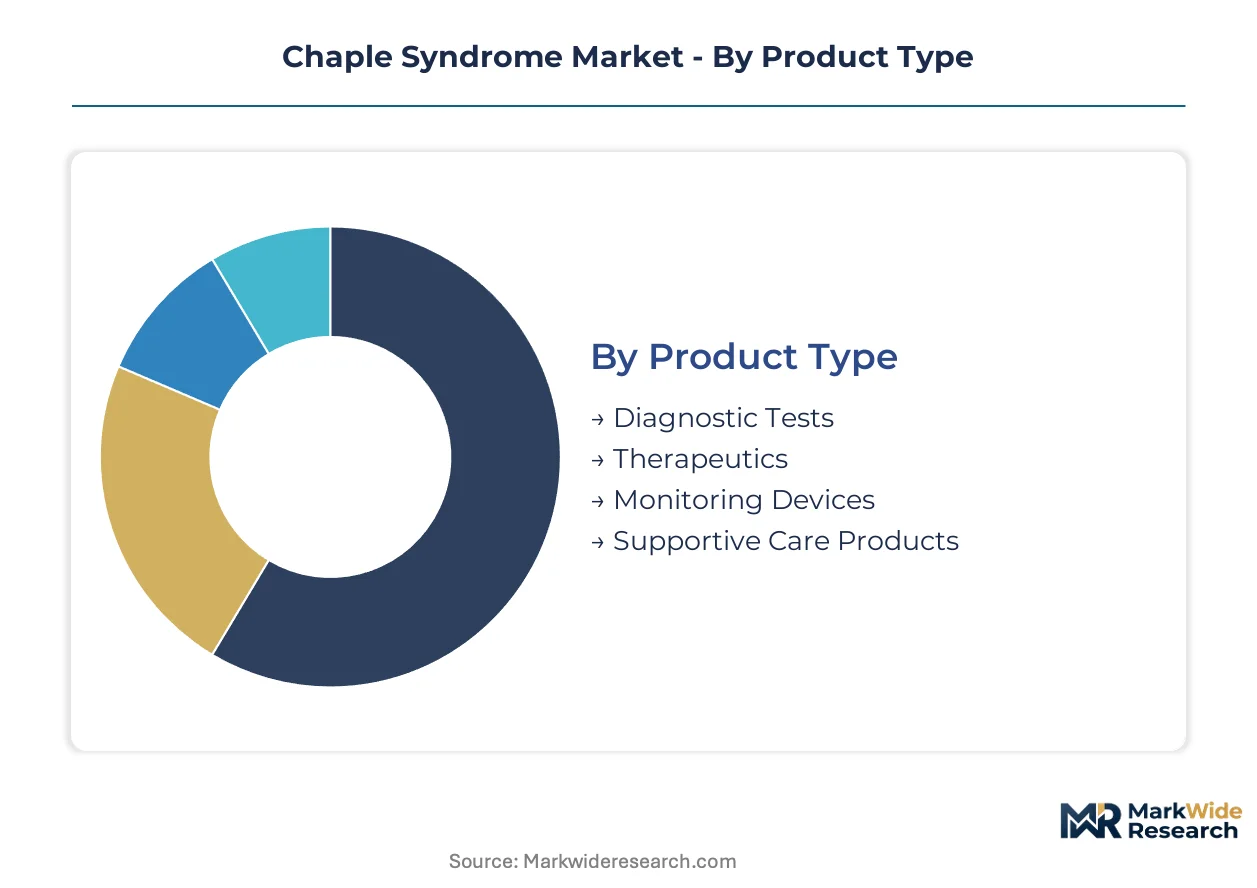
Chaple Syndrome's diagnostic and therapeutic pathways fragment across distinct product architectures, with standalone molecular testing contrasting against integrated biologic delivery systems. Segmentation clarity enables manufacturers to align development priorities with the concentrated infrastructure of academic medical centers and dispersed home-care requirements.
Product Type:
Standalone diagnostic platforms dominate procurement budgets, while embedded therapeutic systems require deeper clinical integration.
- Diagnostic Tests:Next-generation sequencing panels for CD55 gene variant detection command premium pricing at specialized hematology reference laboratories. Demand concentrates at pediatric academic centers in Boston, Philadelphia, and Houston where genetic counselor density supports variant interpretation workflows.
- Therapeutics:Terminal complement inhibitors—primarily intravenous C5 monoclonal antibodies—anchor treatment protocols through biweekly infusion schedules. United States-based comprehensive hemophilia treatment centers aggregate sufficient patient volumes to justify cold-chain inventory investment.
- Monitoring Devices:Portable complement activity assays enable between-visit surveillance.
- Supportive Care Products:Plasma exchange equipment and transfusion support materials address acute thrombotic microangiopathy episodes.
Diagnostic Tests lead volumes today; Therapeutics is gaining share fastest.
Application:
Site-of-care economics drive divergent margin structures, with centralized hospital infusion commanding price premiums against distributed home administration.
- Hospitals:Tertiary pediatric centers manage acute TMA episodes through integrated complement inhibitor infusion and intensive care capabilities. Major United States academic hospitals in New York, Chicago, and Los Angeles maintain dedicated complement disorder protocols.
- Home Healthcare:Subcutaneous formulation development is shifting therapeutic administration away from infusion centers. Home nursing networks in Florida and Texas pilot extended-release C5 inhibitor delivery to reduce travel burden for dispersed rural families.
- Clinical Research:Natural history studies and registry enrollment concentrate at NIH-funded sites.
- Rehabilitation Centers:Post-acute recovery programs address organ function preservation after TMA resolution.
Hospitals capture the majority of current revenue; Home Healthcare shows the steepest expansion trajectory.
End User:
Decision-making authority splits between specialist prescribers and patient self-advocacy networks, with caregiver education gaps limiting rural access.
- Healthcare Professionals:Pediatric hematologists and complement medicine specialists control diagnostic referral pathways and therapeutic initiation. Board-certified practitioners cluster at United States academic medical centers with established rare disease programs.
- Patients:Disease advocacy organizations and peer support networks accelerate diagnostic recognition in undiagnosed populations. Patient registries maintained by the United States-based Complement Research Foundation drive natural history data collection.
- Caregivers:Family members manage home infusion schedules and biomarker monitoring compliance.
- Research Institutions:Academic laboratories conduct CD55 pathophysiology studies and preclinical therapeutic screening.
Healthcare Professionals direct current purchasing decisions; Patients are expanding influence fastest through advocacy channel development.
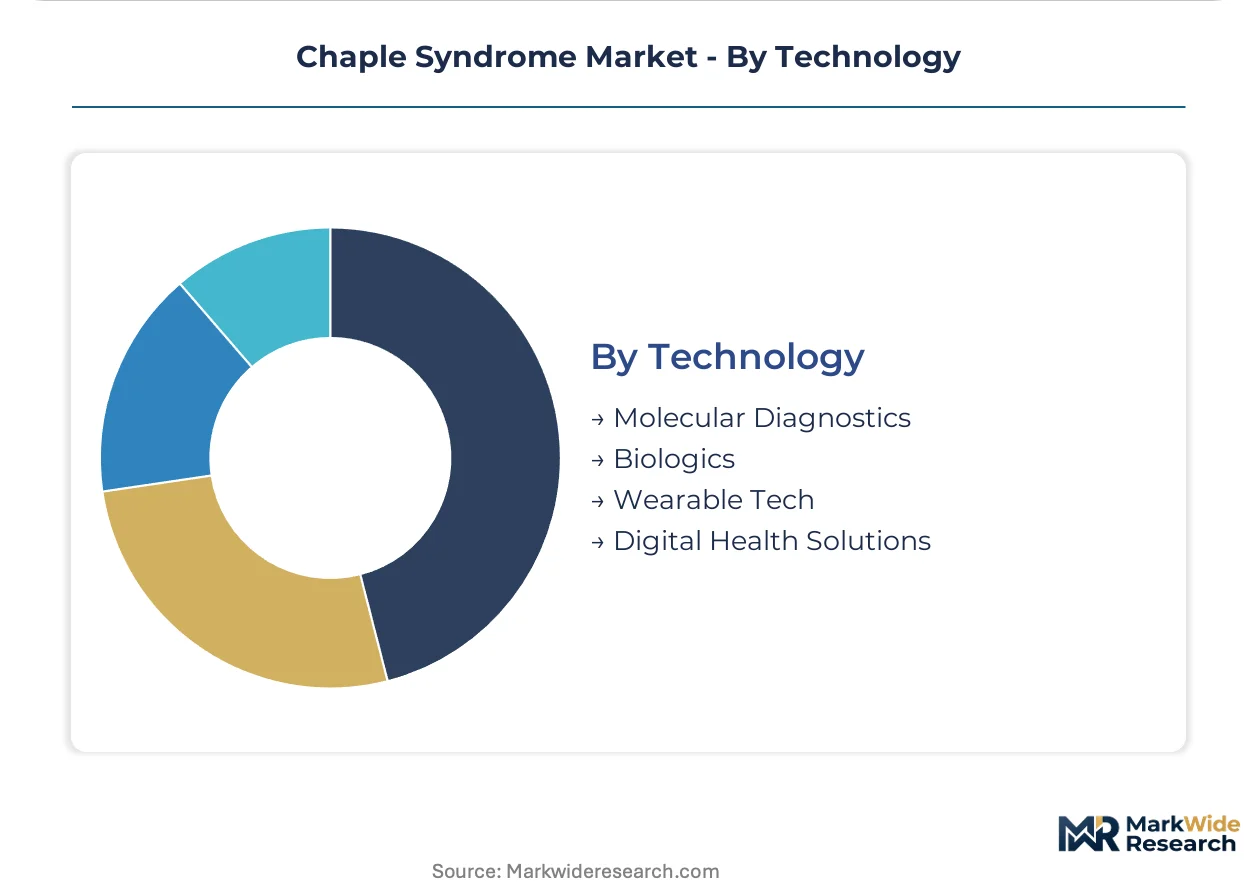
Technology:
Platform maturity varies sharply, with established molecular methods funding emerging digital infrastructure investments.
- Biologics:Recombinant C5 inhibitors manufactured at FDA-inspected biologics facilities sustain therapeutic supply through complex cell culture processes. United States-based contract manufacturing organizations in Massachusetts and North Carolina concentrate production capacity for orphan complement therapeutics.
- Digital Health Solutions:Remote monitoring platforms track LDH, platelet counts, and complement activation markers between specialist visits. Pilot deployments at Cincinnati Children's Hospital and Texas Children's Hospital demonstrate feasibility of home-based thrombotic risk surveillance.
- Molecular Diagnostics:PCR and sequencing-based CD55 testing enables definitive genetic confirmation.
- Wearable Tech:Emerging continuous monitoring devices capture vital sign trends predictive of TMA onset.
Biologics anchor current technology spending; Digital Health Solutions are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pediatric hematology specialists cluster at academic medical centers in the United States, Germany, and Japan, anchoring diagnostic capacity and therapeutic access for Chaple Syndrome patients worldwide.
United States
FDA orphan drug tax credits and seven-year market exclusivity accelerate C5 inhibitor commercialization timelines. Boston Children's Hospital, Cincinnati Children's Hospital, and Texas Children's Hospital maintain dedicated complement disorder clinics that aggregate patient volumes for clinical trials. Subcutaneous formulation pilots in Florida and Texas reduce rural travel burdens.
Germany
EMA centralized assessment procedures streamline European market access for complement-targeted therapies. The country's statutory health insurance system covers genetic testing for ultra-rare indications, reducing diagnostic access barriers. Heidelberg and Munich academic centers coordinate multi-site pediatric rare disease protocols across the German-speaking region.
Japan
PMDA's Sakigake designation system provides priority review for innovative rare disease therapies. Tokyo and Osaka pediatric hematology departments participate in international natural history registries for CD55 deficiency. Domestic biologics manufacturing capacity at Chugai Pharmaceutical facilities supports regional supply security.
United Kingdom
NHS England's specialized commissioning framework designates complement disorder services at designated supra-regional centers. Genomics England's rare disease program funds CD55 gene testing through the National Genomic Test Directory. London, Manchester, and Birmingham academic hospitals coordinate pediatric hematology referral networks.
Switzerland
Swissmedic's parallel scientific advice with FDA and EMA enables synchronized regulatory submissions for orphan indications. Basel and Zurich university hospitals host complement research programs with industry collaboration frameworks. The country's health technology assessment body adapts methodologies for ultra-rare disease valuation.
Chaple Syndrome Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the Chaple Syndrome therapeutic landscape, creating a tiered structure where rare disease infrastructure determines commercial reach. Large-cap biopharmaceuticals leverage established complement platforms and global distribution networks. Mid-cap specialists concentrate on RNA interference and targeted protein modulation technologies. Competitive moves center on subcutaneous formulation development and outcomes-based contracting with academic medical center networks.
Within the rare disease infrastructure tier, Alexion Pharmaceuticals exemplifies complement pathway commercialization capabilities, while Apellis Pharmaceuticals occupies a position in targeted C3 modulation. Alnylam Pharmaceuticals represents RNA interference technology application to genetic complement disorders. These three anchors demonstrate how therapeutic modality specialization shapes competitive positioning in ultra-rare indications.
| Leading Market Players |
|---|
| Alexion Pharmaceuticals |
| Akari Therapeutics |
| Apellis Pharmaceuticals |
| Amgen |
| CinnaGen Co. |
| Ra Pharmaceuticals |
| Alnylam Pharmaceuticals |
| Novartis AG |
| F. Hoffmann-La Roche Ltd |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up reference laboratories in the United States concentrate CD55 gene testing capacity, enabling bundled diagnostic service pricing that captures both molecular confirmation and genetic counseling interpretation. This ownership pattern tightens pricing discipline across pediatric hematology centers while compressing margins for standalone testing providers unable to match integrated service offerings.
Pricing Analysis
Bundled diagnostic services encompassing CD55 sequencing, variant interpretation, and genetic counseling command premium pricing against unbundled test-only alternatives. Three-tier pricing structure across comprehensive panels, targeted gene tests, and reflex confirmation assays stratifies procurement budgets at academic medical centers. Pricing pressure stems from Medicare and Medicaid reimbursement compression for molecular diagnostics, particularly affecting standalone laboratories without therapeutic service integration. Pediatric hematology departments demonstrate lowest price sensitivity due to institutional research funding and orphan drug program subsidies, while community hospitals face acute budget constraints.
Supply Chain Analysis
FDA-inspected biologics manufacturing certification gates terminal complement inhibitor production, concentrating supply among contract manufacturing organizations in Massachusetts and North Carolina. Recombinant C5 inhibitor production draws from Chinese-sourced cell culture media, German-engineered bioreactor systems, and domestic fill-finish capacity. Single-source vulnerability permeates the cold-chain distribution network, where specialized logistics providers maintain exclusive contracts with academic medical center networks. Distribution runs through manufacturer-direct arrangements with hospital pharmacy and therapeutics boards, bypassing traditional wholesale distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
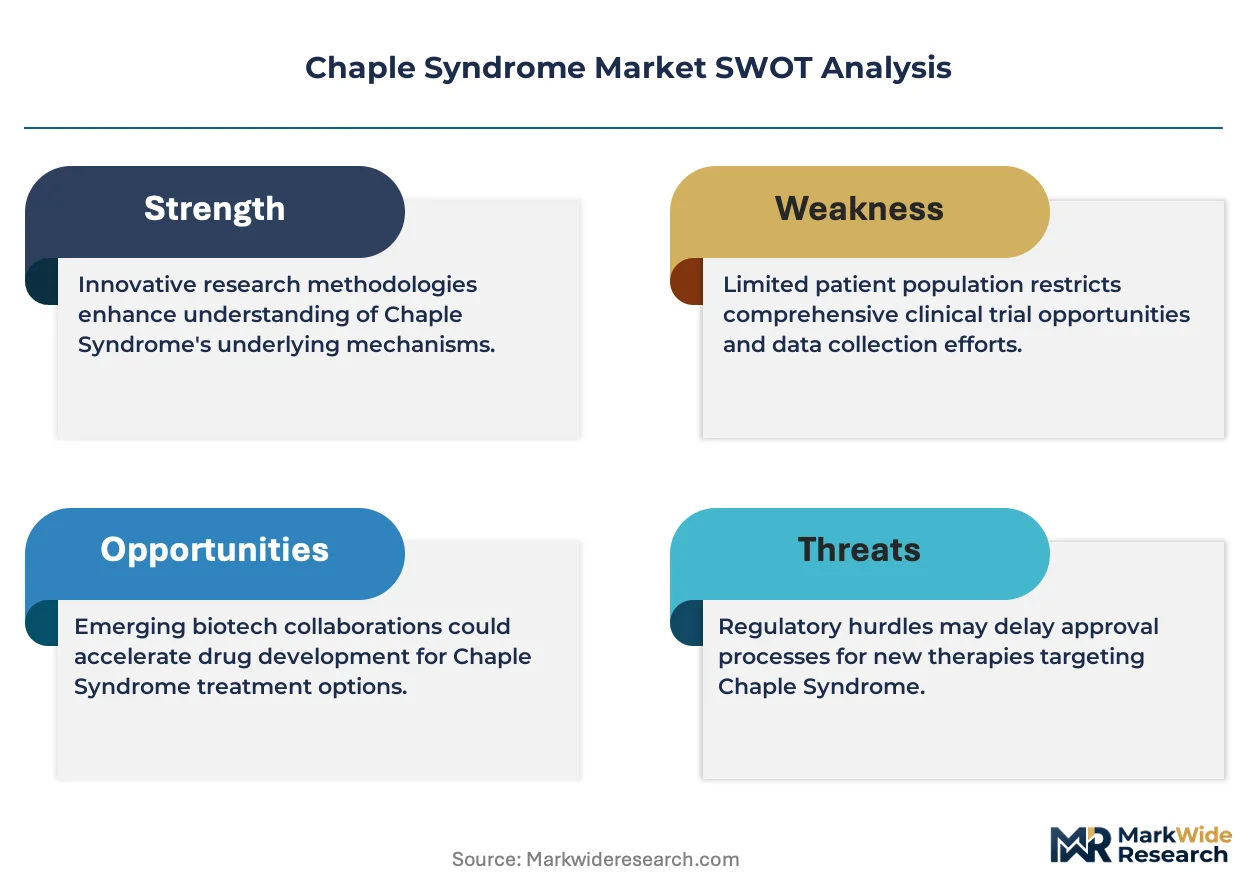
The Chaple Syndrome market functions as a geographic-arbitrage play where FDA orphan drug tax credits in the United States offset development costs that European sponsors bear through national health technology assessment negotiations.
For Market Incumbents: Extend subcutaneous formulation pipelines to decompress infusion center dependency and capture rural patient populations beyond academic medical center catchment areas. Consolidate procurement relationships through outcomes-based contracting with integrated delivery networks, countering emerging RNA interference platforms that threaten C5 inhibitor market position. For New Entrants and Emerging Players: EMA's parallel orphan designation framework in Europe opens a window for synchronized transatlantic development strategies that leverage FDA approval data packages. Target home healthcare administration segments in Florida and Texas where subcutaneous delivery pilots demonstrate patient compliance advantages, deploying direct-to-patient nursing networks as the primary go-to-market channel. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap complement pathway specialists with clinical-stage assets but limited commercial infrastructure. Long-term viability hinges on demonstrating sustained therapeutic response in pediatric populations with heterogeneous CD55 variant presentations. Watch FDA breakthrough therapy designation grants as the inflection signal indicating accelerated review timelines and enhanced acquisition premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Extended-release C5 inhibitors enable home administration, reducing infusion center dependency for rural families. |
| Orphan Drug Designation Pathway | FDA tax credits and market exclusivity accelerate commercialization timelines for complement-targeted therapies. |
| Digital Health Platform Integration | Remote biomarker monitoring at Cincinnati Children's Hospital demonstrates feasibility of between-visit surveillance. |
| Academic Medical Center Partnership | Direct contracts with Boston Children's Hospital and Texas Children's Hospital secure patient access and trial recruitment. |
| EMA Synchronized Submission Strategy | Parallel regulatory pathways compress European market access lag following FDA approval. |
Methodological Framework
Multiple input streams — primary interviews with pediatric hematologists and genetic counselors, secondary validation through FDA orphan drug designations and ClinicalTrials.gov records, and procurement database analysis — were reconciled to construct market estimates. Conversations with complement disorder clinic directors, hospital pharmacy and therapeutics board members, and rare disease advocacy organization leaders informed demand-side assumptions. Bottom-up patient volume estimates from United States academic medical centers were triangulated against top-down therapeutic revenue projections.
Data-stream reconciliation across product type, application, end user, and technology dimensions anchored the analytical framework over the projection horizon. Segmentation modeling incorporated treatment line, administration route, and regional regulatory cluster variables. CAGRs were derived from patient prevalence projections, diagnostic testing adoption curves, and therapeutic penetration assumptions across pediatric hematology centers. Forecast inputs included natural history registry enrollment trends and subcutaneous formulation development timelines.
Revisions become necessary when regulatory designation timelines shift, manufacturing capacity constraints materialize, or health technology assessment methodologies adapt for ultra-rare disease valuation. Forecasts reflect documented assumptions regarding patient identification rates and treatment persistence. A model refresh is warranted upon material change in FDA reimbursement policy for molecular diagnostics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Sarcoidosis Therapeutics Market
Rare Diseases
Europe Rett Syndrome Market
Rare Diseases
Fabry Disease Market
Rare Diseases
Muckle-Wells Syndrome Market
Rare Diseases
Dystrophic Epidermolysis Bullosa Treatment Market
Rare Diseases
Mucopolysaccharidosis (MPS) Treatment Market
Rare Diseases
Aarskog Scott Syndrome Treatment Market
Rare Diseases
Global Guillain-Barre Syndrome Market
Rare Diseases
Rare Diseases Treatment Market
Rare Diseases
Global Gaucher Disease Market
Rare Diseases
Metachromatic Leukodystrophy Market
Rare Diseases
Asia Pacific Rett Syndrome Market
Rare Diseases
Skeletal Dysplasia Market
Rare Diseases
Dravet Syndrome Market
Rare Diseases
Rosai-Dorfman Disease (RDD) Therapeutics Market
Rare Diseases
Acid Sphingomyelinase Deficiency Market