
 Global Loratadine Market | 2026-2036
Global Loratadine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Loratadine Market Foresight
Market Context
The EU Green Deal's pharmaceutical sustainability criteria is hardening procurement standards across European hospital networks. Bayer AG leverages its integrated active pharmaceutical ingredient manufacturing to sustain cost advantages in tablet formulations. Sun Pharmaceutical Industries Ltd. anchors significant capacity in India for generic loratadine exports. Pfizer Inc. competes through established hospital pharmacy contracts in developed markets.
Technical Definition and Segment Structure
Loratadine is a second-generation tricyclic antihistamine with a selective peripheral H1-receptor antagonist mechanism and a molecular formula of C22H23ClN2O2, manufactured through multi-step organic synthesis followed by crystallization and micronization for bioavailability optimization. Tablet formulations dominate volume due to manufacturing economies and patient compliance advantages, while oral strips represent the fastest-expanding product type driven by pediatric and geriatric swallowing convenience. Retail pharmacies capture the largest margin pool in distribution channels, though e-commerce platforms are gaining share through direct-to-consumer subscription models for chronic allergy management.
Regulatory Framework
The US FDA enforces current Good Manufacturing Practice standards for loratadine API purity and dissolution profiles, while India's CDSCO mandates bioequivalence documentation for generic formulations under its revised Schedule Y requirements. The EMA's updated environmental risk assessment guidelines for pharmaceuticals are extending compliance costs for European manufacturers. Stakeholders must monitor evolving pharmacovigilance reporting obligations and API traceability mandates as regulatory divergence between jurisdictions intensifies sourcing complexity.
Market Dynamics
The US FDA's tightened purity standards for active pharmaceutical ingredients are forcing wholesale requalification of loratadine suppliers, compressing the approved vendor base while elevating compliance costs for generic manufacturers.
Growth Catalysts
- Allergic rhinitis prevalence:Rising diagnosis rates in urban India and China's megacities are expanding the addressable patient population for second-generation antihistamines.
- CDSCO bioequivalence streamlining:India's revised Schedule Y documentation requirements are accelerating generic approval timelines for export-oriented manufacturers.
- Oral strip technology:Pediatric and geriatric swallowing convenience is driving formulation diversification beyond conventional tablets.
Market Restraints
- API supply concentration:Bulk loratadine production clusters in Zhejiang and Jiangsu provinces, creating single-source vulnerability for Western formulators.
- Input cost volatility:Piperidine and chlorobenzene derivatives face petrochemical feedstock price swings that compress margin predictability.
- Substitution pressure:Cetirizine and fexofenadine alternatives capture price-sensitive segments through established retail pharmacy contracts.
Strategic Opportunities
- Brazil's ANVISA pathway:Underpenetrated generic substitution policies in São Paulo and Rio de Janeiro retail chains offer volume expansion potential.
- EU Green Deal procurement:Pharmaceutical sustainability criteria are creating preferential purchasing channels for manufacturers with certified green chemistry processes.
- E-commerce subscription models:Direct-to-consumer chronic allergy management platforms bypass traditional retail pharmacy markups.
Industry Challenges
- Pharmacovigilance reporting:Divergent adverse event documentation requirements between FDA, EMA, and CDSCO systems multiply compliance overhead.
- Micronization equipment capex:Bioavailability-optimized particle size specifications demand capital-intensive jet milling capacity upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Loratadine Market |
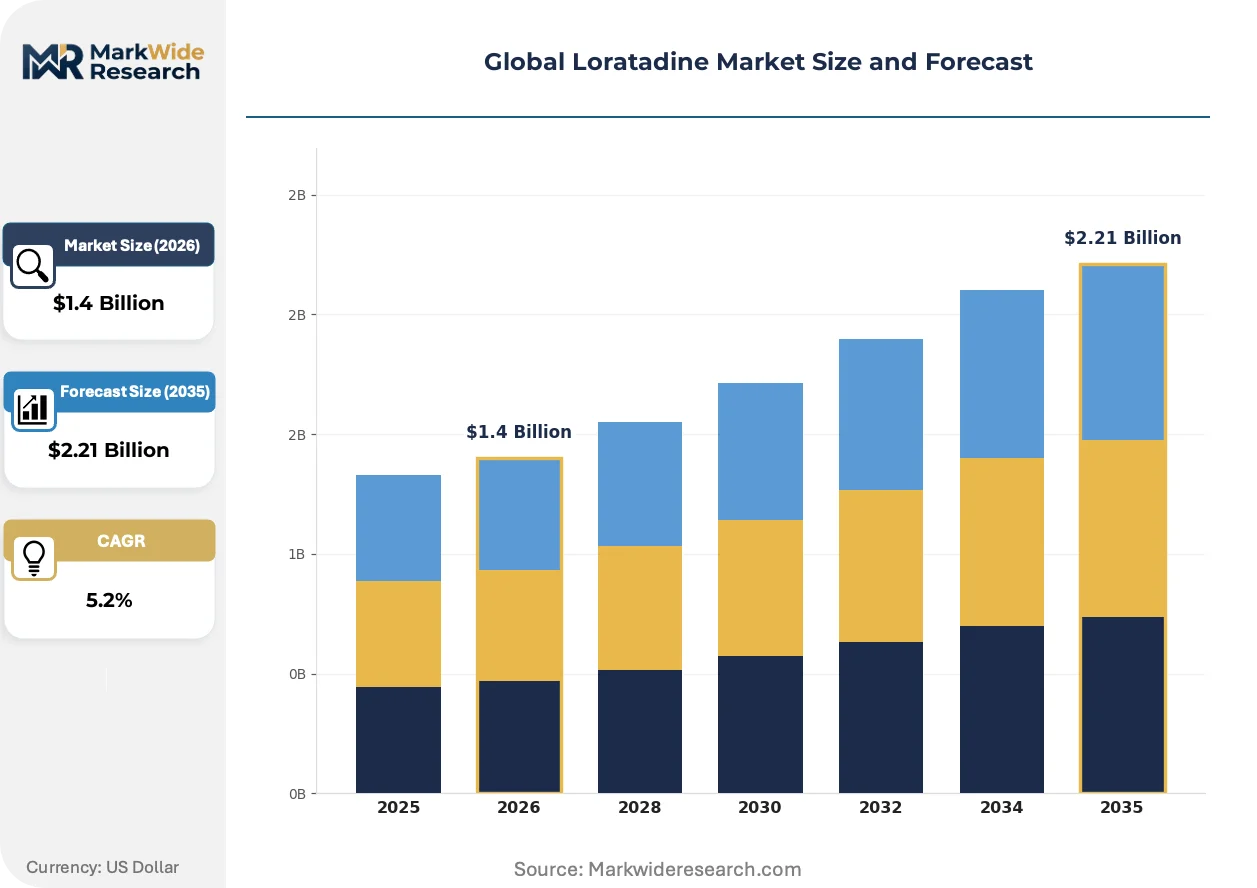
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.21 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Syrups, Effervescent Tablets, Capsules, Oral Strips Therapy Area: Allergic Rhinitis, Urticaria, Conjunctivitis, Atopic Dermatitis, Chronic Idiopathic Urticaria End User: Pharmacies, Hospitals, Clinics, Online Pharmacies, Retail Drug Stores Distribution Channel: Hospital Pharmacies, Retail Pharmacies, E-Commerce Platforms, Wholesale Distributors |
| Companies Covered | Bayer AG, Pfizer Inc., Sun Pharmaceutical Industries Ltd., Viatris Inc., Cadila Pharmaceuticals Ltd., Perrigo Company PLC, Teva Pharmaceutical Industries Ltd., Morepen Laboratories Ltd, Dr. Reddy's Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Loratadine Market Shifts & Advancements
Continuous manufacturing technologies and real-time release testing are compressing batch cycle times while regulatory divergence between jurisdictions is fragmenting quality standards.
Process analytical technology (PAT) is automating in-line monitoring of crystallization kinetics and polymorph consistency. Indian API producers at Hyderabad and Ahmedabad clusters are deploying these systems to preempt FDA 483 observations. The technology is automating quality assurance workflows that previously required offline laboratory testing, reducing release timelines from weeks to days.
EMA's updated environmental risk assessment guidelines for pharmaceuticals are extending compliance costs for European manufacturers. Active pharmaceutical ingredient producers must now submit fate-and-transport modeling for aquatic ecotoxicity. Tablet formulation facilities in Germany and Italy are responding by installing advanced oxidation wastewater treatment systems.
Hospital procurement consortia are consolidating purchasing power through framework agreements that unbundle technical service from product supply. European hospital networks in France, Germany, and the Netherlands are driving this shift, replacing transactional purchasing with multi-year sole-source contracts. The model is most visible in Nordic countries where regional health authorities negotiate centralized antihistamine tenders.
Global Loratadine Market Segmentation
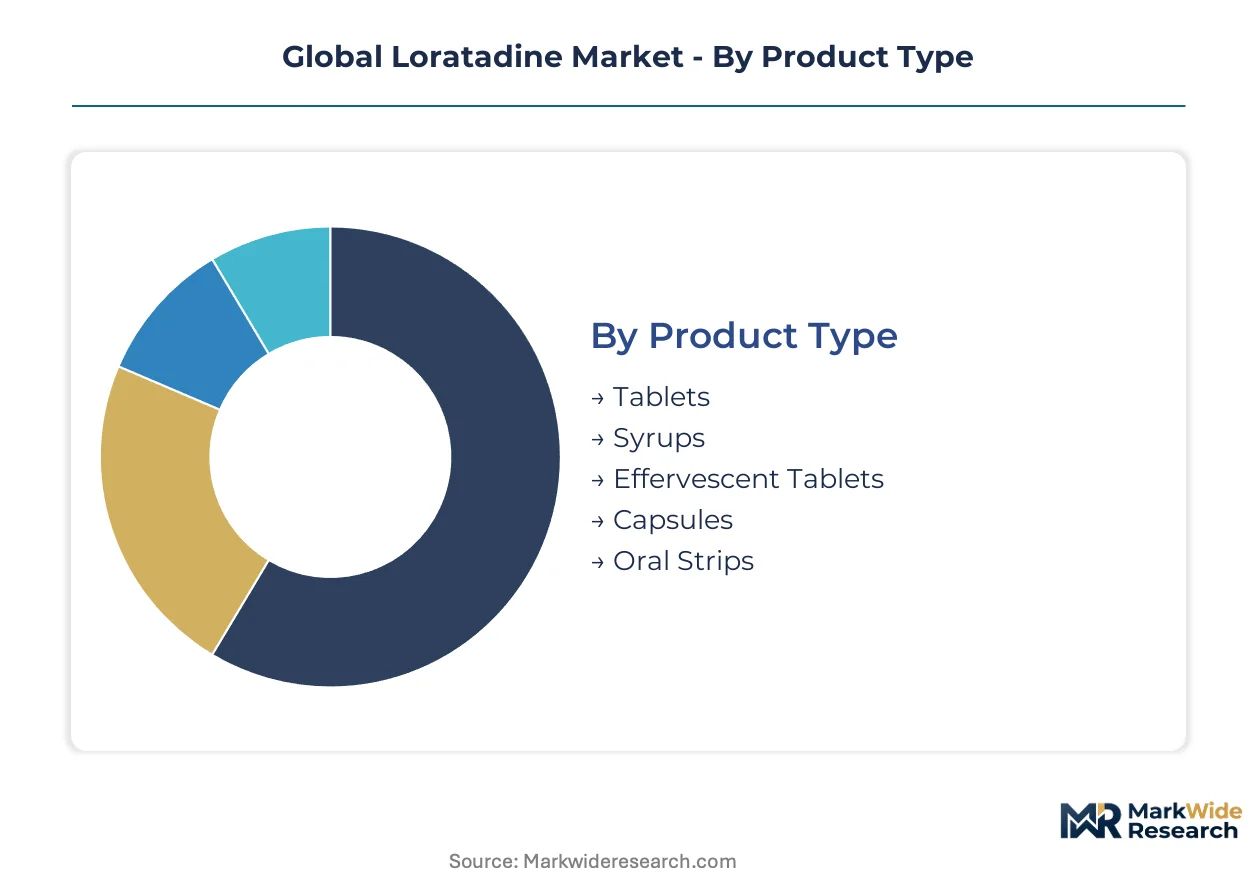
Loratadine market segmentation reveals distinct capital requirements across manufacturing modalities. Tablet production demands micronization equipment and high-speed compression lines, while oral strip technology requires solvent-casting infrastructure and specialized film-forming polymers.
Product Type:
Capital intensity varies sharply across formulation technologies, with solid dosage forms requiring the heaviest upfront investment in containment and processing equipment.
- Tablets:Compressed loratadine formulations with standardized dissolution profiles dominate production volumes. Demand concentrates in North American retail pharmacy chains where 24-hour relief positioning drives repeat purchases, though FDA dissolution specification tightening is elevating quality control costs.
- Oral Strips:Thin-film loratadine delivery systems dissolve sublingually without water. Pediatric prescriptions in Germany and Japan are expanding fastest as swallowing convenience overrides price sensitivity, with strip manufacturing requiring distinct solvent-casting lines separate from conventional solid dosage equipment.
- Syrups:Liquid loratadine suspensions with flavor masking for pediatric compliance.
- Effervescent Tablets:Rapid-dissolve formulations combining loratadine with carbonate-acid effervescence systems.
- Capsules:Hard-shell gelatin or HPMC encapsulation of loratadine granules for modified release.
Most installed capacity flows through Tablets. Expansion is steepest in Oral Strips.
Therapy Area:
Prescription volume correlates with disease prevalence and reimbursement tier positioning across national health systems.
- Allergic Rhinitis:Seasonal and perennial nasal inflammation treatment represents the foundational loratadine application. Urban air quality deterioration in Delhi, Mumbai, and São Paulo is expanding the addressable patient population, with second-generation antihistamines preferred over first-generation sedating alternatives.
- Chronic Idiopathic Urticaria:Recurrent hives of unknown origin requiring sustained antihistamine therapy. Hospital formulary placements in France and Italy are climbing as dermatology specialists favor loratadine's cardiac safety profile over cetirizine alternatives, though higher dosing requirements strain API supply contracts.
- Urticaria:Acute hive and angioedema management with shorter treatment durations.
- Conjunctivitis:Allergic eye inflammation as adjunctive therapy to topical antihistamines.
- Atopic Dermatitis:Eczema-related pruritus control in combination with topical corticosteroids.
Reimbursement concentration favors Allergic Rhinitis. Volume acceleration is strongest in Chronic Idiopathic Urticaria.
End User:
Procurement authority and patient access routes fragment the demand landscape across institutional and direct-to-consumer channels.
- Pharmacies:Community and chain pharmacy networks handle the majority of loratadine transactions. India's Apollo and MedPlus chains are scaling generic substitution programs that displace branded alternatives, while CDSCO bioequivalence certification requirements filter supplier eligibility.
- Hospitals:Inpatient and outpatient formulary procurement operates through centralized purchasing committees. German hospital consortia in Bavaria and North Rhine-Westphalia are consolidating antihistamine tenders under multi-year framework agreements that prioritize EMA environmental risk compliance documentation.
- Clinics:Physician office dispensing and sample distribution for new patient trials.
- Online Pharmacies:Verified internet-based dispensaries with prescription validation requirements.
- Retail Drug Stores:Mass merchandiser health sections with OTC self-selection.
Transaction density peaks at Pharmacies. Digital migration is advancing fastest through Online Pharmacies.
Distribution Channel:
Logistics infrastructure and cold chain requirements shape channel economics for loratadine finished goods.
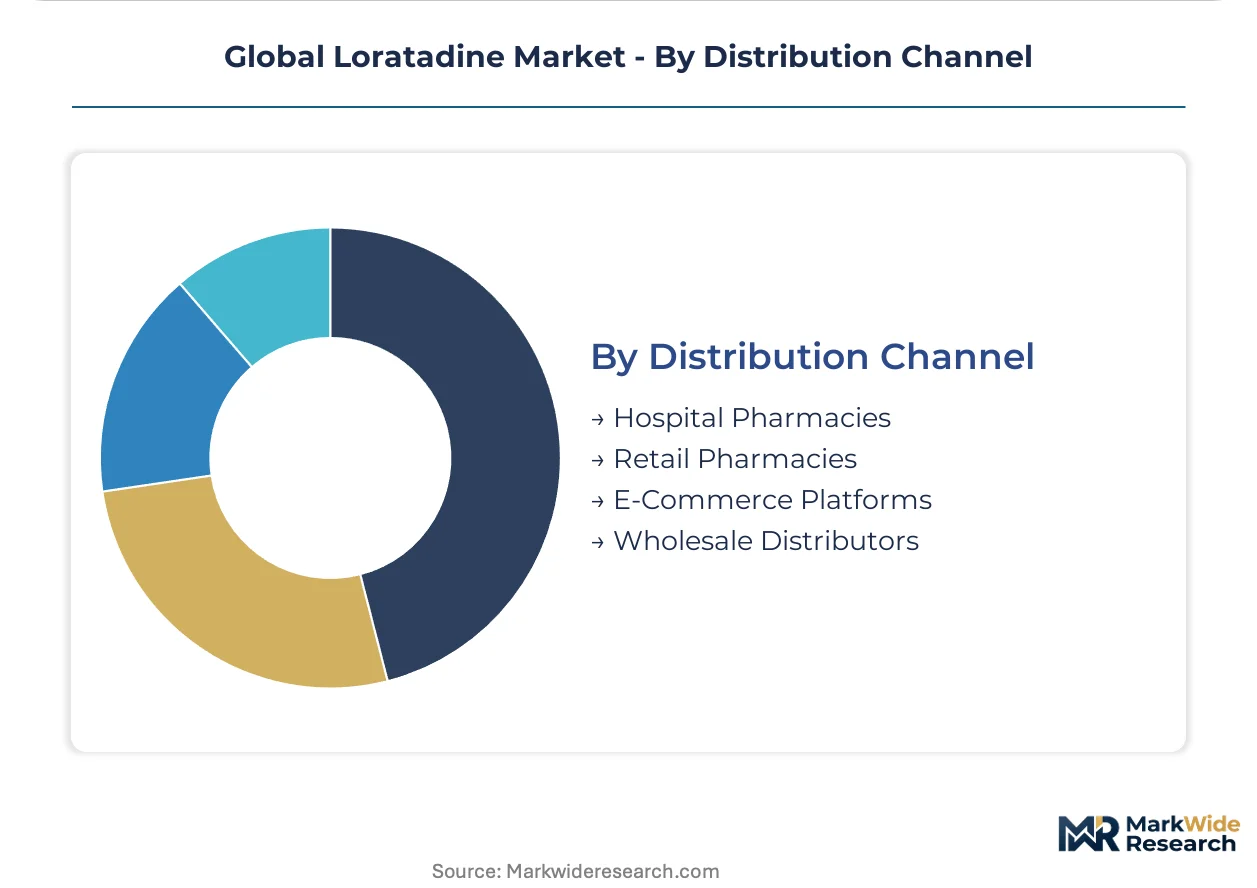
- Retail Pharmacies:Brick-and-mortar dispensaries with direct patient counseling. CVS and Walgreens in the United States leverage loyalty program data to drive chronic allergy management adherence, while inventory turns pressure working capital requirements for independent operators.
- E-Commerce Platforms:Direct-to-consumer subscription services bypass traditional wholesale markups. Amazon Pharmacy and 1mg in India are building recurring revenue models for seasonal allergy sufferers, though last-mile temperature control remains a compliance vulnerability in tropical climates.
- Hospital Pharmacies:Captive dispensing within integrated health systems.
- Wholesale Distributors:McKesson and Cardinal Health-style full-line distribution with inventory financing.
Physical throughput dominates at Retail Pharmacies. Digital penetration is climbing fastest through E-Commerce Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Second-generation antihistamine manufacturing first scaled in Western Europe during the 1980s before migrating to South Asian and East Asian production clusters. Today, loratadine API synthesis concentrates in specific industrial corridors while formulation and distribution networks span distinct national health systems.
United States
CVS and Walgreens loyalty programs drive chronic allergy medication adherence through repeat purchase incentives. FDA dissolution specification tightening elevates quality control costs for tablet manufacturers importing API. New Jersey and Pennsylvania host formulation facilities serving retail pharmacy chains with just-in-time inventory systems.
Germany
Bavarian and North Rhine-Westphalian hospital consortia consolidate antihistamine tenders under multi-year framework agreements. EMA environmental risk assessment guidelines mandate fate-and-transport modeling for API producers. Frankfurt-Rhine-Main corridor facilities install advanced oxidation wastewater treatment to meet pharmaceutical sustainability criteria.
India
Apollo and MedPlus pharmacy chains scale generic substitution programs displacing branded alternatives. CDSCO bioequivalence certification under revised Schedule Y filters supplier eligibility for export-oriented manufacturers. Hyderabad and Ahmedabad API clusters deploy process analytical technology to preempt FDA 483 observations.
China
Zhejiang and Jiangsu provinces concentrate bulk loratadine production creating single-source vulnerability for Western formulators. NMPA alignment with ICH quality guidelines accelerates domestic manufacturer internationalization. Shanghai-Pudong formulation exporters serve Southeast Asian hospital procurement systems.
Brazil
São Paulo and Rio de Janeiro retail chains show underpenetrated generic substitution policies offering volume expansion potential. ANVISA streamlined approval pathways for bioequivalent antihistamines reduce time-to-market for imported formulations. Southeast industrial pharmaceutical corridor distributors build cold chain capacity for tropical climate last-mile delivery.
Global Loratadine Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and regulatory certification tiers. The vendor base spans integrated pharmaceutical conglomerates, specialized generic manufacturers, and API-to-formulation specialists. Three archetypes dominate: backward-integrated API producers with captive tablet capacity, pure-play generic formulators sourcing merchant API, and contract manufacturing organizations serving branded marketers. Capacity expansion and EMA environmental compliance certification represent the dominant competitive moves.
Within the integrated pharmaceutical tier, Bayer AG and Pfizer Inc. occupy positions exemplifying captive API-to-formulation control. Sun Pharmaceutical Industries Ltd. anchors the generic specialist archetype with significant South Asian production presence. These three entities represent distinct strategic postures: European-headquartered conglomerate, US-based diversified pharmaceutical, and India-anchored export-oriented generic manufacturer.
| Leading Market Players |
|---|
| Bayer AG |
| Pfizer Inc. |
| Sun Pharmaceutical Industries Ltd. |
| Viatris Inc. |
| Cadila Pharmaceuticals Ltd. |
| Perrigo Company PLC |
| Teva Pharmaceutical Industries Ltd. |
| Morepen Laboratories Ltd |
| Dr. Reddy's Laboratories |
| Others |
Supply & Pricing Matrix
Piperidine and chlorobenzene derivative costs cascade through loratadine API production into three-tier pricing stratification across premium certified, standard bioequivalent, and economy unbranded tablet tiers. Western formulators absorbing petrochemical feedstock volatility from Zhejiang and Jiangsu province suppliers face compressed margins at the economy tier while EMA environmental compliance investments sustain premium positioning in European hospital procurement.
Pricing Analysis
Three-tier pricing structure across premium certified, standard bioequivalent, and economy unbranded levels dominates loratadine finished goods. Price differentiation hinges on FDA dissolution certification tier and EMA environmental risk documentation completeness. Pricing pressure stems from Indian generic substitution programs at Apollo and MedPlus chains displacing branded alternatives. Retail pharmacy loyalty program participants show lowest price sensitivity; cash-pay patients at independent dispensaries exhibit highest.
Supply Chain Analysis
Dual-sourcing requirements from FDA tightened purity standards are forcing Western formulators to qualify secondary API suppliers beyond Zhejiang and Jiangsu province concentrations. Raw material dependencies center on piperidine intermediates, chlorobenzene derivatives, and micronization-grade excipients. Single-source vulnerability concentrates in East Asian bulk synthesis clusters. Distribution runs through McKesson-style wholesale distributors with inventory financing to retail pharmacy chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The loratadine market offers margin expansion through process analytical technology deployment compressing quality assurance timelines and oral strip premium tier capture in pediatric and geriatric segments.
For Market Incumbents: Acquire solvent-casting film manufacturing lines to capture oral strip formulation premiums before patent cliff erosion. Defend against Sun Pharmaceutical and Dr. Reddy's export-oriented generic pressure by securing multi-year hospital framework agreements in Germany and France. Backward integration into piperidine intermediate production mitigates petrochemical feedstock volatility. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms bypass retail pharmacy markup capture in chronic allergy management. Brazil's ANVISA streamlined approval pathway offers lowest competitive density among major markets. White-space exists in Southeast Asian hospital procurement systems served by Shanghai-Pudong corridor exporters. For Investors and Strategic Acquirers: Consolidation pressure builds where EMA environmental compliance capex burdens fragment mid-scale European tablet manufacturers. Five-to-ten year viability favors CDSCO-certified Indian API producers with FDA pre-approval inspection records. Target acquisition archetype: Hyderabad or Ahmedabad cluster manufacturers with installed PAT systems and pending ANDA submissions. Watch FDA 483 observation rates at Indian facilities as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Process Analytical Technology Deployment | Hyderabad API clusters reduce release timelines from weeks to days preempting FDA observations. |
| EMA Environmental Compliance Certification | German hospital consortia mandate fate-and-transport modeling preferencing certified suppliers. |
| Oral Strip Formulation Capacity Addition | Pediatric prescriptions in Germany and Japan expand fastest as swallowing convenience overrides price sensitivity. |
| Direct-to-Consumer Subscription Launch | Amazon Pharmacy and 1mg build recurring revenue models bypassing traditional wholesale markups. |
| Backward Integration into Piperidine Intermediates | Captive supply of chlorobenzene derivatives insulates margin from petrochemical feedstock swings. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window combining primary discussions with regulatory affairs leads at CDSCO and FDA, hospital procurement managers in German consortia, and generic formulation executives at Indian export manufacturers with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and customs trade data. Bottom-up volume triangulation across tablet, oral strip, and syrup dosage forms reconciled against top-down value estimates.
Comparable historical reference periods anchored the projection horizon across the analysis window with segmentation modeling across dosage form, therapy area, end user channel, and regional regulatory cluster dimensions. CAGRs derived from normalized growth rate convergence across pharmaceutical antihistamine analogs. Forecast inputs incorporated CDSCO Schedule Y approval velocity and FDA dissolution specification tightening trajectories.
The model assumes a particular technology adoption path; alternative pathways for continuous manufacturing and real-time release testing would alter the outlook. Forecasts reflect documented assumptions regarding regulatory divergence intensity and API supply concentration stability. Deviation in FDA inspection intensity at Indian facilities or EMA environmental enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Systemic Lupus Erythematous SLE Drugs Market
Pharmaceuticals
Global Erythropoietin Stimulating Agents Market
Pharmaceuticals
Non-Sterile Liquids/Suspensions Market
Pharmaceuticals
Global Anorexiants Market
Pharmaceuticals
US Intravenous Immunoglobulin Market
Pharmaceuticals
Clindamycin Palmitate Hcl Market
Pharmaceuticals
Global Atherosclerosis Drugs Market
Pharmaceuticals
Global Transdermal Drug Delivery Systems Market
Pharmaceuticals
Asia-Pacific Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Adapalene Market
Pharmaceuticals
Calcitriol Capsules Market
Pharmaceuticals
Radiopharmaceutical (Oral Route) Market
Pharmaceuticals
Europe Sodium-Dependent Glucose Cotransporter 2 Market
Pharmaceuticals
Male Hypogonadism Market
Pharmaceuticals
Europe Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
Next-Generation Immunology Drugs Market