
 North America Alpha-Glucosidase Inhibitors Market | 2026-2036
North America Alpha-Glucosidase Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
North America Alpha-Glucosidase Inhibitors Market Analytics
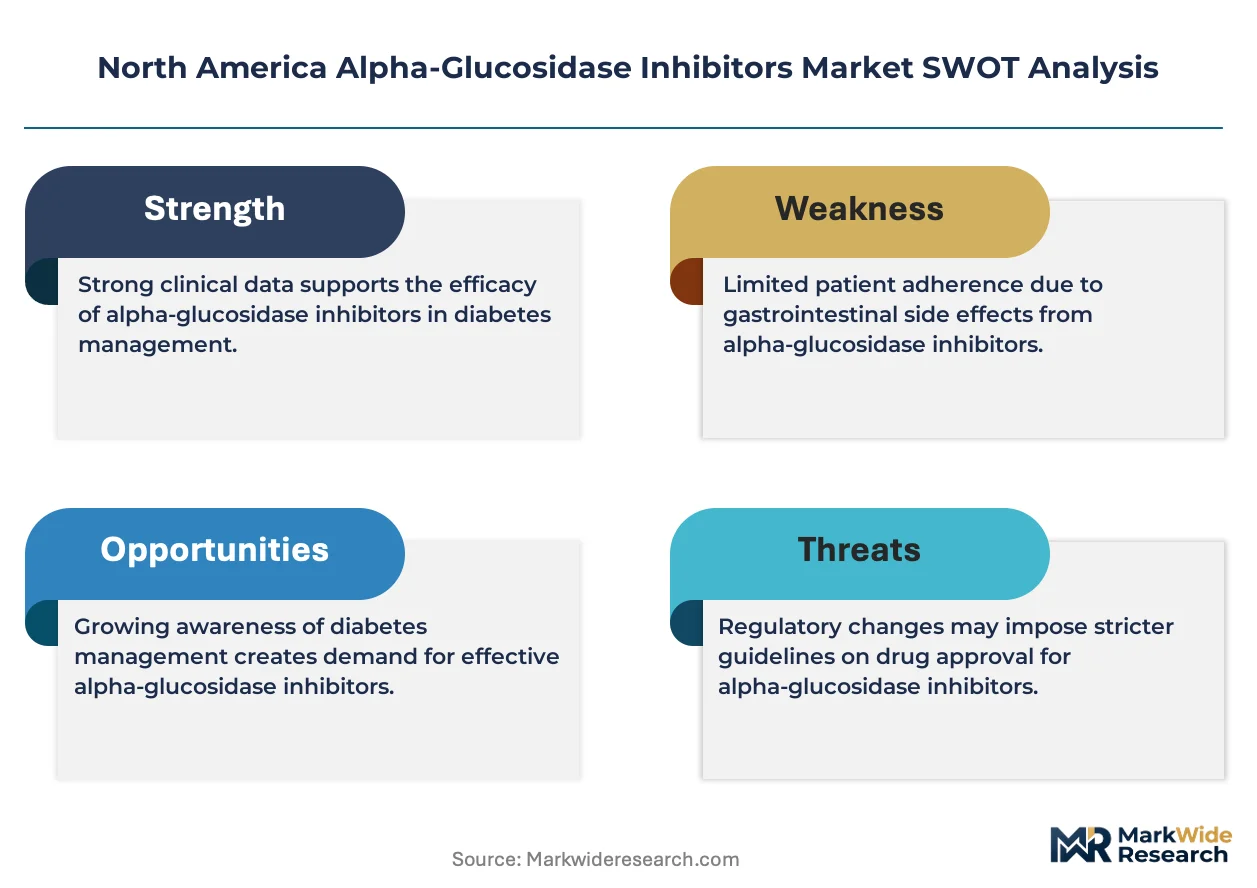
Fixed-dose combination bundling with metformin is consolidating patient preference toward simplified oral regimens in the North America alpha-glucosidase inhibitors landscape. Sun Pharmaceutical Industries Ltd. leverages its generic manufacturing scale to compete on acarbose price points across US retail pharmacies. Takeda Pharmaceutical Company Limited anchors its position through sustained R&D investment in extended-release formulations. Pfizer Inc. differentiates via hospital formulary contracts that emphasize glycemic control outcomes in perioperative settings.
Alpha-glucosidase inhibitors are oral hypoglycemic agents that competitively inhibit intestinal alpha-glucosidase enzymes, delaying carbohydrate digestion and flattening postprandial glucose excursions with typical dosing of 25-100 mg three times daily with meals. Acarbose dominates prescription volumes due to its established safety profile and broad payer coverage, while miglitol occupies a narrower niche among patients with concurrent renal impairment requiring non-renal clearance pathways. Tablet formulations lead unit sales through manufacturing economies and patient familiarity, though oral solutions gain traction in geriatric and dysphagia populations where swallowing barriers limit solid-dose adherence.
FDA bioequivalence standards for generic acarbose and CMS Medicare Part D formularies jointly determine market access and reimbursement tiers for new entrants in the United States. Health Canada’s Notice of Compliance requirements and the US Inflation Reduction Act’s drug price negotiation provisions are reshaping launch sequencing and portfolio prioritization for manufacturers active across the North American trade corridor. Stakeholders must monitor how FDA guidance on complex generic substitutability and provincial formulary harmonization in Ontario and Quebec reshape competitive dynamics for branded and generic alpha-glucosidase inhibitor portfolios.
Market Dynamics
CMS Medicare Part D formularies and FDA bioequivalence standards are restructuring competitive access for alpha-glucosidase inhibitors, forcing manufacturers to align launch sequencing with reimbursement tier negotiations rather than clinical differentiation alone.
Growth Catalysts
- Integrated Delivery Network Standardization:Hospital outpatient departments across the US Northeast corridor are embedding postprandial glucose control protocols into diabetes management pathways, expanding prescribing volume for acarbose-based regimens.
- IRA Price Negotiation Provisions:The US Inflation Reduction Act's drug pricing mechanisms are accelerating generic substitution timelines, creating volume opportunities for cost-competitive manufacturers with established manufacturing scale.
- Geriatric Formulation Demand:Oral solution formulations are capturing prescribing share among dysphagia populations and nursing home residents where tablet adherence barriers limit therapeutic compliance.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Acarbose API production concentrates among a limited set of contract manufacturers in India and China, exposing finished dose supply to geopolitical trade friction and import inspection delays.
- Renal Clearance Limitations:Miglitol's non-renal elimination pathway remains technically necessary for only a narrow subset of type 2 diabetes patients with concurrent chronic kidney disease, capping addressable patient volume.
- Fixed-Dose Combination Substitution:Metformin-SGLT2 inhibitor and metformin-DPP-4 inhibitor bundles are displacing standalone alpha-glucosidase inhibitor prescriptions in formulary preference hierarchies.
Strategic Opportunities
- Extended-Release Formulation Development:Once-daily acarbose formulations would reduce meal-timing adherence burden and capture patients currently non-compliant with three-times-daily dosing requirements.
- Provincial Harmonization in Canada:Ontario and Quebec formulary alignment initiatives are creating streamlined market access pathways for manufacturers with Health Canada Notice of Compliance and simultaneous US FDA approval.
- Perioperative Glycemic Control Contracts:Hospital systems are unbundling surgical admission protocols into discrete outcome-based purchasing agreements, creating a channel for alpha-glucosidase inhibitors with documented postprandial glucose stability data.
Industry Challenges
- Complex Generic Substitutability Guidance:FDA draft guidance on bioequivalence for modified-release alpha-glucosidase inhibitors remains unresolved, delaying ANDA submission timelines and requiring extensive pharmacokinetic bridging studies.
- Formulary Rebate Compression:PBM consolidation across the United States is compressing net pricing for oral anti-diabetic agents, forcing manufacturers to absorb margin erosion or risk exclusion from preferred tier placement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Alpha-Glucosidase Inhibitors Market |
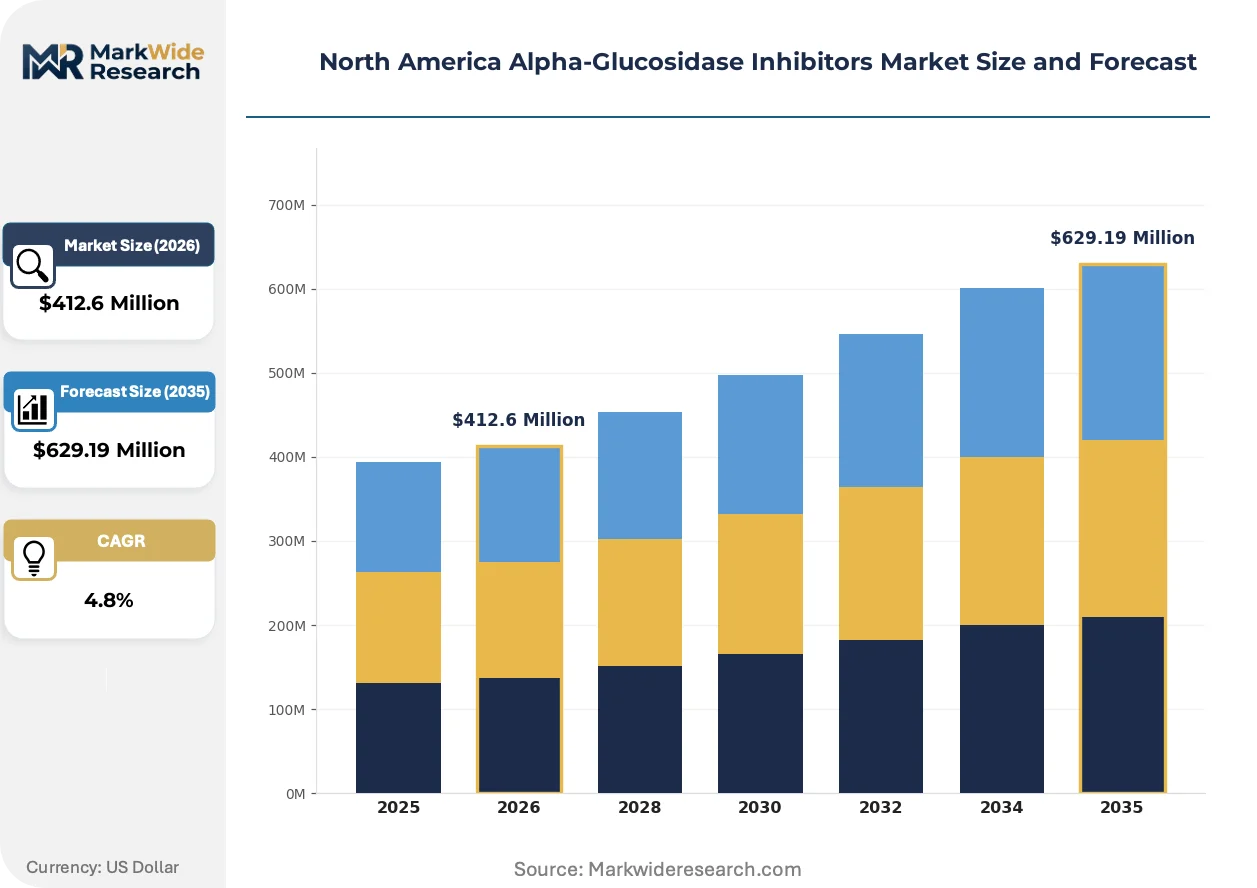
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $629.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acarbose, Miglitol, Voglibose, Others Formulation: Tablets, Capsules, Oral Solutions, Powders End User: Hospitals, Clinics, Homecare, Pharmacies Distribution Channel: Online, Offline, Direct Sales, Third-Party Distributors |
| Companies Covered | Sun Pharmaceutical Industries Ltd., Novartis AG, Takeda Pharmaceutical Company Limited, Sanofi S.A., Merck & Co., Inc., Pfizer Inc., Glenmark Pharmaceuticals Ltd., AstraZeneca PLC, Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Alpha-Glucosidase Inhibitors Market Evolving Landscape
Formulation science and reimbursement policy are jointly reshaping how alpha-glucosidase inhibitors reach patients, with technology convergence and channel restructuring overtaking traditional clinical messaging as primary competitive levers.
Continuous glucose monitoring data is converging with prescribing algorithms to identify patients with pronounced postprandial glucose excursions. Endocrinology practices in the US Midwest are adopting CGM-integrated decision support tools at accelerating rates. This technology convergence is compressing the window between glucose pattern recognition and alpha-glucosidase inhibitor initiation, shortening traditional trial-and-error dosing cycles.
The US Inflation Reduction Act's Medicare drug price negotiation program is restructuring launch sequencing for oral anti-diabetic agents. Manufacturers now prioritize indication breadth and real-world evidence generation to secure favorable maximum fair price determinations. Small-molecule portfolios with established safety databases, including acarbose generics, are responding with volume-based contracting to defend hospital formulary position against negotiated price benchmarks.
Specialty pharmacy distribution is displacing traditional retail channel fulfillment for oral anti-diabetic agents with adherence monitoring requirements. Payers are mandating 90-day dispensing through centralized mail-order facilities with integrated clinical support. This channel consolidation is most visible in Medicare Advantage plans operating across the US Southeast, where preferred network restrictions now govern alpha-glucosidase inhibitor access.
North America Alpha-Glucosidase Inhibitors Market Segmentation
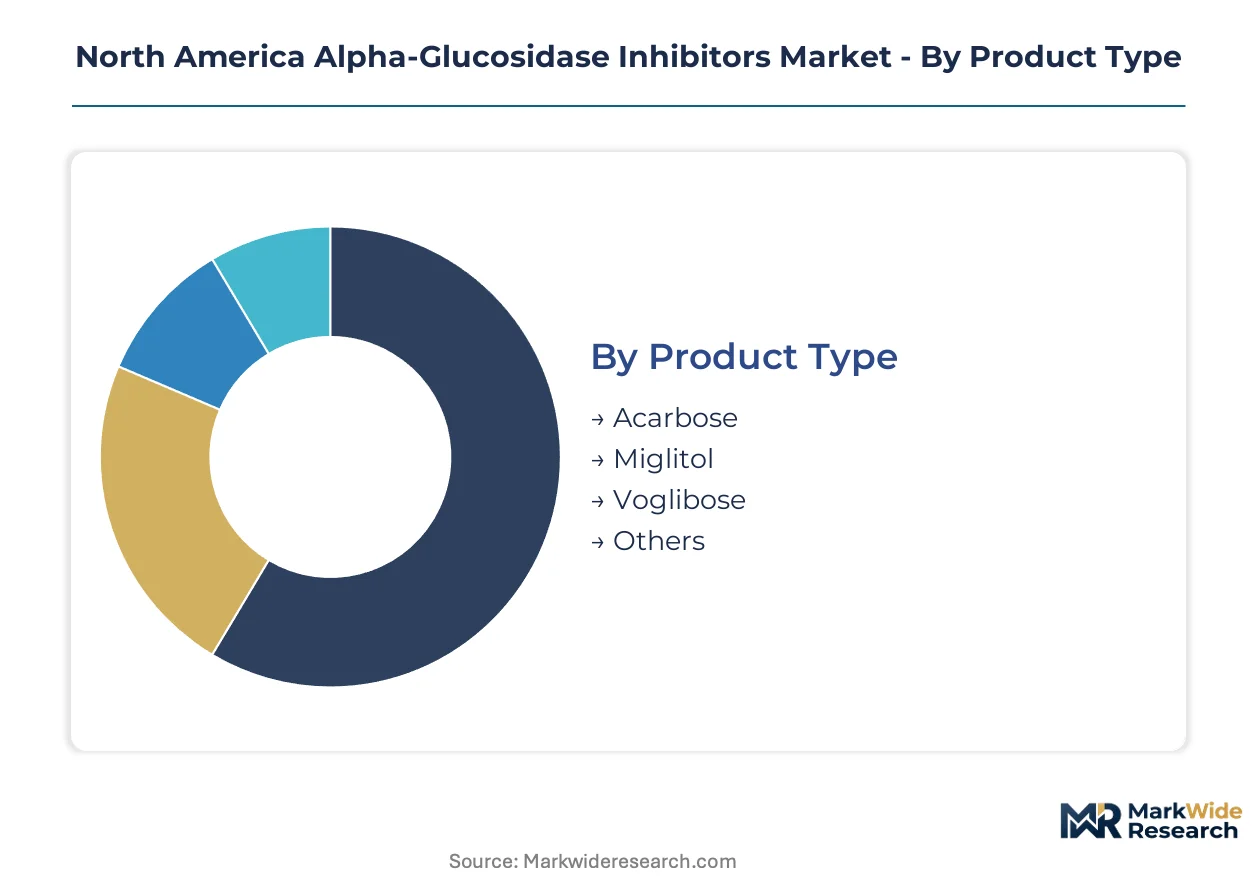
Segmentation in the North America alpha-glucosidase inhibitors market reveals how prescribing patterns diverge across clinical settings, reimbursement pathways, and patient accessibility constraints. Understanding these divides helps manufacturers align formulation development, channel strategy, and formulary negotiation priorities with where actual demand concentrates.
Product Type:
Standalone alpha-glucosidase inhibitors dominate outpatient prescribing, while combination-ready molecules anchor embedded protocols within broader diabetes management bundles.
- Acarbose:A pseudotetrasaccharide derived from Actinoplanes bacteria that competitively inhibits intestinal alpha-glucosidases with 50-100 mg dosing. US Northeast hospital outpatient departments embed acarbose into postprandial glucose control pathways, though fixed-dose combination substitution with metformin-SGLT2 bundles constrains standalone volume expansion.
- Miglitol:A desoxynojirimycin derivative with 100% non-renal clearance via intestinal metabolism, making it technically essential for type 2 diabetes patients with concurrent chronic kidney disease. Narrow addressable patient volume limits miglitol to niche formulary tiers despite its pharmacokinetic differentiation.
- Voglibose:A newer iminosugar with higher alpha-amylase selectivity and lower systemic absorption, positioned for patients experiencing gastrointestinal intolerance with first-generation agents.
- Others:Emerging iminosugar analogs and biosimilar candidates in early Health Canada and FDA review pipelines.
Acarbose leads volumes today; voglibose is gaining share fastest among patients with tolerability barriers to established agents.
Formulation:
Cost tier stratification separates high-volume tablet manufacturing from premium-positioned liquid alternatives serving accessibility-constrained populations.
- Tablets:Compressed acarbose and miglitol solid-dose forms in 25 mg, 50 mg, and 100 mg strengths leveraging decades of manufacturing scale. US retail pharmacies and Medicare Part D formularies drive tablet dominance through 90-day dispensing economics and established bioequivalence pathways for generic substitution.
- Oral Solutions:Liquid formulations with calibrated dosing syringes for patients with dysphagia, gastrostomy tubes, or advanced age-related swallowing dysfunction. Nursing home prescribing across the US Southeast and Ontario long-term care facilities is expanding oral solution share where tablet adherence barriers limit therapeutic compliance.
- Capsules:Gelatin-shell encapsulations offering taste masking and modified release potential, positioned between tablet economy and solution accessibility.
- Powders:Bulk or unit-dose sachet formulations for compounding pharmacies and specialized institutional procurement.
Tablets anchor volume economics; oral solutions climb the fastest as geriatric and institutional prescribing expands.
End User:
Customer type fragmentation splits demand between institutional procurement with outcome-based contracting and dispersed retail channels with adherence monitoring requirements.
- Hospitals:Integrated delivery networks across the US Northeast corridor standardize perioperative glycemic control protocols, creating formulary pull-through for alpha-glucosidase inhibitors with documented postprandial glucose stability data.
- Clinics:Endocrinology and primary care practices adopting CGM-integrated decision support tools, compressing the window between glucose pattern recognition and alpha-glucosidase inhibitor initiation.
- Homecare:Medicare Advantage plans mandating 90-day dispensing through centralized mail-order facilities with integrated clinical support.
- Pharmacies:Traditional retail fulfillment facing displacement by specialty pharmacy distribution for agents with adherence monitoring requirements.
Hospitals dominate value capture through outcome-based contracts; homecare channels expand most quickly under Medicare Advantage consolidation.
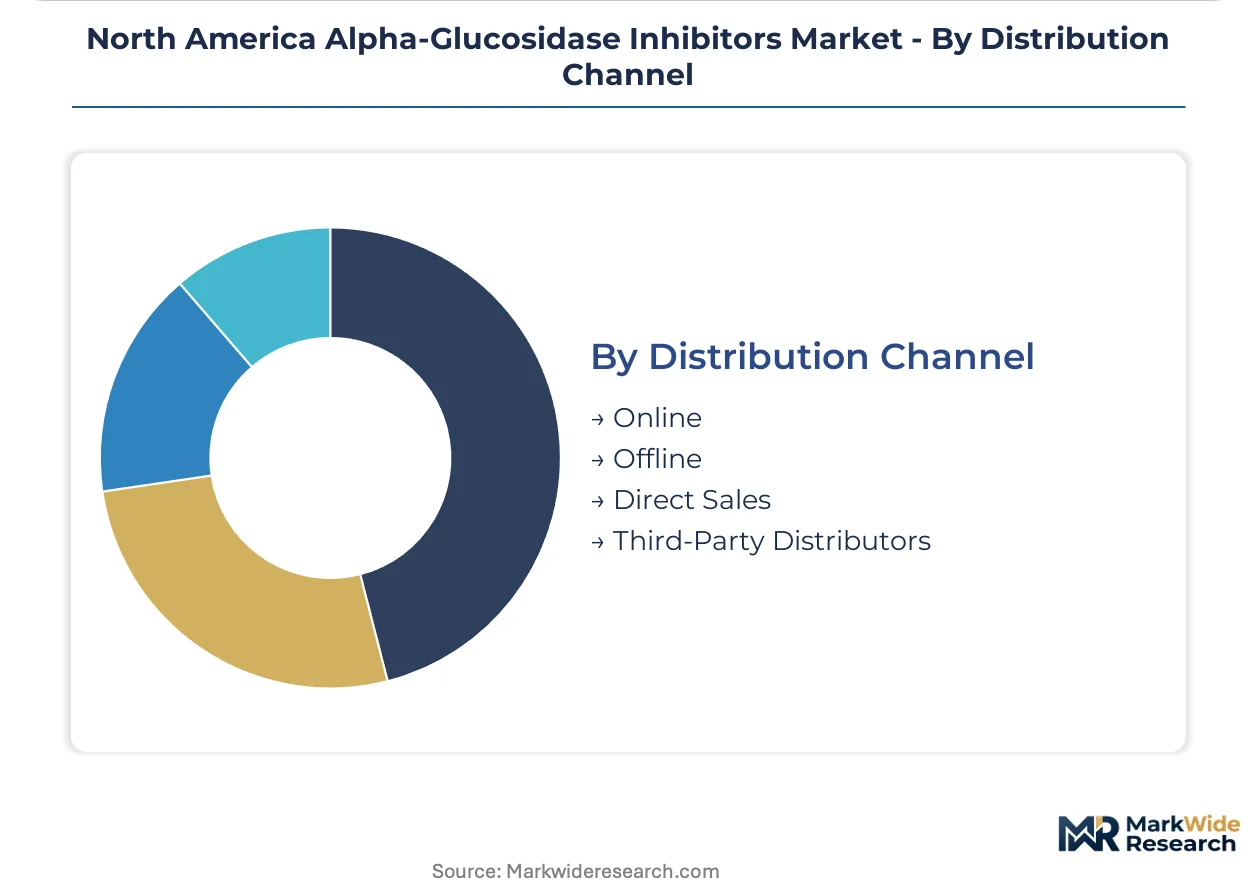
Distribution Channel:
Supply concentration among limited distribution networks is forcing manufacturers to absorb margin erosion or risk exclusion from preferred tier placement.
- Offline:Brick-and-mortar retail pharmacies and hospital outpatient dispensaries handling the majority of acute and maintenance prescriptions.
- Third-Party Distributors:Wholesalers like McKesson, AmerisourceBergen, and Cardinal Health managing inventory flow to institutional and retail endpoints across the US-Canada trade corridor.
- Online:Mail-order fulfillment through PBM-affiliated specialty pharmacies with integrated adherence monitoring, expanding under Medicare Advantage preferred network restrictions.
- Direct Sales:Manufacturer-to-institution contracting for hospital systems unbundling surgical admission protocols into discrete outcome-based purchasing agreements.
Third-party distributors handle volume throughput today; direct sales channels expand fastest as hospital systems consolidate procurement authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Alpha-glucosidase inhibitor commercialization originated in Japan during the 1980s, with Takeda's acarbose development establishing the therapeutic class before US and Canadian market entry through FDA and Health Canada approvals in the mid-1990s.
United States
Hospital outpatient departments across the Northeast corridor embed postprandial glucose control protocols into diabetes management pathways, expanding acarbose prescribing volumes. The US Inflation Reduction Act's Medicare drug price negotiation program is accelerating generic substitution timelines for oral anti-diabetic agents. Integrated delivery networks in Massachusetts and New York standardize perioperative glycemic control contracts that favor alpha-glucosidase inhibitors with documented postprandial stability data.
Canada
Ontario and Quebec formulary harmonization initiatives are streamlining market access for manufacturers with simultaneous Health Canada Notice of Compliance and US FDA approval. Provincial reimbursement adjustments in British Columbia and Alberta are reshaping portfolio prioritization for generic entrants. Long-term care facilities across Ontario are expanding oral solution prescribing for dysphagia populations where tablet adherence barriers limit therapeutic compliance.
Mexico
Federal health system procurement through the Instituto Mexicano del Seguro Social concentrates alpha-glucosidase inhibitor demand within public hospital networks serving type 2 diabetes patients. COFEPRIS regulatory alignment with FDA bioequivalence standards is facilitating generic substitution for imported acarbose formulations. Manufacturing clusters in Mexico State and Jalisco are attracting contract manufacturing organization investment for oral solid-dose production serving North American export markets.
North America Alpha-Glucosidase Inhibitors Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and hospital formulary tier placement in the North America alpha-glucosidase inhibitors landscape. Branded manufacturers with extended-release development programs and outcome-based contracting capabilities capture value above generic price-point competitors. Three archetypes dominate: large-cap pharmaceutical companies with hospital system relationships, mid-tier generic manufacturers with API-to-finished-dose integration, and specialty formulation developers serving geriatric accessibility needs. Competitive moves concentrate on direct-to-institution contracting bypassing traditional wholesale channels and portfolio diversification into combination-ready molecules for metformin bundling.
Among India-based generic manufacturers, Sun Pharmaceutical Industries Ltd. and Glenmark Pharmaceuticals Ltd. represent scale-driven archetypes competing on acarbose price points across US retail pharmacy networks. Takeda Pharmaceutical Company Limited anchors the branded-tier position through sustained investment in modified-release formulation science. Pfizer Inc. occupies a distinct position via hospital formulary contracts emphasizing perioperative glycemic control outcomes rather than outpatient volume capture.
| Leading Market Players |
|---|
| Sun Pharmaceutical Industries Ltd. |
| Novartis AG |
| Takeda Pharmaceutical Company Limited |
| Sanofi S.A. |
| Merck & Co., Inc. |
| Pfizer Inc. |
| Glenmark Pharmaceuticals Ltd. |
| AstraZeneca PLC |
| Bayer AG |
| Others |
Value Network & Pricing Analysis
Extended-release formulation development in acarbose manufacturing simultaneously compresses production costs through process intensification and concentrates technical capability among API-to-finished-dose integrated manufacturers. This dual effect reshapes competitive economics across branded and generic tiers in the North American alpha-glucosidase inhibitor landscape.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates extended-release branded formulations from immediate-release generics and commodity acarbose tablets. Price differentiation rests on FDA bioequivalence certification tier and hospital formulary contract access. Cost compression in the economy tier is intensifying because CMS Medicare Part D rebate compression forces generic manufacturers to absorb margin erosion. Retail pharmacy chains exhibit the highest price sensitivity; integrated delivery networks with outcome-based contracts show the least.
Supply Chain Analysis
Single-source vulnerability sits with Indian and Chinese contract manufacturers for acarbose active pharmaceutical ingredient. Finished dose production draws from API suppliers in India, formulation facilities in the United States, and packaging operations in Mexico. Tariff exposure on imported intermediates creates supply chain risk. Distribution runs through McKesson, AmerisourceBergen, and Cardinal Health to institutional and retail endpoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America alpha-glucosidase inhibitors market functions as a stable compounder anchored by chronic disease prevalence and recurring prescription demand for postprandial glucose management.
For Market Incumbents: Anchor hospital formulary position through perioperative glycemic control outcome contracts that demonstrate postprandial glucose stability data. Deepen backward integration into acarbose API production to insulate margin structure from Indian and Chinese supplier concentration. Defend against metformin-SGLT2 inhibitor bundle substitution by embedding alpha-glucosidase inhibitors into integrated delivery network standardization protocols across the US Northeast corridor. For New Entrants and Emerging Players: Launch via direct-to-institution contracting models that bypass McKesson and AmerisourceBergen wholesale channels. Target Ontario and Quebec provincial formulary harmonization pathways for streamlined Health Canada Notice of Compliance access. Exploit the oral solution formulation white space in US Southeast nursing home and long-term care prescribing where dysphagia populations face tablet adherence barriers. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier generic manufacturers with API-to-finished-dose integration but limited hospital formulary contract penetration. Long-term viability over the projection horizon hinges on portfolio diversification into extended-release development programs and combination-ready molecules for metformin bundling. Monitor FDA draft guidance resolution on complex generic substitutability for modified-release alpha-glucosidase inhibitors as the key inflection signal for ANDA submission timeline clarity.| Strategic Initiative | Industry Significance |
|---|---|
| Extended-Release Formulation Development | Once-daily acarbose dosing reduces meal-timing adherence burden and captures non-compliant patients. |
| Provincial Harmonization Pathway | Ontario and Quebec alignment creates streamlined Health Canada market access for dual-approved manufacturers. |
| Perioperative Glycemic Control Contract | Hospital systems unbundle surgical protocols into outcome-based purchasing favoring postprandial stability data. |
| API Backward Integration | In-house acarbose active pharmaceutical ingredient production insulates margin from Indian supplier concentration. |
| Oral Solution Formulation Launch | Liquid acarbose captures nursing home prescribing share where tablet adherence barriers limit compliance. |
Research Methodology
Direct dialogue with formulary directors, hospital procurement managers, regulatory affairs leads, and payer access specialists grounded this analysis. Secondary validation drew from FDA filings, Health Canada submissions, CMS Medicare Part D formulary databases, and clinical trial registries. Bottom-up prescription volume modeling and top-down therapeutic class expenditure analysis were triangulated against integrated delivery network protocol adoption data.
Bottom-up segmentation across product type, formulation, end user, and distribution channel dimensions were projected across the analysis window. CAGRs were derived from patient population growth, formulary placement probability, and generic substitution rate assumptions. Forecast inputs included CMS reimbursement adjustment schedules, IRA price negotiation timeline implications, and provincial harmonization completion probabilities in Canada.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA bioequivalence guidance delays and geopolitical trade friction affecting API import inspection timelines. Forecasts reflect documented assumptions regarding formulary tier placement, generic substitution elasticity, and extended-release development program success rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
US Hormone Replacement Therapy Market
Pharmaceuticals
Global Viral Vaccines Market
Pharmaceuticals
Global 3D Printed Drugs Market
Pharmaceuticals
Glycerol Fructose and Sodium Chloride Injection Market
Pharmaceuticals
Urinary Antibacterial and Antiseptic Pharmaceuticals Market
Pharmaceuticals
Global Pediatric Vaccines Market
Pharmaceuticals
Antimetabolite Drugs Market
Pharmaceuticals
Canagliflozin Market
Pharmaceuticals
Global Plasma Derived Therapy Market
Pharmaceuticals
Nefopam Hydrochloride Injection Market
Pharmaceuticals
Thin Film Drug Manufacturing Market
Pharmaceuticals
Anti-Inflammatory Biologics Market
Pharmaceuticals
Gastrointestinal OTC Drugs Market
Pharmaceuticals
Retinal Drugs and Biologics Market
Pharmaceuticals
Synthetic Drugs Market
Pharmaceuticals
Europe Small Molecule Sterile Injectable Drugs Market