
 Calcimimetic Market | 2026-2036
Calcimimetic Market Size, Share, and Industry Trends Forecast 2026-2036
Calcimimetic Market Insights
Multi-sourcing of active pharmaceutical ingredients is broadening as a strategic priority among calcimimetic developers seeking supply chain resilience. Amgen leverages its biologics manufacturing infrastructure to sustain competitive positioning in the dialysis therapy segment. Teva Pharmaceutical Industries anchors its presence through generic calcimimetic portfolios across regulated markets. AbbVie competes via specialized nephrology commercial infrastructure that extends reach into hospital-based dialysis units.
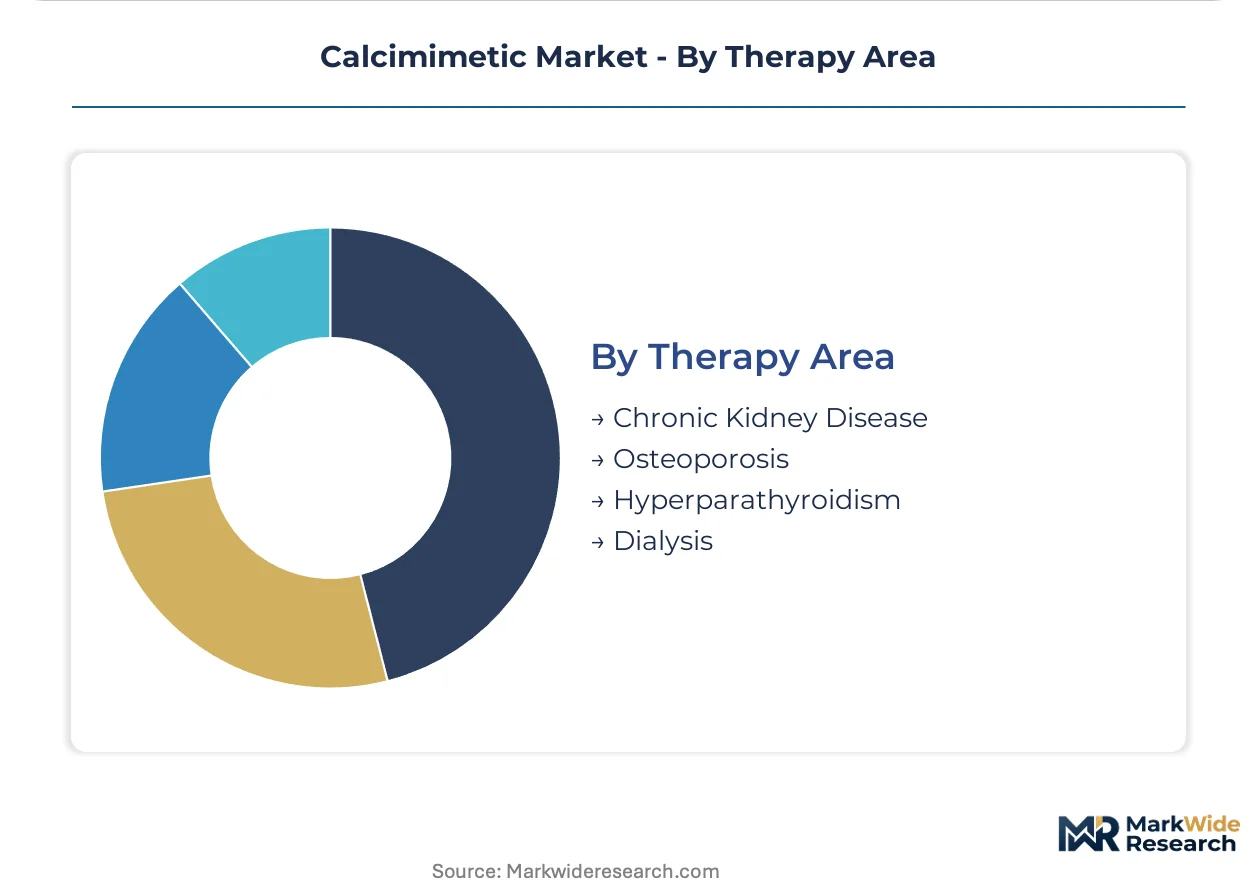
Calcimimetics constitute a class of small-molecule drugs that allosterically activate the calcium-sensing receptor (CaSR) on parathyroid cells, thereby suppressing parathyroid hormone secretion without direct vitamin D receptor agonism; their primary purpose is to manage secondary hyperparathyroidism in patients with chronic kidney disease undergoing dialysis. Capsule formulations occupy the dominant share of product type revenue due to patient compliance advantages in outpatient dialysis settings, while injectable solutions represent the fastest-growing delivery format as clinic-administered protocols expand. The therapy area segmentation reveals chronic kidney disease as the mature revenue base, with hyperparathyroidism applications emerging as the higher-margin growth vector driven by earlier intervention protocols.
FDA orphan drug designations and EMA conditional marketing authorizations shape calcimimetic development timelines and exclusivity structures across the United States and European Union. The EU MDR and FDA's updated bioequivalence guidance for narrow therapeutic index products impose additional validation requirements on generic entrants. Stakeholders must monitor evolving CMS reimbursement benchmarks for oral versus intravenous calcimimetics within bundled dialysis payment models to anticipate prescribing shifts.
Market Dynamics
CMS reimbursement benchmarks for oral versus intravenous calcimimetics within bundled dialysis payment models are forcing manufacturers to recalibrate commercial strategy and formulation development priorities.
Growth Catalysts
- Medicare bundled payment frameworks:The United States reimbursement structure creates substantial pull-through for calcimimetic prescribing in outpatient dialysis centers, anchoring volume concentration in this channel.
- Injectable formulation protocols:Clinic-administered delivery formats are displacing oral capsules in hospital-based dialysis units, expanding addressable patient populations through simplified compliance monitoring.
- Secondary hyperparathyroidism intervention:Earlier-stage therapeutic protocols in chronic kidney disease management are broadening the eligible patient base beyond end-stage renal failure.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient sourcing remains concentrated among a limited cohort of contract manufacturers, exposing developers to single-point-of-failure risks.
- Narrow therapeutic index bioequivalence requirements:FDA guidance imposes additional validation burdens on generic entrants, extending development timelines and elevating regulatory capital requirements.
- Vitamin D analog substitution:Established phosphate binder and vitamin D receptor agonist therapies retain formulary preference in certain European markets, compressing calcimimetic access.
Strategic Opportunities
- Hyperparathyroidism surgical alternatives:Non-dialysis applications for primary hyperparathyroidism represent an underpenetrated indication with higher reimbursement rates and less crowded competitive dynamics.
- EMA conditional marketing authorizations:Accelerated approval pathways in the European Union enable earlier revenue recognition for novel CaSR allosteric modulators in orphan indications.
- Home dialysis expansion:Patient-administered oral formulations align with the shift toward peritoneal dialysis and home hemodialysis modalities in the United States and Japan.
Industry Challenges
- CaSR pharmacology expertise scarcity:Specialized medicinal chemistry and clinical pharmacology capabilities for allosteric GPCR modulation remain concentrated among a limited talent pool, constraining R&D expansion.
- EU MDR technical documentation:Updated medical device and combination product regulations impose extended conformity assessment timelines for drug-device delivery systems.
- Legacy EHR integration:Pharmacy and laboratory data interoperability gaps between dialysis clinic management systems and hospital networks complicate real-time therapeutic monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcimimetic Market |
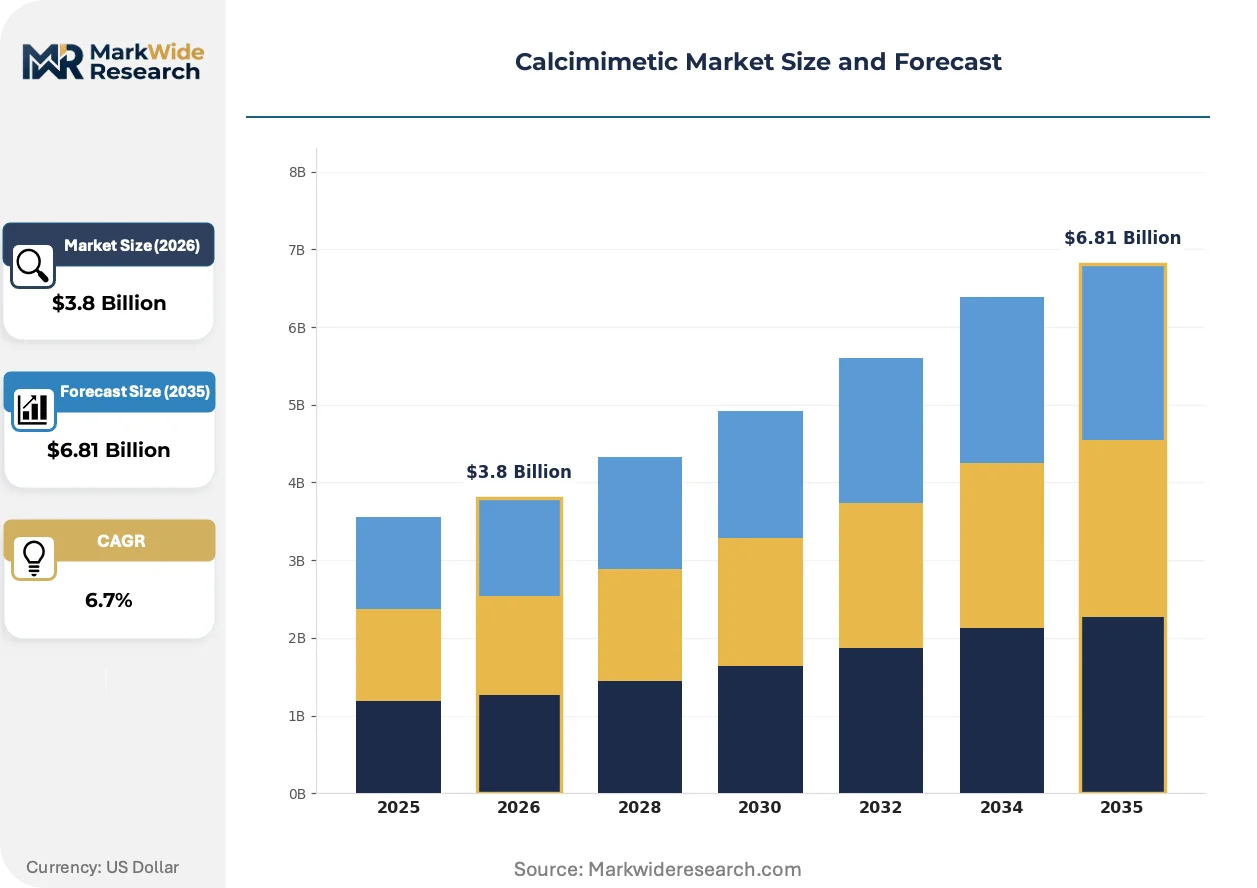
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Tablets, Injectable Solutions, Oral Solutions End User: Hospitals, Specialty Clinics, Homecare Settings, Pharmacists Delivery Mode: Intravenous, Oral, Subcutaneous, Topical Therapy Area: Chronic Kidney Disease, Osteoporosis, Hyperparathyroidism, Dialysis |
| Companies Covered | Amgen, Teva Pharmaceutical Industries, AbbVie, Sandoz, Bristol-Myers Squibb, Eli Lilly, Ono Pharmaceutical, Gilead Sciences, OPKO Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcimimetic Market Trends and Innovations
Calcimimetic development trajectories are converging around three vectors: delivery format innovation, regulatory pathway optimization, and care setting migration toward outpatient and home-based administration.
Long-acting parenteral calcimimetic formulations are expanding into monthly and quarterly dosing schedules. Dialysis center networks in the United States are piloting these extended-interval protocols to reduce nursing burden and improve patient adherence. This technology is compressing the competitive relevance of daily oral regimens in clinic-administered settings.
EMA's updated guidance on clinical investigation of medicinal products in chronic kidney disease is reshaping trial endpoint selection and patient stratification requirements. Developers must now demonstrate cardiovascular outcome benefits alongside parathyroid hormone suppression metrics. This regulatory recalibration most acutely affects Phase III programs targeting European Union market entry, where conditional authorization timelines now hinge on adaptive trial designs.
Hospital procurement consortia are consolidating calcimimetic purchasing decisions under centralized pharmacy and therapeutics committees. Independent dialysis operators face margin compression as group purchasing organizations negotiate exclusive supply agreements with selected manufacturers. This concentration is most visible in the United States, where vertically integrated dialysis providers are internalizing formulary control across their clinic networks.
Calcimimetic Market Segmentation
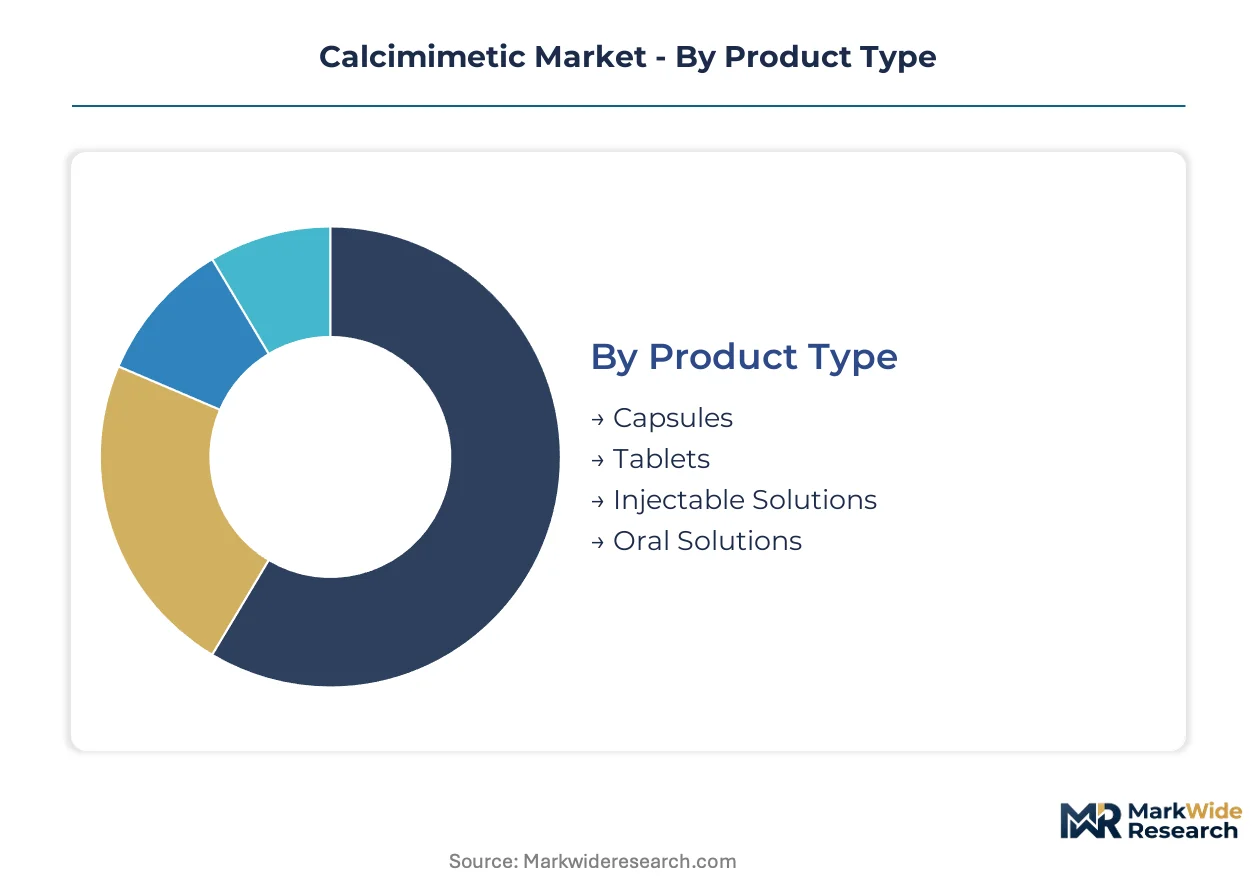
Calcimimetic segmentation reveals how formulation choices, delivery settings, and therapeutic applications concentrate capital deployment and determine margin structures. Manufacturers must align R&D investment with the specific compliance and reimbursement requirements of each segment cluster.
Product Type:
Injectable solutions demand the heaviest upfront manufacturing investment due to sterile fill-finish requirements and cold-chain infrastructure.
- Capsules:Hard-shell gelatin or HPMC encapsulation of CaSR allosteric modulators enables outpatient self-administration. Dialysis centers in the United States favor this format for Medicare-reimbursed take-home prescribing, though adherence monitoring remains a clinical challenge.
- Injectable Solutions:Sterile parenteral formulations require aseptic processing and validated stability protocols. Hospital-based dialysis units in Germany and Japan are transitioning toward clinic-administered injection protocols that simplify nursing workflows and reduce pill burden.
- Tablets:Compressed solid dosage forms with film coating for moisture protection. Compact packaging supports pharmacy inventory efficiency.
- Oral Solutions:Liquid formulations for patients with dysphagia or pediatric indications. Requires flavor masking and preservative systems.
Capsules absorb the bulk of installed capacity; injectable solutions are expanding most quickly.
End User:
Customer concentration varies sharply by procurement sophistication and formulary control mechanisms.
- Hospitals:Integrated delivery networks with centralized pharmacy and therapeutics committees negotiate exclusive supply agreements. These institutions in France and the United Kingdom prioritize CaSR pharmacology expertise when selecting therapeutic protocols.
- Specialty Clinics:Nephrology-focused outpatient facilities with direct dialysis service integration. Clinic administrators in Italy balance nursing burden against patient adherence outcomes when selecting between oral and parenteral protocols.
- Homecare Settings:Patient-administered therapy environments aligned with peritoneal dialysis growth. Requires simplified dosing regimens and remote monitoring compatibility.
- Pharmacists:Retail and specialty pharmacy channels managing prior authorization workflows. Reimbursement verification complexity shapes dispensing patterns.
Hospitals command the largest procurement volumes; homecare settings are climbing the fastest as modality shifts accelerate.
Delivery Mode:
Route of administration determines bioequivalence study design and regulatory capital requirements.
- Intravenous:Direct vascular delivery in hemodialysis suites ensures complete bioavailability. Dialysis providers in Spain and Australia pilot extended-interval protocols to reduce nursing contact time.
- Oral:Gastrointestinal absorption with food-effect considerations. Capsule and tablet formats dominate outpatient prescribing.
- Subcutaneous:Depot formulations enabling weekly or monthly dosing. Requires patient training for self-injection.
- Topical:Transdermal patches under investigation for CaSR modulation. Early-stage development with unproven pharmacokinetic profiles.
Oral delivery retains the steepest volume base; intravenous administration is gaining share fastest in clinic-consolidated networks.
Therapy Area:
Indication selection dictates trial endpoint requirements and exclusivity timeline structures.
- Chronic Kidney Disease:Established indication with validated parathyroid hormone suppression endpoints. Dialysis-dependent populations in the United States and Japan generate predictable demand under reimbursement frameworks.
- Hyperparathyroidism:Earlier intervention protocols in non-dialysis patients command premium pricing. Surgical alternatives create competitive pressure in tertiary care centers.
- Osteoporosis:Adjunctive therapy applications with calcium homeostasis benefits. Requires separate skeletal outcome trials.
- Dialysis:Procedure-integrated administration within end-stage renal disease treatment bundles. CMS payment models directly influence prescribing thresholds.
Chronic kidney disease anchors the revenue base; hyperparathyroidism applications show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States dialysis centers generate the steepest prescription volumes for calcimimetic therapies, with Medicare bundled payment models directly shaping manufacturer commercial strategy. Demand clusters around vertically integrated dialysis networks in Texas, California, and Florida, where outpatient hemodialysis expansion continues.
United States
CMS reimbursement benchmarks for oral versus intravenous calcimimetics within bundled dialysis payment models force manufacturers to recalibrate formulation priorities. FDA orphan drug designations accelerate development timelines for novel CaSR allosteric modulators. Dallas-Fort Worth and Houston dialysis corridor networks pilot extended-interval injectable protocols to reduce nursing burden.
Germany
Hospital-based dialysis units in Bavaria and North Rhine-Westphalia transition toward clinic-administered injection protocols that simplify nursing workflows. EMA conditional marketing authorizations enable earlier revenue recognition for novel therapies targeting orphan indications. Berlin and Munich nephrology centers consolidate purchasing decisions under centralized pharmacy committees.
Japan
Home hemodialysis and peritoneal dialysis modality shifts drive demand for patient-administered oral formulations with simplified dosing regimens. PMDA regulatory frameworks for chronic kidney disease therapies emphasize cardiovascular outcome endpoints alongside parathyroid hormone suppression. Osaka and Nagoya specialty clinics expand remote monitoring compatibility for home-based calcimimetic administration.
United Kingdom
NHS England integrated care systems negotiate calcimimetic procurement through centralized pharmacy and therapeutics frameworks. MHRA post-Brexit regulatory autonomy permits tailored approval pathways for narrow therapeutic index products. London and Manchester hospital networks prioritize CaSR pharmacology expertise when selecting therapeutic protocols for secondary hyperparathyroidism.
France
ANSM oversight of combination product regulations imposes extended conformity assessment timelines for drug-device delivery systems in dialysis settings. Regional hospital procurement consortia in Île-de-France and Auvergne-Rhône-Alpes consolidate purchasing power for nephrology therapeutics. Lyon and Paris tertiary care centers evaluate surgical alternatives for primary hyperparathyroidism against calcimimetic medical management.
Calcimimetic Market Competitive Landscape
Portfolio diversification dominates the current landscape as established nephrology players expand beyond single-molecule dependence. The vendor base concentrates around three strategic archetypes: biologics manufacturers with dialysis therapy infrastructure, generic pharmaceutical specialists with narrow therapeutic index expertise, and diversified pharma groups with nephrology commercial reach. M&A activity and strategic partnerships represent the primary competitive moves, with manufacturers seeking CaSR pharmacology capabilities and regional market access.
Within the biologics-dominant tier, Amgen anchors its position through manufacturing infrastructure calibrated for dialysis service integration. Among generic specialists, Teva Pharmaceutical Industries occupies a position exemplifying regulatory capital deployment for narrow therapeutic index bioequivalence validation. On the diversified pharmaceutical vector, AbbVie represents the archetype of nephrology commercial infrastructure extending into hospital-based dialysis units. These three entities collectively illustrate how formulation expertise, regulatory navigation, and channel-specific reach determine competitive standing.
| Leading Market Players |
|---|
| Amgen |
| Teva Pharmaceutical Industries |
| AbbVie |
| Sandoz |
| Bristol-Myers Squibb |
| Eli Lilly |
| Ono Pharmaceutical |
| Gilead Sciences |
| OPKO Health |
| Others |
Pricing and Supply Chain Analysis
CaSR medicinal chemistry specialists concentrated in Boston and Basel command compensation premiums that compress margins on standard-grade calcimimetics while widening spreads between premium validated formulations and economy-tier alternatives. Labor-cost differentials between these talent clusters and emerging APAC research hubs directly translate into pricing-tier architecture across the industry.
Pricing Analysis
Warranty-backed bioequivalence validation services bundle with premium calcimimetic tiers, while economy formulations ship unbundled with buyer-assumed regulatory risk. Three-tier pricing structure across premium, standard, and economy levels segments by FDA bioequivalence documentation depth and cold-chain integrity guarantees. Cost compression in the standard tier is intensifying because hospital procurement consortia negotiate volume rebates that strip service components. Dialysis center networks exhibit the sharpest price sensitivity; specialty nephrology clinics with orphan drug protocols show the least.
Supply Chain Analysis
Cold-chain freight costs from API manufacturing clusters in India and China to sterile fill-finish facilities in Germany and the United States absorb disproportionate working capital. Active pharmaceutical ingredient production draws from Indian contract manufacturers and Chinese chemical synthesis hubs, with final dosage form conversion anchored in German and Swiss sterile processing plants. Single-source vulnerability concentrates in CaSR allosteric modulator precursor supply. Distribution runs through vertically integrated dialysis provider networks and hospital purchasing consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
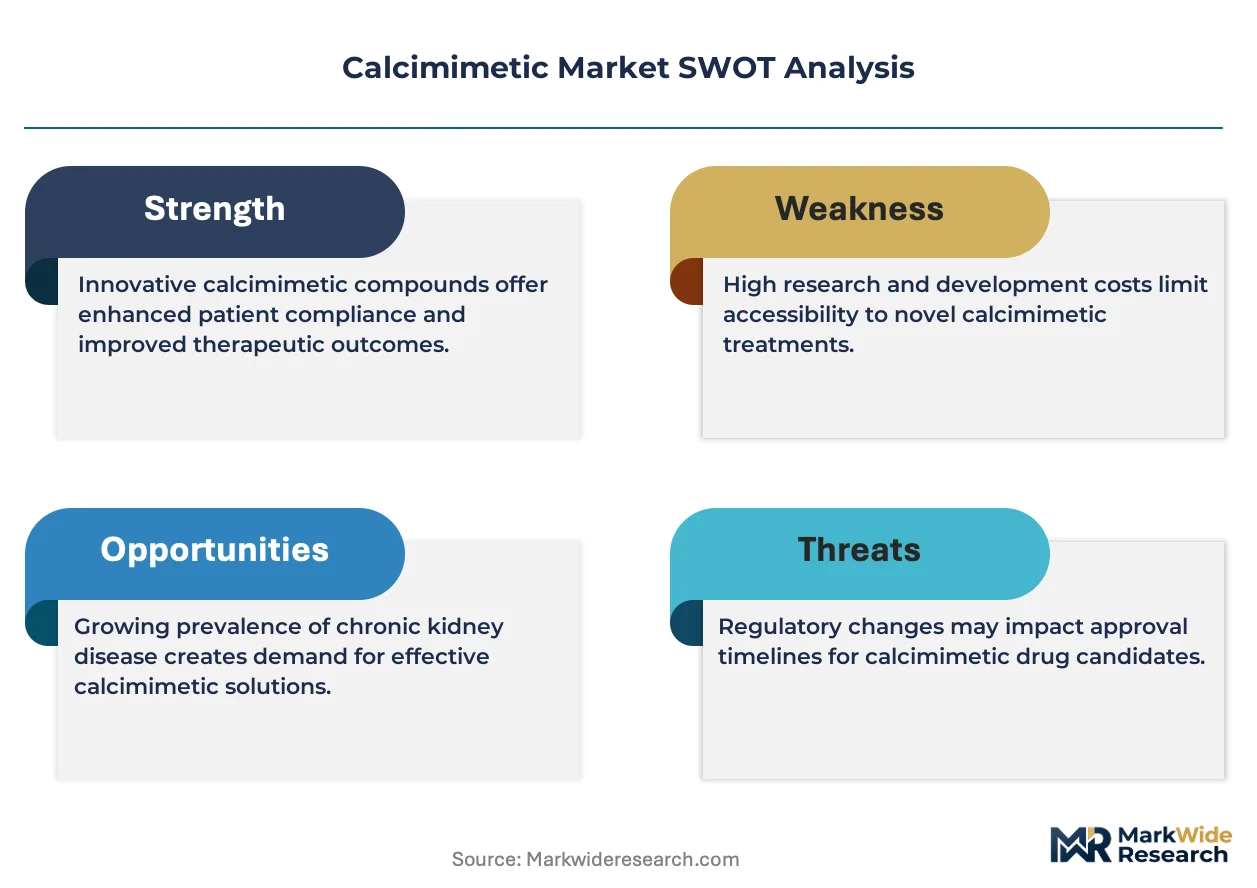
This market functions as a cost-of-compliance story where FDA narrow therapeutic index bioequivalence guidance erects a barrier-to-entry moat that rewards players with validated regulatory capital deployment.
For Market Incumbents: Hedge against vitamin D analog substitution threats by deepening backward integration into CaSR pharmacology talent pools in Boston and Basel. Anchor capacity addition in German sterile fill-finish corridors to secure EMA conditional authorization timelines. Prioritize certification investment for extended-interval parenteral formulations that displace daily oral regimens in hospital-based dialysis units. For New Entrants and Emerging Players: Capture white-space in primary hyperparathyroidism surgical alternatives, where reimbursement rates exceed dialysis-dependent indications and competitive density remains sparse. Target home dialysis modality shifts in Japan and the United States with patient-administered oral formulations featuring remote monitoring compatibility. Lead with simplified prior authorization workflows as the go-to-market angle to bypass entrenched hospital formulary control. For Investors and Strategic Acquirers: The window for entry favors mid-cap specialists with captive CaSR medicinal chemistry capabilities and EMA regulatory track records. Long-term viability hinges on portfolio diversification beyond single-molecule dependence toward delivery format innovation. Watch CMS reimbursement benchmark revisions for oral versus intravenous calcimimetics as the inflection signal for prescribing shift magnitude.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA orphan drug designation accelerates exclusivity timelines for novel CaSR modulators. |
| Manufacturing Scale-Up | Sterile fill-finish capacity expansion in German corridors secures EMA conditional authorizations. |
| Pipeline Diversification | Primary hyperparathyroidism indications command premium pricing outside dialysis bundles. |
| Long-term Supply Agreement | Exclusive API sourcing contracts with Indian manufacturers mitigate single-point-of-failure risk. |
| Reimbursement Strategy | CMS bundled payment alignment determines formulary placement in vertically integrated dialysis networks. |
Research Methodology
Document review covered FDA bioequivalence guidance documents, EMA conditional marketing authorization frameworks, and CMS reimbursement benchmark filings, complemented by interviews with drug development executives, regulatory affairs leads, formulary directors at dialysis provider networks, and hospital procurement managers. Secondary validation drew from ClinicalTrials.gov endpoint specifications, SEC 10-K nephrology segment disclosures, and formulary database extracts. Bottom-up prescription volume modeling triangulated against top-down market sizing from reimbursement claims analysis.
Output projections segment by product type, delivery mode, therapy area, and regional regulatory cluster across the analysis window. CAGR derivation rested on dialysis patient population forecasts, modality shift assumptions, and CMS policy scenario weighting. Model inputs incorporated parathyroid hormone suppression endpoint evolution, cardiovascular outcome trial requirements, and bundled payment penetration curves.
The model holds under stable CMS reimbursement frameworks and EMA regulatory continuity; deviation in FDA bioequivalence guidance stringency or API export restriction policies would shift volume trajectories. Stakeholders should weight assumptions against their own operating context and regulatory risk tolerance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Dengue Vaccine Market
Pharmaceuticals
China Opioids Market
Pharmaceuticals
Sodium Aescinate Market
Pharmaceuticals
Targeted Therapeutics Market
Pharmaceuticals
North America Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
Chemotherapy-Induced Nausea and Vomiting (CINV) Treatment Market
Pharmaceuticals
Pharmaceutical Grade Lactose Market
Pharmaceuticals
North America Travel Vaccines Market
Pharmaceuticals
Amoxicillin Drugs Market
Pharmaceuticals
Pharmacy Dark Store Market
Pharmaceuticals
Alopecia Drugs Market
Pharmaceuticals
Global Gastroparesis Drug Market
Pharmaceuticals
Long-Acting Beta-Agonists Market
Pharmaceuticals
Bispecific Antibody Therapeutics Contract Manufacturing Market
Pharmaceuticals
US Oral Solid Dosage Contract Manufacturing Market
Pharmaceuticals
Valganciclovir Market