
 Hyperphosphatemia Drugs Market | 2026-2036
Hyperphosphatemia Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Hyperphosphatemia Drugs Market Intelligence
The EU Green Deal is restructuring pharmaceutical procurement standards across European healthcare systems, pushing manufacturers toward lower-carbon production pathways for renal therapies. Sanofi leverages its integrated manufacturing network to sustain supply continuity for phosphate binders across multiple continents. Amgen anchors its position through deep specialization in calcimimetic therapies for secondary hyperparathyroidism, a frequent comorbidity. Takeda Pharmaceutical Company Limited competes aggressively in the Asia-Pacific dialysis market through established nephrology partnerships.
Hyperphosphatemia drugs encompass pharmaceutical agents that bind, suppress, or counteract excess serum phosphate in patients with impaired renal clearance, typically formulated as calcium-based or non-calcium-based polymer complexes administered in 800-2400 mg daily doses. These agents prevent metastatic calcification, cardiovascular mortality, and bone mineral disorders in end-stage renal disease populations. Phosphate binders dominate current revenue pools due to entrenched prescribing habits and broad reimbursement coverage, while calcimimetics represent the fastest-expanding category as cinacalcet generics and etelcalcetide adoption penetrate dialysis protocols. The tablets formulation segment occupies the largest volume share, though liquid preparations are gaining traction in pediatric and geriatric homecare settings where swallowing difficulties complicate compliance.
FDA oversight of new drug applications and post-market safety surveillance shapes clinical trial design and label expansion strategies for hyperphosphatemia therapies in the United States. EMA's MDR and REACH frameworks impose additional manufacturing quality and environmental discharge standards on European suppliers. China's NMPA accelerates local market access for imported renal drugs through priority review pathways. Stakeholders must monitor evolving phosphate binder reimbursement tiers and the clinical readout from next-generation iron-based binders to anticipate portfolio rebalancing requirements.
Market Dynamics
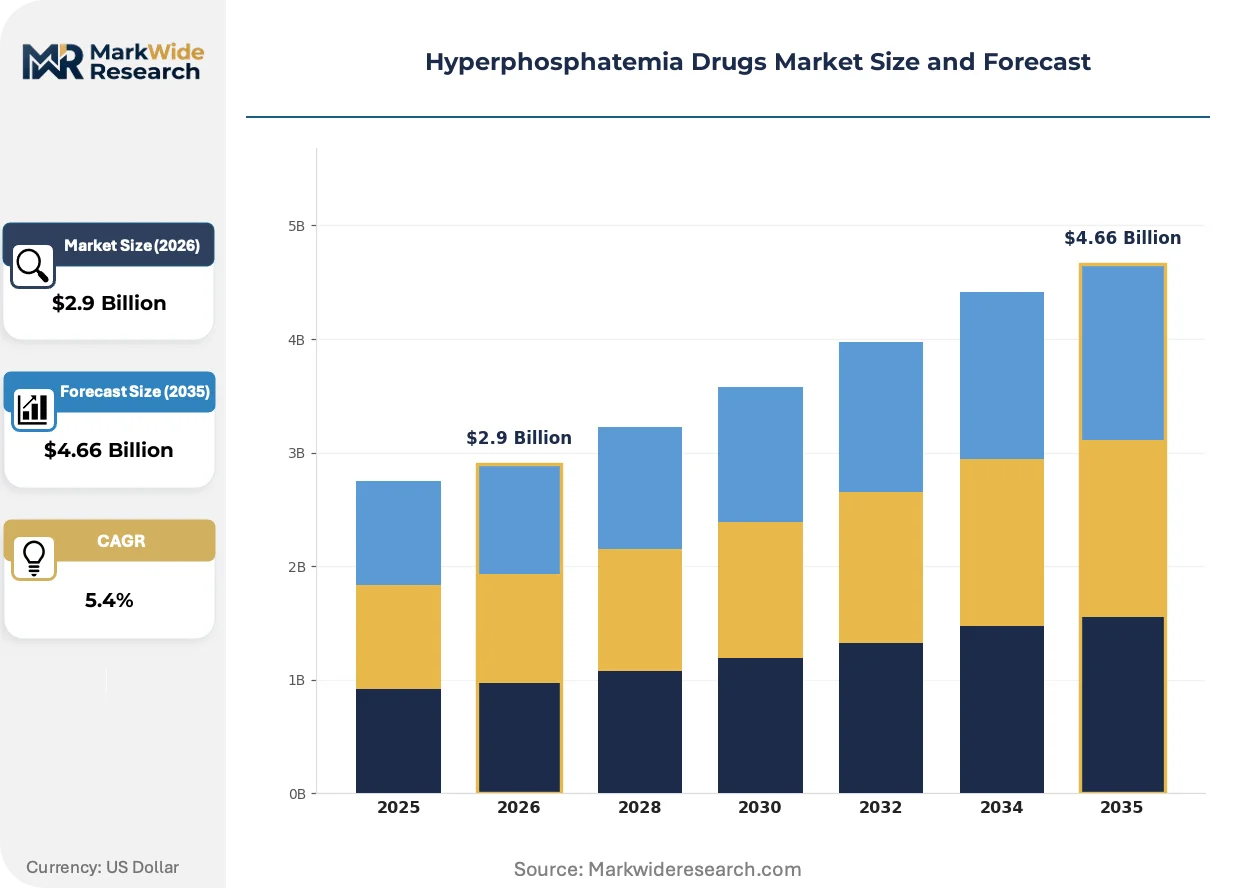
The dialysis-dependent patient population is concentrating demand for phosphate binders around integrated care networks, while Medicare reimbursement tiers and EU Green Deal procurement mandates simultaneously reshape manufacturer priorities toward carbon-efficient production pathways.
Growth Catalysts
- ESKD Prevalence Trajectory:The expanding end-stage kidney disease population in the United States drives consistent phosphate binder utilization through Medicare-covered dialysis protocols.
- REACH Compliance Deadlines:European pharmaceutical manufacturers are retrofitting renal drug production facilities to meet ECHA environmental discharge standards ahead of 2030 enforcement windows.
- Calcimimetic Protocol Expansion:Etelcalcetide adoption in intravenous dialysis settings is displacing oral cinacalcet in high-burden secondary hyperparathyroidism cases.
Market Restraints
- Sevelamer Carbonate Cost Volatility:Polymer feedstock prices for non-calcium binders fluctuate with petrochemical supply disruptions.
- Active Pharmaceutical Ingredient Concentration:China dominates precursor chemical manufacturing for iron-based binders, creating single-source vulnerability.
- Calcium Accumulation Ceiling:Cardiovascular calcification risks limit long-term calcium acetate dosing in high-burden patients.
Strategic Opportunities
- Pediatric Formulation Gap:Liquid phosphate binder development for children with congenital renal disorders remains underaddressed in North American markets.
- Home Hemodialysis Expansion:Patient-managed dialysis protocols create demand for simplified binder regimens with reduced pill burden.
- EU Green Deal Procurement Incentives:Carbon-labeled manufacturing credentials unlock preferred supplier status in German and French hospital purchasing consortia.
Industry Challenges
- Nephrology Specialist Scarcity:Training pipeline gaps for renal pharmacology expertise delay protocol optimization in community dialysis centers.
- Multi-Regional Registration Complexity:Divergent FDA, EMA, and NMPA stability testing requirements extend filing timelines for novel polymer formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hyperphosphatemia Drugs Market |
| Market Size in 2026 | $2.9 Billion |
| Market Size in 2035 | $4.66 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phosphate Binders, Active Vitamin D, Calcimimetics, Others Formulation: Tablets, Liquids, Granules, Injectable End User: Hospitals, Dialysis Centers, Homecare, Pharmacy Delivery Mode: Oral, Parenteral, Intravenous, Others |
| Companies Covered | Sanofi, Akebia Therapeutics, CSL, Ardelyx, Unicycive Therapeutics, Takeda Pharmaceutical Company Limited, Vifor Pharma, Amgen, Lupin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hyperphosphatemia Drugs Market Strategic Shifts & Innovations
Renal therapy development is pivoting toward binder technologies that reconcile phosphate control with cardiovascular risk reduction, while regulatory pressure on manufacturing emissions accelerates process innovation.
Iron-based phosphate binders are unifying mineral metabolism management by addressing both hyperphosphatemia and iron deficiency anemia in a single tablet. Dialysis networks in Germany and Japan are piloting these agents in anemia-protocol patients. This convergence is compressing the addressable market for separate IV iron supplements.
EMA's Medical Device Regulation and REACH chemical registration frameworks are forcing reformulation of polymer-based binders to eliminate residual monomer contaminants. Manufacturing facilities in Belgium and Ireland are retrofitting purification systems. The tablets segment bears the highest compliance cost burden due to batch-scale testing requirements.
Integrated pharmacy benefits within dialysis provider networks are consolidating phosphate binder purchasing decisions away from individual nephrologists. Large United States operators like Fresenius and DaVita are centralizing formularies around contracted suppliers. This concentration is most visible in the Medicare Advantage population where vertical integration between payer and provider is deepest.
Hyperphosphatemia Drugs Market Segmentation
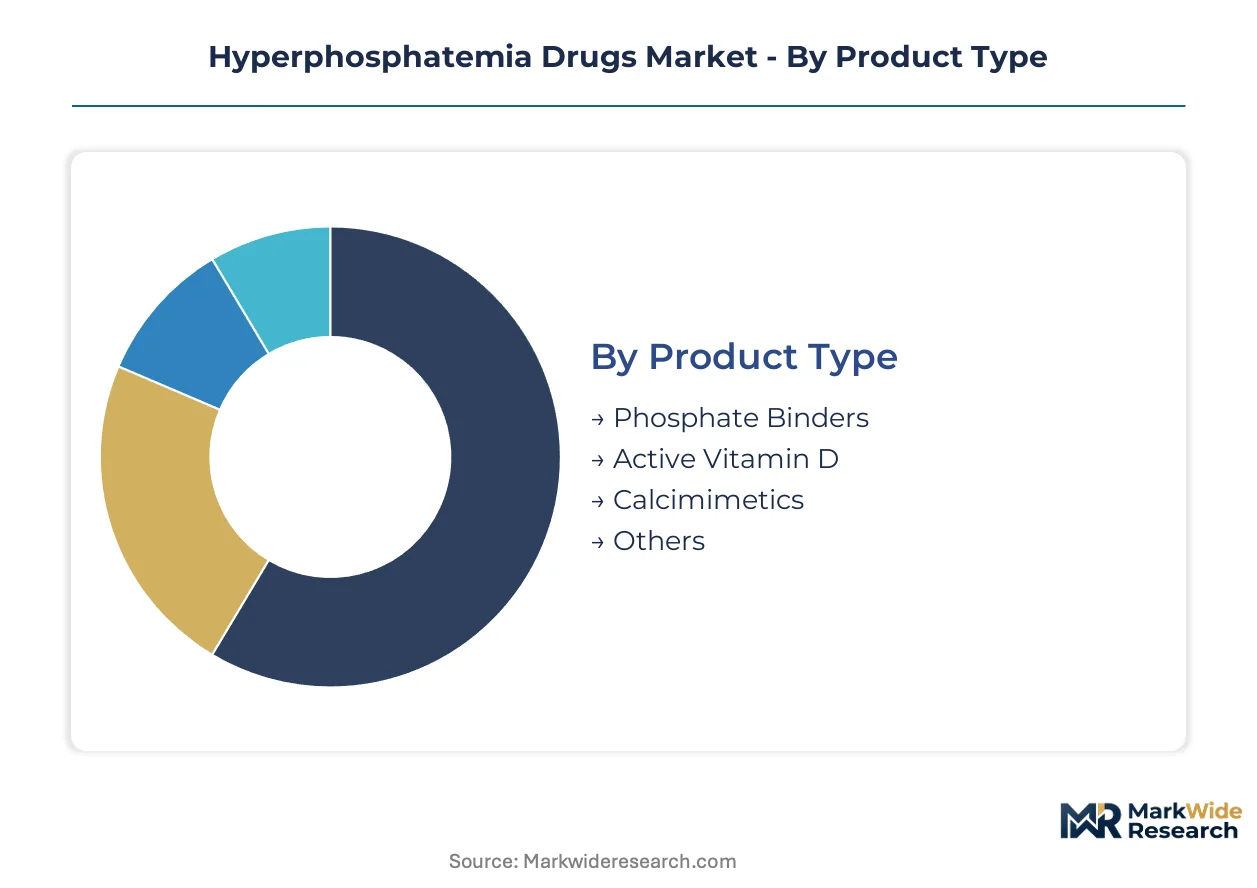
Hyperphosphatemia drug purchasing varies sharply across care settings, with dialysis centers demanding high-volume oral formulations while homecare segments prioritize palatability and reduced pill burden. Manufacturers must align production capacity and formulation development to these divergent channel requirements.
Product Type:
Cost tier differentiation separates chronic maintenance therapies from acute intervention agents, with reimbursement intensity varying by comorbidity complexity and treatment duration.
- Phosphate Binders:Polymer or mineral-based compounds sequester dietary phosphate in the gastrointestinal tract before systemic absorption. Medicare-covered dialysis protocols in the United States concentrate demand for sevelamer carbonate and calcium acetate, though cardiovascular calcification risks constrain long-term calcium-based dosing in high-burden patients.
- Calcimimetics:Allosteric modulators of the calcium-sensing receptor suppress parathyroid hormone secretion while indirectly lowering serum phosphate. Intravenous etelcalcetide adoption in Fresenius and DaVita dialysis networks is displacing oral cinacalcet in secondary hyperparathyroidism cases requiring rapid biochemical control.
- Active Vitamin D:Synthetic analogs of calcitriol manage mineral metabolism disturbances in predialysis chronic kidney disease populations.
- Others:Emerging iron-based agents unify phosphate binding with anemia management in single-tablet regimens.
Volume sits with Phosphate Binders; growth tilts toward Calcimimetics.
Formulation:
Patient adherence challenges and swallowing difficulties reshape formulation priorities across pediatric, geriatric, and home dialysis populations.
- Tablets:Compressed powder matrices dominate manufacturing economics and pharmacy inventory management. EMA's MDR and REACH frameworks impose the highest compliance cost burden on this segment due to batch-scale residual monomer testing requirements for polymer-based binders.
- Liquids:Aqueous suspensions address compliance barriers in children with congenital renal disorders and elderly patients with dysphagia. German and Japanese dialysis networks are piloting liquid iron-based formulations for anemia-protocol patients.
- Granules:Sachet-dosed powder formulations enable dose titration flexibility in weight-adjusted pediatric protocols.
- Injectable:Parenteral calcimimetics bypass gastrointestinal absorption variability in patients with enteral feeding tubes or severe nausea.
Tablets command manufacturing scale; Liquids are expanding most quickly.
End User:
Procurement authority concentration distinguishes institutional purchasing from retail pharmacy dispensing, with vertical integration reshaping channel economics.
- Dialysis Centers:Integrated care networks centralize formulary decisions away from individual nephrologists. Fresenius and DaVita purchasing consortia in the United States negotiate exclusive supply agreements, compressing margins for non-contracted manufacturers.
- Hospitals:Inpatient acute kidney injury protocols drive short-duration phosphate binder utilization, with discharge planning transitioning stable patients to outpatient dialysis or homecare channels.
- Homecare:Patient-managed hemodialysis expansion creates demand for simplified binder regimens with reduced pill burden and clear administration instructions.
- Pharmacy:Retail dispensing of oral cinacalcet and over-the-counter calcium supplements serves predialysis chronic kidney disease populations.
Procurement volume aggregates at Dialysis Centers; Homecare shows the steepest expansion trajectory.
Delivery Mode:
Route selection reflects disease severity, gastrointestinal function, and care setting infrastructure capabilities.
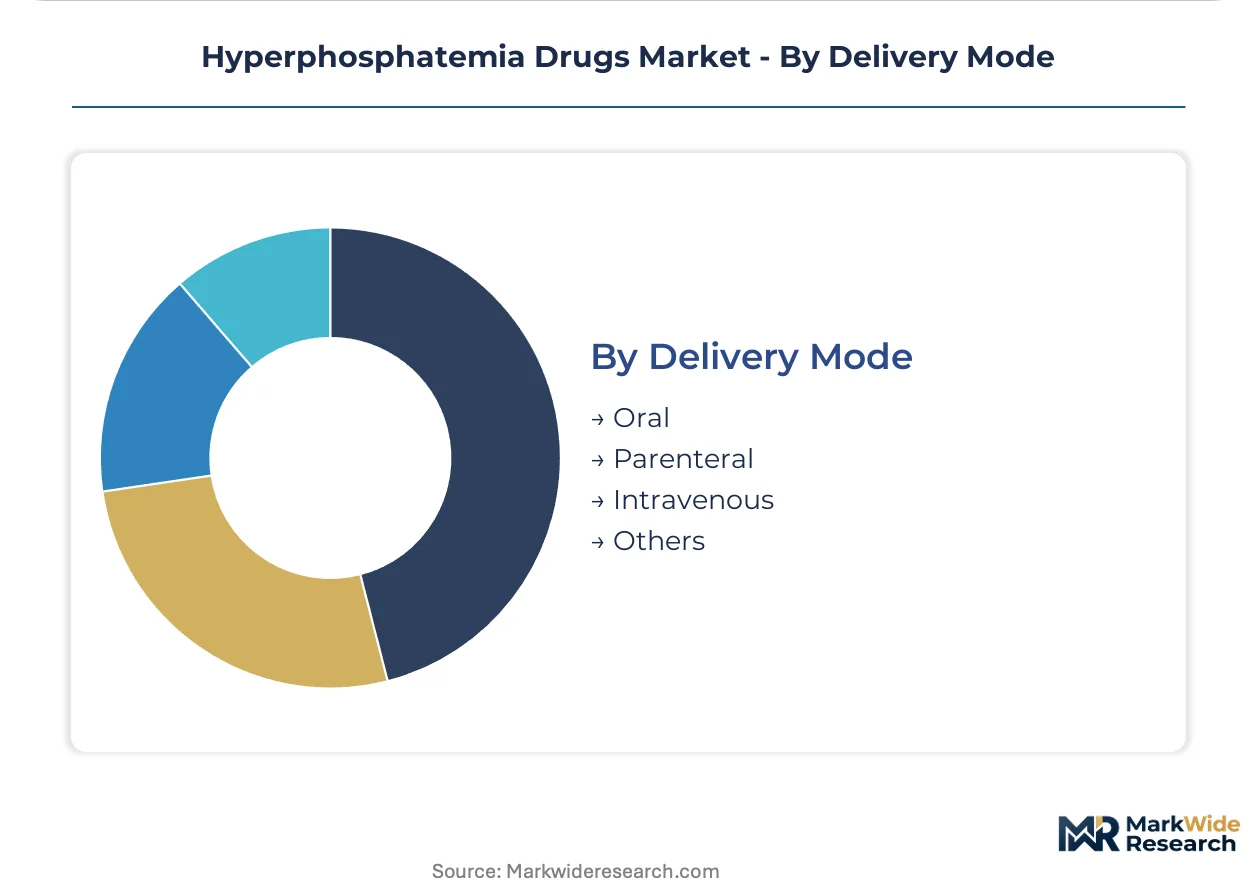
- Oral:Gastrointestinal administration of phosphate binders and cinacalcet tablets remains the default for ambulatory patients with intact enteral absorption.
- Intravenous:Direct vascular delivery of etelcalcetide during hemodialysis sessions ensures complete bioavailability and eliminates adherence variability.
- Parenteral:Subcutaneous or intramuscular routes serve patients with compromised venous access or peritoneal dialysis modalities.
- Others:Nasogastric and enteral feeding tube administration extends oral formulations to patients with swallowing impairment.
Oral routes retain volume dominance; Intravenous delivery is gaining share fastest in calcimimetic substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for phosphate binders clusters in Western Europe and North America, while dialysis-dependent patient populations concentrate demand in the United States, Japan, and Germany. Supply chains bridge this geographic divide through API sourcing from China and formulation finishing in regulated markets.
United States
Medicare reimbursement frameworks sustain the world's largest dialysis-dependent patient base, driving consistent phosphate binder utilization through integrated care networks. FDA oversight of new drug applications shapes clinical trial design for calcimimetic therapies. The Fresenius and DaVita purchasing consortia in Texas and California centralize formulary decisions, compressing margins for non-contracted manufacturers.
Germany
EMA's REACH compliance deadlines are retrofitting renal drug production facilities in North Rhine-Westphalia to meet environmental discharge standards. The EU Green Deal procurement mandates unlock preferred supplier status for carbon-labeled manufacturers in hospital purchasing consortia. Berlin-based dialysis networks pilot iron-based phosphate binders that unify mineral metabolism management.
Japan
PMDA regulatory pathways prioritize rapid review for therapies addressing secondary hyperparathyroidism comorbidities. METI industrial policy supports domestic manufacturing of polymer feedstocks for sevelamer carbonate production. The Osaka-Kobe pharmaceutical cluster houses formulation facilities serving Asia-Pacific dialysis markets.
China
NMPA priority review pathways accelerate local market access for imported renal drugs amid rising chronic kidney disease prevalence. The country's national pharmaceutical regulator enforces stability testing requirements that extend filing timelines for novel polymer formulations. Shanghai and Suzhou host contract manufacturing organizations supplying iron-based binder precursors to global markets.
India
CDSCO regulatory harmonization efforts align with international standards for phosphate binder bioequivalence studies. The country's national pharmaceutical regulator monitors post-market safety surveillance for calcimimetic therapies. Hyderabad and Ahmedabad pharmaceutical corridors produce generic sevelamer formulations for export to regulated markets.
Hyperphosphatemia Drugs Market Key Industry Players
The competitive structure tilts toward diversified pharmaceutical conglomerates with integrated nephrology portfolios. Market concentration reflects entrenched relationships between binder manufacturers and dialysis provider networks. Three archetypes dominate: integrated multinationals with captive supply chains, mid-cap specialists in calcimimetic development, and regional generic manufacturers competing on sevelamer cost. Competitive moves center on backward integration into polymer feedstock production and exclusive supply agreements with vertically integrated dialysis operators.
Among diversified pharmaceutical conglomerates, Sanofi anchors the integrated manufacturing archetype through multi-continental supply continuity for phosphate binders. Amgen occupies a position exemplifying calcimimetic specialization, with deep clinical focus on secondary hyperparathyroidism comorbidities. Takeda Pharmaceutical Company Limited represents the Asia-Pacific regional vector, competing through established nephrology partnerships in dialysis-intensive markets.
| Leading Market Players |
|---|
| Sanofi |
| Akebia Therapeutics |
| CSL |
| Ardelyx |
| Unicycive Therapeutics |
| Takeda Pharmaceutical Company Limited |
| Vifor Pharma |
| Amgen |
| Lupin |
| Others |
Cost & Logistics Intelligence
Iron-based phosphate binder manufacturing retrofits in Germany and Japan are compressing production costs while simultaneously shifting procurement leverage toward vertically integrated dialysis networks. REACH compliance investments and polymer feedstock volatility are forcing a bifurcation between carbon-certified premium supply and commodity generic sourcing.
Pricing Analysis
Margin tightening in sevelamer carbonate reflects petrochemical feedstock instability and concentrated buyer power at Fresenius and DaVita purchasing consortia. Three-tier pricing structure across premium iron-based, standard polymer, and economy calcium acetate levels stratifies by cardiovascular risk profile and reimbursement tier. Cost-down pressure on oral cinacalcet accelerates as intravenous etelcalcetide captures protocol share in Medicare Advantage populations. Dialysis centers exhibit lowest price sensitivity due to pass-through reimbursement mechanics, while independent nephrology practices face highest out-of-pocket cost exposure.
Supply Chain Analysis
Regional distribution centers in Belgium and Ireland anchor European polymer binder finishing, with hub-and-spoke patterns radiating to German and French hospital consortia. Active pharmaceutical ingredient production draws from China and India, with iron-based precursor chemistry concentrated in Shanghai-Suzhou manufacturing corridors. Single-source vulnerability in Chinese polymer feedstock supply creates exposure to environmental enforcement shutdowns. Distribution runs through integrated dialysis provider networks that centralize formulary decisions away from retail pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hyperphosphatemia drugs market is becoming a vertical-integration race, with manufacturers pursuing backward control over polymer feedstock production to defend margin structure against procurement consolidation.
For Market Incumbents: Acquire polymer manufacturing assets in REACH-compliant jurisdictions to secure carbon-certified supply credentials for EU Green Deal procurement. Lock in exclusive supply agreements with vertically integrated dialysis operators before formulary centralization completes. Generic sevelamer entrants from Indian manufacturers threaten pricing floors in Medicare fee-for-service segments. For New Entrants and Emerging Players: Direct-to-clinic digital sampling platforms bypass consolidated purchasing committees and reach individual nephrologists in community dialysis settings. Target pediatric liquid formulation gaps in North American markets where swallowing difficulties create compliance barriers. Position iron-based binders as anemia-protocol substitutes to capture bundled reimbursement economics in German pilot networks. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap calcimimetic specialists with FDA-approved intravenous delivery formats and dialysis network contracts. Five-to-ten year viability hinges on regulatory moats around manufacturing emissions compliance and polymer purity standards. Monitor etelcalcetide protocol penetration rates in Fresenius and DaVita networks as inflection indicator for oral calcimimetic displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Feedstock | REACH-compliant captive supply secures preferred supplier status in German hospital consortia. |
| Pediatric Liquid Formulation Development | Addressable compliance gaps in congenital renal disorder populations unlock Medicare pediatric reimbursement tiers. |
| Iron-Based Binder Anemia Protocol Entry | Single-tablet regimens compress separate IV iron supplement markets in Japanese dialysis networks. |
| Exclusive Supply Agreement with Dialysis Networks | Fresenius and DaVita formulary centralization demands locked-in volume commitments for margin protection. |
| Carbon-Labeled Manufacturing Certification | EU Green Deal procurement mandates in France and Germany require verified emission reduction credentials. |
Research Approach
Independent corroboration across nephrology formulary directors, dialysis procurement managers, and regulatory affairs specialists underwrites the qualitative findings on purchasing concentration trends. Secondary validation draws from FDA new drug application filings, EMA REACH compliance disclosures, CMS Medicare reimbursement databases, and ClinicalTrials.gov calcimimetic protocol registrations. Bottom-up patient population modeling triangulates against top-down manufacturer revenue attribution across phosphate binder and calcimimetic product categories.
Rate-of-change decomposition separates volume drivers from price mix effects across the projection horizon. Segmentation dimensions span product type, formulation, end-user channel, and regional regulatory cluster. CAGRs derive from fitted growth curves anchored to ESKD prevalence trajectories and dialysis center expansion rates. Forecast inputs incorporate polymer feedstock price indices and EU Green Deal procurement implementation timelines.
Inputs from dialysis network purchasing committees and pharmaceutical manufacturing executives were available through the study window; gaps in real-time sevelamer carbonate spot pricing introduce uncertainty bands around cost projection scenarios. Forecasts reflect documented assumptions regarding Medicare reimbursement stability and REACH enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Mild Laxatives Market
Pharmaceuticals
Dermatitis Drugs Market
Pharmaceuticals
Narcotic Analgesics Market
Pharmaceuticals
Global Pharmaceutical Contract Manufacturing Market
Pharmaceuticals
Digital Pharmaceutical Supply Chain Management Market
Pharmaceuticals
Europe Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Disease-Modifying Agents Market
Pharmaceuticals
Injectable Targeted Therapy Market
Pharmaceuticals
Herbal Drugs Market
Pharmaceuticals
US Pharmaceutical Warehousing Market
Pharmaceuticals
Cancer Therapeutics and Biotherapeutics Market
Pharmaceuticals
Medical Grade Sodium Hyaluronate Market
Pharmaceuticals
Trulicity Market
Pharmaceuticals
South Africa Insulin Drugs and Delivery Devices Market
Pharmaceuticals
Istradefylline API Market
Pharmaceuticals
Specialty Active Pharmaceutical Ingredients Market