
 Global Hormone Replacement Therapy Market | 2026-2036
Global Hormone Replacement Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hormone Replacement Therapy Market Foresight
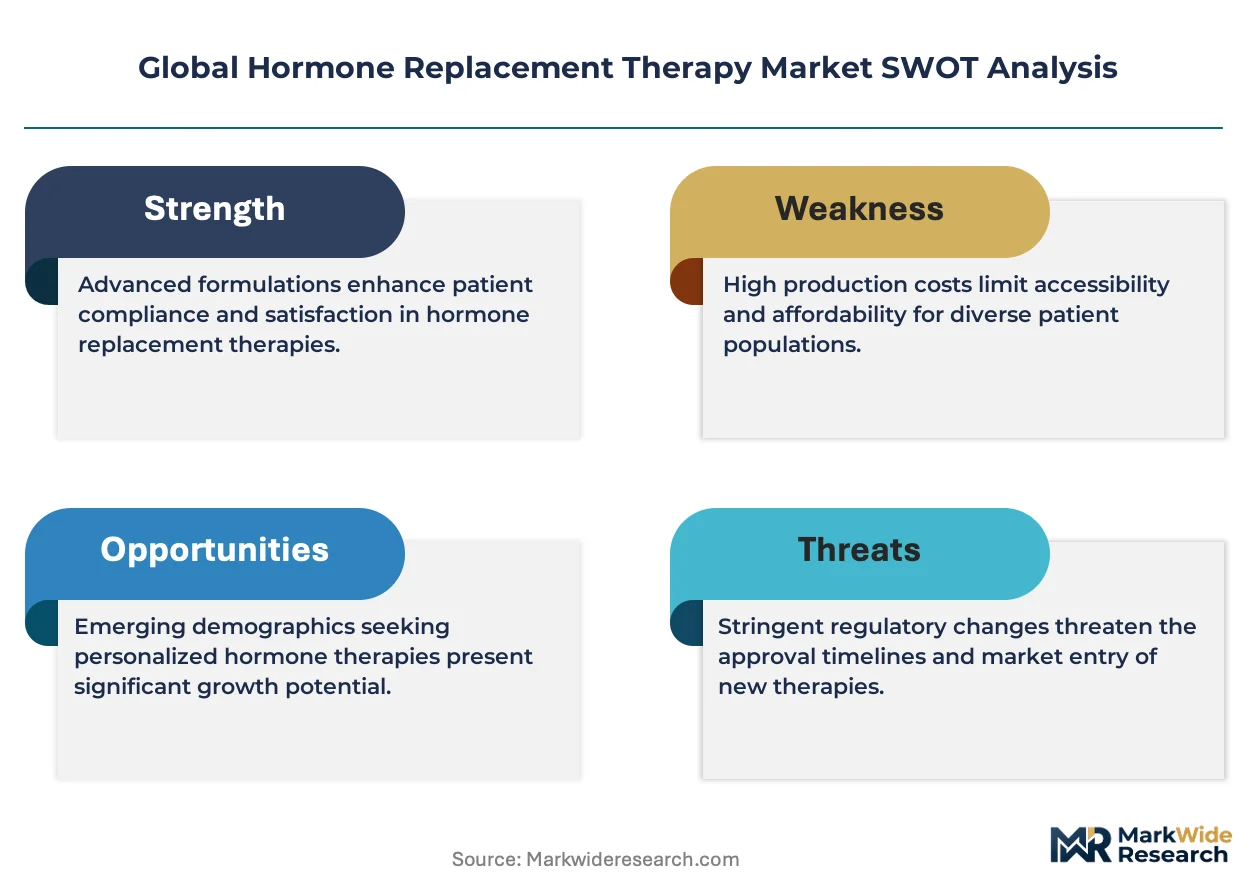
The EU Green Deal is pivoting pharmaceutical manufacturers toward lower-carbon production processes for hormone formulations. Novo Nordisk A/S anchors its portfolio with recombinant peptide expertise and sustained-release platforms. Pfizer Inc. dominates oral and transdermal hormone portfolios through extensive manufacturing scale. AbbVie Inc. specializes in gynecology-focused combination therapies with strong channel presence in endocrinology centers.
Hormone replacement therapy encompasses the clinical administration of synthetic or bioidentical hormones to restore endocrine balance in patients with deficient or declining natural production, typically formulated as estradiol valerate, micronized progesterone, or testosterone esters in standardized dosages measured in milligrams per unit. These therapies primarily serve to alleviate symptomatic hormone deficiency, prevent osteoporosis-related fracture, and maintain metabolic homeostasis in aging populations. Estrogen and combination therapy segments lead prescription volumes due to established menopause management protocols, while transdermal patches and injectable solutions capture expanding share among patients seeking alternatives to first-pass hepatic metabolism. Oral tablets retain the largest installed base across gynecology practices, though topical gels are gaining traction in andropause treatment through simplified self-administration.
FDA, EMA, and WHO standards govern active pharmaceutical ingredient purity, bioequivalence thresholds, and post-market pharmacovigilance reporting for hormone therapies across manufacturing and distribution networks. REACH and RoHS frameworks in Europe further constrain excipient sourcing and packaging material composition, elevating compliance costs for multinational suppliers. Stakeholders must monitor evolving pharmacovigilance requirements and biosimilar pathway clarifications to preserve market access and reimbursement positioning.
Market Dynamics
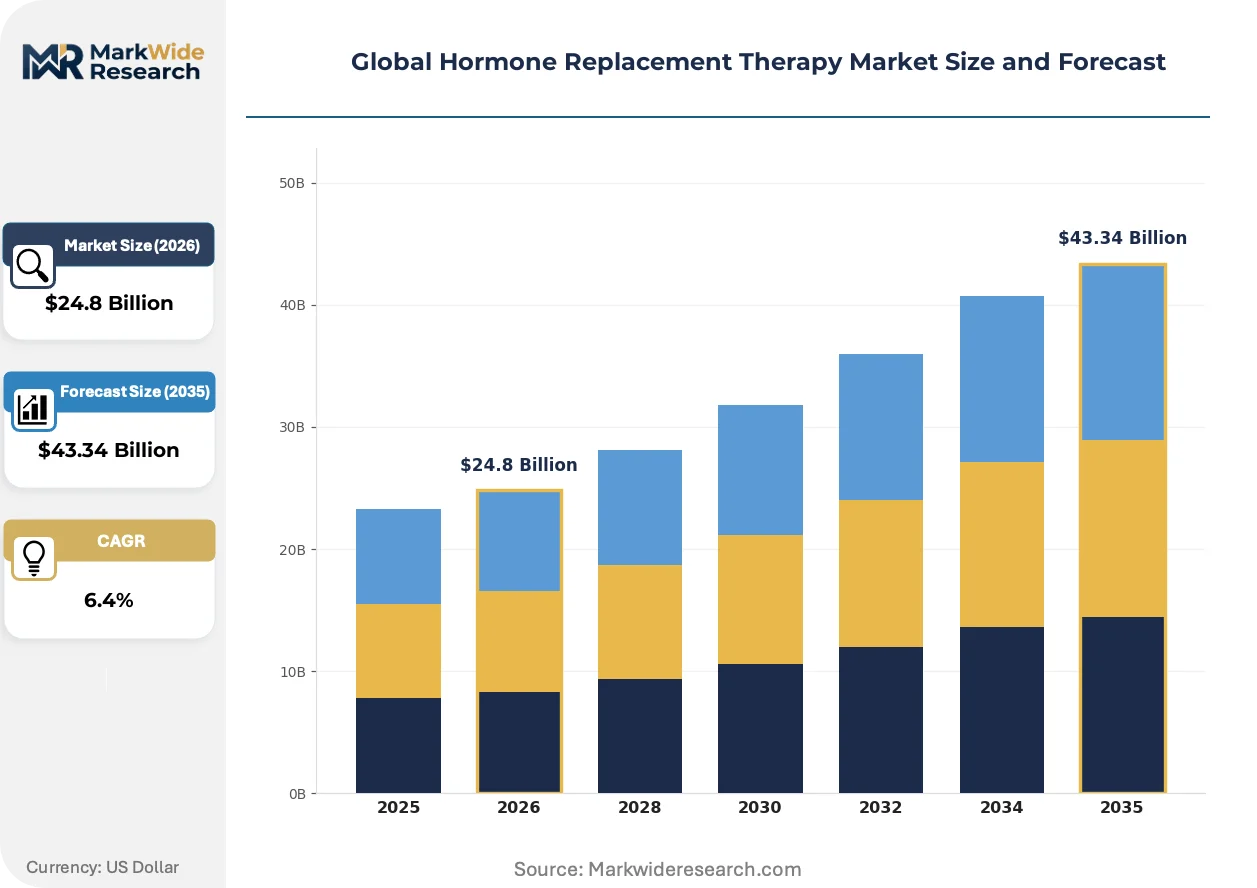
The EU Green Deal and MDR compliance requirements are compressing formulation margins while specialty clinics accelerate toward combination therapies. Manufacturers face simultaneous pressure to decarbonize production processes and validate bioidentical hormone equivalence under tightened pharmacovigilance standards.
Growth Catalysts
- Aging Demographics:Declining natural hormone production in populations over 50 across the United States, Germany, and Japan sustains prescription volume expansion for menopause and andropause management protocols.
- REACH and RoHS Frameworks:European excipient sourcing constraints are accelerating investment in sustainable packaging alternatives and green chemistry manufacturing platforms.
- Transdermal Delivery Systems:Patches and topical gels bypass first-pass hepatic metabolism, attracting patients with cardiovascular risk profiles who require alternative administration routes to oral tablets.
Market Restraints
- API Supply Concentration:Estradiol valerate and testosterone ester active pharmaceutical ingredients concentrate among Chinese and Indian bulk manufacturers, exposing formulators to geopolitical trade friction.
- EMA Pharmacovigilance Burden:Post-market adverse event reporting requirements for hormone therapies impose sustained compliance costs that disproportionately burden mid-scale European manufacturers.
- Compounding Pharmacy Substitution:Customized bioidentical hormone preparations from regulated compounding facilities capture price-sensitive patients seeking personalized dosing outside standardized pharmaceutical portfolios.
Strategic Opportunities
- Pediatric Endocrinology Expansion:Growth hormone deficiency and precocious puberty protocols in Japan and South Korea represent underpenetrated demand for recombinant peptide formulations.
- EU AI Act Alignment:Machine learning-enabled dosing optimization and patient monitoring tools qualify for streamlined regulatory pathways when integrated into connected drug delivery devices.
- Direct-to-Patient Subscription Models:Telehealth platforms in the United States are disintermediating traditional gynecology and endocrinology channels for chronic hormone therapy maintenance.
Industry Challenges
- Bioequivalence Validation Talent:Shortages of clinical pharmacologists capable of designing equivalence studies for novel sustained-release platforms delay product pipeline advancement.
- Cold Chain Reconfiguration:Peptide-based hormone formulations require temperature-controlled distribution infrastructure that legacy oral tablet networks cannot accommodate without substantial capital redeployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hormone Replacement Therapy Market |
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $43.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Estrogen, Progesterone, Testosterone, Combination Therapy Application: Menopause, Andropause, Osteoporosis Prevention, Thyroid Disorder Management End User: Specialty Clinics, Endocrinology Centers, Gynecology Practices, Hormone Therapy Clinics Delivery Mode: Oral Tablets, Transdermal Patches, Topical Gels, Injectable Solutions, Pellets |
| Companies Covered | Pfizer Inc., Novo Nordisk A/S, Bayer AG, Abbott Laboratories, Merck KGaA, Eli Lilly and Company, AbbVie Inc., Viatris Inc., F. Hoffmann-La Roche Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hormone Replacement Therapy Market Shifts & Advancements
Bioidentical hormone formulations are displacing synthetic alternatives as patient awareness of molecular specificity rises. Delivery technology convergence with digital health monitoring is compressing the traditional prescriber-patient feedback loop.
Sustained-release microsphere technology is integrating recombinant peptide hormones into biodegradable polymer matrices that enable weekly or monthly dosing intervals. Specialty endocrinology centers in Germany and Japan are adopting these platforms for growth hormone and testosterone replacement protocols. The technology is integrating chronic disease management into routine primary care by reducing injection frequency and improving adherence metrics.
MDR Article 117 requirements for drug-device combination products are forcing hormone delivery system manufacturers to submit technical documentation through notified body review rather than self-certification. This regulatory shift extends time-to-market for transdermal patches with integrated sensors. European manufacturers are responding by pre-submission engagement with designated notified bodies to clarify clinical evidence expectations.
Patients are consolidating prescription authority with integrated health systems that offer bundled menopause management including hormone therapy, bone density monitoring, and metabolic screening. Independent gynecology practices in the United States are losing chronic therapy maintenance to hospital-affiliated specialty clinics. This concentration is most visible in metropolitan markets where accountable care organization contracts incentivize vertical patient retention.
Global Hormone Replacement Therapy Market Segmentation
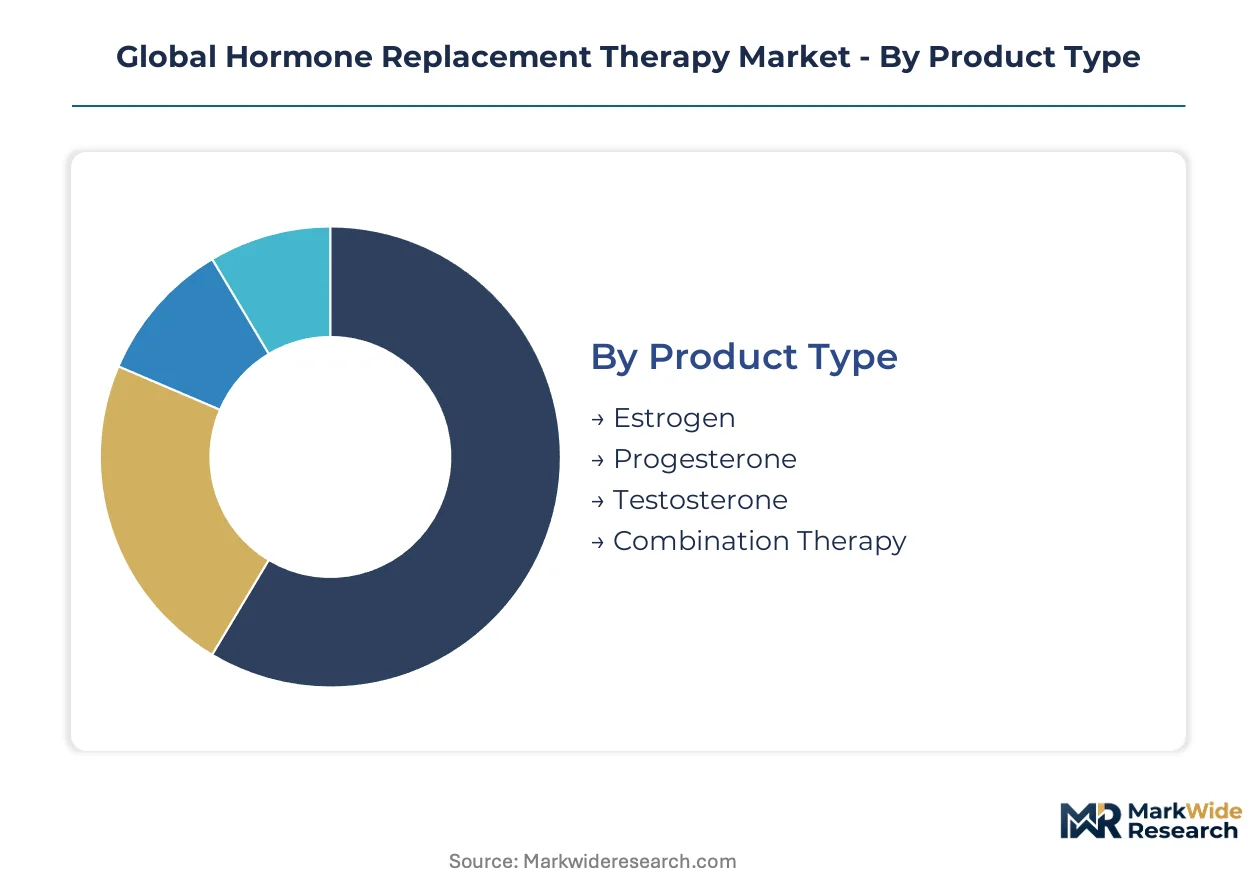
Hormone replacement therapy segmentation reveals divergent supply chain configurations across product chemistry, clinical application, and delivery technology. Each dimension carries distinct manufacturing footprints, regulatory pathways, and channel economics that shape competitive positioning.
Product Type:
API sourcing concentration varies sharply across hormonal moieties, with synthetic estrogen and testosterone supply chains anchored in Asian bulk manufacturing while bioidentical progesterone production localizes in European fermentation facilities.
- Estrogen:Estradiol valerate and conjugated equine estrogen formulations dominate prescription volumes in menopause protocols across the United States and Germany. Supply concentrates among Chinese bulk manufacturers, exposing formulators to REACH-compliant import documentation burdens and extended lead times for European compounders.
- Combination Therapy:Fixed-dose estradiol-progesterone products command premium positioning in specialty clinics seeking simplified adherence regimens. Demand concentrates in hospital-affiliated endocrinology centers in Japan and the United States where bundled reimbursement favors standardized protocols over individual component titration.
- Progesterone:Micronized bioidentical formulations serve patients with synthetic hormone intolerance, primarily through compounding pharmacies in North America and regulated manufacturing in Germany.
- Testosterone:Ester-based injectable and transdermal products target andropause management, with transdermal gel manufacturing scaling in the United States to meet self-administration preferences.
Estrogen absorbs the bulk of installed capacity; combination therapy is expanding most quickly.
Application:
Clinical indication drives formulation selection and channel access, with menopause and osteoporosis prevention protocols enjoying established reimbursement while thyroid applications face narrower prescriber specialization.
- Menopause:Vasomotor symptom management represents the largest addressable population, with transdermal patches gaining preference among patients with cardiovascular risk profiles who require hepatic bypass. German and Japanese regulatory frameworks favor bioidentical estradiol over synthetic conjugated estrogens in public reimbursement formularies.
- Osteoporosis Prevention:Long-term estrogen therapy for bone density maintenance requires sustained patient retention, favoring delivery modes with superior adherence metrics such as weekly transdermal patches over daily oral regimens. Japanese geriatric protocols emphasize this indication given population aging demographics.
- Andropause:Testosterone replacement for age-related hypogonadism concentrates in urology and endocrinology practices in the United States, with topical gel formulations displacing intramuscular injections in metropolitan markets.
- Thyroid Disorder Management:Levothyroxine and liothyronine protocols operate on distinct supply chains from sex hormone therapies, with compounding pharmacies capturing personalized dosing demand outside standardized pharmaceutical portfolios.
Menopause commands the largest patient population; osteoporosis prevention is climbing the fastest as screening protocols expand.
End User:
Channel consolidation is reshaping prescription authority, with integrated health systems capturing chronic therapy maintenance from independent practices through bundled menopause management contracts.
- Specialty Clinics:Hospital-affiliated endocrinology and gynecology centers in the United States and Germany are consolidating hormone therapy maintenance through accountable care organization incentives. These facilities favor combination therapies and sustained-release platforms that reduce visit frequency.
- Gynecology Practices:Independent women's health clinics retain strong positions in initial menopause diagnosis and therapy initiation, though chronic maintenance is migrating to integrated systems. Oral tablet prescribing remains concentrated here due to established familiarity.
- Endocrinology Centers:Academic medical centers in Japan and Germany handle complex cases requiring recombinant peptide hormones and pediatric growth hormone protocols.
- Hormone Therapy Clinics:Dedicated facilities in the United States focus on bioidentical hormone optimization, often operating outside traditional insurance reimbursement through direct-pay models.
Specialty clinics absorb the bulk of chronic therapy volume; hormone therapy clinics are gaining share fastest through telehealth-enabled direct-to-patient models.
Delivery Mode:
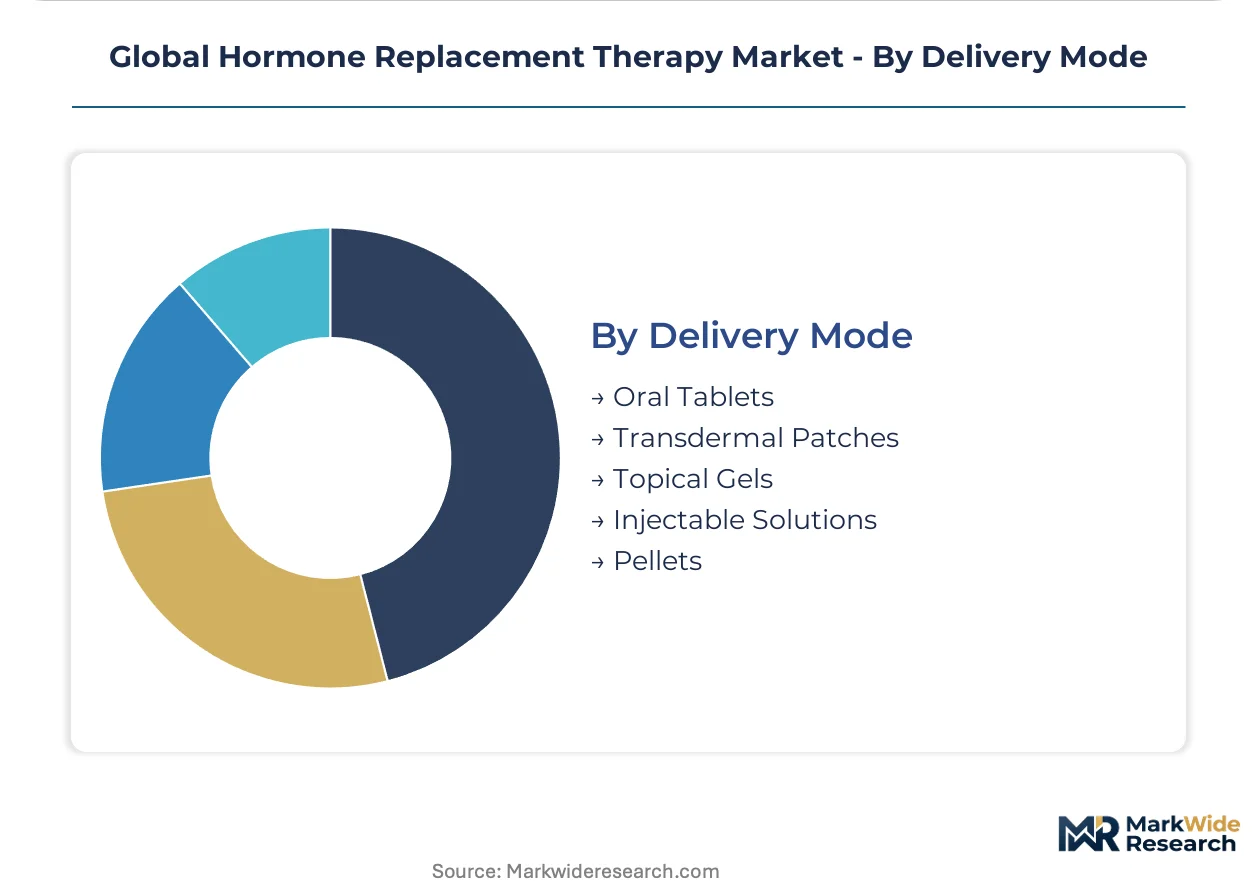
Manufacturing scale and capital intensity diverge across delivery technologies, with oral tablet production leveraging existing pharmaceutical infrastructure while transdermal patches require specialized adhesive and membrane fabrication.
- Oral Tablets:First-pass hepatic metabolism limits bioavailability but manufacturing scale is unmatched, with established production lines across Pfizer and AbbVie facilities serving gynecology practices globally. EMA pharmacovigilance requirements for oral estrogen thromboembolic risk labeling sustain compliance costs.
- Transdermal Patches:Matrix and reservoir patch technologies bypass hepatic metabolism, attracting cardiovascular-risk patients in Germany and Japan. MDR Article 117 drug-device combination requirements extend European regulatory timelines for sensor-integrated next-generation products.
- Topical Gels:Testosterone gel manufacturing scales in the United States meet andropause self-administration demand, with metered-dose pump packaging simplifying patient compliance.
- Injectable Solutions:Intramuscular testosterone esters and estradiol valerate retain cost-sensitive segments, though injection frequency disadvantages versus sustained-release alternatives constrain growth.
- Pellets:Subcutaneous hormone implants deliver three-to-six month dosing intervals, concentrated in compounding and specialty manufacturing for patients seeking maximal adherence convenience.
Oral tablets retain the largest installed manufacturing base; transdermal patches are expanding most quickly as cardiovascular risk awareness reshapes prescribing patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty endocrinology centers in Boston and the Research Triangle anchor North American hormone therapy innovation, while manufacturing scale clusters in the Rhine-Ruhr corridor and Osaka-Kobe pharmaceutical zones.
United States
Hospital-affiliated specialty clinics in metropolitan markets consolidate chronic therapy maintenance through accountable care organization contracts. FDA pharmacovigilance requirements for thromboembolic risk labeling sustain compliance investment. The Research Triangle and Boston-Cambridge biotech corridor concentrate sustained-release platform development for recombinant peptide hormones.
Germany
Public reimbursement formularies favor bioidentical estradiol over synthetic conjugated estrogens, driving prescription volume toward micronized formulations. EMA and EU Green Deal standards compress margins while mandating lower-carbon production processes. The Rhine-Ruhr pharmaceutical manufacturing belt hosts fermentation facilities for bioidentical progesterone production.
Japan
Geriatric protocols emphasize long-term estrogen therapy for osteoporosis prevention given population aging demographics. PMDA maintains stringent bioequivalence thresholds for sustained-release hormone formulations. The Osaka-Kobe pharmaceutical zone anchors transdermal patch manufacturing for cardiovascular-risk patient segments.
India
Bulk active pharmaceutical ingredient production for estradiol valerate and testosterone esters concentrates in Hyderabad and Ahmedabad chemical corridors. CDSCO alignment with ICH guidelines streamlines abbreviated new drug application pathways for hormone generics. Gujarat's specialty chemical clusters supply intermediates to European formulators facing REACH documentation burdens.
Switzerland
Swissmedic maintains premium positioning for bioidentical hormone formulations through rigorous pharmacovigilance standards. Basel-based pharmaceutical headquarters coordinate European distribution networks for recombinant peptide therapies. The country's precision manufacturing infrastructure supports microsphere encapsulation technology for extended-release hormone delivery.
Global Hormone Replacement Therapy Market Competitive Landscape
The competitive structure tilts toward multinational pharmaceutical conglomerates with diversified endocrinology portfolios. Consolidation pressure intensifies as specialty clinics demand bundled menopause management solutions rather than single-product contracts. Three archetypes dominate: recombinant peptide specialists with sustained-release platforms, oral and transdermal scale manufacturers, and gynecology-focused combination therapy providers. M&A activity targets bioidentical formulation capabilities, while strategic partnerships with telehealth platforms reshape direct-to-patient distribution channels.
Among the established pharmaceutical conglomerates, Pfizer Inc. and Novo Nordisk A/S occupy positions representing scale manufacturing and recombinant peptide specialization respectively. AbbVie Inc. exemplifies the gynecology-focused archetype with concentrated channel presence in hospital-affiliated endocrinology centers. These three entities anchor the competitive spectrum without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Novo Nordisk A/S |
| Bayer AG |
| Abbott Laboratories |
| Merck KGaA |
| Eli Lilly and Company |
| AbbVie Inc. |
| Viatris Inc. |
| F. Hoffmann-La Roche Ltd. |
| Others |
Supply & Pricing Matrix
The EU Green Deal gates qualified supply and premium-tier pricing access for hormone replacement therapy manufacturers, forcing compliance investment as a prerequisite for European market participation while compressing margins for non-compliant producers. REACH documentation burdens and MDR Article 117 requirements stratify the supplier base into certified premium tiers and excluded economy tiers.
Pricing Analysis
Adherence-based value anchors pricing in the hormone replacement therapy market, with sustained-release platforms commanding premium positioning against daily oral regimens due to reduced visit frequency and improved retention metrics. Three-tier pricing structure across premium, standard, and economy levels separates MDR-certified drug-device combinations from conventional oral tablets and unregulated compounding alternatives. Pricing pressure stems from EMA pharmacovigilance compliance costs that disproportionately burden mid-scale European manufacturers. Hospital-affiliated specialty clinics demonstrate lowest price sensitivity due to bundled reimbursement contracts, while independent gynecology practices and direct-pay hormone therapy clinics face acute cost compression.
Supply Chain Analysis
Direct-to-specialty-clinic channels handle chronic therapy maintenance demand, with hospital system procurement consolidating prescription authority under accountable care organization contracts. Active pharmaceutical ingredient production concentrates in India and China for estradiol valerate and testosterone esters, while bioidentical progesterone fermentation localizes in German Rhine-Ruhr facilities. Formulation depends on Chinese bulk manufacturers for synthetic estrogen intermediates and European suppliers for micronized bioidentical grades. Single-source vulnerability runs through concentrated API supply from Indian and Chinese chemical corridors exposed to geopolitical trade friction. Distribution runs through temperature-controlled networks for peptide-based formulations that legacy oral tablet infrastructure cannot accommodate without capital redeployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hormone replacement therapy market reads as a cost-of-compliance story where MDR Article 117 and EU Green Deal standards erect barrier-to-entry moats favoring capitalized incumbents with notified body relationships and green chemistry platforms.
For Market Incumbents: Deepen backward integration into bioidentical hormone fermentation capacity in the Rhine-Ruhr corridor to secure supply independence from Asian API concentration. Fortify notified body pre-submission engagement capabilities to accelerate drug-device combination timelines against emerging competitors lacking technical documentation expertise. Priority investments should target sustained-release microsphere platforms that reduce patient visit frequency and lock in specialty clinic loyalty. For New Entrants and Emerging Players: Direct-to-patient subscription seekers represent the most penetrable buyer archetype, disintermediated from traditional gynecology channels by telehealth platforms in United States metropolitan markets. Pediatric endocrinology protocols in Japan and South Korea offer white-space expansion for recombinant peptide formulations with limited incumbent saturation. Go-to-market execution should leverage AI-enabled dosing optimization tools that qualify for streamlined EU AI Act regulatory pathways when integrated into connected delivery devices. For Investors and Strategic Acquirers: First notified body approval for sensor-integrated transdermal patches is the leading indicator that MDR compliance capabilities have reached scalable deployment readiness. Long-term viability across the analysis window favors acquisition targets with demonstrated bioequivalence validation talent and cold chain distribution infrastructure. Monitor CDSCO alignment progress with ICH guidelines as the signal for Indian generic hormone manufacturers achieving European market access eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Pre-Submission Engagement | MDR Article 117 compliance accelerates drug-device combination timelines for sensor-integrated patches. |
| Green Chemistry Manufacturing Transition | EU Green Deal alignment preserves European market access against REACH documentation barriers. |
| Telehealth Platform Partnership | Direct-to-patient subscription models disintermediate traditional gynecology channel control. |
| Bioidentical Fermentation Capacity Expansion | Rhine-Ruhr facility investment reduces dependence on Chinese and Indian API concentration. |
| AI-Enabled Dosing Optimization Development | EU AI Act qualification streamlines regulatory pathways for connected delivery device integration. |
Research Methodology
FDA filings, EMA submissions, and ClinicalTrials.gov formed the secondary backbone of this analysis, supplemented by formulary database audits and pharmacovigilance reporting records. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers validated secondary findings and informed competitive positioning assessments. Bottom-up prescription volume modeling and top-down reimbursement framework analysis enabled triangulation across stakeholder perspectives.
Historical trendline analysis of prescription volume, pricing trajectories, and regulatory approval timelines established baseline growth patterns across the projection horizon. The analytical framework segmented demand by hormone moiety, clinical indication, delivery technology, and regional regulatory cluster. CAGRs were derived from patient population projections, therapy initiation rates, and adherence metric improvements. Forecast inputs incorporated PMDA bioequivalence threshold evolution and CDSCO-ICH alignment progress for generic pathway clarification.
Revisions become necessary when MDR enforcement intensity escalates, REACH documentation requirements expand, or geopolitical trade friction disrupts API supply corridors. Forecasts reflect assumptions regarding sustained specialty clinic consolidation and telehealth platform regulatory accommodation. Practitioners should monitor notified body capacity constraints, EU AI Act implementation guidance, and Indian bulk manufacturer certification progress for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Buruli Ulcer Treatment Market
Specialty Medicine
Overt Hepatic Encephalopathy Market
Specialty Medicine
Gouty Arthritis Market
Specialty Medicine
Congenital Neutropenia Treatment Market
Specialty Medicine
Bipolar Disorder Therapeutics Market
Specialty Medicine
Acromegaly Market
Specialty Medicine
Neurodegenerative Disorder Market
Specialty Medicine
Global Calciphylaxis Treatment Market
Specialty Medicine
Glioma Therapeutics Market
Specialty Medicine
Severe Combined Immunodeficiency Market
Specialty Medicine
Hidradenitis Suppurativa (HS) Treatment Market
Specialty Medicine
Narcolepsy Market
Specialty Medicine
Global Tourette Syndrome Treatment Market
Specialty Medicine
Castrate Resistant Prostate Cancer Therapeutics Market
Specialty Medicine
Complement 3 Glomerulopathy (C3G) Market
Specialty Medicine
Global Amyotrophic Lateral Sclerosis (ALS) Treatment Market