
 Diabetes Associated Ophthalmic Treatment Market | 2026-2036
Diabetes Associated Ophthalmic Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Diabetes Associated Ophthalmic Treatment Market Intelligence
Modular therapy bundling is realigning how ophthalmology clinics procure diabetic eye care solutions. Johnson & Johnson Services, Inc. leverages its integrated surgical-optical portfolio to anchor premium positioning across cataract and retinal workflows. Bayer AG differentiates through sustained investment in sustained-release anti-VEGF platforms for diabetic macular edema.
Diabetes associated ophthalmic treatment encompasses pharmaceutical agents, laser-based interventions, and diagnostic imaging systems designed to prevent, monitor, or reverse vision-threatening complications of diabetes mellitus. Anti-VEGF intravitreal injections require cold-chain logistics and sterile compounding protocols that constrain point-of-care administration. Diagnostic Devices within the product type dimension command disproportionate margin pools as OCT angiography replaces fluorescein-based staging in retina practices. Laser Therapy competes with pharmacologic approaches for diabetic retinopathy, though photocoagulation retains cost advantages in publicly funded health systems where reimbursement for biologics remains restricted.
The FDA regulates anti-VEGF biologics under BLA pathways with post-marketing ophthalmic safety surveillance, while the EMA's MDR framework imposes stricter clinical evidence requirements on diagnostic device software algorithms. Health Canada's PMRA coordinates with provincial formularies to determine public reimbursement for ranibizumab biosimilars in diabetic macular edema. Stakeholders must monitor how real-world evidence requirements from these regulators reshape post-approval study obligations and competitive differentiation for sustained-release formulations.
Market Dynamics
The shift from fluorescein angiography to OCT angiography is compressing diagnostic workflows while elevating software-dependent margin capture for device manufacturers serving retina specialists.
Growth Catalysts
- Medicare reimbursement expansion:CMS coverage for preventive diabetic retinopathy screening in the United States is pulling undiagnosed patients into clinical pathways earlier, expanding addressable procedure volumes for imaging and intervention.
- Anti-VEGF sustained-release platforms:Extended-delivery formulations are reducing injection frequency burdens for diabetic macular edema patients, improving adherence curves and extending therapy persistence in managed care populations.
- Cold-chain infrastructure maturation:Specialized logistics networks for biologic intravitreal agents are enabling point-of-care administration in ambulatory surgical centers beyond hospital ophthalmology departments.
Market Restraints
- Biologic cost concentration:Ranibizumab and aflibercept originator pricing creates budget pressure in publicly funded systems where biosimilar penetration remains constrained by provincial formulary delays in Canada.
- Sterile compounding requirements:USP 797 compliance for intravitreal injection preparation limits pharmacy autonomy and concentrates preparation capacity in certified hospital pharmacies and outsourcing facilities.
- Laser therapy substitution:Photocoagulation retains cost advantages in resource-constrained settings, capping biologic penetration where reimbursement thresholds exclude anti-VEGF first-line use.
Strategic Opportunities
- Home-based monitoring convergence:Smartphone-connected fundus cameras paired with AI grading algorithms are opening remote screening channels for rural and underserved urban populations in India.
- Real-world evidence mandates:EMA MDR post-market surveillance requirements for diagnostic device software are creating differentiation openings for manufacturers with robust clinical data infrastructure.
- Ambulatory surgical center expansion:Office-based surgical suites are capturing retinal procedure volume from hospital outpatient departments, demanding compact, integrated laser-photocoagulation systems.
Industry Challenges
- Vitreoretinal surgeon training pipelines:Fellowship program capacity constraints in the United States are limiting specialist supply growth relative to expanding diabetic patient cohorts requiring intervention.
- Software validation timelines:FDA 510(k) clearance pathways for AI-assisted diagnostic algorithms are extending development cycles as predicate device comparisons become more complex for novel deep-learning architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diabetes Associated Ophthalmic Treatment Market |
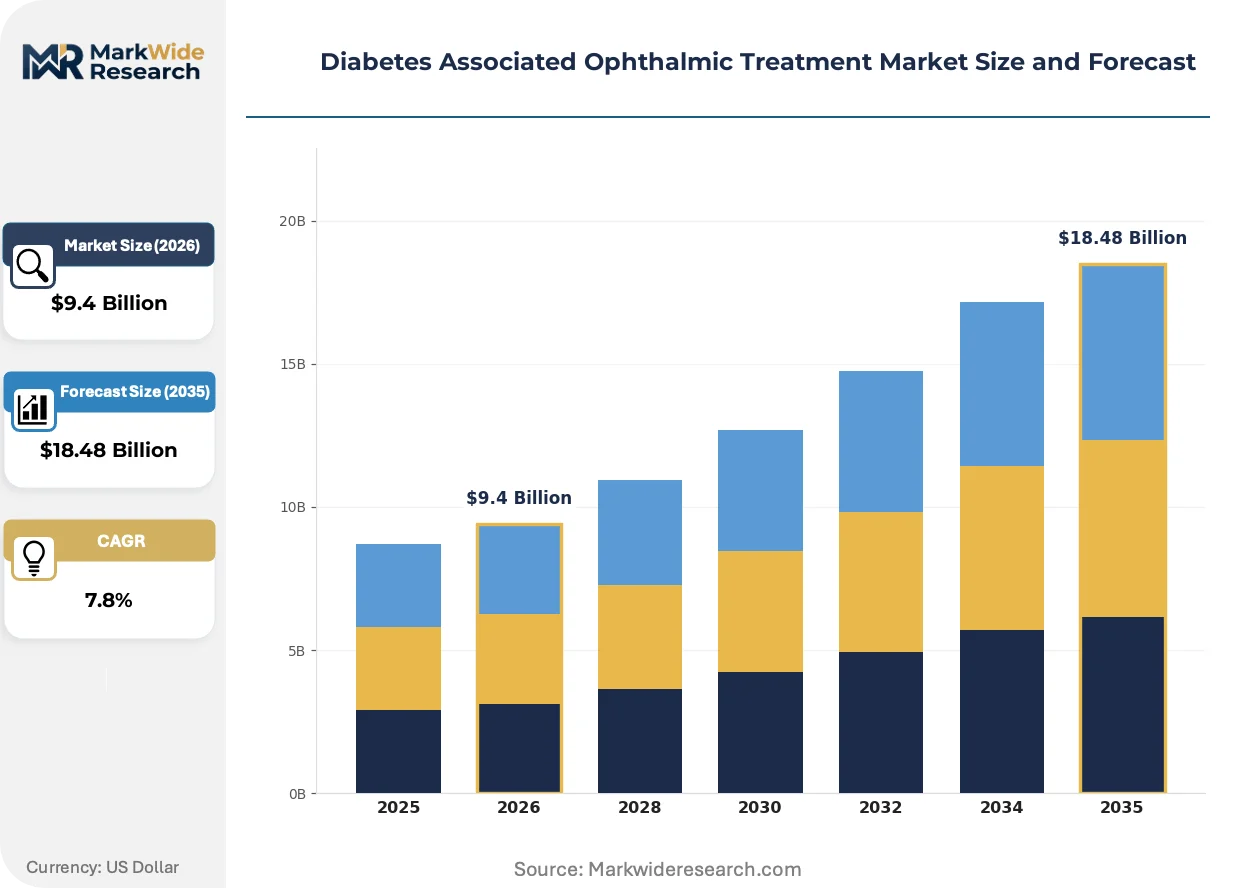
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $18.48 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiglaucoma Agents, Antioxidants, Anti-inflammatory Agents, Diagnostic Devices Technology: Laser Therapy, Gene Therapy, Photocoagulation, Optical Coherence Tomography Application: Retinal Disorders, Diabetic Macular Edema, Cataracts, Diabetic Retinopathy End User: Ophthalmology Clinics, Hospitals, Research Laboratories, Homecare Settings |
| Companies Covered | Alcon, Johnson & Johnson Services, Inc., F. Hoffmann-La Roche Ltd, Novartis AG, Bausch Health Companies Inc., Bayer AG, AbbVie Inc., Pfizer, Inc., Carl Zeiss Meditec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diabetes Associated Ophthalmic Treatment Market Strategic Shifts & Innovations
OCT angiography is displacing invasive staging protocols while regulatory frameworks accelerate for sustained-release therapeutics and AI-integrated diagnostics.
Artificial intelligence-based image interpretation is electrifying diagnostic throughput in high-volume retina practices. Large academic medical centers in the United States are deploying autonomous grading systems for diabetic retinopathy screening, reducing specialist interpretation burdens on asymptomatic patient cohorts. This capability compression is enabling task-shifting to primary care settings, expanding screening reach while preserving specialist capacity for complex interventions.
EMA's Medical Device Regulation framework is imposing stricter clinical evidence requirements on diagnostic software algorithms marketed in Europe. Manufacturers must now generate prospective clinical performance data for AI-driven OCT analysis tools, elevating development costs but creating regulatory moats against lower-evidence competitors. Retina device portfolios with pre-MDR legacy certifications are racing to complete technical documentation updates before certificate expiration deadlines.
Subscription-based equipment access models are displacing capital purchase arrangements for diagnostic devices in United States ophthalmology practices. Smaller group practices and solo retina specialists are adopting per-scan fee structures for OCT angiography systems, transferring utilization risk to manufacturers while preserving cash flow for therapeutic service expansion. This financing rotation is most pronounced in Sun Belt metropolitan markets where practice consolidation has created competitive pressure on equipment refresh cycles.
Diabetes Associated Ophthalmic Treatment Market Segmentation
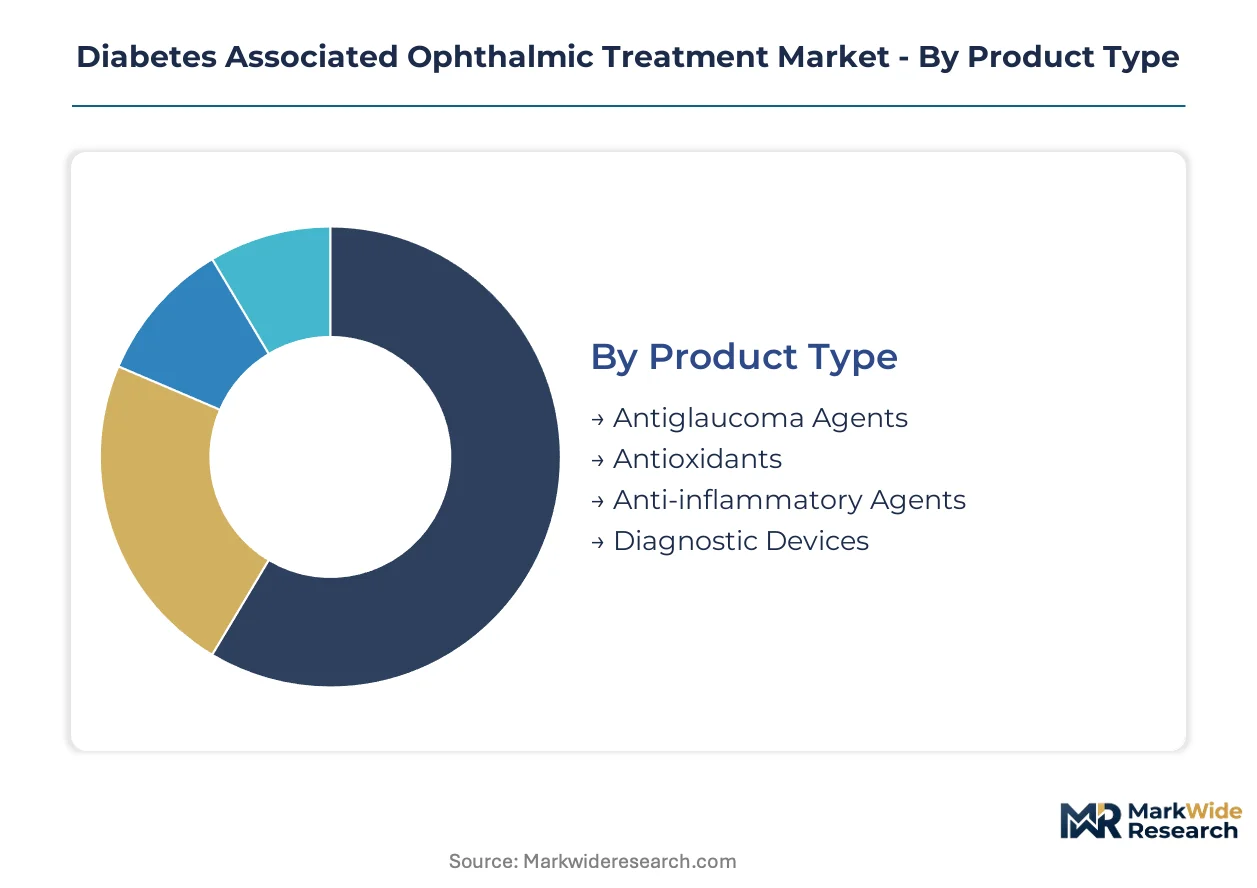
Diabetes associated ophthalmic treatment segments diverge sharply in margin structure and procurement cadence. Equipment refresh cycles and therapeutic protocol shifts reshape how stakeholders allocate capital across diagnostic, pharmaceutical, and surgical modalities.
Product Type:
Replacement timelines stretch from months for biologic agents to five-to-seven years for capital diagnostic platforms, concentrating procurement planning around distinct budget cycles.
- Diagnostic Devices:OCT angiography systems and fundus cameras dominate capital allocation in retina practices upgrading from fluorescein-based staging. Demand clusters in United States metropolitan markets where Medicare reimbursement for preventive screening has expanded procedure volumes beyond specialist interpretation capacity.
- Anti-inflammatory Agents:Corticosteroid intravitreal implants address persistent diabetic macular edema cases failing anti-VEGF monotherapy. Prescription volumes concentrate in managed care populations where step-therapy protocols mandate failure on first-line biologics before authorization.
- Antiglaucoma Agents:Prostaglandin analogs and combination drops manage neovascular glaucoma secondary to proliferative diabetic retinopathy.
- Antioxidants:Oral supplements and topical formulations target oxidative stress pathways in early-stage diabetic eye disease with limited formulary penetration.
Volume placements concentrate in Diagnostic Devices; the faster expansion belongs to Anti-inflammatory Agents as sustained-release platforms extend therapy persistence.
Technology:
Cost tier stratification separates premium image-guided interventions from commodity laser systems, with reimbursement differentials determining technology mix across payer environments.
- Optical Coherence Tomography:Spectral-domain and swept-source architectures deliver cross-sectional retinal imaging with angiographic capability. United States academic medical centers drive demand for AI-integrated analysis software reducing specialist grading burden in high-volume screening programs.
- Laser Therapy:Pattern-scanning photocoagulation systems compete with pharmacologic approaches for diabetic retinopathy treatment. Publicly funded health systems in Canada and Europe retain laser-first protocols where anti-VEGF reimbursement remains restricted by provincial and national formularies.
- Gene Therapy:Viral vector delivery systems for sustained anti-VEGF expression remain investigational with limited commercial availability.
- Photocoagulation:Conventional argon and diode laser platforms persist in resource-constrained settings prioritizing capital efficiency over therapeutic precision.
Revenue concentration favors Optical Coherence Tomography; steepest expansion trajectory sits with Gene Therapy as regulatory pathways mature for inherited retinal disease applications.
Application:
Patient volume distribution follows diabetes prevalence and screening penetration, with severity gradients determining intervention intensity and reimbursement tier.
- Diabetic Retinopathy:Non-proliferative and proliferative stages drive the majority of screening encounters and intervention decisions. United States Medicare expansion for annual retinal photography has pulled asymptomatic patients into earlier treatment pathways, expanding addressable volumes for disease-modifying therapies.
- Diabetic Macular Edema:Center-involved macular thickening represents the primary indication for anti-VEGF intravitreal injections and corticosteroid implants. Treatment persistence challenges in Medicare Advantage populations favor sustained-release formulations reducing injection frequency burdens.
- Retinal Disorders:Neovascularization and tractional retinal detachment complications require surgical intervention with limited pharmaceutical alternatives.
- Cataracts:Diabetes-accelerated lens opacification drives surgical volume with premium intraocular lens upsell opportunities in private-pay segments.
Procedure counts peak in Diabetic Retinopathy screening; value capture is climbing the fastest in Diabetic Macular Edema as biologic pricing and injection frequency compound per-patient revenue.
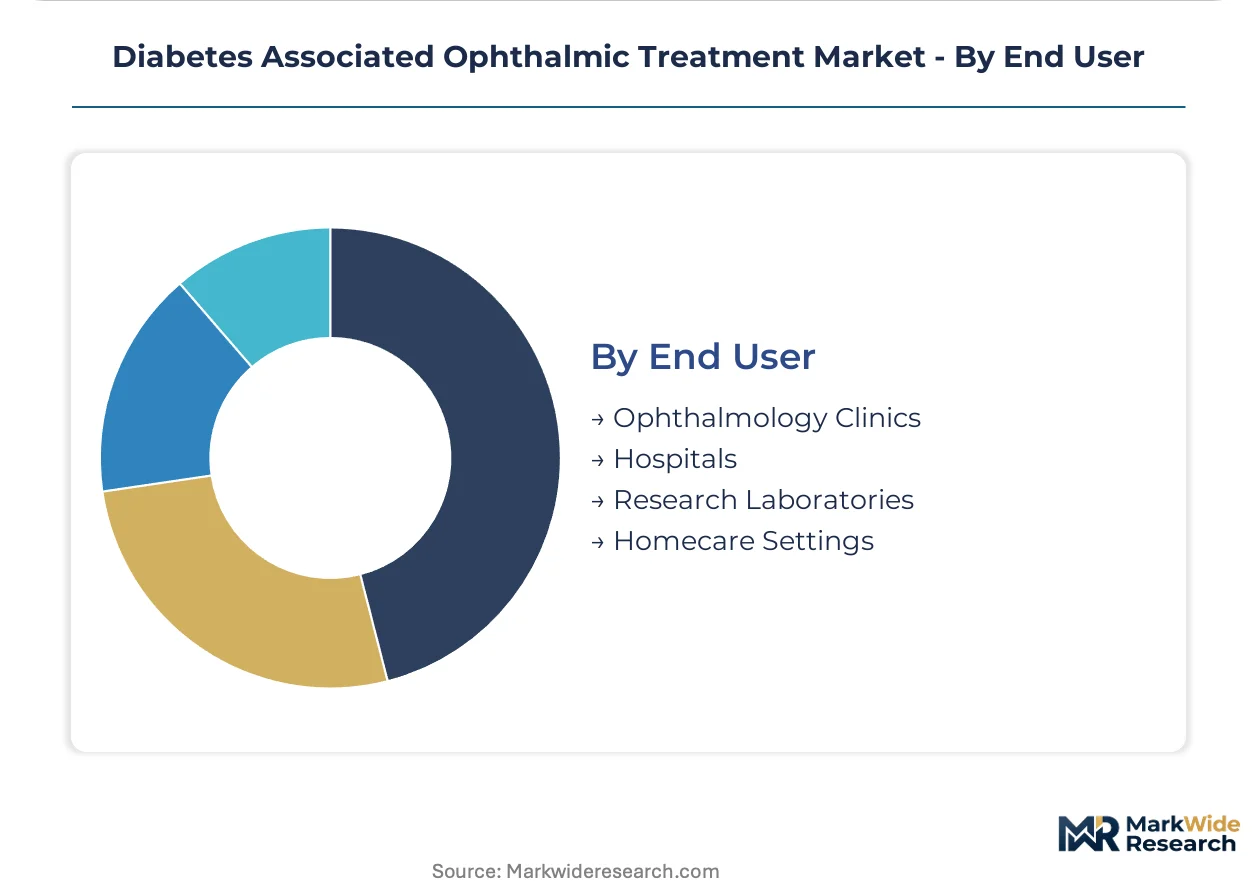
End User:
Customer type determines equipment configuration, with ambulatory settings demanding compact integrated systems versus hospital-based platforms prioritizing throughput and trainee access.
- Ophthalmology Clinics:Private retina practices and group ophthalmology networks concentrate diagnostic device procurement and intravitreal injection services. Subscription-based OCT access models are displacing capital purchases in Sun Belt metropolitan markets where practice consolidation pressures equipment refresh cycles.
- Hospitals:Academic medical centers and community hospital ophthalmology departments anchor complex surgical volume and fellowship training pipelines. Cold-chain infrastructure and USP 797 sterile compounding requirements concentrate biologic preparation capacity in certified hospital pharmacies.
- Research Laboratories:Phase I-III trial sites and academic research centers drive demand for novel imaging biomarkers and gene therapy delivery systems.
- Homecare Settings:Smartphone-connected fundus cameras and remote monitoring platforms are emerging in rural United States markets and Indian urban peripheries with limited specialist density.
Service volume concentrates in Ophthalmology Clinics; capability expansion is gaining share fastest in Homecare Settings as AI-grading algorithms enable task-shifting to primary care channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free-trade zones in Singapore and Shenzhen concentrate cold-chain logistics infrastructure for biologic intravitreal agents. These hubs enable regional distribution of anti-VEGF therapies across Asia-Pacific markets with limited local manufacturing capacity.
United States
Medicare reimbursement expansion for preventive diabetic retinopathy screening has pulled asymptomatic patients into earlier treatment pathways. The FDA's Breakthrough Therapy designation pathway accelerates approvals for novel retinal therapies. Retina specialists in Sun Belt metropolitan markets adopt subscription-based OCT angiography access models to preserve cash flow.
Germany
EMA's Medical Device Regulation framework imposes stricter clinical evidence requirements on diagnostic software algorithms. The country's statutory health insurance system maintains laser-first protocols for diabetic retinopathy where anti-VEGF reimbursement remains restricted. Medical technology clusters in Baden-Württemberg concentrate AI-integrated OCT analysis tool development.
India
Smartphone-connected fundus cameras paired with AI grading algorithms open remote screening channels for rural and underserved urban populations. CDSCO coordinates with state health missions to determine public procurement for diabetic eye care equipment. Manufacturing corridors in Gujarat and Karnataka assemble cost-competitive diagnostic devices for domestic and export markets.
Japan
PMDA's regulatory framework supports sustained-release anti-VEGF platform development for diabetic macular edema. The country's aging demographic concentrates demand for disease-modifying retinal therapies. Tokyo-based academic medical centers deploy autonomous grading systems to reduce specialist interpretation burdens.
Diabetes Associated Ophthalmic Treatment Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across pharmaceutical, device, and diagnostic segments. The market structure consolidates around three tiers: integrated surgical-optical portfolios, sustained-release biologic platforms, and AI-integrated imaging systems. Strategic archetypes include capital equipment bundlers, sustained-delivery innovators, and software-enabled diagnostic providers. Dominant competitive moves encompass subscription-based equipment access models and real-world evidence infrastructure investments.
Within the integrated portfolio tier, Johnson & Johnson Services, Inc. and Alcon occupy positions anchoring premium positioning across cataract and retinal workflows. Bayer AG exemplifies the sustained-release biologic archetype through its investment in extended-delivery anti-VEGF platforms. Among diagnostic specialists, Carl Zeiss Meditec represents the AI-integrated imaging segment with OCT angiography systems displacing fluorescein-based staging protocols.
| Leading Market Players |
|---|
| Alcon |
| Johnson & Johnson Services, Inc. |
| F. Hoffmann-La Roche Ltd |
| Novartis AG |
| Bausch Health Companies Inc. |
| Bayer AG |
| AbbVie Inc. |
| Pfizer, Inc. |
| Carl Zeiss Meditec |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up ophthalmology clinic chains in the United States Sun Belt concentrate procurement leverage for OCT angiography systems, compressing capital equipment margins while sustaining premium pricing for anti-VEGF biologics through formulary exclusivity negotiations.
Pricing Analysis
Margin tightening in diagnostic devices reflects subscription-based access models displacing outright purchase arrangements. Pricing stratifies across premium AI-integrated OCT systems, standard spectral-domain configurations, and economy-tier fundus cameras without angiographic capability. Cost compression in the standard tier accelerates because consolidated group practices negotiate volume discounts with manufacturers. Hospital-based ophthalmology departments exhibit lowest price sensitivity due to bundled reimbursement, while solo retina specialists in competitive metropolitan markets drive hardest bargain.
Supply Chain Analysis
Single-source vulnerability sits with sterile compounding capacity concentrated in United States hospital pharmacies and certified outsourcing facilities. Active pharmaceutical ingredient production for ranibizumab and aflibercept draws from Switzerland, Singapore, and United States biologic manufacturing campuses. Cold-chain logistics for intravitreal biologics rests on specialized temperature-controlled distribution networks with limited redundancy. Tariff exposure on Chinese-assembled optical components creates procurement risk for device manufacturers. Distribution runs through regional ophthalmology distributors and direct manufacturer-to-clinic arrangements for high-value capital equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EMA MDR clinical evidence requirements for diagnostic software create regulatory moats favoring manufacturers with established prospective data infrastructure.
For Market Incumbents: Anchor premium positioning through sustained-release anti-VEGF platform extensions that reduce injection frequency burdens and improve therapy persistence. Defend against laser therapy substitution in publicly funded systems by demonstrating long-term cost-effectiveness through real-world evidence registries. Prioritize backward integration into sterile compounding capacity to secure supply chain autonomy. For New Entrants and Emerging Players: Launch via smartphone-connected fundus camera distribution partnerships with primary care networks in rural India and underserved United States markets. Target homecare monitoring convergence as the most penetrable white-space segment, exploiting AI-grading algorithm maturation to bypass specialist interpretation bottlenecks. Pursue CDSCO state health mission procurement channels for cost-competitive device placement. For Investors and Strategic Acquirers: Distressed-cycle entries favor diagnostic device specialists with legacy EMA certifications facing MDR documentation renewal deadlines in Germany and France. Five-to-ten year viability hinges on software-enabled margin capture replacing hardware depreciation cycles. Watch FDA 510(k) clearance timeline extensions for AI-assisted diagnostic algorithms as inflection indicator for competitive entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Real-World Evidence Infrastructure Investment | EMA MDR post-market surveillance requirements elevate development costs but create regulatory differentiation against lower-evidence competitors. |
| Sustained-Release Formulation Development | Extended-delivery anti-VEGF platforms reduce injection frequency burdens and extend therapy persistence in Medicare Advantage populations. |
| Subscription-Based Equipment Access Model | Per-scan fee structures for OCT angiography transfer utilization risk to manufacturers while preserving clinic cash flow. |
| Ambulatory Surgical Center Partnership | Office-based surgical suites capture retinal procedure volume from hospital outpatient departments, demanding compact integrated systems. |
| AI-Integrated Diagnostic Software Launch | Autonomous grading systems reduce specialist interpretation burdens and enable task-shifting to primary care screening channels. |
Research Approach
Multi-period observation of Medicare reimbursement policy shifts, anti-VEGF injection procedure volumes, and OCT system placement patterns anchored the trend analysis, supplemented by interviews with retina specialists, hospital purchasing committee members, GPO contracts managers, and biomedical engineers. Secondary validation drew from FDA 510(k) clearance databases, CMS Medicare claims data, EMA MDR certification records, and hospital procurement databases. Bottom-up procedure volume estimates triangulated against top-down market sizing from equipment manufacturer revenue disclosures.
Segment-weighting across product type, technology platform, application severity, and end-user setting informed the analytical framework. Growth projections incorporated therapy persistence curves for sustained-release formulations, equipment refresh cycles for diagnostic devices, and screening penetration rates in Medicare-eligible populations. CAGRs were derived from modeled procedure volume expansion and per-procedure revenue trajectories across the projection horizon.
Regulatory timeline delays, biosimilar launch sequencing, and AI diagnostic algorithm validation setbacks are the dominant revision risks. Deviation in FDA Breakthrough Therapy designation grant rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Retinal Disorder Treatment Market
Ophthalmology
Epidemic Keratoconjunctivitis Treatment Market
Ophthalmology
Cataract Treatment Market
Ophthalmology
Europe Ophthalmology Market
Ophthalmology
Pediatric Vitrectomy Market
Ophthalmology
Global Optic Nerve Disorders Treatment Market
Ophthalmology
Brazil Ophthalmic Devices Market
Ophthalmology
Aesthetic Ophthalmology Device Market
Ophthalmology
Exophthalmos Treatment Market
Ophthalmology
Retinal Detachment Market
Ophthalmology
Neurotrophic Keratitis Market
Ophthalmology
Thyroid Eye Disease Treatment Market
Ophthalmology
Ophthalmic Clinical Trials Market
Ophthalmology
Ophthalmology Diagnostics Market
Ophthalmology
Ophthalmic Tonometers Market
Ophthalmology
Optic Nerve Glioma Market