
 Ovarian Cysts Market | 2026-2036
Ovarian Cysts Market Size, Share, and Industry Trends Forecast 2026-2036
Ovarian Cysts Market Outlook
MDR compliance timelines for ovarian cyst diagnostic devices is shifting the cost-of-entry calculus for manufacturers seeking European market access. Pfizer Inc. leverages its endocrinology portfolio to sustain positions in hormonal therapy segments. Bayer AG anchors its competitive stance through diagnostic imaging alliances with ultrasound equipment suppliers.
Ovarian cysts are fluid-filled sacs that develop on or within the ovary, typically classified by histological origin as functional, dermoid, endometriotic, or neoplastic formations, with transvaginal ultrasound serving as the primary non-invasive detection modality measuring lesion diameter, echogenicity, and vascular flow patterns to distinguish benign from suspicious masses. Functional cysts dominate routine clinical volume due to their spontaneous resolution profile and minimal intervention requirements, while endometriomas command premium procedural economics through their association with fertility preservation protocols and specialized laparoscopic excision techniques. Surgical intervention segments concentrate margin pools in ambulatory surgical centers where same-day discharge protocols reduce facility overhead and improve throughput metrics.
FDA premarket notification pathways and EMA medical device regulation frameworks govern ovarian cyst diagnostic and therapeutic product commercialization, with FDA 510(k) clearances for ultrasound contrast agents streamlining market entry and MDR technical documentation requirements extending certification cycles for European distribution. WHO reproductive health guidelines and national screening programs in countries with established gynecological care infrastructure further shape product development priorities and reimbursement landscapes. Stakeholders must monitor evolving FDA guidance on ovarian mass risk stratification algorithms and anticipate how payer coverage determinations for MRI-based characterization protocols will redistribute diagnostic volumes across hospital and clinic settings.
Market Dynamics
Minimally invasive diagnostic protocols are compressing hospital workflows and redistributing procedure volumes from inpatient to ambulatory settings, forcing equipment manufacturers to recalibrate form-factor and software specifications for same-day discharge environments.
Growth Catalysts
- FDA 510(k) Pathway Compression:Streamlined clearances for ultrasound contrast agents are accelerating device commercialization timelines and reducing premarket validation burdens for imaging manufacturers targeting US distribution.
- Ambulatory Surgical Center Expansion:Same-day discharge protocols in outpatient facilities are concentrating margin pools in settings optimized for laparoscopic excision throughput and reduced facility overhead.
- Transvaginal Ultrasound Integration:Tertiary care networks in the United States are embedding this modality into routine gynecological screening workflows, expanding addressable diagnostic volumes.
Market Restraints
- MDR Technical Documentation Burden:Extended certification cycles under European Medical Device Regulation frameworks are elevating cost-of-entry calculus for manufacturers seeking EU market access.
- Specialized Laparoscopic Equipment Concentration:Supply bottlenecks in precision surgical instrument manufacturing concentrate in German and Japanese production clusters, exposing procurement chains to geographic risk.
- Functional Cyst Spontaneous Resolution:The high natural remission rate of follicular and corpus luteum formations limits addressable therapeutic intervention volumes and compresses recurring revenue opportunities.
Strategic Opportunities
- India Gynecological Infrastructure Buildout:National health mission expansions and private hospital chain growth in tier-2 cities are creating first-mover advantages for diagnostic device suppliers establishing service networks.
- MRI-Based Characterization Protocols:Payer coverage determinations for multiparametric magnetic resonance imaging in ovarian mass risk stratification are opening premium diagnostic segments distinct from ultrasound-dominated workflows.
- Fertility Preservation Linkages:Endometrioma management protocols tied to assisted reproductive technology centers are generating specialized procedural economics in integrated women's health campuses.
Industry Challenges
- Sonographer Specialization Scarcity:Shortages in certified gynecological ultrasound technicians are constraining throughput capacity in high-volume screening programs and extending appointment backlogs.
- Legacy PACS Integration Complexity:Hospital information system interoperability requirements are prolonging deployment timelines for AI-enhanced imaging workstations and elevating implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ovarian Cysts Market |
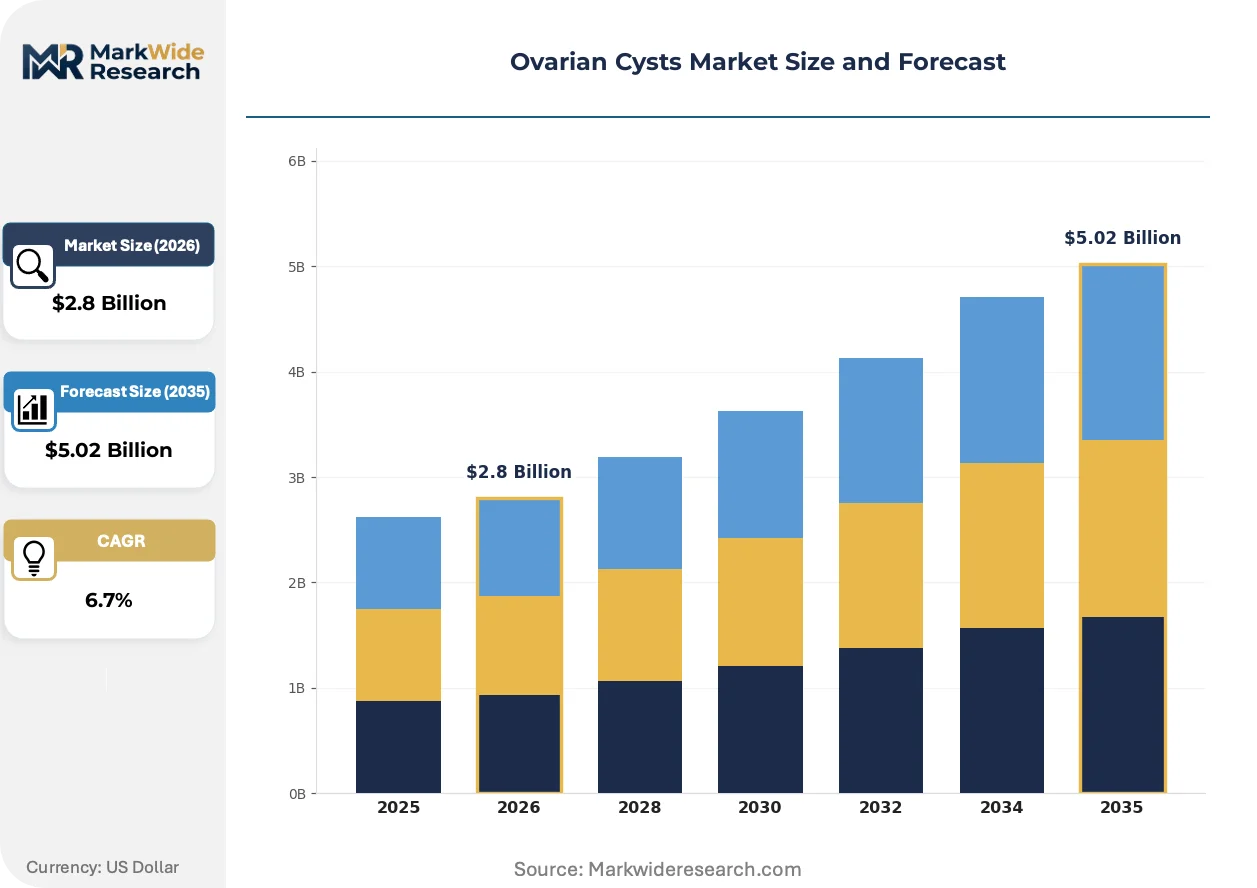
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Functional Cysts, Dermoid Cysts, Endometriomas, Cystadenomas End User: Hospitals, Clinics, Ambulatory Surgical Centers, Research Institutions Diagnosis Method: Ultrasound, MRI, CT Scan, Blood Tests Treatment Approach: Medication, Surgical Intervention, Watchful Waiting, Hormonal Therapy |
| Companies Covered | Pfizer Inc., Merck & Co., Inc., AbbVie Inc., AstraZeneca plc, Bayer AG, Novartis AG, Medtronic plc, Teva Pharmaceutical Industries Ltd., GlaxoSmithKline plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ovarian Cysts Market Strategic Shifts
Artificial intelligence is penetrating ovarian cyst characterization workflows, compressing radiologist interpretation cycles and enabling risk-stratification algorithms that redirect suspicious masses toward expedited surgical consultation pathways.
Portable ultrasound systems equipped with AI-assisted lesion measurement are modularizing point-of-care diagnostic capabilities, allowing gynecology clinics and community health centers to deploy screening capacity without capital-intensive fixed-installation equipment, compressing patient referral chains and capturing volumes previously routed to hospital radiology departments.
EMA Medical Device Regulation enforcement is tightening post-market surveillance requirements for ovarian cyst imaging devices, compelling manufacturers to establish European authorized representatives and maintain clinical evidence registries, with mid-cap suppliers disproportionately affected by notified body capacity constraints and extended technical documentation review timelines.
Subscription-based equipment access models are displacing capital purchase structures in independent gynecology practices, with per-procedure leasing arrangements bundled with maintenance and software updates reducing upfront investment barriers and aligning vendor revenue to utilization rates, this pattern most visible in United States metropolitan markets with high practice consolidation.
Ovarian Cysts Market Segmentation
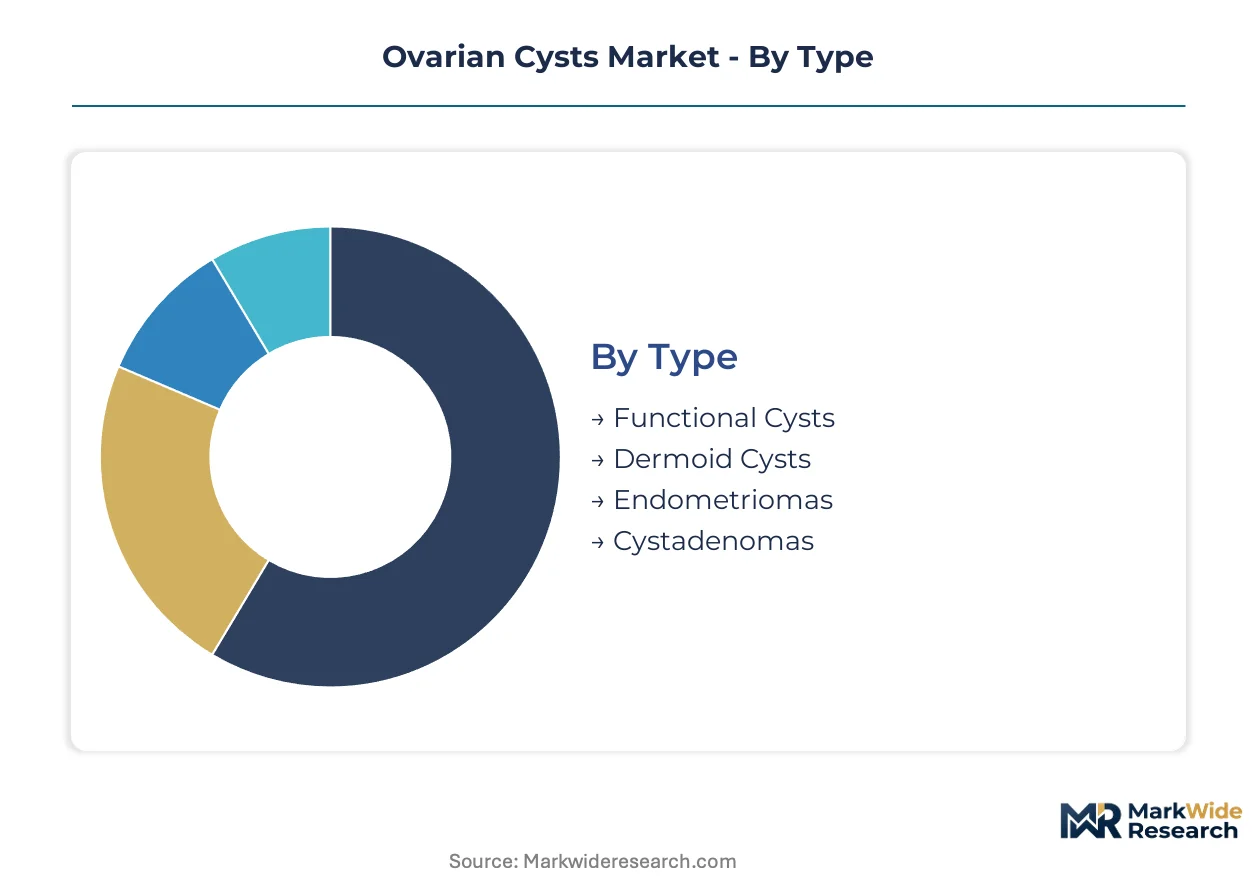
Segmentation in the ovarian cysts market reveals divergent clinical pathways shaped by cyst histology, intervention setting, and diagnostic modality. Volume concentration and premium economics split unevenly across categories, with spontaneous resolution profiles in functional formations contrasting sharply with specialized surgical margins in endometrioma management.
Type:
Volume concentrates in functional formations while premium economics cluster in pathological variants requiring intervention.
- Functional Cysts:Follicular and corpus luteum formations constitute the predominant clinical encounter, characterized by spontaneous resolution within one to three menstrual cycles without therapeutic intervention. Demand concentrates in routine gynecological screening programs across United States tertiary care networks where transvaginal ultrasound protocols identify these transient structures, constraining addressable therapeutic revenue due to minimal intervention requirements.
- Endometriomas:Chocolate cysts arising from ectopic endometrial tissue command specialized procedural economics through their direct linkage to fertility preservation protocols and assisted reproductive technology workflows. Demand concentrates in integrated women's health campuses where laparoscopic excision techniques intersect with in-vitro fertilization counseling, generating premium margins distinct from routine functional cyst management.
- Dermoid Cysts:Teratomas containing mature tissue derivatives including skin, hair, and teeth require surgical excision due to torsion risk and cosmetic concerns.
- Cystadenomas:Serous and mucinous epithelial neoplasms necessitate histological evaluation to exclude malignancy, driving surgical referral volumes.
Mature deployment sits with Functional Cysts in established screening workflows. Newer deployment is concentrated in Endometriomas through fertility-linkage protocols.
End User:
Margin pools redistribute from inpatient facilities toward ambulatory settings optimized for same-day discharge throughput.
- Ambulatory Surgical Centers:Outpatient facilities capture concentrated margin pools through laparoscopic excision protocols designed for rapid patient turnover and reduced facility overhead. Demand is accelerating in United States metropolitan markets where practice consolidation and subscription-based equipment access models reduce capital barriers for independent gynecology groups.
- Hospitals:Tertiary care institutions anchor complex case management including malignancy exclusion and emergency torsion intervention, maintaining volume leadership through integrated radiology and surgical departments. Demand concentrates in academic medical centers where AI-enhanced imaging workstations and specialized sonographer training programs support high-throughput screening workflows.
- Clinics:Community gynecology practices and point-of-care settings deploy portable ultrasound systems for initial detection and surveillance.
- Research Institutions:Academic and clinical trial centers drive biomarker validation and imaging algorithm development for risk stratification protocols.
Established infrastructure sits with Hospitals. Capacity expansion is climbing the fastest in Ambulatory Surgical Centers.
Diagnosis Method:
Cost tier stratification separates commoditized first-line detection from premium characterization protocols.
- Ultrasound:Transvaginal and abdominal sonography dominate first-line detection through non-invasive assessment of lesion diameter, echogenicity, and vascular flow patterns. Demand concentrates in United States screening workflows where FDA 510(k) clearances for contrast agents streamline protocol adoption, though sonographer specialization scarcity constrains throughput in high-volume programs.
- MRI:Multiparametric magnetic resonance imaging commands premium positioning for indeterminate mass characterization and pre-surgical planning. Demand is gaining share fastest in payer-covered risk stratification protocols that redirect complex cases away from ultrasound-dominated workflows toward specialized radiology interpretation.
- CT Scan:Computed tomography serves emergency torsion evaluation and malignancy staging where rapid anatomical assessment overrides radiation exposure concerns.
- Blood Tests:CA-125 and HE4 biomarker panels supplement imaging for malignancy risk assessment in postmenopausal patients.
Standard deployment sits with Ultrasound. Advanced deployment is concentrated in MRI-based characterization protocols.
Treatment Approach:
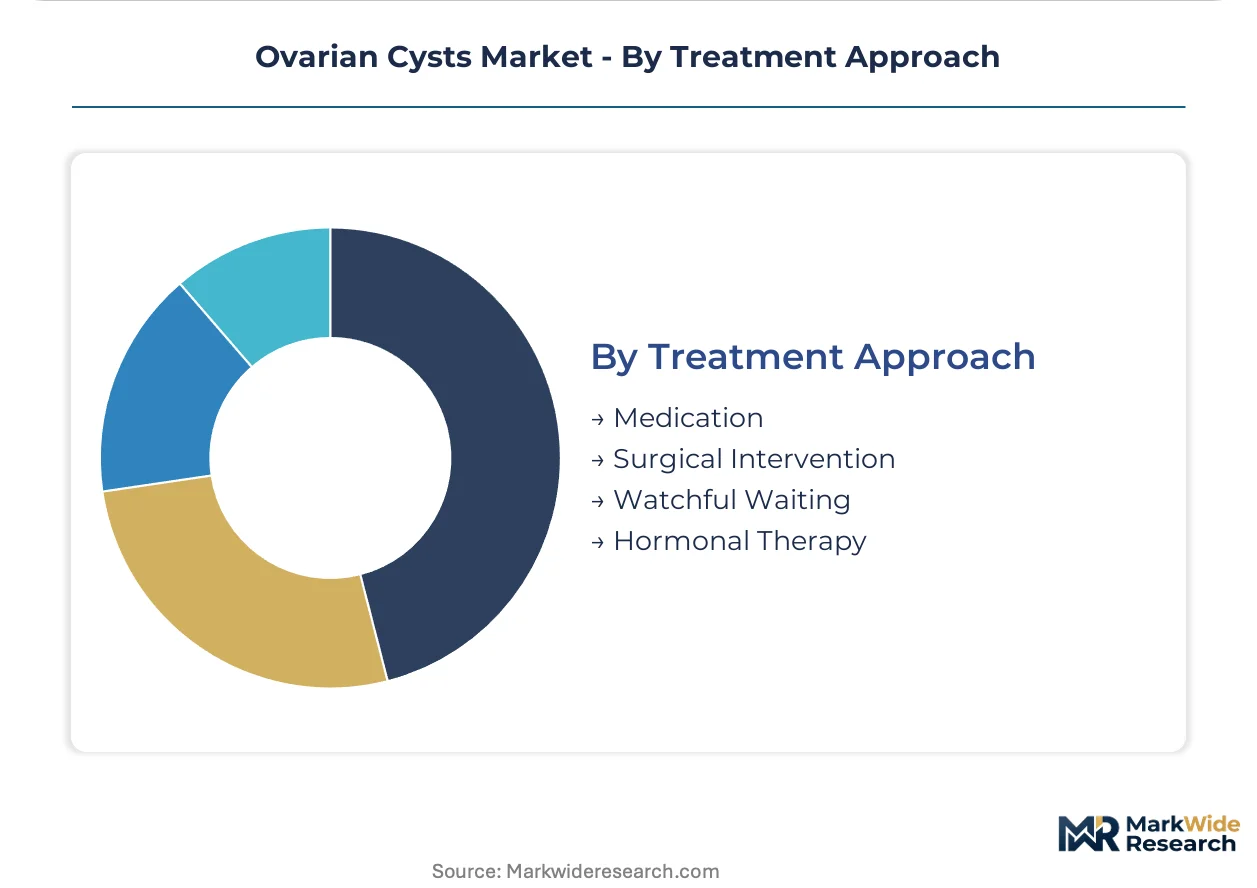
Application context determines intervention selection, with fertility status and symptom severity driving pathway divergence.
- Surgical Intervention:Laparoscopic cystectomy and oophorectomy procedures capture premium economics in endometrioma and dermoid management where tissue preservation or malignancy exclusion mandates operative intervention. Demand concentrates in ambulatory surgical centers equipped with precision instrumentation from German and Japanese manufacturing clusters, exposing procurement chains to geographic supply concentration.
- Hormonal Therapy:Oral contraceptives and GnRH agonists suppress ovulation to prevent functional cyst recurrence and reduce endometrioma progression. Demand is expanding most quickly in fertility preservation protocols where temporary ovarian suppression protects oocyte reserve prior to assisted reproductive technology cycles.
- Medication:Analgesics and anti-inflammatory agents address symptomatic management without structural intervention.
- Watchful Waiting:Surveillance protocols predominate in functional cyst monitoring where spontaneous resolution probability exceeds intervention benefit.
Conservative deployment sits with Watchful Waiting. Intervention-focused deployment is concentrated in Surgical Intervention and Hormonal Therapy pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Shenzhen and Shanghai concentrate diagnostic device manufacturing for Asia-Pacific distribution. Special economic zones in Ireland and the Netherlands anchor European pharmaceutical packaging and logistics. Tax-advantaged research corridors in North Carolina and Massachusetts accelerate clinical trial recruitment for hormonal therapy development.
United States
Tertiary care networks in Boston, Houston, and Cleveland integrate transvaginal ultrasound into routine screening workflows. FDA 510(k) clearances for contrast agents compress premarket validation timelines for imaging manufacturers. The Research Triangle Park corridor in North Carolina hosts contract research organizations managing multi-site endometrioma trials.
Germany
Precision surgical instrument manufacturing clusters in Tuttlingen and Solingen supply laparoscopic excision equipment to ambulatory surgical centers. MDR technical documentation requirements extend certification cycles, elevating cost-of-entry for European market access. Bavarian medical technology hubs in Munich and Erlangen develop AI-enhanced imaging workstations for ovarian mass characterization.
Japan
PMDA accelerated approval pathways for imaging devices support rapid commercialization of portable ultrasound systems. METI funding for women's health infrastructure expands gynecological screening capacity in Tokyo and Osaka metropolitan areas. Nagoya-based manufacturing clusters produce high-resolution transducers for lesion vascular flow assessment.
India
National health mission expansions in tier-2 cities create first-mover advantages for diagnostic device suppliers establishing service networks. CDSCO streamlined medical device registration compresses import clearance timelines for ultrasound equipment. Private hospital chains in Bengaluru, Hyderabad, and Pune deploy point-of-care screening capabilities in community health centers.
United Kingdom
NHS England reimbursement protocols for MRI-based ovarian mass characterization redirect diagnostic volumes from ultrasound-dominated workflows. MHRA post-Brexit regulatory autonomy enables accelerated clearance pathways for AI-enhanced risk stratification algorithms. London academic medical centers anchor specialized endometrioma management protocols tied to fertility preservation services.
Ovarian Cysts Market Competitive Environment
United States pharmaceutical conglomerates anchor the hormonal therapy tier; German and Swiss diagnostic specialists hold imaging and surgical equipment segments. The market structure splits between consolidated pharmaceutical portfolios and fragmented device manufacturing clusters. Three archetypes dominate: endocrinology-focused drug developers, ultrasound equipment alliances, and precision surgical instrument fabricators. Competitive moves concentrate on diagnostic imaging partnerships and ambulatory surgical center supply contracts.
Within the pharmaceutical tier, Pfizer Inc. and Bayer AG exemplify endocrinology portfolio leverage and diagnostic imaging alliance strategies respectively. Among diversified healthcare conglomerates, Novartis AG and AstraZeneca plc occupy positions spanning oncology and women's health therapeutic development. Merck & Co., Inc. represents the research-intensive archetype with historical concentration in reproductive endocrinology segments.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck & Co., Inc. |
| AbbVie Inc. |
| AstraZeneca plc |
| Bayer AG |
| Novartis AG |
| Medtronic plc |
| Teva Pharmaceutical Industries Ltd. |
| GlaxoSmithKline plc |
| Others |
Value Chain & Pricing Dynamics
Ambulatory surgical center procurement consolidation in United States metropolitan markets is compressing vendor margins and forcing equipment manufacturers toward subscription-based pricing models that bundle maintenance and software updates into per-procedure leasing arrangements.
Pricing Analysis
Short lead-time premiums for precision laparoscopic instruments from German and Japanese manufacturing clusters command pricing advantages over spot inventory sourced through secondary distributors. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared AI-enhanced imaging workstations from CE-marked baseline ultrasound systems and unbranded portable devices. Pricing pressure stems from MDR technical documentation requirements elevating European market entry costs for mid-cap suppliers. Hospital purchasing committees exhibit highest price sensitivity due to capital budget constraints, while fertility preservation centers demonstrate lowest sensitivity given procedural economics.
Supply Chain Analysis
Single-source vulnerability sits with high-resolution transducer manufacturing concentrated in Nagoya-based production clusters and precision surgical instrument fabrication anchored in Tuttlingen and Solingen. Raw material dependencies include medical-grade stainless steel, piezoelectric ceramics, and specialized optical components. Tariff exposure on imported imaging equipment from Asia-Pacific manufacturing zones presents structural risk to procurement timelines. Distribution runs through specialized medical device distributors serving hospital systems and direct-to-clinic channels for portable ultrasound systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ovarian cysts market is navigating a technology-transition phase where AI-enhanced risk stratification algorithms are displacing conventional radiologist interpretation workflows in tertiary care screening programs.
For Market Incumbents: Lock in ambulatory surgical center supply contracts through exclusive leasing arrangements that bundle precision instrumentation with training and maintenance services. Deepen backward integration into transducer manufacturing to reduce exposure to Japanese supply concentration. Fortify positions against portable ultrasound entrants by embedding AI software companion capabilities into fixed-installation imaging workstations.
For New Entrants and Emerging Players: Direct-to-clinic digital sales channels bypass traditional distributor markups and accelerate penetration of independent gynecology practices in United States metropolitan consolidation zones. Target tier-2 Indian cities where national health mission expansions create first-mover advantages for point-of-care screening devices. Pursue CDSCO streamlined registration pathways to compress import clearance timelines relative to MDR-burdened European competitors.
For Investors and Strategic Acquirers: The window for entry favors mid-cap diagnostic device specialists with established FDA 510(k) clearance track records and service network infrastructure in high-growth Asia-Pacific corridors. Long-term viability hinges on capabilities spanning both imaging hardware and AI software development. Monitor payer coverage determinations for MRI-based characterization protocols as the inflection signal for diagnostic modality share shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Streamlined premarket notification compresses commercialization timelines for contrast-enhanced ultrasound agents. |
| CE Marking Pathway | MDR technical documentation requirements extend certification cycles, elevating cost-of-entry for European distribution. |
| Hospital System Partnership | Integrated women's health campuses generate premium procedural economics through fertility preservation linkages. |
| Software Companion Development | AI-assisted lesion measurement algorithms differentiate portable systems in point-of-care screening workflows. |
| Reimbursement Strategy | Payer coverage determinations for MRI-based risk stratification redirect diagnostic volumes from ultrasound-dominated pathways. |
Study Parameters
Independent corroboration across gynecological imaging specialists, ambulatory surgical center administrators, and hospital procurement managers underwrites the qualitative findings in this study. Primary fieldwork encompassed structured interviews with biomedical engineers, GPO contracts managers, and regulatory affairs leads at diagnostic device manufacturers. Secondary validation drew from FDA 510(k) filings, EMA medical device regulation submissions, hospital procurement databases, and CMS reimbursement determinations. Bottom-up segmentation modeling triangulated against top-down market sizing across cyst type, intervention setting, and diagnostic modality dimensions.
Comparable-period anchoring to established screening workflow adoption curves informed the projection framework across the analysis window. Segmentation dimensions modeled include cyst histology classification, end-user facility type, diagnostic modality tier, and regional regulatory cluster. CAGRs were derived from weighted average growth contributions across segment-level volume and value trajectories. Forecast inputs incorporated sonographer specialization scarcity constraints, MDR certification timeline extensions, and fertility preservation protocol expansion rates.
The model holds under stable reimbursement environments and continued FDA 510(k) pathway efficiency; deviation in payer coverage determinations or notified body capacity constraints would shift volume projections. Forecasts reflect assumptions regarding AI algorithm adoption curves and ambulatory surgical center buildout rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Nocturnal Polyuria Treatment Market
Specialty Medicine
Hermansky Pudlak Syndrome Therapeutics Market
Specialty Medicine
Global Herpes Market
Specialty Medicine
Myasthenia Gravis Market
Specialty Medicine
Global Urea Cycle Disorder Market
Specialty Medicine
Global Chronic Idiopathic Constipation Market
Specialty Medicine
Axial Spondyloarthritis Treatment Market
Specialty Medicine
Lipoprotein Metabolism Disorders Treatment Market
Specialty Medicine
Achondroplasia Treatment Market
Specialty Medicine
Angioimmunoblastic T-Cell Lymphoma (AILT) Market
Specialty Medicine
North America Alopecia Market
Specialty Medicine
Global Plasma Protease C1 Inhibitor Treatment Market
Specialty Medicine
Primary Biliary Cholangitis (PBC) Treatment Market
Specialty Medicine
Global Post Traumatic Stress Disorder (PTSD) Therapeutics Market
Specialty Medicine
Chordoma Disease Therapeutics Market
Specialty Medicine
Polycystic Kidney Disease Treatment Market