
 Menopause Wellness Market | 2026-2036
Menopause Wellness Market Size, Share, and Industry Trends Forecast 2026-2036
Menopause Wellness Market Analytics
North American compounding pharmacies is decoupling from traditional pharmaceutical supply chains as personalized hormone formulations gain traction. Elektra Health leverages telemedicine infrastructure to extend clinical reach beyond metropolitan hubs. Hims & Hers anchors its position through direct-to-consumer distribution and subscription-based continuity care. HerMD specializes in menopause-specific brick-and-mortar clinics, occupying a differentiated physical-channel niche that digital-native competitors have not replicated.
Menopause wellness encompasses therapeutic and preventive interventions targeting hormonal transition symptoms through pharmacological, botanical, and behavioral modalities; hormone replacement therapy formulations typically combine estradiol with progestogen in standardized or compounded ratios, while transdermal patches deliver controlled release at microgram-per-hour rates. The product landscape segments into hormone replacement therapy commanding the largest revenue pool due to prescription dependency and clinical validation, herbal supplements representing the fastest-expanding category as consumers seek non-pharmaceutical alternatives, and mood support formulations capturing concentrated margin opportunities through premium positioning. Application demand clusters around hot flashes as the most frequently reported symptom driving initial clinical consultation, with sleep disorders emerging as a high-retention indication due to chronic management requirements.
FDA oversight of compounded bioidentical hormones under Section 503A of the Federal Food, Drug, and Cosmetic Act shapes manufacturer compliance burdens and product availability constraints, while state-level pharmacy board regulations create fragmented dispensing requirements across jurisdictions. The Drug Enforcement Administration and state controlled-substance authorities additionally govern testosterone and certain hormonal adjuncts used off-label in menopause protocols. Stakeholders must monitor evolving FDA draft guidance on 503B outsourcing facilities versus traditional compounding, as reclassification would reshape competitive economics for Midi Health, Jayla Health, and NNABI.
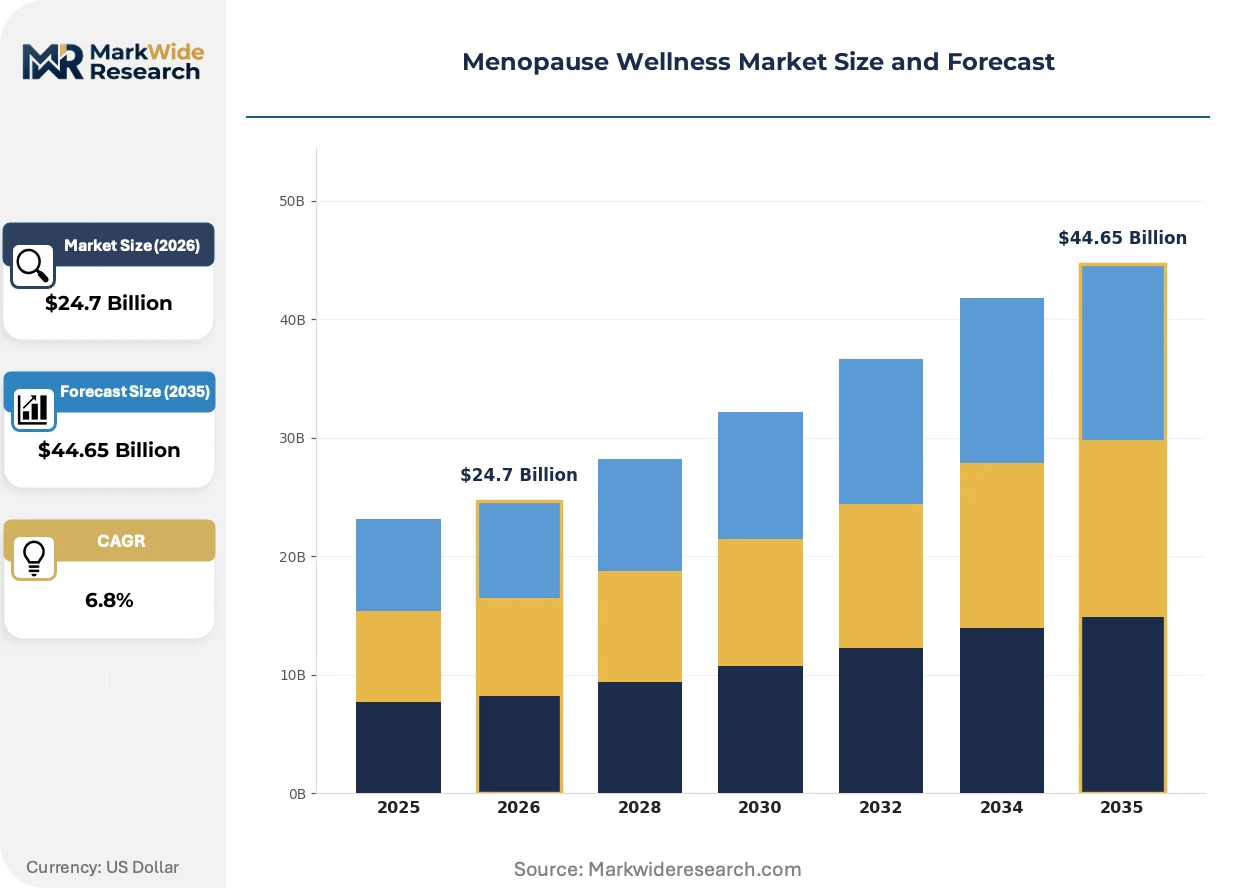
Market Dynamics
FDA Section 503A enforcement is fragmenting compounded hormone supply chains as traditional 503A pharmacies face heightened scrutiny while 503B outsourcing facilities gain regulatory clarity, forcing manufacturers to reconfigure production footprints and compliance architectures.
Growth Catalysts
- Employer-sponsored telemedicine expansion:Large self-insured employers are adding menopause-specific benefits to reduce absenteeism and retention costs, channeling demand toward virtual-first care models.
- Bioidentical hormone compounding standardization:State pharmacy boards in California, Texas, and Florida are harmonizing quality standards for estradiol-progesterone formulations, reducing interstate dispensing friction.
- Perimenopause symptom recognition:Diagnostic criteria refinement by the North American Menopause Society is expanding addressable patient populations earlier in the hormonal transition timeline.
Market Restraints
- Active pharmaceutical ingredient concentration:Estradiol and micronized progesterone API supply concentrates among three Indian and Chinese manufacturers, creating single-source vulnerability for US compounders.
- Transdermal patch manufacturing complexity:Multi-layer adhesive matrix production requires specialized coating equipment with 18-24 month lead times, constraining capacity expansion.
- Testosterone scheduling friction:DEA Schedule III classification for off-label female testosterone therapy triggers state-level prescription monitoring program variances that complicate multi-state practice.
Strategic Opportunities
- Underserved rural and exurban geographies:Federally Qualified Health Centers in Appalachia and the Great Plains lack menopause-specialized providers, creating whitespace for asynchronous telemedicine platforms.
- Menopause-friendly workplace certification:The Menopause Society's employer accreditation program creates B2B channel demand for bundled education, symptom tracking, and care navigation services.
- Continuous glucose monitoring convergence:Integration of CGM data with hormonal symptom tracking enables personalized lifestyle intervention protocols for metabolic symptom clusters.
Industry Challenges
- Reproductive endocrinology workforce scarcity:Fellowship-trained menopause specialists number under 1,500 nationally, forcing reliance on OB-GYN generalists with limited hormonal therapy training.
- Compounding pharmacy GMP retrofit costs:USP <795> and <797> revisions require environmental monitoring and cleanroom infrastructure investments that strain independent pharmacy economics.
- EHR interoperability gaps:Menopause-specific symptom scoring tools lack standardized integration with Epic, Cerner, and Athenahealth workflows, fragmenting care continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Menopause Wellness Market |
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $44.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hormone Replacement Therapy, Herbal Supplements, Nutritional Products, Mood Support Application: Hot Flashes, Sleep Disorders, Mood Swings, Vaginal Dryness End User: Hospitals, Clinics, Home Care, Wellness Centers Delivery Mode: Topical, Oral, Injectable, Transdermal |
| Companies Covered | Elektra Health, Gliss Wellness, Hims & Hers, Fertifa, Stripes, HerMD, Jayla Health, NNABI, Midi Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Menopause Wellness Market Evolving Landscape
Digital biomarker integration is compressing the diagnostic gap between symptom onset and clinical intervention, while regulatory clarity on compounded formulations is reordering competitive economics across manufacturing tiers.
Transdermal hormone delivery systems are consolidating market preference as estradiol patches and gels demonstrate superior thrombotic risk profiles versus oral formulations. Self-insured employers and Medicare Advantage plans are steering formulary placement toward transdermal options. This consolidation is compressing oral HRT prescription volumes and forcing legacy tablet manufacturers to defend hospital and cash-pay channels.
FDA draft guidance distinguishing traditional 503A compounding from 503B outsourcing facility production is reshaping manufacturer compliance investments. Facilities producing "essentially copies" of commercially available drugs face restricted interstate distribution. Compounding pharmacies in high-enforcement districts are consolidating into regional 503B networks or exiting hormone production entirely.
Subscription-based continuity care is displacing episodic menopause consultations as the dominant commercial model. Direct-to-consumer platforms bundle asynchronous messaging, prescription management, and symptom tracking into annual contracts. This shift is most visible in metropolitan markets where employer benefits administrators prefer predictable per-member-per-month pricing over fee-for-service unpredictability.
Menopause Wellness Market Segmentation
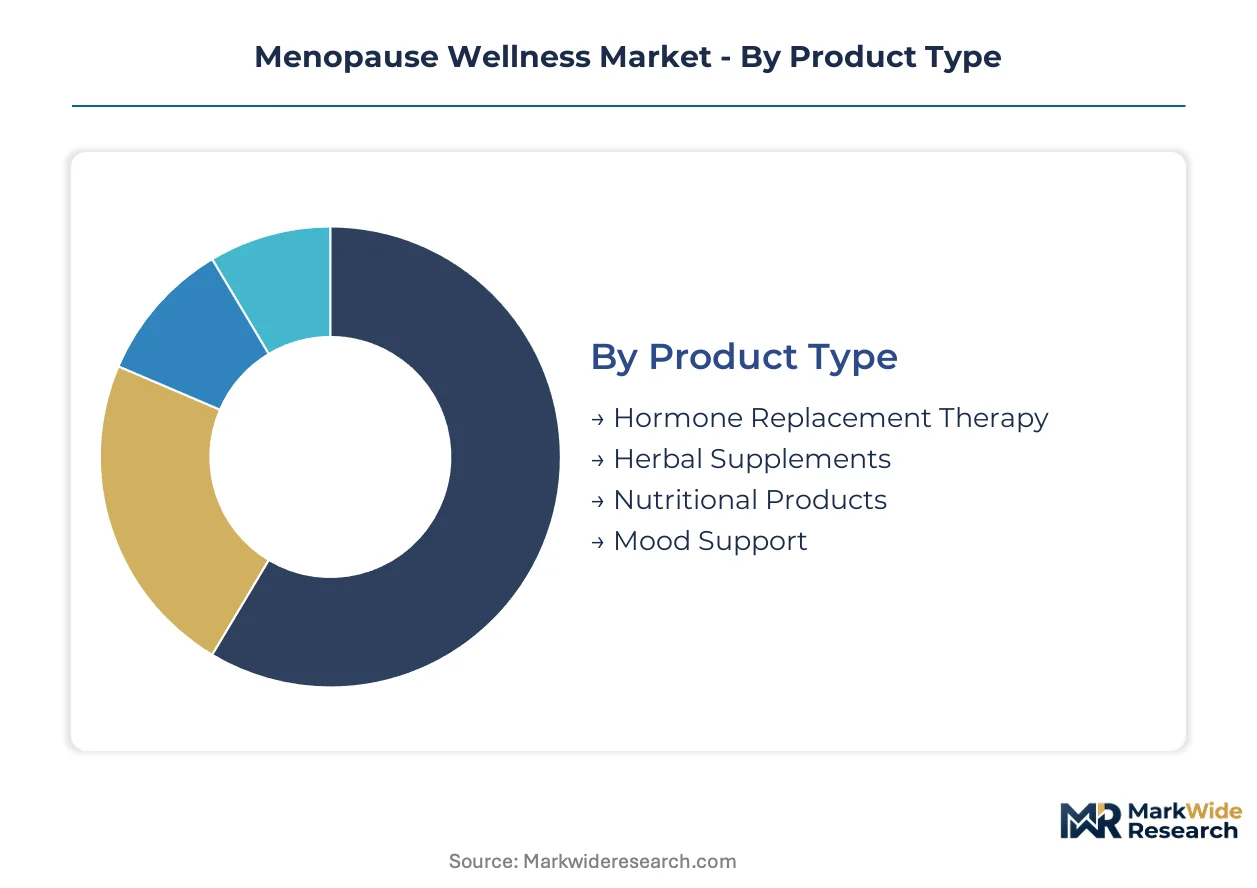
Segmentation in menopause wellness reveals divergent capital requirements across manufacturing modalities. Product type and delivery mode categories demand specialized infrastructure investments that reshape competitive economics for market participants.
Product Type:
Hormone replacement therapy absorbs the heaviest upfront investment burden due to sterile manufacturing requirements and regulatory compliance architecture.
- Hormone Replacement Therapy:Estradiol-progesterone formulations require multi-stage synthesis and USP <795>/<797> compliant cleanroom infrastructure. Demand concentrates in employer-sponsored benefits programs where clinical validation drives formulary placement, though API sourcing from concentrated Indian and Chinese suppliers creates supply vulnerability.
- Herbal Supplements:Botanical extracts including black cohosh and red clover undergo standardized marker compound testing without prescription-level GMP burden. Consumer preference for non-pharmaceutical alternatives is expanding addressable populations fastest, particularly in direct-to-consumer channels seeking subscription continuity.
- Nutritional Products:Calcium-vitamin D complexes and omega-3 formulations target bone density and cardiovascular support adjunctively.
- Mood Support:Adaptogenic and nootropic blends command premium positioning through concentrated margin structures.
Most installed capacity flows through hormone replacement therapy. Expansion is steepest in herbal supplements.
Application:
Volume concentration varies sharply by symptom chronicity and consultation frequency, with sleep-related indications sustaining longer patient relationships.
- Hot Flashes:Vasomotor symptom severity drives initial clinical consultation and prescription initiation across all channels. Severity scoring tools deployed by the North American Menopause Society standardize diagnostic thresholds, expanding reimbursable intervention windows.
- Sleep Disorders:Chronic insomnia and night sweat disruption require sustained management protocols with highest retention economics. Medicare Advantage plans increasingly cover sleep-focused menopause benefits, channeling volume toward integrated care models.
- Mood Swings:Anxiety-depression symptom clusters attract behavioral health crossover referrals.
- Vaginal Dryness:Localized estrogen therapy and lubricant products address genitourinary syndrome with discrete prescribing patterns.
Patient acquisition costs are lowest in hot flashes. Lifetime value peaks in sleep disorders.
End User:
Channel selection determines pricing power and regulatory exposure, with institutional buyers extracting volume discounts unavailable in consumer-direct pathways.
- Hospitals:Academic medical centers anchor evidence-based protocol development and specialist training pipelines. OB-GYN residency programs at institutions including Johns Hopkins and Mayo Clinic integrate menopause-specific curricula, shaping prescriber behavior downstream.
- Clinics:Dedicated perimenopause-focused networks such as HerMD and Midi Health consolidate physical-channel presence in metropolitan markets. Brick-and-mortar density in Texas and Florida markets outpaces national averages, reflecting demographic concentration and regulatory permissiveness.
- Home Care:Telemedicine platforms and mail-order pharmacies reduce geographic access barriers.
- Wellness Centers:Integrative medicine practices bundle hormonal assessment with lifestyle coaching.
Revenue per encounter is highest in hospitals. Visit frequency concentrates in clinics.
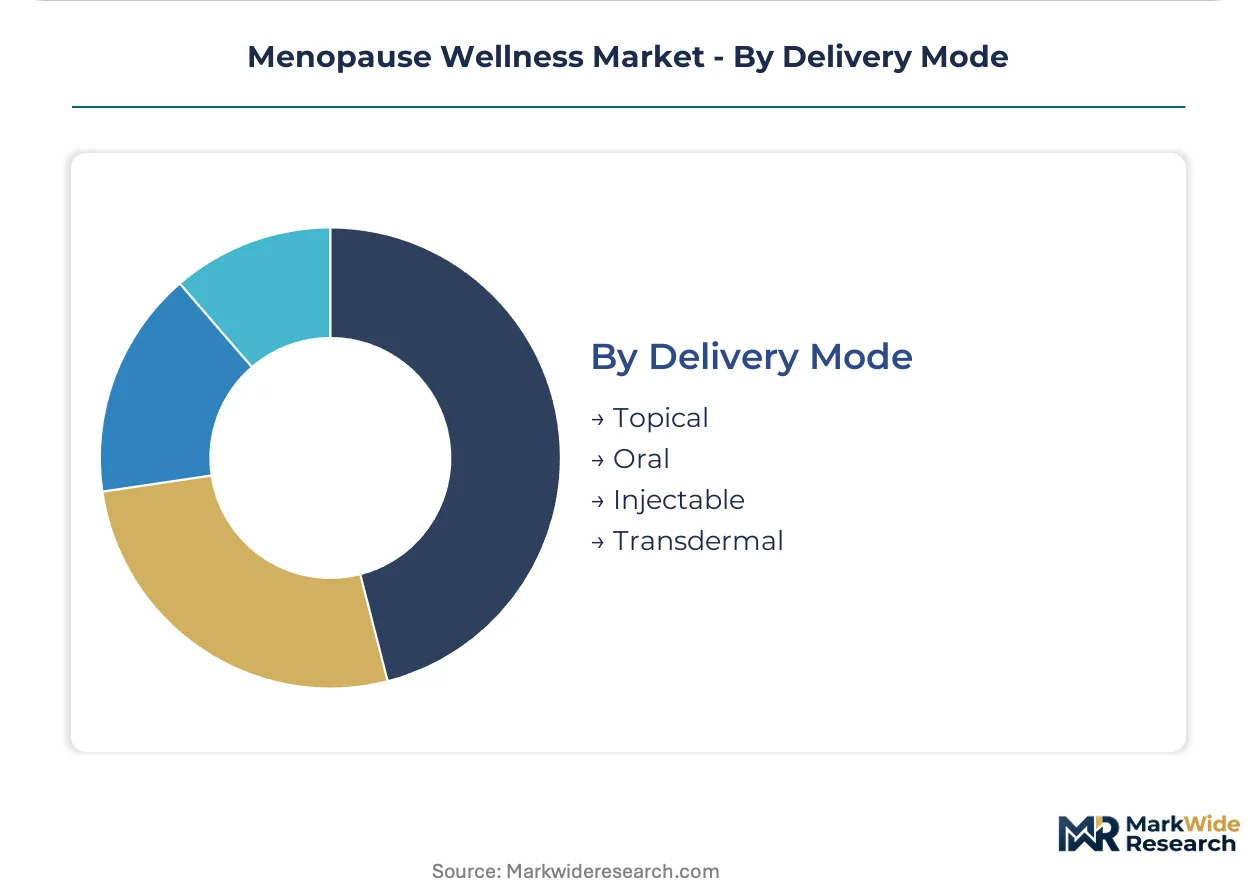
Delivery Mode:
Manufacturing complexity and capital intensity escalate from oral solids through multi-layer transdermal systems, reordering competitive moats by technical capability.
- Transdermal:Multi-layer adhesive matrix patches deliver estradiol at microgram-per-hour rates with superior thrombotic risk profiles versus oral routes. Self-insured employers and Medicare Advantage plans steer formulary placement toward transdermal options, compressing oral prescription volumes and forcing legacy tablet manufacturers toward defensive positioning.
- Oral:Compressed tablets and capsules dominate historical prescription volumes with lowest unit manufacturing cost. Hospital and cash-pay channels sustain residual demand despite formulary displacement, particularly where patch adhesion issues or skin sensitivity limit transdermal tolerability.
- Topical:Gels and creams offer dose flexibility with intermediate manufacturing requirements.
- Injectable:Depot formulations serve non-compliant or convenience-seeking populations with extended dosing intervals.
Equipment utilization is tightest in transdermal. Capacity additions are proceeding fastest in oral.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands the highest per-capita spending on menopause-specific interventions, while Germany anchors European regulatory harmonization efforts for bioidentical hormone formulations.
United States
Employer-sponsored benefits expansion and direct-to-consumer telemedicine platforms drive demand concentration. FDA Section 503A enforcement under the Federal Food, Drug, and Cosmetic Act reshapes compounding pharmacy compliance requirements. Texas and Florida host the densest clinic networks, with HerMD and Midi Health expanding brick-and-mortar presence in metropolitan markets.
Germany
Statutory health insurance reimbursement for hormone replacement therapy sustains prescription volumes through pharmacy channels. EMA guidance on transdermal estradiol formulations influences national pharmaceutical regulator positioning on thrombotic risk profiles. Bavaria and North Rhine-Westphalia concentrate compounding pharmacy infrastructure serving cross-border Austrian and Dutch patients.
United Kingdom
NHS menopause pathway standardization expands specialist referral access through primary care networks. National Institute for Health and Care Excellence guidelines on hormone therapy duration limit long-term prescribing patterns. London and Southeast England anchor private clinic density, with telemedicine platforms extending reach into underserved Midlands and Northern regions.
Canada
Provincial formulary variations create fragmented reimbursement landscapes for compounded formulations. Health Canada oversight of bioidentical hormones under the Food and Drugs Act parallels FDA Section 503A structures. Ontario and Quebec concentrate menopause-focused clinical research and specialist training programs at academic medical centers.
Australia
Pharmaceutical Benefits Scheme listing decisions determine transdermal patch accessibility and patient out-of-pocket exposure. Therapeutic Goods Administration scheduling of testosterone for off-label female use creates prescription monitoring complexities. New South Wales and Victoria host the majority of specialized menopause clinics and telemedicine platform headquarters.
Menopause Wellness Market Competitive Landscape
United States digital health platforms anchor one tier; European wellness specialists hold regional pharmacy-channel positions. The vendor base separates into telemedicine-native providers, brick-and-mortar clinic networks, and employer benefits administrators. Three archetypes dominate: virtual-first care platforms, physical-channel consolidators, and B2B benefits intermediaries. Capacity expansion and strategic partnerships constitute the primary competitive vectors.
Within the telemedicine-native tier, Elektra Health and Hims & Hers exemplify subscription-based continuity care models. HerMD occupies a differentiated position among brick-and-mortar consolidators. Midi Health and Jayla Health represent emerging platforms navigating FDA compounding guidance evolution.
| Leading Market Players |
|---|
| Elektra Health |
| Gliss Wellness |
| Hims & Hers |
| Fertifa |
| Stripes |
| HerMD |
| Jayla Health |
| NNABI |
| Midi Health |
| Others |
Value Network & Pricing Analysis
Captive API sourcing from Indian and Chinese manufacturers anchors both cost structures and pricing power for US compounders, with vertical integration into estradiol and micronized progesterone production determining margin resilience against formulary pressure from self-insured employers and Medicare Advantage plans.
Pricing Analysis
Capacity additions in transdermal patch manufacturing are reshaping price floors as specialized coating equipment with extended lead times constrains rapid supply response. Subscription-based continuity care dominates, with price differentiation driven by clinical validation tier and employer benefits integration depth. Cost compression in oral HRT is intensifying because formulary displacement to transdermal routes squeezes legacy tablet manufacturers. Self-insured employers show lowest price sensitivity; cash-pay channels face highest.
Supply Chain Analysis
USP <795> and <797> certification gating determines compounding pharmacy participation, with cleanroom retrofit requirements filtering independent operators. API supply concentrates in India, China, and Italy for estradiol and micronized progesterone. Raw material dependencies include pharmaceutical-grade ethanol, adhesive polymers, and release liner substrates. Single-source vulnerability runs through concentrated Indian and Chinese API manufacturers. Distribution runs through 503A compounding pharmacies, 503B outsourcing facilities, and mail-order direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA Section 503A enforcement evolution and 503B outsourcing facility clarification are accelerating demand consolidation toward compliant manufacturing tiers.
For Market Incumbents: Acquire 503B outsourcing facility licenses to secure interstate distribution rights as FDA draft guidance restricts traditional compounding. Defend against telemedicine-native entrants by anchoring formulary placement through employer benefits channel control. Capacity additions in Texas and Florida clinic networks reinforce physical-channel density that digital competitors cannot replicate. For New Entrants and Emerging Players: Federally Qualified Health Centers in Appalachia and the Great Plains represent the most penetrable buyer archetype, with asynchronous telemedicine platforms addressing workforce scarcity gaps. White-space targets include rural perimenopause populations and employer certification bundling services. Go-to-market through B2B benefits administrators enables predictable per-member-per-month revenue capture. For Investors and Strategic Acquirers: Roll-up economics work for regional 503B networks because FDA enforcement fragmentation is forcing independent 503A pharmacies to exit or consolidate. Long-term viability centers on platforms with compliant manufacturing infrastructure and employer channel lock-in. Watch FDA final guidance on 503B "essentially copies" classification as the inflection signal for competitive economics reordering.| Strategic Initiative | Industry Significance |
|---|---|
| 503B Outsourcing Facility Licensing | Secures interstate distribution rights under evolving FDA enforcement priorities for compounded hormones. |
| Employer Benefits Channel Partnership | Locks in predictable per-member-per-month revenue through self-insured plan formulary placement. |
| Transdermal Manufacturing Capacity Expansion | Captures formulary displacement from oral HRT as thrombotic risk profiles steer payer preference. |
| Telemedicine Platform Integration | Extends clinical reach beyond metropolitan hubs into federally qualified health center networks. |
| API Supply Chain Backward Integration | Reduces single-source vulnerability to Indian and Chinese pharmaceutical ingredient concentration. |
Research Methodology
Direct dialogue with compounding pharmacy operators, employer benefits administrators, reproductive endocrinologists, and FDA regulatory affairs specialists grounded qualitative insights, validated against FDA guidance documents, USP compounding standards, CMS Medicare formulary data, and state pharmacy board regulations. Bottom-up and top-down triangulation cross-checked prescription volume trends with employer benefits adoption metrics.
Bottom-up modeling anchored segmentation across hormone replacement therapy, herbal supplements, nutritional products, and mood support categories, with delivery mode, application symptom, and end-user channel dimensions. Top-down validation referenced macro healthcare expenditure patterns and demographic transition timelines. CAGRs were derived from fitted growth curves across the projection horizon, with inputs including FDA enforcement trajectory, employer benefits penetration rates, and compounding pharmacy consolidation velocity.
Inputs from FDA draft guidance releases and state pharmacy board harmonization initiatives were available through the study window; gaps in real-time prescription monitoring program data and proprietary employer benefits claims introduce uncertainty bands around telemedicine platform market share estimates. Forecasts reflect documented assumptions on regulatory clarity timelines and workforce training pipeline expansion. A model refresh is warranted upon material change in FDA final guidance on 503B outsourcing facility classification.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Health
Patient Health Management Market
Personal Health
Asia Health Check-Ups Market
Personal Health
Global on Site Preventive Care Market
Personal Health
Workplace Wellness Market
Personal Health
Health Coaching Market
Personal Health
Menstrual Cup Market
Personal Health
Global OTC Hair Loss Treatment Market
Personal Health
Foot Insole Market
Personal Health
US Vaginal Moisturizers and Lubricants Market
Personal Health
Parents-In-Waiting: Global Prenatal Market
Personal Health
Asia Pacific Hair Loss Treatment Products Market
Personal Health
Medical Wellness Market
Personal Health
Smoking Cessation and Nicotine De Addiction Market
Personal Health
Global Weight Loss Services Market
Personal Health
Maternity Personal Care Products Market
Personal Health
Biohacking Market