
 Mitochondrial-Based Therapeutics Market | 2026-2036
Mitochondrial-Based Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Mitochondrial-Based Therapeutics Market Outlook
EMA's evolving advanced therapy medicinal products framework is restructuring the cost-of-entry calculus for European developers of mitochondrial gene therapies. Reata Pharmaceuticals leverages its Nrf2 activator platform to anchor rare mitochondrial disease indications. Takeda Pharmaceuticals sustains a broad rare disease pipeline that competes across multiple therapy areas. Pfizer Inc. differentiates through manufacturing scale and global distribution reach for specialized biologics.
Mitochondrial-based therapeutics comprise biologically active agents engineered to modulate mitochondrial function, restore cellular energy metabolism, or replace defective mitochondrial components through targeted delivery mechanisms. These interventions address primary mitochondrial disorders and secondary mitochondrial dysfunction arising from neurodegenerative, cardiovascular, and metabolic diseases. Small molecules currently dominate commercial revenue due to established manufacturing routes and oral bioavailability, while gene therapy represents the fastest-expanding segment as viral vector manufacturing matures and regulatory pathways clarify. Peptide therapy occupies a specialized niche where blood-brain barrier penetration and mitochondrial membrane targeting create premium pricing power.
FDA orphan drug incentives and EMA's ATMP classification collectively shape clinical development priorities and reimbursement negotiations for mitochondrial therapeutics. The NIH Office of Rare Diseases Research and the European Joint Programme on Rare Diseases further direct public funding toward investigator-initiated trials. Stakeholders must monitor how payer evidence requirements evolve for one-time gene therapies versus chronic small molecule regimens.
Market Dynamics
Gene therapy manufacturing scale-up is compressing development timelines for mitochondrial interventions while simultaneously intensifying competition for viral vector production capacity. This supply bottleneck is forcing developers to secure manufacturing partnerships before clinical proof-of-concept, fundamentally restructuring capital deployment sequencing across the sector.
Growth Catalysts
- Orphan drug incentives:The FDA's accelerated approval pathway and EMA's PRIME designation compress regulatory review timelines for mitochondrial drug candidates, reducing time-to-market for rare disease therapies.
- NIH funding concentration:Dedicated research streams through the Office of Rare Diseases Research sustain investigator-initiated trials and de-risk early-stage mitochondrial therapeutic discovery.
- Viral vector manufacturing maturation:Contract development and manufacturing organizations are expanding GMP capacity for AAV and lentiviral platforms, enabling gene therapy segment expansion.
Market Restraints
- Plasmid DNA supply concentration:Viral vector production depends on plasmid sourcing from a limited supplier base, creating input cost volatility and batch-to-batch consistency risks.
- ATMP reimbursement friction:EMA's advanced therapy classification creates pricing negotiation complexity with national payers unaccustomed to single-administration high-value therapies.
- Small molecule substitution:Chronic oral regimens for metabolic symptom management compete with curative gene therapy approaches on total cost-of-ownership metrics.
Strategic Opportunities
- Cardiovascular application expansion:Mitochondrial dysfunction in heart failure represents an underpenetrated indication where energy metabolism modulation shows clinical promise.
- Peptide blood-brain barrier delivery:Cyclosporin derivatives and mitochondrial-targeted antioxidants enable neurodegenerative applications where small molecules fail to achieve therapeutic CNS concentrations.
- Japan's Sakigake designation:PMDA's early approval pathway for regenerative medicines accelerates mitochondrial gene therapy market access in the world's third-largest pharmaceutical market.
Industry Challenges
- GMP vector manufacturing skill scarcity:Qualified personnel for cell culture, purification, and analytical development remain concentrated at a handful of contract manufacturers and large pharmaceutical firms.
- Biomarker validation timelines:Lack of validated surrogate endpoints for mitochondrial function forces reliance on clinical outcome measures, extending trial duration and capital requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mitochondrial-Based Therapeutics Market |
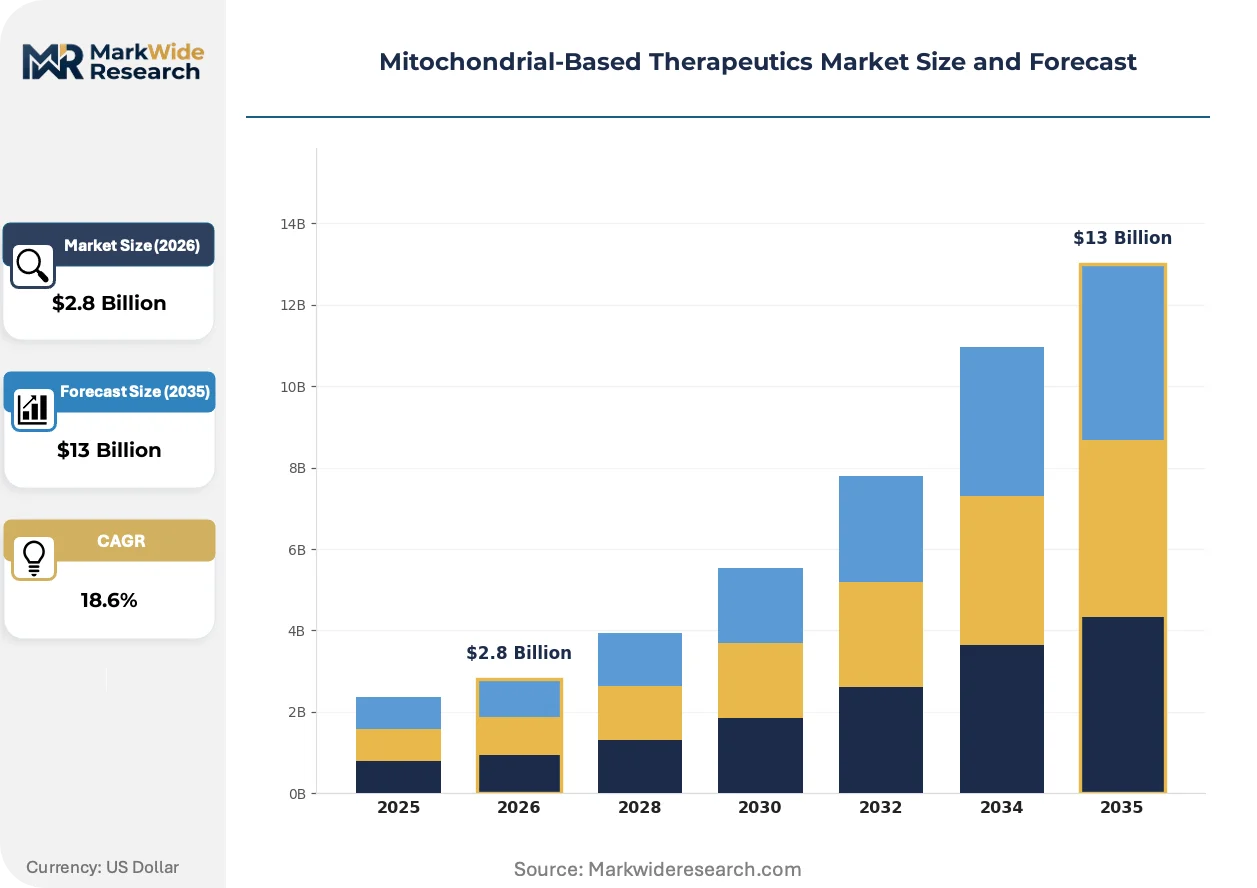
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gene Therapy, Small Molecules, Enzyme Replacement, Peptide Therapy Therapy Area: Neurological Disorders, Muscular Dystrophies, Cardiovascular Diseases, Metabolic Disorders End User: Hospitals, Research Laboratories, Specialty Clinics, Academic Institutions Delivery Mode: Intravenous, Subcutaneous, Oral, Localized |
| Companies Covered | Reata Pharmaceuticals, Takeda Pharmaceuticals, Pfizer Inc., Biogen, Amgen Inc., Novartis AG, NeuroVive Pharmaceutical AB, Khondrion, Stealth BioTherapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mitochondrial-Based Therapeutics Market Strategic Shifts
Bioconjugation chemistry and organelle-specific targeting moieties are redefining therapeutic index calculations for mitochondrial drug developers. These advances are compressing the gap between preclinical efficacy and clinical translation.
Mitochondria-penetrating peptides are integrating cell-penetrating sequences with delocalized lipophilic cations to achieve matrix-localized drug delivery. Academic medical centers and specialized biotechs are adopting these platforms for neurodegenerative and metabolic indications. This targeting precision is integrating previously undruggable mitochondrial enzymes into the therapeutic landscape while reducing off-tissue toxicity liabilities.
EMA's evolving ATMP framework is restructuring evidence requirements for gene therapies addressing primary mitochondrial disorders. The industrial consequence is a shift toward adaptive trial designs with integrated biomarker endpoints. Developers targeting Leigh syndrome and MELAS are most affected, responding by embedding natural history studies within pivotal trials to strengthen payer value demonstrations.
Hospital procurement committees are consolidating gene therapy purchasing decisions under centralized pharmacy and therapeutics committees rather than individual physician preference. Specialty distributors and manufacturer direct-to-site models are displacing traditional wholesale relationships for high-value biologics. This concentration is most visible in United States academic medical centers where mitochondrial disease referral networks concentrate patient volumes.
Mitochondrial-Based Therapeutics Market Segmentation
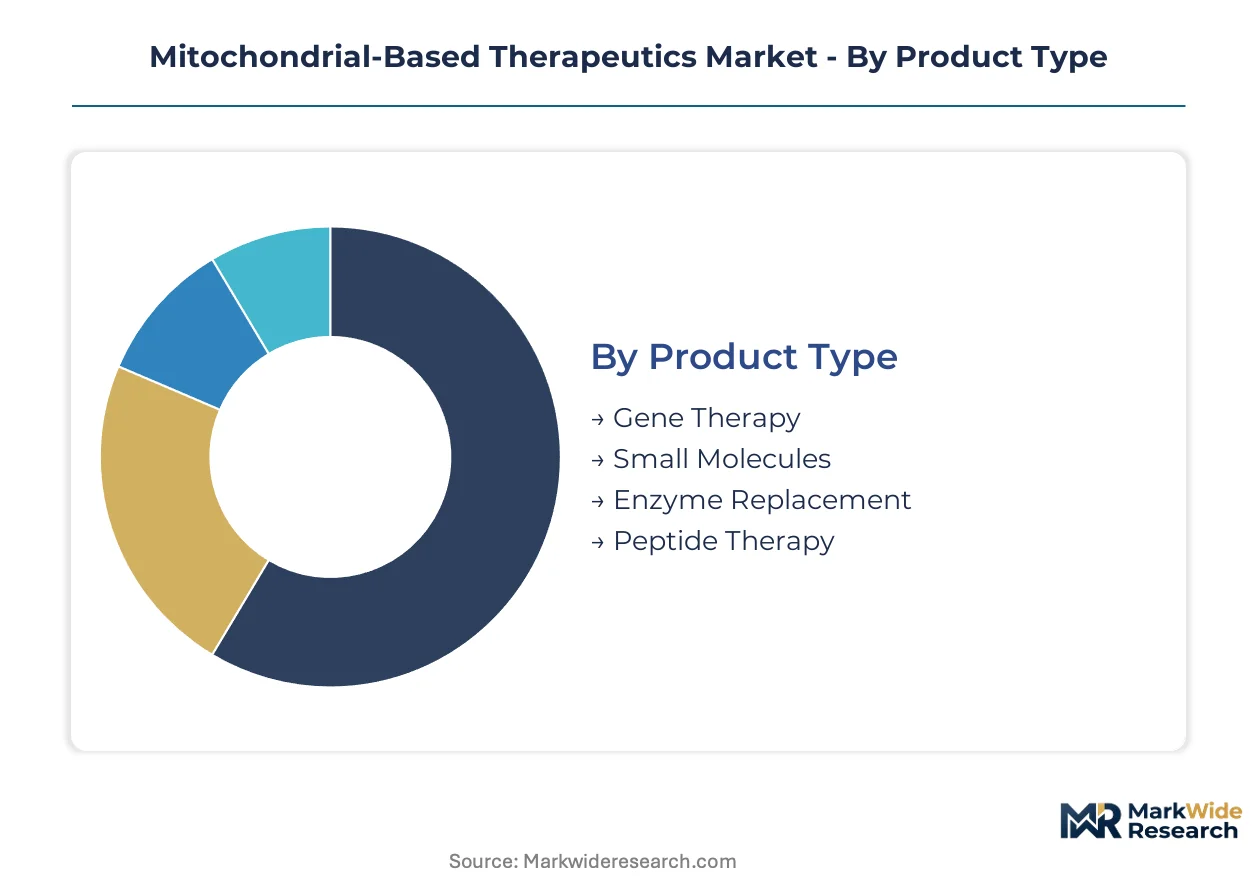
Mitochondrial therapeutics span modalities with vastly different capital requirements, from GMP viral vector facilities to conventional small molecule plants. Segment-specific investment profiles dictate partnership strategies and timeline risk for developers across the value chain.
Product Type:
Gene therapy manufacturing demands the heaviest upfront capital, with AAV production suites requiring $200-400 million per facility. Small molecules leverage depreciated oral solid dose infrastructure. Peptide synthesis occupies a middle tier, while enzyme replacement requires dedicated biologics capacity with specialized cold chain logistics.
- Gene Therapy:Viral vector-based delivery of functional mitochondrial DNA or nuclear-encoded mitochondrial proteins. United States academic medical centers concentrate demand as FDA accelerated approval pathways mature for rare disease indications. Manufacturing partnerships must close before Phase II to secure GMP slotting.
- Small Molecules:Orally bioavailable compounds modulating mitochondrial function through metabolic pathway intervention. Established contract manufacturers in India and China absorb volume as chronic administration regimens compete on total cost-of-ownership against curative alternatives. Regulatory familiarity accelerates payer negotiations.
- Enzyme Replacement:Recombinant proteins compensating for deficient mitochondrial enzymes. Intravenous infusion requirements limit administration to hospital settings with specialized metabolic disease expertise.
- Peptide Therapy:Short amino acid sequences engineered for mitochondrial membrane penetration. Blood-brain barrier targeting justifies premium positioning in neurodegenerative applications where small molecules fail.
Most installed capacity flows through Small Molecules. Expansion is steepest in Gene Therapy.
Therapy Area:
Neurological applications command the highest pricing power due to blood-brain barrier penetration challenges and unmet medical need. Cardiovascular indications represent emerging volume opportunity as energy metabolism science validates clinical endpoints. Metabolic and muscular applications anchor the orphan disease reimbursement framework.
- Neurological Disorders:Leigh syndrome, MELAS, and mitochondrial encephalomyopathies drive gene therapy pipeline concentration. United States referral networks at Boston Children's Hospital and Children's Hospital of Philadelphia aggregate patient volumes for natural history studies.
- Cardiovascular Diseases:Heart failure with preserved ejection fraction shows mitochondrial dysfunction biomarker validation. European Society of Cardiology guidelines are incorporating metabolic modulators as adjunctive therapy.
- Muscular Dystrophies:Mitochondrial myopathies and related myopathies require chronic intervention with exercise intolerance management.
- Metabolic Disorders:Primary mitochondrial disease with multi-system involvement demands coordinated specialty care across endocrinology, cardiology, and neurology.
Neurological Disorders capture the majority of development-stage investment. Cardiovascular Diseases are climbing the fastest as biomarker validation matures.
End User:
Hospital procurement committees now centralize gene therapy purchasing decisions, displacing individual physician preference. Academic institutions anchor early-phase clinical trial execution. Specialty clinics concentrate patient volumes for rare disease management.
- Hospitals:Tertiary care centers with mitochondrial disease referral networks administer infused therapies and manage acute metabolic decompensation. Pharmacy and therapeutics committees gate gene therapy access.
- Research Laboratories:Academic medical centers and contract research organizations execute natural history studies and biomarker validation work.
- Specialty Clinics:Dedicated mitochondrial disease centers coordinate multi-disciplinary care across cardiology, neurology, and metabolic genetics.
- Academic Institutions:University-affiliated hospitals bridge investigator-initiated trials to industry-sponsored pivotal studies through NIH funding mechanisms.
Hospital systems control the majority of commercial volume. Specialty Clinics are expanding most quickly as disease-specific care models proliferate.
Delivery Mode:
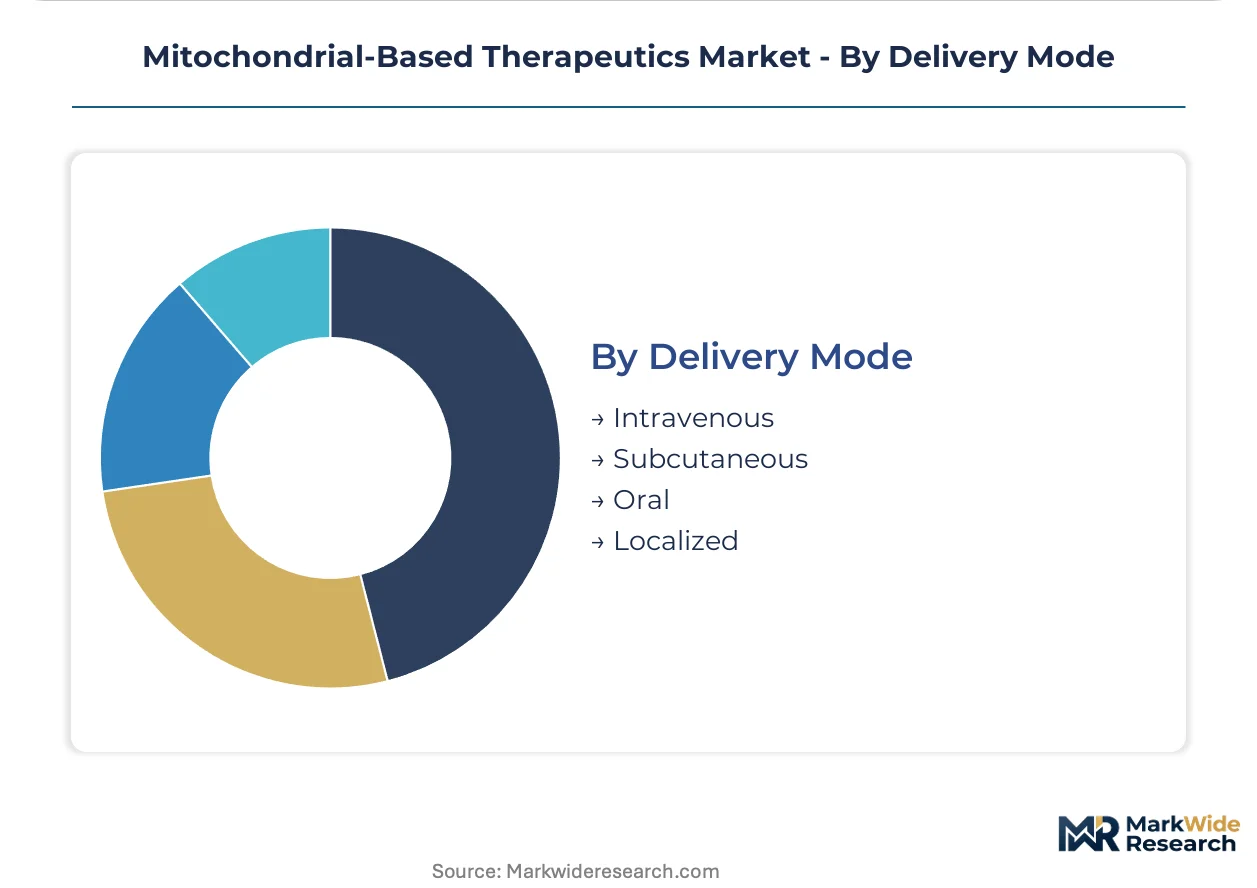
Route selection determines manufacturing complexity, cold chain requirements, and administration setting economics. Intravenous delivery dominates biologics and gene therapy, while oral routes preserve patient compliance for chronic metabolic management.
- Intravenous:Infusion center administration required for AAV gene therapy and enzyme replacement. United States hospital outpatient departments capture reimbursement through pass-through payment mechanisms.
- Oral:Small molecule metabolic modulators enable home administration with periodic monitoring. Patient compliance advantages support chronic regimen economics.
- Subcutaneous:Self-administration potential for peptide therapies with appropriate stability profiles and injection training.
- Localized:Direct tissue delivery for ophthalmic or muscular applications with targeted mitochondrial dysfunction.
Intravenous infrastructure handles the largest patient volumes. Oral delivery is gaining share fastest as small molecule pipelines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The mitochondrial therapeutics industry traces its commercial origins to United States academic medical centers, where early gene therapy trials for rare metabolic disorders established the clinical and regulatory template now diffusing to other markets.
United States
The NIH Office of Rare Diseases Research channels dedicated funding toward investigator-initiated trials, while FDA accelerated approval pathways compress development timelines for mitochondrial drug candidates. Boston Children's Hospital and Children's Hospital of Philadelphia anchor referral networks that aggregate patient volumes for natural history studies and pivotal gene therapy trials.
Germany
Specialized metabolic disease centers in Munich and Heidelberg coordinate multi-disciplinary care for mitochondrial encephalomyopathies, generating clinical data that informs EMA regulatory submissions. The country's national pharmaceutical regulator maintains close scientific dialogue with academic consortia through the European Joint Programme on Rare Diseases.
Japan
PMDA's Sakigake designation for regenerative medicines accelerates market access for mitochondrial gene therapies, attracting developers seeking early approval in the world's third-largest pharmaceutical market. Tokyo and Osaka academic hospitals concentrate expertise in mitochondrial myopathy management.
United Kingdom
The NHS England specialized commissioning framework governs access to high-cost gene therapies for mitochondrial disorders, with Great Ormond Street Hospital serving as the national referral hub for pediatric metabolic disease. NICE technology appraisals set reimbursement benchmarks that influence pricing negotiations across Europe.
Switzerland
Swissmedic's streamlined review procedures for advanced therapy medicinal products support early-phase clinical development, while Basel and Zurich host contract manufacturing organizations expanding GMP viral vector capacity for gene therapy sponsors.
Mitochondrial-Based Therapeutics Market Competitive Environment
The competitive structure tilts toward platform-specialized biopharmaceutical firms with rare disease expertise. Large-cap diversified pharmaceutical companies occupy adjacent positions through manufacturing scale and global distribution infrastructure. Three archetypes dominate: Nrf2 pathway modulators, viral vector gene therapy platforms, and mitochondrial-targeted small molecule developers. Strategic moves concentrate on manufacturing partnerships secured before clinical proof-of-concept and adaptive trial designs integrating biomarker endpoints.
Within the platform-specialized tier, Reata Pharmaceuticals and Stealth BioTherapeutics exemplify developers anchoring rare disease indications through distinct mechanistic approaches. Takeda Pharmaceuticals occupies a position bridging large-cap manufacturing scale with rare disease portfolio breadth. These three represent the competitive spectrum from targeted biotech to diversified pharmaceutical capability.
| Leading Market Players |
|---|
| Reata Pharmaceuticals |
| Takeda Pharmaceuticals |
| Pfizer Inc. |
| Biogen |
| Amgen Inc. |
| Novartis AG |
| NeuroVive Pharmaceutical AB |
| Khondrion |
| Stealth BioTherapeutics |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up contract manufacturing organizations have consolidated viral vector production capacity across the United States and Europe, tightening supply discipline and anchoring premium pricing for GMP-grade AAV slots. This ownership concentration feeds directly into gene therapy development economics, where manufacturing partnerships must close before clinical proof-of-concept to secure capacity.
Pricing Analysis
Value-based pricing anchored to clinical outcomes dominates gene therapy negotiations, while small molecules compete on total cost-of-ownership metrics against curative alternatives. Price differentiation separates orphan-designated biologics with accelerated FDA review from chronic oral regimens sourced from Indian and Chinese contract manufacturers. Cost compression in the small molecule tier intensifies as metabolic symptom management substitutes fragment market share. Academic medical center pharmacy and therapeutics committees exhibit the highest price sensitivity, whereas specialty clinics managing rare mitochondrial encephalopathies accept premium positioning for blood-brain barrier-penetrating peptides.
Supply Chain Analysis
Reverse-logistics capabilities for temperature excursion management and viral vector batch recall are becoming competitive differentiators among specialized distributors serving hospital outpatient departments. Plasmid DNA sourcing concentrates in the United States and Germany, with GMP-grade nucleic acid production resting on a limited supplier base of academic spinouts and CDMOs. Single-source vulnerability in AAV capsid manufacturing creates supply chain risk as developers compete for finite GMP suite capacity. Distribution runs through manufacturer direct-to-site models for high-value biologics, displacing traditional wholesale relationships at academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mitochondrial therapeutics sector functions as a regulatory compounder, where FDA orphan drug incentives and EMA's ATMP classification continuously expand addressable demand by accelerating approval timelines for rare disease indications.
For Market Incumbents: Extend manufacturing partnerships into exclusive multi-year GMP slotting agreements before competitor pipeline maturation crowds viral vector capacity. Consolidate control over plasmid DNA supply through equity stakes in specialized nucleic acid manufacturers, defending against emerging biotech entrants with platform-agnostic vector designs. For New Entrants and Emerging Players: Direct-to-specialist digital channels targeting mitochondrial disease referral networks at Boston Children's Hospital and Children's Hospital of Philadelphia offer the most penetrable entry vector. Cardiovascular applications in heart failure with preserved ejection fraction represent underexploited white space where metabolic modulator science outpaces established therapeutic paradigms. For Investors and Strategic Acquirers: Valuations sit cheapest among peptide therapy developers with validated blood-brain barrier delivery platforms but incomplete pivotal trial data. The five-to-ten year viability window favors acquisition targets possessing adaptive trial design capabilities integrated with natural history study infrastructure. Monitor EMA reimbursement negotiations for single-administration gene therapies as the critical inflection signal for sector-wide repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Early GMP partnership closure secures viral vector capacity before clinical proof-of-concept. |
| Regulatory Approval Pathway | FDA orphan drug designation compresses development timelines for Leigh syndrome candidates. |
| Clinical Trial Advancement | Adaptive designs embedding biomarker endpoints accelerate payer value demonstration for ATMPs. |
| Pipeline Diversification | Cardiovascular energy metabolism expansion hedges against neurological gene therapy competition. |
| Licensing Agreement | Peptide platform out-licensing to large-cap partners defrays blood-brain barrier validation costs. |
Study Parameters
Direct dialogue with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists grounded the qualitative foundation, cross-referenced against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Secondary validation drew from NIH funding disclosures and European Joint Programme on Rare Diseases reports. Bottom-up patient population sizing and top-down therapeutic category spend estimates were triangulated to anchor market scope.
Segment-level projections across gene therapy, small molecule, peptide, and enzyme replacement modalities were generated through the analysis window, with therapy area splits for neurological, cardiovascular, metabolic, and muscular applications. Administration route economics and regional regulatory cluster adoption curves fed into CAGR derivation. Manufacturing capacity buildout timelines and plasmid supply constraints were modeled as supply-side boundary conditions.
The model assumes a particular technology adoption path; alternative pathways for mitochondria-penetrating peptide platforms would alter the outlook if blood-brain barrier validation timelines compress unexpectedly. Forecasts reflect assumptions about EMA reimbursement accommodation for single-administration therapies and FDA accelerated approval pathway durability. Practitioners should monitor PMDA Sakigake designation uptake rates and national payer gene therapy budget impact assessments for early signals of access expansion or contraction.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Seropositive Rheumatoid Arthritis Drug Market
Pharmaceuticals
Immunoglobulin Market
Pharmaceuticals
Pharmacy Market
Pharmaceuticals
Hyperphosphatemia Drugs Market
Pharmaceuticals
Pain Management Drugs Market
Pharmaceuticals
Global Dengue Vaccine Market
Pharmaceuticals
HPV Vaccines Market
Pharmaceuticals
Global Pneumococcal Vaccines Market
Pharmaceuticals
Targeted Liposomes Drug Delivery Market
Pharmaceuticals
Demerol (Meperidine) Market
Pharmaceuticals
Carbetocin Acetate Market
Pharmaceuticals
Carglumic Acid Market
Pharmaceuticals
Veterinary Active Pharmaceutical Ingredients Manufacturing Market
Pharmaceuticals
Global Alpha-Blocker Market
Pharmaceuticals
Oral Antibiotics Market
Pharmaceuticals
Gastrointestinal OTC Drugs Market