
 Global Autism Spectrum Disorder Therapeutics Market | 2026-2036
Global Autism Spectrum Disorder Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Autism Spectrum Disorder Therapeutics Market Foresight
Software-defined patient monitoring and digital therapeutics delivery is consolidating into recurring subscription models that alter how autism interventions are monetized. F. Hoffmann-La Roche Ltd. leverages its neurology R&D infrastructure to sustain pipeline depth across pharmacological candidates. Johnson & Johnson Services Inc. anchors its position through behavioral health platform investments that span clinical and home settings. Pfizer Inc. competes by extending its rare disease capabilities into neurodevelopmental indications.
Autism spectrum disorder therapeutics encompasses behavioral interventions, pharmacological agents, nutritional supplements, and alternative treatments designed to modulate neurotransmitter function, synaptic plasticity, and sensory processing pathways in individuals with ASD. These interventions target core deficits in social communication, repetitive behaviors, and cognitive flexibility through mechanisms ranging from dopamine and serotonin pathway modulation to applied behavioral analysis protocols. Pharmacological therapies command the deepest margin pools due to patent-protected formulations and chronic administration profiles, while digital therapeutics represent the fastest-expanding delivery mode as remote patient monitoring gains clinical acceptance. Behavioral interventions remain the most mature segment, anchored by decades of insurance reimbursement precedent and standardized practitioner certification pathways.
The FDA's accelerated approval framework for neurological therapies shapes demand by compressing development timelines for novel ASD pharmacological candidates, while the EMA's pediatric investigation plans mandate early-age trial inclusion that expands addressable patient populations. Health Canada and the TGA enforce comparable evidentiary standards, creating a transatlantic regulatory convergence that streamlines multi-jurisdictional product registration. Stakeholders must monitor how reimbursement policy evolution across Medicare, Medicaid, and national health systems determines which delivery modes achieve sustainable commercial scale.
Market Dynamics
Digital therapeutics delivery is consolidating into subscription-based models that fundamentally alter how autism interventions are monetized, compressing traditional fee-for-service revenue cycles while expanding remote patient access.
Growth Catalysts
- Insurance mandate expansion:United States state-level autism service coverage requirements broaden addressable patient pools and stabilize reimbursement visibility for behavioral health providers.
- FDA accelerated approval:The FDA's neurological therapy fast-track pathway compresses development timelines for novel pharmacological candidates targeting core ASD symptoms.
- Applied behavioral analysis standardization:Board-certified practitioner credentialing pathways mature across pediatric clinics, reducing service variability and enabling scalable program replication.
Market Restraints
- Specialized workforce scarcity:Board-certified behavior analyst certification bottlenecks constrain service expansion velocity despite capital availability.
- Reimbursement fragmentation:Medicaid state-level variation in autism service coverage creates administrative complexity that elevates operational overhead for multi-state providers.
- Clinical trial heterogeneity:Inconsistent outcome measurement frameworks across ASD pharmacological studies complicate regulatory evidentiary requirements.
Strategic Opportunities
- Home-based digital delivery:Remote patient monitoring platforms penetrate underserved rural geographies where specialist clinic density remains insufficient.
- Sensory processing technology convergence:Wearable biofeedback devices integrate with behavioral intervention protocols to create measurable outcome datasets.
- Pediatric investigation plan alignment:EMA-mandated early-age trial inclusion expands addressable populations for developmental trajectory-modifying therapies.
Industry Challenges
- Interoperability complexity:Electronic health record integration with digital therapeutic platforms demands substantial customization investment.
- Practitioner retention friction:Burnout rates among registered behavior technicians elevate workforce turnover costs for clinic operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Autism Spectrum Disorder Therapeutics Market |
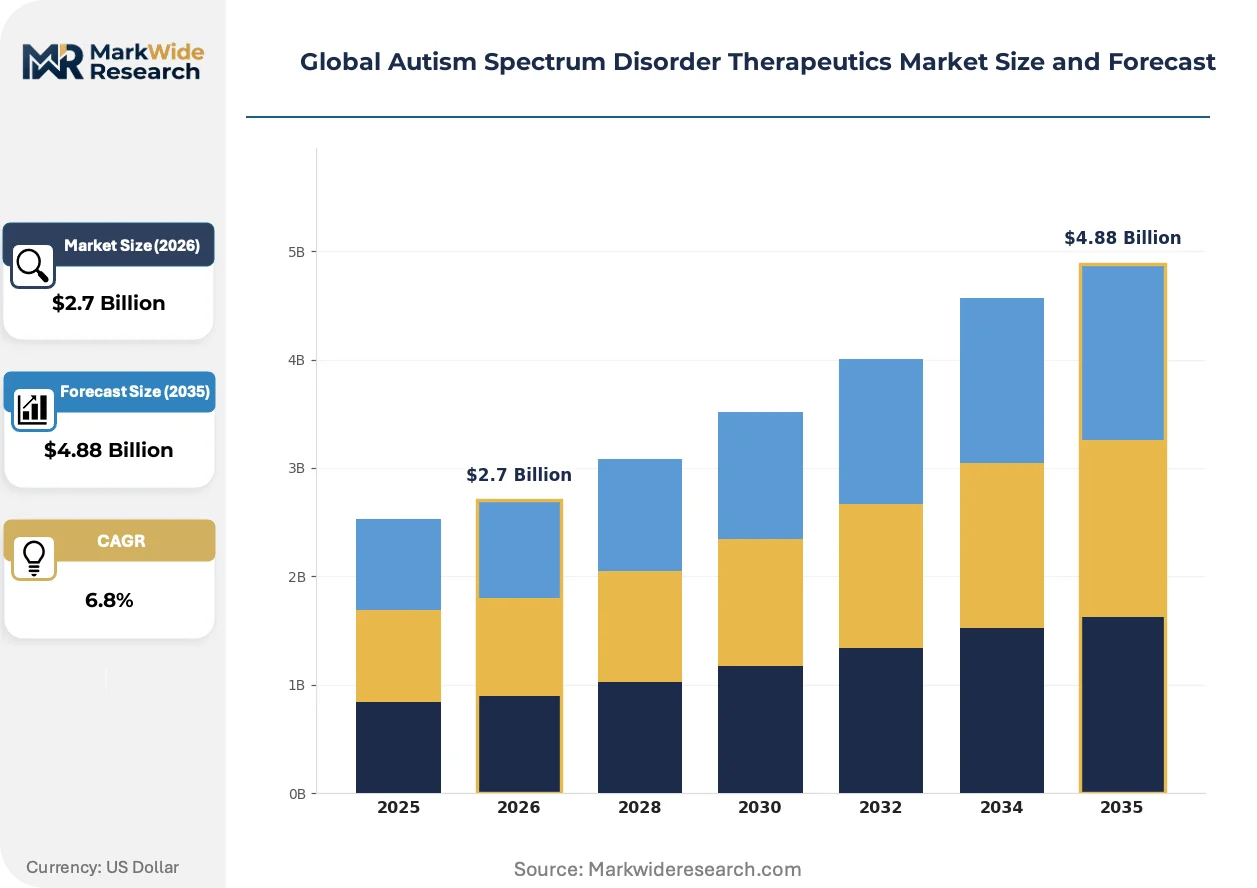
| Market Size in 2026 | $2.7 Billion |
| Market Size in 2035 | $4.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Behavioral Interventions, Pharmacological Therapies, Nutritional Supplements, Alternative Treatments Application: Communication Improvement, Social Skills Development, Anxiety Reduction, Cognitive Enhancement, Sensory Processing End User: Specialized Clinics, Research Institutions, Rehabilitation Centers, Home Care Providers Delivery Mode: Oral Medication, Injectable Therapy, Digital Therapeutics, Occupational Therapy, Speech Therapy |
| Companies Covered | Johnson & Johnson Services Inc., Otsuka Pharmaceutical Co., Ltd., F. Hoffmann-La Roche Ltd., Bristol-Myers Squibb Company, Novartis AG, Pfizer Inc., Curemark LLC, Yamo Pharmaceuticals, Axial Therapeutics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Autism Spectrum Disorder Therapeutics Market Shifts & Advancements
Autism therapeutics delivery is fragmenting across modality boundaries as digital platforms, pharmacological agents, and behavioral protocols converge into integrated care pathways that demand new outcome measurement frameworks.
Software-defined patient monitoring is consolidating fragmented behavioral data streams into unified dashboards that enable real-time intervention adjustment. Pediatric clinics in the United States are adopting these platforms fastest, driven by insurance documentation requirements. The structural consequence is compressing the latency between symptom observation and therapeutic modification from weeks to hours.
EMA pediatric investigation plans mandate early-age trial inclusion that reshapes pharmacological development timelines for neurodevelopmental indications. European sponsors now front-load juvenile toxicology studies to satisfy parallel regulatory submissions. Development-stage assets targeting core ASD symptoms face compressed preclinical-to-clinical transition windows.
Subscription-based access models displace per-session billing across behavioral health platforms serving school districts and self-insured employers. Channel intermediation shifts toward direct enterprise contracts that bundle assessment, intervention, and progress reporting. This procurement evolution concentrates most visibly in United States commercial payer networks seeking utilization management tools.
Global Autism Spectrum Disorder Therapeutics Market Segmentation
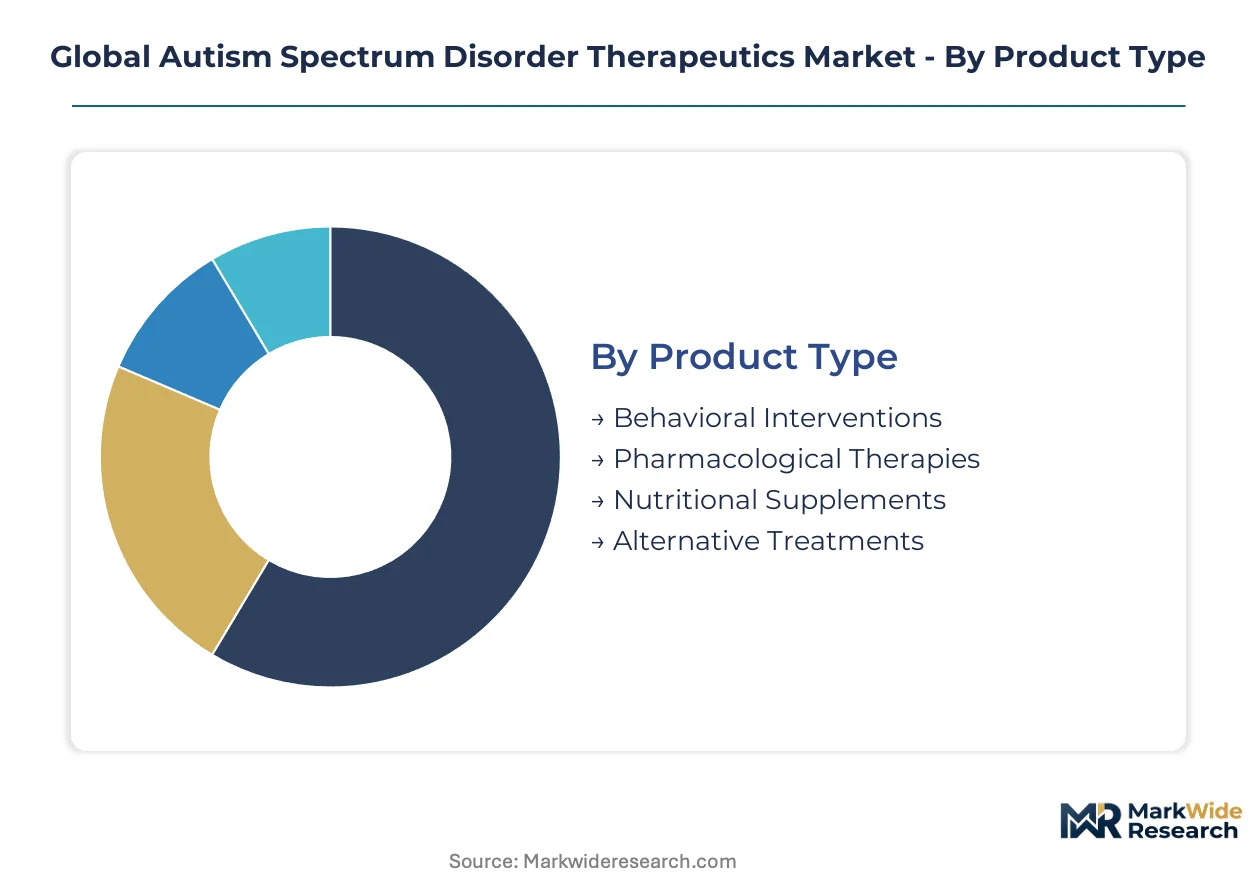
ASD therapeutics fragment across intervention modalities that command fundamentally different margin structures and reimbursement pathways. Understanding where volume concentrates versus where growth accelerates determines resource allocation for manufacturers and service providers.
Product Type:
Payers prioritize evidence tiers when authorizing intervention spend, creating distinct commercial trajectories for each modality.
- Behavioral Interventions:Applied behavioral analysis protocols and structured skill-building programs delivered by board-certified practitioners. Demand concentrates in United States pediatric clinics where state insurance mandates guarantee reimbursement visibility, though workforce certification bottlenecks constrain expansion velocity.
- Pharmacological Therapies:Patent-protected small molecules and biologics targeting dopamine, serotonin, and glutamate pathways to modulate irritability and repetitive behaviors. Revenue pools deepen through chronic administration profiles in United States commercial and Medicare Part D formularies, with FDA accelerated approval compressing development timelines for novel candidates.
- Nutritional Supplements:Omega-3 fatty acids, vitamin D, and specialized dietary formulations addressing metabolic and gastrointestinal comorbidities.
- Alternative Treatments:Sensory integration approaches, music therapy, and animal-assisted interventions lacking standardized evidentiary frameworks.
Volume sits with behavioral interventions; growth tilts toward pharmacological therapies.
Application:
Clinical trial design and outcome measurement frameworks align around symptom domains rather than diagnostic categories, shaping development-stage investment.
- Communication Improvement:Speech-generating devices, social communication training, and augmentative alternative communication systems. Research institutions in the United States and Germany drive protocol standardization, with digital therapeutics platforms capturing measurable engagement metrics that satisfy payer documentation requirements.
- Social Skills Development:Structured peer interaction programs and video modeling interventions targeting relationship formation and reciprocal engagement. Specialized clinics across California, Massachusetts, and Ontario concentrate service delivery where insurance density supports intensive programming.
- Anxiety Reduction:Cognitive-behavioral adaptations and pharmacological anxiolytics addressing comorbid mood dysregulation.
- Cognitive Enhancement:Executive function training and working memory interventions targeting academic and adaptive performance.
- Sensory Processing:Environmental modification protocols and biofeedback systems addressing hyper- and hypo-sensory reactivity.
Service volume clusters around communication and social skills; sensory processing applications are expanding most quickly through wearable technology integration.
End User:
Procurement authority and reimbursement mechanism vary sharply across care settings, fragmenting go-to-market requirements.
- Specialized Clinics:Dedicated autism centers employing multidisciplinary teams of behavior analysts, speech therapists, and occupational therapists. United States metropolitan markets—particularly Boston, Los Angeles, and Chicago—anchor capacity expansion where commercial payer contracts sustain operational scale.
- Research Institutions:Academic medical centers and contract research organizations conducting interventional trials under FDA and EMA pediatric investigation plans. Johns Hopkins, University of California system, and Karolinska Institutet concentrate early-phase asset development.
- Rehabilitation Centers:Post-acute facilities integrating autism-specific programming into broader neurodevelopmental service lines.
- Home Care Providers:Direct-to-consumer platforms and in-home behavior technician deployment extending reach into rural geographies.
Revenue concentrates in specialized clinics; addressable population expansion favors home care providers.
Delivery Mode:
Technology enablement is compressing the latency between symptom observation and therapeutic adjustment across physical and digital channels.
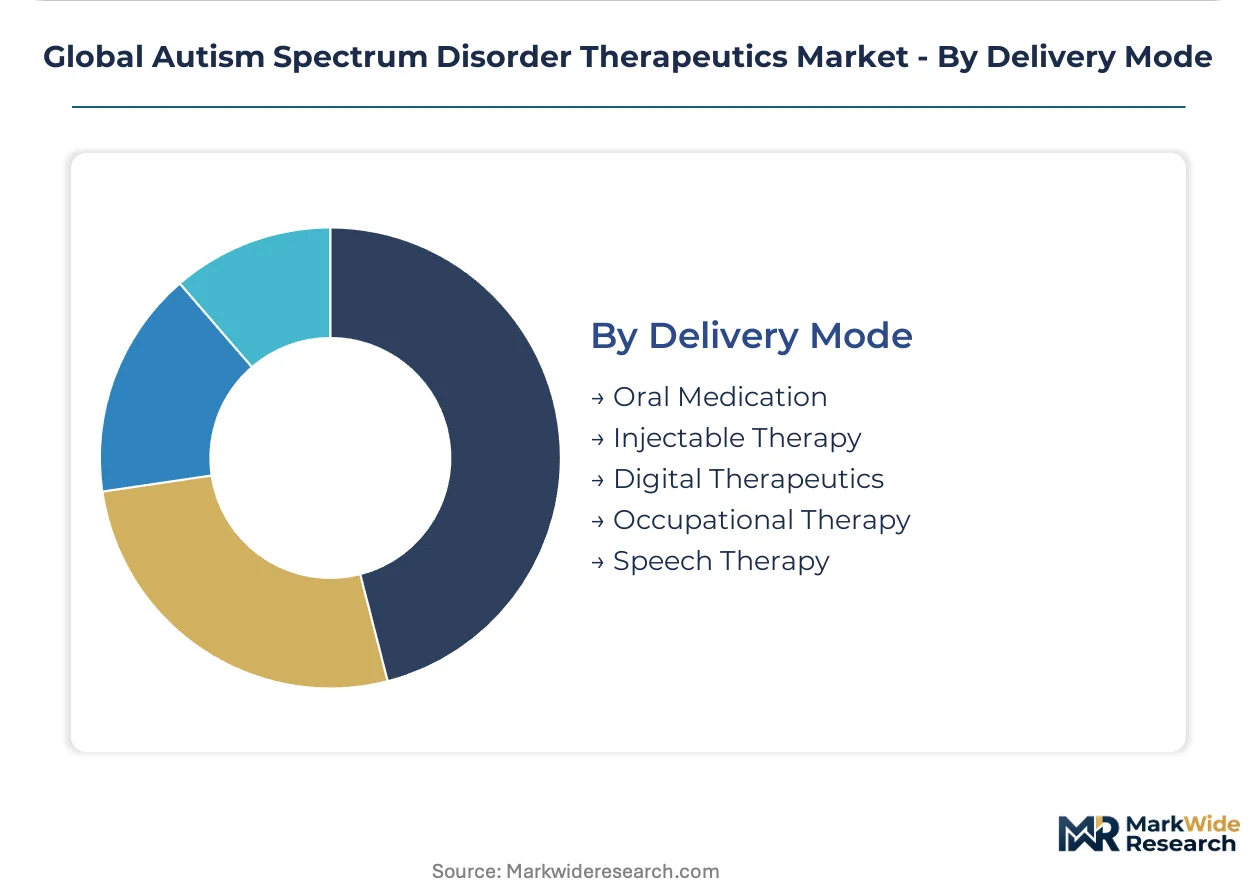
- Digital Therapeutics:Software-based interventions delivered through mobile applications and remote monitoring platforms with real-time data capture. School districts in Texas, Florida, and New York are adopting subscription models fastest, driven by individualized education plan compliance requirements and shortage of in-person specialists.
- Oral Medication:Small-molecule formulations including atypical antipsychotics and selective serotonin reuptake inhibitors with established pediatric labeling. Formulary positioning in United States Medicaid and commercial plans determines commercial scale, with generic penetration eroding originator revenue in mature categories.
- Injectable Therapy:Long-acting antipsychotic formulations and emerging biologic candidates requiring clinical administration.
- Occupational Therapy:Sensory integration and adaptive skill training delivered in clinic, school, or home settings.
- Speech Therapy:Articulation, language comprehension, and pragmatic communication interventions.
Patient volume remains with oral medication; steepest expansion trajectory belongs to digital therapeutics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston anchors autism therapeutics development through its concentration of academic medical centers and specialized pediatric clinics. The metropolitan corridor between Massachusetts General Hospital and Boston Children's Hospital generates substantial clinical trial volume. This geographic pattern repeats across specific national markets with differentiated regulatory and reimbursement environments.
United States
State-level insurance mandates in California, Texas, and New York broaden addressable patient pools for behavioral intervention providers. FDA accelerated approval pathways compress development timelines for novel pharmacological candidates targeting core ASD symptoms. The Los Angeles metropolitan area concentrates specialized clinic capacity where commercial payer density sustains operational scale.
Germany
EMA pediatric investigation plans mandate early-age trial inclusion that expands addressable populations for developmental trajectory-modifying therapies. The country's national pharmaceutical regulator enforces evidentiary standards comparable to FDA requirements, streamlining multi-jurisdictional product registration. Heidelberg and Berlin anchor academic research clusters where university hospitals conduct interventional trials under structured pediatric protocols.
Japan
PMDA review pathways for pediatric neurological indications reshape pharmacological development timelines for neurodevelopmental assets. METI funding programs support digital therapeutics platform development targeting communication and social skills domains. The Kanto region surrounding Tokyo concentrates specialized rehabilitation centers where insurance reimbursement for behavioral interventions has expanded under revised disability support frameworks.
United Kingdom
NICE technology appraisals determine formulary positioning for pharmacological therapies addressing irritability and repetitive behaviors in ASD populations. NHS England commissioning frameworks standardize behavioral intervention access across integrated care systems. The Cambridge-Oxford-London corridor concentrates research institution density where academic medical centers anchor early-phase asset development.
Canada
Health Canada evidentiary requirements for pediatric neurological therapies enforce standards comparable to FDA and EMA frameworks. Provincial variation in autism service coverage creates administrative complexity that elevates operational overhead for multi-jurisdictional providers. The Greater Toronto Area concentrates specialized clinic capacity where provincial funding commitments for behavioral health services have expanded.
Global Autism Spectrum Disorder Therapeutics Market Competitive Landscape
Capital-heavy pharmaceutical manufacturers compete with asset-light digital therapeutics developers across fundamentally different margin structures and capital intensity profiles. The market structure fragments across three tiers: established neurology-focused pharmaceutical conglomerates with deep R&D infrastructure, emerging biotech specialists targeting core ASD symptom domains, and software-native platform developers monetizing through subscription-based access models. Dominant competitive moves include strategic partnerships between pharmaceutical developers and digital therapeutics platforms to create integrated care pathways, plus geographic expansion through direct-to-enterprise contracts with school districts and self-insured employers.
Within the established pharmaceutical tier, F. Hoffmann-La Roche Ltd. and Johnson & Johnson Services Inc. exemplify divergent strategic positioning—Roche anchoring its approach through neurology R&D infrastructure while J&J extends through behavioral health platform investments spanning clinical and home settings. Pfizer Inc. occupies a distinct position leveraging rare disease capabilities into neurodevelopmental indications. These three Swiss and American conglomerates represent contrasting archetypes for how legacy pharmaceutical infrastructure adapts to evolving ASD intervention delivery models.
| Leading Market Players |
|---|
| Johnson & Johnson Services Inc. |
| Otsuka Pharmaceutical Co., Ltd. |
| F. Hoffmann-La Roche Ltd. |
| Bristol-Myers Squibb Company |
| Novartis AG |
| Pfizer Inc. |
| Curemark LLC |
| Yamo Pharmaceuticals |
| Axial Therapeutics Inc. |
| Others |
Supply & Pricing Matrix
EMA pediatric investigation plans mandating early-age trial inclusion gate qualified pharmacological supply and premium-tier pricing access for developmental trajectory-modifying therapies, compressing preclinical-to-clinical transition windows while elevating evidentiary investment thresholds.
Pricing Analysis
Value-based pricing anchored to measurable behavioral outcome improvements dominates behavioral intervention contracts, particularly for board-certified applied behavioral analysis programs where insurance documentation requirements enforce standardized metrics. Three-tier pricing structure across premium, standard, and economy levels separates intensive clinic-based delivery from remote digital platforms and unlicensed practitioner services. Cost compression in the economy tier is intensifying because Medicaid state-level coverage variation elevates administrative overhead for multi-state providers. Self-insured employers and school districts exhibit lowest price sensitivity due to individualized education plan compliance mandates, while uninsured families face highest sensitivity where state mandate gaps persist.
Supply Chain Analysis
Dual-sourcing requirements for active pharmaceutical ingredients mandate multi-supplier qualification for dopamine and serotonin pathway modulators, with pharmaceutical sponsors qualifying both Indian and Chinese API manufacturers alongside domestic United States facilities. Raw material dependencies center on specialized neurotransmitter precursors, biologic fermentation media, and pediatric-compatible excipient formulations. Single-source vulnerability concentrates in long-acting injectable formulations where complex manufacturing processes limit qualified CMO capacity. Distribution runs through specialty pharmacy networks for pharmacological therapies, while behavioral interventions deploy through direct-to-clinic and direct-to-home care provider channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Board-certified behavior analyst certification bottlenecks prop pricing power across behavioral intervention tiers, constraining service expansion velocity despite capital availability for clinic operators.
For Market Incumbents: Deploy backward integration into digital therapeutics platform development to counter asset-light subscription-based entrants compressing traditional fee-for-service revenue cycles. Secure exclusive formulary positioning for novel pharmacological candidates through FDA accelerated approval pathway navigation ahead of generic penetration in established categories. Vertical integration into home-based care provider networks defends against workforce turnover friction elevating operational costs. For New Entrants and Emerging Players: Enter via rural geography penetration where specialist clinic density remains insufficient and school district procurement authority concentrates demand for remote patient monitoring solutions. Target sensory processing applications through wearable biofeedback device integration, the fastest-expanding segment through measurable outcome dataset generation. Pursue direct-to-enterprise contracts with self-insured employers bundling assessment, intervention, and progress reporting. For Investors and Strategic Acquirers: FDA breakthrough therapy designation for core ASD symptom candidates is the leading indicator that developmental trajectory-modifying pharmacological assets warrant premium valuation multiples. Long-term viability rests on pipeline assets demonstrating juvenile toxicology study completion under EMA pediatric investigation plans. Acquisition focus should center on digital therapeutics platforms with established school district procurement relationships and real-time electronic health record integration capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Juvenile toxicology studies under EMA pediatric investigation plans compress preclinical-to-clinical transitions for neurodevelopmental assets. |
| Regulatory Approval Pathway | FDA accelerated approval for neurological therapies reshapes evidentiary requirements for novel ASD pharmacological candidates. |
| Platform Integration | Electronic health record integration with digital therapeutic platforms reduces symptom observation-to-intervention adjustment latency. |
| Strategic Partnership | School district enterprise contracts bundle assessment, intervention, and progress reporting for individualized education plan compliance. |
| Geographic Expansion | Home-based digital delivery penetrates underserved rural geographies where board-certified practitioner scarcity constrains in-person capacity. |
Research Methodology
Independent corroboration across drug development executives, regulatory affairs leads, formulary directors, and payer access specialists underwrites the qualitative findings, validated against FDA filings, EMA submissions, ClinicalTrials.gov entries, and formulary databases. Bottom-up demand modeling triangulates against top-down market sizing across behavioral intervention, pharmacological therapy, nutritional supplement, and alternative treatment modalities.
Comparable-period anchoring to historical reimbursement policy evolution and regulatory pathway maturation frames the projection horizon, with segmentation across intervention modality, application domain, end-user setting, and delivery mode. CAGRs derive from patent expiration timelines, pipeline progression rates, and insurance mandate expansion trajectories, incorporating workforce certification velocity and digital therapeutics adoption curves as industry-specific inputs.
Revisions become necessary when FDA accelerated approval pathway modifications, state-level insurance mandate rollbacks, or breakthrough therapy designation withdrawals materialize. A model refresh is warranted upon material change in board-certified behavior analyst certification throughput or Medicaid federal matching rate adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Two Piece Empty Hard Capsule Market
Pharmaceuticals
Etoricoxib Market
Pharmaceuticals
Long-Acting Insulin Market
Pharmaceuticals
Europe Pharmaceutical Contract Manufacturing Market
Pharmaceuticals
Hydroxypropyl Methylcellulose (HPMC) Capsules Market
Pharmaceuticals
Carbapenem Antibiotics Market
Pharmaceuticals
Oral Solid Dosage Contract Manufacturing Market
Pharmaceuticals
Organ Transplant Rejection Medications Market
Pharmaceuticals
Short-Acting Beta-Agonists Market
Pharmaceuticals
Vitiligo Drugs Market
Pharmaceuticals
Methylphenidate Hydrochloride Market
Pharmaceuticals
OTC Topical Drugs Market
Pharmaceuticals
Global Autogenous Vaccines Market
Pharmaceuticals
Collagenase Clostridium Histolyticum Market
Pharmaceuticals
Critical Care Antiarrhythmic Drugs Market
Pharmaceuticals
Global Erectile Dysfunction Drugs Market