
 Global Colorectal Cancer Therapeutics Market | 2026-2036
Global Colorectal Cancer Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Colorectal Cancer Therapeutics Market Foresight
Hospital-based infusion centers versus community oncology clinics is rebalancing as care delivery fragments toward outpatient settings. F. Hoffmann-La Roche Ltd leverages its diagnostic-therapeutic pairing to anchor biomarker-driven patient selection. Merck & Co. Inc sustains dominance in checkpoint inhibitor combinations through extensive investigator-sponsored trial networks. Bristol-Myers Squibb competes on dual immunotherapy regimens with differentiated safety profiles in microsatellite-stable populations.
Colorectal cancer therapeutics encompass pharmaceutical agents designed to inhibit tumor progression, induce apoptosis, or stimulate immune recognition of malignant colonic and rectal epithelial cells, with monoclonal antibodies requiring cold-chain distribution at two-to-eight degrees Celsius to preserve protein integrity. These therapies serve to extend progression-free survival and overall survival in patients spanning Stage II through metastatic disease. Immunotherapies command premium positioning as the fastest-expanding product category, though chemotherapy agents retain volume leadership due to entrenched first-line protocols across oncology clinics. Metastatic management generates the deepest margin pools as therapy duration extends over multiple lines of treatment, while neoadjuvant therapy segments show structural growth as surgeons and medical oncologists collaborate on organ-preservation strategies.
FDA breakthrough therapy designation and EMA PRIME eligibility compress development timelines, compelling sponsors to generate biomarker-defined efficacy signals earlier in clinical programs. The EU AI Act introduces algorithmic accountability requirements for diagnostic tools that stratify patients toward specific therapeutic classes, adding compliance layers to companion diagnostic commercialization. Stakeholders must monitor evolving reimbursement criteria for combination regimens as payers tighten evidence requirements for additive therapy costs.
Market Dynamics
FDA breakthrough therapy designation and EMA PRIME eligibility are compressing clinical development timelines, compelling sponsors to generate biomarker-defined efficacy signals earlier and reshaping how oncology pipelines advance toward commercialization.
Growth Catalysts
- Accelerated Approval Pathways:FDA breakthrough therapy and EMA PRIME eligibility compress Phase II-to-approval timelines, rewarding sponsors who front-load biomarker stratification in metastatic colorectal cancer trials.
- Immunotherapy Protocol Expansion:Oncology clinics in the United States, Germany, and Japan are building dedicated infusion capacity for checkpoint inhibitor combinations, anchoring demand for combination-ready therapeutic assets.
- Companion Diagnostic Integration:PCR-based and next-generation sequencing assays for MSI-H/dMMR status are becoming standard-of-care prerequisites, creating pull-through demand for matched therapeutics in precision oncology workflows.
Market Restraints
- Cold-Chain Distribution Costs:Monoclonal antibodies require two-to-eight degrees Celsius preservation throughout distribution, elevating logistics spend and limiting reach to regions with established cold-chain infrastructure.
- Reimbursement Compression:CMS and statutory health insurance funds in Germany are tightening evidence requirements for additive therapy costs in combination regimens, extending formulary negotiation timelines.
- Biomarker Testing Fragmentation:Discordant MSI-H testing methodologies across pathology laboratories create enrollment friction for biomarker-driven trials and delay treatment initiation.
Strategic Opportunities
- Neoadjuvant Therapy Expansion:Organ-preservation strategies in rectal cancer are opening new treatment windows, with surgeons and medical oncologists collaborating to defer or eliminate surgical resection.
- EU AI Act Compliance Services:Algorithmic accountability requirements for diagnostic tools that stratify patients toward specific therapeutic classes create adjacent revenue streams for companion diagnostic commercialization support.
- Community Oncology Clinic Migration:Outpatient infusion center buildouts in suburban United States markets are fragmenting care delivery away from hospital-based settings, creating channel expansion opportunities.
Industry Challenges
- Biomarker-Qualified Investigator Scarcity:Clinical trial sites with demonstrated patient screening throughput for rare molecular subsets are capacity-constrained, elongating enrollment timelines for targeted therapy studies.
- Combination Regimen Evidence Generation:Payer demands for additive benefit demonstration in checkpoint inhibitor plus chemotherapy combinations require larger, longer-duration trials than monotherapy programs.
- Legacy EHR Integration:Real-world evidence collection for post-marketing commitments depends on structured pathology and genomic data flows that remain inconsistently implemented across health system electronic health record architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Colorectal Cancer Therapeutics Market |
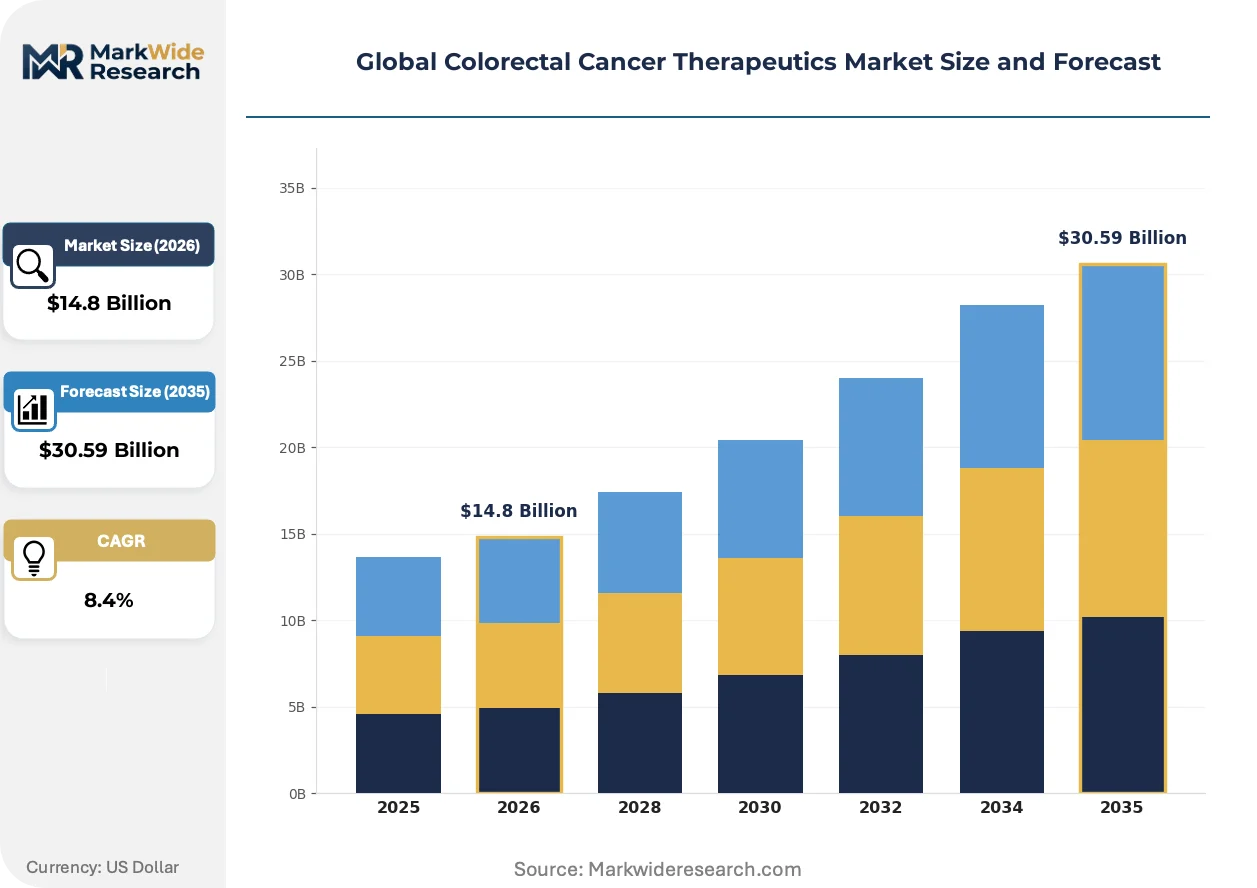
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $30.59 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Chemotherapy Agents, Targeted Therapies, Immunotherapies, Hormonal Therapies Therapy Area: Early Stage Treatment, Metastatic Management, Adjuvant Therapy, Neoadjuvant Therapy, Palliative Care Care Setting: Oncology Clinics, Specialized Cancer Centers, Outpatient Facilities, Ambulatory Care Units, Research Hospitals Administration Route: Oral, Intravenous, Intramuscular, Subcutaneous, Transdermal |
| Companies Covered | F. Hoffmann-La Roche Ltd, Eli Lilly and Company, Merck & Co. Inc, Taiho Pharmaceutical, Bayer AG, Amgen Inc, Pfizer Inc, Genentech, Inc., Bristol-Myers Squibb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Colorectal Cancer Therapeutics Market Shifts & Advancements
Tumor-agnostic approval frameworks and decentralized diagnostic platforms are rewriting how therapeutic value is demonstrated and accessed, compressing the distance between molecular profiling and treatment selection.
Peripheral blood circulating tumor DNA assays are expanding into minimal residual disease monitoring for Stage II-III colorectal cancer patients completing curative-intent therapy. Community oncology clinics in the United States are adopting these platforms to reduce reliance on imaging-based surveillance. The technology is expanding into adjuvant therapy duration decisions, enabling earlier intervention for molecular recurrence.
The EU AI Act introduces algorithmic accountability requirements for diagnostic software that stratifies patients toward specific therapeutic classes. Companion diagnostic vendors must now document training data provenance and performance across demographic subgroups before CE marking. European pathology laboratories are restructuring procurement criteria to prioritize compliant decision-support tools.
Hospital-based infusion centers face displacement as payers in Germany and Japan expand reimbursement for community oncology clinic administration of complex biologics. Site-of-care economics now favor outpatient settings with lower overhead structures. This channel rotation is most visible in United States suburban markets where physician-owned infusion centers capture volume from academic medical center competitors.
Global Colorectal Cancer Therapeutics Market Segmentation
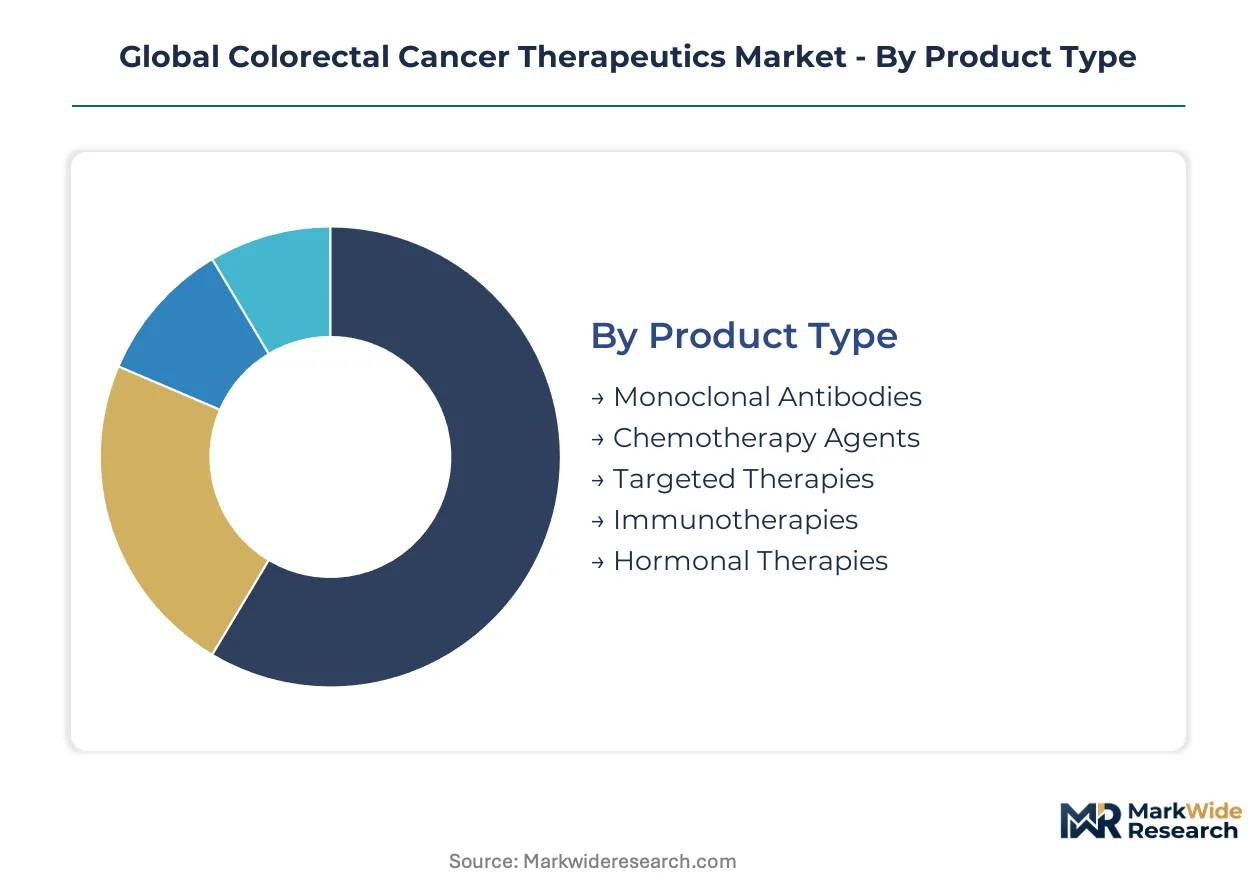
Segmentation in colorectal cancer therapeutics reveals how treatment protocols fragment across molecular profiles, care settings, and administration logistics. These divisions expose where pharmaceutical investment concentrates and where channel strategies must adapt to shifting site-of-care economics.
Product Type:
Integration depth varies sharply across product categories, with standalone biologics requiring specialized infrastructure versus small-molecule agents embedded in standard pharmacy workflows.
- Monoclonal Antibodies:Large-molecule therapeutics engineered to bind specific tumor antigens, requiring cold-chain distribution at two-to-eight degrees Celsius. Demand concentrates in specialized cancer centers across the United States, Germany, and Japan where infusion capacity and biomarker testing infrastructure align. Cold-chain logistics constrain reach to regions with established distribution networks.
- Immunotherapies:Checkpoint inhibitors and immune modulators that activate T-cell recognition of malignant cells, representing the most rapidly expanding therapeutic class. Oncology clinics in the United States and Japan are building dedicated infusion capacity for pembrolizumab and nivolumab combinations, anchoring demand for combination-ready assets. FDA breakthrough therapy designation accelerates development timelines for sponsors generating biomarker-defined efficacy signals.
- Chemotherapy Agents:Cytotoxic small molecules disrupting DNA replication in rapidly dividing cells, embedded in first-line protocols across community oncology settings.
- Targeted Therapies:Signal transduction inhibitors blocking EGFR or VEGF pathways, requiring companion diagnostic stratification before administration.
- Hormonal Therapies:Endocrine modulators with limited application in colorectal subsets, prescribed in specialized protocols for hormone-receptor-positive rare variants.
Chemotherapy agents lead volumes today; immunotherapies are gaining share fastest.
Therapy Area:
Cost tier stratification separates curative-intent protocols with finite duration from chronic management regimens extending across multiple lines of therapy.
- Metastatic Management:Chronic therapy protocols for Stage IV disease spanning sequential lines of treatment, generating the deepest margin pools due to extended duration. Demand concentrates in the United States and Germany where reimbursement supports combination regimens and biomarker-driven sequencing. Payer tightening on additive therapy evidence requirements extends formulary negotiation timelines.
- Neoadjuvant Therapy:Pre-surgical treatment windows enabling organ-preservation strategies in rectal cancer, representing structural growth as surgeons and medical oncologists collaborate. Academic medical centers in Japan and the United States are expanding neoadjuvant immunotherapy trials to defer or eliminate surgical resection. Protocol complexity requires coordinated multidisciplinary care teams.
- Early Stage Treatment:Curative-intent protocols for Stage II-III disease, concentrated in high-volume surgical centers with integrated pathology services.
- Adjuvant Therapy:Post-surgical treatment to eliminate micrometastatic disease, with duration decisions increasingly informed by circulating tumor DNA monitoring.
- Palliative Care:Symptom-focused protocols prioritizing quality of life, administered across hospice and community oncology settings with simplified logistics.
Metastatic management commands the largest revenue footprint; neoadjuvant therapy shows the steepest expansion trajectory.
Care Setting:
Site-of-care migration is fragmenting patient volume away from hospital-based infrastructure toward outpatient models with lower overhead structures.
- Oncology Clinics:Community-based infusion centers capturing volume from academic competitors, particularly in suburban United States markets. These facilities prioritize efficiency in high-throughput monoclonal antibody administration. Physician ownership models align prescriber and site economics.
- Specialized Cancer Centers:Academic and comprehensive cancer programs anchoring complex protocol development and biomarker-driven trial enrollment. Concentrated in the United States, Germany, and Japan where research infrastructure and patient volume sustain multidisciplinary programs. These sites dominate investigator-sponsored trial networks for combination regimens.
- Outpatient Facilities:Ambulatory settings with streamlined logistics for oral and subcutaneous agents, expanding in Germany as statutory insurance expands reimbursement for community administration.
- Ambulatory Care Units:Hospital-affiliated day units bridging inpatient and community settings, common in European integrated health systems.
- Research Hospitals:Clinical trial sites with demonstrated patient screening throughput for rare molecular subsets, capacity-constrained and elongating enrollment timelines.
Oncology clinics are climbing the fastest; specialized cancer centers retain protocol leadership.
Administration Route:
Patient convenience and pharmacokinetic requirements determine route selection, with oral agents enabling decentralized management versus infusion-dependent biologics requiring site tethering.
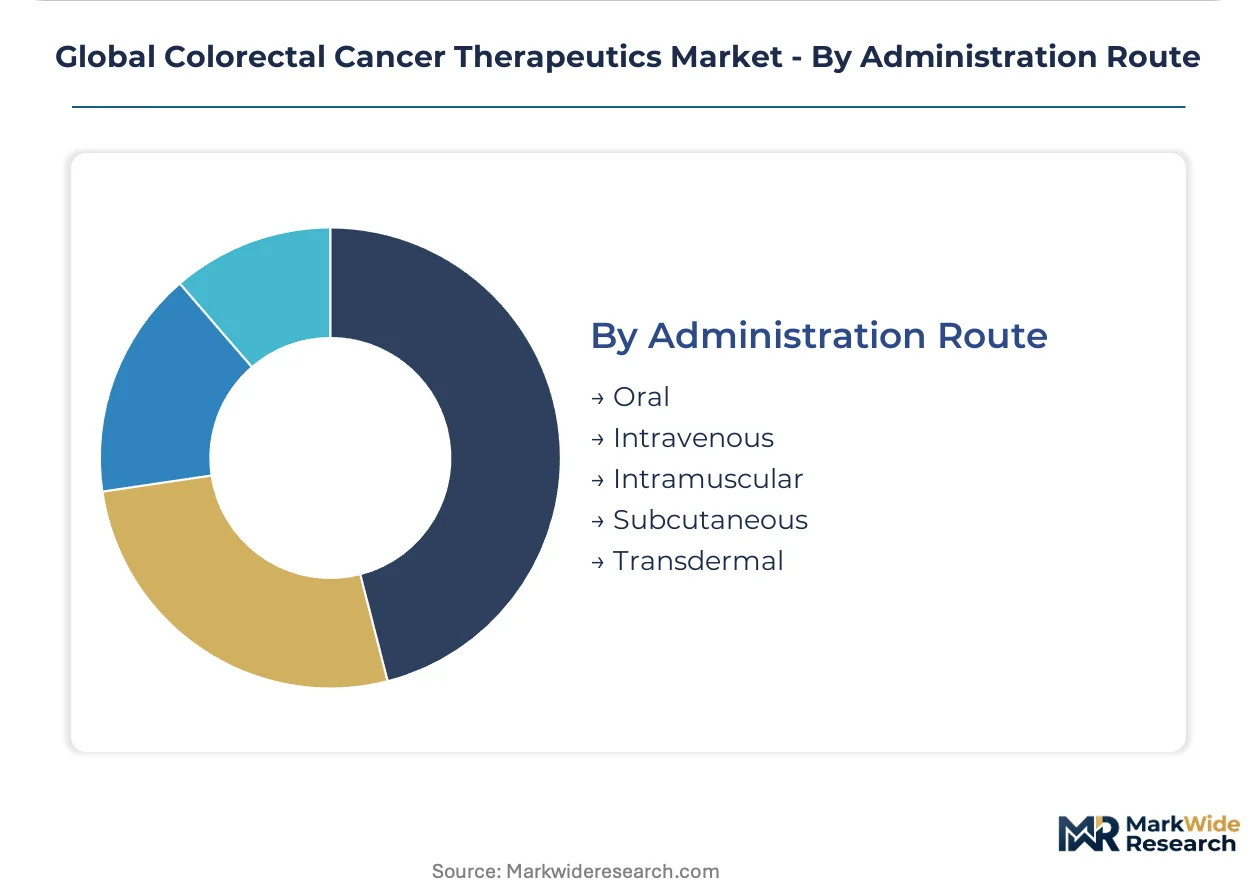
- Intravenous:Infusion-dependent delivery for monoclonal antibodies and chemotherapy combinations, anchoring patients to site-of-care infrastructure. Cold-chain requirements and infusion chair capacity constrain throughput. United States and Japanese oncology clinics are expanding dedicated infusion capacity to capture this volume.
- Oral:Small-molecule targeted therapies enabling home administration and reducing site-of-care dependency. Demand concentrates in community oncology settings and markets with limited infusion infrastructure. Patient adherence monitoring and pharmacy benefit management shape commercialization strategy.
- Subcutaneous:Self-administered biologics with reduced cold-chain burden, expanding in Europe as EMA guidelines support alternative delivery.
- Intramuscular:Limited application for hormonal and supportive care agents in colorectal protocols.
- Transdermal:Minimal penetration in oncology, restricted to supportive care applications for symptom management.
Intravenous administration dominates biologic delivery; oral routes are gaining share fastest in targeted therapy segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping clinical trial placement as sponsors migrate studies toward jurisdictions with streamlined oncology approval pathways and biomarker-qualified site density. Cost-of-compliance gaps between FDA breakthrough therapy eligibility and EMA PRIME acceleration are influencing where Phase II-to-approval programs concentrate. This divergence concentrates investment in markets where diagnostic-therapeutic pairing infrastructure aligns with compressed development timelines.
United States
FDA breakthrough therapy designation compresses Phase II-to-approval timelines for sponsors generating biomarker-defined efficacy signals. CMS reimbursement policies for combination regimens in metastatic disease anchor demand concentration in specialized cancer centers. The Greater Boston corridor and Research Triangle Park sustain investigator-sponsored trial networks for checkpoint inhibitor combinations.
Germany
Statutory health insurance funds tighten evidence requirements for additive therapy costs, extending formulary negotiation timelines for combination regimens. The EU AI Act introduces algorithmic accountability requirements for companion diagnostic tools, adding compliance layers to CE marking processes. Heidelberg and Munich anchor precision oncology clusters where pathology laboratories restructure procurement criteria for compliant decision-support platforms.
Japan
PMDA accelerated approval pathways for orphan oncology indications compress commercialization timelines for biomarker-stratified therapies. METI funding for community oncology clinic infrastructure expands reimbursement for complex biologic administration outside hospital settings. The Kansai region and Nagoya medical corridor concentrate neoadjuvant immunotherapy trials for organ-preservation strategies in rectal cancer.
United Kingdom
NICE technology appraisals demand cost-effectiveness evidence for checkpoint inhibitor combinations, shaping formulary access timelines. MHRA post-Brexit regulatory autonomy enables divergence from EMA centralized procedures for innovative oncology therapies. The Cambridge-London corridor concentrates circulating tumor DNA assay development for minimal residual disease monitoring in adjuvant therapy decisions.
China
NMPA priority review pathways for innovative biologics compress registration timelines for domestically manufactured checkpoint inhibitors. National reimbursement drug list negotiations concentrate volume in hospital-based infusion centers with established cold-chain infrastructure. Shanghai and Suzhou biotech clusters anchor diagnostic-therapeutic pairing capabilities for MSI-H/dMMR patient stratification.
Global Colorectal Cancer Therapeutics Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with large-cap pharmaceutical conglomerates anchoring immunotherapy development while regional licensees capture manufacturing scale. The vendor base concentrates around three strategic tiers: integrated diagnostic-therapeutic pairers, checkpoint inhibitor combination specialists, and chemotherapy backbone suppliers. Competitive positioning depends on biomarker-qualified investigator network density and companion diagnostic commercialization speed. M&A activity targets precision oncology platforms with validated PCR-based or next-generation sequencing assays, while strategic partnerships concentrate on co-development agreements for neoadjuvant therapy expansion.
Within the integrated diagnostic-therapeutic tier, F. Hoffmann-La Roche Ltd and Genentech, Inc. exemplify the pairing archetype where biomarker infrastructure anchors patient selection workflows. Merck & Co. Inc occupies a position among checkpoint inhibitor combination specialists, with Bristol-Myers Squibb representing the dual immunotherapy regimen segment. These three entities collectively illustrate how competitive positioning fragments across biomarker-driven stratification capabilities, trial network density, and site-of-care channel relationships.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Eli Lilly and Company |
| Merck & Co. Inc |
| Taiho Pharmaceutical |
| Bayer AG |
| Amgen Inc |
| Pfizer Inc |
| Genentech, Inc. |
| Bristol-Myers Squibb |
| Others |
Supply & Pricing Matrix
Circulating tumor DNA assay miniaturization is collapsing per-test manufacturing costs while concentrating production in automated sequencing hubs, simultaneously lowering price floors and tightening supply control among diagnostic-therapeutic pairers with captive reagent supply.
Pricing Analysis
Hospital procurement markups on infused biologics absorb cold-chain logistics premiums and site-of-care overhead, creating three-tier pricing structure across premium checkpoint inhibitors, standard chemotherapy backbones, and economy biosimilar equivalents. Price differentiation rests on biomarker stratification complexity and companion diagnostic bundling. Cost compression in the biosimilar tier is intensifying because statutory health insurance funds in Germany and CMS in the United States demand additive benefit evidence for combination premiums. Community oncology clinics exhibit highest price sensitivity due to physician ownership models; academic medical centers with research subsidies show lowest.
Supply Chain Analysis
Direct-to-hospital channels handle hyperscale monoclonal antibody demand from specialized cancer centers, while specialty distributors serve fragmented community oncology clinic networks. Active pharmaceutical ingredient synthesis concentrates in Switzerland, Singapore, and Ireland where FDA and EMA inspection histories anchor qualification status. Fill-finish operations draw from single-source sterile manufacturing suites with limited geographic redundancy. Tariff exposure on Chinese-sourced starting materials for checkpoint inhibitor production creates supply vulnerability. Distribution runs through temperature-validated lanes with continuous monitoring from manufacturing site to infusion chair.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Immunotherapy protocol expansion toward neoadjuvant settings signals a late-cycle quality story, with demand tilting toward premium-priced organ-preservation regimens requiring multidisciplinary care coordination.
For Market Incumbents: Lock in biomarker-qualified investigator networks through exclusive trial site agreements before capacity constraints elongate enrollment timelines for targeted therapy studies. Deepen backward integration into companion diagnostic manufacturing to capture margin pools from PCR-based and next-generation sequencing assay commercialization. Defend against emerging biosimilar entrants by embedding real-world evidence collection infrastructure that satisfies payer demands for additive benefit demonstration.
For New Entrants and Emerging Players: Enter via neoadjuvant therapy expansion in rectal cancer, where organ-preservation protocols remain underpenetrated relative to metastatic management saturation. Target suburban United States community oncology clinic buildouts where site-of-care economics favor lower-overhead infusion competitors. Lead with subcutaneous delivery formulations that reduce cold-chain burden and enable pharmacy benefit management channel access outside hospital-based settings.
For Investors and Strategic Acquirers: Valuations sit cheapest among precision oncology platform developers with validated MSI-H/dMMR stratification assays but limited therapeutic pairing. Long-term viability hinges on diagnostic-therapeutic integration depth across the analysis window. Acquisition focus should center on companion diagnostic vendors with EU AI Act compliance documentation and demonstrated training data provenance. The signal to watch is PMDA accelerated approval pathway utilization rates for biomarker-stratified submissions.
| Strategic Initiative | Industry Significance |
|---|---|
| Neoadjuvant Immunotherapy Trial Expansion | Organ-preservation protocols in rectal cancer defer surgical resection and extend therapy duration. |
| Companion Diagnostic CE Marking Pathway | EU AI Act compliance documentation accelerates European pathology laboratory procurement decisions. |
| Community Oncology Clinic Partnership | Suburban United States site buildouts fragment volume from academic medical center competitors. |
| Cold-Chain Distribution Optimization | Temperature-validated logistics preserve monoclonal antibody integrity through last-mile delivery. |
| Real-World Evidence Infrastructure Buildout | Structured pathology data flows satisfy CMS post-marketing commitment requirements. |
Research Methodology
Direct dialogue with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers anchored qualitative grounding. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up and top-down triangulation cross-checked patient volume estimates against reimbursement claims patterns.
Bottom-up modeling segmented across therapy line, administration route, care setting, and regional regulatory cluster to isolate growth vectors. Top-down validation anchored aggregate market trajectories against statutory health insurance fund expenditure reports and CMS Medicare Part B claims. CAGRs were derived from treatment duration assumptions and protocol penetration curves. Forecast inputs included biomarker testing adoption rates and site-of-care migration velocity.
Inputs from payer policy databases and clinical trial registries were available through the study window; gaps in real-world treatment sequencing data introduce uncertainty bands around second-line therapy transition probabilities. Forecasts reflect documented assumptions regarding immunotherapy protocol expansion and reimbursement stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
OTC Analgesic Market
Pharmaceuticals
Nasal Vaccines Market
Pharmaceuticals
Anti-Viral Therapeutics Market
Pharmaceuticals
Computer-Aided Drug Discovery Market
Pharmaceuticals
US External Analgesics Market
Pharmaceuticals
Non-Alcoholic Steatohepatitis (NASH) Therapeutics and Diagnostics Market
Pharmaceuticals
Motilium Market
Pharmaceuticals
Global Nasal Drug Delivery Technology Market
Pharmaceuticals
Global Janus Kinase Inhibitor (JAK) Market
Pharmaceuticals
Vasopressin Antagonists Market
Pharmaceuticals
Mouth Ulcers Treatment Market
Pharmaceuticals
Smart Pills Market
Pharmaceuticals
Canagliflozin Market
Pharmaceuticals
Global 3D Printed Drugs Market
Pharmaceuticals
Dermatitis Drugs Market
Pharmaceuticals
North America Alpha-Glucosidase Inhibitors Market