
 Saudi Arabia Diabetes Drugs Market | 2026-2036
Saudi Arabia Diabetes Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Diabetes Drugs Market Analytics
SFDA's tightened bioequivalence requirements for imported insulins is rebalancing the cost-of-entry calculus for multinational manufacturers seeking Saudi market access. Novo Nordisk leverages its established local distribution infrastructure to sustain insulin pen penetration across government hospital networks. Sanofi anchors its position through long-standing supply agreements with the Ministry of Health's centralized procurement system. Eli Lilly and Company differentiates via concentrated R&D investment in next-generation GLP-1 receptor agonist formulations tailored to regional metabolic profiles.
Diabetes drugs comprise pharmaceutical agents engineered to regulate blood glucose levels through mechanisms including insulin supplementation, incretin pathway modulation, and renal glucose reabsorption inhibition; these formulations typically require cold-chain stability between 2°C and 8°C and precise bioactivity standardization measured via HPLC purity assays. Their primary commercial purpose centers on preventing microvascular and macrovascular complications in diabetic populations while reducing hospitalization burden. Insulin retains dominant volume share across hospital and pharmacy channels, yet GLP-1 agonists command disproportionate margin pools due to premium pricing and expanding Type 2 diabetes indications. The injectable delivery mode still occupies the majority of administered doses, though oral SGLT2 inhibitors are gaining ground in home care settings where patient self-management preferences steer prescribing decisions.
SFDA and the Ministry of Health's National Unified Procurement Company jointly shape market access through centralized tender mechanisms and localized manufacturing incentives embedded in Saudi Vision 2030's pharmaceutical sector strategy. The country's national pharmaceutical regulator enforces GCC harmonized stability testing protocols that extend product registration timelines but elevate quality benchmarks for imported biologics. Stakeholders must monitor how the kingdom's health privatization trajectory and mandatory health insurance expansion reshape reimbursement pathways for novel diabetes therapies.
Market Dynamics
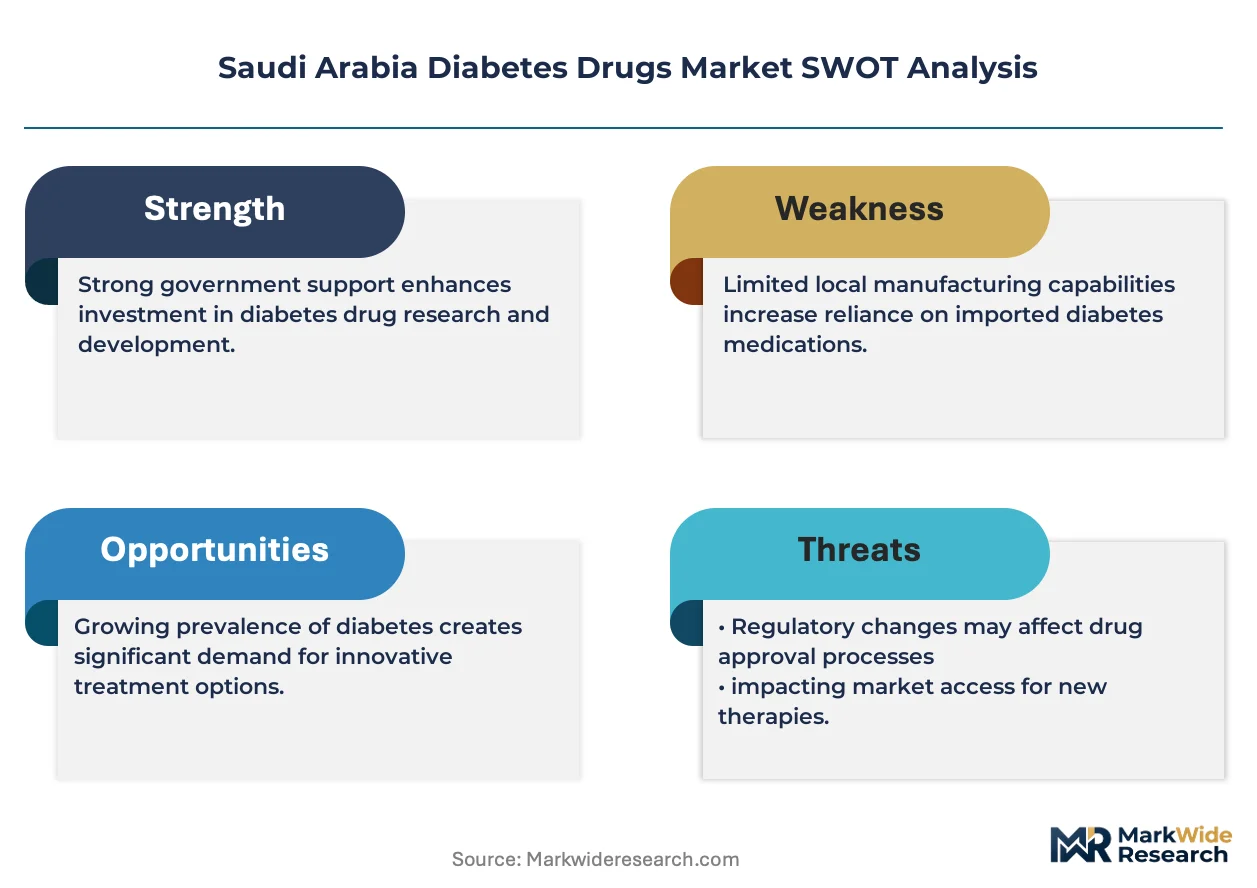
SFDA's tightened bioequivalence standards for imported insulins are reconfiguring competitive entry costs and redirecting procurement flows toward localized manufacturing partnerships under Vision 2030.
Growth Catalysts
- Vision 2030 Localization Incentives:The pharmaceutical sector strategy mandates domestic production partnerships, creating preferential tender access for manufacturers establishing Saudi-based fill-finish operations.
- Hospital Procurement Centralization:The National Unified Procurement Company's consolidated purchasing power concentrates demand volumes, enabling economies of scale for advanced diabetes therapies across tertiary networks.
- GLP-1 Receptor Agonist Pipeline:Next-generation incretin formulations targeting regional metabolic profiles are expanding prescriber options beyond insulin monotherapy in specialized endocrine centers.
Market Restraints
- Biologics Cold-Chain Infrastructure Gaps:Temperature excursions during last-mile distribution to peripheral regions degrade insulin potency and trigger SFDA quality enforcement actions.
- Imported Input Concentration:Active pharmaceutical ingredient sourcing remains concentrated among Asian contract manufacturers, exposing supply continuity to geopolitical friction and shipping volatility.
- Bioequivalence Testing Burden:Extended GCC harmonized stability protocols delay product registration timelines by twelve to eighteen months for multinational entrants.
Strategic Opportunities
- Eastern Province Undersupply:Dammam and Khobar's expanding healthcare infrastructure presents first-mover advantage for insulin pen and GLP-1 agonist distribution networks.
- Home Care Channel Expansion:Self-administered oral SGLT2 inhibitors are capturing patient preference outside hospital settings, creating pharmacy-centric revenue streams.
- Public-Private Partnership Frameworks:Health privatization trajectories enable joint venture structures for localized biologics manufacturing with Ministry of Health offtake guarantees.
Industry Challenges
- Specialized Biologics Talent Scarcity:Qualified personnel for cold-chain logistics management and biologics quality assurance remain concentrated in Riyadh and Jeddah, constraining regional expansion.
- Legacy Health IT Integration:Hospital pharmacy management systems require costly upgrades to support real-time inventory tracking for temperature-sensitive diabetes drugs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Diabetes Drugs Market |
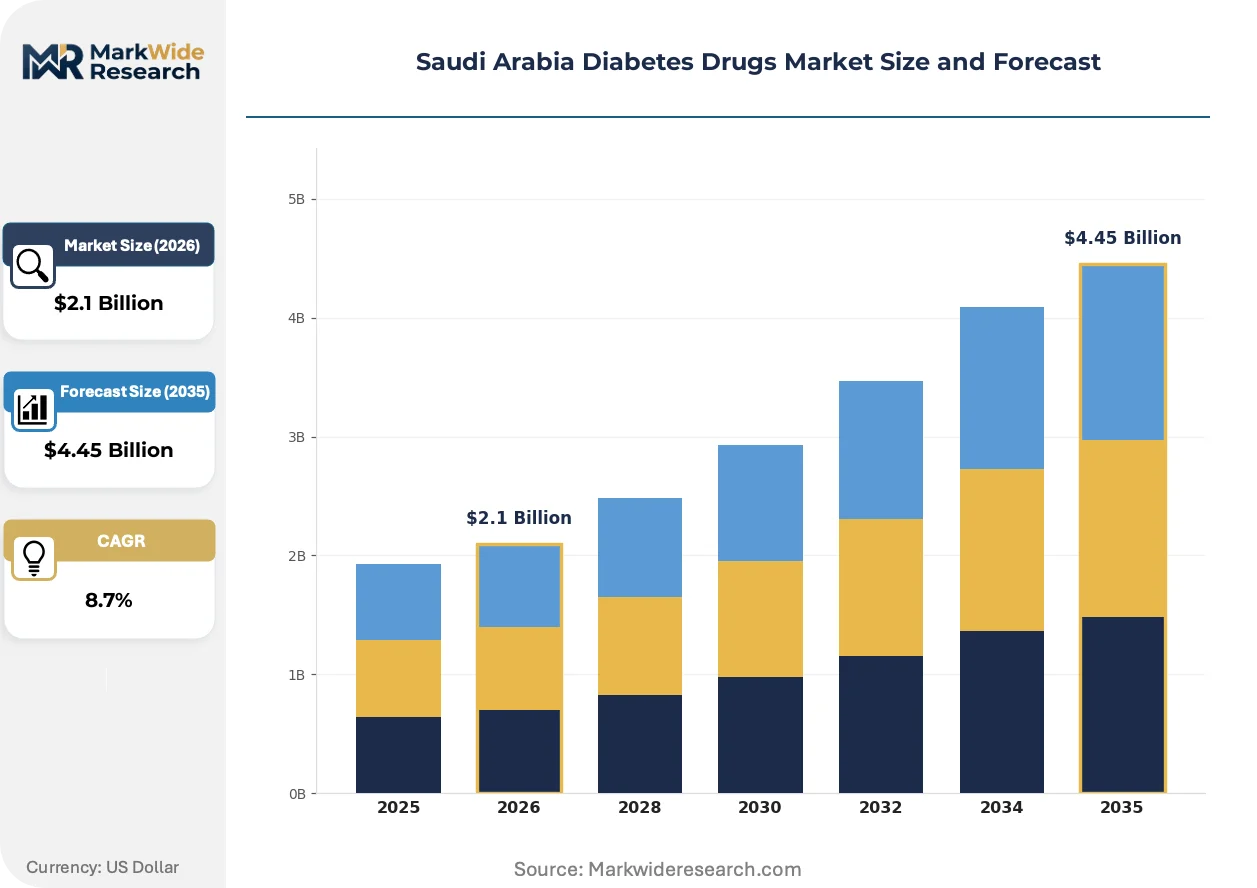
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin, GLP-1 Agonists, DPP-4 Inhibitors, SGLT2 Inhibitors End User: Hospitals, Clinics, Home Care, Pharmacies Delivery Mode: Injectable, Oral, Transdermal, Inhalable Therapy Area: Type 1 Diabetes, Type 2 Diabetes, Prediabetes, Gestational Diabetes |
| Companies Covered | Novo Nordisk, Sanofi, Eli Lilly and Company, AstraZeneca, Merck, Novartis, Pfizer, Boehringer Ingelheim, Biocon, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Diabetes Drugs Market Evolving Landscape
Technological convergence between continuous glucose monitoring and automated insulin delivery is reshaping therapeutic protocols, while regulatory localization pressures and shifting patient self-management preferences are reconfiguring channel economics.
Smart insulin pens with dose-memory and Bluetooth connectivity are expanding into hospital discharge protocols and pharmacy dispensing workflows. Endocrinology departments at King Faisal Specialist Hospital and Johns Hopkins Aramco Healthcare are piloting these devices for Type 1 diabetes transitions to home care. The technology is expanding into remote monitoring infrastructure, compressing traditional in-person follow-up intervals and enabling asynchronous clinician oversight of glycemic control.
SFDA's implementation of GCC harmonized stability testing protocols for biologics is extending registration timelines while elevating quality benchmarks for imported insulins. Manufacturers must now submit real-time stability data from Saudi climate conditions, not extrapolated northern hemisphere studies. Local fill-finish partnerships with SFDA-registered facilities are gaining competitive preference in Ministry of Health tenders as a compliance pathway.
Patient self-management preferences are steering prescribing decisions toward oral formulations in home care settings. SGLT2 inhibitors are displacing injectable basal insulin as first-line add-on therapy in pharmacy channels across Riyadh's retail clusters. This behavioral shift concentrates margin pressure on traditional insulin portfolios while creating reimbursement complexity for mixed public-private insurance coverage.
Saudi Arabia Diabetes Drugs Market Segmentation
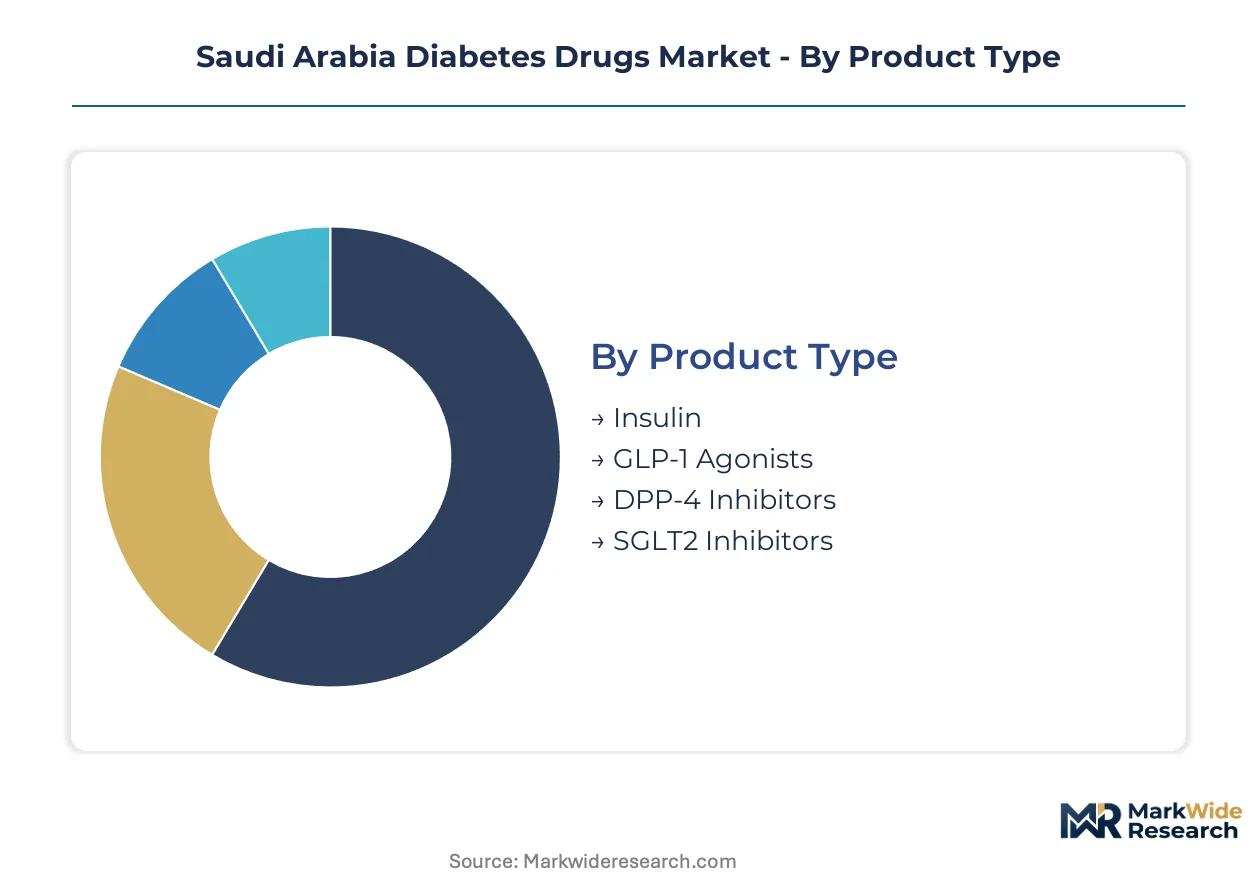
Diabetes drug procurement patterns across Saudi Arabia diverge sharply between institutional tenders and retail pharmacy channels, with therapy complexity and cold-chain requirements determining distribution economics. Understanding segment-level demand concentration enables manufacturers to align formulation portfolios with the kingdom's health transformation priorities.
Product Type:
Formulation chemistry dictates reimbursement pathways and manufacturing localization incentives under Vision 2030's pharmaceutical strategy.
- Insulin:Recombinant human and analog insulins require 2°C to 8°C stability throughout distribution. Hospital networks in Riyadh and Jeddah concentrate procurement volumes through the National Unified Procurement Company's centralized tenders, though cold-chain infrastructure gaps in peripheral regions degrade potency and trigger SFDA enforcement.
- GLP-1 Agonists:Incretin-based therapies modulate postprandial glucose through gastric emptying delay and satiety signaling. Specialized endocrine centers at King Faisal Specialist Hospital anchor demand for next-generation formulations, with premium pricing sustained by expanding Type 2 diabetes indications beyond insulin monotherapy.
- DPP-4 Inhibitors:Oral gliptins offer weight-neutral glycemic control with simpler storage requirements than biologics.
- SGLT2 Inhibitors:Sodium-glucose cotransporter-2 blockers reduce renal glucose reabsorption and are capturing patient preference in pharmacy channels across Riyadh's retail clusters.
Insulin leads on scale; GLP-1 agonists lead on momentum.
End User:
Channel structure reflects the Ministry of Health's centralization agenda and emerging privatization trajectories.
- Hospitals:Tertiary institutions dominate advanced therapy consumption through consolidated procurement mechanisms. King Faisal Specialist Hospital and Johns Hopkins Aramco Healthcare anchor insulin and GLP-1 agonist volumes, with discharge protocols increasingly incorporating smart pen technology for home care transitions.
- Home Care:Self-administration preferences are expanding pharmacy-centric revenue streams for oral formulations. Patient-driven prescribing decisions in this channel favor SGLT2 inhibitors over injectable basal insulin as first-line add-on therapy.
- Clinics:Primary care facilities serve as triage points for therapy escalation decisions.
- Pharmacies:Retail dispensaries capture growing SGLT2 inhibitor volumes amid mixed public-private insurance complexity.
Hospitals concentrate procurement power; home care channels are expanding most quickly.
Delivery Mode:
Administration route determines cold-chain intensity, patient adherence economics, and reimbursement coding complexity.
- Injectable:Subcutaneous delivery remains dominant for insulin and GLP-1 agonists, with pen devices displacing vial-and-syringe formats in government hospital networks. Smart insulin pens with Bluetooth connectivity are entering discharge protocols at specialized centers.
- Oral:Tablet formulations eliminate cold-chain burden and align with patient self-management preferences in home settings. SGLT2 and DPP-4 inhibitors drive pharmacy channel growth through simplified storage and administration.
- Transdermal:Patch-based delivery systems remain limited in commercial penetration.
- Inhalable:Pulmonary insulin delivery has minimal presence in Saudi formularies.
Injectable modes retain volume leadership; oral formulations gain share fastest.
Therapy Area:
Disease progression stage determines treatment intensity and monitoring infrastructure requirements.
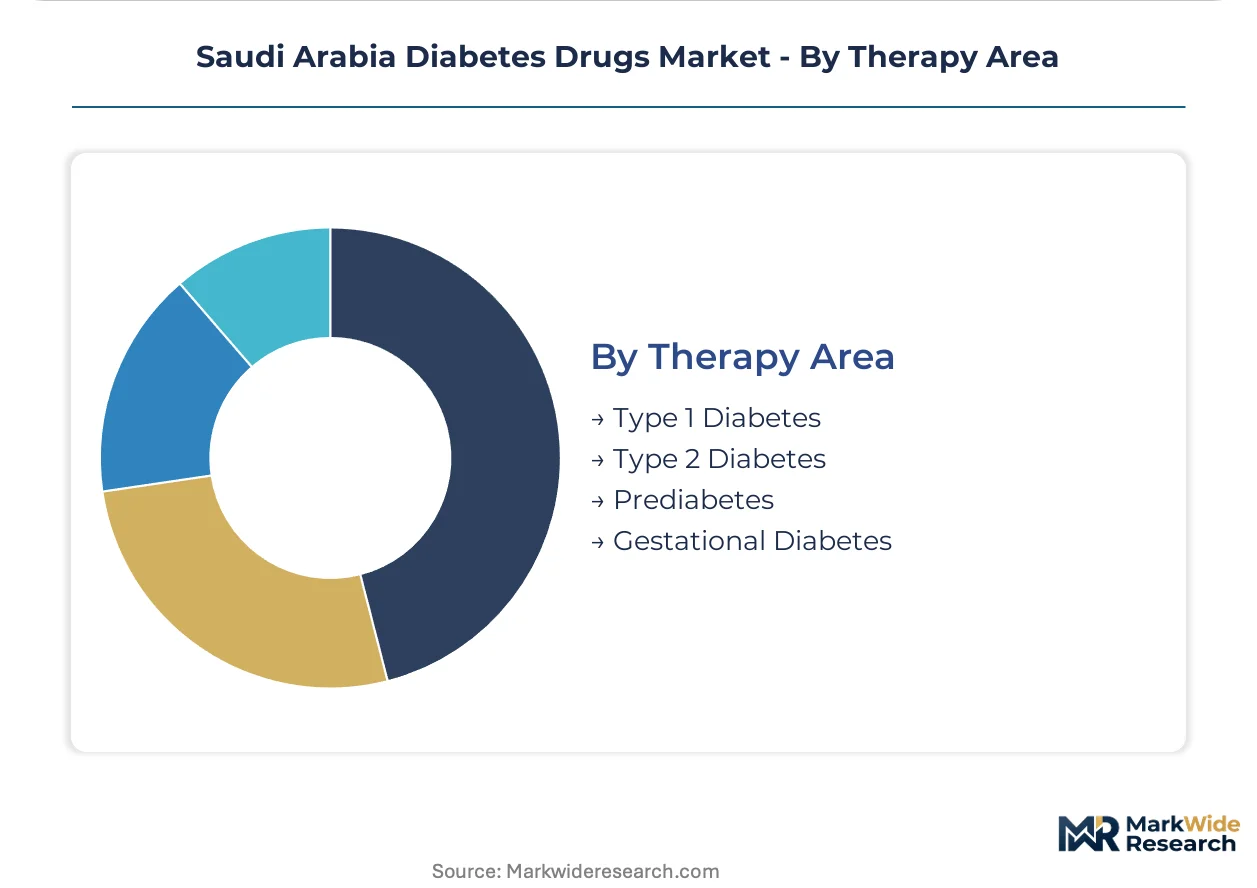
- Type 2 Diabetes:Metabolic syndrome progression drives the majority of pharmaceutical consumption, with prescriber protocols evolving from metformin monotherapy toward combination regimens incorporating SGLT2 inhibitors and GLP-1 agonists.
- Type 1 Diabetes:Absolute insulin deficiency mandates lifelong exogenous replacement, with continuous glucose monitoring integration reshaping therapeutic protocols at specialized centers.
- Prediabetes:Lifestyle intervention focus limits pharmacological penetration.
- Gestational Diabetes:Pregnancy-specific glycemic targets create niche insulin demand.
Type 2 diabetes anchors commercial scale; Type 1 diabetes shows steepest technology integration trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qualified personnel for cold-chain logistics and biologics quality assurance concentrate in Riyadh and Jeddah, creating talent scarcity that constrains pharmaceutical distribution across peripheral provinces.
Riyadh
King Faisal Specialist Hospital and tertiary hospital clusters anchor insulin and GLP-1 agonist procurement volumes through the National Unified Procurement Company's centralized tenders. SFDA's tightened bioequivalence standards redirect procurement toward local manufacturing partnerships under Vision 2030. The Riyadh-based pharmaceutical workforce manages cold-chain distribution protocols for temperature-sensitive biologics across government hospital networks.
Eastern Province
Dammam and Khobar's expanding healthcare infrastructure generates undersupply conditions for insulin pen and GLP-1 agonist distribution networks. The Ministry of Health's health privatization trajectory enables joint venture structures for localized biologics manufacturing with offtake guarantees. Aramco-affiliated healthcare facilities at Johns Hopkins Aramco Healthcare pilot smart insulin pen technology for Type 1 diabetes home care transitions.
Western Region
Jeddah's specialized endocrine centers anchor disproportionate GLP-1 receptor agonist consumption through premium pricing and expanding Type 2 diabetes indications. Patient self-management preferences in home care settings favor SGLT2 inhibitors over injectable basal insulin in pharmacy channels. Retail clusters across Jeddah's commercial districts capture growing oral formulation volumes amid mixed public-private insurance complexity.
NEOM Northwest
The giga-project's healthcare infrastructure buildout creates greenfield demand for diabetes therapy distribution networks without legacy system constraints. Vision 2030 pharmaceutical sector strategy embeds localized manufacturing incentives that attract multinational fill-finish partnerships. NEOM's planned medical city targets integration of continuous glucose monitoring with automated insulin delivery protocols.
Saudi Arabia Diabetes Drugs Market Competitive Landscape
The competitive structure tilts toward multinational biologics specialists with established local distribution infrastructure. Hospital procurement centralization through the National Unified Procurement Company concentrates purchasing power among suppliers with government tender access. Three archetypes dominate: Nordic insulin specialists with pen device penetration, diversified European pharma conglomerates with supply agreements, and emerging market biosimilar manufacturers with cost positioning. Competitive moves center on localized manufacturing partnerships and smart delivery device licensing.
Among the multinational biologics tier, Novo Nordisk A/S and Sanofi S.A. exemplify established infrastructure archetypes, while Eli Lilly and Company occupies a position within the next-generation incretin formulation segment. Novo Nordisk leverages its Danish headquarters' cold-chain expertise to sustain insulin pen penetration across government hospital networks. Sanofi anchors its competitive position through long-standing supply agreements with centralized procurement systems. Eli Lilly and Company represents concentrated R&D investment in GLP-1 receptor agonist formulations tailored to regional metabolic profiles.
| Leading Market Players |
|---|
| Novo Nordisk |
| Sanofi |
| Eli Lilly and Company |
| AstraZeneca |
| Merck |
| Novartis |
| Pfizer |
| Boehringer Ingelheim |
| Biocon |
| Others |
Value Network & Pricing Analysis
Multinational biologics specialists with established Saudi distribution infrastructure anchor both supply security and pricing discipline through long-standing Ministry of Health tender relationships. Their capital-intensive cold-chain networks create natural barriers that sustain premium positioning for GLP-1 agonists while compressing margins on commoditized insulin vials through centralized procurement leverage.
Pricing Analysis
Bundled device-and-drug offerings for smart insulin pens command premium positioning against unbundled vial-and-syringe formats in hospital discharge protocols. Three-tier pricing structure across originator biologics, licensed biosimilars, and unbranded generics reflects SFDA bioequivalence certification tiers and volume scale under National Unified Procurement Company tenders. Cost compression in the biosimilar tier is intensifying as local fill-finish partnerships gain tender preference under Vision 2030 localization mandates. Government hospital networks exhibit highest price sensitivity due to consolidated purchasing power, while specialized endocrine centers at King Faisal Specialist Hospital sustain lowest sensitivity for next-generation incretin formulations.
Supply Chain Analysis
Vision 2030 domestic-content mandates are reshaping sourcing patterns toward Saudi-based fill-finish partnerships with multinational API suppliers. Active pharmaceutical ingredient supply draws from India, China, and Switzerland for recombinant insulin and GLP-1 agonist production. Cold-chain logistics hinge on temperature-controlled distribution from Riyadh and Jeddah to peripheral regions, with specialized biologics talent scarcity creating single-source vulnerability at quality assurance nodes. Distribution runs through Ministry of Health central warehouses to tertiary hospital clusters, with pharmacy channel expansion for oral SGLT2 inhibitors introducing parallel retail distribution pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Saudi Arabia's diabetes drugs market rests on the shift toward high-value GLP-1 agonist portfolios and localized manufacturing cost structures that capture Vision 2030 incentive premiums.
For Market Incumbents: Acquire cold-chain logistics capabilities in the Eastern Province to preempt Dammam and Khobar infrastructure buildout. Consolidate position through backward integration into Saudi-based fill-finish operations that secure preferential National Unified Procurement Company tender access, while investing in SFDA bioequivalence certification for next-generation smart pen devices to defend against emerging biosimilar entrants. For New Entrants and Emerging Players: SFDA's tightened bioequivalence standards in Saudi Arabia open a window for specialized regulatory affairs capabilities that accelerate product registration timelines. Target the Eastern Province's undersupplied hospital networks with insulin pen distribution partnerships, and penetrate pharmacy channels through oral SGLT2 inhibitor formulations that align with patient self-management preferences in home care settings. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale biosimilar manufacturers with pending SFDA registrations and established Asian API supply relationships. Long-term viability over the coming decade centers on acquisition targets possessing localized manufacturing partnerships or cold-chain logistics assets in Riyadh and Jeddah. Watch for Ministry of Health privatization announcements as the inflection signal for joint venture structuring opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Local Fill-Finish Partnership | Vision 2030 incentives secure preferential tender access at National Unified Procurement Company. |
| Smart Insulin Pen Licensing | Bluetooth-enabled devices capture hospital discharge protocol integration at King Faisal Specialist Hospital. |
| Eastern Province Distribution Buildout | Dammam and Khobar infrastructure gaps create first-mover advantage for cold-chain networks. |
| GLP-1 Agonist Portfolio Expansion | Next-generation incretin formulations target specialized endocrine center premium pricing. |
| SFDA Bioequivalence Certification | GCC harmonized stability protocols elevate quality barriers against unregistered competitors. |
Research Methodology
Direct dialogue with hospital procurement managers, formulary directors at tertiary institutions, regulatory affairs leads, and cold-chain logistics operators grounded qualitative findings in operational reality. Secondary validation drew from SFDA registration databases, Ministry of Health tender disclosures, National Unified Procurement Company procurement bulletins, and GCC harmonized stability protocol documentation. Bottom-up demand modeling across therapy lines, delivery modes, and regional hospital clusters was triangulated against top-down pharmaceutical spending forecasts.
Top-down macroeconomic framing anchored growth projections across the analysis window, while bottom-up segmentation by product type, end user channel, and therapy area calibrated volume assumptions. Modeled dimensions encompassed insulin versus non-insulin therapies, hospital versus home care settings, and Type 1 versus Type 2 diabetes populations. CAGRs were derived from regression analysis of historical procurement volumes and elasticity-adjusted pricing trajectories, with specific inputs including SFDA registration timeline data and Vision 2030 localization incentive uptake rates.
Revisions become necessary when SFDA regulatory enforcement intensity shifts, Ministry of health privatization timelines accelerate, or geopolitical friction disrupts API supply from concentrated Asian sources. Forecasts reflect documented assumptions regarding tender centralization continuity and cold-chain infrastructure investment patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Prostaglandin Analogs Market
Pharmaceuticals
Guaifenesin Market
Pharmaceuticals
Isoflurane Market
Pharmaceuticals
Gastric Cancer Drugs Market
Pharmaceuticals
Herpes Labialis Treatment Market
Pharmaceuticals
Global Alpha-Blocker Market
Pharmaceuticals
Middle-East and Africa Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Asia-Pacific Gastrointestinal Drugs Market
Pharmaceuticals
Hepatocellular Carcinoma Drugs Market
Pharmaceuticals
Eperisone Hcl Market
Pharmaceuticals
Intranasal Corticosteroids Market
Pharmaceuticals
Photophobia Drug Market
Pharmaceuticals
Nasal Antihistamines Market
Pharmaceuticals
Cough Cold and Allergy Hay Fever Remedies in Mexico Market
Pharmaceuticals
Drug-Induced Dyskinesia Market
Pharmaceuticals
Long-Acting Beta-Agonists Market