
 North America Glue-Laminated Timber Market | 2026-2036
North America Glue-Laminated Timber Market Size, Share, and Industry Trends Forecast 2026-2036
North America Glue-Laminated Timber Market Intelligence
Commercial building developers is redrawing procurement patterns across engineered wood systems. Rosboro leverages vertical integration from Pacific Northwest timberlands through finished glulam production. Weyerhaeuser anchors large-scale manufacturing capacity serving multi-story commercial and institutional projects. Structurlam Mass Timber Corporation specializes in custom architectural-grade members for signature buildings across Canada and the United States.
Glue-laminated timber consists of dimension lumber laminations bonded with moisture-resistant adhesives under controlled pressure and temperature, creating structural members with predictable strength properties for spans exceeding solid-sawn alternatives. Structural glued laminated timber dominates volume as builders specify standardized beams and columns for repetitive commercial framing, while architectural glued laminated timber commands premium positioning where exposed wood finishes drive aesthetic value in institutional and civic buildings. Pre-manufactured glued laminated timber segments are gaining traction as off-site construction methods reduce labor hours and schedule risk for mid-rise developments.
The American Wood Council, CSA O86 standards in Canada, and the International Code Council shape material grading, adhesive performance requirements, and height allowances that directly determine addressable project scope. APA — The Engineered Wood Association maintains quality certification protocols that builders and insurers require for risk acceptance on multi-story structures. Stakeholders must track evolving code harmonization between United States and Canadian jurisdictions as this determines cross-border product acceptance and manufacturing location decisions.
Market Dynamics
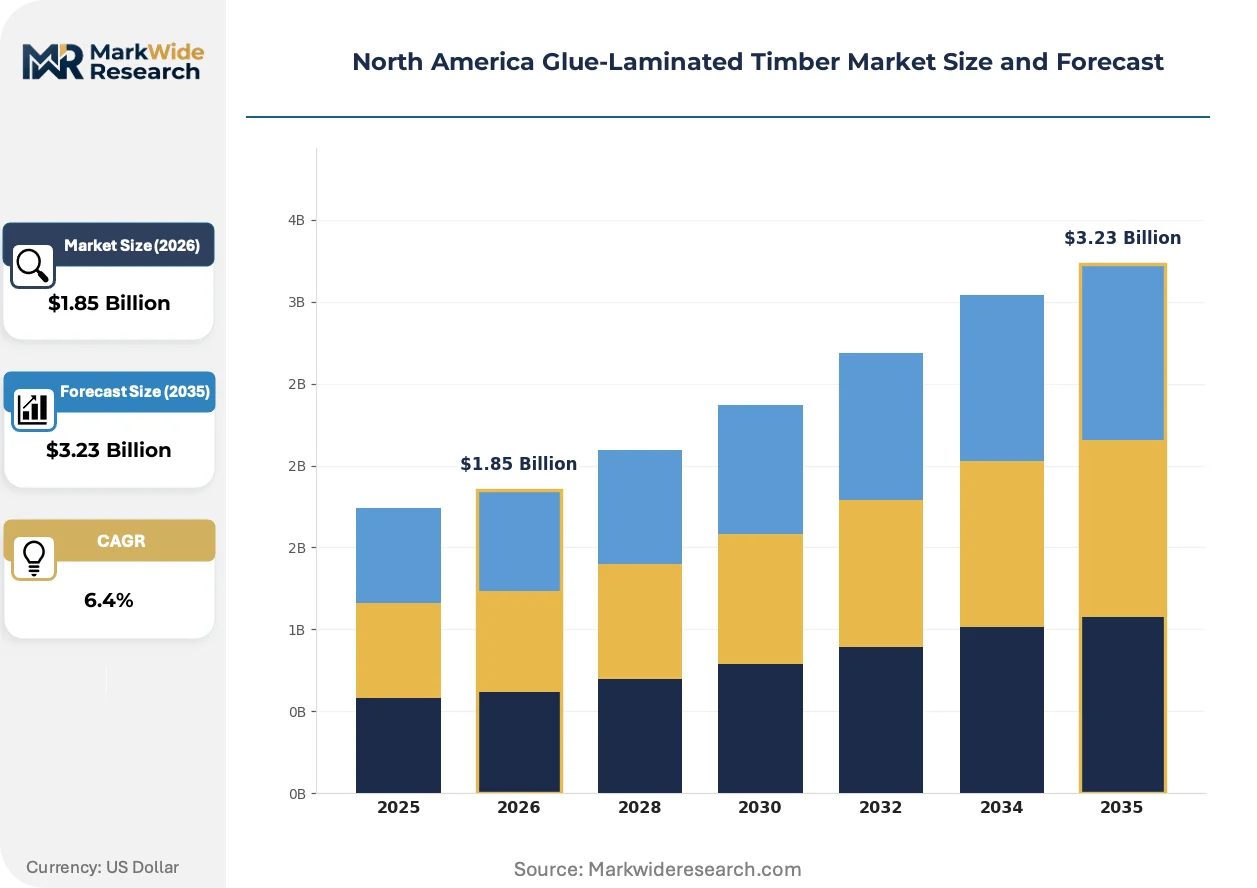
The International Building Code's 2021 and 2024 expansion of mass timber height allowances is compressing project timelines for mid-rise developers across the United States and Canada. This regulatory shift is redrawing competitive positioning between engineered wood systems and conventional steel-concrete framing.
Growth Catalysts
- IBC Height Expansion:The International Code Council's 14-story allowance for Type IV-A construction in the 2024 IBC unlocks mid-rise residential and office segments previously reserved for steel and concrete.
- CSA O86 Harmonization:Canadian standards alignment with US provisions is accelerating cross-border manufacturing consolidation and simplifying specification for architects working binational portfolios.
- Pacific Northwest Softwood Cluster:Concentrated Douglas-fir and hem-fir supply chains from Oregon through British Columbia reduce lamstock procurement lead times relative to dispersed solid-sawn alternatives.
Market Restraints
- Adhesive Cost Volatility:Phenol-resorcinol and polyurethane adhesive prices track petrochemical feedstock indices, compressing margins when oil markets spike.
- Certified Inspector Scarcity:The limited pool of APA-certified quality auditors creates bottlenecks at plant commissioning and annual recertification cycles.
- Concrete-Steel Incumbency:Established relationships between general contractors and rebar/formwork subcontractors create switching friction even where glulam offers structural equivalence.
Strategic Opportunities
- US Southeast Greenfield Capacity:Underpenetrated markets from Texas through Georgia lack regional glulam manufacturing, forcing long-haul logistics from Pacific Northwest and Great Lakes plants.
- Institutional Carbon Accounting:Public-sector procurement mandates in California, Washington, and British Columbia now require embodied carbon disclosure, favoring laminated timber over emissions-intensive alternatives.
- Hybrid Construction Convergence:Integration of glulam with cross-laminated timber floor panels and steel moment frames is opening 18-25 story envelopes previously inaccessible to pure mass timber systems.
Industry Challenges
- Mass Timber Design Competency Gap:Fewer than 12% of US structural engineering programs require mass timber coursework, forcing employers to fund intensive retraining for fire-rated connection design.
- Long-Lead Capital Equipment:Finger-jointing lines and continuous presses require 18-24 month delivery cycles from European and Asian OEMs, complicating capacity planning against volatile construction demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Glue-Laminated Timber Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Structural Glued Laminated Timber, Architectural Glued Laminated Timber, Pre-manufactured Glued Laminated Timber, Specialty Glued Laminated Timber End User: Residential Buildings, Commercial Buildings, Industrial Structures, Infrastructure Projects Application: Roofing, Beams, Columns, Floors Distribution Channel: Direct Sales, Wholesalers, Online Retail, Specialty Stores |
| Companies Covered | Rosboro, American Laminators, Boise Cascade Company, Weyerhaeuser, LP Building Solutions, Stora Enso Oyj, Structurlam Mass Timber Corporation, Georgia-Pacific, Canfor Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Glue-Laminated Timber Market Strategic Shifts & Innovations
Digital fabrication and automated quality control are compressing the gap between architectural aspiration and manufacturing repeatability. These advances are enabling more complex geometries while tightening variance tolerances that insurers and code officials scrutinize.
Hybrid adhesive systems combining phenol-resorcinol durability with polyurethane cure speed are bifurcating the market between commodity structural members and premium architectural grades. Large-scale commercial builders specify the faster-cure formulations for repetitive beam-column framing where speed dominates cost. Custom fabricators serving museums and civic buildings retain slower-cure PRF adhesives for their superior moisture resistance and visual clarity in exposed applications.
Canadian provincial regulators and US state building code adoptions are diverging on fire-testing protocols for encapsulated mass timber assemblies. British Columbia's Building Code maintains more permissive char-rate assumptions than California's Office of the State Fire Marshal, forcing manufacturers to maintain dual certification libraries. This friction is concentrating specification authority with national architectural firms capable of navigating jurisdictional variance.
Developer procurement of glulam through design-build and integrated project delivery contracts is displacing traditional bid-specify-award sequences. General contractors with captive mass timber expertise now package structural engineering, fabrication, and erection into single-source agreements. This consolidation is most visible in Vancouver, Seattle, and Portland where repeat developer-contractor pairings dominate mid-rise residential pipelines.
North America Glue-Laminated Timber Market Segmentation
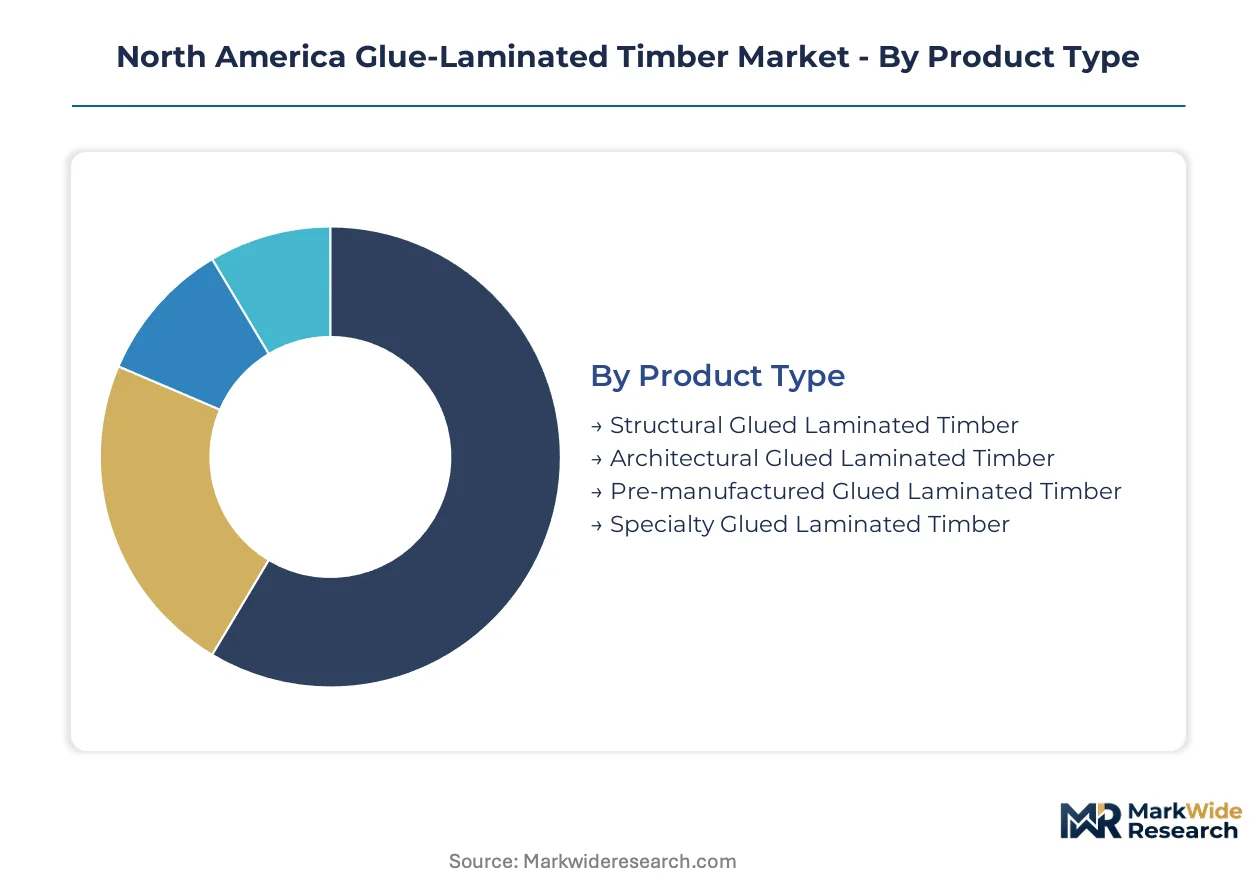
Segmentation reveals where engineered wood systems displace incumbent materials. Each dimension exposes distinct substitution pressures, cost structures, and specification authority that determine competitive outcomes across the United States and Canada.
Product Type:
Substitution pressure from steel and concrete varies sharply across product categories, with structural grades facing the most intense price competition while architectural grades defend premium positioning through aesthetic differentiation.
- Structural Glued Laminated Timber:Standardized beams and columns with predictable mechanical properties specified for repetitive commercial framing. Demand concentrates in Pacific Northwest mid-rise office and residential projects where the International Building Code's expanded height allowances accelerate permitting against steel alternatives.
- Architectural Glued Laminated Timber:Exposed-grade members with tight visual quality standards for institutional and civic buildings. Museums and performance venues in Vancouver, Seattle, and Portland specify these for biophilic design outcomes that concrete cannot replicate.
- Pre-manufactured Glued Laminated Timber:Off-site fabricated assemblies reducing field labor hours for mid-rise developers.
- Specialty Glued Laminated Timber:Custom-curved and tapered members for signature architectural statements.
Structural glued laminated timber anchors the volume base while pre-manufactured glued laminated timber gains share at the steepest rate.
End User:
Cost tier segmentation separates price-sensitive volume buyers from specification-driven premium adopters, with procurement authority residing in fundamentally different stakeholder groups across each tier.
- Commercial Buildings:Office, retail, and hospitality developers driving the bulk of mid-rise mass timber adoption. British Columbia and Washington State public-sector procurement mandates for embodied carbon disclosure tilt specification toward laminated timber over steel-concrete hybrid systems.
- Residential Buildings:Mid-rise multifamily developers in Portland, Vancouver, and Toronto pursuing faster construction schedules through prefabricated structural systems.
- Industrial Structures:Warehousing and manufacturing facilities with wide-span requirements.
- Infrastructure Projects:Bridges, pedestrian overpasses, and transit facilities with durability demands.
Commercial buildings command the dominant revenue share while residential buildings demonstrate the steepest expansion trajectory.
Application:
Volume concentration in horizontal versus vertical structural elements determines manufacturing scale economies and press capacity planning across Pacific Northwest production facilities.
- Beams:Primary horizontal load-bearing members spanning 20-60 feet in commercial and institutional construction. Repetitive specification in Type IV-A mid-rise buildings across Seattle and Portland drives continuous press utilization at regional manufacturing plants.
- Columns:Vertical compression members enabling open floor plates. Fire-rated connection detailing requirements concentrate demand with engineered wood specialists capable of integrated design-build delivery.
- Roofing:Long-span systems for arenas, hangars, and agricultural facilities.
- Floors:Hybrid assemblies combining glulam beams with cross-laminated timber panels.
Beams anchor the volume base while floors gain share at the steepest rate.
Distribution Channel:
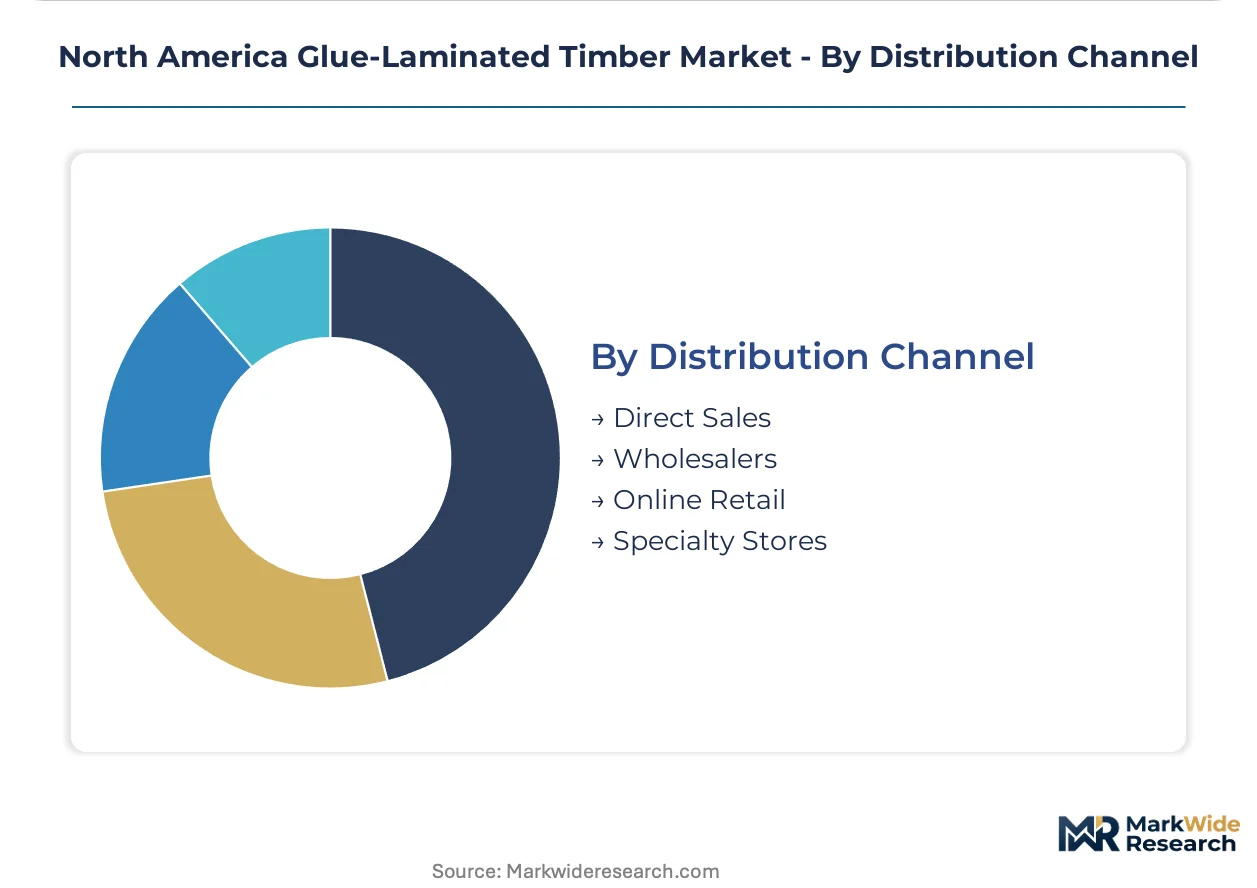
Supply chain configuration determines lead time reliability and specification influence, with channel choice reflecting project scale and contractor capability maturity across the United States and Canada.
- Direct Sales:Manufacturer-to-contractor relationships for large-scale commercial and institutional projects. Design-build and integrated project delivery contracts in Vancouver and Portland consolidate procurement through single-source agreements with captive engineering services.
- Wholesalers:Regional distributors serving smaller commercial builders and residential contractors without direct mill relationships.
- Online Retail:Emerging channel for standardized beam and column specifications with transparent pricing.
- Specialty Stores:Localized outlets serving renovation and custom residential markets.
Direct sales anchors the volume base while online retail gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Columbia River-Snake River waterway system anchors Pacific Northwest timber logistics, moving Douglas-fir lamstock from interior British Columbia and Oregon to manufacturing clusters along the I-5 corridor. This infrastructure underwrites North America's densest concentration of glulam production capacity.
United States
Mid-rise developers in Seattle and Portland are accelerating mass timber permitting under the International Building Code's 2024 Type IV-A height expansions. Washington State's Buy Clean Washington Act mandates embodied carbon disclosure for public projects above five thousand square feet. Oregon's Willamette Valley hosts finger-jointing and laminating facilities serving California demand through I-5 freight corridors.
Canada
British Columbia's tall wood building code precedents have compressed approval timelines for twelve-story residential towers in Vancouver and Victoria. The CSA O86 standard's harmonization with US provisions simplifies cross-border specification for architects with binational portfolios. The Okanagan Valley and Vancouver Island concentrate custom architectural-grade manufacturing for museum and civic projects.
Pacific Northwest Cluster
The Cascadia bioregion spanning Oregon, Washington, and British Columbia functions as an integrated supply basin for Douglas-fir and hem-fir lamstock. Port of Vancouver BC and Port of Longview handle bulk exports to Asian markets while feeding domestic West Coast demand. This concentration reduces procurement lead times relative to Great Lakes or Southeast US alternatives.
US Southeast
Texas and Georgia developers currently source glulam through long-haul logistics from Pacific Northwest plants, creating cost penalties against regional steel-concrete supply chains. No major laminating capacity exists between Arkansas and Florida despite accelerating mid-rise construction in Dallas, Houston, and Atlanta. This underpenetration forces project teams to absorb extended delivery schedules or specify incumbent materials.
Great Lakes Region
Minnesota and Wisconsin manufacturers serve Upper Midwest institutional markets with shorter haul distances than West Coast competitors. Ontario's cross-border manufacturing presence leverages Great Lakes shipping for Michigan and Ohio projects. This sub-region captures public-sector work in Chicago, Minneapolis, and Milwaukee where carbon disclosure requirements favor laminated timber.
North America Glue-Laminated Timber Market Key Industry Players
Concentration sits with integrated forest products companies controlling timberland through finished glulam production. The vendor base spans three tiers: captive timberland operators with laminating divisions, independent custom fabricators serving architectural-grade specifications, and diversified building materials distributors adding glulam to structural product portfolios. Scale-driven capacity expansion and design-build partnership formation represent the dominant competitive vectors as developers consolidate procurement authority.
Among Pacific Northwest integrated producers, Rosboro and Weyerhaeuser exemplify timberland-to-finished-product architectures, while Structurlam Mass Timber Corporation occupies a specialist position in custom architectural-grade fabrication. Boise Cascade Company and Georgia-Pacific represent diversified building materials platforms where glulam complements broader engineered wood portfolios. These five entities anchor competitive dynamics across commercial, institutional, and residential specification channels.
| Leading Market Players |
|---|
| Rosboro |
| American Laminators |
| Boise Cascade Company |
| Weyerhaeuser |
| LP Building Solutions |
| Stora Enso Oyj |
| Structurlam Mass Timber Corporation |
| Georgia-Pacific |
| Canfor Corporation |
| Others |
Cost & Logistics Intelligence
Eighteen-to-twenty-four-month delivery cycles for finger-jointing lines and continuous presses concentrate pricing power with Pacific Northwest manufacturers holding installed capacity, while buyers absorb extended lead times or pay premiums for spot availability.
Pricing Analysis
Volume-discount tiering separates architectural-grade members from structural commodity beams and pre-manufactured assemblies. Pricing stratifies across premium, standard, and economy tiers based on visual quality certification and project scale, with cost compression in structural grades intensifying as steel-concrete hybrids compete for mid-rise frames. Institutional buyers demonstrate lowest price sensitivity where biophilic design mandates override material cost, while residential developers exhibit highest sensitivity to delivered cost per square foot.
Supply Chain Analysis
Columbia River-Snake River waterway transit underwrites Pacific Northwest lamstock flows from interior British Columbia and Oregon to I-5 corridor manufacturing clusters. Supply draws from Douglas-fir and hem-fir timberlands in the United States and Canada, with phenol-resorcinol and polyurethane adhesives sourced from petrochemical feedstock networks. Single-source vulnerability concentrates in European and Asian OEMs for capital equipment. Distribution runs through direct manufacturer-contractor relationships for large projects and regional wholesalers for smaller commercial builders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mass timber design competency gaps—fewer than twelve percent of United States structural engineering programs require relevant coursework—create bottlenecks that determine competitive outcomes more than raw material access.
For Market Incumbents: Consolidate captive engineering services and design-build delivery capabilities to lock out steel-concrete subcontractors from mid-rise developer relationships. Add press capacity in the US Southeast before regional competitors capture Texas and Georgia demand. Certification investment in dual fire-testing protocols for British Columbia and California jurisdictions defends specification authority against architectural firms with limited jurisdictional expertise. For New Entrants and Emerging Players: Anchor in US Southeast greenfield territory where no major laminating capacity exists between Arkansas and Florida. Target Dallas, Houston, and Atlanta mid-rise residential pipelines with faster delivery schedules than Pacific Northwest haul logistics permit. Pursue integrated project delivery partnerships with general contractors seeking single-source structural packages. For Investors and Strategic Acquirers: Long-term, this sits as a carbon-accounting infrastructure play because California, Washington, and British Columbia public-sector procurement mandates hardwire laminated timber into institutional construction. Acquisition targets include custom architectural-grade fabricators with museum and civic building portfolios. Watch for International Building Code adoption velocity in additional states as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Timberlands | Rosboro and Weyerhaeuser control Douglas-fir supply from Pacific Northwest forests through finished production. |
| Design-Build Partnership Formation | General contractors in Vancouver and Seattle package structural engineering, fabrication, and erection into single-source agreements. |
| Dual Certification Investment | Manufacturers maintain separate fire-testing libraries for British Columbia's char-rate assumptions and California's Office of the State Fire Marshal protocols. |
| Southeast US Capacity Expansion | Greenfield plants in Texas or Georgia would eliminate long-haul logistics penalties against regional steel-concrete supply chains. |
| Hybrid Adhesive System Development | Formulations combining phenol-resorcinol durability with polyurethane cure speed bifurcate commodity and premium product lines. |
Research Approach
The analysis maps structural glued laminated timber, architectural grade, pre-manufactured assemblies, and specialty curved members, each validated through plant managers at laminating facilities, procurement leads at multi-story commercial developers, structural engineers specifying mass timber systems, and APA-certified quality auditors. Secondary sources include International Building Code adoption records, CSA O86 standard documentation, American Wood Council technical bulletins, and state-level carbon disclosure mandate filings. Bottom-up capacity utilization data triangulates against top-down construction permit flows.
Consistency checks validated volume and value outputs against regional construction spending benchmarks and engineered wood product trade flows across the analysis window. The analytical framework models product type, end-use sector, application element, and distribution channel dimensions. CAGRs derive from installed capacity expansion schedules, code adoption timelines, and substitution elasticity against steel-concrete alternatives. Forecast inputs include Pacific Northwest timber harvest volumes and petrochemical adhesive price indices.
Material uncertainties—IBC height allowance adoption rates in additional states, adhesive cost volatility tied to oil markets, and certified inspector pool expansion—sit outside the modeled envelope. Practitioners should keep alternative scenarios live as regulatory harmonization between United States and Canadian jurisdictions evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
North America & Europe Adhesives and Sealants Market
Adhesives & Sealants
Cycloaliphatic Epoxy Market
Adhesives & Sealants
Middle East & Africa Adhesives and Sealants Market
Adhesives & Sealants
Europe Adhesives and Sealants Market
Adhesives & Sealants
Ocular Sealants and Glues Market
Adhesives & Sealants
South America Electronics Adhesives Market
Adhesives & Sealants
Lignin for Adhesives Market
Adhesives & Sealants
PVA Glue Market
Adhesives & Sealants
Global Elastic Adhesive Market
Adhesives & Sealants
Waterproof Tapes Market
Adhesives & Sealants
Wood to Metal Glue Market
Adhesives & Sealants
Construction Repair and Rehabilitation Chemicals Market
Adhesives & Sealants
Windscreen Adhesive Market
Adhesives & Sealants
Global Stone and Tile Adhesives and Sealants Market
Adhesives & Sealants
Asia-Pacific Adhesives Market
Adhesives & Sealants
North America Electronics Adhesives Market