
 Waterproof Tapes Market | 2026-2036
Waterproof Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Waterproof Tapes Market Analysis
Multi-source procurement among construction chemical distributors is recalibrating how waterproof tape volumes flow into European building projects. 3M leverages its polymer science portfolio to sustain premium positioning in electrical insulation tapes. Henkel anchors its construction adhesives channel with complementary waterproof tape SKUs for professional contractors.
Waterproof tapes are pressure-sensitive adhesive strips engineered from PVC, polyethylene, rubber, or fabric backings with acrylic or silicone adhesives, designed to block moisture ingress across seams, joints, and substrate transitions in harsh environments. PVC tapes dominate mature repair and maintenance segments where cost sensitivity shapes contractor purchasing, while rubber tapes capture margin pools in automotive underhood and marine sealing applications where temperature cycling resistance commands specification premiums. Fabric tapes are gaining fastest in DIY and contractor segments where hand-tearability and conformability to irregular surfaces reduce installation labor.
REACH compliance in Europe, EPA VOC regulations in the United States, and China's GB standards for construction materials collectively elevate formulation costs while screening out low-grade imports. ECHA's expanding SVHC candidate list is forcing solvent-based adhesive reformulation toward waterborne and hot-melt systems. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory in cross-border supply chains.
Market Dynamics
The waterproof tapes market is restructuring around tightening building envelope regulations under the EU Green Deal, forcing contractors to specify certified sealing systems that outperform commodity-grade alternatives. This regulatory compression is accelerating specification-grade tape displacement of PVC-based maintenance products in commercial construction across Germany, France, and the Netherlands.
Growth Catalysts
- Energy Performance Certificate mandates:Germany's EPC tightening under the EU Green Deal compels building envelope upgrades, expanding specification-grade tape volumes for air and moisture barrier continuity.
- Marine electrical sealing:China's coastal manufacturing provinces generate bulk orders for rubber-backed tapes with silicone adhesives resisting salt corrosion and thermal cycling in shipboard cable management.
- Hot-melt adhesive systems:ECHA's SVHC expansion is absorbing solvent-based formulation capacity into waterborne and reactive hot-melt platforms with lower VOC profiles.
Market Restraints
- Petrochemical input volatility:Acrylic monomer and silicone rubber feedstock costs fluctuate with crude oil and natural gas pricing, compressing formulation margins unpredictably.
- Specialty polymer supply concentration:High-performance rubber backing production concentrates among a limited supplier base in Northeast Asia, creating single-source vulnerability for temperature-rated marine and automotive grades.
- Technical performance ceiling:PVC tapes face inherent plastizer migration limits that restrict long-term adhesion in sub-zero exterior applications, capping their specification potential.
Strategic Opportunities
- Indian infrastructure buildout:Highway tunnel waterproofing and metro rail expansion create demand for fabric-backed conformable tapes in geotechnical sealing applications.
- Electric vehicle battery pack sealing:Thermal runaway containment specifications are absorbing multi-layer tape laminates combining flame resistance with pressure-sensitive conformability.
- Professional contractor direct channels:Construction chemical distributors are building dedicated waterproof tape SKUs alongside structural adhesives, capturing specification influence at the point of envelope design.
Industry Challenges
- REACH SVHC reformulation timelines:ECHA's expanding candidate list forces 12-18 month adhesive requalification cycles, straining R&D bandwidth and delaying product launches.
- Cross-border inventory stranding:Divergent VOC regulations between EPA jurisdictions and EU member states create compliance mismatches that trap mislabeled stock in transit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Waterproof Tapes Market |
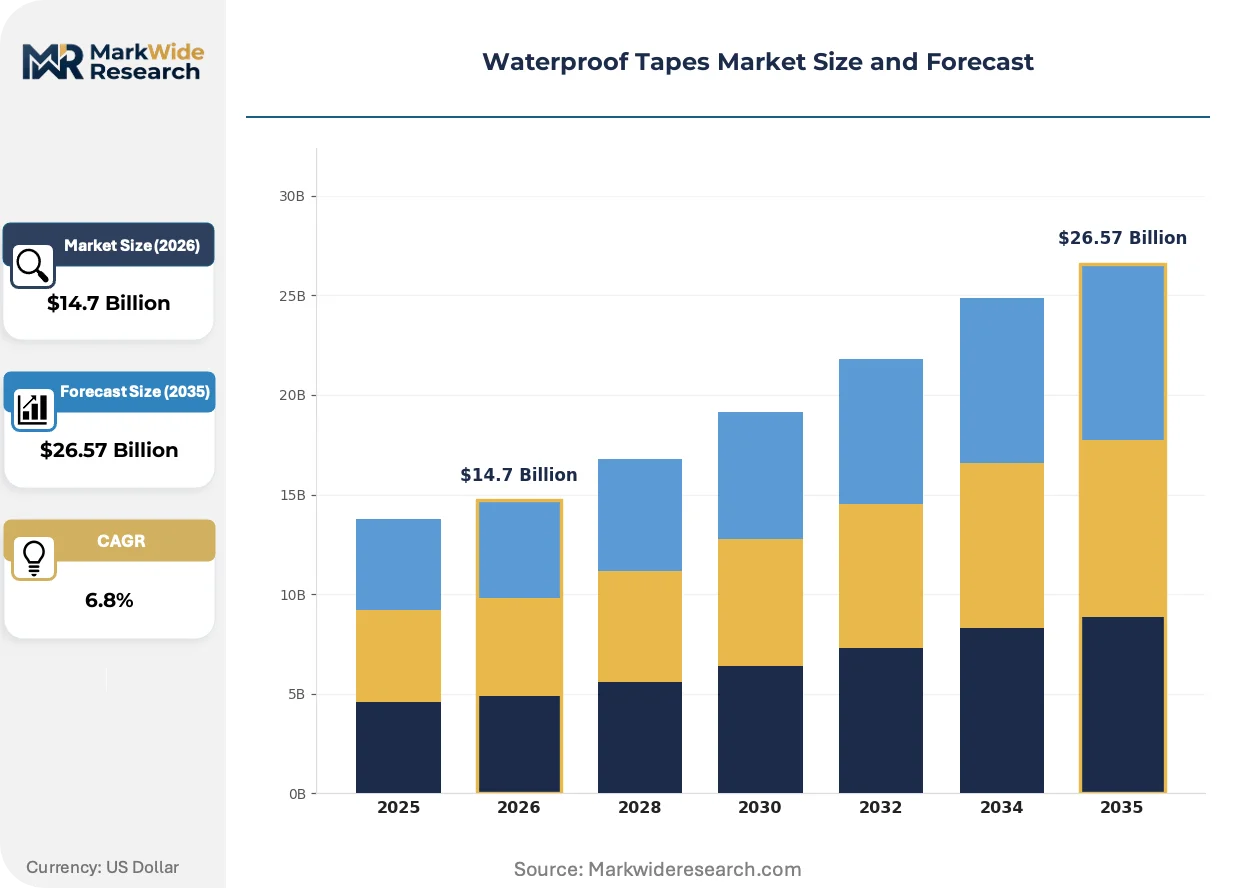
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PVC Tapes, Polyethylene Tapes, Rubber Tapes, Fabric Tapes Application: Construction, Automotive, Electrical, Marine Material: Polyester, Polypropylene, Silicone, Acrylic End User: Contractors, Manufacturers, Retailers, DIY Enthusiasts |
| Companies Covered | 3M, tesa SE, Nitto Denko Corporation, Henkel, Scapa, Shurtape Technologies, Johnson & Johnson, DuPont, H.B. Fuller Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Waterproof Tapes Market Emerging Trajectories
Formulation chemistry and specification workflows are converging to displace commodity-grade tapes from high-performance building envelope and transportation applications. Three distinct vectors are compressing the addressable market for legacy PVC products while expanding margin pools in certified systems.
Butyl rubber hybrid tapes with integrated non-woven reinforcement layers are absorbing specification volume in below-grade foundation waterproofing. German and Austrian contractors specify these systems for basement tanking where hand-tearable conformability reduces labor hours on irregular concrete surfaces. The technology is absorbing market share from torch-applied bituminous membranes in residential and light commercial segments.
REACH authorization requirements for diisocyanates in polyurethane adhesive systems are forcing tape manufacturers toward alternative chemistries. Industrial hygiene mandates now require worker training certification for handling legacy PU formulations, elevating waterborne acrylic and UV-cured silicone platforms. Construction chemical distributors in Belgium and the Netherlands report accelerating SKU transitions to compliant alternatives ahead of 2025 enforcement deadlines.
Building envelope commissioning protocols now require continuous air barrier documentation, shifting contractor preference toward manufacturer-certified tape systems with third-party test reports. This specification behavior compresses spot-buying of unbranded commodity tapes in commercial construction. The shift is most visible in Nordic markets where passive house standards mandate blower-door verified performance.
Waterproof Tapes Market Segmentation
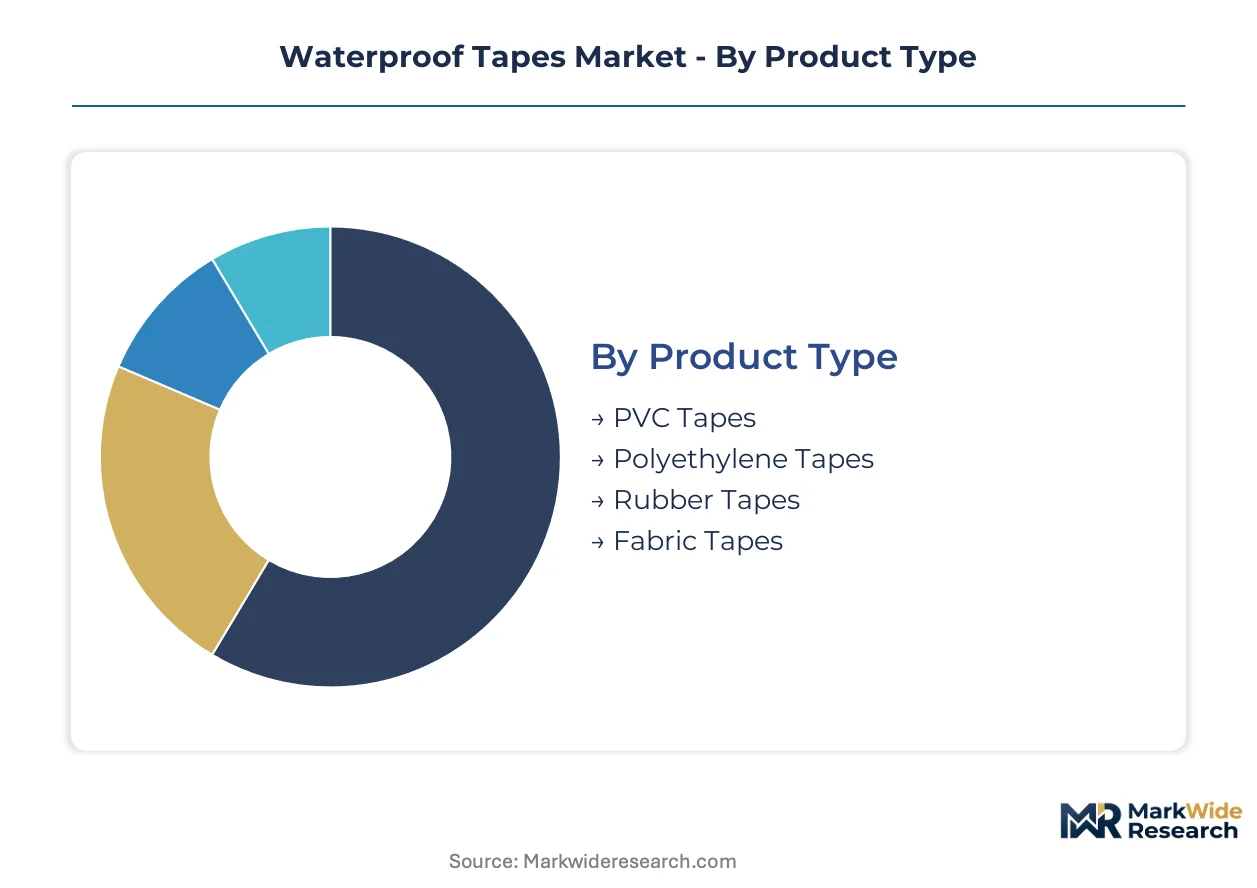
Waterproof tape procurement patterns diverge sharply between specification-driven commercial construction and price-sensitive maintenance channels. Material chemistry and application environment dictate performance premiums, while end-user sophistication determines distribution pathway selection.
Product Type:
Cost sensitivity separates maintenance contractors from specification-grade buyers across material platforms.
- Rubber Tapes:These silicone or EPDM-backed strips deliver temperature cycling resistance from -40°C to 150°C with superior conformability to irregular substrates. Marine electrical sealing in China's coastal manufacturing provinces absorbs bulk volumes where salt corrosion and thermal shock demand specification-grade performance.
- Fabric Tapes:Woven or non-woven reinforcement layers bonded with aggressive adhesives enable hand-tearable installation without tools. German basement waterproofing contractors specify butyl-rubber hybrids with integrated fleece backing for below-grade tanking where labor efficiency on irregular concrete surfaces commands premium positioning.
- PVC Tapes:Plasticized vinyl backings with rubber or acrylic adhesives dominate mature repair segments where cost-per-meter drives contractor purchasing decisions.
- Polyethylene Tapes:Cross-linked PE films with butyl or hot-melt adhesives serve temporary weatherproofing and surface protection applications in construction staging.
Volume sits with PVC Tapes; growth tilts toward Fabric Tapes.
Application:
Regulatory stringency determines specification depth and margin capture across vertical markets.
- Construction:Building envelope continuity systems under EU Green Deal EPC mandates require certified air and moisture barrier tapes with third-party test documentation. German and Dutch commercial projects now specify manufacturer-certified systems over spot-bought commodity alternatives.
- Electrical:Insulation and cable management tapes face dual requirements for dielectric strength and environmental sealing. Marine electrical applications in China's shipbuilding clusters absorb rubber-backed silicone adhesive tapes rated for continuous salt spray exposure.
- Automotive:Underhood sealing and NVH applications demand temperature-rated acrylic foam tapes with OEM qualification protocols.
- Marine:Hull sealing and deck waterproofing combine UV resistance with saltwater immersion performance in shipyard production environments.
Construction commands current volume; electrical applications are climbing the fastest on marine and EV battery pack sealing specifications.
Material:
Formulation chemistry alignment with regulatory deadlines is reshaping adhesive platform selection.
- Silicone:Platinum-cured polysiloxane adhesives deliver unmatched thermal stability and UV resistance for exterior building envelope and marine applications. REACH SVHC expansion is accelerating waterborne silicone platform adoption ahead of solvent-based phase-outs.
- Acrylic:UV-curable and emulsion acrylics balance adhesion build with regulatory compliance in professional contractor channels. Construction chemical distributors in Belgium and the Netherlands report accelerating SKU transitions to waterborne acrylic alternatives ahead of diisocyanate handling certification requirements.
- Polyester:PET film backings provide dimensional stability for electrical insulation tapes with thin-gauge precision.
- Polypropylene:Oriented PP films offer moisture barrier properties in cost-optimized packaging and temporary protection applications.
Acrylic formulations hold installed base volume; silicone platforms are gaining share fastest on temperature-rated specification demand.
End User:
Channel structure and technical support requirements segment buyer sophistication tiers.
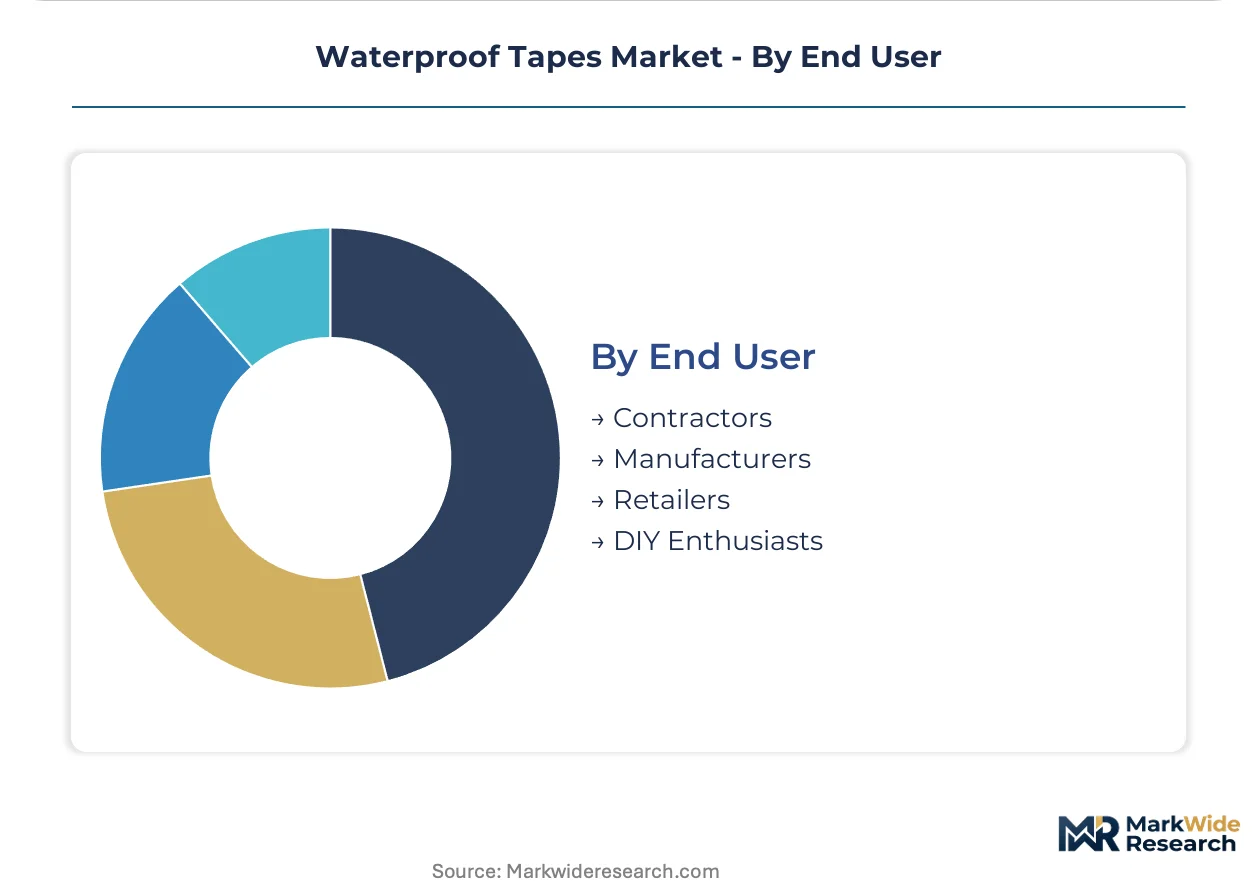
- Contractors:Professional envelope and waterproofing specialists require manufacturer-certified systems with application training and job-site technical support. German building envelope contractors now specify integrated tape-and-membrane systems with continuous air barrier documentation for blower-door verification.
- Manufacturers:OEM and tier-1 suppliers demand lot-traceable materials with statistical process control documentation for automotive and marine production integration. EV battery pack assemblers specify multi-layer laminates combining flame resistance with pressure-sensitive conformability for thermal runaway containment.
- Retailers:Big-box and specialty distribution channels stock consumer-format SKUs with simplified performance claims for homeowner maintenance applications.
- DIY Enthusiasts:Online-direct and home improvement store purchasers drive fabric tape growth where hand-tearability and conformability reduce skill barriers for irregular surface repair.
Contractors represent current volume concentration; manufacturers are expanding most quickly on transportation electrification sealing specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicone rubber feedstock concentration in Northeast Asia anchors waterproof tape production networks. German construction chemical distributors channel specification-grade volumes into building envelope upgrades. China's coastal manufacturing provinces generate bulk orders for marine electrical sealing applications.
Germany
Building envelope contractors specify certified air barrier tapes for EPC compliance under the EU Green Deal. REACH SVHC expansion forces 12-18 month adhesive requalification cycles. The Rhine-Ruhr industrial corridor concentrates formulation R&D for waterborne acrylic platforms ahead of diisocyanate handling mandates.
China
Marine electrical sealing in shipbuilding clusters absorbs rubber-backed silicone adhesive tapes rated for salt spray exposure. GB standards for construction materials elevate formulation costs while screening low-grade imports. Yangtze River Delta manufacturing provinces generate bulk procurement for cable management in coastal industrial facilities.
United States
EPA VOC regulations compress solvent-based adhesive capacity toward compliant alternatives. Construction staging drives temporary weatherproofing demand for cross-linked polyethylene tapes. The Gulf Coast petrochemical corridor supplies acrylic monomer feedstock for pressure-sensitive adhesive production.
India
Highway tunnel waterproofing and metro rail expansion create demand for fabric-backed conformable tapes in geotechnical sealing. BIS standards for construction materials shape import qualification protocols. Maharashtra infrastructure projects specify butyl-rubber hybrids for below-grade foundation applications.
Netherlands
Construction chemical distributors build dedicated waterproof tape SKUs alongside structural adhesives for professional contractors. ECHA's expanding candidate list accelerates SKU transitions to waterborne alternatives. The Randstad logistics hub channels specification-grade volumes into Nordic passive house construction markets.
Waterproof Tapes Market Vendor Landscape
Global majors compete with regional champions across formulation chemistry and specification influence. The vendor base stratifies into three tiers: diversified adhesive conglomerates with polymer science portfolios, construction chemical specialists with contractor channel access, and regional fabricators serving price-sensitive maintenance segments. Dominant competitive moves include portfolio diversification into certified building envelope systems and backward integration into specialty rubber backing production.
Within the diversified conglomerate tier, 3M and Henkel exemplify contrasting strategic positions. 3M leverages its materials science heritage to anchor premium electrical insulation and industrial sealing applications. Henkel occupies a complementary position through its construction adhesives channel, integrating waterproof tape SKUs into professional contractor workflows. Nitto Denko Corporation represents the Asia-Pacific specialist archetype, with its corporate structure suggesting concentrated exposure to electronics and transportation sealing markets.
| Leading Market Players |
|---|
| 3M |
| tesa SE |
| Nitto Denko Corporation |
| Henkel |
| Scapa |
| Shurtape Technologies |
| Johnson & Johnson |
| DuPont |
| H.B. Fuller Company |
| Others |
Supply Flow & Price Mechanics
Specialized adhesive formulation chemists concentrated in Germany's Rhine-Ruhr corridor and Japan's Kansai region command wage premiums that widen spreads between specification-grade and commodity tape pricing tiers. Labor-cost differentials between these technical centers and mass-production facilities in coastal China directly shape three-tier pricing structures across premium certified systems, professional-grade SKUs, and economy maintenance products.
Pricing Analysis
Warranty-backed application support bundled with manufacturer-certified systems separates premium positioning from unbundled commodity spot purchases. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with EPC-compliant air barrier systems commanding spreads over uncertified PVC alternatives. Cost compression in the economy tier intensifies as Asian imports absorb spot-buying volumes in maintenance channels. DIY enthusiasts and small repair contractors exhibit highest price sensitivity, while building envelope specialists prioritize specification compliance over per-meter cost.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Los Angeles anchor hub-and-spoke patterns channeling bulk volumes to construction chemical distributors. Manufacturing concentration in China, Germany, and Japan feeds from acrylic monomer and silicone rubber feedstock streams tethered to petrochemical corridors. Single-source vulnerability concentrates in high-performance rubber backing production among limited Northeast Asian suppliers. Distribution runs through construction chemical specialists and big-box retail channels serving distinct contractor and consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH SVHC expansion and ECHA's diisocyanate handling mandates erect barrier-to-entry moats favoring incumbents with dedicated reformulation bandwidth and regulatory affairs infrastructure.
For Market Incumbents: Lock in specification influence through backward integration into specialty silicone rubber production, eliminating single-source exposure for temperature-rated marine and automotive grades. Anchor contractor relationships via certified application training programs that embed your systems into blower-door verification workflows. Priority defensive moves center on capturing EPC-mandated building envelope volumes before commodity alternatives achieve requalification. For New Entrants and Emerging Players: The price-point gap between premium certified systems and economy PVC tapes creates white-space for mid-tier professional-grade SKUs with simplified certification. Target India's highway tunnel and metro rail infrastructure buildout where BIS qualification protocols favor local formulation partnerships over import-dependent incumbents. Go-to-market leverage rests on fabric-backed butyl-rubber hybrids optimized for geotechnical labor efficiency rather than specification depth. For Investors and Strategic Acquirers: Re-rating potential sits with construction chemical distributors given their specification influence at the point of envelope design and accelerating SKU buildouts alongside structural adhesives. Long-term viability over the coming decade favors platforms with waterborne adhesive capabilities ahead of solvent-based phase-outs. The signal to watch is ECHA enforcement velocity on diisocyanate handling certifications, which will accelerate consolidation among non-compliant regional fabricators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Rubber Production | Captive supply of temperature-rated backings eliminates Northeast Asian single-source vulnerability for marine grades. |
| Waterborne Adhesive Platform Transition | REACH SVHC compliance ahead of 2025 diisocyanate mandates secures specification access in EU Green Deal projects. |
| Certified Contractor Training Programs | Application support bundling embeds manufacturer systems into blower-door verification workflows across Germany and Netherlands. |
| Regional Distribution Center Expansion | Hub-and-spoke proximity to India's Maharashtra infrastructure corridor captures geotechnical sealing demand. |
| Multi-Layer Laminate Development for EV Battery Packs | Thermal runaway containment specifications absorb flame-resistant tape laminates into automotive OEM qualification protocols. |
Methodological Framework
Multi-period observation of formulation chemistry transitions, regulatory deadline pacing, and specification-grade displacement patterns anchored the trend analysis, supplemented by interviews with construction chemical distribution managers, building envelope contractors, adhesive R&D directors, marine electrical procurement leads, and automotive Tier 1 sealing engineers. Secondary validation drew from ECHA SVHC candidate list updates, EU Green Deal EPC implementation guidance, GB standards construction material databases, customs trade flow records, and SEC filings of diversified adhesive conglomerates. Bottom-up volume triangulation across product type, application, and end-user segments converged with top-down market sizing.
Input-output matrix modeling mapped acrylic monomer and silicone rubber feedstock cost trajectories to formulation margin structures across the projection horizon. Segmentation dimensions spanned material chemistry, backing construction, adhesive platform, end-use vertical, and regional regulatory cluster. CAGRs derived from fitted trend lines applied to specification-grade penetration curves and displacement rates of legacy PVC products. Industry-specific forecast inputs incorporated EPC mandate implementation schedules and EV battery pack thermal management specification evolution.
Inputs from primary field contacts and published regulatory guidance were available through the study window; gaps in real-time contractor procurement data and OEM qualification timeline visibility introduce uncertainty bands around near-term specification-grade volume assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Chlorinated Polyolefin Adhesion Promoter Market
Adhesives & Sealants
Middle East & Africa Automotive Adhesives & Sealants Market
Adhesives & Sealants
Waterproofing Admixture Market
Adhesives & Sealants
Global Hybrid Adhesives and Sealants Market
Adhesives & Sealants
Global Contact Adhesives Market
Adhesives & Sealants
Middle-East and Africa Polyurethane (PU) Adhesives Market
Adhesives & Sealants
Global Silicone Adhesives and Sealants Market
Adhesives & Sealants
Europe Hot-Melt Adhesives Market
Adhesives & Sealants
Europe Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Acrylic Glue Market
Adhesives & Sealants
Middle East & Africa Adhesives and Sealants Market
Adhesives & Sealants
Wood to Metal Glue Market
Adhesives & Sealants
South America Cyanoacrylate Adhesives Market
Adhesives & Sealants
Metal Bonding Adhesives Market
Adhesives & Sealants
Europe Adhesives and Sealants Market
Adhesives & Sealants
Restorative Materials and Bonding Agents Market