
 Global Stone and Tile Adhesives and Sealants Market | 2026-2036
Global Stone and Tile Adhesives and Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Stone and Tile Adhesives and Sealants Market Foresight
Aftermarket service revenue for substrate preparation and extended warranty application is fragmenting across regional service networks and certified installer programs. MAPEI S.p.A. leverages its global training infrastructure to anchor specification loyalty among commercial contractors. LATICRETE International, Inc. competes through its specialized epoxy adhesive formulations for demanding swimming pool and facade bonding environments.
Stone and tile adhesives and sealants comprise polymer-modified cementitious compounds, reactive resin systems, and elastomeric sealants engineered to bond natural stone, ceramic, porcelain, and glass tile substrates across variable temperature and moisture conditions. Epoxy adhesives dominate structural load-bearing applications where chemical resistance and zero-shrinkage performance are mandatory, while silicone sealants capture premium weatherproofing and movement-joint specifications in exterior facade systems. Polyurethane adhesives sustain the fastest growth trajectory among reactive chemistries, driven by their superior elongation properties and compatibility with engineered stone substrates in commercial flooring installation.
EMA's construction product regulations under the EU Green Deal, EPA VOC emission limits for architectural coatings in the United States, and BIS certification requirements for tile adhesives in India collectively tighten formulation compliance and testing documentation burdens. CE marking and REACH substance restrictions are forcing raw material substitutions away from certain isocyanate and solvent-based chemistries toward water-dispersed and bio-based alternatives. Stakeholders must monitor regulatory divergence between European carbon-footprint disclosure rules and emerging Indian domestic-content mandates when configuring regional product portfolios and supply chain footprints.
Market Dynamics
Polyurethane adhesive chemistry is hybridizing with cementitious systems to capture load-bearing flooring specifications previously reserved for epoxies, compressing specification cycles and forcing raw material suppliers to reconfigure additive portfolios.
Growth Catalysts
- Facade bonding specifications:Commercial contractors in the United States are specifying high-performance reactive resin systems for exterior cladding projects subject to thermal cycling stress.
- PLI scheme acceleration:India's production-linked incentive framework for construction chemicals is accelerating domestic manufacturing capacity for polymer-modified cementitious compounds.
- Zero-shrinkage epoxy demand:Swimming pool and wet-area installers require chemical-resistant bonding systems that eliminate substrate stress cracking.
Market Restraints
- Isocyanate input volatility:Polyurethane adhesive producers face raw material cost instability tied to MDI and TDI supply concentration in Northeast Asian petrochemical complexes.
- REACH substance restrictions:ECHA's evolving candidate list for Substances of Very High Concern is forcing reformulation away from certain solvent-based chemistries before alternatives achieve cost parity.
- Cement price escalation:Energy-intensive clinker production in Europe and India is elevating base material costs for cementitious adhesive formulations.
Strategic Opportunities
- Engineered stone compatibility:Porcelain and sintered stone slab fabricators in Italy and Spain require adhesives with superior elongation properties for large-format installation.
- Water-dispersed bio-based alternatives:Formulators exploiting bio-polyol feedstocks can position ahead of EU Green Deal carbon-footprint disclosure mandates.
- Certified installer channel development:MAPEI's global training infrastructure demonstrates how anchoring specification loyalty through technical education captures commercial contractor preference.
Industry Challenges
- Multi-jurisdiction certification timelines:Products requiring simultaneous BIS approval in India, CE marking in Europe, and EPA VOC compliance in the United States face extended commercialization cycles.
- Skilled applicator scarcity:Proper mixing and placement of reactive resin systems demands trained technicians, constraining project velocity in fast-track commercial construction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Stone and Tile Adhesives and Sealants Market |
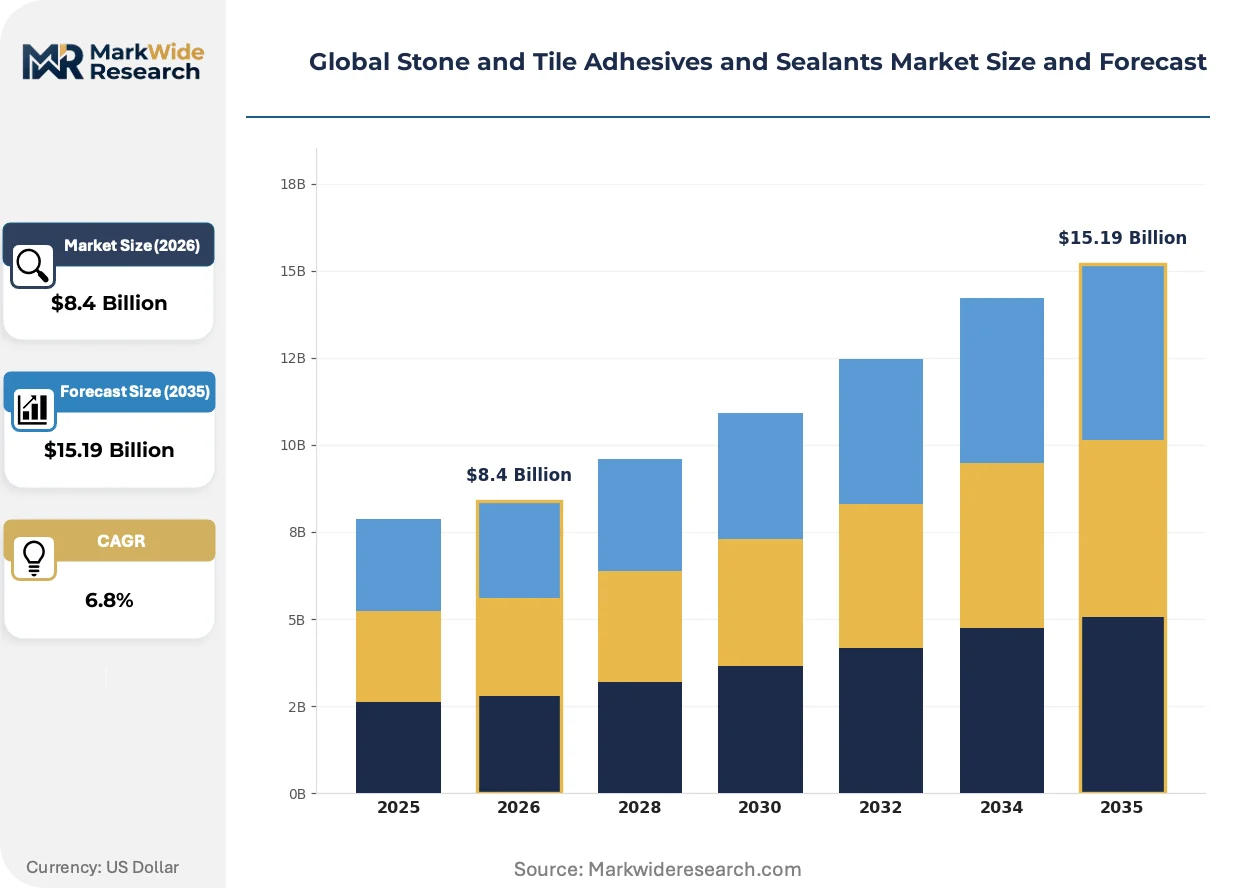
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy Adhesives, Acrylic Sealants, Polyurethane Adhesives, Silicone Sealants, Latex Adhesives, Others Application: Wall Cladding, Flooring Installation, Countertops, Swimming Pools, Facade Bonding, Masonry Repair End User: Residential Builders, Commercial Contractors, Renovation Specialists, Flooring Companies, Stone Fabricators Packaging Type: Cartridges, Buckets, Tubes, Pouches, Drums, Sachets |
| Companies Covered | Bostik S.A.S., ParexGroup SA, MAPEI S.p.A., Henkel AG & Co. KGaA, Fosroc International Limited, ARDEX GmbH, LATICRETE International, Inc., H.B. Fuller Company, Sika AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Stone and Tile Adhesives and Sealants Market Shifts & Advancements
Formulation science is converging with digital specification tools to compress product selection cycles, while regulatory chemistry restrictions and substrate material evolution are forcing parallel innovation tracks across adhesive families.
Hybrid polyurethane-cementitious adhesive technology is hybridizing the performance characteristics of reactive resin and polymer-modified cement systems. Commercial flooring contractors in Germany and the Netherlands are adopting these systems for engineered stone installations requiring both structural bond strength and substrate accommodation. This chemistry convergence is compressing the traditional specification boundary between epoxy and cementitious product categories.
REACH substance restrictions and EU Green Deal carbon-footprint disclosure rules are tightening formulation compliance burdens across European construction chemical portfolios. ECHA's candidate list expansions are forcing raw material substitutions away from certain isocyanate and aromatic solvent chemistries toward water-dispersed alternatives with shorter track records in structural applications. Adhesive producers serving facade and wet-area specifications are responding with accelerated bio-based polyol testing programs.
Certified installer programs are displacing traditional distribution-dependent specification influence in commercial contracting channels. LATICRETE's specialized epoxy formulations demonstrate how technical training infrastructure anchors loyalty among swimming pool and facade bonding specialists. This channel evolution is most visible in the United States and Australia, where contractor liability exposure drives preference toward manufacturer-backed warranty systems.
Global Stone and Tile Adhesives and Sealants Market Segmentation
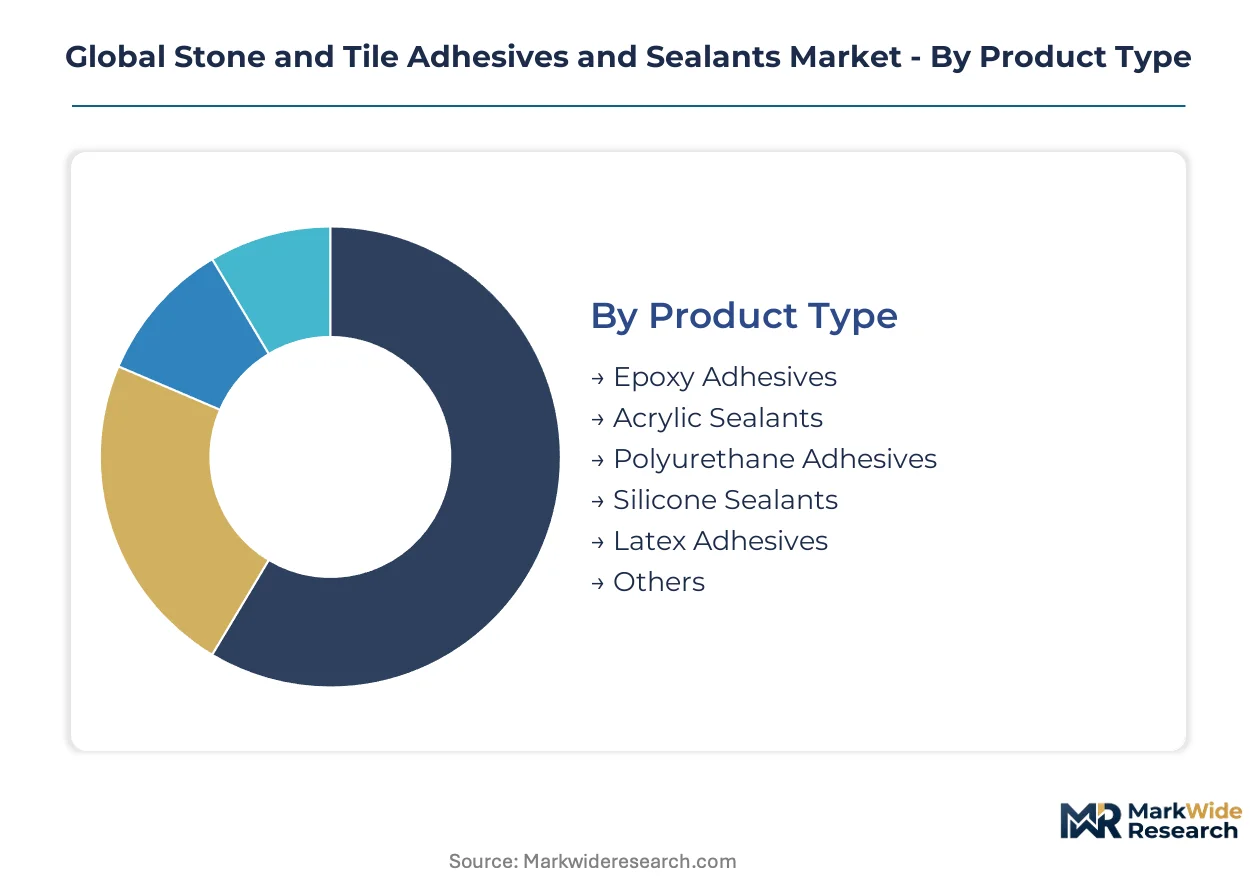
Stone and tile adhesive specifications diverge sharply across substrate types, climate exposure, and installation scale. Segmentation reveals how formulation chemistry, packaging logistics, and end-user procurement power reshape competitive positioning across residential, commercial, and industrial construction channels.
Product Type:
Reactive resin and elastomeric chemistries span a performance spectrum from structural load-bearing to flexible weatherproofing applications.
- Epoxy Adhesives:Two-component systems deliver zero-shrinkage bonding with complete chemical resistance for submerged wet-area installations. Demand concentrates in swimming pool construction across Florida and Mediterranean coastal markets where substrate cracking elimination is mandatory.
- Polyurethane Adhesives:Hybrid reactive systems combine elongation properties with structural strength for engineered stone substrates. German and Dutch commercial flooring contractors specify these for large-format porcelain slabs requiring substrate accommodation without epoxy rigidity.
- Acrylic Sealants:Water-based formulations serve interior movement joints and perimeter sealing with moderate elasticity.
- Silicone Sealants:Premium weatherproofing specifications for exterior facade systems subject to thermal cycling stress.
- Latex Adhesives:Polymer-modified cementitious compounds for standard ceramic tile bedding in residential applications.
- Others:Specialty reactive systems including modified silane and UV-cure formulations for niche substrate combinations.
Established volume favors latex adhesives; emerging adoption favors polyurethane hybrid systems.
Application:
Installation environment dictates adhesive selection through moisture exposure, thermal stress magnitude, and structural load requirements.
- Facade Bonding:Exterior cladding installations subject to wind loading and daily temperature swings demand high-performance reactive resin systems. Commercial contractors in the United States specify these for rainscreen assemblies where bond failure carries catastrophic liability exposure.
- Flooring Installation:Engineered stone and large-format porcelain deployment in commercial spaces requires adhesives balancing structural strength with substrate accommodation. Italian and Spanish fabricators drive specification toward high-elongation formulations for sintered stone slabs.
- Wall Cladding:Vertical surface bonding emphasizes non-sag rheology and rapid grab strength for overhead installation.
- Countertops:Kitchen and bath surface fabrication prioritizes stain resistance and food-contact compliance.
- Swimming Pools:Immersed applications mandate chemical-resistant epoxies eliminating substrate stress cracking.
- Masonry Repair:Historic restoration and structural rehabilitation applications favor breathable, compatible formulations.
Facade bonding commands premium pricing; flooring installation drives volume scale.
End User:
Procurement sophistication and warranty requirements separate specification-driven commercial channels from price-sensitive residential segments.
- Commercial Contractors:Large-scale construction firms with bonded installer networks specify manufacturer-backed warranty systems. These stakeholders anchor loyalty through certified training programs and extended coverage for high-exposure installations.
- Stone Fabricators:Italian and Spanish sintered stone producers influence adhesive selection through fabrication-to-installation workflow integration. Their technical specifications propagate through distributor networks to installation crews.
- Residential Builders:Volume-driven procurement emphasizes cost efficiency and distribution availability over performance margins.
- Renovation Specialists:Retrofit-focused operators prioritize rapid cure times and compatibility with existing substrates.
- Flooring Companies:Specialized installation firms concentrate demand for self-leveling underlayments and acoustic isolation systems.
Commercial contractors concentrate premium specification power; residential builders drive standard-grade volume.
Packaging Type:
Logistics configuration and site-scale economics determine packaging selection across project types and distribution channels.
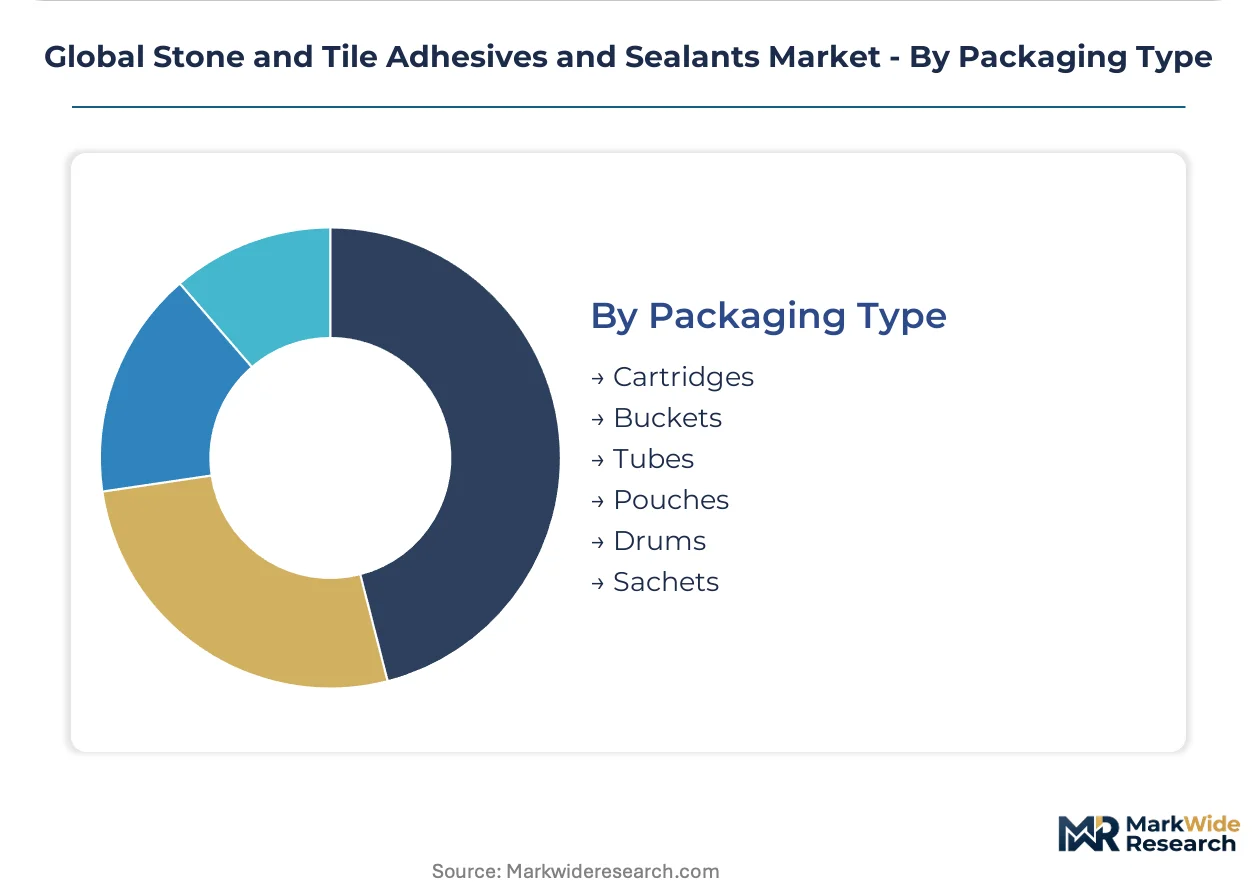
- Buckets:Bulk containers serve commercial flooring and facade projects with high-volume adhesive consumption. German construction sites favor these for two-component epoxy and polyurethane systems requiring field mixing.
- Cartridges:Standardized 300-600ml formats dominate sealant application for movement joints and perimeter sealing. Professional installers across Australian commercial construction specify these for silicone and polyurethane sealant deployment.
- Tubes:Squeeze formats target consumer DIY and small-scale repair applications.
- Pouches:Flexible packaging reduces shipping cube for polymer-modified cementitious compounds in emerging markets.
- Drums:Industrial-scale containers serve manufacturing and prefabrication operations.
- Sachets:Single-use portions address developing market affordability constraints and waste reduction requirements.
Buckets anchor commercial project economics; cartridges dominate sealant application precision.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyurethane feedstock concentration in Northeast Asian petrochemical corridors shapes raw material flows for adhesive formulators worldwide. European REACH compliance costs and Indian PLI scheme subsidies are redrawing regional manufacturing footprints. Climate exposure severity and substrate material evolution drive specification divergence across construction markets.
United States
Facade bonding specifications for rainscreen assemblies and commercial flooring retrofits drive reactive resin consumption. EPA VOC emission limits for architectural coatings tighten formulation compliance burdens nationwide. Miami and Phoenix construction corridors concentrate demand for thermal-cycling-resistant exterior cladding systems.
Germany
Engineered stone fabrication in North Rhine-Westphalia and commercial flooring renovation in Bavaria sustain polyurethane hybrid adoption. ECHA substance restrictions under REACH force reformulation away from certain isocyanate chemistries toward water-dispersed alternatives. The Stuttgart industrial cluster anchors testing and certification infrastructure for CE-marked construction chemicals.
China
GB standard evolution for tile adhesives and dual carbon goals reshape domestic formulation requirements. Evolving MIIT industrial policy accelerates consolidation among polymer-modified cementitious compound manufacturers. The Yangtze River Delta cement production corridor faces energy-intensity pressures elevating base material costs.
India
PLI scheme support for construction chemical manufacturing accelerates domestic capacity buildout for polymer-modified systems. BIS certification requirements for tile adhesives extend commercialization timelines for imported formulations. Gujarat and Maharashtra industrial zones concentrate new adhesive blending and packaging operations serving South Asian project demand.
Italy
Sintered stone slab fabricators in Emilia-Romagna and Veneto propagate technical specifications through European distributor networks. EU Green Deal carbon-footprint disclosure rules pressure raw material sourcing transparency across supply chains. The Sassuolo ceramic district drives adhesive performance requirements for large-format porcelain installation.
Global Stone and Tile Adhesives and Sealants Market Competitive Landscape
Specialist adhesive formulators and diversified construction chemical conglomerates split the market across performance tiers. Three archetypes dominate: epoxy-focused wet-area specialists, polyurethane hybrid innovators, and polymer-modified cementitious volume players. Competitive moves concentrate on certified installer channel development and bio-based raw material partnerships.
Within the specialist tier, MAPEI S.p.A. and LATICRETE International, Inc. exemplify technical-education-driven specification anchoring. ARDEX GmbH occupies a position among German-engineered system providers emphasizing substrate preparation integration. These three represent distinct geographic anchoring strategies—Italian global training infrastructure, American swimming pool and facade specialization, and German precision flooring systems.
| Leading Market Players |
|---|
| Bostik S.A.S. |
| ParexGroup SA |
| MAPEI S.p.A. |
| Henkel AG & Co. KGaA |
| Fosroc International Limited |
| ARDEX GmbH |
| LATICRETE International, Inc. |
| H.B. Fuller Company |
| Sika AG |
| Others |
Supply & Pricing Matrix
Isocyanate input volatility in Northeast Asian petrochemical corridors determines both the pricing tier spreads between epoxy and polyurethane formulations and the regional distribution of blending capacity. REACH substance restrictions and BIS certification timelines further compress margin structures for formulators serving multi-jurisdiction specifications.
Pricing Analysis
EPA VOC emission limits dictate the pricing tier structure for architectural coating-grade adhesives in the United States. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked facade systems from residential-grade latex compounds. Pricing pressure stems from cement price escalation in European clinker production. Residential builders exhibit highest price sensitivity; commercial contractors with certified installer networks accept performance premiums.
Supply Chain Analysis
MDI and TDI feedstock production concentrates in China, South Korea, and Japan. Polyurethane adhesive formulators draw from this Northeast Asian petrochemical base while cementitious compound producers source clinker from India and European kiln operations. Single-source vulnerability runs through isocyanate supply concentration. Distribution runs through certified installer networks and construction chemical distributors serving commercial contracting channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Trained applicator scarcity for reactive resin systems creates a bottleneck that constrains project velocity and anchors specification loyalty to manufacturers with technical education infrastructure.
For Market Incumbents: Pre-empt bio-based polyol scale-up partnerships ahead of EU Green Deal carbon-footprint disclosure mandates. Anchor specification loyalty through expanded certified installer programs in facade bonding and swimming pool segments. Backward integration into regional cement grinding capacity mitigates clinker cost volatility in European operations. For New Entrants and Emerging Players: Build out water-dispersed polyurethane capacity targeting Indian PLI scheme subsidies for domestic construction chemical manufacturing. Gujarat and Maharashtra industrial zones offer penetrable white space for polymer-modified cementitious compound blending. Technical partnership with Italian sintered stone fabricators provides specification entry channel. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized epoxy formulators with wet-area certification depth. Long-term viability hinges on regulatory compliance infrastructure spanning REACH, EPA VOC, and BIS frameworks. Acquisition targets with hybrid polyurethane-cementitious R&D pipelines warrant priority attention. Watch ECHA candidate list expansions as inflection signal for forced reformulation cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Installer Channel Development | MAPEI's global training infrastructure demonstrates how technical education anchors commercial contractor specification loyalty. |
| Bio-Based Polyol Partnership | Formulators exploiting bio-polyol feedstocks position ahead of EU Green Deal carbon-footprint disclosure mandates. |
| Regional Blending Capacity Expansion | PLI scheme support in Gujarat and Maharashtra accelerates domestic capacity for polymer-modified cementitious compounds. |
| Hybrid Chemistry R&D Investment | German and Dutch commercial flooring contractors specify polyurethane-cementitious systems for engineered stone substrate accommodation. |
| Multi-Jurisdiction Certification Investment | Products requiring simultaneous BIS, CE marking, and EPA VOC compliance face extended commercialization timelines without dedicated regulatory infrastructure. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across commercial contracting, stone fabrication, and construction chemical manufacturing domains. Primary interviews captured specification dynamics from facade bonding specialists, swimming pool installers, and flooring contractors in Germany, the United States, and India. Secondary validation drew from ECHA substance restriction updates, EPA VOC emission databases, BIS certification registries, and customs trade data for MDI and TDI flows. Bottom-up volume estimates triangulated against top-down construction spending allocation models.
Calibration against historical adhesive consumption patterns and construction output indices anchored projection parameters across the analysis window. Segmentation modeling incorporated chemistry type, application environment, end-user procurement sophistication, and packaging configuration dimensions. CAGRs derived from regression analysis of construction chemical intensity trends and substrate material evolution patterns. Clinker production cost curves and isocyanate supply concentration metrics informed input cost sensitivity layers.
Sensitivities concentrate around REACH substance restriction timeline acceleration, PLI scheme subsidy modifications, and cement price volatility in European energy markets. Forecasts reflect assumptions regarding certified installer program penetration rates and engineered stone substrate adoption curves. Cross-checking against national construction output statistics and construction chemical trade flow data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Asia-Pacific Epoxy Curing Agents Market
Adhesives & Sealants
Metal Glue Market
Adhesives & Sealants
Flock Binder Market
Adhesives & Sealants
Hydrophobic Pore-Blocking Agents for Waterproof Concrete Market
Adhesives & Sealants
France Sealants Market
Adhesives & Sealants
Europe Reactive Adhesives Market
Adhesives & Sealants
Vietnam Construction Chemicals Market
Adhesives & Sealants
Floor Adhesive Market
Adhesives & Sealants
Semiconductor Packaging Adhesives Market
Adhesives & Sealants
Acetate Silicone Sealant Market
Adhesives & Sealants
Acrylic Glue Market
Adhesives & Sealants
Asia-Pacific Waterborne Adhesives Market
Adhesives & Sealants
Global Sealants Market
Adhesives & Sealants
Co-Polymer Sealants Market
Adhesives & Sealants
Global Hybrid Adhesives and Sealants Market
Adhesives & Sealants
Curing Adhesives Market