
 Construction Repair and Rehabilitation Chemicals Market | 2026-2036
Construction Repair and Rehabilitation Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Repair and Rehabilitation Chemicals Market Insights
Skilled applicator shortages across certified concrete repair crews is unwinding project timelines and pushing contractors toward pre-formulated, site-ready systems. Sika AG leverages its global training academy network to lock in specification loyalty among municipal engineers. MAPEI S.p.A. anchors Southern European demand through specialized grout and anchoring product lines tailored to heritage structure constraints.
Construction repair and rehabilitation chemicals encompass polymer-modified cementitious systems, epoxy-based bonding agents, polyurethane sealants, and silane-siloxane protective treatments formulated to restore structural integrity and extend service life of deteriorated concrete, masonry, and steel substrates. These materials typically achieve compressive strengths exceeding 40 MPa within 24 hours and bond to saturated surfaces through hydrophobic polymer interpenetration. Adhesives and grouts command the deepest specification entrenchment in seismic retrofit and structural strengthening, where engineering liability drives premium product selection. Waterproofing coatings represent the fastest-growing application segment as building envelope regulations tighten and basement leakage claims escalate insurance costs for commercial property portfolios.
German regulators enforce DIN 18533 for waterproofing systems, while the UAE's MOHAP mandates material safety data disclosure for imported chemical construction products. Japan's METI coordinates JIS standard updates for earthquake-resistant repair materials following revised seismic zone classifications. Contractors, project managers, and architects must track evolving national certification requirements to avoid specification disqualification on publicly tendered infrastructure rehabilitation.
Market Dynamics
Skilled applicator shortages across certified concrete repair crews are compressing project timelines and forcing contractors toward pre-formulated, site-ready systems that reduce field-mixing complexity.
Growth Catalysts
- Seismic retrofit mandates:Japan's METI coordinates JIS standard updates for earthquake-resistant repair materials following revised seismic zone classifications, accelerating specification of structural adhesives.
- DIN 18533 enforcement:German regulators mandate waterproofing system compliance, redirecting specification authority toward certified material producers with documented performance data.
- Coastal chloride exposure:Megacities facing combined saltwater corrosion and structural aging are expanding procurement of silane-siloxane protective treatments for marine infrastructure.
Market Restraints
- Epoxy resin price volatility:Petrochemical feedstock fluctuations create margin pressure for manufacturers of polymer-modified cementitious systems and bonding agents.
- Specialized applicator concentration:Certification requirements limit qualified contractor pools in Germany, Japan, and UAE, creating installation bottlenecks on large infrastructure tenders.
- Extended cure-time limitations:Traditional cementitious repairs requiring 28-day strength development face displacement by rapid-setting alternatives on time-critical highway contracts.
Strategic Opportunities
- Heritage structure specialization:Southern European conservation frameworks favor grout and anchoring systems formulated for reversible, low-impact intervention on historic masonry.
- Building envelope tightening:Basement leakage insurance cost escalation in commercial property portfolios is expanding specification of crystalline waterproofing admixtures.
- Pre-formulated system channels:Direct-to-contractor distribution of site-ready repair kits bypasses traditional specifier intermediaries, capturing margin and reducing field failure risk.
Industry Challenges
- Certification timeline compression:Municipal engineers in Germany and UAE increasingly require DIN or MOHAP-compliant documentation prior to tender submission, extending pre-qualification cycles.
- Multi-substrate compatibility testing:Structural strengthening projects demand validated performance across saturated concrete, corroded steel, and carbon fiber reinforcement interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Repair and Rehabilitation Chemicals Market |
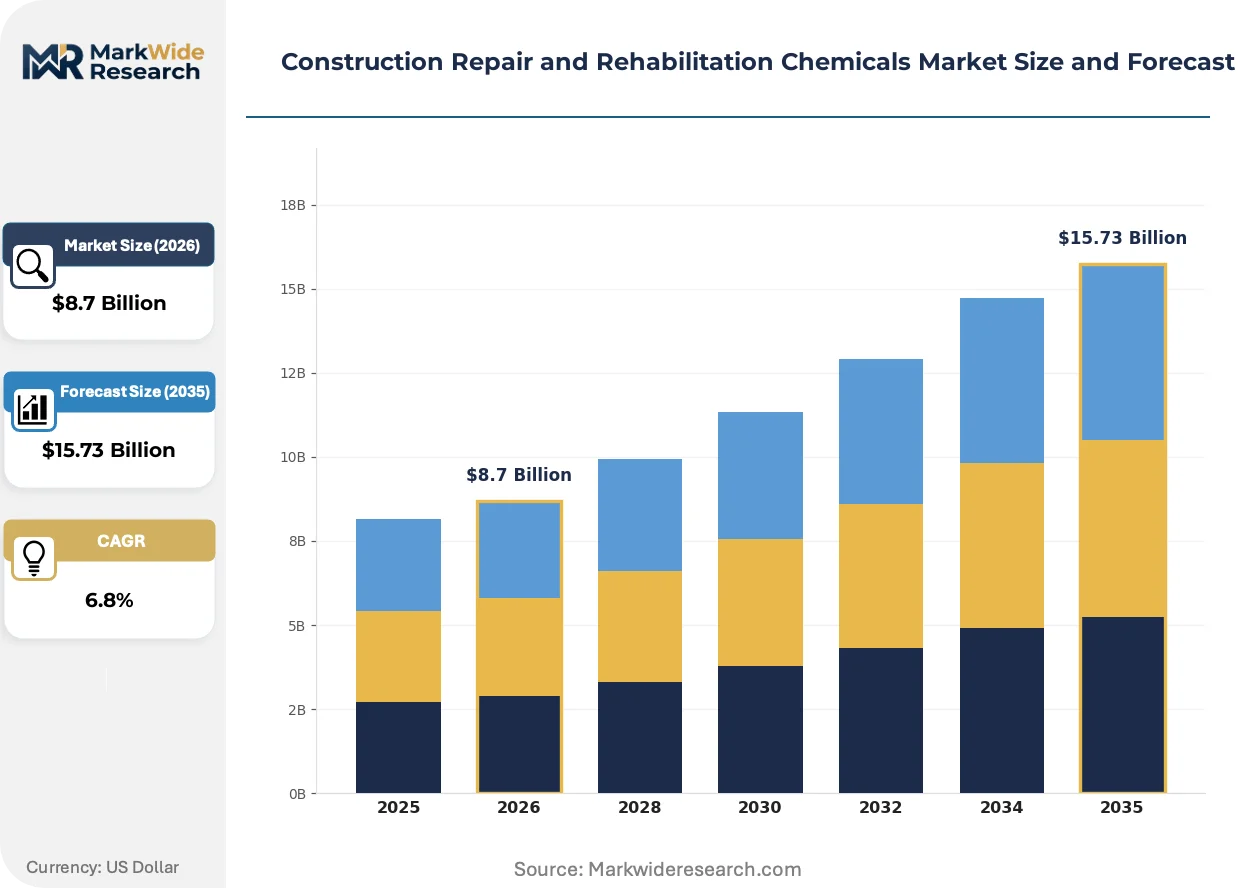
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adhesives, Sealants, Coatings, Grouts Application: Concrete Repair, Surface Treatment, Waterproofing, Chemical Resistance End User: Contractors, Project Managers, Architects, Municipalities Form: Liquid, Paste, Powder, Gel |
| Companies Covered | Sika AG, MAPEI S.p.A., Saint-Gobain, RPM International Inc., Ardex Group, Fosroc Inc., MBCC Group, MC-Bauchemie, Remmers Gruppe AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Repair and Rehabilitation Chemicals Market Trends and Innovations
Formulation chemistry and application logistics are converging to reduce field variability, with manufacturers embedding quality assurance into packaged systems rather than relying on site-mixing precision.
Hybrid polymer-cement composites combining acrylic or vinyl acetate copolymers with Portland cement are displacing conventional epoxy injection systems in non-structural crack repair. Municipal maintenance crews across coastal US states and Japanese prefectures are adopting these materials for their tolerance of damp substrates and reduced VOC exposure. The shift is compressing demand for two-component epoxy cartridges in below-grade waterproofing while expanding the addressable market to semi-skilled applicators.
REACH registration requirements for construction chemical imports are forcing non-European manufacturers to establish EU-based formulation or toll-manufacturing arrangements. The industrial consequence is a consolidation of supply relationships around established registrants with full substance data dossiers. Waterproofing coating producers serving German commercial construction are responding by localizing blending operations to maintain specification access.
Asset owners in commercial property and municipal infrastructure are unbundling material procurement from installation services, creating direct purchasing relationships with certified producers. This pattern is displacing traditional distributor-specifier channels in UAE and Japanese metropolitan markets. Facility managers with portfolio-scale maintenance obligations are consolidating annual chemical volumes to capture tiered pricing and technical support commitments.
Construction Repair and Rehabilitation Chemicals Market Segmentation
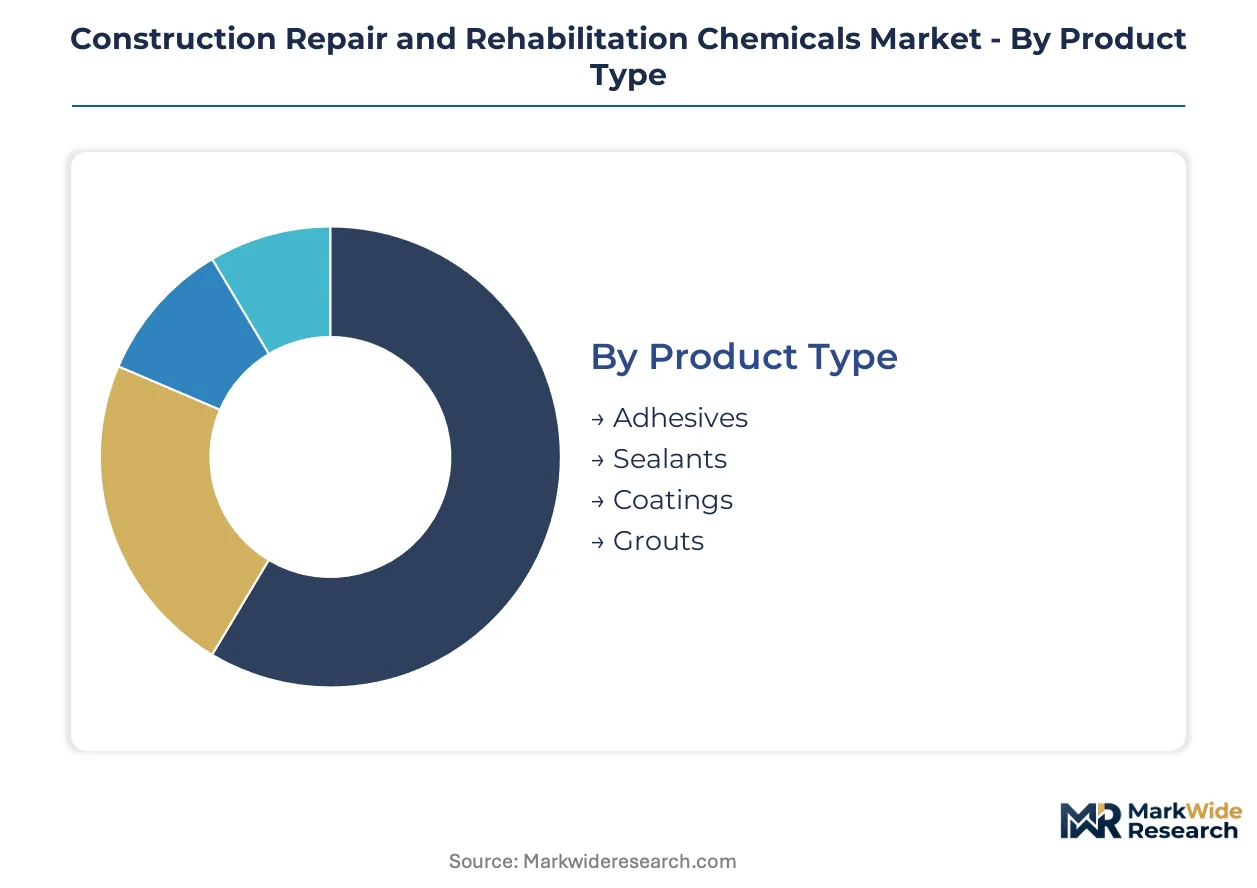
Segmentation in construction repair chemicals reveals how specification authority flows from regulatory compliance through to application method. Product chemistry, physical form, and procurement channel each create distinct margin structures and competitive barriers.
Product Type:
German DIN 18533 enforcement and UAE MOHAP disclosure mandates favor certified producers with documented performance data across adhesive and coating categories.
- Adhesives:Epoxy and polyurethane structural bonding agents achieve compressive strengths exceeding 40 MPa within 24 hours. Seismic retrofit obligations in Japan and chloride-induced corrosion in coastal US states are concentrating procurement of these systems for carbon fiber reinforcement anchoring.
- Coatings:Crystalline waterproofing and silane-siloxane protective treatments penetrate concrete pores to block moisture ingress. Basement leakage insurance cost escalation in commercial property portfolios across Germany and the UAE is accelerating specification of crystalline admixtures for below-grade structures.
- Sealants:Polyurethane and polysulfide joint sealants accommodate structural movement while maintaining watertight integrity.
- Grouts:Cementitious and epoxy injection grouts fill voids and restore load transfer in deteriorated masonry.
Established volume favors adhesives; emerging adoption favors coatings.
Application:
Customer procurement patterns differentiate by project urgency and liability exposure, with waterproofing commanding premium pricing in high-insurance-cost jurisdictions.
- Waterproofing:Building envelope tightening and basement leakage claims are expanding crystalline admixture and membrane system demand. German commercial construction and UAE municipal infrastructure tenders now require certified waterproofing documentation prior to bid submission.
- Concrete Repair:Polymer-modified cementitious systems and epoxy injection materials restore structural integrity to deteriorated substrates. Highway bridge maintenance crews across Japan and coastal US states are adopting rapid-setting alternatives to compress cure timelines on critical infrastructure.
- Surface Treatment:Silane-siloxane and acrylic protective coatings extend service life through hydrophobic barrier formation.
- Chemical Resistance:Epoxy and vinyl ester systems protect industrial concrete from acid and solvent exposure.
Waterproofing applications are climbing the fastest as building codes tighten; concrete repair retains the deepest specification entrenchment in seismic zones.
End User:
Asset ownership structure determines whether procurement flows through traditional specifier channels or direct manufacturer relationships.
- Contractors:Skilled applicator shortages are pushing certified concrete repair crews toward pre-formulated, site-ready systems that reduce field-mixing complexity. Municipal infrastructure tenders in Germany and Japan now require documented applicator certification.
- Municipalities:Portfolio-scale maintenance obligations are consolidating annual chemical volumes to capture tiered pricing and technical support commitments. Japanese prefectures and UAE metropolitan authorities are unbundling material procurement from installation services.
- Project Managers:Timeline compression on highway contracts favors rapid-setting repair materials over traditional 28-day cure systems.
- Architects:Heritage conservation frameworks in Southern Europe drive specification of reversible, low-impact intervention materials.
Direct purchasing favors municipalities; traditional channel dependence favors contractors.
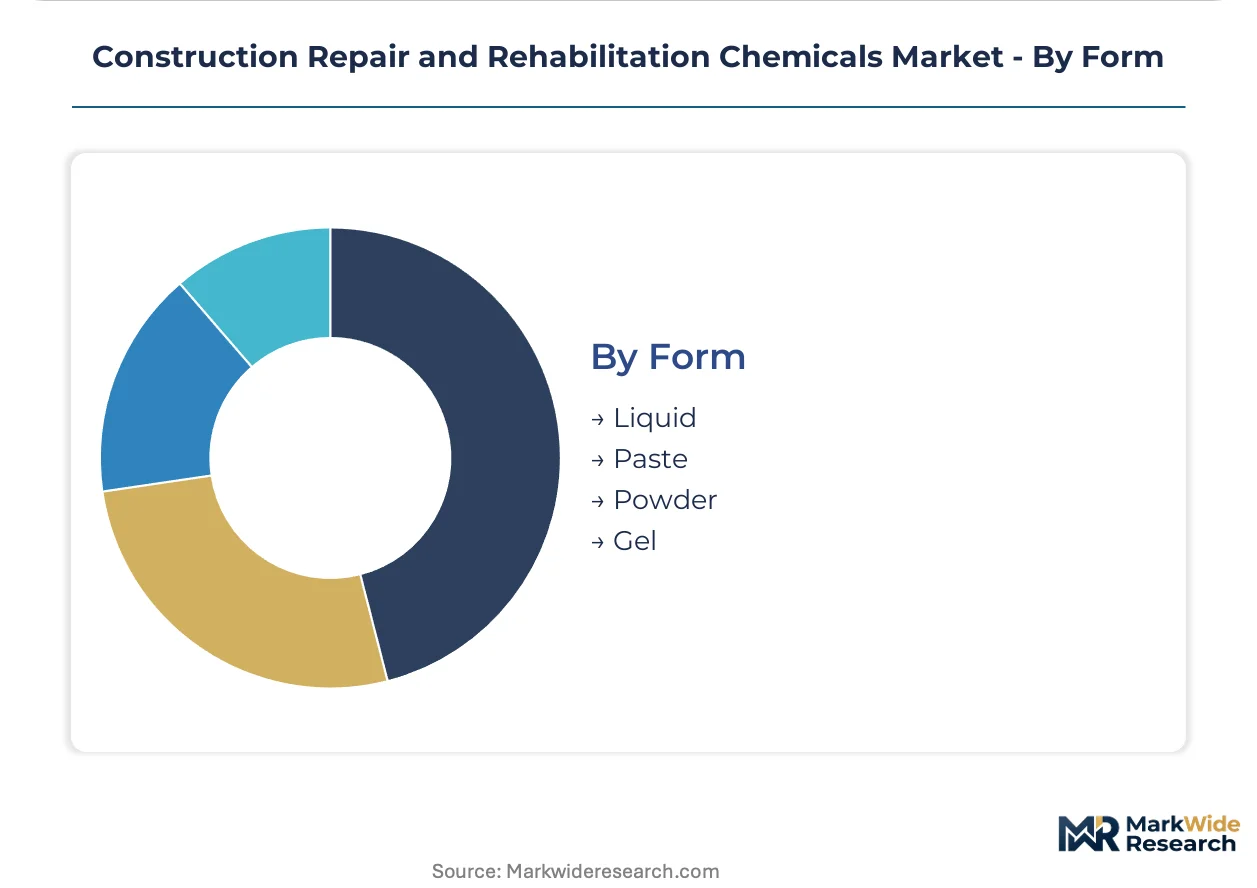
Form:
Physical state determines logistics cost, shelf stability, and field mixing precision requirements.
- Liquid:Two-component epoxy and polyurethane systems penetrate cracks and saturate carbon fiber reinforcement. Japanese maintenance crews favor liquid injection systems for their tolerance of damp substrates.
- Powder:Polymer-modified cementitious repair mortars achieve high early strength through controlled hydration. German contractors specify powder systems for heritage structure constraints requiring reversible intervention.
- Paste:Pre-thickened epoxy and acrylic compounds enable vertical and overhead application without sag.
- Gel:Thixotropic injection grouts maintain position in wide cracks and voids.
Powder dominates volume in heritage-sensitive markets; liquid forms are gaining share fastest in rapid-turnaround infrastructure maintenance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan consume construction repair chemicals through specification-heavy municipal procurement, while UAE demand concentrates in rapid-build commercial envelopes where waterproofing insurance premiums drive material selection.
Germany
DIN 18533 enforcement redirects specification authority toward certified waterproofing producers with full performance documentation. Heritage structure constraints across Bavaria and Baden-Württemberg favor reversible grout systems for historic masonry intervention. The Rhine-Ruhr industrial corridor generates concentrated demand for concrete repair systems on aging manufacturing infrastructure.
Japan
METI-coordinated JIS standard updates for earthquake-resistant materials accelerate structural adhesive procurement following seismic zone reclassifications. Prefecture-level infrastructure maintenance programs in Kanto and Kansai consolidate annual chemical volumes for tiered pricing. The Tokyo-Osaka corridor dominates rapid-setting repair material adoption on time-critical highway contracts.
United States
Coastal state highway departments expand silane-siloxane procurement for chloride-induced corrosion protection on marine-exposed bridges. EPA and state-level VOC regulations compress demand for high-emission epoxy systems in below-grade applications. The California-Texas-Florida triangle leads hybrid polymer-cement composite adoption among municipal maintenance crews.
United Arab Emirates
MOHAP-mandated material safety data disclosure for imported chemicals filters specification toward documented producers. Basement leakage insurance cost escalation in Dubai and Abu Dhabi commercial portfolios accelerates crystalline waterproofing admixture demand. The Dubai-Sharjah construction corridor concentrates site-ready system distribution bypassing traditional specifier channels.
China
Dual carbon goals and GB standard updates for building energy efficiency tighten envelope performance requirements in coastal megacities. Provincial infrastructure investment programs in Yangtze River Delta and Pearl River Delta regions scale polymer-modified cementitious system procurement. Shanghai and Shenzhen municipal authorities consolidate repair chemical volumes for portfolio-scale maintenance obligations.
Construction Repair and Rehabilitation Chemicals Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding specification loyalty through certified training networks and documented compliance archives. The middle tier fragments across regional formulators with heritage conservation or rapid-setting specialization. Two strategic archetypes dominate: full-system integrators bundling material with technical support, and chemistry-focused specialists anchoring niche performance segments. Competitive moves concentrate on pre-formulated site-ready kit development and direct-to-contractor distribution channel capture.
Within the full-system integrator tier, Sika AG and Saint-Gobain exemplify the training-academy model that locks municipal engineer specification loyalty through certified applicator pipelines. MAPEI S.p.A. occupies a specialist position anchored in Southern European heritage structure constraints. Among diversified chemical conglomerates, RPM International Inc. represents the portfolio-breadth archetype spanning multiple construction chemical categories.
| Leading Market Players |
|---|
| Sika AG |
| MAPEI S.p.A. |
| Saint-Gobain |
| RPM International Inc. |
| Ardex Group |
| Fosroc Inc. |
| MBCC Group |
| MC-Bauchemie |
| Remmers Gruppe AG |
| Others |
Pricing and Supply Chain Analysis
DIN 18533 certification gates both supplier qualification and price tiering in German waterproofing markets, compressing uncertified producers into commodity pricing while documented performers capture specification premiums across municipal infrastructure tenders.
Pricing Analysis
Project-based contracting dominates structural adhesive procurement, with seismic retrofit mandates in Japan and chloride-exposed coastal infrastructure driving premium pricing for rapid-cure systems. Price differentiation separates DIN-compliant certified grades from standard formulations, while volume-scale tiering rewards portfolio-holding municipalities. Cost compression in epoxy resin feedstocks is intensifying margin pressure on polymer-modified cementitious producers. Contractors represent the most price-sensitive segment; asset owners with insurance-exposure concentrate procurement on performance tiers regardless of unit cost.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for silane-siloxane raw material shipments, particularly affecting UAE and German formulators dependent on Asian petrochemical intermediates. Supply concentrates in Germany, Japan, and China for specialty polymer production, with epoxy resin synthesis anchored in Northeast Asian chemical corridors. Raw material dependencies span bisphenol-A, aliphatic amine hardeners, and vinyl acetate copolymers. Single-source vulnerability in certified additive supply creates qualification bottlenecks. Distribution runs through direct manufacturer relationships with municipal procurement authorities, displacing traditional specifier intermediaries in Japanese and UAE metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification authority is consolidating around training-academy platforms that lock municipal engineer loyalty through certified applicator pipelines, creating ecosystem interoperability between material producers and installation capacity.
For Market Incumbents: Compound specification entrenchment by expanding DIN and JIS certification archives ahead of tender documentation deadlines. Deepen backward integration into epoxy resin synthesis to offset petrochemical feedstock volatility threatening polymer-modified cementitious margins. Channel control through direct-to-contractor site-ready kit distribution defends position against regional formulators bypassing specifier intermediaries.
For New Entrants and Emerging Players: Differentiate on heritage-structure specialization for Southern European conservation frameworks requiring reversible, low-impact intervention materials. Target crystalline waterproofing admixtures in UAE commercial property portfolios facing basement leakage insurance cost escalation. Penetrate through pre-formulated system channels offering site-ready repair kits with embedded quality assurance.
For Investors and Strategic Acquirers: REACH registration deadlines for construction chemical imports reshape the acquisition landscape, favoring targets with full substance data dossiers over non-European manufacturers facing toll-manufacturing establishment costs. Long-term viability centers on certified training network assets and documented compliance archives. Watch JIS standard update implementation timelines as inflection indicators for structural adhesive specification velocity in Japanese seismic zones.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epoxy Resin Synthesis | Captive supply of bisphenol-A intermediates insulates margin from petrochemical volatility. |
| Training Academy Network Expansion | Sika AG's certified applicator pipeline locks municipal engineer specification loyalty across German infrastructure tenders. |
| Pre-formulated Site-Ready Kit Development | Site-ready repair systems reduce field-mixing complexity for certified concrete repair crews facing skilled applicator shortages. |
| REACH Registration Completion | Full substance data dossiers maintain specification access for waterproofing coating producers serving German commercial construction. |
| Direct-to-Contractor Distribution Channel | Bypassing traditional specifier intermediaries captures margin and reduces field failure risk in UAE and Japanese metropolitan markets. |
Research Methodology
Desk research of customs trade data, DIN and JIS standard documentation, and municipal procurement tender records preceded structured interviews with certified concrete repair contractors, municipal infrastructure procurement officers, waterproofing specification engineers, and polymer-modified cementitious R&D directors. Primary fieldwork across German, Japanese, and UAE metropolitan markets combined with secondary validation from SEC filings of diversified chemical conglomerates and ECHA REACH registration databases. Bottom-up volume estimates triangulated against top-down construction chemical spending projections.
Variance decomposition across product chemistry, application method, and procurement channel dimensions structured the analytical framework over the projection horizon. Modeled segmentation spans adhesive and coating categories, waterproofing versus concrete repair applications, contractor versus municipality end users, and liquid versus powder physical forms. CAGRs derived from regression analysis against infrastructure investment cycles and regulatory implementation timelines. Industry-specific forecast inputs incorporated seismic zone reclassification schedules and building envelope code adoption curves.
The analysis sits within stated boundaries; outcomes outside continued DIN 18533 enforcement, METI-coordinated JIS updates, and MOHAP disclosure mandate implementation would require recalibration. Forecasts reflect assumptions regarding skilled applicator certification expansion, petrochemical feedstock stability, and heritage conservation framework continuity. Practitioners should keep alternative scenarios live as REACH registration deadlines, seismic zone reclassifications, and insurance premium escalation patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
United States Adhesives Market
Adhesives & Sealants
Dispersion Adhesives Market
Adhesives & Sealants
United Kingdom Hot-Melt Adhesives Market
Adhesives & Sealants
Global Adhesion Promoter Market
Adhesives & Sealants
Melamine Formaldehyde (MF) Market
Adhesives & Sealants
Epoxy Glue Market
Adhesives & Sealants
North America Automotive Adhesives and Sealants Market
Adhesives & Sealants
Urethane Adhesives Market
Adhesives & Sealants
South America Reactive Adhesives Market
Adhesives & Sealants
Hot Melt Adhesives Market
Adhesives & Sealants
Timber Laminating Adhesives Market
Adhesives & Sealants
Asia-Pacific Flock Adhesives Market
Adhesives & Sealants
Dental Impression Tray Adhesives Market
Adhesives & Sealants
Tile and Stone Adhesive Market
Adhesives & Sealants
Leather Glue Market
Adhesives & Sealants
Middle East and Africa Bone Glue Market