
 Wood to Metal Glue Market | 2026-2036
Wood to Metal Glue Market Size, Share, and Industry Trends Forecast 2026-2036
Wood to Metal Glue Market Analytics
Premium epoxy formulations for aerospace-grade bonding is decoupling from commodity polyurethane lines serving construction bulk buyers. Henkel leverages its European R&D footprint to sustain high-performance certification pipelines. H.B. Fuller Company anchors North American supply through direct contractor channels. Sika AG dominates transportation-sector specifications with dedicated application-engineering teams.
Wood to metal glue comprises structural adhesives engineered to bond lignocellulosic substrates to ferrous and non-ferrous metals, typically formulated with silane coupling agents and toughening modifiers to manage differential thermal expansion coefficients. These adhesives serve primary industrial purposes in furniture lamination, vehicle panel assembly, and architectural cladding systems where mechanical fasteners compromise aesthetics or corrosion resistance. Epoxy resin systems command the highest margin pools due to their shear strength and chemical resistance in automotive underhood applications. Polyurethane adhesives lead volume in furniture manufacturing, where flexible cure profiles accommodate varied production line speeds. Cyanoacrylate instant adhesives occupy a narrow but defensible niche in repair shop environments demanding rapid fixture times.
EPA regulates VOC emissions from adhesive formulations under 40 CFR Part 59, while REACH restricts hazardous substance content in European industrial bonding products. OSHA workplace exposure limits further shape formulation choices and application equipment investments in US manufacturing facilities. ISO 4587 lap-shear testing standards govern performance claims and cross-border procurement specifications. Stakeholders must monitor evolving dual carbon goals in China and the EU Green Deal's embodied-carbon accounting rules, as these frameworks increasingly influence material selection criteria in export-oriented furniture and automotive supply chains.
Market Dynamics
REACH compliance in Europe is tightening VOC thresholds for industrial bonding agents, forcing reformulation investments across epoxy and polyurethane product lines while concentrating procurement among certified suppliers.
Growth Catalysts
- Dual carbon goals in China:MEE enforcement of embodied-carbon accounting in export-oriented furniture supply chains is mandating low-VOC adhesive specifications for Guangdong OEM clusters.
- ISO 4587 certification pipelines:Automotive underhood applications require lap-shear validated epoxy systems, creating specification lock-in for shear-strength grade formulations.
- Mixed-material furniture designs:German manufacturers are expanding adhesive procurement for metal-wood laminations that mechanical fasteners cannot achieve without corrosion compromise.
Market Restraints
- Petrochemical feedstock volatility:Epoxy resin and isocyanate precursor costs fluctuate with crude derivatives, compressing margin pools for commodity polyurethane lines.
- Guangdong supply concentration:OEM furniture production clusters dominate regional consumption, creating geographic dependency risk for adhesive distributors.
- Cyanoacrylate substitution ceiling:Instant adhesives face performance barriers in structural load-bearing applications, limiting penetration beyond repair shop environments.
Strategic Opportunities
- EU Green Deal procurement criteria:Embodied-carbon accounting rules create specification advantages for bio-based toughening modifiers in architectural cladding systems.
- Application-engineering services:Transportation-sector buyers are contracting dedicated technical teams for cure-profile optimization on varied production line speeds.
- Silane coupling agent convergence:Hybrid formulations combining ferrous and non-ferrous metal compatibility are opening specification gaps in vehicle panel assembly.
Industry Challenges
- Thermal expansion coefficient matching:Formulators face technical complexity managing differential contraction between lignocellulosic substrates and metal alloys across temperature cycles.
- OSHA compliance capex:US manufacturing facilities must invest in application equipment and ventilation systems to meet workplace exposure limits for isocyanate-containing products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wood to Metal Glue Market |
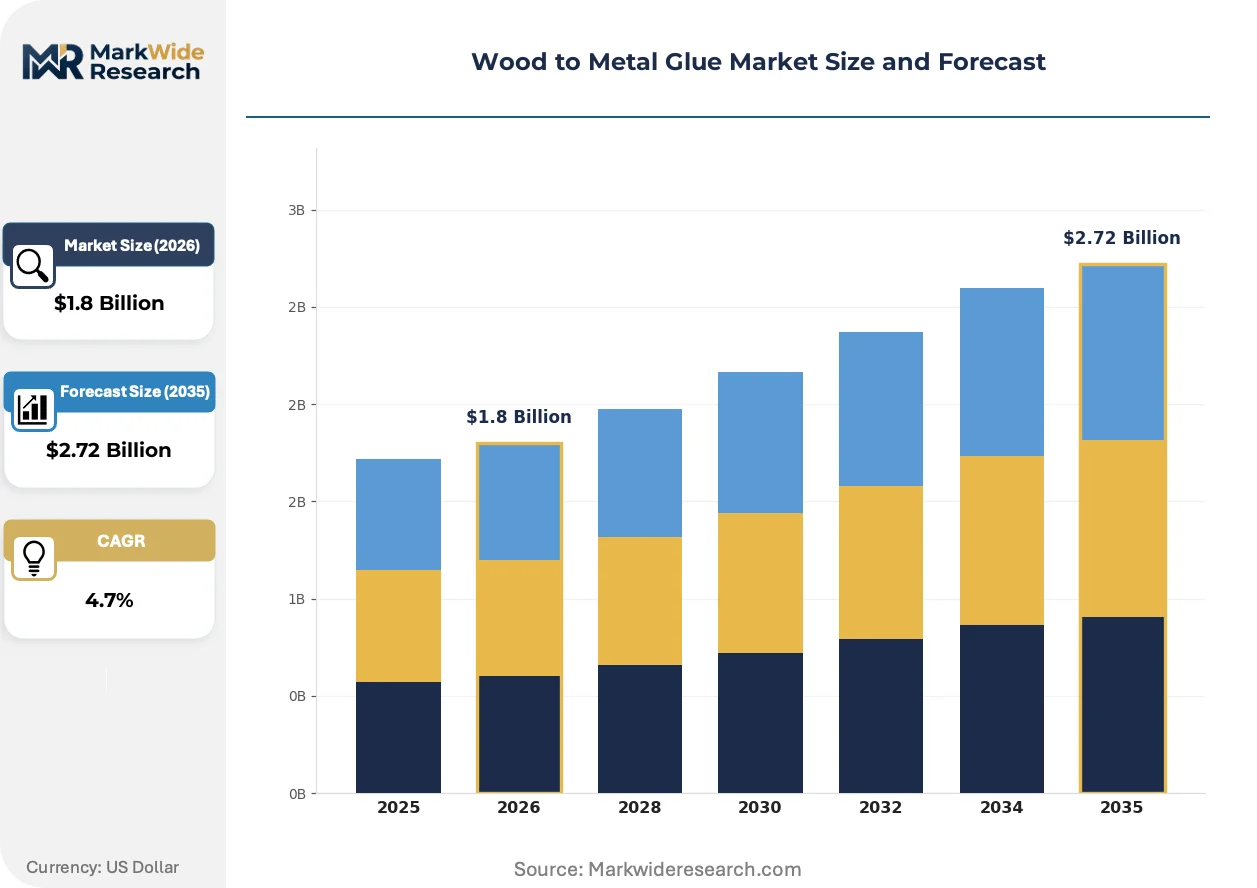
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Furniture, Construction, Automotive, Aerospace Product Type: Epoxy, Polyurethane, Silicone, Cyanoacrylate End User: Manufacturers, DIY Enthusiasts, Contractors, Repair Shops Distribution Channel: Online Retail, Specialty Stores, Wholesale, Direct Sales |
| Companies Covered | Henkel, H.B. Fuller Company, Sika AG, Arkema Group, 3M, Jowat SE, Akzo Nobel N.V., Dow, Loctite, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wood to Metal Glue Market Evolving Landscape
Adhesive formulation is pivoting toward performance-tier specialization, with aerospace-grade certification requirements diverging from construction bulk specifications. Technical service capabilities now determine competitive positioning.
Bio-based toughening modifiers are absorbing R&D investment from European and North American formulators seeking to meet EU Green Deal embodied-carbon thresholds. Furniture manufacturers in Germany and automotive tier suppliers in the US are piloting these systems for mixed-material laminations. The technology is absorbing margin pressure from petrochemical volatility while opening premium pricing tiers for certified low-carbon formulations.
EPA enforcement under 40 CFR Part 59 is intensifying VOC monitoring at US adhesive manufacturing facilities and downstream application sites. Industrial bonding product imports face heightened documentation requirements at ports of entry. Construction-sector distributors are consolidating supplier relationships to reduce compliance verification overhead.
Buyer concentration among direct contractor channels is compressing distributor margins in North American construction applications. Large-scale furniture OEMs in China's Guangdong province are negotiating volume-based specification lock-ins with certified adhesive suppliers. This pattern is most visible in automotive underhood and architectural cladding procurement, where application-engineering support has become a bundled service rather than a separate fee.
Wood to Metal Glue Market Segmentation
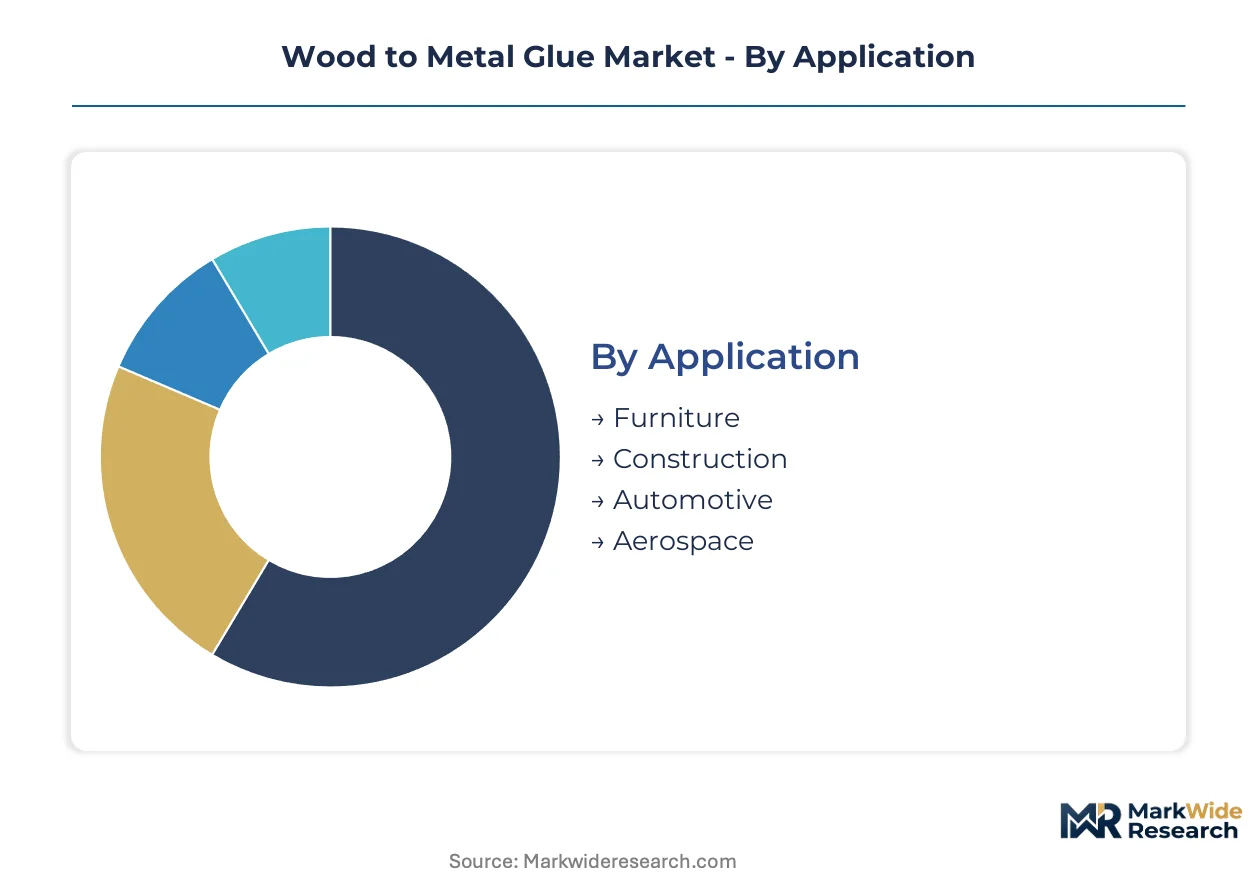
Wood to metal glue procurement patterns diverge sharply across application contexts, with aerospace-grade specifications demanding certified batch traceability while construction bulk buyers prioritize volume pricing. Understanding these segment boundaries clarifies where formulation investments concentrate and which channels capture margin.
Application:
Supply concentration in Guangdong's OEM furniture clusters shapes procurement volumes, while automotive underhood specifications concentrate among tier suppliers with ISO 4587 validation capabilities.
- Furniture:Polyurethane adhesives dominate lamination workflows for metal-wood designs where mechanical fasteners compromise corrosion resistance. German manufacturers are expanding adhesive procurement for mixed-material aesthetics that fasteners cannot achieve.
- Construction:Bulk epoxy and polyurethane lines serve architectural cladding systems requiring weathering resistance. EPA 40 CFR Part 59 compliance costs are compressing distributor margins and consolidating supplier relationships.
- Automotive:Lap-shear validated epoxy systems lock in specification for underhood panel bonding where thermal cycling demands differential expansion management.
- Aerospace:Premium formulations with toughening modifiers and silane coupling agents command certification pipelines that commodity lines cannot access.
Today's leader: Furniture. Tomorrow's challenger: Aerospace.
Product Type:
Cost tier stratification separates aerospace-grade certification investments from construction commodity volumes, with bio-based modifiers absorbing R&D spend at the premium end.
- Epoxy:Two-part systems with silane coupling agents deliver highest shear strength for structural load-bearing applications. Automotive tier suppliers in the US are piloting bio-based toughening modifiers to meet EU Green Deal embodied-carbon thresholds for export-bound cladding systems.
- Polyurethane:Flexible cure profiles accommodate varied production line speeds in furniture manufacturing, though isocyanate precursor costs fluctuate with crude derivatives.
- Silicone:Thermal stability suits expansion-joint applications in architectural systems where temperature cycling exceeds epoxy tolerance ranges.
- Cyanoacrylate:Instant fixture times occupy repair shop environments, yet performance barriers in structural applications limit penetration beyond niche maintenance workflows.
Volume concentrates in Polyurethane. Margin accumulates in Epoxy.
End User:
Customer type determines technical service intensity, with manufacturers contracting application-engineering teams while DIY channels drive unit volume through retail placement.
- Manufacturers:OEM furniture producers in China's Guangdong province negotiate volume-based specification lock-ins with certified adhesive suppliers, bundling engineering support into procurement contracts.
- DIY Enthusiasts:Online retail channels and specialty stores serve home repair projects with consumer-packaged instant adhesives and small-volume epoxy kits.
- Contractors:Direct sales relationships dominate North American construction procurement, where large-scale projects require batch documentation for EPA compliance verification.
- Repair Shops:Cyanoacrylate demand concentrates here for rapid fixture requirements, though structural bonding needs push some shops toward two-part epoxy systems.
Procurement gravity sits with Manufacturers. Channel expansion targets DIY.
Distribution Channel:
Geography shapes channel viability, with direct sales penetrating industrial clusters while online retail captures dispersed DIY demand.
- Online Retail:E-commerce platforms serve DIY enthusiasts and small contractors with consumer-packaged formulations, though bulk industrial buyers require technical documentation that digital channels struggle to provide.
- Specialty Stores:Staff expertise supports product selection for professional contractors navigating VOC compliance and substrate compatibility questions.
- Wholesale:Construction-sector distributors consolidate supplier relationships to reduce EPA 40 CFR Part 59 verification overhead across multiple product lines.
- Direct Sales:Application-engineering bundling dominates automotive and aerospace procurement, where cure-profile optimization requires dedicated technical teams.
Consolidation favors Wholesale. Differentiation requires Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized adhesive chemists and application engineers concentrate in Germany, China, and the United States, anchoring formulation development and technical service delivery for wood-to-metal bonding systems.
United States
Automotive tier suppliers in Michigan and Ohio drive epoxy procurement for underhood panel bonding where thermal cycling demands differential expansion management. EPA enforces VOC emissions under 40 CFR Part 59, forcing reformulation investments at manufacturing facilities and downstream application sites. Construction distributors in the Southeast consolidate supplier relationships to reduce compliance verification overhead across multiple product lines.
Germany
Furniture manufacturers in Baden-Württemberg and North Rhine-Westphalia expand adhesive procurement for mixed-material designs that mechanical fasteners cannot achieve without corrosion compromise. REACH compliance tightens VOC thresholds for industrial bonding agents, concentrating procurement among certified suppliers with ECHA-registered formulations. The Stuttgart automotive cluster sustains specification lock-in for lap-shear validated epoxy systems.
China
OEM furniture production clusters in Guangdong province dominate regional consumption, with OEMs negotiating volume-based specification lock-ins for low-VOC formulations. MEE enforces dual carbon goals through embodied-carbon accounting in export-oriented supply chains. Shenzhen and Dongguan manufacturers pilot bio-based toughening modifiers to meet EU Green Deal thresholds for European-bound shipments.
Japan
Precision equipment manufacturers in the Kanto region demand high-shear-strength formulations for compact electronic enclosures combining wood veneer with aluminum frames. METI guidelines on chemical substance management shape formulation disclosure requirements for industrial adhesives. The Nagoya automotive corridor sustains demand for silane-coupled epoxy systems in vehicle interior panel assembly.
India
Furniture exporters in Gujarat and Tamil Nadu adopt wood-to-metal adhesives for premium office furniture targeting European and North American markets. BIS certification requirements for industrial chemicals create entry barriers for uncertified imports. The Morbi ceramics cluster diversifies into metal-wood furniture components, absorbing polyurethane adhesive volumes for production line flexibility.
Wood to Metal Glue Market Competitive Landscape
Capital-heavy producers compete with asset-light designers in the adhesive formulation space, with integrated resin manufacturers controlling precursor supply while specialized compounders focus on application engineering. The market structure concentrates among three to five multinational suppliers with full certification pipelines, surrounded by regional specialists serving single-country procurement. Two strategic archetypes dominate: vertically integrated chemical conglomerates with captive epoxy and polyurethane resin production, and independent formulators bundling technical service with niche certifications. Competitive moves center on M&A to secure bio-based modifier technology and geographic expansion through direct sales teams in Guangdong and Stuttgart industrial clusters.
Among European-based chemical conglomerates, Henkel AG exemplifies the integrated archetype with REACH-registered formulation pipelines spanning construction and automotive specifications. H.B. Fuller Company anchors North American supply through direct contractor channels, representing the independent formulator model with bundled application-engineering services. Sika AG occupies a position within the transportation-sector specialist tier, with dedicated technical teams for cure-profile optimization. These three companies illustrate how certification depth and technical service intensity separate premium-tier suppliers from commodity volume players.
| Leading Market Players |
|---|
| Henkel |
| H.B. Fuller Company |
| Sika AG |
| Arkema Group |
| 3M |
| Jowat SE |
| Akzo Nobel N.V. |
| Dow |
| Loctite |
| Others |
Value Network & Pricing Analysis
Captive resin production among European chemical conglomerates anchors both supply security and premium pricing power for aerospace-grade epoxy formulations, while outsourced polyurethane precursor sourcing exposes commodity lines to petrochemical volatility. This integration divergence concentrates margin capture among REACH-registered suppliers with in-house silane coupling agent capabilities.
Pricing Analysis
The bundled-vs-unbundled service split separates automotive and aerospace procurement, where application-engineering teams command specification lock-in, from construction bulk buying driven by spot-price sensitivity. Three-tier pricing structure across aerospace-certified, industrial-grade, and commodity construction tiers reflects ISO 4587 validation depth and batch traceability investment. Pricing pressure stems from isocyanate precursor cost fluctuations compressing polyurethane margin pools. DIY enthusiasts and small contractors exhibit highest price sensitivity, while German furniture OEMs and US automotive tier suppliers prioritize performance certification over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany, China, and the United States feed hub-and-spoke patterns serving Guangdong furniture clusters, Stuttgart automotive corridors, and Michigan manufacturing belts. Epoxy resin and isocyanate precursor supply rests on petrochemical feedstock flows from integrated refineries in the US Gulf Coast and Rotterdam Antwerp hub. Single-source vulnerability concentrates in silane coupling agent production, where three multinational suppliers control specialty chemical output. Distribution runs through direct sales teams for industrial OEMs and wholesale consolidators for construction-sector procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wood to metal glue market reads as a late-cycle quality story, with specification lock-in for lap-shear validated epoxy systems displacing price-driven procurement in automotive underhood and architectural cladding applications.
For Market Incumbents: Lock in certification pipeline depth by acquiring bio-based toughening modifier technology from European specialty chemical developers. Defend margin position through backward integration into silane coupling agent production, reducing exposure to single-source supply risk. Prioritize application-engineering team expansion in Guangdong and Stuttgart industrial clusters where OEM procurement bundles technical service into long-term contracts.
For New Entrants and Emerging Players: Capture white-space in repair shop cyanoacrylate substitution by developing rapid-cure two-part epoxy systems with structural load-bearing performance. Target India's Gujarat and Tamil Nadu furniture export corridors, where BIS certification barriers filter out uncertified imports but create entry paths for compliant formulations. Lead with online retail channel penetration for DIY enthusiasts seeking consumer-packaged metal-wood bonding solutions.
For Investors and Strategic Acquirers: Roll-up economics work for independent formulators with bundled technical service capabilities because buyer concentration among direct contractor channels compresses distributor margins and rewards scale. Five-to-ten year viability hinges on embodied-carbon accounting rule adoption across EU and Chinese export supply chains. Watch MEE enforcement intensity in Guangdong as the signal for low-VOC specification acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silane Coupling Agents | Captive supply of critical adhesion promoters reduces single-source dependency for aerospace-grade formulations. |
| Bio-Based Toughening Modifier Acquisition | EU Green Deal embodied-carbon thresholds create premium pricing tiers for certified low-carbon epoxy systems. |
| Application-Engineering Team Expansion | Direct technical support in Stuttgart and Guangdong clusters secures specification lock-in with automotive and furniture OEMs. |
| REACH-Registered Formulation Pipeline Investment | ECHA compliance concentration forces procurement consolidation among certified suppliers with validated batch traceability. |
| Online Retail Channel Development | E-commerce penetration captures dispersed DIY demand for consumer-packaged instant adhesives and small-volume epoxy kits. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with adhesive formulators, procurement leads at German furniture OEMs, automotive tier supplier engineers, and construction-sector distributors with secondary validation against customs trade data, REACH registration databases, SEC 10-K filings, and ISO certification records. Bottom-up demand modeling across application segments triangulated with top-down chemical industry production estimates.
Segment-weighting approaches distributed volume and value across furniture, construction, automotive, and aerospace applications, with further stratification by epoxy, polyurethane, silicone, and cyanoacrylate product types. CAGRs derived from historical consumption patterns and projected specification shifts across the analysis window incorporated petrochemical feedstock cost trajectories, regulatory enforcement timelines for EPA 40 CFR Part 59 and REACH VOC thresholds, and OEM procurement consolidation trends in Guangdong province.
Feedstock price volatility, regulatory enforcement intensity variation, and OEM procurement consolidation pace are the dominant revision risks that could alter trajectory assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Paper-Backing Abrasive Adhesive Discs Market
Adhesives & Sealants
Europe Adhesives and Sealants Market
Adhesives & Sealants
Global Medical Adhesives and Sealants Market
Adhesives & Sealants
Structural Sealants Market
Adhesives & Sealants
Instant Adhesive Market
Adhesives & Sealants
Global Adhesives Market
Adhesives & Sealants
Dural Sealant Market
Adhesives & Sealants
Saudi Arabia Sealants Market
Adhesives & Sealants
Global Stone and Tile Adhesives and Sealants Market
Adhesives & Sealants
Middle East and Africa Adhesives Market
Adhesives & Sealants
Global Acrylic Adhesives Market
Adhesives & Sealants
Asia-Pacific Adhesives Market
Adhesives & Sealants
Malaysia Sealants Market
Adhesives & Sealants
Water Based Adhesive Market
Adhesives & Sealants
Urea Formaldehyde Concrete Market
Adhesives & Sealants
Europe Cyanoacrylate Adhesives Market