
 Japan Adhesives Market | 2026-2036
Japan Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Adhesives Market Foresight
Buyer concentration among Japanese automotive tier suppliers is restructuring procurement relationships across the adhesives value chain. 3M leverages its fluoropolymer adhesive portfolio to sustain dominance in powertrain thermal management applications. Henkel competes through localized reactive polyurethane production serving Toyota and Honda assembly networks. DIC Corporation anchors its position with water-based acrylic systems tailored to Japanese electronics OEM specifications.
Adhesives are non-metallic substances formulated from synthetic polymers, tackifying resins, and curing agents that develop structural or semi-structural bonds through chemical crosslinking, mechanical interlocking, or diffusion mechanisms at substrate interfaces, typically achieving lap shear strengths from 1 to 40 MPa depending on chemistry and cure conditions. Their primary industrial purpose is to replace mechanical fasteners and welding in assemblies where weight reduction, stress distribution, or dissimilar-material joining is required. Epoxy formulations occupy the highest-value niche in Japanese semiconductor packaging and aerospace bonding due to their thermal stability and dielectric properties. Water-based acrylics lead volume in construction and consumer applications where METI VOC regulations have accelerated solvent substitution. Reactive polyurethane technology captures expanding share in automotive assembly as Japanese OEMs adopt multi-material body-in-white designs requiring flexible, crash-durable joints.
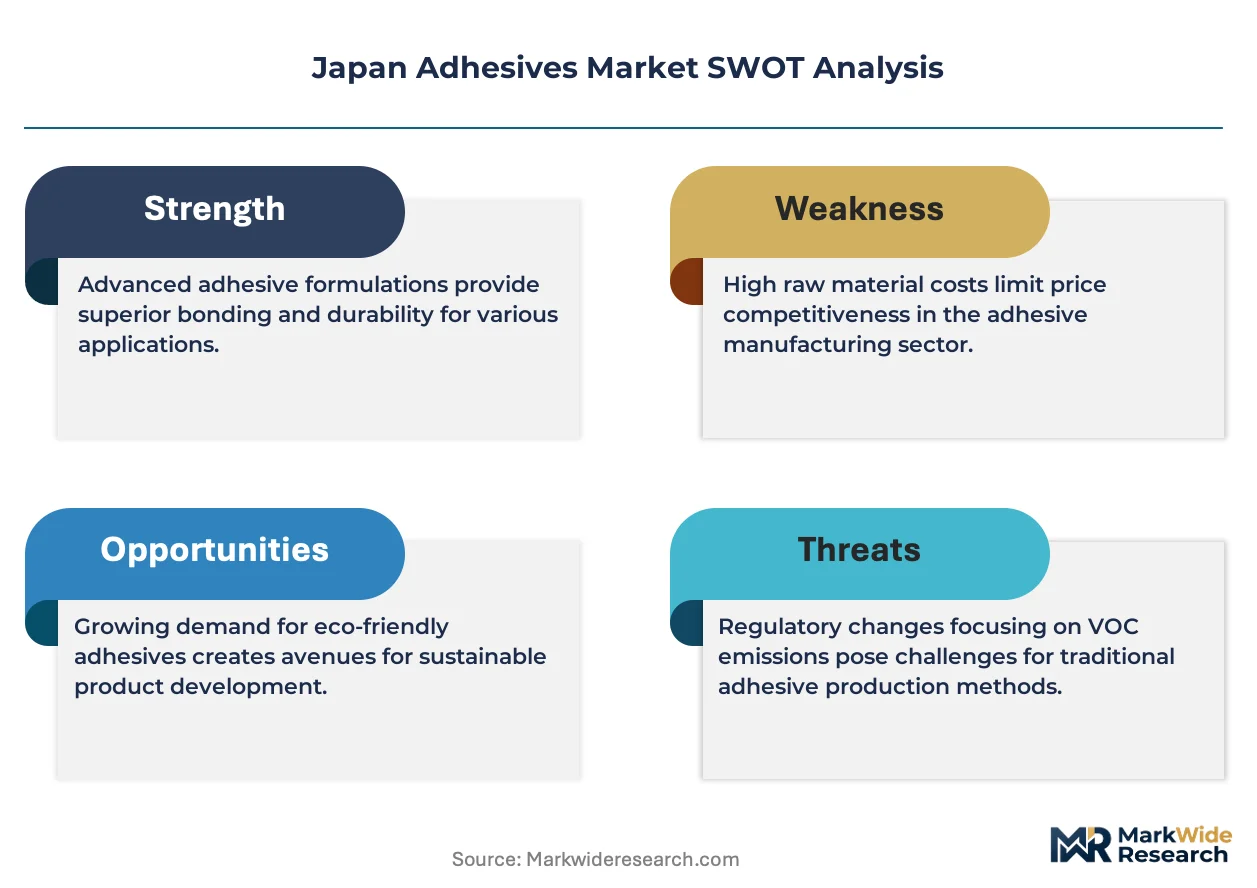
METI enforces industrial chemical reporting under the Chemical Substances Control Law, while JIS standards govern adhesive performance testing for construction and transportation applications, creating dual compliance burdens that favor domestic laboratories and certified product portfolios. The PMDA and Ministry of Health, Labour and Welfare regulate medical-grade adhesives through biocompatibility protocols that limit market entry for uncertified imports. Stakeholders must monitor evolving carbon accounting rules under Japan's GX League framework, which will soon require Scope 3 disclosure from adhesive suppliers serving export-oriented manufacturers.
Market Dynamics
Automotive lightweighting mandates from Japanese OEMs are compressing bonding cycle times and elevating thermal performance specifications across the supplier base. Tier-1 procurement teams now disqualify adhesive portfolios lacking JIS-certified crash-durability data.
Growth Catalysts
- Multi-material vehicle architectures:Honda and Toyota assembly lines now specify flexible polyurethane joints for aluminum-steel hybrid body-in-white structures, expanding reactive adhesive consumption per vehicle.
- METI carbon neutrality roadmap:Manufacturing sector emission targets are accelerating solvent-to-water-based formulation conversions in construction and consumer applications.
- Osaka-Kyoto electronics cluster:Precision component assemblers in the Kansai corridor are consolidating procurement around high-purity epoxy systems for semiconductor packaging applications.
Market Restraints
- Petrochemical feedstock volatility:Polyol and isocyanate input costs fluctuate with naphtha cracking margins, compressing formulation margins for domestic polyurethane producers.
- Fluoropolymer supply concentration:Powertrain thermal management adhesives depend on imported fluorinated resin precursors subject to export control scrutiny.
- JIS certification timelines:Construction adhesive approval cycles extend 18-24 months, freezing product portfolios for suppliers lacking accredited testing laboratory relationships.
Strategic Opportunities
- Medical-grade skin adhesives:PMDA biocompatibility pathways for wearable device attachment present white space for hydrogel and silicone formulations.
- GX League Scope 3 disclosure:Carbon accounting mandates for export-oriented manufacturers create service revenue streams for suppliers offering lifecycle-assessed product portfolios.
- Recyclable bonding systems:Convergence of debond-on-demand chemistry with circular economy targets enables disassembly-friendly automotive and electronics applications.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in reactive polyurethane catalyst systems and epoxy curing kinetics concentrates among retiring cohorts at legacy chemical manufacturers.
- Legacy equipment retrofit costs:Water-based acrylic transitions require oven humidity controls and spray booth modifications that strain mid-tier coating applicator capital budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Adhesives Market |
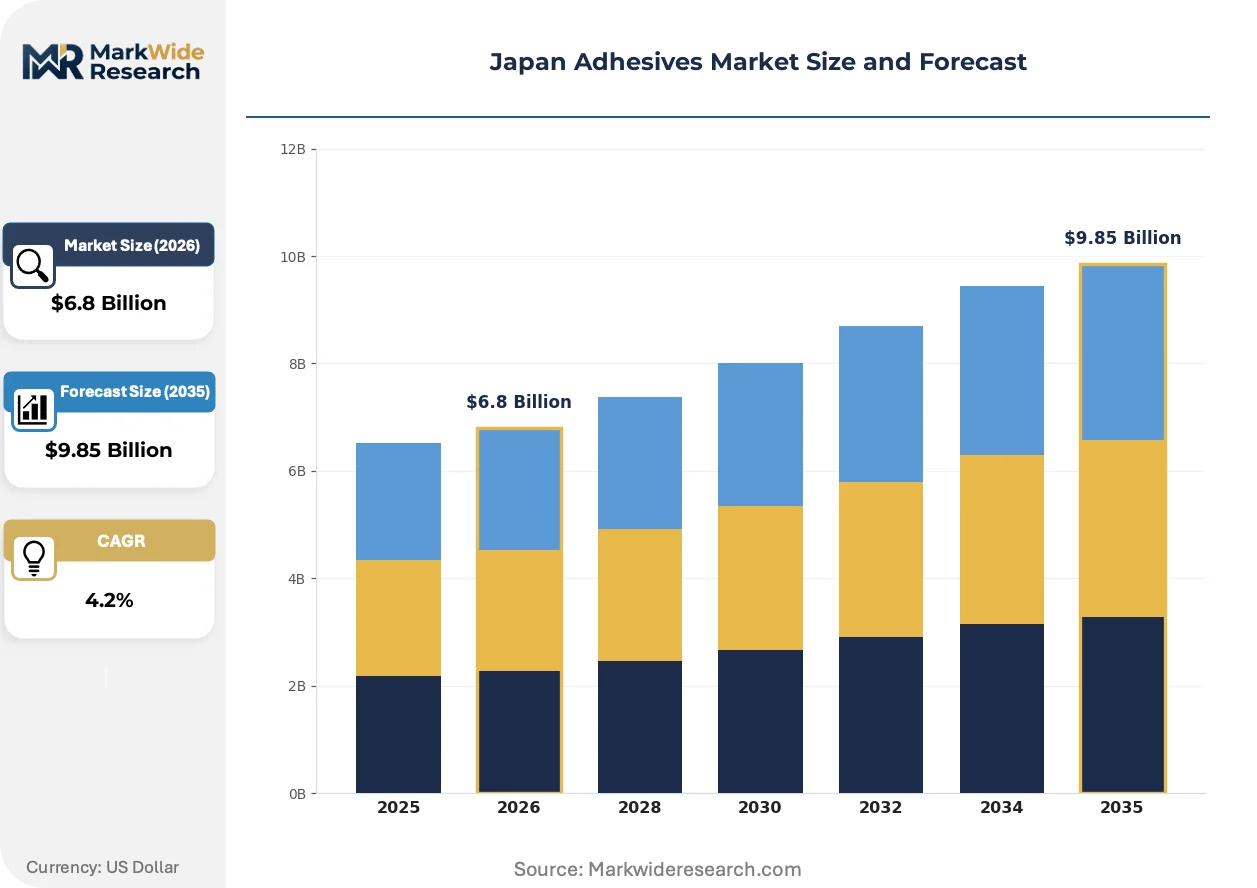
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.85 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Silicone, Acrylic End User: Automotive, Construction, Electronics, Packaging Application: Bonding, Sealing, Coating, Assembly Technology: Water-Based, Solvent-Based, Hot Melt, Reactive |
| Companies Covered | Sika, H.B. Fuller, 3M, DIC Corporation, Mitsui Chemicals, Aica Kogyo, Toyochem, Sumitomo Chemical, Henkel, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Adhesives Market Shifts & Advancements
Japanese adhesive markets are restructuring around thermal management performance, regulatory compliance automation, and compressed procurement cycles that favor pre-certified product portfolios.
Bio-based polyol feedstocks are integrating into automotive reactive polyurethane formulations to meet OEM sustainability scorecard requirements. Toyota and Honda engineering teams now specify minimum renewable content thresholds for interior assembly adhesives, forcing suppliers to requalify petroleum-derived formulations. This chemistry shift is integrating crop-derived raw materials into supply chains previously dominated by naphtha cracking outputs.
METI's Chemical Substances Control Law reporting requirements are expanding to include nano-scale additives in adhesive formulations. Domestic laboratories are building automated compliance documentation platforms to handle the 18-month pre-manufacture notification windows. Electronics assemblers in the Kanto region are most affected, as their solder-mask and die-attach adhesives frequently incorporate functionalized nanoparticles.
Consolidated tier-1 procurement is compressing supplier qualification cycles and elevating technical service expectations. Japanese automotive suppliers now demand on-site bonding process optimization within 48 hours of line stoppage, displacing traditional distributor-only relationships. This service intensity is most visible in Nagoya-area Toyota supply chain clusters, where adhesive vendors maintain resident engineers at major stamping and assembly facilities.
Japan Adhesives Market Segmentation
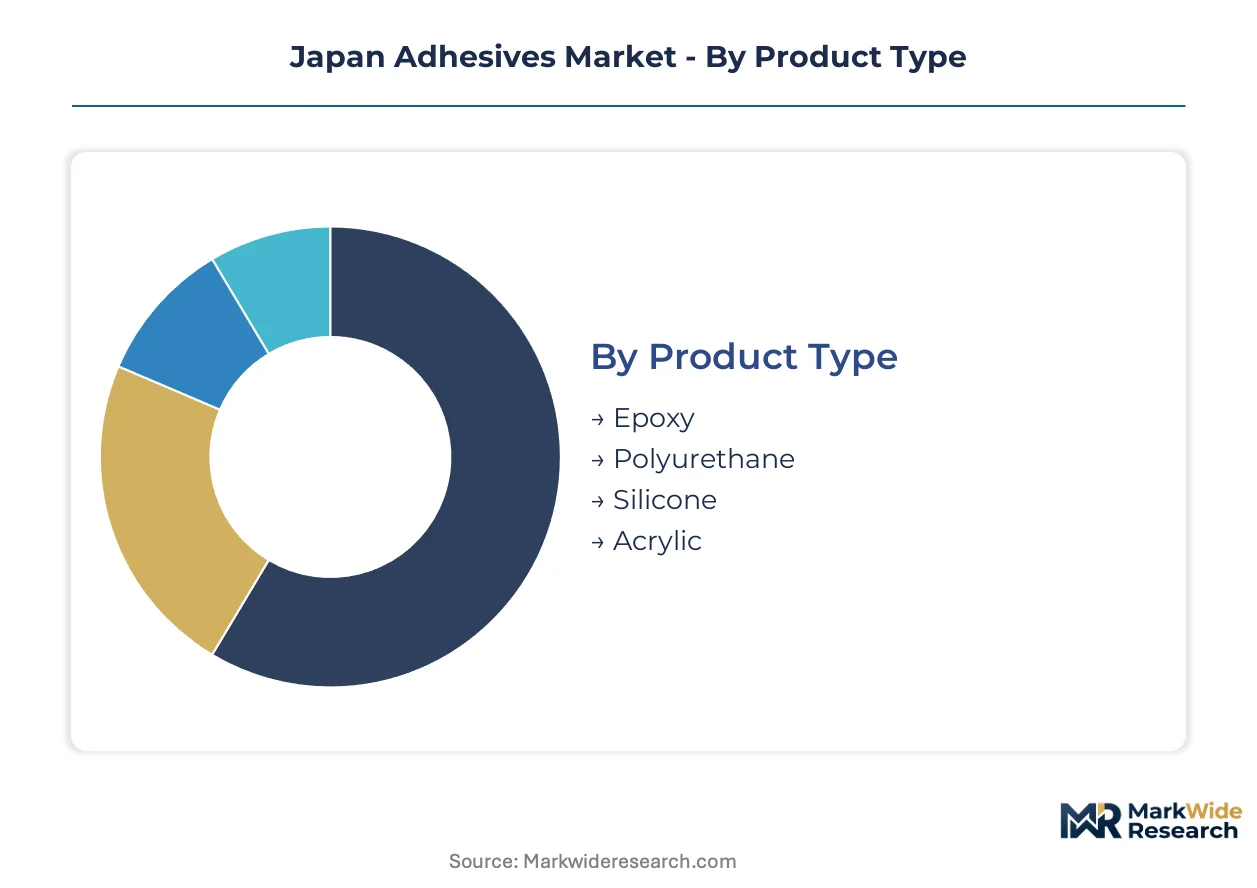
Segmentation reveals how procurement specifications diverge across Japanese industrial clusters. Automotive OEMs prioritize thermal performance and crash durability, while electronics assemblers emphasize purity and process compatibility. Understanding these divides clarifies where formulation investments yield competitive advantage.
Product Type:
Replacement cycles for legacy solvent systems are accelerating as METI emission thresholds tighten, forcing reformulation investments across all chemistry families.
- Epoxy:Two-part thermosetting systems built from bisphenol-A or novolac resins achieve glass transition temperatures exceeding 150°C. Semiconductor packaging operations in Kyoto prefecture specify these for die-attach and underfill applications where thermal cycling resistance prevents solder joint failure. METI's nano-additive reporting requirements now capture functionalized silica fillers common in these grades.
- Polyurethane:Reactive systems combining polyol and isocyanate components cure to flexible elastomers with elongation at break exceeding 200%. Toyota and Honda assembly networks in Aichi prefecture specify these for aluminum-steel hybrid body joints where crash energy absorption protects occupant compartments. Feedstock volatility in naphtha-derived polyols compresses margins for domestic producers.
- Silicone:Polydimethylsiloxane-based formulations deliver service temperatures from -60°C to 230°C with stable dielectric properties. Medical device manufacturers in Tokyo prefecture specify platinum-cured grades for wearable sensor attachment where PMDA biocompatibility certification is mandatory.
- Acrylic:Water-borne emulsions of polyacrylate copolymers achieve peel strengths of 2-5 N/mm on polar substrates. Construction contractors in Osaka prefecture specify these for interior finishing where JIS-certified low-VOC compliance enables project bidding.
Acrylic sits at the top of the volume ranking, with polyurethane climbing the fastest.
End User:
Cost tier stratification separates specification-grade procurement from commodity purchasing across Japanese industrial verticals.
- Automotive:Tier-1 suppliers demand JIS-certified crash-durability data and resident engineering support at stamping facilities. Multi-material body-in-white architectures specify reactive polyurethane for 40% of bonding points per vehicle.
- Construction:General contractors face 18-24 month JIS approval cycles that freeze product portfolios. Water-based acrylic substitution accelerates as METI carbon neutrality roadmaps tighten solvent emission thresholds for commercial building retrofits.
- Electronics:Precision assemblers in the Osaka-Kyoto corridor consolidate procurement around high-purity epoxy systems. Semiconductor packaging applications require sub-ppm ionic contamination levels and automated compliance documentation for nano-additive reporting.
- Packaging:Consumer goods manufacturers specify food-contact compliant hot melt systems for carton sealing and label application. GX League Scope 3 disclosure requirements now extend to adhesive suppliers serving export-oriented food processors.
Construction commands the largest volume position, while electronics gains share fastest on semiconductor packaging demand.
Application:
Application selection tracks directly to stress distribution requirements and disassembly needs in circular economy frameworks.
- Bonding:Structural joints replacing welds and mechanical fasteners in lightweight vehicle architectures. Lap shear specifications of 15-25 MPa qualify adhesives for chassis and suspension attachments.
- Sealing:Fluid and environmental barrier functions in powertrain and battery enclosures. Fluoropolymer-modified grades dominate thermal management applications where 150°C continuous service is required.
- Coating:Protective films and corrosion barriers on metal substrates prior to assembly. Water-based acrylic conversions require humidity-controlled cure ovens that strain mid-tier applicator capital budgets.
- Assembly:Component positioning and fixturing operations in electronics and consumer goods manufacturing. Debond-on-demand chemistry enables disassembly-friendly designs aligned with circular economy targets.
Bonding anchors volume consumption, with assembly expanding most quickly on electronics miniaturization trends.
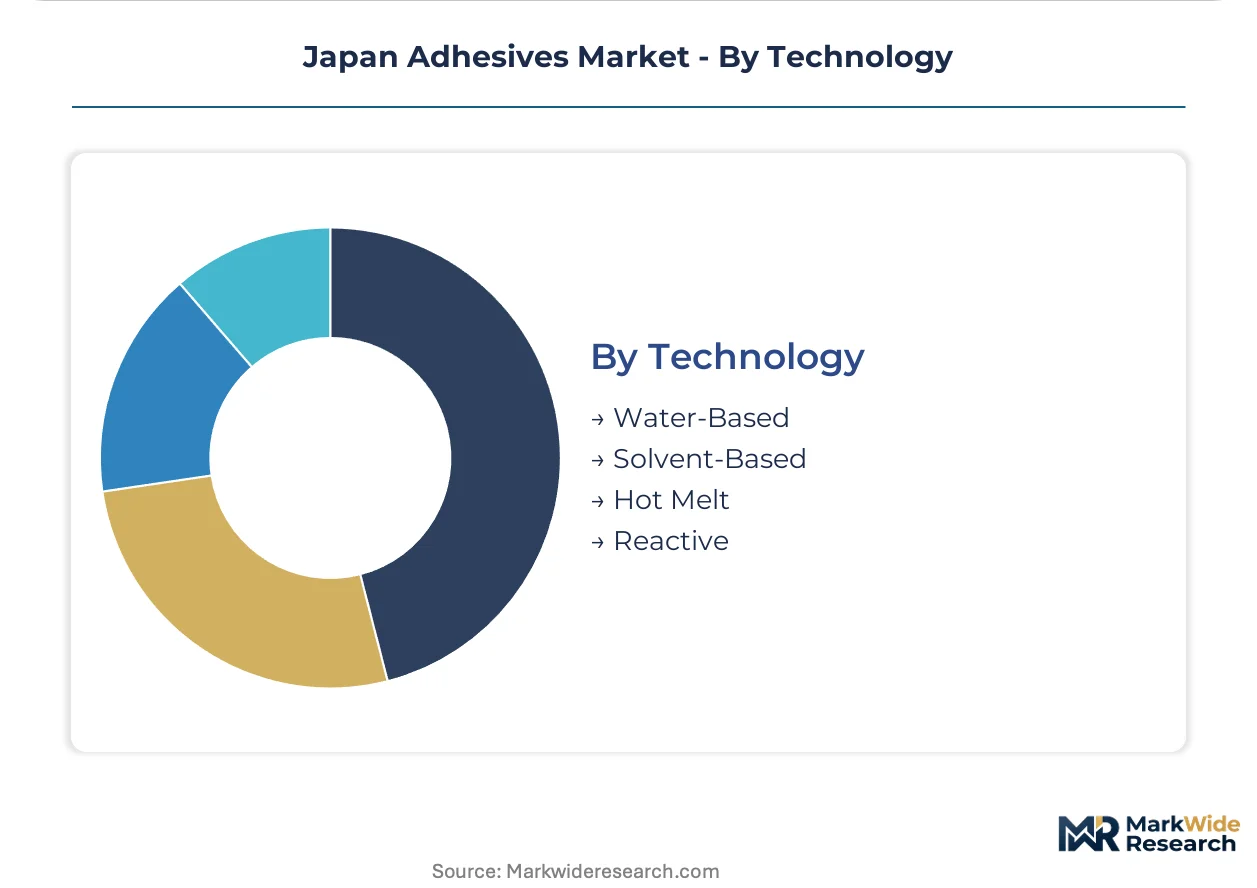
Technology:
Technology selection reflects the tension between performance requirements and regulatory compliance automation burdens.
- Water-Based:Acrylic and polyurethane dispersions with 40-60% solids content cure through moisture evaporation. METI VOC regulations have accelerated solvent substitution in construction and consumer applications where emission thresholds tightened.
- Solvent-Based:High-solids solutions of rubber and resin tackifiers deliver aggressive tack and fast green strength. Regulatory pressure confines remaining demand to specialty applications where water-borne alternatives lack adhesion to low-surface-energy substrates.
- Hot Melt:Thermoplastic EVA and polyolefin formulations applied at 150-180°C and set on cooling. Packaging lines specify these for high-speed carton sealing where instant handling strength enables line speeds exceeding 200 units per minute.
- Reactive:Two-component polyurethane and epoxy systems curing through chemical crosslinking rather than physical drying. Automotive lightweighting mandates specify these for 70% of structural bonding points in multi-material body architectures.
Water-based technology leads by volume, with reactive systems posting the steepest expansion trajectory on automotive procurement shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's adhesives market structure diverges sharply from China's volume-driven expansion, with Japanese procurement emphasizing JIS-certified performance data and resident engineering support over commodity pricing.
Kanto/Tokyo
Medical device manufacturers and electronics assemblers in Tokyo prefecture drive demand for PMDA-certified silicone and high-purity epoxy systems. METI's Chemical Substances Control Law reporting requirements capture nano-scale additives in die-attach adhesives produced here. The Yokohama-Kawasaki industrial corridor concentrates precision component bonding operations serving semiconductor packaging applications.
Kansai/Osaka
Construction contractors and consumer goods manufacturers specify water-based acrylic adhesives meeting tightened METI VOC emission thresholds. JIS certification cycles for building applications extend 18-24 months, freezing product portfolios for suppliers lacking accredited laboratory relationships. The Osaka-Kyoto corridor anchors regional consumption for electronics assembly and interior finishing applications.
Chubu/Nagoya
Toyota and Honda assembly networks specify reactive polyurethane joints for aluminum-steel hybrid body-in-white structures. Tier-1 procurement teams disqualify adhesive portfolios lacking JIS-certified crash-durability data. Nagoya-area stamping facilities demand on-site bonding process optimization within 48 hours of line stoppage.
Kyushu
Automotive component suppliers and heavy industry manufacturers consume structural epoxy and polyurethane systems for chassis and powertrain applications. Regional producers face feedstock volatility in naphtha-derived polyols that compress formulation margins. Fukuoka prefecture hosts specialized coating applicators retrofitting humidity-controlled cure ovens for water-based acrylic transitions.
Tohoku
Renewable energy equipment manufacturers and precision machinery builders specify thermal management adhesives for power electronics and battery enclosures. Fluoropolymer-modified grades dominate applications requiring 150°C continuous service. Sendai-based assemblers consolidate procurement around suppliers offering lifecycle-assessed product portfolios aligned with GX League Scope 3 disclosure requirements.
Japan Adhesives Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Japan's adhesives value chain. The market exhibits tiered concentration, with multinational chemical groups holding dominant positions in automotive and electronics segments while domestic specialists capture construction and consumer applications. Three strategic archetypes define competitive positioning: integrated petrochemical groups with captive resin supply, specialty chemical houses with JIS-certified product portfolios, and regional distributors with localized technical service capabilities. M&A activity concentrates on acquiring formulation expertise in reactive polyurethane systems, while strategic partnerships target co-development of bio-based polyol feedstocks for OEM sustainability scorecards.
Within the multinational tier, 3M and Henkel occupy positions anchored by fluoropolymer and polyurethane portfolios respectively. DIC Corporation exemplifies the domestic specialist archetype with water-based acrylic systems tailored to Japanese regulatory requirements. These three companies represent divergent competitive vectors: technology licensing from US and European parents, localized production serving Toyota and Honda networks, and indigenous formulation expertise aligned with METI compliance frameworks.
| Leading Market Players |
|---|
| Sika |
| H.B. Fuller |
| 3M |
| DIC Corporation |
| Mitsui Chemicals |
| Aica Kogyo |
| Toyochem |
| Sumitomo Chemical |
| Henkel |
| Others |
Supply & Pricing Matrix
Naphtha-derived polyol feedstock costs cascade through three distinct pricing tiers before reaching Japanese automotive OEM procurement desks. Domestic polyurethane producers absorb margin compression when cracking margins tighten, while water-based acrylic suppliers pass humidity-control retrofit costs to mid-tier construction applicators.
Pricing Analysis
Capacity additions in South Korea and China are reshaping price floors for standard-grade epoxy and acrylic formulations. Three-tier pricing structure across premium, standard, and economy levels separates JIS-certified construction adhesives from uncertified imports and commodity spot offerings. Price differentiation hinges on certification grade and resident engineering support bundled with supply contracts. Cost compression in reactive polyurethane segments is intensifying because naphtha cracking margin volatility feeds directly into polyol and isocyanate input costs. General contractors in Osaka prefecture exhibit highest price sensitivity, while Toyota and Honda tier-1 procurement teams prioritize thermal performance specifications over unit economics.
Supply Chain Analysis
Return flows of spent adhesive containers and expired formulations from electronics assemblers are creating reverse-logistics infrastructure demands in the Kanto region. Geographic supply concentrates in Japan, South Korea, and China, with fluoropolymer resin precursors drawing from specialized Japanese and US chemical manufacturers. Raw material dependencies rest on naphtha cracking outputs, imported fluorinated monomers, and bio-based polyol feedstocks from Southeast Asian agricultural processors. Single-source vulnerability in fluoropolymer thermal management grades exposes powertrain adhesive suppliers to export control disruptions. Distribution runs through certified chemical distributors with accredited laboratory relationships for JIS compliance documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japanese adhesive markets reward geographic-arbitrage strategies that exploit the cost differential between domestic JIS certification timelines and faster regulatory pathways in South Korea for electronics-grade formulations.
For Market Incumbents: Cement dominance in reactive polyurethane supply to Toyota and Honda networks by acquiring captive polyol production capacity in Chubu prefecture. Invest in automated METI compliance documentation platforms before nano-additive reporting deadlines tighten. Defend against emerging bio-based feedstock specialists by locking long-term renewable content contracts with agricultural processors. For New Entrants and Emerging Players: Enter via PMDA-certified medical-grade silicone segments where incumbent concentration remains lowest and biocompatibility certification barriers filter commodity competition. Target wearable device attachment applications in Tokyo prefecture where hydrogel formulation expertise concentrates among retiring cohorts at legacy manufacturers. Pursue co-development partnerships with Osaka-based electronics assemblers seeking debond-on-demand chemistry for circular economy compliance. For Investors and Strategic Acquirers: Consolidation pressure builds where formulation chemist expertise concentrates among retiring professionals at legacy chemical houses. Five-to-ten year viability favors specialists with JIS-certified portfolios and resident engineering capabilities at Nagoya-area stamping facilities. Acquisition targets should display captive laboratory relationships and automated compliance platforms. Monitor METI carbon neutrality roadmap implementation for solvent-to-water-based conversion inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyol Production | Captive supply of naphtha-derived feedstocks insulates margins from cracking volatility in Chubu manufacturing clusters. |
| JIS Certification Laboratory Acquisition | Accredited testing relationships compress 18-24 month construction adhesive approval cycles for Osaka contractors. |
| Bio-Based Polyol Feedstock Partnership | Southeast Asian agricultural sourcing meets Toyota and Honda renewable content thresholds for interior assembly adhesives. |
| Automated METI Compliance Platform | Software documentation handles 18-month nano-additive pre-manufacture notification windows for Kanto electronics assemblers. |
| Resident Engineering Deployment | On-site bonding process optimization within 48 hours satisfies Nagoya-area Toyota supply chain service demands. |
Research Methodology
Direct dialogue with adhesive formulation chemists, tier-1 automotive procurement managers, construction contractor purchasing leads, and METI compliance officers grounded qualitative findings in operational reality. Secondary validation drew from Japan Chemical Industry Association trade statistics, METI Chemical Substances Control Law filings, JIS standard revision notices, and customs import data for fluoropolymer resin precursors. Bottom-up segment sizing triangulated against top-down industrial consumption estimates across automotive, electronics, construction, and medical device verticals.
Segment-level projections across product type, end-use industry, application method, and technology chemistry combined with regional production cluster analysis. CAGRs derived from elasticity-adjusted demand modeling that linked automotive lightweighting mandates to reactive polyurethane consumption per vehicle. Key inputs included Toyota and Honda multi-material body-in-white adoption curves, METI VOC regulatory phase-in schedules, and semiconductor packaging epoxy purity specifications from Kyoto-area assemblers.
The model holds under stable naphtha cracking margins and intact JIS certification timelines; deviation in fluoropolymer export controls or accelerated METI carbon neutrality enforcement would shift volume trajectories. Forecasts embed assumptions regarding bio-based feedstock cost parity and tier-1 procurement consolidation patterns. Practitioners should monitor METI nano-additive reporting implementation and GX League Scope 3 disclosure adoption for early signals of compliance cost escalation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
South America Sealants Market
Adhesives & Sealants
Glass Adhesive Market
Adhesives & Sealants
Europe Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Hydrophobic Pore-Blocking Agents for Waterproof Concrete Market
Adhesives & Sealants
Spain Adhesives Market
Adhesives & Sealants
Polysulfide Sealants Market
Adhesives & Sealants
South America Adhesives and Sealants Market
Adhesives & Sealants
Silicone Sealants Market
Adhesives & Sealants
Europe Electronics Adhesives Market
Adhesives & Sealants
Thailand Adhesives and Sealants Market
Adhesives & Sealants
United Kingdom Sealants Market
Adhesives & Sealants
Moisture Curing Adhesives Market
Adhesives & Sealants
Restorative Materials and Bonding Agents Market
Adhesives & Sealants
South America Epoxy Adhesives Market
Adhesives & Sealants
Curing Adhesives Market
Adhesives & Sealants
Solvent-Borne Adhesives Market