
 Asia-Pacific Adhesives Market | 2026-2036
Asia-Pacific Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Adhesives Market Analysis
Electric vehicle assembly is broadening the Asia-Pacific adhesives end-use mix as battery pack encapsulation and body-in-white bonding displace traditional mechanical fastening. Henkel AG & Co. KGaA leverages its automotive OEM qualification network across Japan and South Korea to sustain high-specification supply contracts. Pidilite Industries Ltd. anchors its position through dominant distribution reach into India's tier-two manufacturing cities and construction belts. Dow competes on materials science integration, extending silicone and polyurethane platforms into electronics thermal management applications.
Adhesives are non-metallic substances applied between surfaces to develop structural or functional bonds through chemical curing, pressure activation, or thermal processing, with formulations typically comprising base polymers, tackifiers, curing agents, and rheology modifiers engineered to specific shear strengths, temperature resistance, and substrate compatibility. Water-based acrylic and polyurethane systems lead volume in packaging and consumer goods due to regulatory pressure on solvent emissions, while reactive epoxy and hot-melt technologies capture premium margin pools in automotive and electronics where cure speed and thermal cycling endurance determine specification. Solvent-based technology retains niche dominance in specialty industrial laminates where moisture sensitivity or extreme chemical exposure excludes aqueous alternatives.
China's MEE enforces GB standards limiting VOC content in adhesive formulations, compelling reformulation investments across domestic and multinational producers. Japan's METI promotes low-carbon manufacturing incentives that favor water-based and bio-derived feedstock adoption in keiretsu supply chains. India's BIS certification requirements for construction-grade adhesives create compliance barriers for unqualified imports while elevating quality baselines for domestic manufacturers. Stakeholders must monitor divergence between national emission regimes and harmonize formulation platforms to avoid fragmented compliance costs across the region's multi-jurisdictional procurement landscape.
Market Dynamics
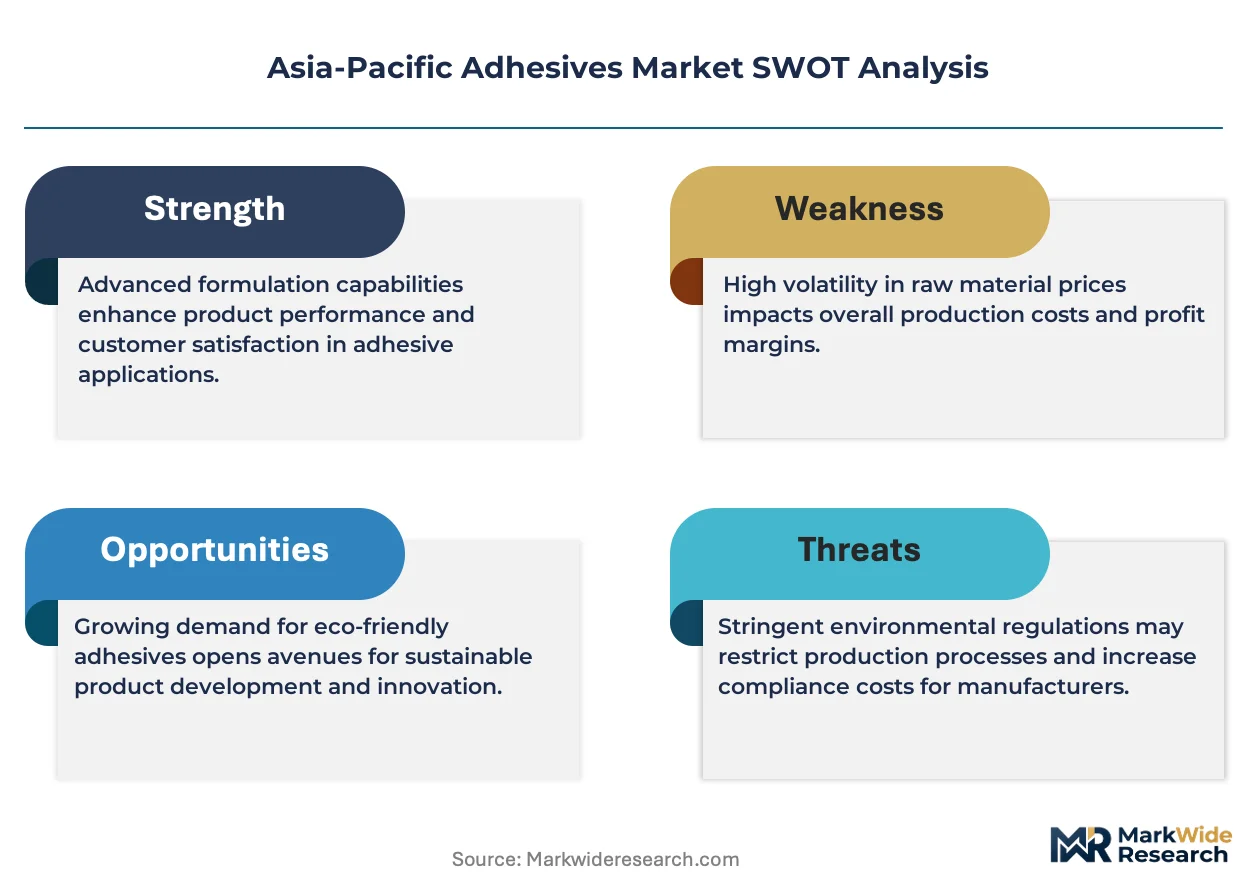
China's GB standards on volatile organic compound emissions are compressing formulation margins across the Asia-Pacific adhesives market, forcing multinational and domestic producers into simultaneous reformulation cycles while automotive lightweighting programs in Japan and South Korea pull structural bonding specifications higher.
Growth Catalysts
- Automotive lightweighting mandates:Japan's keiretsu supply chains and South Korea's OEM assembly networks are expanding specification requirements for structural bonding solutions that replace mechanical fastening in body-in-white applications.
- MEE emission enforcement:China's Ministry of Ecology and Environment is compelling water-based and hot-melt technology adoption across manufacturing provinces through tightened GB standards on adhesive VOC content.
- Battery pack encapsulation demand:Electric vehicle assembly lines across eastern China's industrial corridor are creating dedicated demand streams for thermal management and cell bonding chemistries.
Market Restraints
- Petrochemical feedstock volatility:Polyurethane and epoxy resin input costs fluctuate with naphtha and propylene pricing, compressing margin predictability for formulation houses.
- East China supply concentration:Production gravity centers on Shanghai, Jiangsu, and Zhejiang provinces, creating geographic vulnerability to regional logistics disruptions or environmental enforcement waves.
- Solvent-based regulatory exclusion:GB standards and METI low-carbon incentives are systematically narrowing viable application scope for high-performance solvent systems in moisture-sensitive laminates.
Strategic Opportunities
- India tier-two manufacturing penetration:Construction-grade adhesive demand in Ahmedabad, Pune, and Coimbatore remains underserved by qualified domestic distribution networks.
- Bio-derived feedstock qualification:METI manufacturing incentives and keiretsu sustainability targets are opening specification windows for plant-based tackifiers and curing agents in Japanese automotive supply chains.
- Electronics thermal management convergence:Silicone and polyurethane platforms are extending into 5G base station and data center applications where thermal cycling endurance determines procurement decisions.
Industry Challenges
- Multi-jurisdictional compliance harmonization:Divergence between China's GB emission regimes, Japan's METI low-carbon frameworks, and India's BIS certification requirements fragments formulation platform economics.
- Reactive cure speed optimization:Automotive OEMs demand sub-minute fixture times for body-in-white bonding that aqueous systems struggle to deliver without capital-intensive thermal activation infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Adhesives Market |
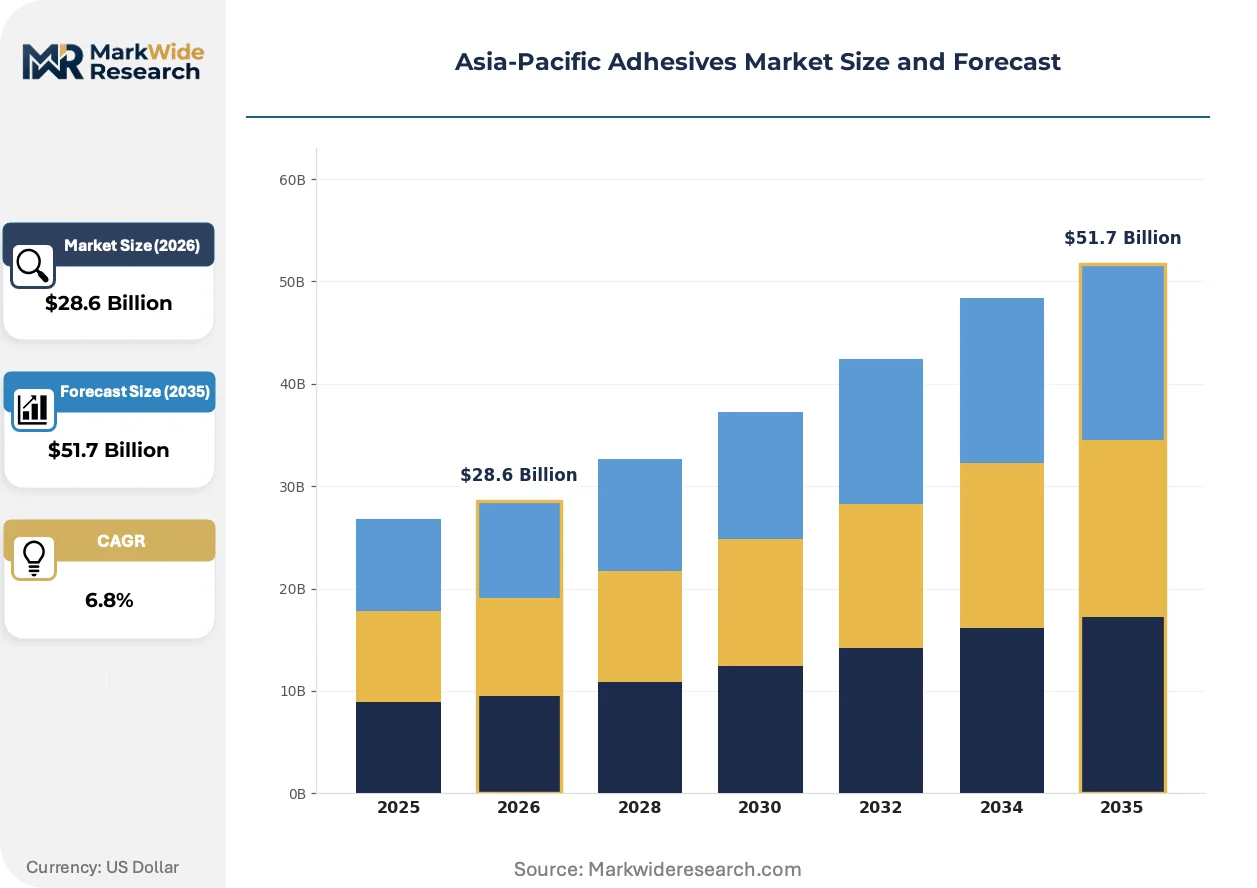
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Epoxy, Acrylic, Silicone Application: Construction, Automotive, Packaging, Electronics End User: Manufacturers, Contractors, Distributors, Retailers Technology: Water-Based, Solvent-Based, Hot Melt, Reactive |
| Companies Covered | 3M, Henkel AG & Co. KGaA, Sika AG, H.B. Fuller Company, Arkema Group, BASF AG, Dow, Pidilite Industries Ltd., Avery Dennison Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Adhesives Market Emerging Trajectories
Formulation science and procurement logic across the Asia-Pacific adhesives market are being restructured by three concurrent pressures: materials integration with adjacent functional requirements, regulatory compression of legacy chemistries, and buyer consolidation around qualified supply bases.
Two-component polyurethane systems are integrating thermal management and structural bonding functions into single-application chemistries for electric vehicle battery modules. Korean and Japanese automotive OEMs are accelerating qualification timelines for these hybrid platforms. This convergence is integrating adhesive specification into thermal engineering workflows rather than discrete procurement categories.
China's GB standards on VOC emissions in adhesive formulations are forcing systematic reformulation investments across domestic and multinational producers. The industrial consequence is accelerated phase-out of solvent-based systems in packaging and consumer goods applications. Water-based acrylic and hot-melt technologies are capturing displaced volume in eastern China's manufacturing provinces.
Consolidated procurement by automotive and electronics OEMs is compressing supplier qualification cycles and unbundling after-sales technical service from material supply contracts. Tier-one assemblers in Japan and South Korea are replacing distributor intermediaries with direct formulation house relationships. This disintermediation is most visible in keiretsu supply chains where captive engineering resources reduce reliance on third-party application support.
Asia-Pacific Adhesives Market Segmentation
Segmentation in the Asia-Pacific adhesives market reveals how formulation chemistry, application requirements, and procurement channels intersect to create distinct competitive arenas. Each dimension carries different margin profiles and regulatory exposure across China's industrial corridor, Japan's keiretsu networks, and India's tier-two manufacturing belts.
Product Type:
Upgrade cycles in automotive lightweighting and battery encapsulation are pulling specification requirements higher across polymer platforms, with OEMs replacing legacy mechanical fastening with structural bonding solutions.
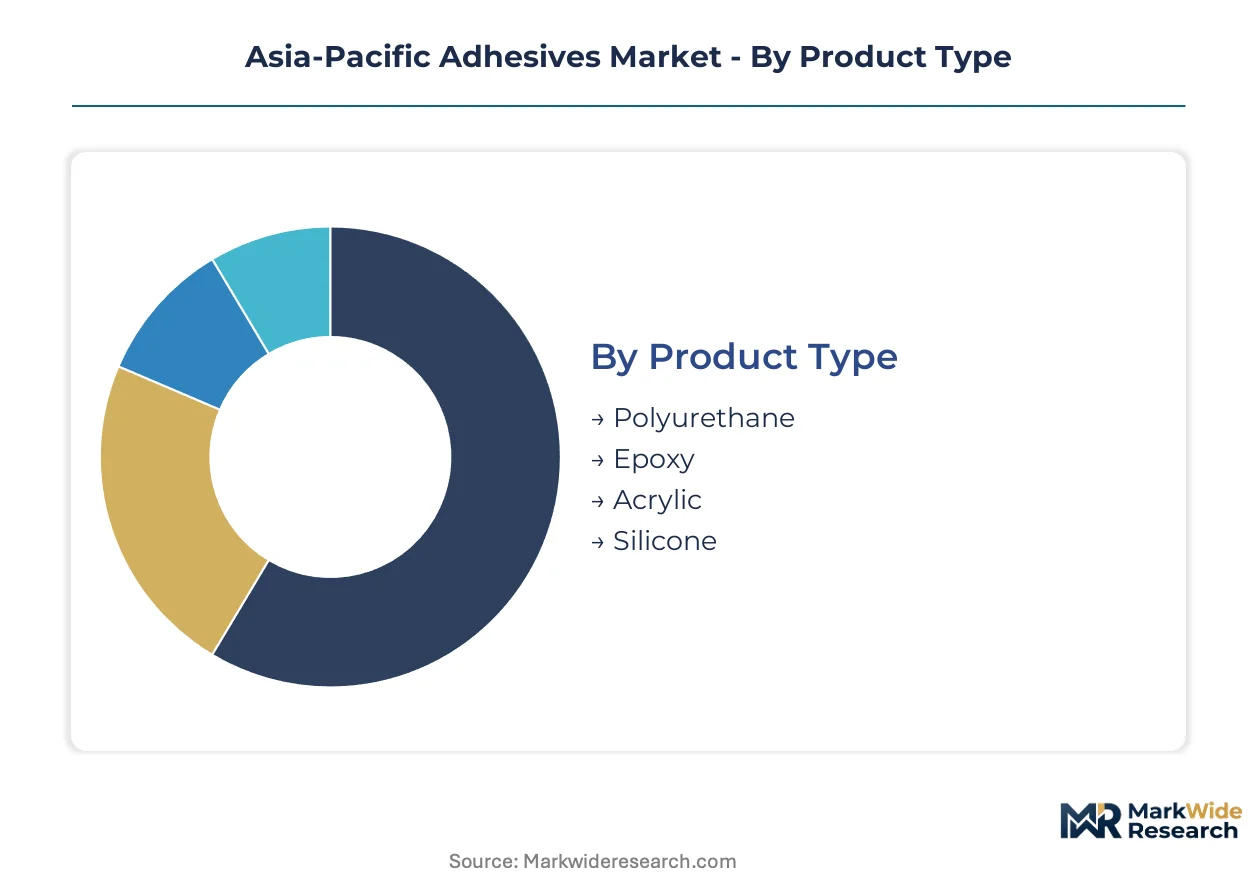
- Polyurethane:Two-component systems combine structural bonding with thermal management functions for electric vehicle battery modules. Korean and Japanese OEMs are accelerating qualification timelines for these hybrid platforms in body-in-white applications.
- Acrylic:Water-based formulations dominate packaging and consumer goods volume in eastern China's manufacturing provinces due to MEE enforcement of GB standards on VOC emissions. Shanghai and Jiangsu converters favor these systems for regulatory compliance without capital-intensive thermal activation.
- Epoxy:Reactive chemistries capture premium positioning in electronics and industrial laminates where moisture sensitivity or chemical exposure excludes aqueous alternatives.
- Silicone:Thermal cycling endurance determines procurement for 5G base station and data center applications across the region's electronics manufacturing clusters.
Acrylic sits at the top of the volume ranking, with polyurethane climbing the fastest.
Application:
Cost tier differentiation separates specification-grade automotive and electronics bonding from commodity construction and packaging applications, with margin compression most severe in price-sensitive building materials.
- Automotive:Body-in-white bonding and battery pack encapsulation displace traditional mechanical fastening as Japan and South Korea expand structural bonding specifications. Keiretsu supply chains favor qualified formulation houses over distributor intermediaries.
- Electronics:Thermal management convergence integrates silicone and polyurethane platforms into 5G infrastructure and data center procurement workflows.
- Construction:India's BIS certification requirements create compliance barriers for unqualified imports while elevating quality baselines for domestic manufacturers in Ahmedabad and Pune.
- Packaging:Water-based acrylic systems capture displaced solvent volume as GB standards phase out high-VOC formulations in Shanghai, Jiangsu, and Zhejiang converter operations.
Construction generates the highest absolute volume, with electronics gaining share fastest.
End User:
Customer type determines technical service bundling and pricing power, with direct OEM relationships commanding premium positioning against distributor-mediated contractor and retail channels.
- Manufacturers:Tier-one automotive and electronics assemblers in Japan and South Korea consolidate procurement around qualified supply bases, unbundling after-sales technical service from material supply contracts.
- Distributors:Pidilite Industries anchors position through dominant reach into India's tier-two manufacturing cities, serving contractors and smaller fabricators with construction-grade formulations.
- Contractors:Building material applicators in India's construction belts face BIS compliance requirements that fragment procurement across certified and uncertified supply sources.
- Retailers:Consumer goods and DIY channels concentrate in China's eastern provinces where packaging adhesive demand aligns with e-commerce logistics growth.
Manufacturers command the highest contract values, with distributors expanding reach most aggressively.
Technology:
Regulatory maturity across national emission regimes is systematically narrowing viable application scope for legacy solvent systems while opening specification windows for water-based and reactive alternatives.
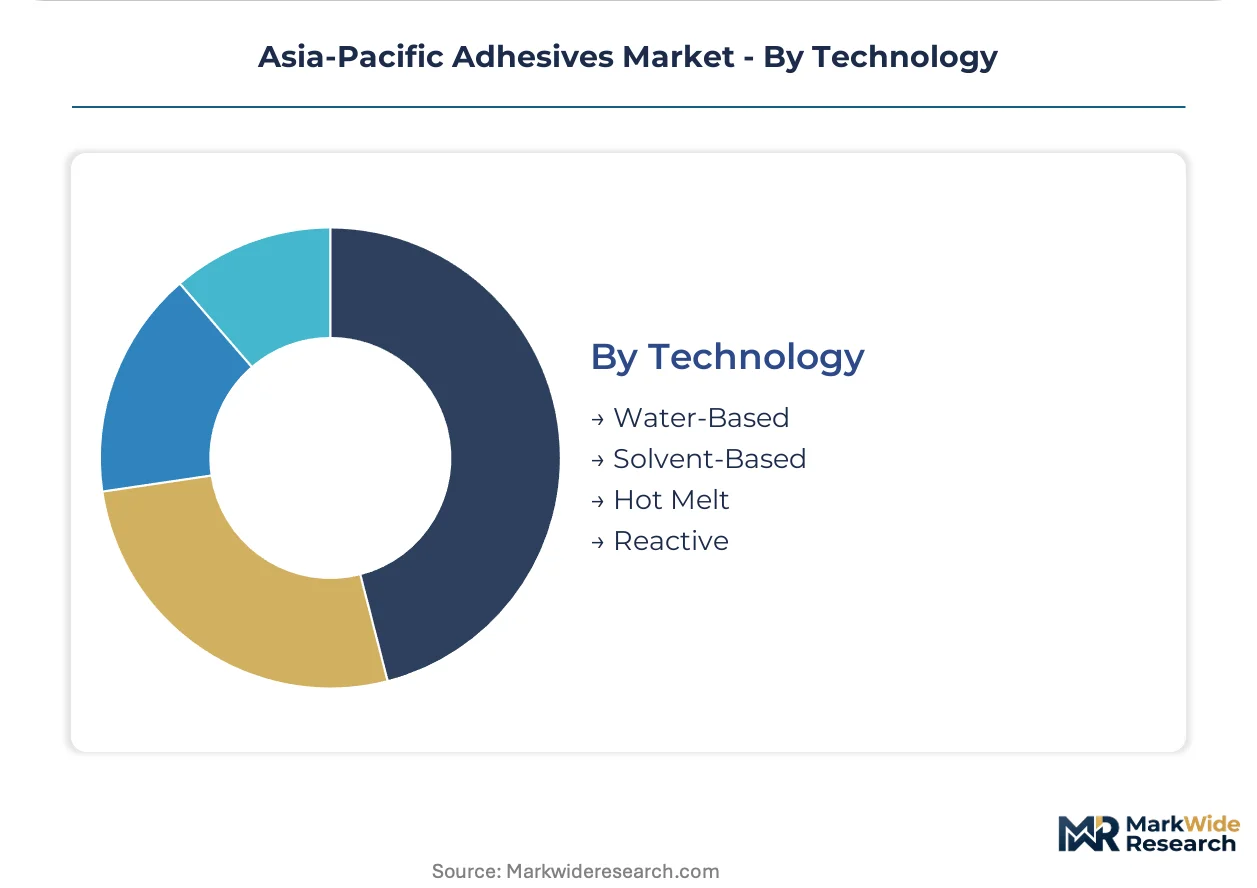
- Water-Based:Acrylic and polyurethane systems lead packaging and consumer goods volume due to MEE enforcement of GB standards limiting VOC content. Reformulation investments concentrate in Shanghai and Jiangsu manufacturing provinces.
- Reactive:Epoxy and polyurethane platforms capture automotive and electronics premium where sub-minute fixture times and thermal cycling endurance determine specification. Korean OEMs demand accelerated cure speeds for battery module assembly.
- Hot Melt:Pressure-activated systems displace solvent alternatives in moisture-sensitive packaging applications across China's industrial corridor.
- Solvent-Based:GB standards and METI low-carbon incentives compress viable scope to specialty industrial laminates where moisture sensitivity or extreme chemical exposure excludes aqueous alternatives.
Water-based technology holds the volume lead, with reactive systems expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reformulation costs from China's GB standards on VOC emissions are pushing multinational producers toward regulatory-arbitrage strategies, with some capacity migrating to ASEAN jurisdictions where emission enforcement remains less stringent while maintaining proximity to eastern China's demand clusters.
China
MEE enforcement of GB standards on adhesive VOC content is accelerating water-based and hot-melt technology adoption across Shanghai, Jiangsu, and Zhejiang manufacturing provinces. Eastern China's industrial corridor concentrates demand from electric vehicle battery pack encapsulation and electronics thermal management applications.
Japan
Keiretsu supply chains are expanding structural bonding specifications for automotive lightweighting programs in body-in-white applications. METI low-carbon manufacturing incentives favor water-based and bio-derived feedstock adoption among tier-one assemblers in Kanto and Kansai industrial belts.
South Korea
OEM assembly networks are driving qualification timelines for two-component polyurethane systems that combine thermal management with structural bonding. Battery module manufacturers in Gyeonggi and Ulsan industrial complexes demand sub-minute fixture times for high-volume electric vehicle production.
India
BIS certification requirements for construction-grade adhesives are elevating quality baselines for domestic manufacturers while creating compliance barriers for unqualified imports. Ahmedabad and Pune construction belts remain underserved by qualified distribution networks for tier-two manufacturing cities.
Thailand
Automotive component suppliers serving Japanese and Korean OEM networks are absorbing displaced solvent-based capacity as multinational producers seek lower-compliance-cost manufacturing bases. Eastern seaboard industrial estates near Rayong and Chonburi are attracting adhesive formulation investments.
Asia-Pacific Adhesives Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with keiretsu-qualified formulation houses commanding premium positioning in Japanese automotive supply chains while distributor-mediated players dominate India's construction belts. The market structures around three tiers: multinational chemical conglomerates with materials science integration, regional specialists with dominant distribution reach, and domestic formulators with cost-positioned commodity supply. Consolidation pressure is intensifying through direct OEM relationships that disintermediate distributor intermediaries, while bio-derived feedstock investments accelerate in response to METI sustainability incentives.
Among multinational chemical conglomerates, Henkel AG & Co. KGaA and Dow exemplify the materials science integration archetype, with the former anchoring automotive OEM qualification networks across Japan and South Korea and the latter extending silicone and polyurethane platforms into electronics thermal management. Pidilite Industries Ltd. represents the regional distribution specialist model, occupying a position built on dominant reach into India's tier-two manufacturing cities and construction belts. These three players illustrate how competitive positioning diverges between specification-grade automotive supply and volume-driven construction markets.
| Leading Market Players |
|---|
| 3M |
| Henkel AG & Co. KGaA |
| Sika AG |
| H.B. Fuller Company |
| Arkema Group |
| BASF AG |
| Dow |
| Pidilite Industries Ltd. |
| Avery Dennison Corporation |
| Others |
Supply Flow & Price Mechanics
Automotive OEM consolidation around qualified formulation houses in Japan and South Korea is compressing distributor margins and forcing supply base rationalization across the Asia-Pacific adhesives market, with tier-one assemblers extracting direct pricing leverage that reshapes channel economics.
Pricing Analysis
Distributor margin compression dominates channel economics as keiretsu procurement offices in Kanto and Kansai industrial belts negotiate direct supply contracts that bypass traditional intermediaries. Three-tier pricing structure across premium, standard, and economy levels separates specification-grade automotive formulations from commodity construction adhesives, with BIS-certified construction grades in India commanding modest premiums over uncertified alternatives. Cost compression in water-based acrylic systems is intensifying because MEE enforcement of GB standards has triggered simultaneous reformulation investments across Shanghai and Jiangsu manufacturing provinces. Contractors and smaller fabricators in India's tier-two cities exhibit highest price sensitivity, while Japanese automotive OEMs prioritize thermal cycling performance over unit cost.
Supply Chain Analysis
China's domestic-content preferences in government procurement and state-owned enterprise sourcing are reshaping raw material sourcing patterns for multinational formulation houses operating in eastern provinces. Production gravity centers on China, Japan, and South Korea, with formulation operations drawing from naphtha and propylene feedstock networks anchored in Northeast Asian petrochemical complexes. Supply chains rest on epoxy resin, polyurethane prepolymer, and silicone monomer inputs whose pricing fluctuates with regional olefin markets. Single-source vulnerability concentrates in specialty curing agent supply from Japanese chemical intermediates producers. Distribution runs through qualified distributor networks in India and direct OEM relationships in Japanese keiretsu supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific adhesives market functions as a geographic-arbitrage play where Thailand and Vietnam absorb displaced solvent-based capacity from China at lower compliance cost while maintaining proximity to eastern China's demand clusters.
For Market Incumbents: Anticipate accelerated qualification timeline compression from Korean battery module manufacturers demanding sub-minute fixture times, and respond with captive R&D investment in two-component polyurethane cure acceleration or acquisition of thermal management specialists with existing OEM validation. Defend keiretsu positioning by deepening backward integration into bio-derived tackifier supply chains eligible for METI low-carbon manufacturing incentives. For New Entrants and Emerging Players: Tier-two manufacturing contractors in Ahmedabad and Pune construction belts remain underserved by qualified BIS-certified distribution networks, presenting white-space penetration opportunities. Target electronics thermal management applications in 5G base station assembly where silicone platform qualification windows remain open. Pursue technical service bundling as primary go-to-market mechanism to differentiate against price-commoditized construction adhesive supply. For Investors and Strategic Acquirers: Asymmetric upside sits with regional specialists possessing dominant distribution reach into India's tier-two manufacturing cities combined with formulation flexibility for water-based technology migration. Long-term viability favors assets with demonstrated OEM qualification in Japanese or Korean automotive supply chains over pure construction-grade commodity positions. Monitor METI bio-derived feedstock incentive expansion as inflection signal for sustainable chemistry platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Derived Feedstocks | Captures METI low-carbon incentives while qualifying for keiretsu sustainability procurement criteria. |
| Capacity Expansion in Thailand Eastern Seaboard | Absorbs displaced solvent-based production at lower MEE compliance cost while serving Japanese OEM component networks. |
| Long-Term Supply Agreement with Korean Battery Manufacturers | Locks in volume commitment for thermal management adhesives ahead of competing qualification cycles. |
| Joint Venture with Indian Distributor Networks | Accelerates BIS-certified construction adhesive penetration into underserved Ahmedabad and Pune manufacturing belts. |
| Green Manufacturing Transition Certification | Enables specification access to METI-incentivized keiretsu supply chains favoring water-based and bio-derived platforms. |
Methodological Framework
Direct dialogue with adhesive formulation chemists, automotive OEM procurement managers, construction distributor operators, and MEE regulatory compliance officers grounded this analysis in operational reality. Primary insights were cross-referenced against secondary sources including China customs trade data, ACC regional chemical industry reports, Japanese METI manufacturing incentive disclosures, and SEC filings from publicly traded chemical conglomerates. Bottom-up and top-down triangulation validated volume estimates across polymer platforms and application segments.
Bottom-up modeling anchored forecast outputs, with top-down macroeconomic cross-checks from regional industrial production indices. Segmentation dimensions span polymer chemistry, application end-use, technology type, and procurement channel structure. CAGRs were derived from trend extrapolation of electric vehicle assembly growth, GB standard enforcement timelines, and keiretsu supply chain restructuring patterns. Key inputs included battery pack encapsulation intensity assumptions and thermal management adhesive content per 5G base station.
Underlying measurement precision varies by segment; automotive and electronics specification-grade categories carry tighter precision than fragmented construction contractor channels. Forecasts reflect documented assumptions regarding MEE enforcement consistency, METI incentive continuity, and petrochemical feedstock price stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Adhesive Resin Market
Adhesives & Sealants
Paper-Backing Abrasive Adhesive Discs Market
Adhesives & Sealants
De-Seamable Adhesives Market
Adhesives & Sealants
Asia-Pacific Contact Adhesives Market
Adhesives & Sealants
Gelatin Bone Glue Market
Adhesives & Sealants
Lignin for Adhesives Market
Adhesives & Sealants
American Epoxy Adhesives Market
Adhesives & Sealants
Middle East & Africa Adhesives and Sealants Market
Adhesives & Sealants
Applicator Tips Market
Adhesives & Sealants
Asia-Pacific Urea-Formaldehyde Glues and Resins Market
Adhesives & Sealants
Europe Chemical Anchors Market
Adhesives & Sealants
Acetate Silicone Sealant Market
Adhesives & Sealants
Global Adhesion Promoter Market
Adhesives & Sealants
Automotive Adhesives and Sealants Market
Adhesives & Sealants
Anti-Tacking Agents Market
Adhesives & Sealants
Emulsion Pressure Sensitive Adhesives Market