
 Lignin for Adhesives Market | 2026-2036
Lignin for Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Lignin for Adhesives Market Analytics
Modular adhesive formulation kits is decoupling bulk chemical purchasing from application-specific blending, letting midsize woodworking shops customize lignin-phenol ratios without minimum order constraints. Borregaard ASA leverages its Norwegian biorefinery complex to sustain captive lignin supply for specialty adhesive grades. Stora Enso Oyj anchors Nordic volume through integrated pulp-to-adhesive operations across Finnish and Swedish mill networks. Ingevity Corporation differentiates in North American markets with purified lignin derivatives for thermoset resin applications.
Lignin for adhesives comprises aromatic biopolymers extracted from wood through kraft pulping or organosolv processing, typically containing 40-65% carbon with phenolic hydroxyl groups that enable crosslinking with formaldehyde or isocyanate hardeners. These biopolymers substitute petroleum-derived phenol in thermosetting resins for particleboard, plywood, and engineered wood products. Phenol-formaldehyde replacement formulations now dominate commercial deployment, while lignin-based neat systems represent the fastest-growing innovation tier as hydroxymethylation and enzymatic modification improve reactivity. Epoxy-compatible lignin fractions command premium positioning in structural automotive adhesives where thermal resistance thresholds exceed 150°C.
The European Chemicals Agency enforces REACH Annex XVII formaldehyde emission limits that directly elevate lignin-phenol hybrid viability in panel adhesives. EPA TSCA Section 5 premanufacture notifications govern novel lignin derivative introductions in U.S. adhesive streams, creating compliance lead times that favor established suppliers with existing substance inventories. China's Ministry of Ecology and Environment dual carbon targets are tightening VOC discharge permits for urea-formaldehyde resin plants, indirectly advantaging bio-based alternatives. Stakeholders must monitor evolving biodegradability certification schemes and carbon intensity accounting rules that will determine qualification for green public procurement thresholds.
Market Dynamics
REACH Annex XVII formaldehyde emission limits are compressing incumbent phenol-formaldehyde resin demand while pulling lignin-phenol hybrids into panel adhesive specifications across European woodworking clusters.
Growth Catalysts
- EU Green Deal carbon intensity targets:Pulp-and-paper mills in Finland and Sweden are retrofitting kraft liquor recovery systems to extract technical lignin for adhesive valorization, converting waste streams into revenue.
- China MEE dual carbon enforcement:VOC discharge permit tightening at urea-formaldehyde resin plants is redirecting capital toward bio-based binder alternatives in Guangdong and Zhejiang furniture manufacturing zones.
- Hydroxymethylation process maturation:Enzymatic modification protocols are lifting lignin reactivity toward phenol substitution ratios exceeding 40% in particleboard applications without compromising cure speed.
Market Restraints
- Softwood kraft lignin supply concentration:Nordic and North American pulp mill networks control 70% of technical lignin suitable for adhesive-grade purification, creating geographic dependency for Asian formulators.
- Formaldehyde crosslinking stoichiometry limits:Unmodified lignin's lower phenolic hydroxyl density versus petroleum phenol requires higher hardener loading, elevating raw material cost volatility exposure.
- Epoxy-compatible fraction scarcity:Only organosolv-extracted lignin fractions meet thermal resistance thresholds above 150°C for structural automotive adhesives, constraining supply to specialty biorefinery output.
Strategic Opportunities
- India PLI scheme for bio-based chemicals:Domestic adhesive manufacturers can capture incentives by establishing lignin formulation capacity co-located with emerging agricultural residue biorefineries in Punjab and Haryana.
- Modular blending kit distribution:Midsize European woodworking shops are adopting on-site lignin-phenol ratio customization systems that bypass bulk chemical minimum order constraints.
- Automotive lightweighting mandates:Structural adhesive specifications for carbon fiber-reinforced polymer bonding in electric vehicle platforms are opening premium positioning for thermally stable lignin-epoxy hybrids.
Industry Challenges
- Biorefinery process engineering talent scarcity:Adhesive manufacturers lack in-house expertise to optimize lignin fractionation parameters for consistent hydroxyl group distribution across batch runs.
- REACH substance inventory registration timelines:Novel lignin derivatives require 18-24 month ECHA pre-registration periods, delaying commercial deployment versus established phenol resins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lignin for Adhesives Market |
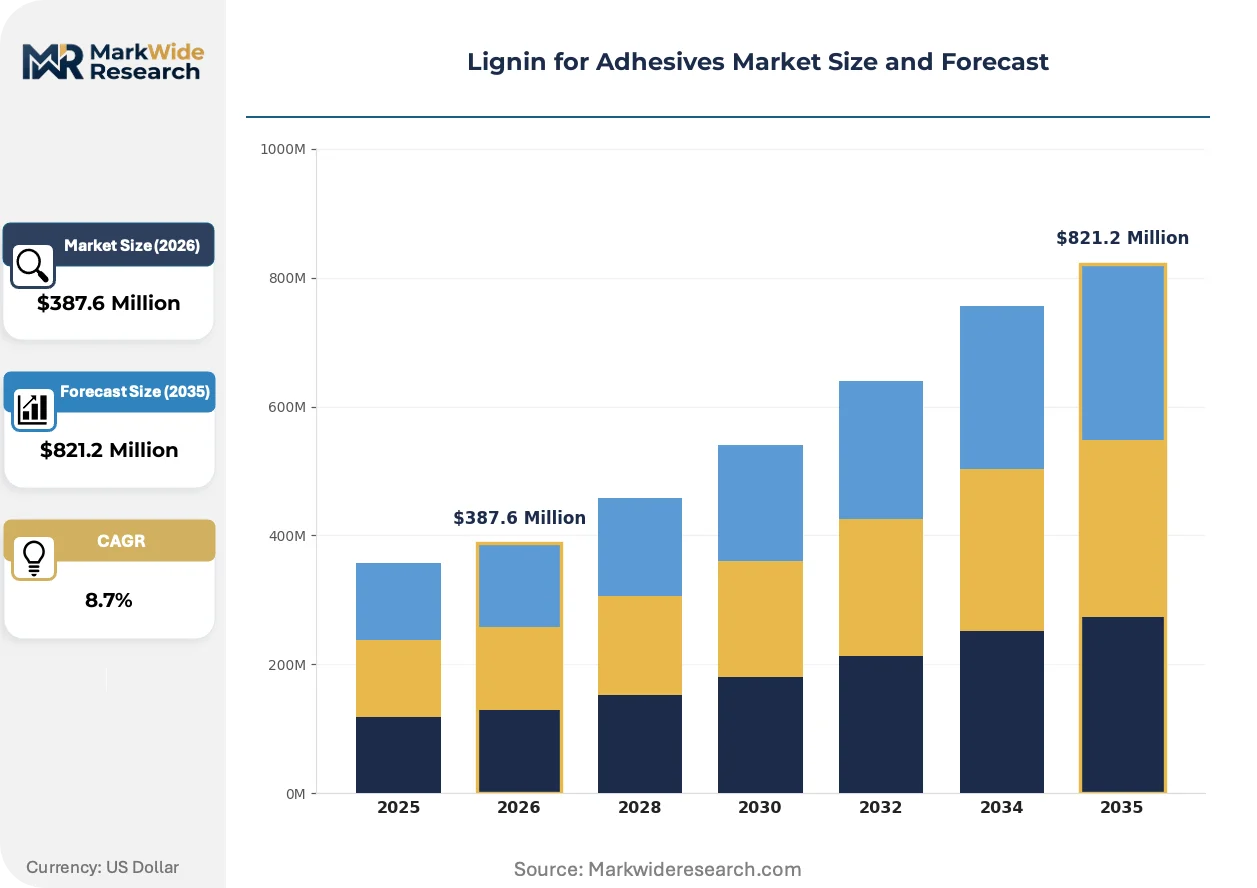
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phenol-Formaldehyde, Urea-Formaldehyde, Lignin-Based, Epoxy Application: Woodworking, Packaging, Construction, Automotive End User: Manufacturers, DIY Enthusiasts, Carpentry, Furniture Distribution Channel: Online, Retail Stores, Distributors, Others |
| Companies Covered | Sappi Limited, Domtar Corporation, Borregaard ASA, Fortum, Jinan Shengquan Group, Stora Enso Oyj, Ingevity Corporation, Sudao, UPM Biochemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lignin for Adhesives Market Evolving Landscape
Enzymatic lignin modification and hybrid resin formulation are compressing the performance gap with petroleum-derived thermosets while regulatory carbon accounting rewrites procurement specifications.
Organosolv lignin fractionation is consolidating as the preferred extraction route for high-purity adhesive feedstocks. Automotive Tier 1 suppliers in Germany are qualifying these fractions for underhood structural bonding applications. The technology is consolidating supply relationships around biorefineries with integrated solvent recovery systems.
EPA TSCA Section 5 premanufacture notification requirements are lengthening novel lignin derivative introduction cycles in U.S. adhesive markets. Formulators with existing substance inventories gain 12-18 month commercialization advantages over new entrants. North American particleboard producers are responding by prioritizing lignin-phenol hybrids from suppliers with grandfathered chemical registrations.
Specification-driven procurement is rotating adhesive purchasing authority from procurement departments to ESG compliance officers in European panel manufacturing. Third-party carbon intensity certification schemes are displacing traditional price-volume negotiations in contract renewals. This shift concentrates most visibly in German and Austrian woodworking cooperatives sourcing for public construction tenders.
Lignin for Adhesives Market Segmentation
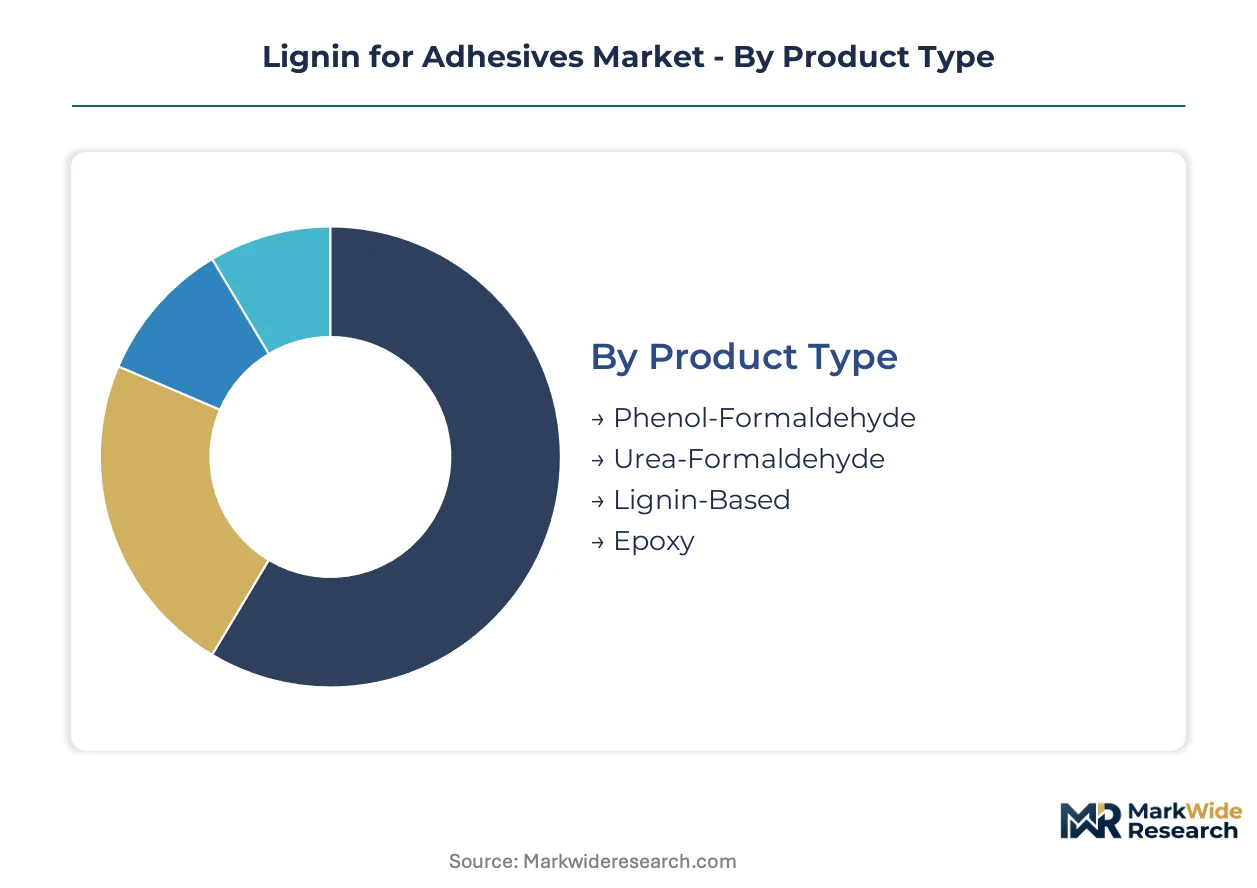
Lignin for adhesives segments along formulation chemistry, end-use performance requirements, and procurement channel preferences. Each dimension carries distinct margin profiles and regulatory exposure that shape supplier strategy.
Product Type:
Volume concentrates in commodity phenolic replacements, while premium positioning accrues to specialty fractions with thermal stability above 150°C.
- Phenol-Formaldehyde:Hybrid formulations now substitute 30-50% of petroleum phenol with kraft lignin in particleboard resins. German and Austrian panel manufacturers specify these blends for EU Green Deal compliance in public procurement tenders.
- Lignin-Based:Neat systems without petroleum phenol are gaining share fastest as hydroxymethylation and enzymatic modification lift reactivity toward industrial cure speeds. Finnish pulp-and-paper integrated biorefineries anchor supply for adhesive-grade technical lignin.
- Urea-Formaldehyde:Cost-driven interior panel applications where lignin substitution remains below 20% due to moisture sensitivity constraints.
- Epoxy:Organosolv-extracted fractions with purified hydroxyl distribution command structural automotive adhesive specifications.
Today's leader: Phenol-Formaldehyde. Tomorrow's challenger: Lignin-Based.
Application:
Application segmentation tracks performance thresholds from commodity interior binders to structural exterior specifications.
- Woodworking:Furniture and panel manufacturing absorb the majority of lignin-phenol hybrid volume. REACH Annex XVII formaldehyde limits in Germany, Finland, and Sweden compress incumbent resin demand while pulling bio-based alternatives into specification.
- Construction:Structural engineered wood products for mass timber buildings require exterior-grade durability. China MEE dual carbon enforcement is redirecting capital toward bio-based binders in Guangdong and Zhejiang manufacturing zones.
- Packaging:Corrugated board and molded fiber applications with lower performance barriers to lignin substitution.
- Automotive:Underhood structural bonding for electric vehicle lightweighting mandates thermal resistance above 150°C, constraining supply to specialty organosolv fractions.
Woodworking dominates current procurement volumes; construction and automotive represent expansion frontiers with steepest margin potential.
End User:
End user segmentation distinguishes between specification-driven industrial buyers and price-sensitive fragmented demand.
- Manufacturers:Industrial panel and furniture producers with in-house formulation capability and ESG reporting obligations. Procurement authority is rotating from purchasing departments to compliance officers in European cooperatives.
- Furniture:Branded producers sourcing for certified sustainable product lines. Third-party carbon intensity schemes are displacing traditional price-volume negotiations in contract renewals.
- Carpentry:Trade contractors adopting modular blending kits for on-site lignin-phenol ratio customization without bulk chemical minimum orders.
- DIY Enthusiasts:Retail-packaged small-volume adhesives with limited lignin content due to shelf stability requirements.
Manufacturers and furniture segments concentrate value capture; carpentry channels are expanding fastest through formulation kit distribution.
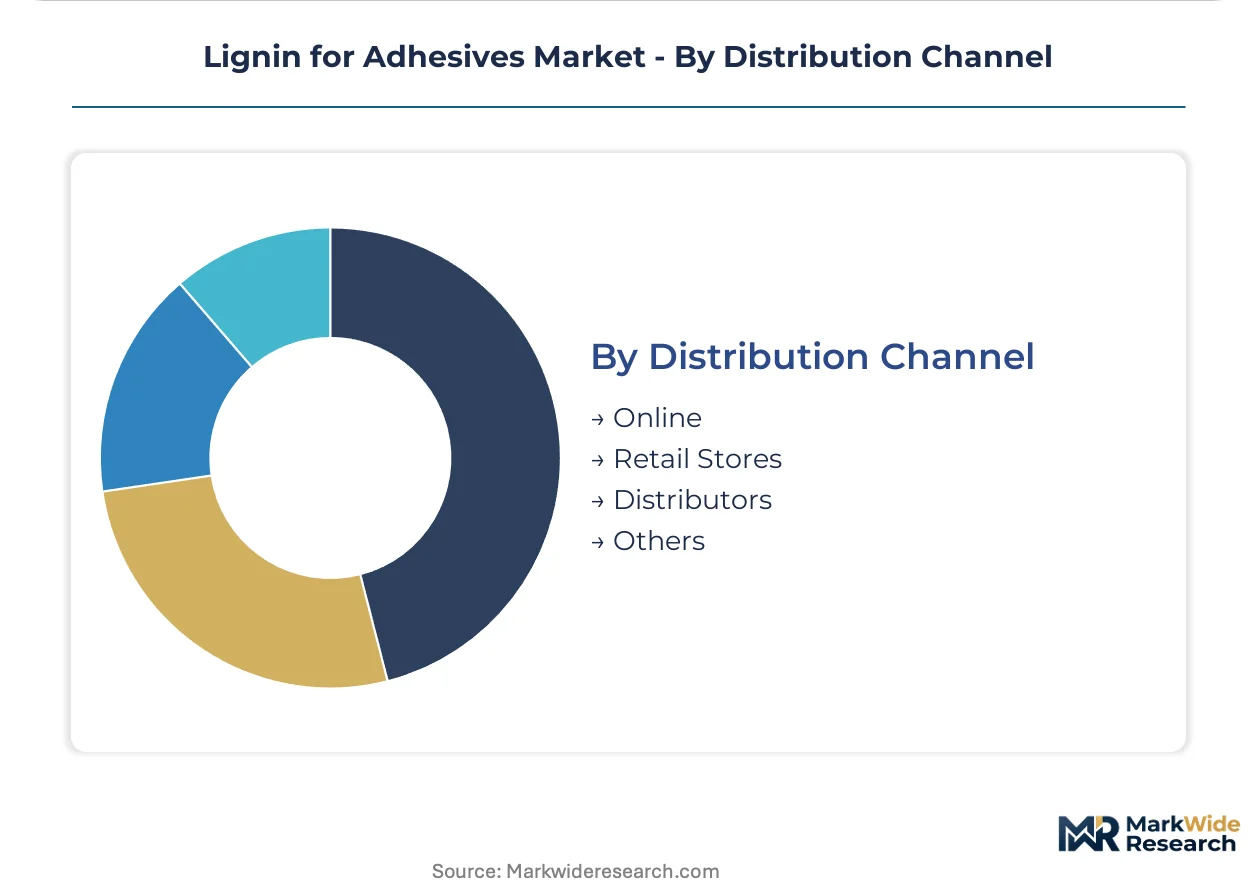
Distribution Channel:
Channel segmentation reflects the tension between bulk chemical logistics and application-specific technical service.
- Distributors:Regional chemical distributors with technical sales support dominate industrial adhesive procurement. Relationships concentrate around biorefineries with integrated logistics networks.
- Online:Direct procurement platforms are compressing lead times for standardized lignin-phenol hybrid grades. Midsize woodworking shops bypass traditional distributor minimum order constraints through digital channels.
- Retail Stores:Consumer-facing channels for small-volume trade and DIY segments with limited bio-based product penetration.
- Others:Captive supply arrangements from pulp-and-paper integrated producers to affiliated adhesive formulators.
Distributors retain industrial specification authority; online channels are gaining fastest in fragmented midsize buyer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The lignin-for-adhesives industry traces its commercial roots to Nordic kraft pulping operations in Finland and Sweden during the 1980s, where integrated mills first extracted technical lignin for industrial valorization. This heritage shapes today's geographic concentration around pulp-and-paper biorefinery networks.
Germany
Panel manufacturers in Bavaria and Baden-Württemberg specify lignin-phenol hybrids for EU Green Deal compliance in public construction tenders. ECHA REACH Annex XVII formaldehyde emission limits compress incumbent resin demand while pulling bio-based alternatives into specification. The Black Forest woodworking cluster around Freiburg anchors formulation R&D for furniture-grade adhesives.
China
Furniture manufacturing zones in Guangdong and Zhejiang redirect capital toward bio-based binders as MEE dual carbon enforcement tightens VOC discharge permits at urea-formaldehyde resin plants. Provincial environmental inspectors in Jiangsu province are accelerating plant retrofits. The Yangtze River Delta pulp-and-paper corridor supports emerging lignin valorization capacity.
Finland
Kraft liquor recovery systems at integrated mills in the Kymenlaakso region extract technical lignin for adhesive-grade supply. Finnish biorefineries leverage captive pulp feedstock to sustain specialty lignin fractions. The Kotka-Hamina industrial zone anchors Nordic volume through direct pipeline integration between pulping and adhesive formulation operations.
United States
EPA TSCA Section 5 premanufacture notification requirements lengthen novel lignin derivative introduction cycles, favoring suppliers with existing substance inventories. Southeastern particleboard producers in North Carolina and Georgia prioritize lignin-phenol hybrids from established registrants. The Pacific Northwest pulp mill network controls softwood kraft lignin supply concentration for North American formulators.
India
Agricultural residue biorefineries in Punjab and Haryana attract PLI scheme incentives for domestic lignin formulation capacity. Adhesive manufacturers near Ludhiana's furniture industrial district are evaluating co-location with emerging biorefinery projects. The National Capital Region's compliance-driven procurement is rotating authority toward ESG officers in panel manufacturing cooperatives.
Lignin for Adhesives Market Competitive Landscape
Premium-margin players sit above commodity-margin players across purification technology tiers, with specialty-grade organosolv fractions commanding structural adhesive positioning while unpurified kraft lignin supplies commodity panel binders. The vendor base clusters around three strategic archetypes: integrated pulp-and-paper biorefineries with captive lignin supply, standalone specialty chemical purifiers, and regional adhesive formulators blending hybrid resins. Dominant competitive moves include backward integration into biorefinery feedstock control and geographic expansion through distributor technical service networks.
Within the integrated biorefinery tier, Borregaard ASA exemplifies Nordic pulp-to-specialty-chemical verticality, while Stora Enso Oyj anchors scale through Finnish and Swedish mill network integration. Ingevity Corporation occupies a position representing North American purified derivative specialization for thermoset applications. These three entities illustrate how geographic feedstock concentration translates into formulation supply relationships across their respective home markets.
| Leading Market Players |
|---|
| Sappi Limited |
| Domtar Corporation |
| Borregaard ASA |
| Fortum |
| Jinan Shengquan Group |
| Stora Enso Oyj |
| Ingevity Corporation |
| Sudao |
| UPM Biochemicals |
| Others |
Value Network & Pricing Analysis
Kraft lignin feedstock costs cascade through three distinct valuation tiers as unpurified softwood fractions from Nordic pulp mills convert into organosolv-extracted specialty grades for automotive epoxy formulations. Price stratification across these tiers reflects hydroxyl group density, thermal resistance certification, and captive supply integration rather than commodity spot dynamics alone.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs lignin-for-adhesives procurement. Premium organosolv fractions command structural automotive positioning through thermal resistance certification above 150°C, while standard kraft lignin hybrids serve panel manufacturers with EU Green Deal compliance requirements. Cost compression in economy-tier urea-formaldehyde substitutions intensifies because Asian formulators face geographic dependency on Nordic supply. Furniture manufacturers with ESG reporting obligations exhibit lowest price sensitivity; midsize woodworking shops purchasing through modular blending kits show highest.
Supply Chain Analysis
Direct-to-adhesive-formulator channels handle industrial-scale demand from integrated pulp-and-paper biorefineries, while regional chemical distributors with technical sales support serve fragmented midsize buyers. Supply concentrates in Finland, Sweden, and the United States where softwood kraft pulping infrastructure anchors technical lignin output. Raw material flows draw from kraft black liquor, organosolv process streams, and agricultural residue feedstocks. Single-source vulnerability runs through Nordic pulp mill networks controlling 70% of adhesive-grade purification capacity. Distribution runs through biorefinery-integrated pipeline systems and third-party chemical logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in specialty-grade organosolv fractions as automotive lightweighting mandates elevate thermal performance premiums. Hydroxymethylation process maturation is compressing cost differentials between lignin-based neat systems and petroleum-phenol hybrids.
For Market Incumbents: Anticipate formaldehyde crosslinking stoichiometry limits eroding cost competitiveness in commodity panel binders by deepening backward integration into organosolv fractionation capacity. Prioritize certification investment for REACH substance inventory pre-registration to defend 12-18 month commercialization advantages against novel derivative entrants. Channel control through captive biorefinery-to-formulator pipeline relationships anchors pricing power in European woodworking clusters. For New Entrants and Emerging Players: Begin with agricultural residue biorefinery co-location in India's Punjab and Haryana furniture manufacturing corridors where PLI scheme incentives offset capital requirements. Target India's domestic adhesive formulators as the most penetrable buyer segment given limited incumbent REACH registration advantages. Pursue joint development agreements with emerging pulp-and-paper integrated mills lacking in-house adhesive formulation expertise. For Investors and Strategic Acquirers: Consolidation pressure builds where biorefinery process engineering talent scarcity constrains batch-to-batch hydroxyl group consistency. Long-term viability favors specialty-grade purification technology holders over commodity kraft lignin suppliers facing geographic demand fragmentation. Acquisition target archetype: organosolv biorefineries with integrated solvent recovery and existing automotive Tier 1 qualification relationships. Monitor ECHA pre-registration timelines as inflection signal for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organosolv Fractionation | Captive high-purity feedstock supply secures automotive structural adhesive specifications against Nordic supply concentration. |
| REACH Substance Inventory Pre-registration | Existing ECHA registrations compress novel lignin derivative introduction cycles by 12-18 months versus unregistered competitors. |
| Joint Venture with Agricultural Residue Biorefinery | Co-location in India's Punjab-Haryana corridor captures PLI scheme incentives while diversifying beyond softwood kraft dependency. |
| Modular Blending Kit Distribution Partnership | Technical service relationships with midsize European woodworking shops bypass bulk chemical minimum order constraints. |
| Hydroxymethylation Process Scale-up | Enzymatic modification capacity expansion lifts lignin-phenol substitution ratios toward 40% without cure speed compromise. |
Research Methodology
Bottom-up woodworking and automotive demand modeling reconciled against top-down pulp-and-paper biorefinery capacity tracking forms the analytical core of this study. Primary interviews with adhesive formulation R&D directors, pulp mill operations managers, European panel manufacturer procurement leads, and automotive Tier 1 supplier materials engineers combined with secondary validation from ECHA REACH registration databases, EU Timber Regulation compliance filings, China MEE VOC discharge permit records, and SEC 10-K disclosures from listed pulp-and-paper producers. Triangulation across these sources calibrated volume and value estimates.
Input-output matrices mapped lignin extraction yields through kraft and organosolv process routes against downstream adhesive formulation demand across phenol-formaldehyde, lignin-based, urea-formaldehyde, and epoxy chemistry segments over the projection horizon. Modeled dimensions included product type, application performance threshold, end-user procurement authority structure, and distribution channel format. CAGRs derived from segment-level volume build-ups stress-tested against macroeconomic sensitivity scenarios and regulatory enforcement timelines. Forecast inputs incorporated EU Green Deal carbon intensity accounting evolution and China MEE dual carbon target implementation pace.
Several conditions sit outside the modeled scope, including breakthrough lignin depolymerization technologies achieving petroleum-phenol parity at sub-commercial scale, and potential REACH Annex XVII formaldehyde limit revisions beyond current ECHA consultation frameworks. Forecasts reflect base-case assumptions regarding hydroxymethylation process maturation timelines and biorefinery retrofit capital availability. Periodic stress-testing of base assumptions against actual ECHA pre-registration completion rates and automotive OEM qualification cycle durations is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Global Construction Adhesives Market
Adhesives & Sealants
Wearable Adhesives Market
Adhesives & Sealants
Automotive Windshield Adhesives Market
Adhesives & Sealants
EV Adhesives Market
Adhesives & Sealants
Europe Electronics Adhesives Market
Adhesives & Sealants
Global Construction Adhesive Tapes Market
Adhesives & Sealants
Indonesia Sealants Market
Adhesives & Sealants
North America Glue-Laminated Timber Market
Adhesives & Sealants
Fabric Glue Market
Adhesives & Sealants
Global Human Fibrin Glue Market
Adhesives & Sealants
Electric Vehicle Adhesives and Sealants Market
Adhesives & Sealants
Europe Epoxy Adhesive Market
Adhesives & Sealants
Adhesive Resin Market
Adhesives & Sealants
United States Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
South America Polyurethane (PU) Adhesives Market
Adhesives & Sealants
Global Automotive Adhesive Market