
 Global Agricultural Lubricants Market | 2026-2036
Global Agricultural Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Agricultural Lubricants Market Analysis
Large-scale agribusiness cooperatives and contract farming enterprises are redrawing procurement patterns across the lubricant value chain. Shell plc leverages its integrated supply network to sustain bulk delivery contracts with major equipment operators across North America and Latin America. Exxon Mobil Corporation anchors its position through high-performance synthetic formulations designed for extended drain intervals in severe-duty harvest cycles. Chevron Corporation differentiates via specialized hydraulic fluid portfolios engineered for precision irrigation and modern planter systems.
Agricultural lubricants are formulated lubricating oils and greases engineered to protect farm machinery powertrains, hydraulics, and gearboxes under high-load, dusty, and thermally variable operating conditions, typically meeting OEM specifications for viscosity grades, oxidation stability, and anti-wear additive packages. Engine oils dominate volume consumption due to universal deployment across tractor fleets, while biodegradable formulations represent the fastest-expanding margin pool as sustainability mandates tighten across European and North American supply chains. Hydraulic fluids command premium positioning within precision agriculture applications where contamination tolerance and shear stability directly correlate with equipment uptime.
The EPA governs lubricant discharge and waste-oil handling protocols in the United States, while REACH and the EU Green Deal impose substance restrictions and carbon-footprint disclosure requirements on lubricant formulations sold across Europe. Brazil's ANVISA and environmental agencies enforce growing scrutiny on agricultural chemical runoff, indirectly pressuring lubricant selection toward biodegradable and non-toxic alternatives. Stakeholders must monitor evolving OEM fluid specifications and regional chemical registries to maintain market access and avoid reformulation costs.
Market Dynamics
Mechanization intensity in contract farming operations is compressing lubricant procurement cycles and forcing bulk supply agreements that bypass traditional distributor networks. This structural shift toward direct OEM-lubricant supplier relationships is redrawing margin capture across the value chain.
Growth Catalysts
- EPA Tier 4 Final standards:These emission mandates in the United States are accelerating demand for lower-viscosity engine oils that reduce fuel consumption in high-horsepower tractors and combines.
- Sugarcane mechanization in Brazil:Harvester fleet expansion across São Paulo and Goiás is driving concentrated bulk lubricant offtake from processing cooperatives.
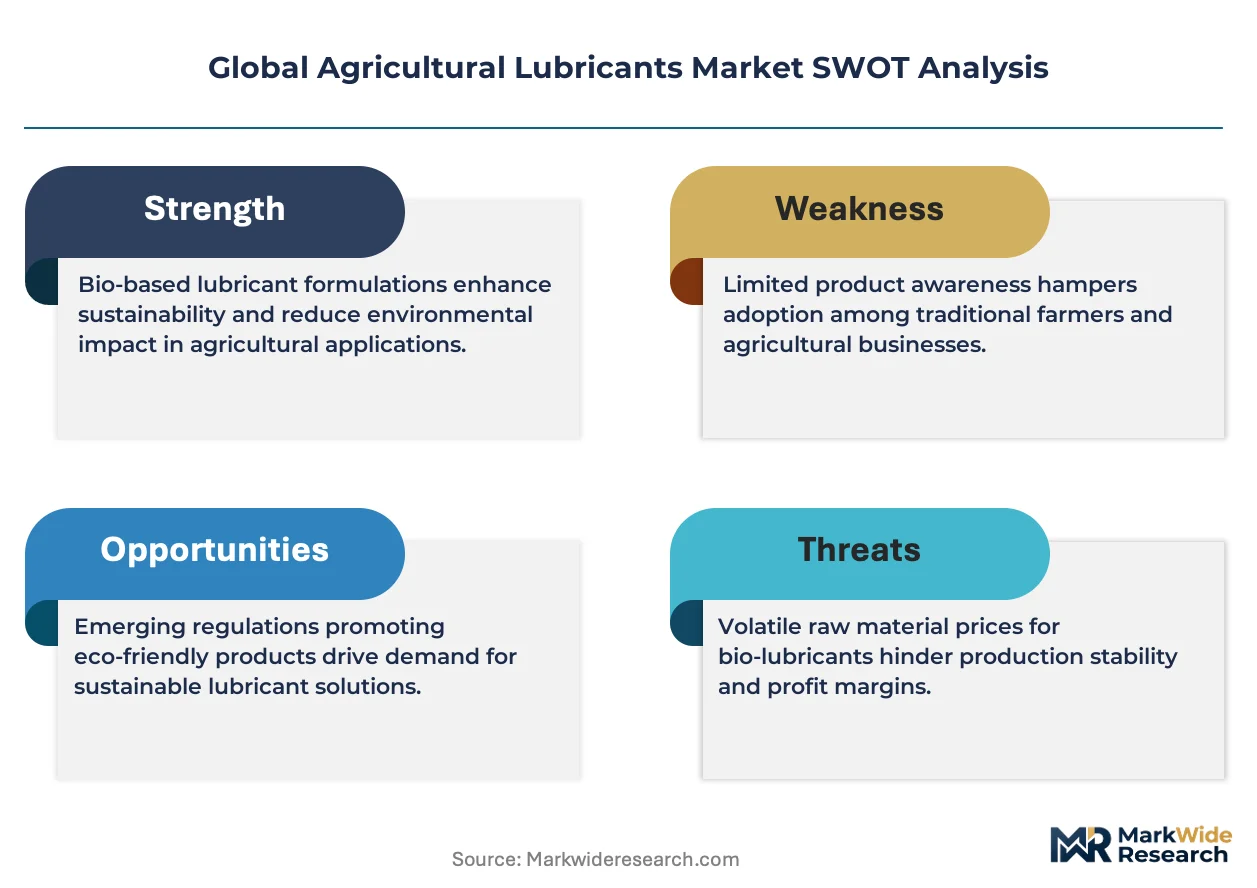
- Biodegradable base stocks:Vegetable-oil-derived formulations are capturing regulatory preference as EU Green Deal Farm to Fork requirements tighten discharge protocols.
Market Restraints
- Group II/III base oil supply concentration:Refinery capacity for high-purity feedstocks clusters in the US Gulf Coast and Northeast Asia, exposing buyers to freight-driven cost volatility.
- REACH substance registration timelines:European additive chemistry approvals stretch 18-24 months, delaying reformulation launches and freezing product line updates.
- Extended drain interval engineering:Synthetic formulations lasting 500+ hours between changes compress total addressable lubricant volume per machine.
Strategic Opportunities
- Precision irrigation hydraulics:Variable-rate sprinkler and drip systems require shear-stable hydraulic fluids with contamination tolerance specifications that command formulation premiums.
- EU Green Deal carbon-footprint disclosure:Lubricant suppliers publishing lifecycle emissions data gain preferred-supplier status with sustainability-audited agribusiness cooperatives.
- Drone application equipment:Compact electric-hybrid aerial sprayers create demand for lightweight, thermally conductive greases in motor and gearbox assemblies.
Industry Challenges
- Tribology specialization deficit:Field engineers capable of diagnosing lubricant-related failures in hydrostatic transmissions remain scarce relative to fleet expansion rates.
- OEM fluid specification fragmentation:Proprietary approvals from Deere, CNH, and AGCO require parallel certification tracks that extend product development timelines.
- Used-oil collection infrastructure gaps:Rural service territories lack reverse logistics density to support mandatory recycling quotas under state-level environmental codes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Agricultural Lubricants Market |
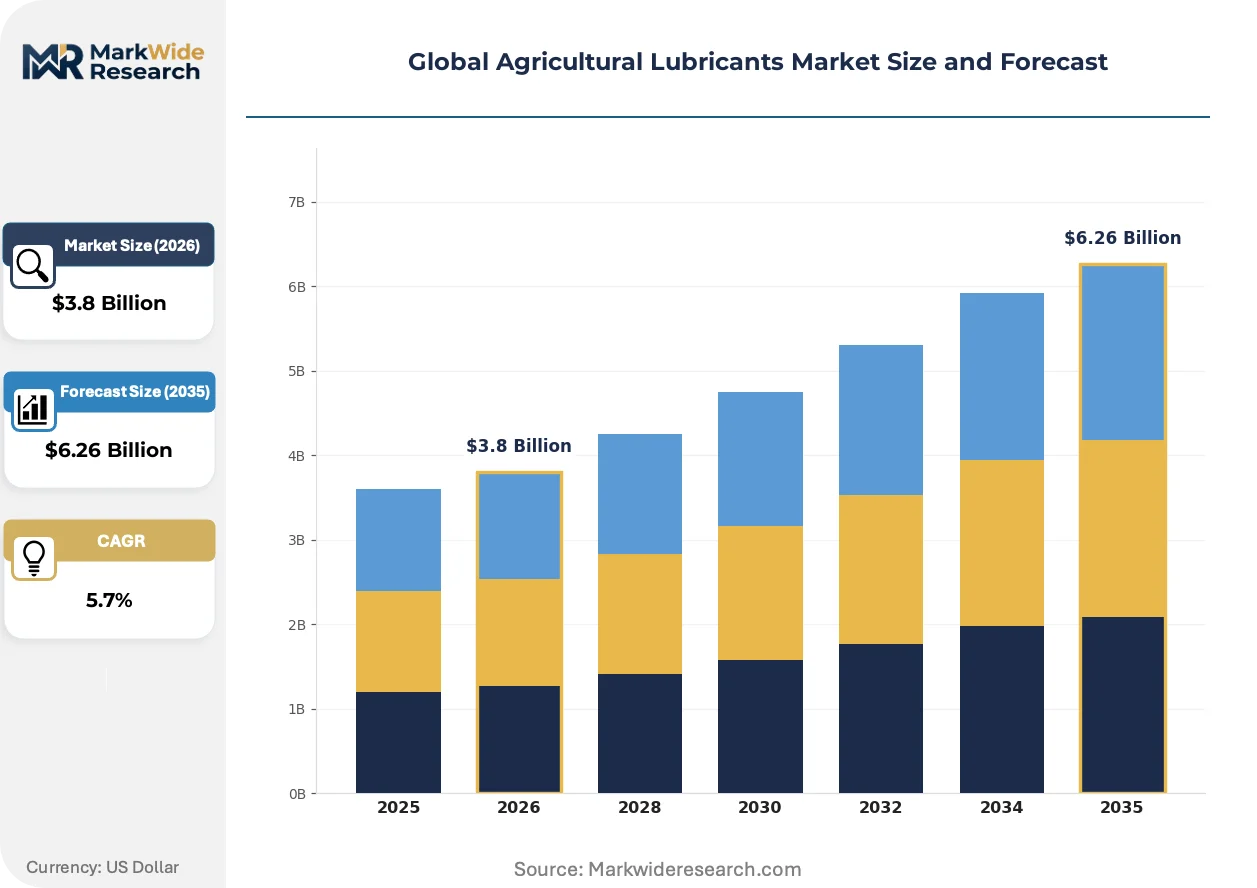
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oils, Gear Oils, Hydraulic Fluids, Greases Application: Tractors, Harvesters, Irrigation Systems, Implements Formulation: Synthetic, Mineral, Biodegradable, Semi-Synthetic Distribution Channel: Retail, Online, Direct Sales, Distributors |
| Companies Covered | Fuchs Petrolub, TotalEnergies, BP p.l.c., Frontier Performance Lubricants, Inc., Phillips 66, Chevron Corporation, Shell plc, Cougar Lubricants International Ltd., Exxon Mobil Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Agricultural Lubricants Market Emerging Trajectories
Formulation chemistry and procurement architecture are diverging simultaneously. Synthetic base stocks are displacing mineral oils in severe-duty applications while digital monitoring tools compress maintenance decision cycles.
Polyalphaolefin (PAO) and ester-based synthetic lubricants are penetrating high-load gearbox and hydraulic applications where thermal stability determines equipment uptime. Large-scale soybean and sugarcane operators in Brazil and the US Midwest are specifying these products for 1000-hour drain intervals. The technology is bifurcating the market between premium synthetics for continuous-duty fleets and commodity mineral oils for seasonal, lower-utilization machinery.
REACH substance restrictions and the EU Green Deal's carbon-border adjustment mechanisms are forcing reformulation of zinc-based anti-wear additives and certain pour-point depressants. Lubricant blenders serving European agricultural OEMs are accelerating substitution with ashless phosphorus chemistry and bio-derived viscosity modifiers. Hydraulic fluid portfolios face the most immediate compliance pressure due to higher discharge risk in open-field applications.
Cooperative procurement consortia are consolidating lubricant purchasing decisions across multi-thousand-hectare farming operations. These entities negotiate direct supply agreements with blenders, displacing traditional agricultural distributor networks that previously managed inventory and technical service. The shift is most pronounced in Brazil's Mato Grosso region and the US Corn Belt, where equipment fleet scale justifies dedicated bulk storage and on-site analysis capabilities.
Global Agricultural Lubricants Market Segmentation
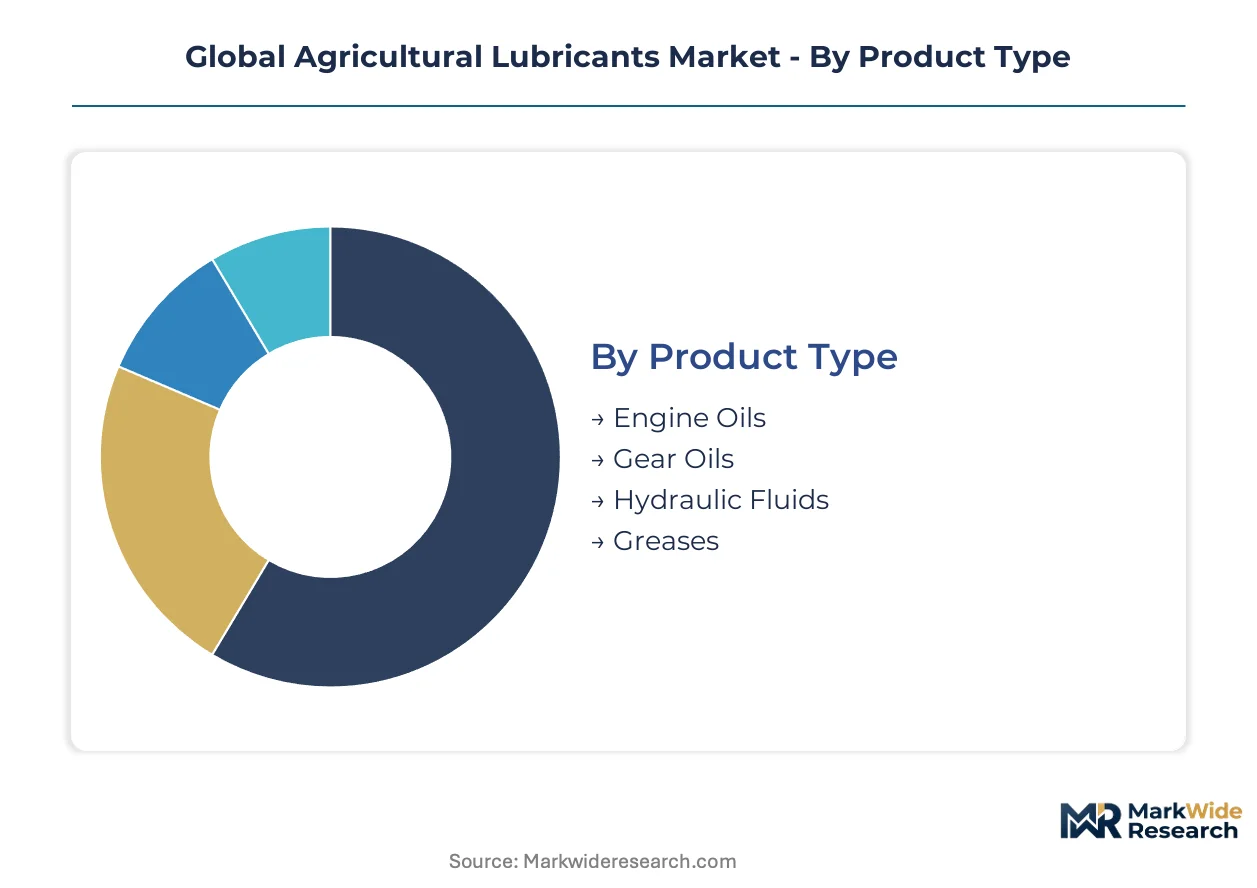
Segmentation in agricultural lubricants reveals how equipment specifications, regulatory pressure, and procurement scale reshape product mix and channel economics. Understanding these divides exposes where formulation premiums concentrate and where volume commoditization threatens margin.
Product Type:
Margin pools cluster in hydraulic fluids and high-performance engine oils where OEM specifications and severe-duty cycles justify formulation investment, while commodity gear oils and general-purpose greases compete on bulk pricing.
- Engine Oils:These lubricants protect tractor and harvester powertrains under high-load, thermally variable conditions with viscosity grades typically spanning SAE 15W-40 to 10W-30. Demand concentrates in Brazil's Mato Grosso soybean belt and the US Corn Belt where 500+ horsepower tractor fleets operate continuous-duty cycles. EPA Tier 4 Final standards are accelerating specification shifts toward lower-viscosity formulations that reduce fuel consumption.
- Hydraulic Fluids:Formulations engineered for shear stability and contamination tolerance in precision irrigation and modern planter hydraulics command the strongest price premiums. Demand clusters in California's Central Valley and São Paulo's sugarcane processing cooperatives where equipment uptime directly correlates with harvest economics. REACH substance restrictions are forcing rapid reformulation of zinc-based anti-wear additives.
- Gear Oils:High-viscosity lubricants for transmission and final drive protection in severe-duty applications.
- Greases:Lithium-complex and calcium-sulfonate thickened lubricants for chassis, bearings, and implement pivot points.
The dominant share belongs to Engine Oils, while Hydraulic Fluids is closing the gap fastest.
Application:
Equipment utilization intensity and fleet scale determine lubricant consumption velocity, with continuous-duty harvesters and irrigation systems outpacing seasonal implements in per-machine volume.
- Tractors:Universal deployment across all farming operations makes this the volume anchor, with large-scale contract farming operations in Brazil and the US Midwest driving bulk procurement consolidation. Engine oils dominate tractor lubricant portfolios, though hydrostatic transmission fluids gain share as continuously variable transmissions proliferate in high-horsepower models.
- Harvesters:Severe-duty cycles and seasonal intensity concentrate synthetic lubricant demand where 1000-hour drain intervals justify premium pricing. Sugarcane mechanization across Goiás and São Paulo states is expanding harvester fleets fastest.
- Irrigation Systems:Precision variable-rate sprinklers and drip systems require shear-stable hydraulic fluids with contamination tolerance specifications.
- Implements:Seasonal use patterns and lower utilization support commodity mineral oil and grease consumption.
Tractors retain the largest volume position, though Harvesters demonstrate the steepest expansion trajectory as mechanization intensifies in tropical agriculture.
Formulation:
Base stock chemistry separates premium synthetics commanding formulation premiums from commodity mineral oils competing on price, with biodegradable alternatives capturing regulatory preference in environmentally sensitive jurisdictions.
- Synthetic:PAO and ester-based formulations deliver thermal stability for 500-1000 hour drain intervals in severe-duty gearbox and hydraulic applications. Large-scale operators in Brazil and the US Midwest specify synthetics for continuous-duty fleets where equipment downtime costs exceed lubricant premiums.
- Biodegradable:Vegetable-oil-derived base stocks with ester modifications meet EU Green Deal Farm to Fork discharge protocols and ANVISA scrutiny on agricultural chemical runoff. Regulatory pressure in Europe and Brazil is accelerating substitution for open-field hydraulic applications with higher environmental exposure risk.
- Mineral:Group I/II base oil formulations dominate seasonal, lower-utilization machinery where drain intervals remain standard.
- Semi-Synthetic:Blended formulations balancing performance enhancement with cost containment for mid-tier equipment operators.
Mineral formulations hold the volume lead, while Biodegradable options are gaining share fastest as sustainability mandates tighten across European and Latin American supply chains.
Distribution Channel:
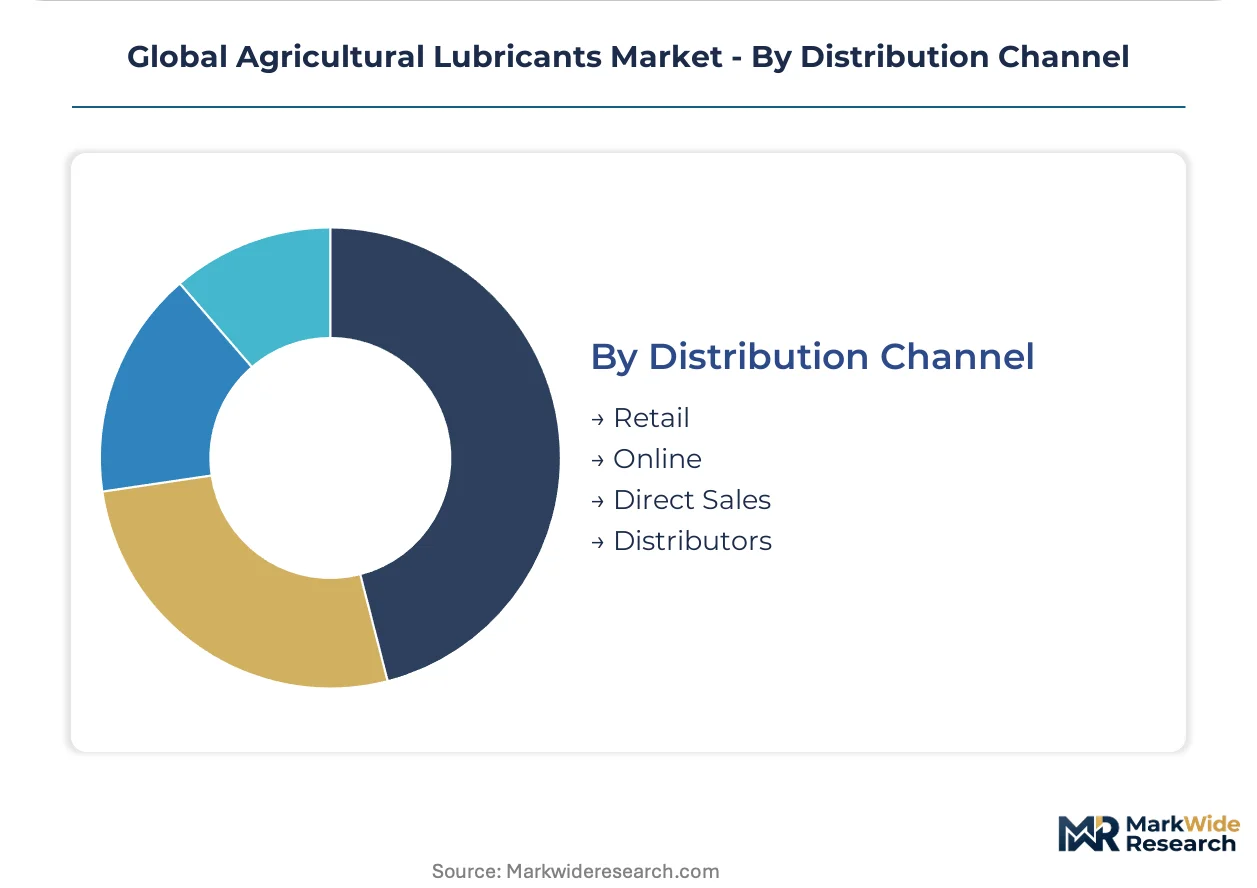
Procurement scale and technical service requirements determine channel selection, with large fleet operators bypassing traditional networks for direct supply relationships.
- Direct Sales:Cooperative procurement consortia and contract farming enterprises negotiate bulk supply agreements with blenders, displacing agricultural distributor networks. This channel concentrates in Brazil's Mato Grosso region and the US Corn Belt where multi-thousand-hectare operations justify dedicated bulk storage and on-site fluid analysis.
- Distributors:Traditional agricultural supply networks retain relevance for mid-scale operators requiring inventory management and field technical service.
- Retail:Farm supply stores and equipment dealerships serve smallholder and seasonal operators with immediate availability needs.
- Online:E-commerce platforms capture specification-transparent buyers with predictable maintenance schedules and established product loyalty.
Distributors maintain the broadest reach, while Direct Sales is expanding most quickly as procurement centralizes across large-scale agribusiness operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil exports refined lubricant formulations to neighboring Mercosur markets while sourcing base stock feedstocks from US Gulf Coast refineries. This trade corridor shapes procurement economics across Latin American agribusiness.
United States
EPA Tier 4 Final standards accelerate specification shifts toward lower-viscosity engine oils in 500+ horsepower tractor fleets across the Corn Belt. The USDA conservation programs indirectly influence lubricant selection through equipment upgrade incentives. Iowa and Illinois concentrate bulk procurement decisions among contract farming enterprises with dedicated on-site fluid analysis capabilities.
Brazil
Sugarcane mechanization across São Paulo and Goiás states drives concentrated bulk lubricant offtake from processing cooperatives with thousand-hectare fleet scales. ANVISA scrutiny on agricultural chemical runoff pressures selection toward biodegradable hydraulic alternatives. Mato Grosso soybean belt operators negotiate direct supply agreements that displace traditional distributor networks.
Germany
REACH substance restrictions force rapid reformulation of zinc-based anti-wear additives in hydraulic fluid portfolios serving precision agriculture OEMs. The EU Green Deal Farm to Fork strategy mandates carbon-footprint disclosure for preferred-supplier qualification. Bavaria's agricultural machinery clusters test ashless phosphorus chemistry in severe-duty gearbox applications.
India
Farm mechanization subsidies under the central government's agricultural modernization schemes expand tractor fleet penetration in Punjab and Haryana. BIS certification requirements for lubricant quality standards create compliance barriers for unorganized blenders. Gujarat's chemical manufacturing corridor supplies base stock intermediates to domestic formulators serving cooperative procurement networks.
China
Dual carbon goals and rural revitalization policies accelerate replacement of mineral oils with synthetic formulations in state-owned farm machinery fleets. The Ministry of Ecology and Environment tightens discharge protocols for open-field hydraulic applications. Shandong Peninsula lubricant blenders serve the North China Plain's expanding contract farming operations with extended-drain-interval products.
Global Agricultural Lubricants Market Vendor Landscape
Player mix skews toward integrated petroleum majors with captive base stock supply and specialized lubricant blenders with formulation expertise. Market structure concentrates around three to five global suppliers controlling bulk procurement relationships with large-scale agribusiness cooperatives. Strategic archetypes include integrated energy conglomerates with backward integration into base oil refining, independent lubricant specialists with OEM certification depth, and regional blenders with localized technical service capabilities. Dominant competitive moves span direct supply agreement negotiation with multi-thousand-hectare operators and accelerated biodegradable formulation development to capture regulatory preference in Europe and Brazil.
Within the integrated energy tier, Shell plc, Exxon Mobil Corporation, and Chevron Corporation exemplify archetypes distinguished by supply network scale and synthetic formulation depth. Shell leverages integrated infrastructure to sustain bulk delivery contracts across North and Latin America. Exxon Mobil anchors positioning through high-performance synthetic portfolios. Chevron differentiates via specialized hydraulic fluid ranges engineered for precision irrigation systems. These petroleum majors represent the competitive standard against which regional specialists and independent blenders position formulation customization and technical service responsiveness.
| Leading Market Players |
|---|
| Fuchs Petrolub |
| TotalEnergies |
| BP p.l.c. |
| Frontier Performance Lubricants, Inc. |
| Phillips 66 |
| Chevron Corporation |
| Shell plc |
| Cougar Lubricants International Ltd. |
| Exxon Mobil Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term bulk supply contracts with take-or-pay provisions lock in both base stock access and price predictability for large-scale Brazilian and US agribusiness cooperatives, insulating procurement teams from spot market volatility in Group II/III feedstocks while compressing margins for distributors excluded from direct blender relationships.
Pricing Analysis
Synthetic PAO and ester-based formulations command 40-60% premiums over mineral-base equivalents, while next-generation biodegradable hydraulic fluids with ashless phosphorus chemistry carry additional formulation premiums driven by REACH compliance costs. Three-tier pricing structure across premium synthetics, mid-tier semi-synthetics, and commodity mineral oils segments buyers by fleet utilization intensity. Cost compression in mineral-base engine oils intensifies as Brazilian and US contract farming operations consolidate procurement volume and negotiate direct supply agreements. Smallholder operators in India and China's fragmented farm sectors remain most price-sensitive, while Mato Grosso soybean processors and São Paulo sugarcane cooperatives prioritize uptime economics over unit lubricant cost.
Supply Chain Analysis
US Gulf Coast refinery capacity for high-purity Group II/III base stocks functions as a critical chokepoint, with Northeast Asian facilities providing secondary supply anchors for Asia-Pacific blenders. Formulation chemistry draws from vegetable oil esters, zinc-based and ashless anti-wear additives, and viscosity modifier polymers sourced through agricultural commodity and petrochemical channels. Single-source vulnerability concentrates in PAO base stock supply, where limited global producers expose premium synthetic blenders to allocation risk. Distribution runs through cooperative procurement consortia in Brazil and the US Corn Belt, bypassing traditional agricultural distributor networks for direct blender relationships with dedicated bulk storage and on-site fluid analysis.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from biodegradable formulations capturing regulatory preference under EU Green Deal Farm to Fork mandates and ANVISA scrutiny on agricultural chemical runoff, requiring defensive repositioning to sustain margin pools.
For Market Incumbents: Compound formulation expertise in ashless phosphorus chemistry and bio-derived base stocks to preempt REACH-driven specification shifts. Deepen backward integration into vegetable oil ester supply chains to secure feedstock access as Brazilian and European sustainability mandates tighten. Defend against regional blender encroachment by embedding technical service capabilities within Mato Grosso and US Corn Belt cooperative procurement networks. For New Entrants and Emerging Players: Differentiate on biodegradable hydraulic fluid portfolios targeting São Paulo sugarcane processing cooperatives and California Central Valley precision irrigation operators facing discharge protocol scrutiny. White-space concentration sits with mid-scale Brazilian operators in Goiás and Minas Gerais seeking technical service responsiveness absent from petroleum major direct sales models. Go-to-market execution should anchor in cooperative procurement consortium relationships rather than distributor channel penetration. For Investors and Strategic Acquirers: Independent lubricant specialists with OEM certification depth across Deere, CNH, and AGCO approval tracks present acquisition targets with defensive moats against petroleum major scale. Long-term viability hinges on reformulation agility as regulatory chemistry restrictions proliferate across European and Latin American jurisdictions. Watch for inflection signals in ANVISA enforcement intensity on agricultural chemical runoff and EU carbon-border adjustment mechanism implementation affecting lubricant lifecycle disclosure requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Formulation Development | Captures regulatory preference under EU Green Deal Farm to Fork and ANVISA discharge protocols in Brazil. |
| Direct Supply Agreement Negotiation | Bypasses distributor networks to secure bulk procurement relationships with Mato Grosso soybean cooperatives. |
| OEM Certification Investment | Secures proprietary fluid approvals from Deere, CNH, and AGCO that extend product development timelines for competitors. |
| Backward Integration into Base Stocks | Insulates margin from Group II/III feedstock freight volatility between US Gulf Coast and Latin American blenders. |
| Technical Service Embedding | Places tribology specialists on-site at large-scale operations to diagnose hydrostatic transmission failures and reduce downtime. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EPA enforcement databases, REACH substance registries, ANVISA agricultural chemical filings, and OEM technical service bulletins, combining interviews with lubricant blender procurement directors, agricultural cooperative fleet managers, and hydraulic systems engineers with customs trade data and SEC petroleum major segment disclosures. Bottom-up equipment fleet modeling across Brazil's Mato Grosso and São Paulo states, the US Corn Belt, and Germany's Bavaria machinery cluster triangulates against top-down lubricant consumption estimates derived from base stock import and production statistics.
Segmentation dimensions modeled span product type, application equipment category, base stock formulation chemistry, and distribution channel structure across the projection horizon. CAGRs derive from equipment penetration rates, fleet utilization intensity assumptions, and regulatory-driven specification shift timelines. Industry-specific inputs include harvester fleet expansion trajectories in Brazilian sugarcane regions and EPA Tier 4 Final compliance adoption curves in US high-horsepower tractor segments.
Decision-makers should treat outputs as directional under assumptions of sustained mechanization intensity in contract farming operations and stable REACH substance approval timelines; material deviation in Brazilian environmental enforcement or EU carbon-border adjustment implementation would warrant model refresh. Practitioners should keep alternative scenarios live as biodegradable formulation cost curves and base stock refinery capacity expansion plans evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Neat Cutting Oil Market
Lubricants
Yarn Lubricant Market
Lubricants
Heavy Equipment Lubricants Market
Lubricants
Food Grade Lubricant Market
Lubricants
Global Lubricant Antioxidants Market
Lubricants
Poland Industrial Lubricants Market
Lubricants
Lubrication Equipment Market
Lubricants
China Automotive Engine Oils Market
Lubricants
Hydraulic Oil Additives Market
Lubricants
Global Independent Lubricant Manufacturers Market
Lubricants
Japan Automotive Lubricants Market
Lubricants
Vietnam Automotive Lubricants Market
Lubricants
Global Lubricants Market
Lubricants
Singapore Automotive Lubricants Market
Lubricants
Bio-Based Lubricants Market
Lubricants
India Industrial Lubricants Market