
 North America & Europe Adhesives and Sealants Market | 2026-2036
North America & Europe Adhesives and Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
North America & Europe Adhesives and Sealants Market Analytics
Electric vehicle OEMs is bifurcating demand away from traditional automotive tiers toward battery pack and body-in-white specialists. Henkel AG & Co. KGaA leverages its polyurethane portfolio to dominate structural bonding for EV battery enclosures across German assembly plants. H.B. Fuller Company anchors its position in North American packaging hot melts through extensive channel control with corrugated converters. Sika AG specializes in reactive cementitious systems for European construction refurbishment, sustaining margin pools in renovation-driven markets.
Adhesives and sealants encompass formulated polymer systems engineered to bond, seal, or cushion substrates through surface adhesion and cohesive strength, with viscosities ranging from water-thin cyanoacrylates to paste-consistency epoxy gap fillers and cure mechanisms spanning moisture, heat, UV, or two-part catalytic initiation. Their primary industrial purpose centers on distributing mechanical loads across bonded areas, preventing fluid ingress, and enabling lightweight multi-material assemblies in transportation and building applications. Water-based acrylics lead volume in European decorative and DIY channels where REACH restrictions on solvent emissions have compressed solvent-based share, while reactive polyurethanes capture the fastest growth in North American automotive as OEMs pursue bonded aluminum-steel mixed-material body structures. Hot melt technology occupies mature, high-throughput packaging lines where speed and bond immediacy outweigh structural performance requirements.
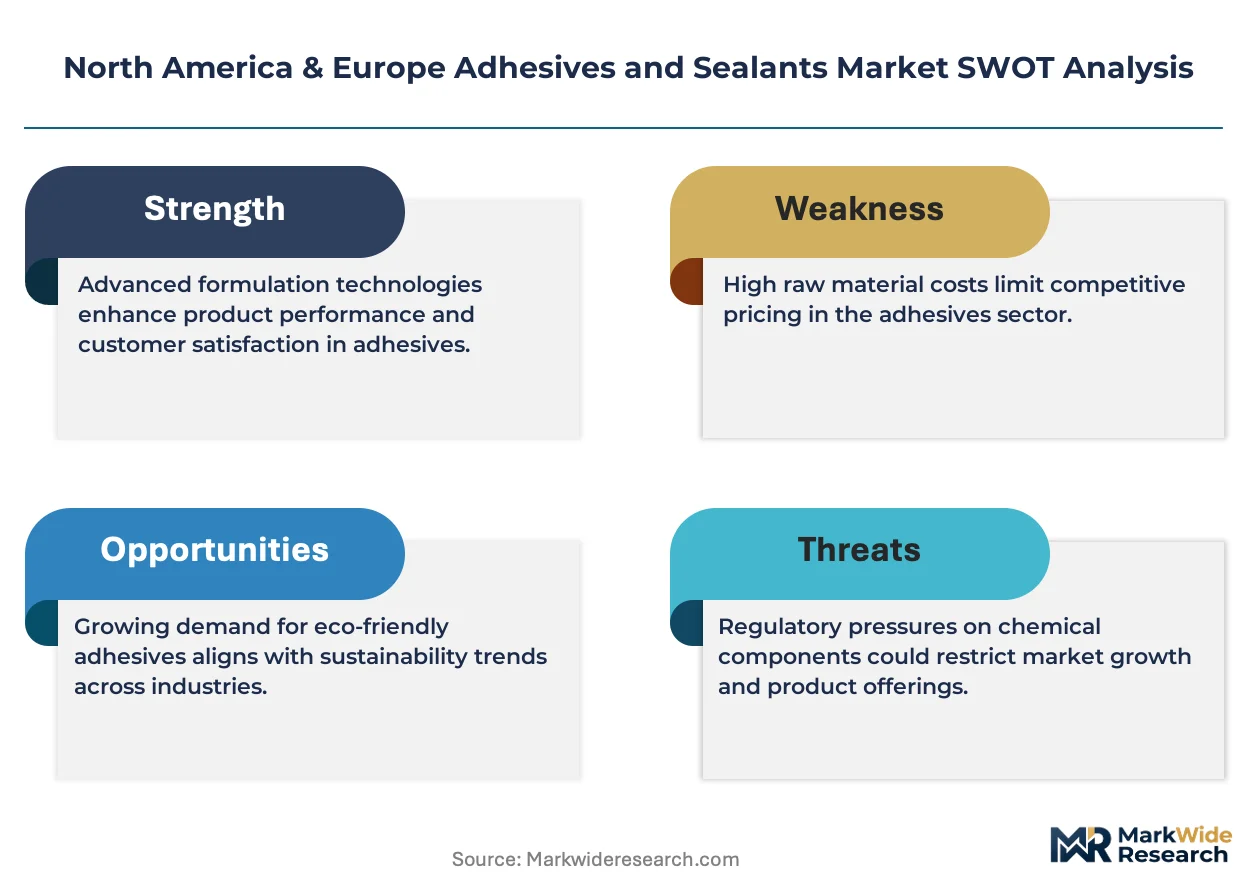
EPA VOC regulations in the United States and REACH in the European Union constrain solvent-based formulations, compelling producers to reformulate around water-based, hot melt, and reactive chemistries that reduce hazardous air pollutant emissions. The EU F-Gas Regulation and California Air Resources Board measures further restrict blowing agents and propellants in sealant delivery systems, reshaping product development priorities for suppliers serving both jurisdictions. Stakeholders must monitor diverging compliance timelines between U.S. state-level rules and EU harmonized standards when allocating R&D budgets and plant certification investments.
Market Dynamics
Automotive OEMs in Germany and Michigan are systematically replacing mechanical fasteners with bonded assembly lines, creating structural demand pull for reactive polyurethane systems across mixed-material vehicle architectures.
Growth Catalysts
- REACH solvent restrictions:European decorative and DIY channels have compressed solvent-based formulation share, redirecting volume toward water-based acrylics with compliant emission profiles.
- EV battery enclosure bonding:German assembly plants are scaling structural polyurethane applications for aluminum-steel battery pack housings, generating specialized demand outside traditional automotive tiers.
- Corrugated packaging throughput:North American hot melt systems capture volume in high-speed converting lines where bond immediacy outweighs structural performance requirements.
Market Restraints
- Petrochemical feedstock volatility:Polyol and isocyanate input costs fluctuate with crude oil indices, compressing margin stability for polyurethane formulators serving automotive contracts.
- Specialty additive concentration:Catalyst and rheology modifier supply concentrates among German and Swiss chemical suppliers, creating single-source vulnerability for North American compounders.
- Cure time limitations:Moisture-cured silicones face throughput constraints in high-volume assembly environments where line speed requirements exceed ambient humidity activation rates.
Strategic Opportunities
- Polish and Romanian construction refurbishment:EU renovation wave funding is accelerating reactive cementitious sealant demand in Eastern European markets with underpenetrated distribution infrastructure.
- UV-curable electronics potting:Convergence of LED curing systems with miniaturized component protection is opening specification opportunities in German automotive sensor manufacturing.
- California CARB compliance premiums:Low-VOC formulation mandates create pricing power for suppliers with pre-certified water-based systems ahead of federal EPA alignment.
Industry Challenges
- Formulation chemist scarcity:Reactive system expertise concentrates among aging technical workforces in German industrial clusters, constraining R&D expansion timelines.
- Dual certification complexity:Suppliers must simultaneously navigate EPA VOC timelines and EU F-Gas Regulation phase-down schedules, fragmenting product development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America & Europe Adhesives and Sealants Market |
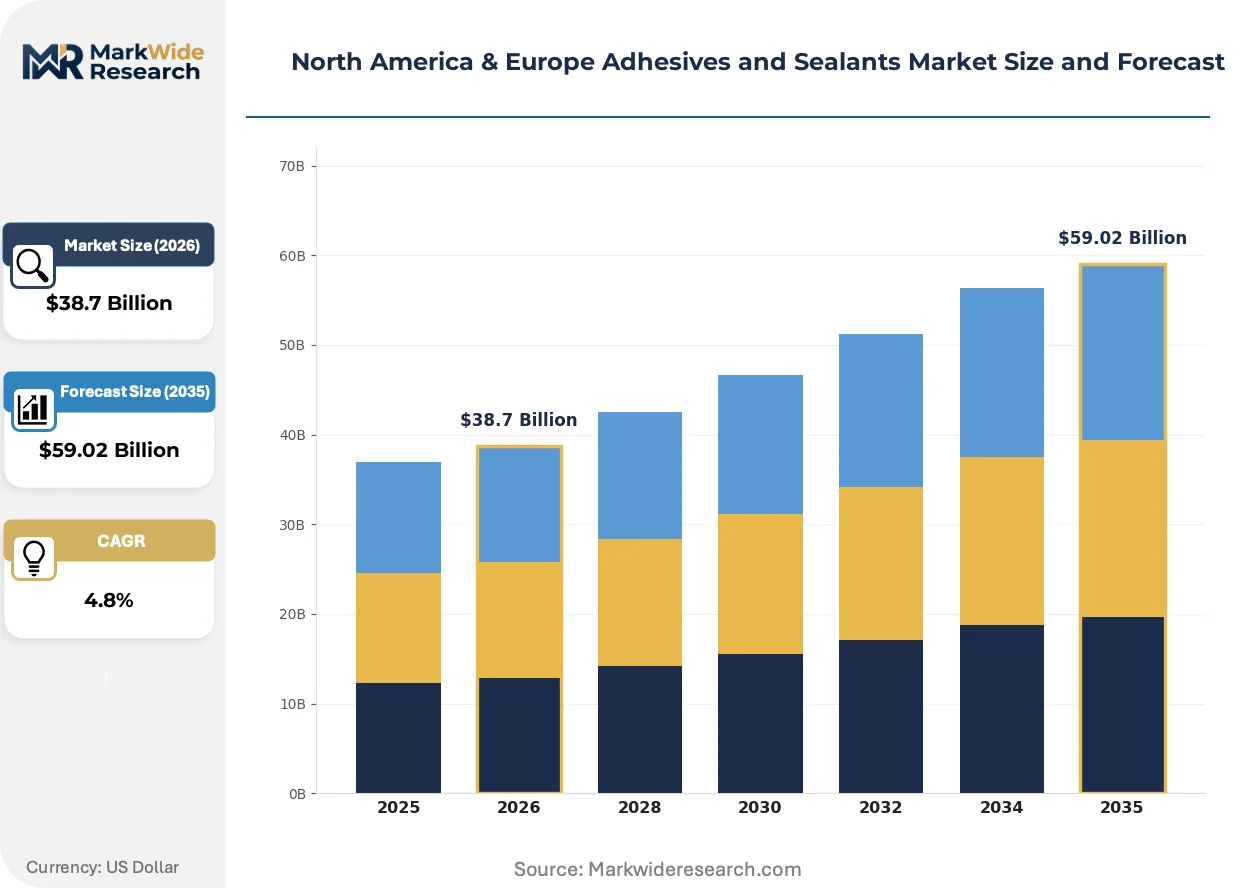
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, Reactive, Hot Melt End User: Construction, Automotive, Aerospace, Electronics Application: Packaging, Woodworking, Assembly, Repair Technology: Polyurethane, Epoxy, Silicone, Acrylic |
| Companies Covered | Henkel AG & Co. KGaA, H.B. Fuller Company, Arkema, Sika AG, 3M, Dow, Wacker Chemie AG, RPM International Inc., Avery Dennison Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America & Europe Adhesives and Sealants Market Evolving Landscape
Formulation chemistry is pivoting toward reactive and water-based systems as regulatory pressure compounds with automotive lightweighting requirements, compressing legacy solvent technologies across both continents.
Two-part epoxy structural adhesives are decomposing the traditional weld-bond hybrid approach in Michigan and Stuttgart body-in-white operations. EV manufacturers are specifying these systems for aluminum-intensive platforms at accelerating rates. This technology is decomposing established supply relationships between tier suppliers and mechanical fastener producers.
EPA VOC regulations and the EU F-Gas Regulation are synchronizing to eliminate hydrofluorocarbon propellants from sealant delivery systems by decade end. Industrial consequence includes forced reformulation of aerosolized construction sealants toward compressed gas or pumpable alternatives. North American architectural applications face compressed compliance timelines relative to European harmonized standards, advantaging suppliers with cross-certified platforms.
Specification authority is migrating from general contractors to OEM engineering departments in automotive and battery manufacturing verticals. Traditional distribution through construction-focused merchants is losing share to direct technical sales engagement with German and Michigan manufacturing engineering teams. This pattern concentrates most visibly in EV battery enclosure procurement, where bonding specifications are locked at platform design phase rather than construction execution.
North America & Europe Adhesives and Sealants Market Segmentation
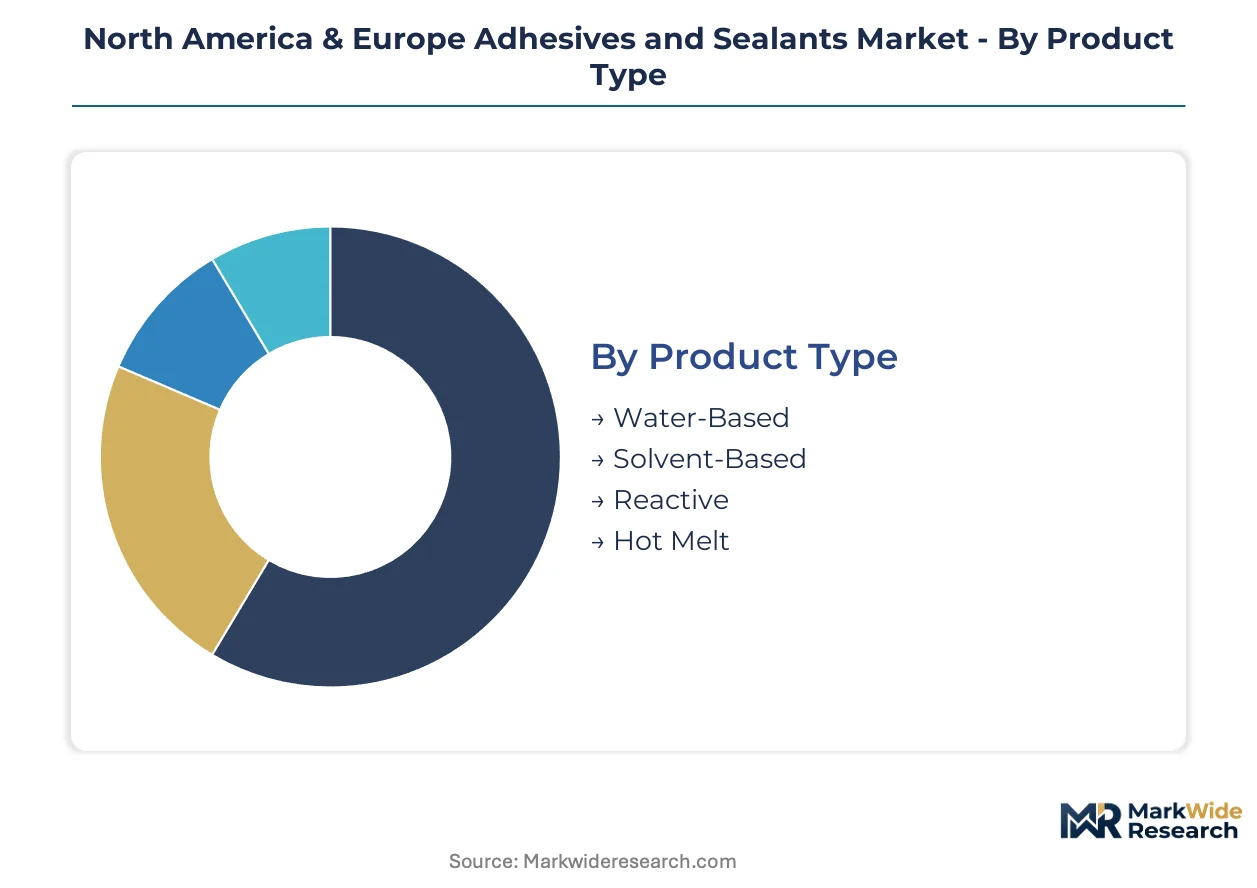
Segmentation in this market tracks how regulatory pressure and automotive electrification are reallocating demand across chemistry types and application methods. Understanding these divides reveals where formulation investments generate compliance advantage versus where mature technologies defend volume.
Product Type:
REACH solvent restrictions and EPA VOC regulations have fragmented competitive position across chemistry platforms, advantaging compliant systems in specification-driven verticals.
- Water-Based:Acrylic dispersions dominate European decorative channels where ECHA emission limits have eliminated solvent alternatives. German DIY retailers now specify water-based systems exclusively for interior applications, compressing legacy product shelf space.
- Reactive:Two-part polyurethanes and epoxies capture specification authority in Stuttgart and Detroit EV battery enclosures, where structural load distribution requirements exceed mechanical fastener capabilities. Cure-on-demand chemistry enables aluminum-steel mixed-material bonding.
- Solvent-Based:Declining share in regulated jurisdictions; residual demand concentrates in specialized industrial maintenance where rapid tack and solvent resistance justify compliance costs.
- Hot Melt:Ethylene-vinyl acetate and metallocene polyolefin systems anchor North American corrugated packaging throughput, where line speeds exceed 500 feet per minute and bond immediacy outweighs structural performance.
Water-Based handles the majority of throughput; Reactive is the fastest mover on share.
End User:
Procurement authority is migrating toward engineering departments in transportation verticals, displacing traditional construction-merchant distribution in high-value applications.
- Automotive:Michigan and German OEMs are specifying structural adhesives at platform design phase for body-in-white and battery pack assembly, locking in chemistry decisions years before production. Bonded mixed-material architectures now outpace welded alternatives in EV platforms.
- Construction:EU renovation wave funding is accelerating reactive cementitious sealant demand in Polish and Romanian refurbishment markets, where thermal envelope upgrades require compliant joint sealing systems.
- Electronics:German automotive sensor manufacturers are adopting UV-curable potting compounds for miniaturized component protection, converging with LED curing system advances.
- Aerospace:Structural film adhesives maintain specification in legacy programs; qualification timelines constrain new chemistry adoption despite lightweighting pressure.
Construction retains the largest installed base; Automotive is climbing the fastest on specification value.
Application:
Speed-to-bond requirements separate high-throughput industrial applications from precision assembly environments where cure control dominates equipment selection.
- Packaging:North American corrugated converters deploy hot melt systems in continuous web operations where open time and set speed determine line efficiency. Case and carton sealing volume concentrates with multi-plant operators.
- Assembly:EV battery enclosure bonding in German plants demands robotic dispensing of two-part polyurethanes with precision gap control and thermal conductivity management.
- Woodworking:European furniture manufacturers balance water-based PVA cost position against reactive PUR durability for edgebanding and lamination applications.
- Repair:Construction maintenance channels favor moisture-cured silicones and hybrid polymers for facade joint remediation, constrained by ambient humidity activation rates in seasonal climates.
Packaging generates the highest unit volume; Assembly is gaining share fastest on EV platform proliferation.
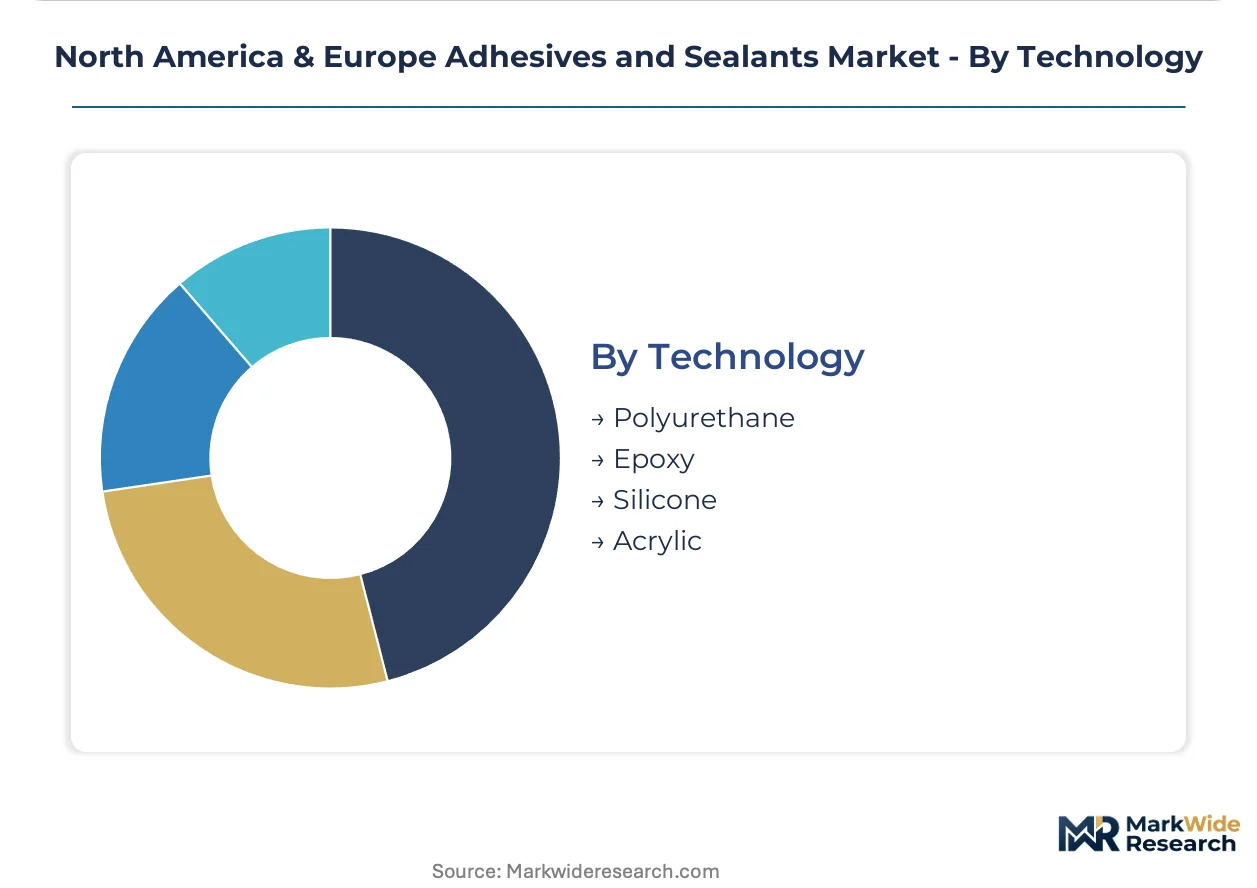
Technology:
Polymer backbone selection determines regulatory compliance trajectory and performance ceiling across substrate combinations.
- Polyurethane:Dominant structural chemistry for automotive lightweighting, spanning flexible foam bonding to rigid composite assembly. German formulators lead in low-VOC, high-modulus systems for crash-resistant applications.
- Epoxy:Two-part systems decompose traditional weld-bond hybrid approaches in Michigan body shops, specified for aluminum-intensive platforms where galvanic corrosion prevention is critical.
- Silicone:Moisture-cure and addition-cure formulations serve construction glazing and automotive gasketing; F-Gas Regulation restrictions on propellants are forcing delivery system reformulation.
- Acrylic:Water-based dispersions lead European decorative coatings; UV-curable variants penetrate German electronics potting as LED curing capital costs decline.
Polyurethane commands the deepest specification penetration; Epoxy is expanding most quickly on mixed-material vehicle architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German adhesive formulators export structural polyurethane systems to Michigan and Stuttgart automotive assembly corridors, while water-based acrylic shipments from the Netherlands serve French and British decorative channels under REACH compliance deadlines.
Germany
EV battery enclosure bonding and body-in-white mixed-material assembly dominate demand pull. REACH solvent restrictions enforced by ECHA redirect decorative formulation toward water-based acrylics. Stuttgart and Wolfsburg assembly plants scale robotic dispensing of two-part polyurethanes for aluminum-steel architectures.
United States
Michigan OEMs specify structural adhesives at platform design phase for electrified vehicle lines. EPA VOC regulations compress solvent-based share in architectural applications. Detroit-Warren corridor facilities bond aluminum-intensive platforms faster than traditional weld-bond hybrid approaches.
France
Construction refurbishment drives reactive cementitious sealant demand through EU renovation wave funding. ECHA emission limits eliminate solvent-based alternatives in interior DIY channels. Paris and Lyon distribution networks consolidate water-based acrylic shelf space exclusively.
Poland
Thermal envelope upgrades accelerate compliant joint sealing specification in residential refurbishment. EU F-Gas Regulation restricts propellant delivery systems for aerosolized construction sealants. Warsaw and Krakow merchant channels underpenetrate reactive cementitious distribution infrastructure.
United Kingdom
Packaging hot melts capture volume in corrugated converting lines serving FMCG export demand. REACH alignment pressures retain solvent-based compression in decorative coatings. Midlands industrial clusters deploy ethylene-vinyl acetate systems in continuous web operations exceeding 500 feet per minute.
North America & Europe Adhesives and Sealants Market Competitive Landscape
Player mix skews toward diversified chemical conglomerates with cross-regional formulation portfolios. Market structure concentrates specification authority among German and Swiss suppliers serving automotive engineering departments. Three archetypes dominate: polyurethane structural specialists, water-based acrylic volume leaders, and hot melt packaging incumbents. Competitive moves center on direct technical sales engagement with OEM engineering teams and backward integration into specialty additive supply.
Among German-based diversified chemical suppliers, Henkel AG & Co. KGaA and Wacker Chemie AG occupy positions within the reactive systems tier, while H.B. Fuller Company represents the North American packaging adhesive archetype. These three exemplify how geographic clustering around industrial corridors shapes competitive positioning.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| H.B. Fuller Company |
| Arkema |
| Sika AG |
| 3M |
| Dow |
| Wacker Chemie AG |
| RPM International Inc. |
| Avery Dennison Corporation |
| Others |
Value Network & Pricing Analysis
Ninety-day polyol inventory cycles in German chemical clusters concentrate pricing power among formulators with captive isocyanate supply, while REACH compliance investments compress margin pools for spot-market-dependent compounders serving automotive OEMs in Stuttgart and Detroit.
Pricing Analysis
Reactive polyurethane systems command substantial premiums over water-based acrylics and hot melt alternatives, with price stratification across premium structural grades, standard industrial formulations, and economy packaging tiers. Price differentiation hinges on REACH certification status and volume scale, with German automotive OEMs showing lowest sensitivity due to platform-locked specifications. Pricing pressure stems from petrochemical feedstock volatility, while North American corrugated converters exhibit highest price sensitivity in high-throughput packaging applications.
Supply Chain Analysis
Inventory concentration in German and Swiss chemical corridors creates lead-time vulnerability for North American compounders sourcing specialty catalysts and rheology modifiers. Raw material dependencies center on crude oil-derived polyols, aromatic isocyanates, and silicone precursors. Single-source concentration among German additive suppliers generates structural risk for cross-Atlantic formulators. Distribution runs through direct technical sales to OEM engineering departments, displacing traditional merchant channels in high-value automotive applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of reactive system chemists in German industrial clusters constrains R&D expansion timelines, making formulation expertise the scarcest capability across the North American and European footprint.
For Market Incumbents: Fortify backward integration into specialty additive supply to offset single-source vulnerability from German and Swiss chemical suppliers. Expand technical sales presence in Michigan and Stuttgart automotive corridors before specification authority fully migrates to OEM engineering departments. Prioritize dual EPA-REACH certification investments to capture compliance premiums in California and EU renovation wave markets.
For New Entrants and Emerging Players: REACH fast-track certification for water-based acrylic systems opens shelf space in French and British DIY channels where ECHA emission limits have eliminated solvent alternatives. Target Polish and Romanian construction refurbishment markets with reactive cementitious sealants, exploiting underpenetrated distribution infrastructure in Warsaw and Krakow merchant channels. Lead with EU renovation wave funding alignment as the primary go-to-market angle.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because specification authority concentration among German polyurethane specialists and North American packaging adhesive incumbents favors scaled platforms with cross-regional compliance capabilities. Acquisition targets should display captive additive supply or direct OEM technical relationships. The signal to watch is EV platform bonding specification migration from tier suppliers to OEM engineering departments.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Additives | Captive catalyst supply insulates margin stability from German single-source concentration risk. |
| Dual EPA-REACH Certification Investment | Pre-certified platforms capture California CARB premiums ahead of federal alignment. |
| Direct Technical Sales Expansion | OEM engineering engagement locks specifications at platform design phase in Stuttgart and Detroit. |
| Polish Distribution Infrastructure Buildout | EU renovation wave funding accelerates reactive cementitious penetration in underpenetrated channels. |
| UV-Curable Electronics Potting Development | LED curing convergence opens German automotive sensor manufacturing specifications. |
Research Methodology
Initial hypotheses were tested against primary input from adhesive formulators, automotive OEM procurement leads, construction merchant buyers, and regulatory affairs directors, then refined through secondary validation against ECHA REACH filings, EPA VOC regulatory dockets, Cefic industry statistics, and customs trade data. Bottom-up volume estimates from plant-level capacity assessments were triangulated with top-down demand modeling across end-use segments.
Variance decomposition across chemistry type, end-use vertical, application method, and regional production hub informed the analytical framework throughout the projection horizon. CAGRs were derived from segment-level demand elasticity modeling and input cost trajectory assumptions. Industry-specific forecast inputs included EV platform proliferation rates and EU renovation wave funding disbursement patterns.
Decision-makers should treat outputs as directional under stable petrochemical feedstock pricing and sustained regulatory enforcement timelines; material deviation would warrant model refresh. Revision becomes warranted when polyol-isocyanate cost spreads or REACH compliance timeline acceleration crosses thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Craft Glue Market
Adhesives & Sealants
Polyurethane Adhesives and Sealants Market
Adhesives & Sealants
Polyurethane (PU) Adhesives Market
Adhesives & Sealants
Adhesive Dispensing Systems Market
Adhesives & Sealants
Asia-Pacific Reactive Adhesives Market
Adhesives & Sealants
Gasket and Seal Material Market
Adhesives & Sealants
Russia Adhesives Market
Adhesives & Sealants
Flexible Packaging Adhesive Market
Adhesives & Sealants
Asia-Pacific Hot-Melt Adhesives Market
Adhesives & Sealants
Global Bone Glue Market
Adhesives & Sealants
Nigeria Tile Adhesive Market
Adhesives & Sealants
Amine Curing Agents Market
Adhesives & Sealants
Global Lithium Ion Battery Binders Market
Adhesives & Sealants
Latin America Adhesives and Sealants Market
Adhesives & Sealants
Tile and Stone Adhesive Market
Adhesives & Sealants
Global Dimer Acid Market