
 South America Electronics Adhesives Market | 2026-2036
South America Electronics Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
South America Electronics Adhesives Market Analytics
Consolidation among Brazilian smartphone and automotive electronics OEMs is repositioning procurement leverage toward volume buyers with technical specification authority. Henkel AG & Co. KGaA leverages its São Paulo technical center to anchor formulation support for local EMS providers. Dow competes through silicone adhesive portfolios optimized for high-humidity operating environments across the Amazon basin. H.B. Fuller Company specializes in pressure-sensitive adhesives for flexible circuit applications serving Argentina's growing medical device sector.
Electronics adhesives are polymer-based bonding systems formulated with viscosities ranging from 500 to 50,000 cP, cured through thermal activation or UV exposure to achieve dielectric strengths exceeding 20 kV/mm, serving primarily to secure components, dissipate heat, and protect sensitive circuitry from mechanical stress and environmental ingress. Epoxy formulations dominate structural bonding in automotive assemblies due to established supply chains and processing familiarity, while UV-curing technology captures expanding share in consumer electronics where line-speed throughput determines manufacturing economics. Conductive adhesives represent the fastest-growing technology segment as silver-filled systems displace solder in temperature-sensitive medical device assemblies across the region.
ANVISA in Brazil enforces biocompatibility standards for adhesives contacting patient-facing medical electronics, while Argentina's national chemical regulator mandates substance registration consistent with Mercosur harmonization protocols. REACH-equivalent substance restrictions through Mercosur's developing regulatory framework are forcing reformulation away from legacy brominated flame retardants toward phosphorus-based alternatives. Stakeholders must monitor regulatory divergence between Brazilian state-level environmental enforcement and federal chemical policy to anticipate compliance cost allocation across their South American manufacturing footprints.
Market Dynamics
Consolidation among Brazilian smartphone and automotive electronics OEMs is repositioning procurement leverage toward volume buyers with technical specification authority, compressing margin structures for mid-tier adhesive suppliers across the São Paulo-Campinas industrial corridor.
Growth Catalysts
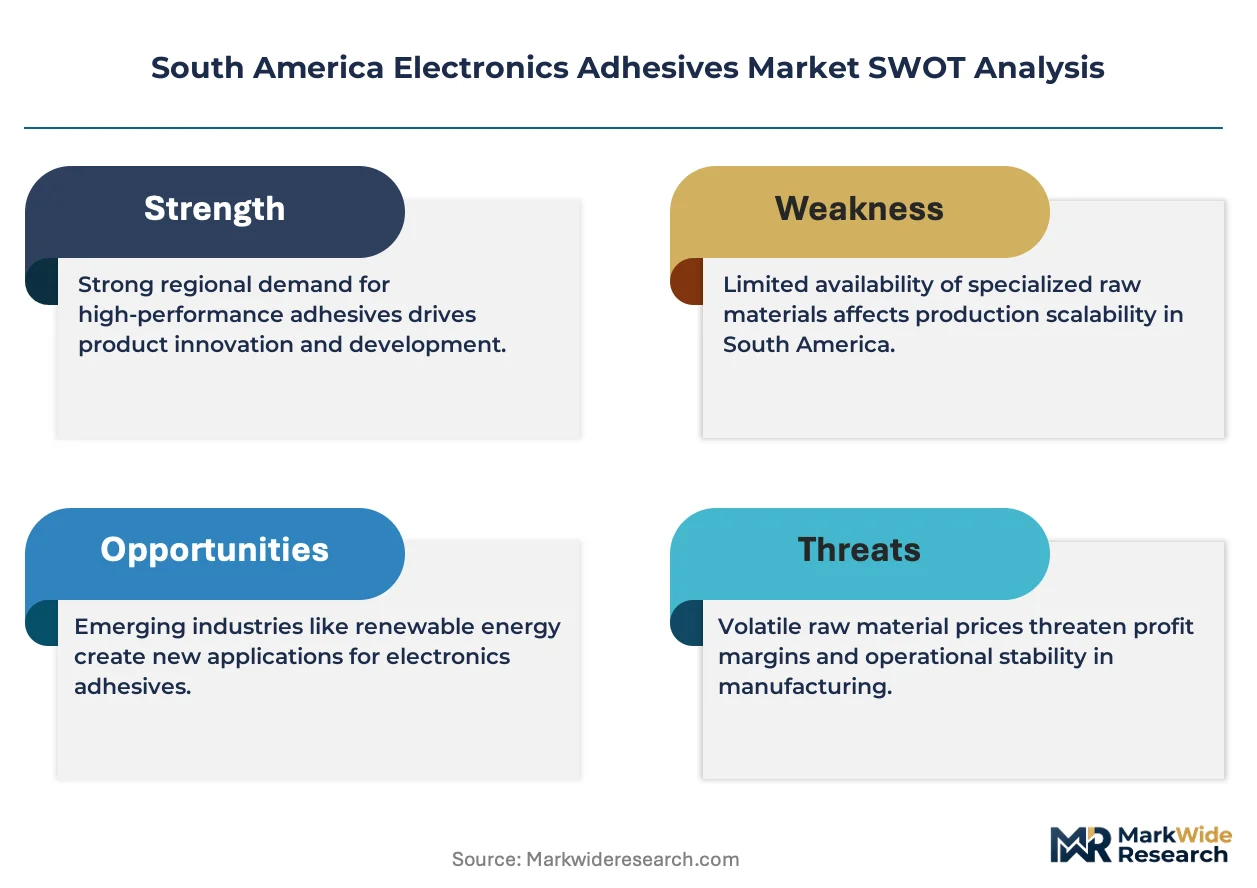
- Mercosur REACH-equivalent frameworks:ANVISA biocompatibility standards for patient-facing medical electronics in Brazil are accelerating halogen-free epoxy adoption among formulators seeking preemptive compliance positioning.
- Wearable device miniaturization:Smartphone and wearable manufacturers in Brazil are expanding adhesive procurement for miniaturized circuit assemblies requiring dielectric strengths exceeding 20 kV/mm.
- Silver-filled conductive systems:Temperature-sensitive medical device assemblies across Argentina's Córdoba electronics cluster are displacing solder with conductive adhesives in precision bonding applications.
Market Restraints
- Silver price volatility:Conductive adhesive formulators face input cost instability from silver-filled systems comprising the fastest-growing technology segment.
- Regulatory divergence friction:Brazilian state-level environmental enforcement creates compliance cost allocation uncertainty against federal chemical policy under ANVISA jurisdiction.
- Established epoxy supply chains:Automotive OEMs exhibit processing familiarity lock-in with legacy epoxy formulations, slowing UV-curing technology penetration despite throughput advantages.
Strategic Opportunities
- Argentina medical device expansion:Pressure-sensitive adhesive demand for flexible circuit applications in Córdoba's growing medical device sector remains underpenetrated relative to Brazilian volumes.
- Amazon basin humidity specialization:Silicone adhesive portfolios optimized for high-humidity operating environments address an underserved technical specification gap across northern Brazil.
- Phosphorus-based flame retardant convergence:Mercosur harmonization protocols on substance registration create formulation standardization tailwinds for brominated flame retardant alternatives.
Industry Challenges
- Formulation chemistry expertise scarcity:Local EMS providers in Brazil lack technical personnel capable of specifying dielectric strength and viscosity parameters for miniaturized assemblies.
- Dual certification timelines:Medical electronics adhesives require simultaneous ANVISA biocompatibility clearance and Mercosur substance registration, extending product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Electronics Adhesives Market |
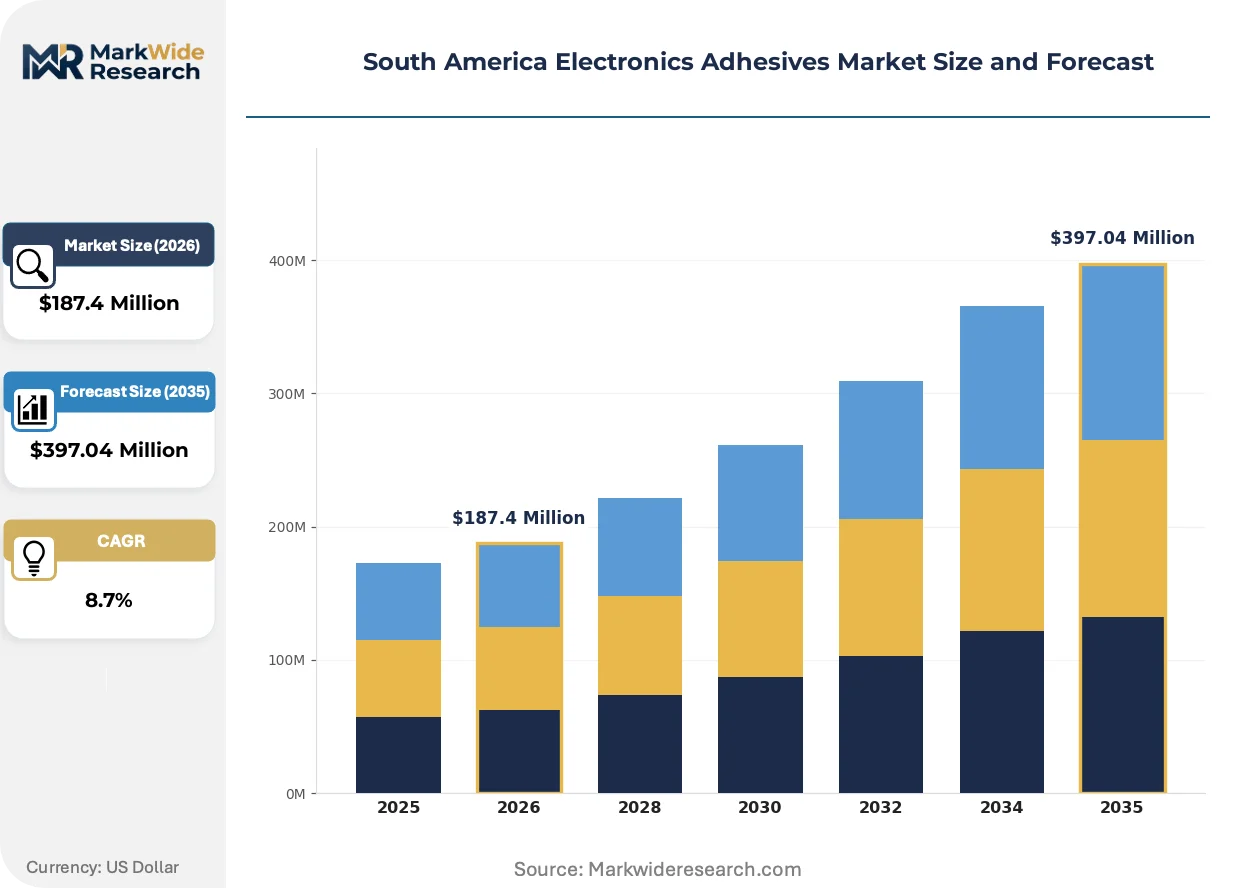
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Acrylic, Silicone, Polyurethane Application: Consumer Electronics, Automotive Assemblies, Industrial Equipment, Medical Devices Technology: UV-Curing, Thermal Curing, Pressure Sensitive, Conductive End User: Manufacturers, OEMs, R&D Institutions, Aftermarket Providers |
| Companies Covered | Henkel AG & Co. KGaA, 3M, Dow, H.B. Fuller Company, BASF SE, Sika AG, Avery Dennison Corporation, Huntsman International LLC, Ashland, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Electronics Adhesives Market Evolving Landscape
Active reformulation away from legacy chemistries is compressing product development cycles while opening technical specification gaps between established automotive suppliers and emerging medical device entrants.
UV-curing adhesive technology is consolidating its position in consumer electronics manufacturing by enabling line-speed throughput economics that thermal-cure epoxies cannot match. Brazilian smartphone OEMs in the São Paulo corridor are adopting UV systems at accelerating rates for display bonding and component encapsulation. This consolidation is compressing batch-processing equipment installed bases and favoring continuous-flow capital investments among contract manufacturers.
ANVISA biocompatibility standards for adhesives contacting patient-facing medical electronics are forcing reformulation investments across Brazilian medical device supply chains. The industrial consequence is a bifurcation between general industrial adhesive portfolios and certified medical-grade product lines with separate supply chain documentation. Argentina's national chemical regulator under Mercosur harmonization protocols is adopting comparable substance registration requirements, extending compliance burdens across the southern cone.
Buyer concentration among consolidated Brazilian smartphone and automotive OEMs is compressing supplier negotiation cycles and elevating technical specification authority toward procurement departments with embedded materials engineering functions. Direct supplier relationships are displacing distributor intermediaries for volume adhesive purchases in São Paulo state. This pattern is most visible in consumer electronics assembly where line-down risk penalties have shifted sourcing accountability from plant-floor technicians to centralized procurement teams with formulation veto power.
South America Electronics Adhesives Market Segmentation
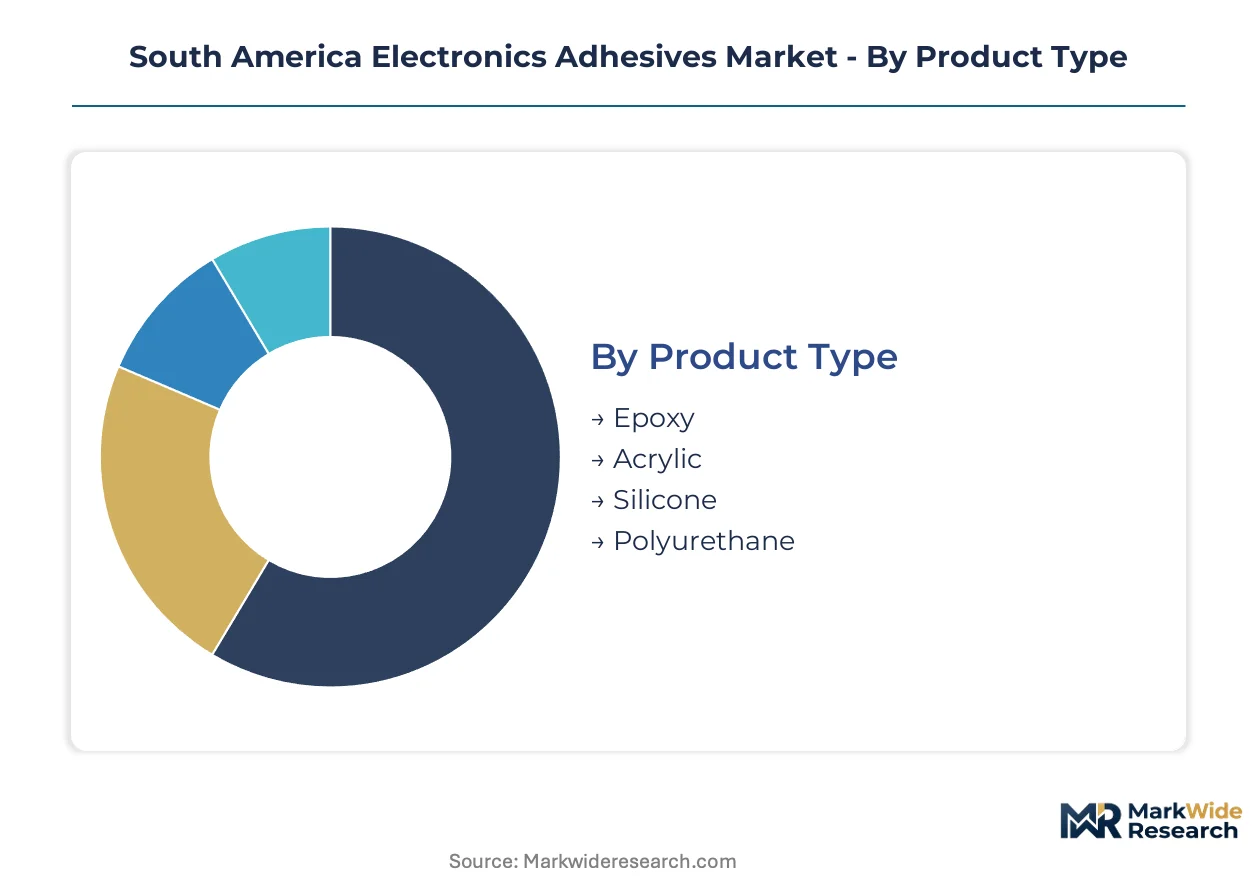
Electronics adhesives in South America fragment across four critical dimensions that determine procurement patterns and margin structures. Product chemistry dictates performance ceilings in Brazil's humidity-stressed environments, while application mix shifts with automotive electronics consolidation and medical device regulatory expansion.
Product Type:
Volume concentrates in commodity epoxy formulations, while premium pricing attaches to specialized silicone and conductive systems serving medical and automotive specifications.
- Epoxy:Dominant chemistry for structural bonding in automotive assemblies with established supply chains from São Paulo to Campinas. Brazilian OEMs exhibit processing familiarity lock-in that slows displacement despite thermal-cure cycle limitations.
- Silicone:Optimized for high-humidity operating environments across the Amazon basin, addressing dielectric stability requirements where epoxies degrade. Northern Brazil's industrial expansion is expanding specification demand for moisture-resistant formulations.
- Acrylic:Pressure-sensitive variants serve flexible circuit applications in Argentina's Córdoba medical device cluster with rapid room-temperature bonding.
- Polyurethane:Flexible encapsulation systems for wearable device miniaturization requiring mechanical stress absorption in Brazilian consumer electronics.
Today's leader: Epoxy. Tomorrow's challenger: Silicone.
Application:
Automotive and consumer electronics absorb the majority of procurement volume, though medical devices command the steepest expansion trajectory on regulatory tailwinds.
- Consumer Electronics:Brazilian smartphone manufacturers in the São Paulo corridor drive UV-curing adhesive adoption for display bonding and component encapsulation where line-speed throughput determines manufacturing economics.
- Automotive Assemblies:Structural bonding for electronic control units and sensor modules with established epoxy supply chains and processing familiarity across Brazil's industrial corridor.
- Industrial Equipment:Heavy-duty thermal interface materials for power electronics in mining and energy infrastructure across Chile and Peru.
- Medical Devices:ANVISA biocompatibility standards for patient-facing electronics are forcing reformulation investments and bifurcating supply chains between general industrial and certified medical-grade product lines.
Procurement volume peaks in automotive; regulatory premium concentrates in medical.
Technology:
Cure mechanism selection hinges on throughput requirements versus thermal sensitivity of bonded components, with UV systems gaining ground on batch-processing economics.
- UV-Curing:Consolidating position in consumer electronics manufacturing by enabling line-speed throughput that thermal-cure epoxies cannot match. Brazilian smartphone OEMs are adopting these systems at accelerating rates.
- Thermal Curing:Established automotive standard with familiar processing parameters, though cycle times create throughput disadvantages against UV alternatives.
- Pressure Sensitive:H.B. Fuller's specialization for flexible circuit applications serving Argentina's growing medical device sector with repositionable bonding.
- Conductive:Silver-filled systems displacing solder in temperature-sensitive medical device assemblies across Argentina's Córdoba electronics cluster, climbing the fastest on miniaturization demands.
UV-curing captures share in consumer electronics; conductive adhesives expand in medical precision bonding.
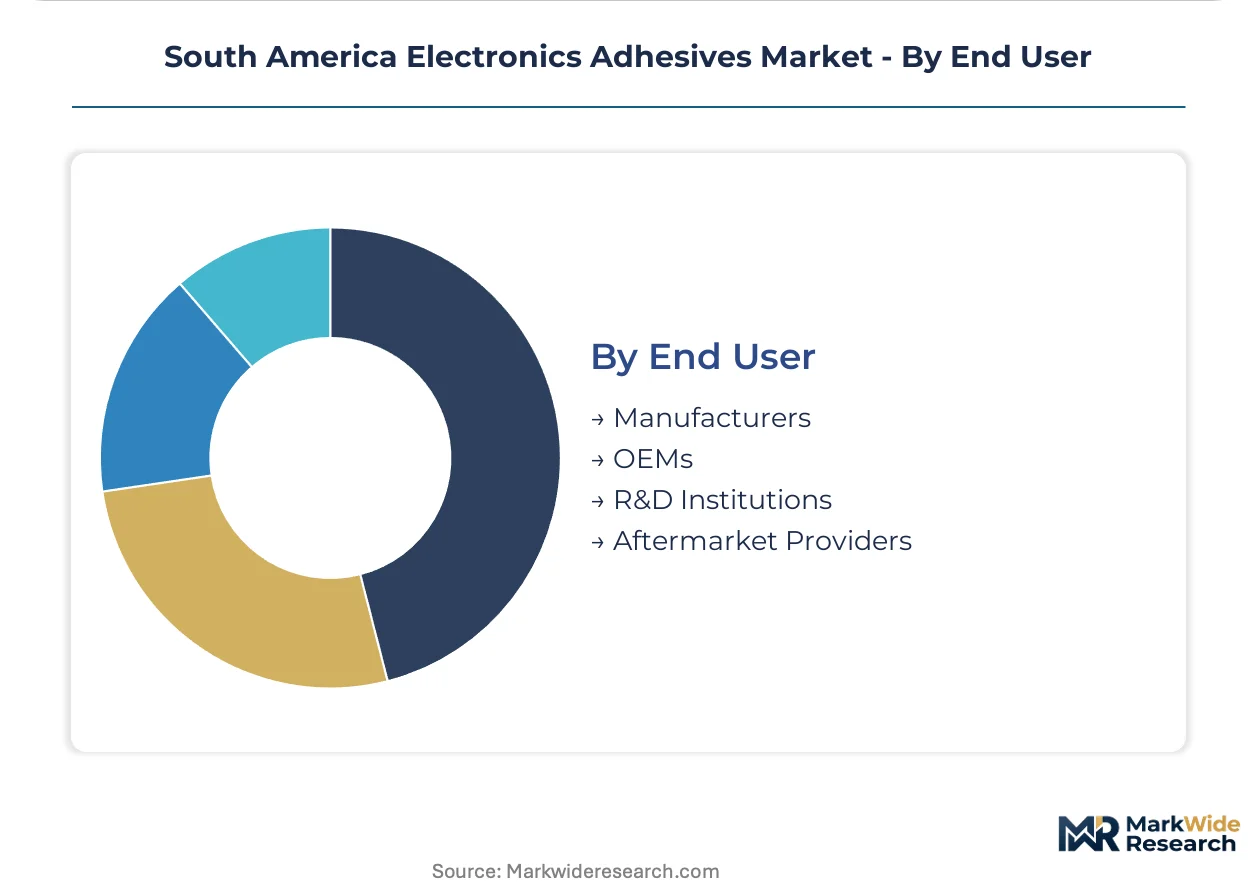
End User:
Direct procurement relationships are displacing distributor intermediaries as consolidated OEMs centralize materials engineering authority.
- Manufacturers:Contract electronics manufacturers across São Paulo state with line-down risk penalties shifting sourcing accountability from plant-floor technicians to centralized procurement teams.
- OEMs:Consolidated Brazilian smartphone and automotive electronics producers repositioning procurement leverage toward volume buyers with technical specification authority.
- R&D Institutions:Universities and national labs in Brazil and Argentina developing halogen-free epoxy formulations aligned with REACH-equivalent Mercosur frameworks.
- Aftermarket Providers:Repair and refurbishment services for consumer electronics with lower specification requirements than OEM procurement.
Specification authority concentrates in OEM procurement departments; R&D institutions drive regulatory-aligned formulation innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized formulation chemists and materials engineers concentrate in Brazil's southeastern industrial corridor, anchoring regional technical capacity for electronics adhesive development.
Brazil
Smartphone OEMs and automotive electronics manufacturers in São Paulo state drive procurement volume for UV-curing and thermal-cure epoxy systems. ANVISA enforces biocompatibility standards for medical device adhesives, forcing halogen-free reformulation investments. The São Paulo-Campinas industrial corridor hosts contract manufacturers centralizing materials engineering authority in procurement departments.
Argentina
Medical device assemblers in Córdoba expand silver-filled conductive adhesive procurement for temperature-sensitive precision bonding applications. The national chemical regulator mandates substance registration consistent with Mercosur harmonization protocols. Córdoba's electronics cluster attracts pressure-sensitive adhesive specialists serving flexible circuit manufacturers.
Chile
Mining and energy infrastructure operators in Santiago and Antofagasta procure heavy-duty thermal interface materials for power electronics. The country's national chemical regulator maintains alignment with international substance restriction frameworks. Northern mining districts generate specification demand for adhesives surviving extreme thermal cycling in remote installations.
Colombia
Consumer electronics distributors in Bogotá and Medellín channel imported adhesive volumes to Andean assembly operations. Environmental enforcement agencies implement REACH-equivalent substance screening at import checkpoints. Bogotá's logistics hubs consolidate regional distribution for northern Andean manufacturing footprints.
Peru
Telecommunications equipment installers in Lima specify moisture-resistant formulations for coastal and high-altitude operating environments. The national standards body adopts IEC-aligned electrical safety requirements affecting adhesive dielectric specifications. Lima's industrial parks host emerging electronics assembly serving domestic and export markets.
South America Electronics Adhesives Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation technology tiers. The market exhibits moderate consolidation with tiered procurement leverage favoring volume buyers with embedded technical specification authority. Strategic archetypes include diversified chemical majors with adhesive divisions, regional formulation specialists with technical service proximity, and materials science innovators targeting conductive and UV-curing niches. Competitive moves concentrate on portfolio diversification toward medical-grade certifications and geographic expansion through technical center investments.
Among diversified chemical conglomerates, Henkel AG & Co. KGaA and Dow occupy positions exemplifying formulation support proximity and humidity-specialized portfolio breadth respectively. H.B. Fuller Company represents the focused specialist archetype with concentration in pressure-sensitive technologies. These three entities anchor the competitive structure while mid-tier regional formulators compete on technical service responsiveness and regulatory compliance speed.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| 3M |
| Dow |
| H.B. Fuller Company |
| BASF SE |
| Sika AG |
| Avery Dennison Corporation |
| Huntsman International LLC |
| Ashland |
| Others |
Value Network & Pricing Analysis
Captive formulation support through São Paulo-based technical centers anchors both supply position and pricing power for multinational adhesive suppliers serving Brazilian electronics OEMs. This integration pattern compresses margin capture for distributors while elevating volume buyers with embedded materials engineering functions to specification authority.
Pricing Analysis
Capacity additions in northern Brazil are reshaping price floors for silicone adhesive systems optimized for Amazon basin humidity conditions. Three-tier pricing structure across medical-grade, industrial-performance, and commodity epoxy levels reflects ANVISA certification burdens and silver-filled conductive material costs. Pricing pressure stems from consolidated smartphone OEM procurement leverage in São Paulo state. Contract electronics manufacturers exhibit acute price sensitivity, while medical device assemblers prioritize biocompatibility certification over unit economics.
Supply Chain Analysis
Specialized polymer chemists and formulation engineers concentrate in Brazil's southeastern industrial corridor, creating workforce-availability constraints for adhesive production scaling. Raw material sourcing draws from German epoxy resin suppliers, Japanese silicone feedstock producers, and Argentine silver flake processors. Single-source vulnerability runs through Asian conductive filler suppliers serving Argentina's Córdoba medical device cluster. Distribution runs through São Paulo logistics hubs with direct procurement relationships displacing distributor intermediaries for volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where ANVISA biocompatibility standards are redirecting procurement budgets toward certified medical-grade adhesive portfolios with separate supply chain documentation.
For Market Incumbents: To counter margin compression from consolidated Brazilian smartphone OEM procurement leverage, anchor position through backward integration into halogen-free epoxy resin formulation in São Paulo state. Deepen technical service staffing at Campinas technical centers to accelerate ANVISA certification timelines for medical device customers. For New Entrants and Emerging Players: Northern Brazilian industrial parks with unmet silicone adhesive specification demand represent the most penetrable white-space target. Establish humidity-specialized formulation partnerships with Amazon basin contract manufacturers before multinational technical center expansion. Lead with regulatory compliance speed against incumbent certification backlogs. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier Brazilian formulation specialists with ANVISA-cleared product lines because regulatory compliance creates durable customer switching costs. Five-to-ten year viability hinges on Mercosur harmonization protocol convergence. Monitor silver price volatility as the inflection indicator for conductive adhesive segment profitability.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Certification Investment | Medical-grade adhesive portfolios command specification lock-in from Córdoba device assemblers. |
| Amazon Basin Technical Center | São Paulo-based humidity specialization addresses underserved northern Brazil industrial expansion. |
| Halogen-Free Formulation Partnership | REACH-aligned substance restrictions favor phosphorus-based flame retardant alternatives. |
| Direct Procurement Channel | Consolidated OEM buyers displace distributor intermediaries for volume adhesive purchases. |
| Silver-Filled Conductive Capacity | Argentina's temperature-sensitive medical device assemblies displace solder with conductive systems. |
Research Methodology
Bottom-up electronics OEM procurement modeling reconciled against top-down adhesive formulation capacity tracking forms the analytical core of this study. Primary interviews with Brazilian contract manufacturer procurement directors, Argentine medical device quality assurance leads, São Paulo-based formulation chemists, and Chilean mining equipment maintenance heads combined with secondary validation from ANVISA regulatory filings, Mercosur substance registration databases, Brazilian customs trade records, and SEC 10-K disclosures from multinational adhesive suppliers.
Historical trendline analysis across installed epoxy and silicone adhesive volumes informed projection framework development. Segmentation modeling captured product chemistry, cure technology, application end-use, and geographic manufacturing cluster dimensions throughout the forecast period. CAGRs derived from elasticity-adjusted demand curves incorporating ANVISA regulatory implementation timelines and silver price volatility assumptions.
Inputs from São Paulo industrial corridor stakeholders were available through the study window; gaps in northern Brazil contract manufacturer procurement data introduce uncertainty bands around Amazon basin humidity-specialized demand estimates. Forecasts reflect documented assumptions regarding Mercosur harmonization protocol adoption velocity and automotive OEM processing familiarity persistence. Material deviation in ANVISA enforcement intensity or silver commodity pricing warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Polyurethane Sealant Market
Adhesives & Sealants
Global Adhesion Promoter Market
Adhesives & Sealants
Elastomeric Adhesive Market
Adhesives & Sealants
Industrial Wood Adhesives Market
Adhesives & Sealants
Low Trauma/Skin Friendly Adhesives Market
Adhesives & Sealants
EMEA Epoxy Adhesives Market
Adhesives & Sealants
Europe Construction Adhesives and Sealants Market
Adhesives & Sealants
Vietnam Construction Chemicals Market
Adhesives & Sealants
Heat Resistant Sealant Market
Adhesives & Sealants
Tobacco and Cigarette Adhesives Market
Adhesives & Sealants
Craft Glue Market
Adhesives & Sealants
Mexico Sealants Market
Adhesives & Sealants
Tissue Adhesives Market
Adhesives & Sealants
Ocular Sealants and Glues Market
Adhesives & Sealants
Middle-East and Africa Contact Adhesives Market
Adhesives & Sealants
Laminating Adhesives Market