
 Sand Testing Equipments Market | 2026-2036
Sand Testing Equipments Market Size, Share, and Industry Trends Forecast 2026-2036
Sand Testing Equipments Market Outlook
Direct-to-foundry distribution is reconfiguring as equipment manufacturers bypass traditional industrial distributors and sell through specialized technical service networks. Simpson Technologies leverages its foundry-specific expertise to anchor premium positioning in automated testing systems across North American metalcasting hubs. KELSONS competes on manufacturing scale in manual and semi-automatic units for South Asian foundry clusters. Dietert Foundry Testing Equipment Inc specializes in permeability and strength testing rigs, sustaining decades-old relationships with legacy gray-iron operations.
Sand testing equipments encompass instruments that measure grain size distribution, moisture content, permeability, compressive strength, and clay content in molding and core sands used for metal casting. A digital permeability tester typically resolves airflow resistance to within 0.1 permeability units, ensuring repeatable green sand mold quality for automotive engine block production. Digital testing technology leads in margin contribution where foundries integrate Industry 4.0 data logging, while manual testing persists in small job shops across India and Southeast Asia due to lower capital thresholds. Automated testing systems represent the fastest-growing segment as tier-one automotive suppliers adopt real-time sand property monitoring to reduce casting scrap rates.
India's BIS mandates silica sand gradation standards for construction and foundry applications, pushing domestic equipment buyers toward certified testing protocols. China's MIIT enforces GB standards for green sand reclamation and quality verification in heavy machinery casting, directly stimulating replacement demand for compliant instruments. The EU F-Gas Regulation indirectly affects oil sand testing protocols through refrigerant-linked extraction processes in northern European operations. Stakeholders must monitor how digital twin integration in foundry sand management reshapes equipment specification requirements and service revenue models.
Market Dynamics
Foundry digitization is compressing equipment replacement cycles as real-time sand monitoring migrates from quality labs to production lines, forcing vendors to reconfigure service architectures around predictive analytics rather than periodic calibration visits.
Growth Catalysts
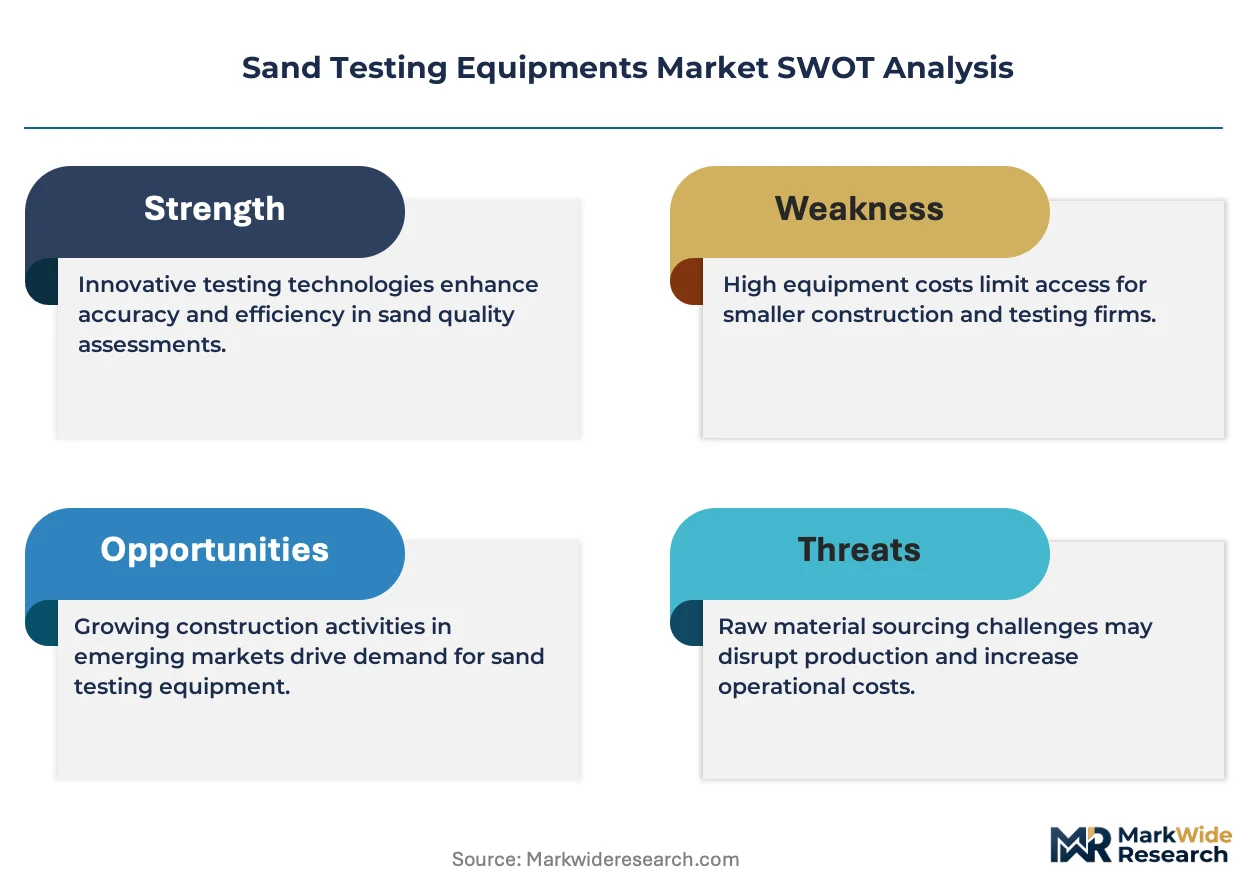
- MIIT green sand mandates:China's Ministry of Industry and Information Technology enforces GB standards for raw material verification in heavy machinery casting, compelling coastal foundries to upgrade manual testing rigs with automated permeability and strength analyzers.
- Automotive lightweighting:Tier-one suppliers for aluminum powertrain components require tighter green sand control to reduce porosity-related scrap, driving adoption of digital moisture and clay content testers with data logging capabilities.
- BIS certification expansion:India's Bureau of Indian Standards tightened silica sand gradation protocols for construction-grade foundry applications, creating compliance-driven replacement demand across Gujarat and Tamil Nadu metalcasting clusters.
Market Restraints
- Capital intensity barrier:Fully automated testing systems require substantial upfront investment, excluding small job shops across Southeast Asia from digital upgrade paths and perpetuating manual equipment dependence.
- Sensor supply concentration:Precision airflow sensors and load cells for permeability and compression testing concentrate among German and Japanese component suppliers, exposing equipment manufacturers to extended lead times and input cost volatility.
- Technical limitation in reclaimed sand:Existing digital testers struggle with variable binder residue in mechanically reclaimed green sand, forcing foundries to maintain parallel manual verification protocols and diluting automation ROI.
Strategic Opportunities
- Service revenue unbundling:Equipment vendors are virtualizing calibration and predictive maintenance through cloud-connected instruments, creating recurring revenue streams independent of hardware replacement cycles.
- Indonesian foundry modernization:Java's expanding automotive component casting sector remains underpenetrated by automated testing, offering first-mover positioning for vendors establishing local technical service networks.
- EU F-Gas Regulation spillover:Northern European oil sand extraction operations face refrigerant-linked environmental compliance, stimulating demand for specialized cold-box core sand testing equipment with emission-tracking documentation.
Industry Challenges
- Metallurgical technician scarcity:Foundries struggle to recruit operators capable of interpreting digital permeability curves and correlating sand properties with casting defects, slowing Industry 4.0 integration despite equipment availability.
- Legacy system integration friction:Greenfield automated testers must interface with decades-old molding line PLCs and proprietary foundry management software, requiring costly custom protocol bridges and extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sand Testing Equipments Market |
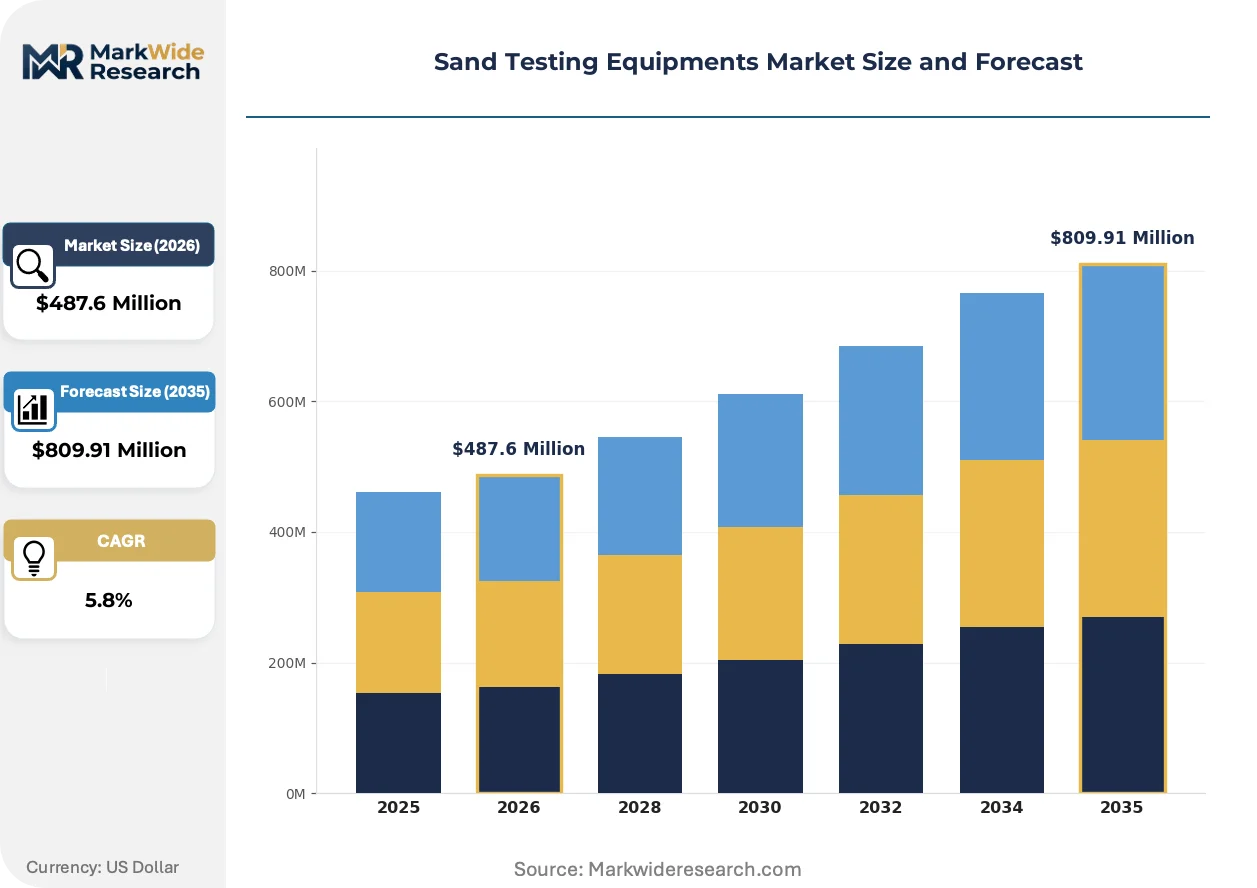
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Sand Tester, Sand Sieve Shaker, Permeability Tester, Sand Strength Machine End User: Construction, Foundries, Manufacturing, Research Institutions Material: Silica Sand, Green Sand, Oil Sand, Shell Sand Technology: Digital Testing, Manual Testing, Automated Testing, Hybrid Systems |
| Companies Covered | Versatile Equipments Pvt Ltd, KELSONS, Associated Scientific and Engineering Works, Supertech Scientific, Simpson Technologies, Dietert Foundry Testing Equipment Inc, Foundry Sand Testing Equipment Inc, CB Machinery, Royals Enterprises, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sand Testing Equipments Market Strategic Shifts
Digital twin architectures are penetrating foundry sand management, compressing the feedback loop between laboratory testing and shop floor adjustment while reshaping how equipment vendors structure hardware-software-service bundles.
Cloud-based sand property databases are virtualizing quality documentation across multi-site foundry groups. Automotive casting networks in Germany and the US Midwest deploy these systems to synchronize green sand specifications across dispersed production facilities. The technology is virtualizing traditional audit-based customer verification, replacing physical sample shipments with real-time data dashboards accessible to OEM quality engineers.
REACH chemical registration requirements in the European Union now extend to certain foundry sand additives and binders, compelling equipment manufacturers to certify that their testing protocols can detect restricted substance thresholds. Laboratory equipment vendors serving German gray-iron operations have responded by integrating additive-specific calibration curves into digital clay content analyzers, positioning compliance documentation as a differentiated feature.
Direct technical service networks are displacing industrial distributor channels for complex automated systems. Foundries in China's Yangtze River Delta now expect equipment manufacturers to embed application engineers who understand green sand rheology, not merely hardware maintenance. This pattern concentrates in automotive supply chain hubs where casting quality disputes carry substantial penalty exposure and buyers demand immediate technical escalation paths.
Sand Testing Equipments Market Segmentation
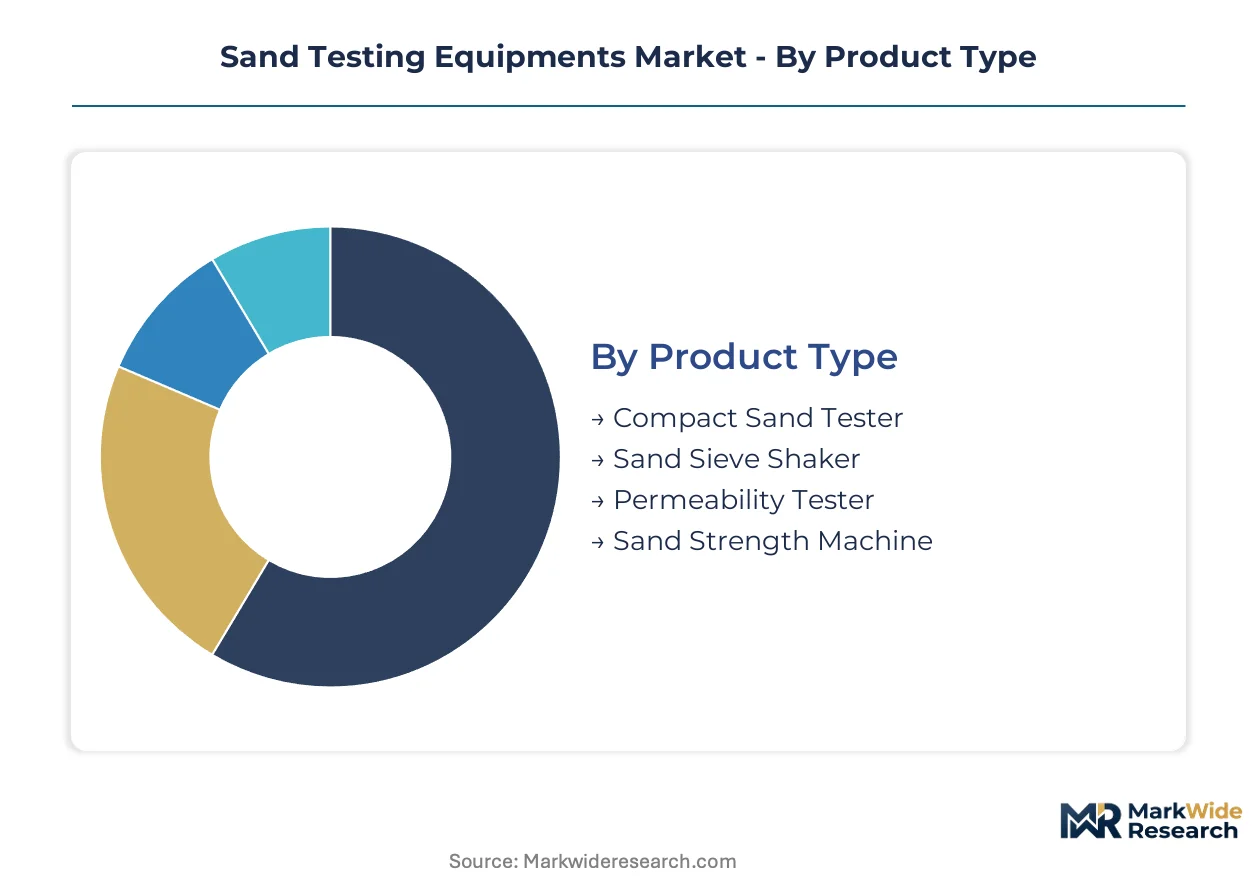
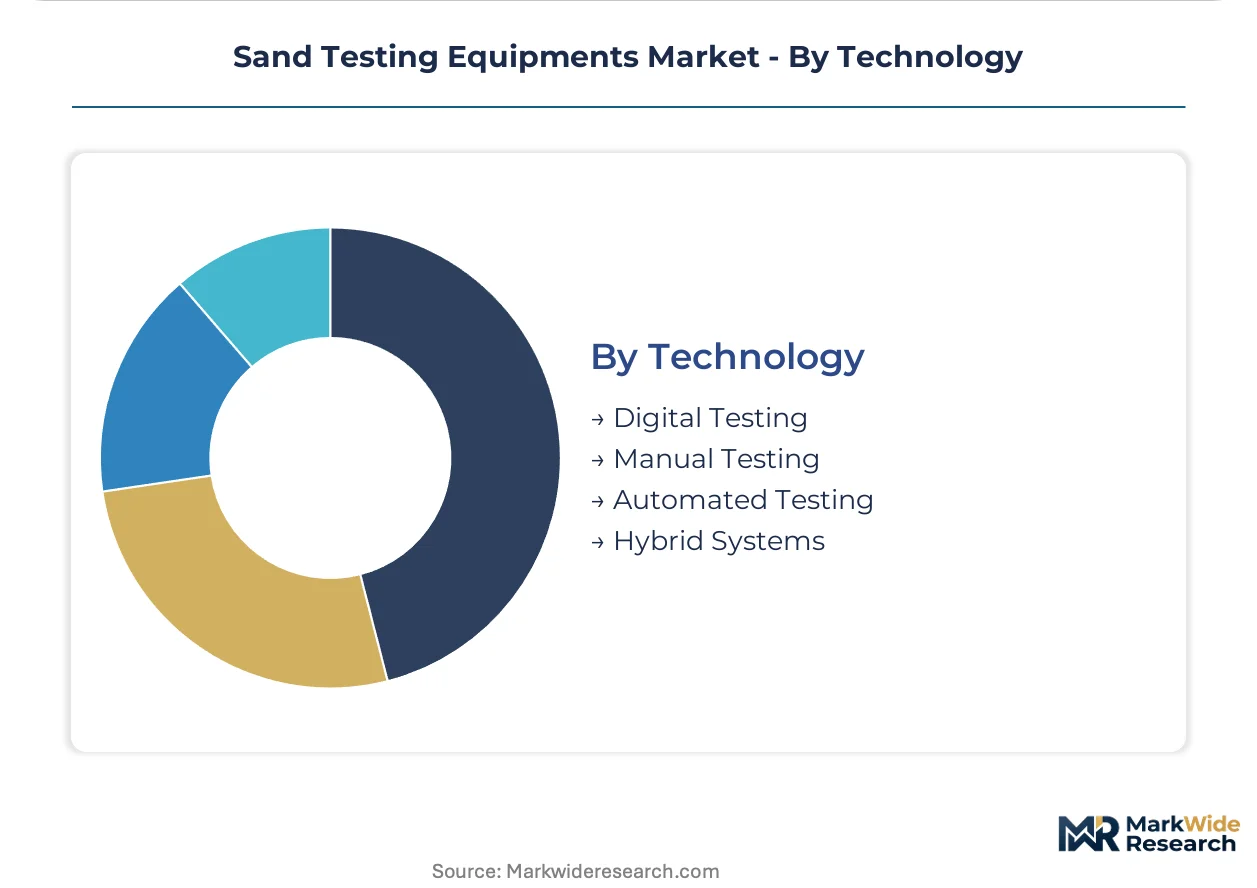
Sand testing equipment segmentation reflects divergent capital deployment patterns across foundry modernization cycles. Equipment specifications vary sharply between tier-one automotive suppliers demanding real-time data integration and job shops prioritizing manual verification protocols.
Product Type:
Mature benchtop instruments coexist with emerging automated analyzers across foundry quality laboratories.
- Compact Sand Tester:Portable units measure moisture content and clay percentages through capacitive sensing for field verification at remote casting sites. Demand concentrates in India's Gujarat foundry belt where BIS certification requires on-site gradation checks before silica sand unloading.
- Permeability Tester:Digital airflow resistance analyzers resolve permeability to 0.1 units for green sand mold consistency. China's Yangtze River Delta automotive casting clusters drive replacement demand as MIIT mandates stricter raw material verification protocols.
- Sand Sieve Shaker:Mechanical or electromagnetic particle size distribution analyzers separate molding sand across standard mesh gradients.
- Sand Strength Machine:Compression and shear testing rigs evaluate green sand specimen integrity under standardized load conditions.
Compact sand testers handle the majority of throughput in emerging market verification workflows; permeability testers are expanding most quickly as coastal Chinese foundries automate quality control.
End User:
Cost tier differentiation separates capital-intensive automated deployments from maintenance-focused manual equipment purchases.
- Foundries:Green sand and chemically bonded sand casting operations require permeability, strength, and moisture verification across molding and core-making lines. Germany's gray-iron automotive component suppliers prioritize digital testers with cloud data logging for OEM quality documentation.
- Construction:Silica sand gradation testing for concrete and mortar applications demands sieve analysis and fineness modulus calculation. India's BIS-certified construction material suppliers face compliance pressure to document silica sand particle distribution.
- Manufacturing:Heavy machinery and industrial equipment producers verify reclaimed sand quality for in-house casting operations.
- Research Institutions:Universities and national laboratories develop next-generation molding sand formulations and binder systems.
Foundries absorb the dominant equipment volume; construction sector buyers are climbing the fastest as infrastructure-grade silica sand standards tighten.
Material:
Application-specific testing protocols drive instrument configuration differences across sand chemistry categories.
- Green Sand:Bentonite-bonded silica sand mixtures require permeability, compressive strength, moisture, and active clay content measurement. US Midwest automotive foundries deploy real-time digital monitoring to reduce porosity-related scrap in aluminum powertrain castings.
- Silica Sand:Base aggregate for construction and foundry applications demands grain size distribution and purity verification. China's coastal manufacturing clusters source imported silica sand requiring MIIT-compliant testing documentation.
- Oil Sand:Hydrocarbon-impregnated sands used in northern European cold-box core production face EU F-Gas Regulation compliance verification.
- Shell Sand:Resin-coated sands for precision casting require thermal property and binder content analysis.
Green sand testing commands the largest installed base; silica sand verification is gaining share fastest on construction certification expansion.
Technology:
Customer type stratification separates tier-one suppliers from small job shops across automation investment decisions.
- Automated Testing:Integrated systems execute permeability, strength, and moisture analysis with robotic specimen handling and direct MES/ERP data transmission. German automotive casting networks synchronize multi-site sand specifications through cloud-connected instrument clusters.
- Digital Testing:Standalone electronic instruments with data logging capabilities bridge manual and fully automated workflows. Southeast Asian foundry clusters adopt these units as intermediate steps toward Industry 4.0 integration.
- Manual Testing:Mechanical dial gauges and hand-operated compression frames persist in capital-constrained operations.
- Hybrid Systems:Configurations combine digital sensors with operator-controlled specimen preparation for flexible deployment.
Automated testing systems carry the steepest expansion trajectory; digital testing retains the broadest geographic penetration across mid-tier foundry operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT's GB standards for green sand verification anchor demand concentration in China's coastal manufacturing clusters, while BIS certification mandates in India and REACH compliance requirements in Germany shape equipment procurement patterns across three distinct regulatory environments.
China
Automotive powertrain casting operations in the Yangtze River Delta drive automated permeability tester deployments as MIIT enforces raw material quality documentation. GB standards for green sand reclamation compel foundries to replace manual rigs with digital analyzers. Shanghai and Jiangsu province metalcasting hubs absorb the majority of compliant instrument installations.
India
Gujarat and Tamil Nadu foundry clusters face BIS-mandated silica sand gradation protocols for construction-grade applications. Compact sand testers dominate field verification workflows at portside unloading points. Rajkot and Coimbatore metalcasting belts generate replacement demand as certification audits intensify.
Germany
Gray-iron automotive component suppliers in Bavaria and Baden-Württemberg prioritize digital testers with cloud data logging for OEM quality documentation. REACH chemical registration extends to foundry sand additives, requiring additive-specific calibration capabilities. Stuttgart and Munich automotive supply chain hubs synchronize multi-site sand specifications through networked instrument clusters.
United States
Midwest aluminum foundries serving powertrain lightweighting programs deploy real-time green sand monitoring to reduce porosity-related scrap. EPA industrial emissions frameworks indirectly shape sand reclamation testing priorities. Michigan and Ohio automotive casting corridors lead digital moisture and clay content tester adoption.
Indonesia
Java's expanding automotive component casting sector remains underpenetrated by automated testing systems, with manual equipment persisting in Surabaya and Jakarta manufacturing zones. The country's national standards body has begun drafting silica sand quality protocols for infrastructure applications. Local technical service networks remain sparse, creating first-mover positioning opportunities for vendors establishing direct support infrastructure.
Sand Testing Equipments Market Competitive Environment
Technology-anchored specialists and scale-driven fabricators split the market between premium automated systems and cost-optimized manual equipment. The vendor base concentrates around three strategic archetypes: foundry-specific technology leaders with embedded application expertise, regional manufacturing-scale competitors serving price-sensitive clusters, and legacy equipment specialists maintaining decades-old customer relationships. Dominant competitive moves include direct technical service network expansion displacing traditional distributor channels, and cloud-connected instrument portfolios unbundling recurring calibration revenue from hardware sales cycles.
Among North American technology-anchored players, Simpson Technologies and Dietert Foundry Testing Equipment Inc occupy positions exemplifying the premium automated and legacy specialist archetypes respectively. Simpson Technologies anchors the foundry-specific technology tier with automated testing systems integrated into Industry 4.0 data architectures. Dietert Foundry Testing Equipment Inc represents the legacy equipment specialist model, sustaining long-tenured relationships with established gray-iron operations. KELSONS sits within the scale-driven manufacturing tier, competing on production volume for manual and semi-automatic units across South Asian foundry markets.
| Leading Market Players |
|---|
| Versatile Equipments Pvt Ltd |
| KELSONS |
| Associated Scientific and Engineering Works |
| Supertech Scientific |
| Simpson Technologies |
| Dietert Foundry Testing Equipment Inc |
| Foundry Sand Testing Equipment Inc |
| CB Machinery |
| Royals Enterprises |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in China's Yangtze River Delta testing equipment fabrication is compressing margins for automated permeability analyzer producers while simultaneously accelerating supplier consolidation around technical service capabilities. German and Japanese precision sensor suppliers maintain pricing leverage through single-source dependencies, forcing equipment manufacturers to absorb component volatility or pass through costs to tier-one automotive foundries with limited elasticity.
Pricing Analysis
Price spreads between German-engineered automated systems and Indian-manufactured manual units exceed 400 percent across equivalent functional specifications. Three-tier pricing structure across premium, standard, and economy levels stratifies by data integration depth, with cloud-connected instruments commanding service-bundled premiums. Cost compression in mid-tier digital testers is intensifying because Southeast Asian foundries delay automation investments. Small job shops in India's Rajkot cluster exhibit highest price sensitivity; German automotive suppliers prioritize total cost of ownership over acquisition price.
Supply Chain Analysis
Contract manufacturing for precision load cells and airflow sensors concentrates among German component specialists and Japanese sensor fabricators with limited second-source alternatives. Final assembly draws from China, India, and Germany as anchor production geographies. Supply chain risk centers on extended lead times for MIIT-compliant calibration standards from designated Chinese metrology institutes. Distribution runs through direct technical service networks displacing traditional industrial distributors for complex automated systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Sand Testing Equipments Market is recovering from cyclical capital expenditure compression in automotive casting, with MIIT enforcement in China and BIS expansion in India providing synchronized regulatory tailwinds.
For Market Incumbents: Insulate core revenue through captive calibration service contracts and predictive maintenance subscriptions that reduce customer churn. Deepen backward integration into precision sensor supply by qualifying alternative Japanese component sources, reducing exposure to German supplier concentration. Prioritize certification investment for BIS and MIIT compliance documentation as defensive moats against emerging regional competitors. For New Entrants and Emerging Players: Build out technical service infrastructure in Indonesia's underpenetrated Java automotive casting corridor before incumbent networks solidify. Target construction-sector silica sand verification as the most penetrable segment, riding BIS certification expansion with compact field-portable testers. Pursue direct-to-foundry go-to-market positioning that bypasses distributor markups and captures price-sensitive replacement demand. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across digital testing instrument portfolios as cloud-connected platforms reduce hardware refresh frequency. Long-term viability favors vendors with recurring service revenue exceeding 35 percent of total mix. Acquisition targets should demonstrate embedded application engineering teams capable of interpreting green sand rheology. Monitor MIIT audit enforcement intensity as the signal to watch for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Technical Service Network Expansion | Simpson Technologies and KELSONS embed application engineers in Yangtze River Delta and Gujarat clusters to displace distributor channels. |
| Cloud-Connected Instrument Portfolio Development | Real-time sand property databases virtualize quality documentation across multi-site German automotive casting networks. |
| MIIT Compliance Certification Investment | Equipment manufacturers integrate GB standard calibration curves to capture replacement demand in Shanghai and Jiangsu province hubs. |
| Construction Sector Channel Development | Compact sand tester vendors target India's BIS-certified silica sand suppliers for infrastructure-grade gradation verification. |
| Sensor Supply Diversification | Equipment fabricators qualify secondary Japanese load cell sources to reduce dependency on German component suppliers. |
Study Parameters
Operator-level perspectives from foundry quality managers, maintenance directors at tier-one automotive suppliers, OEM procurement specialists, and technical service heads anchored the qualitative base. Primary interviews with equipment manufacturers and distributor networks combined with secondary validation from BIS certification registries, MIIT GB standard documentation, SEC filings of publicly traded foundry equipment vendors, and customs trade data for precision sensor imports. Bottom-up equipment deployment estimates triangulated against top-down foundry capacity expansion projections.
Scenario-bracketing framed demand trajectories across regulatory enforcement intensities and automotive lightweighting adoption curves over the projection horizon. Segmentation modeling spanned technology tier, end-user vertical, material chemistry, and regional regulatory cluster dimensions. CAGRs derived from equipment replacement cycle analysis correlated with foundry capital expenditure surveys and green sand reclamation rate trends.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed equipment consortia or accelerated German sensor supplier consolidation would shift outcomes. Quarterly review of MIIT audit announcement frequency and BIS certification expansion timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Low-Pressure Liquid Chromatography Market
Testing Equipment
Pitting Machines Market
Testing Equipment
Microplastics Particle Size and Shape Characterization Systems Market
Testing Equipment
Chromatography Market
Testing Equipment
Hydrogen Gas Analyzers Market
Testing Equipment
Dynamic Vapor Sorption Analyzer Market
Testing Equipment
Global Chromatography Columns Market
Testing Equipment
Oxidation Stability Analyzer Market
Testing Equipment
Binary High Pressure Gradient Liquid Chromatography System Market
Testing Equipment
Ammonia Testing Market
Testing Equipment
Chemical Detection Equipment Market
Testing Equipment
Laboratory Balances and Scales Market
Testing Equipment
Ambient Temperature Gel Permeation Chromatography Market
Testing Equipment
PFAS Ultra-Trace Water Analysis Test Instruments Market
Testing Equipment
Global Trace Metal Analysis Market
Testing Equipment
Nitrogen Tester Market