
 Europe Adhesives and Sealants Market | 2026-2036
Europe Adhesives and Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Adhesives and Sealants Market Foresight
German chemical producers is rebalancing capacity toward low-VOC adhesive platforms after energy cost shocks disrupted feedstock economics. Henkel AG & Co. KGaA leverages its Cologne R&D campus to sustain polyurethane innovation pipelines. Sika AG anchors construction-grade sealant supply across Alpine infrastructure projects. BASF competes through backward integration into specialty acrylic monomers.
Adhesives and sealants are polymeric bonding materials formulated from acrylics, epoxies, polyurethanes, or silicones that cure through moisture, heat, or anaerobic reaction to create load-bearing joints or environmental barriers. These materials serve industrial applications by distributing stress across bonded surfaces rather than concentrating it at mechanical fixation points. Polyurethane formulations command premium positioning in automotive assembly where flexibility under thermal cycling protects margin pools. Silicone sealants lead construction applications across Mediterranean markets given superior UV resistance. Hot melt adhesives dominate packaging throughput in Central European converting operations where speed determines unit economics.
REACH registration requirements and the EU F-Gas Regulation constrain fluorinated sealant chemistries while CE marking mandates performance disclosure for structural bonding applications. ECHA substance evaluations are forcing reformulation timelines for legacy epoxy hardeners containing SVHC candidates. Stakeholders must monitor delegated acts under the EU Green Deal that will redefine recyclability criteria for bonded assemblies.
Market Dynamics
REACH substance evaluations and the EU Green Deal are compressing reformulation timelines for legacy chemistries while simultaneously opening premium positioning for compliant bio-based alternatives. German automotive OEMs are accelerating adhesive bonding to reduce vehicle weight and assembly complexity.
Growth Catalysts
- Automotive Lightweighting Mandates:German and French OEMs are expanding structural adhesive applications to replace mechanical fasteners in battery enclosures and body-in-white assemblies, driven by fleet emissions targets under EU CO2 regulations.
- CE Marking for Structural Bonding:Construction-grade adhesive certification requirements under harmonized European standards are displacing uncertified commodity formulations in Alpine infrastructure and Mediterranean solar installations.
- Rhine-Ruhr Manufacturing Concentration:Industrial demand clusters along this corridor sustain dedicated supply chain infrastructure for high-performance polyurethane and epoxy platforms serving packaging and electronics sectors.
Market Restraints
- Feedstock Cost Volatility:European propylene oxide and MDI pricing remains exposed to natural gas cost shocks, compressing margin pools for polyurethane formulators dependent on regional petrochemical supply.
- Fluorinated Chemistry Constraints:The EU F-Gas Regulation restricts hydrofluorocarbon propellants and sealant bases, forcing premature phase-out of high-performance weatherproofing products without drop-in replacements.
- Substitution by Mechanical Fastening:Structural riveting and laser welding retain cost advantages in high-volume automotive platforms where adhesive curing cycles create throughput bottlenecks.
Strategic Opportunities
- Eastern European Industrial Expansion:Polish and Czech automotive component manufacturing is underpenetrated for structural bonding relative to German assembly plants, creating whitespace for technical service-intensive suppliers.
- CSRD-Driven Circularity Reporting:The Corporate Sustainability Reporting Directive mandates disclosure of bonded assembly recyclability, creating advisory service revenue streams for adhesive producers with lifecycle assessment capabilities.
- UV-Curable Hot Melt Convergence:Packaging converters in Central European folding carton operations are adopting dual-cure systems combining speed with heat resistance for premium food contact applications.
Industry Challenges
- Formulation Chemist Scarcity:REACH compliance expertise and bio-based raw material compatibility testing require specialized talent that European technical universities are not producing at replacement rates.
- Multi-Site Certification Complexity:ECHA SVHC candidate list updates force simultaneous reformulation across production facilities in Germany, France, and Italy with non-harmonized national implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Adhesives and Sealants Market |
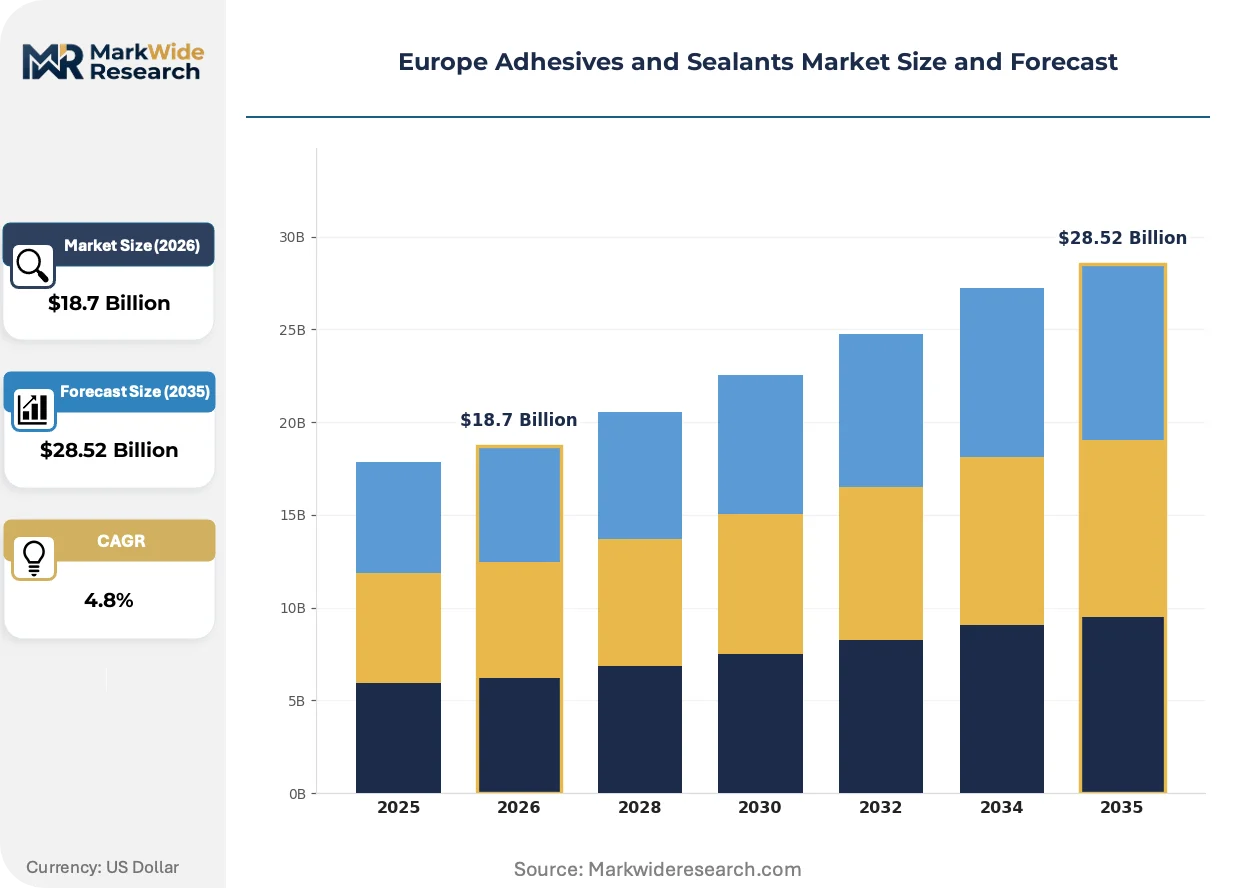
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Epoxy, Polyurethane, Silicone, Hot Melt, Anaerobic Application: Construction, Packaging, Footwear, Electronics, Aerospace, Marine End User Industry: OEMs, Aftermarket Providers, Fabrication Shops, Contract Manufacturers, Repair Services Distribution Channel: Direct Sales, Wholesale Distributors, E-Commerce Platforms, Specialized Dealers, Industrial Suppliers |
| Companies Covered | Sika AG, Henkel AG & Co. KGaA, H.B. Fuller Company, 3M, Arkema, Wacker Chemie AG, Dow, BASF, Avery Dennison Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Adhesives and Sealants Market Shifts & Advancements
Formulation chemistry is pivoting toward solvent-free and bio-based platforms as regulatory pressure compounds with energy cost-driven feedstock rebalancing. Digital tools are compressing development cycles for customized adhesive specifications.
Reactive hot melt polyurethane technology is decentralizing supply chain control for automotive interior assembly. Tier-1 suppliers in Stuttgart and Munich are adopting on-demand dispensing systems that cure through moisture activation rather than thermal ovens. This platform is decentralizing inventory requirements and enabling just-in-sequence delivery models that reduce working capital intensity for seating and trim manufacturers.
REACH authorization procedures for diisocyanates are forcing systematic substitution in industrial coatings and construction sealants. ECHA's restriction roadmap is accelerating investment in aliphatic and waterborne alternatives among formulators serving the Alpine tunneling and Mediterranean facade markets. German industrial users are responding with multi-year qualification protocols that extend supplier switching timelines.
Specification authority is migrating from procurement departments to sustainability and engineering functions within European OEMs and construction firms. French and Dutch building contractors now require Environmental Product Declarations before adhesive approval, displacing price-driven commodity selection. This pattern is most visible in Netherlands infrastructure tenders where circularity scoring determines technical qualification thresholds.
Europe Adhesives and Sealants Market Segmentation
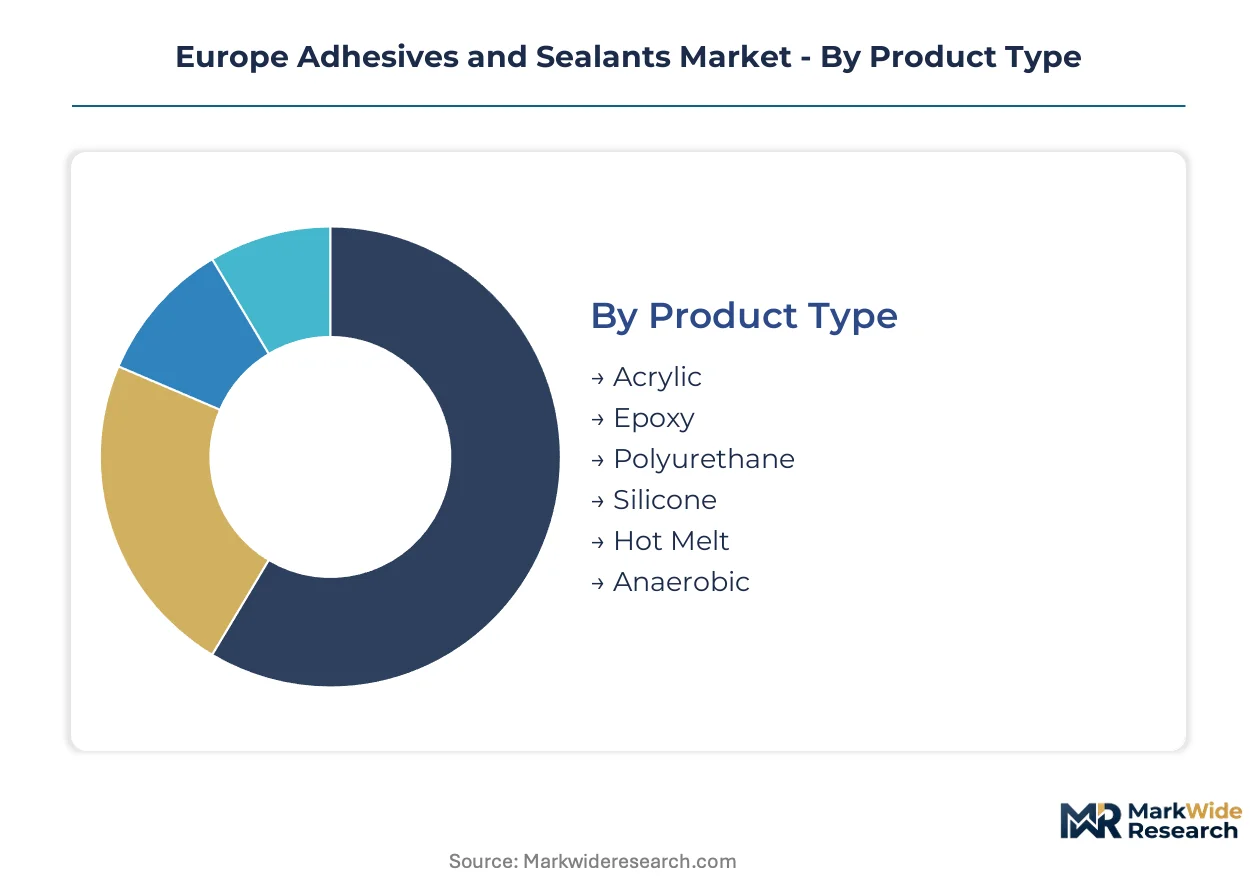
Segmentation in the Europe Adhesives and Sealants Market reveals how formulation chemistry, application requirements, and supply chain configuration create distinct competitive arenas. Understanding these divides exposes where margin pools concentrate and where technical service investments yield differentiation.
Product Type:
Volume production concentrates in commodity formulations serving high-throughput packaging and construction applications, while premium positioning accrues to specialized chemistries meeting automotive and electronics specifications.
- Polyurethane:These two-part or moisture-cure systems deliver flexibility under thermal cycling and vibration damping critical for battery enclosure bonding in German EV assembly. Rhine-Ruhr industrial corridors sustain dedicated polyurethane supply infrastructure serving both automotive OEMs and Alpine tunneling projects.
- Silicone:Room-temperature vulcanizing formulations command construction premiums across Mediterranean markets where UV resistance and 50-year durability specifications dominate facade and infrastructure tenders. ECHA scrutiny of legacy silicone sealant additives is compressing reformulation timelines for facade specialists.
- Acrylic:Waterborne and solvent-based systems serve general industrial assembly with fast cure speeds and broad substrate compatibility.
- Epoxy:High-strength structural bonding for aerospace composites and wind turbine blade assembly, constrained by SVHC evaluations of amine hardeners.
- Hot Melt:Ethylene-vinyl acetate and polyolefin formulations dominate Central European folding carton converting where line speed determines unit economics.
- Anaerobic:Threadlocking and retaining compounds for precision mechanical assembly in French and Italian industrial maintenance channels.
Mature deployment sits with Hot Melt systems in established packaging corridors. Newer deployment is concentrated in Polyurethane platforms serving electrified vehicle architectures.
Application:
Application segmentation tracks divergent performance requirements across load-bearing structural joints versus environmental sealing barriers, with certification mandates fragmenting competitive dynamics.
- Construction:CE marking requirements under harmonized European standards displace uncertified commodity formulations in Alpine infrastructure and Mediterranean solar installations. French and Dutch contractors now mandate Environmental Product Declarations before technical qualification.
- Packaging:Central European converting operations prioritize hot melt throughput speed for food contact applications, with UV-curable dual-cure systems gaining traction in premium folding carton segments.
- Electronics:Miniaturization trends drive demand for electrically conductive and thermally conductive adhesives in PCB assembly and display bonding.
- Aerospace:Structural bonding for composite airframes and interior assemblies, qualified to stringent OEM specifications with multi-year certification protocols.
- Footwear:Reactive hot melt polyurethane systems enable just-in-sequence delivery for athletic and luxury footwear manufacturing in Portugal and Italy.
- Marine:Below-deck sealing and hull bonding applications across Mediterranean shipbuilding and Nordic leisure craft production.
Certification-intensive applications in Construction and Aerospace sustain premium pricing. Volume throughput in Packaging and Footwear rewards formulation cost discipline and supply chain proximity.
End User Industry:
Customer type segmentation separates specification authority held by engineering and sustainability functions from procurement-driven commodity purchasing.
- OEMs:German and French automotive manufacturers consolidate adhesive specifications at platform engineering level, with sustainability teams gaining veto authority over bonded assembly recyclability under CSRD disclosure requirements.
- Contract Manufacturers:Electronics and medical device assemblers in Czech and Polish industrial zones demand technical service support for process optimization and regulatory documentation.
- Fabrication Shops:Metalworking and plastics processors across Benelux and Northern Italy purchase through industrial distributors with just-in-time replenishment expectations.
- Aftermarket Providers:Automotive repair and marine maintenance channels in Southern Europe and Scandinavia favor established brand recognition and application training support.
- Repair Services:Building maintenance and infrastructure refurbishment contractors selecting sealants based on contractor familiarity and local availability.
Direct technical engagement concentrates with OEMs and Contract Manufacturers. Indirect distribution through wholesale and specialized channels dominates Fabrication Shops and Repair Services.
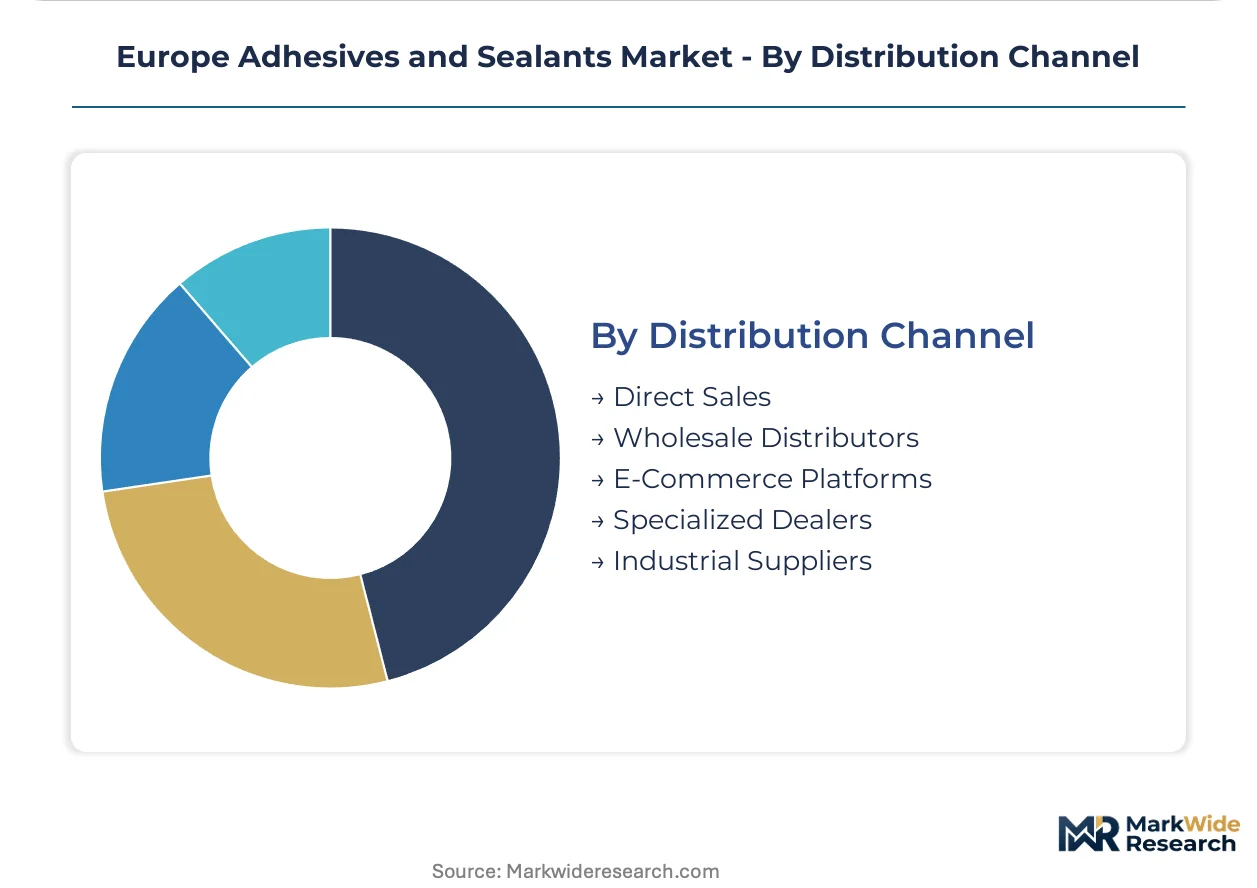
Distribution Channel:
Channel configuration reflects customer scale, technical complexity, and geographic concentration across European industrial corridors.
- Direct Sales:Large-volume automotive and aerospace OEMs in Germany and France negotiate frame contracts with dedicated technical account management and on-site formulation support.
- Wholesale Distributors:Broad-line industrial distributors serve fragmented fabrication and repair segments across multiple European countries with consolidated logistics.
- Specialized Dealers:Construction-focused channels in Alpine regions and Mediterranean markets provide application training and local regulatory compliance guidance.
- E-Commerce Platforms:Standard grades and maintenance quantities for small fabricators and repair contractors, constrained by hazardous material shipping regulations.
- Industrial Suppliers:Integrated supply contracts with manufacturing facilities in Rhine-Ruhr and Po Valley corridors combining adhesive supply with dispensing equipment and process engineering.
Relationship-intensive channels in Direct Sales and Specialized Dealers defend margin pools. Transactional efficiency in Wholesale Distribution and E-Commerce serves price-sensitive maintenance and small-batch production segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Propylene oxide and MDI feedstock availability along the Rhine-Ruhr corridor anchors European adhesive manufacturing capacity. Industrial demand concentrates in German automotive clusters, French construction corridors, and Mediterranean solar installations. Regulatory pressure from REACH and the EU Green Deal is compressing reformulation timelines across all major production zones.
Germany
Battery enclosure bonding for electric vehicle platforms drives polyurethane demand at Stuttgart and Munich assembly plants. REACH authorization procedures for diisocyanates force systematic substitution in industrial coatings. The Rhine-Ruhr manufacturing cluster sustains dedicated supply infrastructure for high-performance epoxy and polyurethane platforms.
France
Facade and infrastructure sealant specifications prioritize UV-resistant silicone formulations across Mediterranean markets. Environmental Product Declarations are now mandatory in Netherlands infrastructure tenders involving French contractors. The Auvergne-Rhône-Alpes region concentrates specialty adhesive R&D for aerospace composite bonding.
Italy
Luxury footwear manufacturing in Portugal and Northern Italy adopts reactive hot melt polyurethane for just-in-sequence delivery models. CE marking requirements displace uncertified commodity formulations in Alpine tunneling projects. The Po Valley corridor integrates adhesive supply with dispensing equipment for packaging converters.
Netherlands
Circularity scoring under the Corporate Sustainability Reporting Directive determines technical qualification thresholds for construction adhesives. Dutch building contractors mandate lifecycle assessment documentation before adhesive approval. The Randstad region hosts formulation technical service centers serving Benelux industrial fabricators.
Poland
Automotive component manufacturing in Czech and Polish industrial zones remains underpenetrated for structural bonding relative to German assembly plants. ECHA SVHC candidate list updates force simultaneous reformulation across production facilities with non-harmonized national implementation timelines. Warsaw and Krakow industrial zones attract technical service-intensive adhesive suppliers.
Europe Adhesives and Sealants Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-based and solvent-free formulation spaces to bypass legacy compliance burdens. The vendor base separates into three tiers: integrated chemical conglomerates with captive monomer supply, mid-scale formulators with regional technical service networks, and specialized niche players serving single-application segments. Two dominant competitive moves are reshaping positioning: backward integration into specialty raw materials to secure margin pools, and advisory service bundling around CSRD-driven circularity reporting to capture specification authority.
Within the integrated chemical tier, BASF and Dow exemplify upstream control strategies through captive acrylic monomer and polyurethane precursor production. Sika AG anchors construction-grade sealant supply across Alpine infrastructure and Mediterranean facade markets. Henkel AG & Co. KGaA occupies a position at the premium automotive vector, with its Cologne R&D campus sustaining polyurethane innovation pipelines for German OEM bonding applications. These three represent distinct archetypes: feedstock-integrated conglomerate, construction-specialized formulator, and automotive-focused technical service provider.
| Leading Market Players |
|---|
| Sika AG |
| Henkel AG & Co. KGaA |
| H.B. Fuller Company |
| 3M |
| Arkema |
| Wacker Chemie AG |
| Dow |
| BASF |
| Avery Dennison Corporation |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between CE-marked structural adhesives and uncertified commodity formulations manifests in both pricing power and supply chain configuration across European industrial corridors. Premium polyurethane platforms for German automotive battery enclosures command bundled technical service contracts, while hot melt volumes in Central European packaging run through transactional spot purchasing with minimal service attachment.
Pricing Analysis
Warranty-backed technical service bundling separates premium-tier suppliers from unbundled commodity competitors in European adhesive markets. Three-tier pricing structure across premium, standard, and economy levels tracks certification complexity, with CE-marked construction sealants and automotive-qualified polyurethanes anchoring the top tier. Cost compression in commodity hot melts intensifies because packaging converters prioritize line-speed throughput over formulation sophistication. Small fabrication shops and repair contractors exhibit highest price sensitivity, while German OEM platform engineers prioritize bonded assembly reliability over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with German propylene oxide and MDI feedstock production concentrated along the Rhine-Ruhr corridor. Raw material supply draws from Belgian petrochemical complexes and Dutch chemical manufacturing hubs as secondary sources. Regulatory restriction through REACH authorization timelines for diisocyanates threatens qualified supplier continuity. Distribution runs through direct sales for automotive OEM frame contracts, wholesale distributors for fragmented industrial accounts, and specialized construction dealers for Alpine infrastructure projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized formulation capacity constraints in REACH-compliant chemistries prop pricing power for qualified suppliers. This supply-constrained structure favors incumbents with certified production assets and technical service depth.
For Market Incumbents: To counter feedstock cost volatility from natural gas price shocks, prioritize backward integration into specialty acrylic monomers and captive polyurethane precursor production. Secure multi-year qualification protocols with German OEMs to extend switching timelines. CE marking investment for construction-grade portfolios defends margin position against uncertified commodity displacement.
For New Entrants and Emerging Players: The EU Green Deal in Europe opens a window for bio-based adhesive platforms bypassing legacy diisocyanate compliance burdens. Polish and Czech automotive component manufacturing offers the most penetrable geography for structural bonding technical services. Lead with lifecycle assessment documentation and CSRD advisory bundling to capture specification authority from sustainability functions.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale formulators possessing regional technical service networks and REACH compliance expertise given tightening formulation chemist scarcity. Long-term viability centers on advisory service capabilities around circularity reporting and bonded assembly recyclability. Monitor ECHA SVHC candidate list expansion velocity as the inflection signal for accelerated industry consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Monomers | Captive acrylic and polyurethane precursor supply secures margin pools against feedstock volatility. |
| CE Marking Pathway Investment | Harmonized European standards certification displaces uncertified competitors in Alpine infrastructure tenders. |
| CSRD Advisory Service Development | Lifecycle assessment capabilities capture specification authority from Dutch and French sustainability teams. |
| Reactive Hot Melt Polyurethane Scale-Up | Moisture-cure platforms enable just-in-sequence delivery for Stuttgart and Munich automotive seating manufacturers. |
| Eastern European Technical Service Expansion | Polish and Czech industrial zones offer whitespace for structural bonding qualification support. |
Research Methodology
Trade databases, ECHA regulatory filings, and Cefic industry statistics formed the secondary backbone for this analysis. Primary interviews with adhesive formulators, automotive platform engineers, construction procurement leads, and distribution channel partners validated demand assumptions. Bottom-up volume estimates triangulated against top-down market sizing across formulation chemistry segments and application verticals.
Historical trendline analysis established baseline growth patterns across the analysis window without assuming structural breaks. Segmentation modeling incorporated product type, application requirements, end-user industry, and regional production hub configurations. CAGRs derived from fitted trend extrapolation adjusted for regulatory phase-out timelines and feedstock cost trajectory assumptions.
The model assumes a particular technology adoption path; alternative pathways for solvent-free bio-based platforms would alter the outlook if qualification protocols accelerate or stall. Forecasts reflect documented assumptions about REACH implementation timelines and automotive electrification content per vehicle. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Roofing Adhesive Market
Adhesives & Sealants
South Korea Sealants Market
Adhesives & Sealants
Europe Acrylic Adhesives Market
Adhesives & Sealants
North America Cyanoacrylate Adhesives Market
Adhesives & Sealants
Canada Adhesives Market
Adhesives & Sealants
Tobacco and Cigarette Adhesives Market
Adhesives & Sealants
Global Self-Adhesive Vinyl Films Market
Adhesives & Sealants
Debonding-on-Demand Adhesives for EV Battery Modules Market
Adhesives & Sealants
Global Hygiene Adhesives Market
Adhesives & Sealants
Construction Adhesives and Sealants Chemical Market
Adhesives & Sealants
EV Adhesives Market
Adhesives & Sealants
Polyester Hot Melt Adhesives Market
Adhesives & Sealants
Floor Tile Adhesive Market
Adhesives & Sealants
Lamination Adhesive Market
Adhesives & Sealants
France Adhesives Market
Adhesives & Sealants
Mirror Adhesive Market