
 Windscreen Adhesive Market | 2026-2036
Windscreen Adhesive Market Size, Share, and Industry Trends Forecast 2026-2036
Windscreen Adhesive Market Insights
Asset-light leasing models for adhesive dispensing equipment are tilting competitive dynamics toward mid-tier suppliers that lack capital for full production lines. Henkel AG & Co. KGaA leverages its captive polyurethane resin supply to protect margin pools across European OEM contracts. Sika AG anchors its position through deep specialization in cold-cure systems for commercial vehicle assembly. Dow competes on manufacturing scale, operating integrated silane-modified polymer plants that feed both automotive and marine adhesive grades.
Windscreen adhesive denotes a structural bonding agent formulated primarily from polyurethane, silicone, or modified acrylic chemistries, engineered to achieve shear strengths exceeding 6 MPa while maintaining elastomeric flexibility across temperature extremes from minus 40 to 90 degrees Celsius; its core function is to bond laminated safety glass to vehicle body flanges, transferring crash loads and maintaining occupant compartment integrity during rollover events. Polyurethane formulations dominate current OEM specification sheets due to proven durability in structural glazing applications, while silicone adhesives capture expanding share in heavy machinery and marine segments where thermal cycling resistance outweighs pure strength requirements. The technology dimension reveals cold-cure systems leading in aftermarket channels where portable dispensing and ambient curing eliminate oven infrastructure, whereas hot-melt platforms concentrate in high-volume passenger vehicle plants seeking sub-60-second fixture times.
Federal Motor Vehicle Safety Standard 212/208 in the United States and ECE R43 in Europe both mandate retention of bonded windscreens during headform impact and rollover tests, directly elevating structural adhesive performance thresholds and disqualifying lower-grade sealants from type-approved applications. China's GB standards for automotive glass bonding, administered by SAMR, now require localized testing documentation that extends certification timelines for imported formulations. Stakeholders must monitor divergence between regional crash-test protocols and adhesive qualification procedures, as compliance investments in one jurisdiction do not automatically transfer to approval in others.
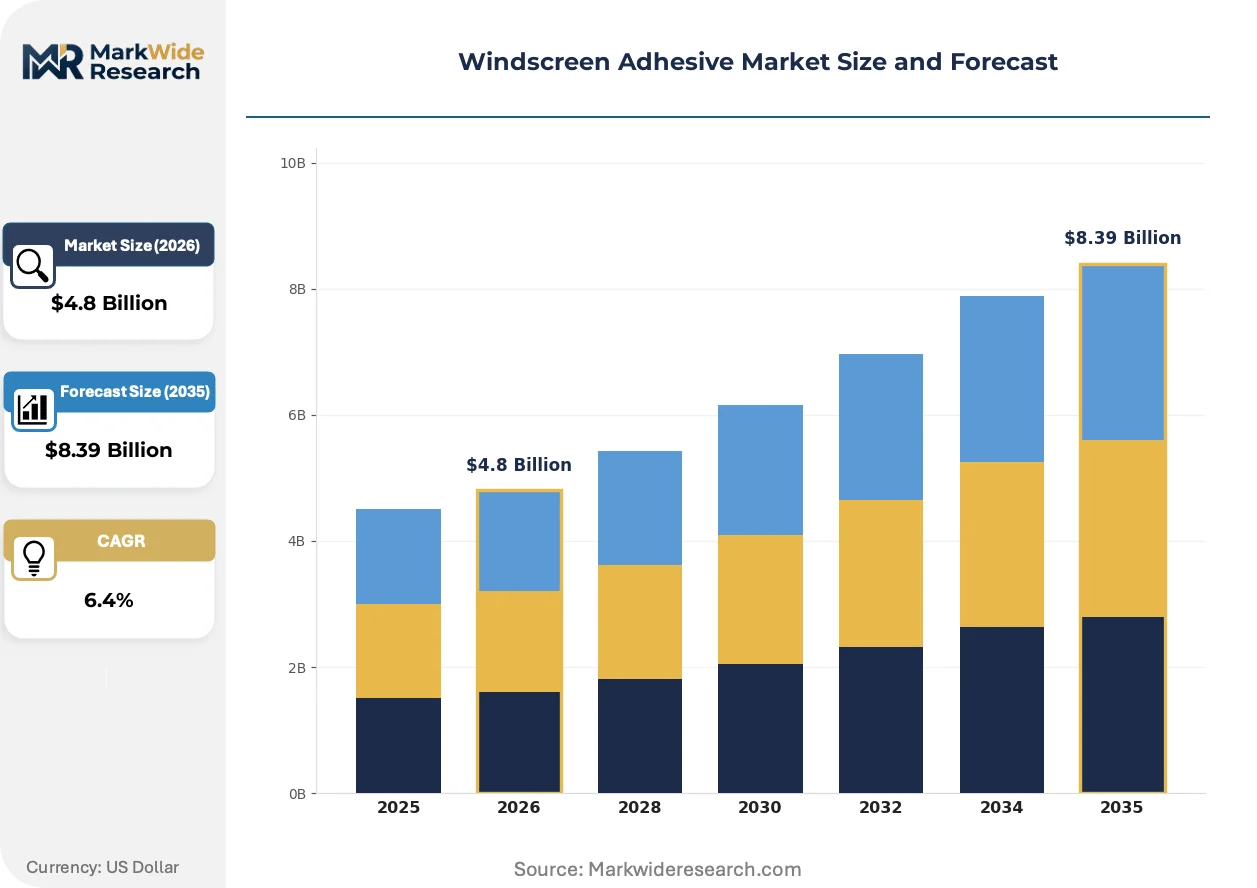
Market Dynamics
Automotive OEMs are consolidating direct adhesive procurement as ECE R43 crashworthiness standards tighten across Europe, compressing supplier margins while elevating technical qualification barriers for secondary manufacturers.
Growth Catalysts
- ECE R43 compliance mandates:European regulators now require bonded windscreen retention during rollover tests, disqualifying lower-grade sealants and forcing specification upgrades across premium vehicle platforms.
- Polyurethane cold-cure systems:Portable dispensing technology eliminates oven infrastructure requirements, unlocking aftermarket penetration in independent repair networks and mobile service fleets.
- Germany's manufacturing density:Stuttgart and Munich host concentrated premium OEM assembly and glass bonding R&D clusters, creating localized demand pull for high-shear structural formulations.
Market Restraints
- MDI feedstock volatility:Methylene diphenyl diisocyanate prices fluctuate with crude oil and benzene derivatives, compressing polyurethane adhesive margins without pass-through mechanisms in annual OEM contracts.
- Silane-modified polymer supply concentration:Dow and Henkel control captive silane-terminated polymer production, limiting formulation flexibility for mid-tier suppliers dependent on merchant resin markets.
- Cure-time physics:Cold-cure systems require 4-6 hour fixture periods versus sub-60-second hot-melt cycles, constraining throughput in high-volume passenger vehicle plants.
Strategic Opportunities
- India's PLI scheme for automotive components:Production-linked incentives for advanced manufacturing create localized adhesive demand as global OEMs establish Chennai and Pune assembly operations.
- Marine and heavy machinery glazing:Silicone thermal cycling resistance outperforms polyurethane in offshore and mining equipment, opening specification expansion beyond automotive verticals.
- Asset-light dispensing equipment leasing:Mid-tier suppliers bypass capital barriers by leasing automated application systems, tilting competitive dynamics toward formulation expertise over production scale.
Industry Challenges
- Multi-jurisdiction certification timelines:China's SAMR requires localized GB standard testing documentation, extending approval cycles for European and North American formulations without mutual recognition agreements.
- Crash-test protocol divergence:NHTSA FMVSS 212 headform impact requirements differ materially from ECE R43 rollover retention criteria, forcing redundant qualification investments for suppliers serving both markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Windscreen Adhesive Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Silicone, Acrylic, Epoxy End User: OEMs, Aftermarket Providers, Independent Garages, Fleet Operators Application: Passenger Vehicles, Commercial Vehicles, Heavy Machinery, Marine Technology: Hot Melt, Cold Cure, Pre-Cured, One-Part |
| Companies Covered | Henkel AG & Co. KGaA, 3M Company, Sika AG, Dow, H.B. Fuller Company, Arkema, Bostik, Lord Corporation, Avery Denison Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Windscreen Adhesive Market Trends and Innovations
Formulation chemistry and curing platforms are diverging across OEM and aftermarket channels, with regulatory pressure accelerating specification tiering between structural and non-structural applications.
Silane-modified polyurethane hybrid chemistry is migrating from marine sealing into automotive structural glazing, where Sika and Dow formulations now compete with conventional two-component systems. Commercial vehicle manufacturers in Brazil and Australia specify these hybrids for chassis-mounted cab glazing where thermal expansion coefficients mismatch. The technology is migrating from specialty marine grades into mainstream automotive specifications by combining polyurethane shear strength with silicone UV resistance.
REACH Annex XVII restrictions on isocyanate workplace exposure entered full enforcement across EU member states, mandating automated dispensing and enclosed mixing systems in assembly plants. German KBA type-approval documentation now requires adhesive batch traceability from resin synthesis through vehicle VIN assignment. Tier-1 suppliers are responding by consolidating formulation production at single-site facilities with integrated quality laboratories.
Leasing arrangements for robotic dispensing cells now displace capital purchase models among independent glass installers and regional collision repair chains. Equipment-as-a-service contracts bundle preventive maintenance with consumable supply agreements, locking aftermarket channels into single-supplier ecosystems. This shift concentrates most visibly in Germany's dense network of authorized repair facilities serving Mercedes-Benz and BMW certified collision programs.
Windscreen Adhesive Market Segmentation
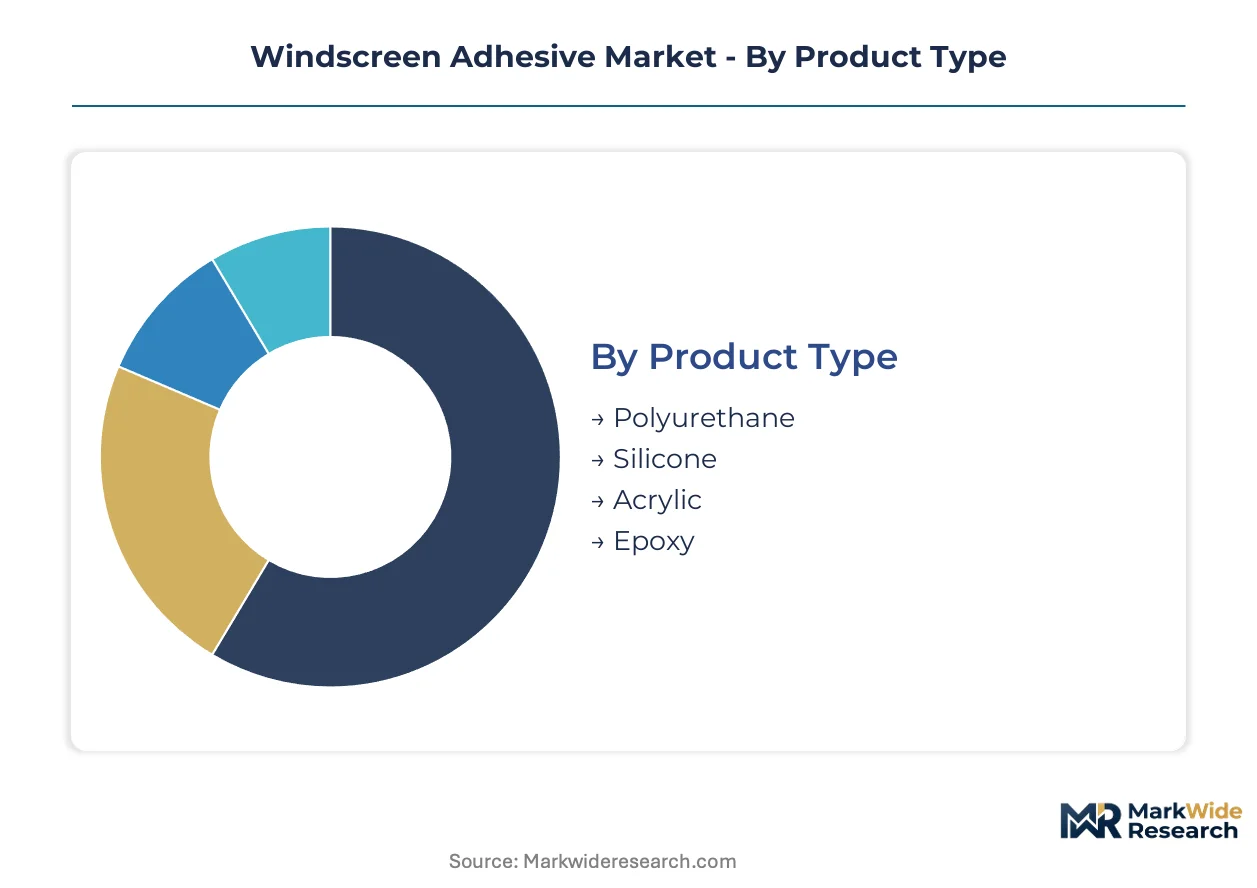
Windscreen adhesive segmentation reveals divergent technical requirements across OEM assembly lines and aftermarket repair channels. Specification tiers separate structural glazing applications governed by crash-test protocols from non-structural sealing where cost efficiency dominates.
Product Type:
Mature polyurethane formulations anchor structural glazing specifications, while emerging hybrid chemistries challenge incumbent positions in thermal cycling applications.
- Polyurethane:Two-component systems achieve shear strengths above 6 MPa with elastomeric flexibility across temperature extremes. German premium OEM assembly plants specify these formulations exclusively for rollover-rated windscreen bonding under KBA type-approval requirements.
- Silicone:Single-component moisture-cure systems deliver superior UV resistance and thermal cycling durability. Heavy machinery manufacturers in mining and offshore segments specify silicone where equipment operates across 80-degree daily temperature swings.
- Acrylic:UV-curable formulations serve niche applications requiring rapid fixture without heat activation.
- Epoxy:Rigid structural systems limited to specialty marine glazing where brittleness tolerance permits.
Polyurethane retains volume leadership; silicone holds the steepest expansion curve.
End User:
Customer type determines procurement scale and technical qualification intensity, with OEM direct purchasing concentrating specification authority.
- OEMs:Direct adhesive procurement now dominates premium vehicle platforms as ECE R43 compliance mandates elevate technical barriers. Stuttgart and Munich assembly plants require batch traceability from resin synthesis through VIN assignment.
- Aftermarket Providers:Authorized repair networks serve Mercedes-Benz and BMW certified collision programs with cold-cure systems and leased dispensing equipment.
- Independent Garages:Mobile service fleets drive portable dispensing technology adoption where oven infrastructure is unavailable.
- Fleet Operators:Commercial vehicle managers prioritize rapid turnaround over maximum structural rating for non-passenger applications.
OEMs command specification authority; aftermarket providers are gaining share fastest through equipment-as-a-service contracts.
Application:
Vehicle category dictates performance thresholds, with passenger safety regulations creating the most stringent adhesive qualification requirements.
- Passenger Vehicles:Laminated safety glass bonding must retain occupant compartment integrity during FMVSS 212 headform impact and ECE R43 rollover tests.
- Commercial Vehicles:Cab glazing on chassis-mounted assemblies in Brazil and Australia specifies silane-modified polyurethane hybrids where thermal expansion coefficients mismatch between glass and steel.
- Heavy Machinery:Mining and construction equipment glazing prioritizes thermal cycling resistance over pure shear strength.
- Marine:Offshore vessel specifications demand UV-stable formulations with 20-year service life expectations.
Passenger vehicles dominate value concentration; marine applications climb the fastest on specification expansion.
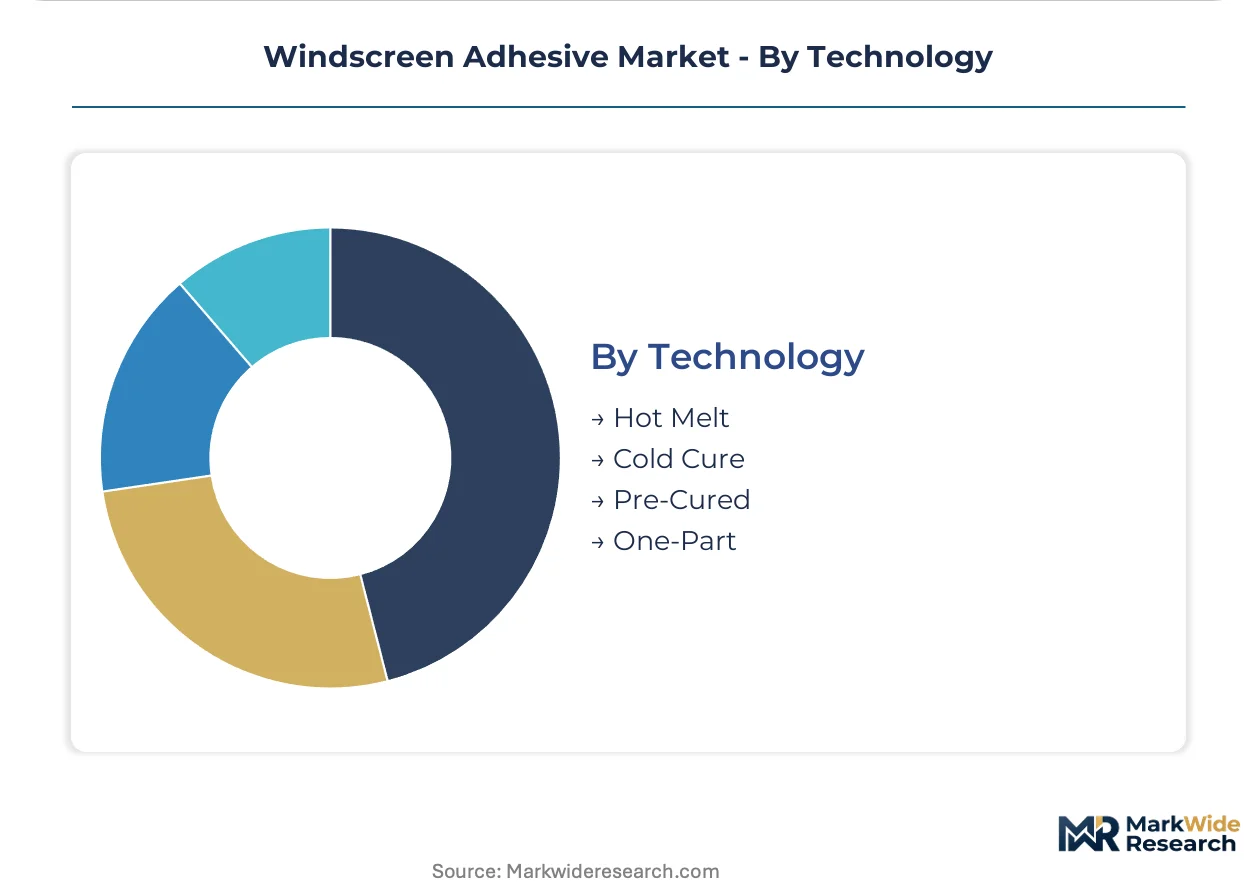
Technology:
Cure mechanism separates high-volume manufacturing from distributed aftermarket service models.
- Hot Melt:Reactive polyurethane systems achieve sub-60-second fixture times in high-volume passenger vehicle plants. Oven infrastructure requirements limit deployment to greenfield assembly facilities.
- Cold Cure:Ambient-temperature systems eliminate capital-intensive curing ovens. Independent glass installers and regional collision repair chains adopt these for 4-6 hour fixture periods.
- Pre-Cured:Factory-cured adhesive tapes serve specialty applications requiring immediate handling strength.
- One-Part:Moisture-cure silicones simplify application logistics for field service operations.
Hot melt retains manufacturing dominance; cold cure expands most quickly through equipment leasing models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in windscreen adhesive formulations tilt toward net-exporting economies with captive resin synthesis capacity. Import dependence concentrates in assembly-heavy markets lacking upstream chemical infrastructure.
United States
NHTSA's FMVSS 212 headform impact protocols drive structural adhesive specification upgrades across Detroit Three assembly networks. The Inflation Reduction Act's domestic content incentives accelerate localized formulation production. Michigan and Ohio host concentrated automotive glass bonding operations serving light-truck and SUV platforms.
Germany
KBA type-approval requirements now mandate batch traceability from resin synthesis through VIN assignment for rollover-rated windscreen bonds. REACH Annex XVII isocyanate workplace exposure rules enforce automated dispensing investments across Stuttgart and Munich assembly plants. Baden-Württemberg's premium OEM clusters anchor European demand for high-shear polyurethane systems.
China
SAMR-administered GB standards for automotive glass bonding require localized testing documentation that extends certification timelines for imported formulations. The dual carbon goals pressure MDI feedstock sourcing toward lower-carbon intensity pathways. Yangtze River Delta manufacturing zones concentrate domestic adhesive blending capacity for BYD and Tesla Shanghai operations.
India
PLI scheme production-linked incentives for advanced automotive components create localized adhesive demand as global OEMs establish Chennai and Pune assembly bases. BIS certification requirements for automotive chemicals remain in harmonization with UN ECE regulations. Tamil Nadu's electronics and auto component corridors attract formulation toll-manufacturing investments.
Brazil
ANVISA chemical registration requirements intersect with INMETRO automotive safety standards for bonded glazing in commercial vehicle applications. Mercosur trade rules facilitate Argentine and Uruguayan adhesive imports for assembly operations. São Paulo state's ABC automotive cluster concentrates windshield installation capacity for Fiat and Volkswagen truck platforms.
Windscreen Adhesive Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in resin and curing-agent supply. The vendor base organizes around three strata: multinational chemical conglomerates with captive polymer production, mid-tier formulators leasing dispensing infrastructure, and regional distributors serving independent repair networks. Consolidation pressures concentrate among formulation specialists lacking backward integration into MDI or silane-terminated polymer supply. Competitive moves center on equipment-as-a-service contracts locking aftermarket channels and single-site consolidation of quality laboratories for KBA traceability compliance.
Among European-headquartered chemical conglomerates, Henkel AG & Co. KGaA and Sika AG occupy positions exemplifying divergent specialization strategies—Henkel leveraging captive polyurethane resin supply across OEM contracts, Sika anchoring cold-cure system expertise for commercial vehicle assembly. Dow represents the scale-driven archetype with integrated silane-modified polymer plants feeding multiple adhesive grades. These three entities collectively illustrate how raw material access, curing-technology specialization, and manufacturing scale define competitive positioning in structural glazing applications.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| 3M Company |
| Sika AG |
| Dow |
| H.B. Fuller Company |
| Arkema |
| Bostik |
| Lord Corporation |
| Avery Denison Corporation |
| Others |
Pricing and Supply Chain Analysis
German captive production of methylene diphenyl diisocyanate anchors polyurethane adhesive supply, concentrating margin capture with resin-integrated formulators serving Stuttgart and Munich OEM clusters. Annual contract structures limit feedstock pass-through, compressing mid-tier suppliers dependent on merchant MDI markets.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with annual volume commitments and limited price renegotiation windows. Pricing stratifies across structural certification tiers, with KBA type-approved formulations commanding premiums over general-purpose grades. Cost compression in mid-tier supply is intensifying because REACH Annex XVII compliance investments are not fully recoverable under legacy contract terms. Independent aftermarket channels exhibit highest price sensitivity due to equipment leasing overhead, while premium OEM direct procurement shows lowest sensitivity given crashworthiness liability exposure.
Supply Chain Analysis
MDI feedstock synthesis concentrates in Germany, Belgium, and China, with Dow and Henkel maintaining captive supply that limits formulation flexibility for non-integrated competitors. The supply chain draws from benzene derivatives, crude oil fractions, and silane-terminated polymer precursors. Single-source vulnerability concentrates in silane-modified polymer production where Dow and Henkel control merchant availability. Distribution runs through Tier 1 automotive suppliers with direct OEM dispatch, bypassing traditional chemical distribution for structural glazing specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment-as-a-service ecosystems are reconfiguring aftermarket access, with interoperability between dispensing hardware and consumable supply locking independent installers into single-supplier platforms.
For Market Incumbents: Harden batch traceability infrastructure from resin synthesis through VIN assignment to satisfy KBA documentation mandates. Consolidate formulation production at single-site facilities with integrated quality laboratories. Cold-cure system commoditization from leasing-enabled mid-tier entrants threatens margin pools in aftermarket channels; backward integration into silane-terminated polymer production protects formulation flexibility. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-supported automotive corridors where localized adhesive blending capacity lags OEM assembly expansion. Target Chennai and Pune operations with toll-manufacturing partnerships that satisfy BIS certification requirements. Marine and heavy machinery glazing offers specification expansion beyond automotive verticals where thermal cycling resistance requirements favor silicone hybrid formulations. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier formulators lacking captive resin supply but holding equipment-as-a-service contract portfolios. Five-to-ten year viability hinges on consolidation into integrated platforms with backward polymer control. The signal to watch is KBA type-approval documentation consolidation favoring single-site producers with end-to-end traceability systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MDI Synthesis | Captive feedstock supply protects margin pools under volatile benzene derivative pricing. |
| Single-Site Quality Laboratory Consolidation | KBA traceability mandates favor integrated production with end-to-end batch documentation. |
| Equipment-as-a-Service Contract Expansion | Leasing models lock aftermarket channels into single-supplier ecosystems across Germany's repair networks. |
| Silane-Modified Polymer Capacity Addition | Hybrid chemistry migration requires UV-resistant polymer supply for thermal cycling applications. |
| Localized Blending Investment in India | PLI scheme incentives attract toll-manufacturing for BYD and Tesla Shanghai supply chains. |
Research Methodology
The analysis maps polyurethane, silicone, and hybrid chemistry sub-sectors, each validated through procurement leads at automotive OEMs, technical directors at adhesive formulators, plant managers at resin synthesis facilities, and aftermarket equipment distributors. Primary interviews combined with secondary validation from customs trade data, ACC and Cefic chemical industry reports, SEC 10-K filings, and vehicle production databases. Bottom-up volume estimates triangulated against top-down market sizing across formulation chemistries and cure technologies.
Assumptions held fixed include ECE R43 and FMVSS 212 regulatory stability, MDI feedstock availability from major synthesis hubs, and OEM direct procurement consolidation trends. Variables stress-tested encompass benzene derivative price volatility, REACH enforcement intensity, and China GB standard harmonization timelines. Segmentation dimensions modeled span chemistry type, cure technology, end-user category, and vehicle application across the projection horizon. CAGRs derived from volume trajectory analysis against content-per-vehicle assumptions and regional production cluster expansion.
Stress conditions across MDI price bands, regulatory certification timelines, and equipment leasing penetration rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding feedstock supply continuity and crashworthiness standard stability. Cross-checking against IHS Markit vehicle registration data and chemical trade flow statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
North America Glue-Laminated Timber Market
Adhesives & Sealants
Global Non-Woven Adhesives Market
Adhesives & Sealants
Carpet Adhesive Market
Adhesives & Sealants
Rubber Repair Adhesives Market
Adhesives & Sealants
Middle East and Africa Human Fibrin Glue Market
Adhesives & Sealants
Adhesive Equipment Market
Adhesives & Sealants
South America Contact Adhesives Market
Adhesives & Sealants
Asia-Pacific Hot-Melt Adhesives Market
Adhesives & Sealants
Acrylates Copolymer Market
Adhesives & Sealants
Polyurethane Sealant Market
Adhesives & Sealants
South America Adhesives Market
Adhesives & Sealants
Japan Sealants Market
Adhesives & Sealants
Lead Encapsulants Market
Adhesives & Sealants
South America Construction Adhesives Market
Adhesives & Sealants
India Waterproofing Solutions Market
Adhesives & Sealants
Marine Sealants Market