
 North America Phenol Market | 2026-2036
North America Phenol Market Size, Share, and Industry Trends Forecast 2026-2036
North America Phenol Market Intelligence
A wide capital-intensity divergence between players is bifurcating competitive dynamics across the North America phenol landscape. INEOS Phenol leverages its integrated cumene-to-phenol chain along the Gulf Coast to sustain margin resilience against feedstock volatility. Dow Inc. anchors its position through deep backward integration into refinery-grade propylene and benzene supplies.
Phenol, also known as carbolic acid or hydroxybenzene, is an aromatic organic compound with the chemical formula C₆H₅OH, typically produced via the cumene oxidation process where cumene hydroperoxide cleaves into phenol and acetone as co-products. This white crystalline solid serves as a foundational chemical intermediate for manufacturing bisphenol A, phenolic resins, caprolactam, and alkylphenols that feed plastics, adhesives, and pharmaceutical synthesis chains. Bisphenol A dominates product-type value capture due to its lock-in with polycarbonate and epoxy resin demand from automotive and electronics end users. Phenolic resins hold mature, defensible margin pools in construction adhesives and insulation binders where thermal performance specifications resist substitution.
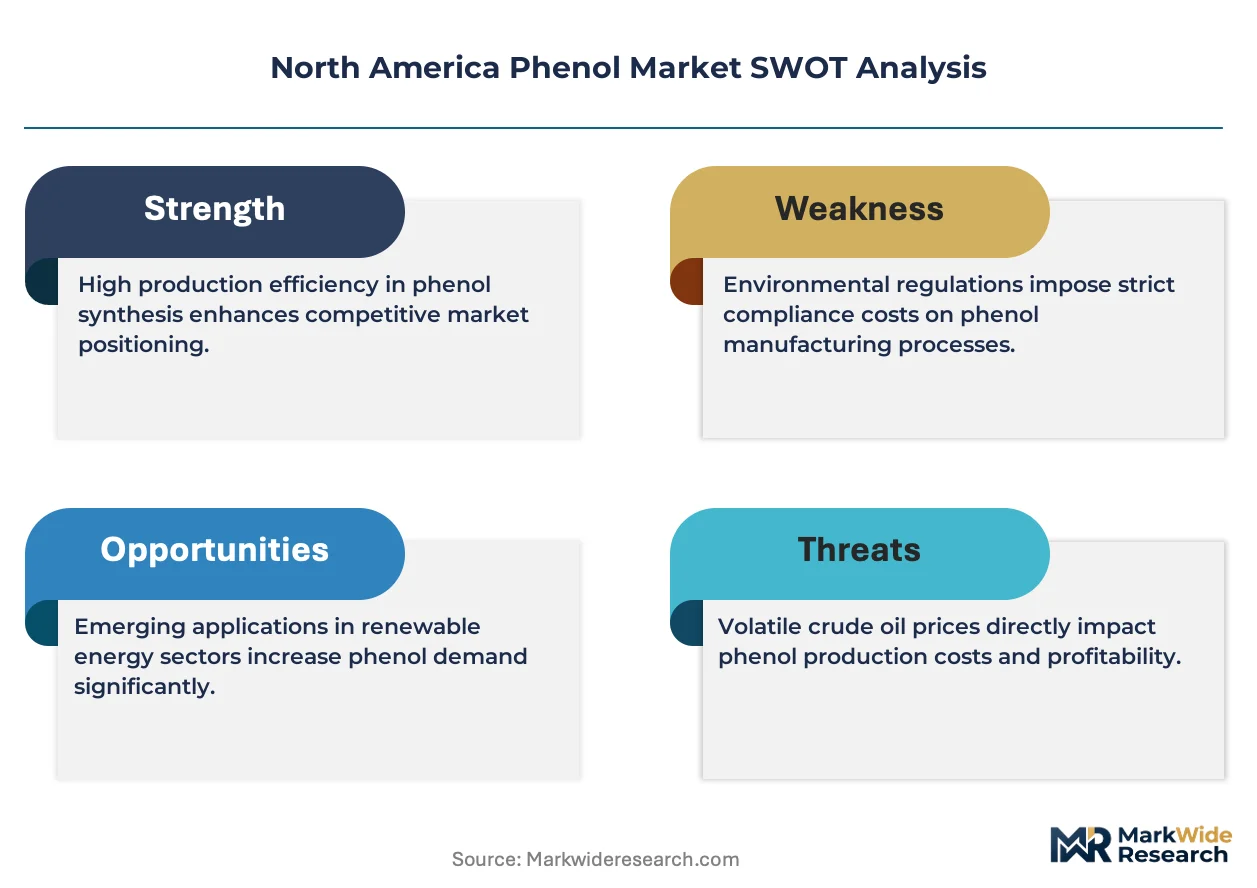
EPA Clean Air Act standards and OSHA permissible exposure limits for phenol vapor shape capital allocation toward emission control systems and closed-loop process designs across US production assets. The Toxic Substances Control Act and state-level air quality implementation plans in Texas and Louisiana add compliance layers that favor scaled operators with dedicated environmental health and safety infrastructure. Stakeholders must monitor cumene supply tightness and acetone co-product offtake dynamics as decisive variables for capacity economics and site-level investment timing.
Market Dynamics
Integrated Gulf Coast cumene-phenol-acetone complexes are tightening feedstock arbitrage windows, forcing merchant buyers into longer-term offtake commitments to secure volume certainty against volatile benzene and propylene input costs.
Growth Catalysts
- Automotive lightweighting mandates:NHTSA Corporate Average Fuel Economy standards are accelerating polycarbonate penetration in vehicle glazing and structural components, pulling bisphenol A demand through the phenol value chain.
- Texas-Louisiana cluster expansion:Concentrated petrochemical infrastructure along the Gulf Coast enables economies of scale in cumene oxidation capacity that smaller inland sites cannot replicate.
- OSHA workplace exposure rulemaking:Stricter permissible exposure limits for phenol vapor are driving capital deployment into closed-loop process designs that reduce fugitive emissions and liability exposure.
Market Restraints
- Benzene price volatility:Refinery-grade benzene supply fluctuations from steam cracker operating rate adjustments transmit directly into phenol production cost instability.
- Acetone co-product absorption:Weak acetone offtake in solvents and methyl methacrylate synthesis compresses effective phenol netbacks during periods of oversupply.
- EPA Clean Air Act compliance layering:New source review requirements and Title V permitting timelines extend brownfield expansion cycles by 18-36 months.
Strategic Opportunities
- Mexico manufacturing reshoring:Nearshoring of automotive and electronics assembly is creating incremental phenolic resin and bisphenol A demand in Monterrey and Tijuana industrial corridors.
- Bio-based feedstock pathways:Lignin-derived phenol pilot programs are attracting Department of Energy funding for renewable chemical intermediate qualification.
- Carbon capture integration:Inflation Reduction Act 45Q tax credits are incentivizing post-combustion capture retrofits at high-emission oxidation units.
Industry Challenges
- Process control engineering scarcity:Specialized expertise in cumene hydroperoxide cleaver optimization and safety instrumented systems is concentrated among retiring workforce cohorts in Texas and Louisiana.
- Legacy distributed control system migration:Decades-old DCS architectures at established Gulf Coast sites require phased replacement to support advanced process control and predictive maintenance analytics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Phenol Market |
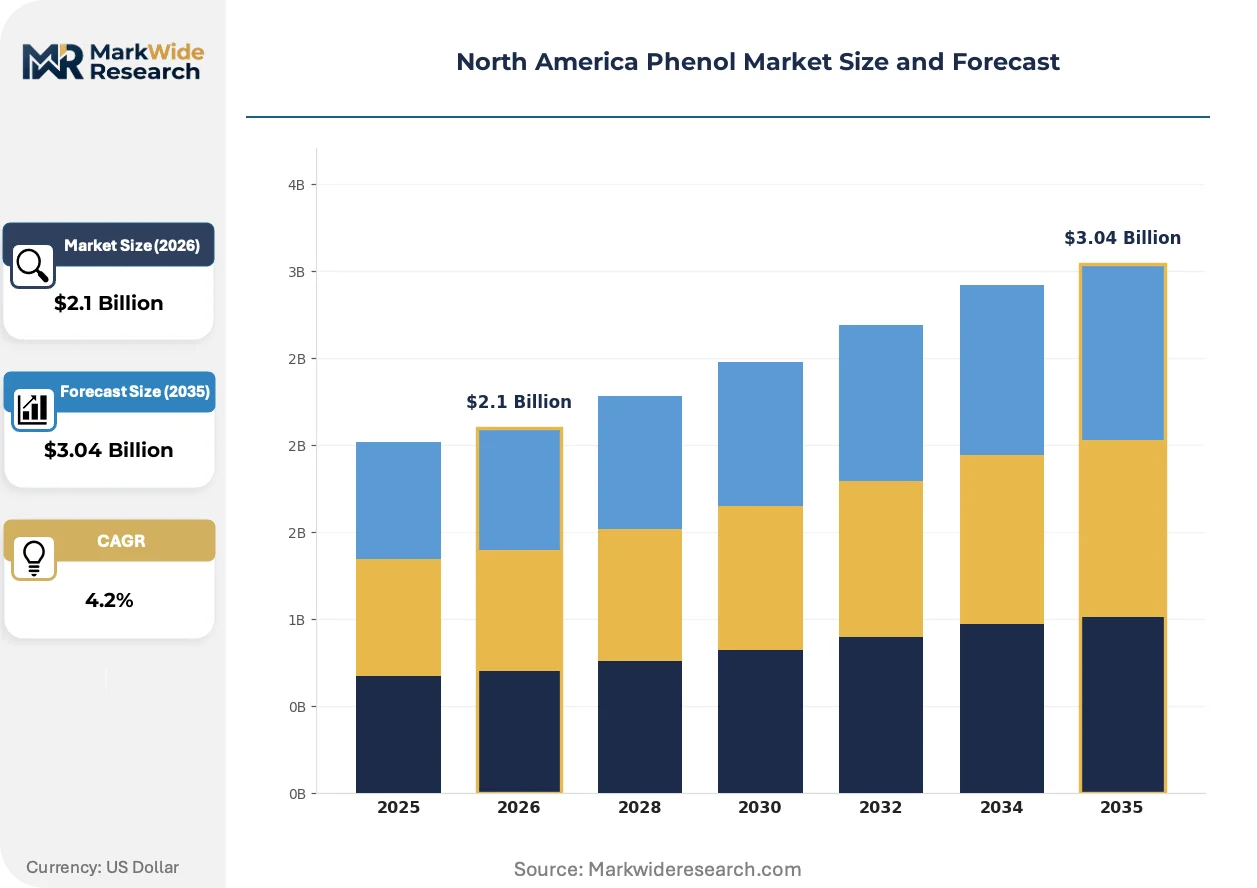
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.04 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acetone, Bisphenol A, Resins, Liquid Phenol Application: Plastics, Pharmaceuticals, Coatings, Adhesives End User: Automotive, Construction, Electronics, Healthcare Distribution Channel: Direct Sales, Online, Distributors, Retail |
| Companies Covered | INEOS Phenol, Shell Chemicals, Dow Inc., Formosa Chemicals & Fibre Corporation, Mitsui Chemicals Inc., ALTIVIA, AdvanSix Inc., SI Group, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Phenol Market Strategic Shifts & Innovations
Cumene oxidation process intensification is compressing capital intensity thresholds, while regulatory pressure on co-product economics and end-use substitution risks are forcing producers to reconceptualize site-level competitive positioning.
Advanced membrane separation technology for phenol-acetone purification is decomposing traditional distillation energy requirements. Automotive polycarbonate compounders in Michigan and Ohio are piloting these units to reduce steam consumption and carbon intensity metrics. The technology is decomposing the historical trade-off between purity specifications and operating cost at medium-scale integrated sites.
EPA Risk Management Plan amendments are tightening process safety information disclosure and third-party audit requirements for high-hazard chemical facilities. Phenol producers must now submit updated worst-case release scenarios and response protocols. Texas and Louisiana facilities face accelerated compliance timelines relative to other chemical manufacturing categories.
Direct long-term contracting between phenol producers and polycarbonate resin manufacturers is displacing merchant market spot transactions. Tier-one automotive suppliers in Detroit and Windsor are consolidating supplier bases to secure volume commitments and technical service support. This concentration is most visible in the Great Lakes automotive supply corridor where just-in-time delivery requirements dominate procurement specifications.
North America Phenol Market Segmentation
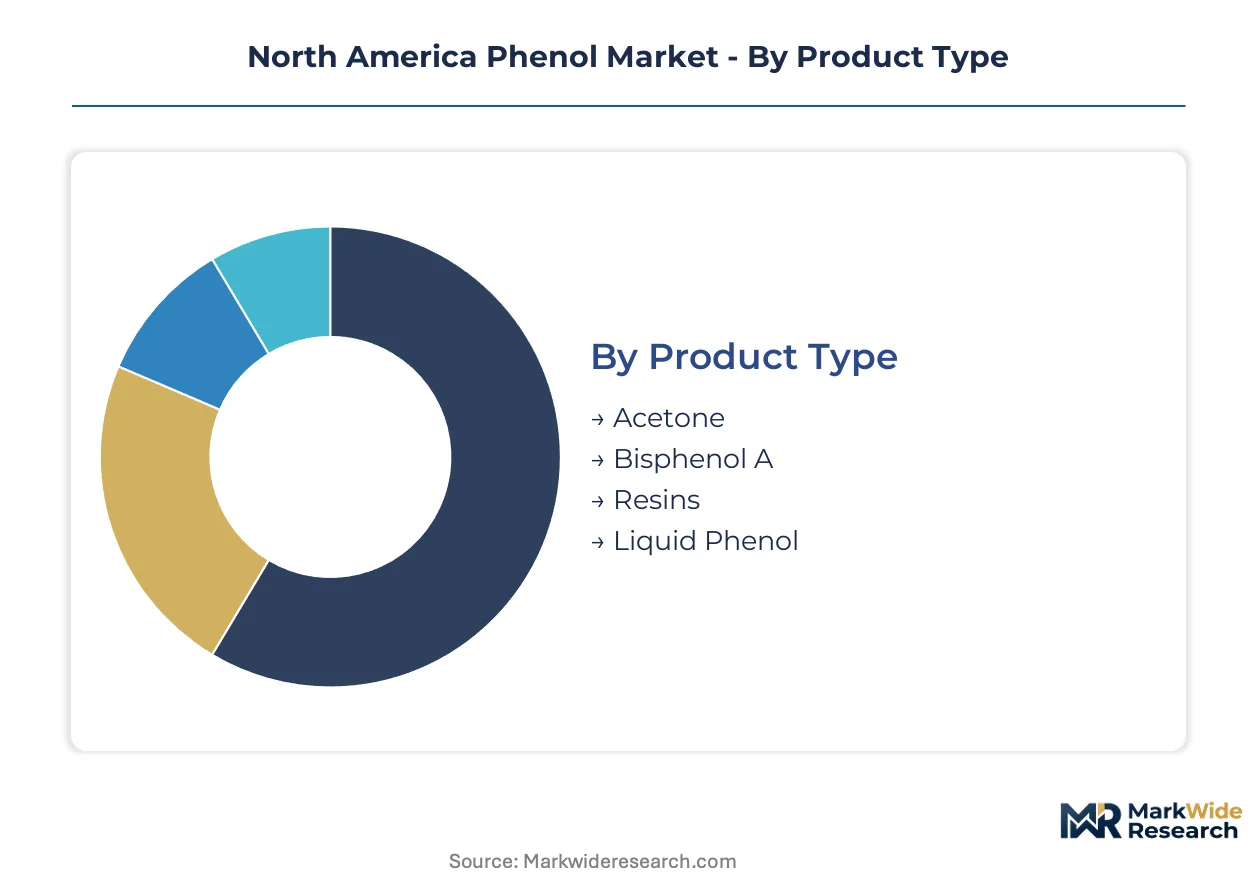
Phenol market segmentation reveals how EPA and OSHA compliance burdens concentrate differently across product grades and end-use specifications. Regulatory thresholds for residual impurities and vapor exposure limits create tiered qualification barriers that reshape procurement patterns across the value chain.
Product Type:
EPA Clean Air Act emission standards and OSHA permissible exposure limits apply differential stringency based on product purity tiers and downstream application criticality.
- Bisphenol A:High-purity grade specification (99.5%+) required for polycarbonate polymerization in automotive glazing and electronics housings. Demand concentrates in Michigan and Ohio automotive supply corridors where NHTSA fuel economy standards accelerate polycarbonate substitution for glass and metal. FDA food-contact approvals for epoxy can linings add compliance layers that favor established producers with dedicated regulatory affairs infrastructure.
- Acetone:Co-product of cumene oxidation with purity grades spanning technical solvent to pharmaceutical specification. Gulf Coast petrochemical clusters in Texas and Louisiana dominate merchant supply where refinery-grade propylene integration sustains margin resilience against benzene feedstock volatility.
- Resins:Phenol-formaldehyde and phenol-novolac grades for thermal insulation binders and friction materials. Construction adhesive specifications in Texas and Louisiana industrial zones favor suppliers with ISO 9001 certification and documented formaldehyde emission compliance.
- Liquid Phenol:Molten or aqueous solution forms for captive chemical synthesis and disinfectant manufacturing. Healthcare sector procurement in US hospital systems requires USP-grade documentation and batch-level traceability for antiseptic formulations.
Established volume favors Bisphenol A; emerging adoption favors pharmaceutical-grade liquid phenol.
Application:
Cost tier differentiation separates commodity-scale plastic intermediates from specification-driven pharmaceutical and coating segments.
- Plastics:Polycarbonate and epoxy resin feedstocks dominate volume throughput. Automotive lightweighting mandates from NHTSA Corporate Average Fuel Economy standards pull demand through Detroit and Windsor manufacturing corridors where just-in-time delivery requirements favor direct producer relationships.
- Pharmaceuticals:Active pharmaceutical ingredient synthesis and excipient applications demand cGMP-compliant production with FDA drug master file documentation. Compounding pharmacies and generic manufacturers in New Jersey and Pennsylvania pharmaceutical clusters drive specification-grade procurement.
- Coatings:Epoxy curing agents and alkyd resin modifiers for industrial protective applications. Marine and offshore infrastructure projects in Louisiana and Texas coastal zones specify phenolic epoxy systems for corrosion resistance in saltwater environments.
- Adhesives:Phenol-resorcinol and phenol-formaldehyde binders for engineered wood products. Construction activity in US Southeast and Pacific Northwest lumber markets sustains demand for moisture-resistant adhesive formulations.
Volume concentration sits with plastics; margin expansion sits with pharmaceutical synthesis applications.
End User:
Customer type segmentation separates integrated chemical processors from specification-driven OEM procurement functions.
- Automotive:Tier-one suppliers and polycarbonate compounders in Michigan, Ohio, and Ontario anchor demand for bisphenol A with technical service requirements spanning color matching and impact testing support.
- Construction:Insulation manufacturers and engineered wood producers specify phenolic resin binders for thermal performance and fire resistance ratings in US building code jurisdictions.
- Electronics:Epoxy molding compounders for semiconductor encapsulation and printed circuit board laminates demand ultra-low ionic content grades with documented chloride and sodium specifications.
- Healthcare:Hospital disinfectant formulators and pharmaceutical API manufacturers require USP or EP-grade certification with comprehensive impurity profiling and stability data packages.
Procurement scale favors automotive; specification complexity favors healthcare.
Distribution Channel:
Supply concentration along the Gulf Coast cumene-phenol-acetone corridor shapes logistics economics and channel selection.
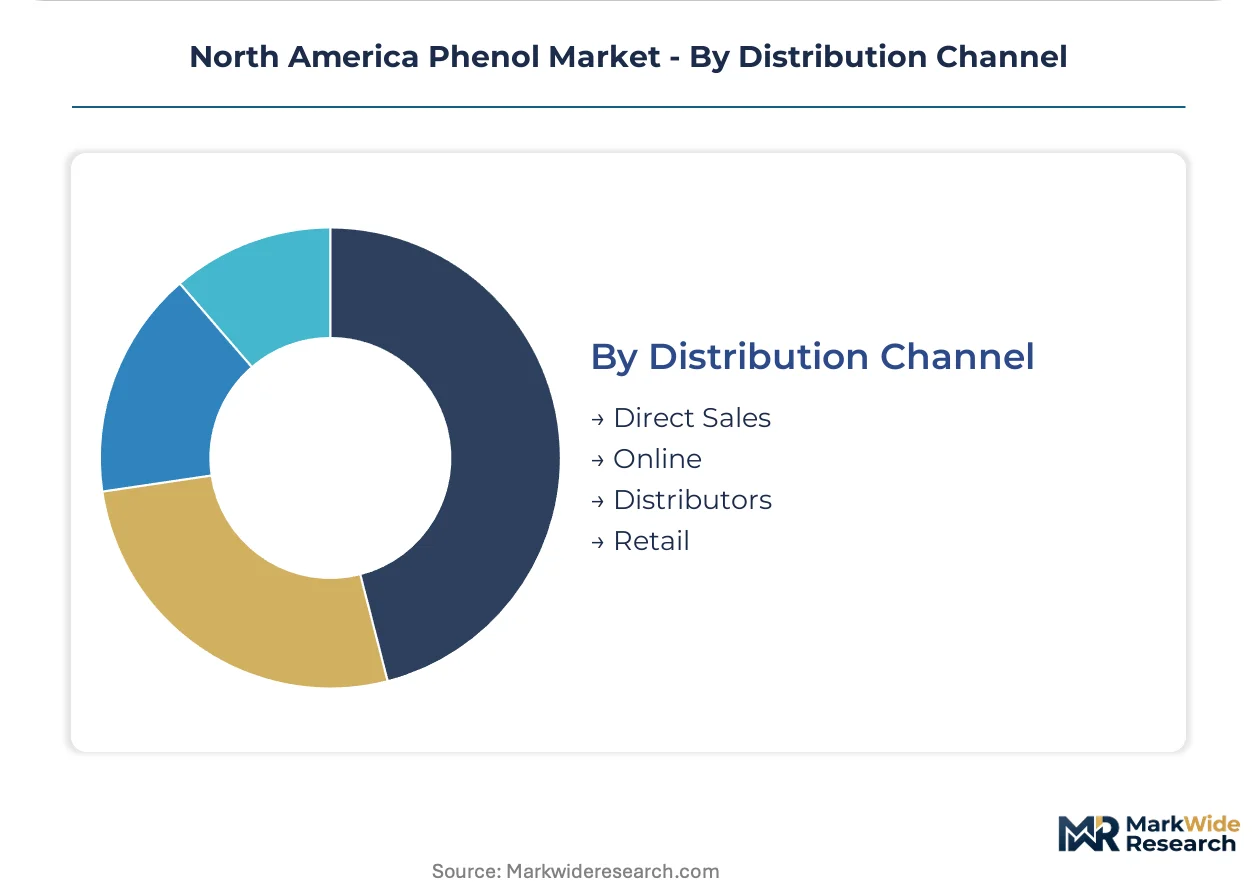
- Direct Sales:Long-term offtake agreements between phenol producers and polycarbonate resin manufacturers displace spot market transactions. Tier-one automotive suppliers consolidate supplier bases to secure volume commitments and dedicated technical service support.
- Distributors:Regional chemical distributors serve mid-scale adhesive and coating formulators with less-than-truckload quantities and blended product portfolios. Texas and Louisiana-based distributors leverage proximity to Gulf Coast production assets for inventory positioning.
- Online:E-procurement platforms for laboratory chemicals and small-volume specialty grades. Research institutions and pilot-scale chemical processors in US academic corridors utilize digital channels for specification-grade sourcing.
- Retail:Limited to consumer disinfectant and antiseptic products in pharmacy and industrial supply chains. Concentrated liquid phenol formulations for veterinary and agricultural applications move through farm supply cooperatives.
Channel margin capture favors direct sales; geographic reach extension favors distributor networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in North American phenol tilt toward net self-sufficiency, with Gulf Coast production clusters supplying domestic automotive and electronics corridors while limited cross-border trade addresses specialty grade imbalances.
United States
Texas and Louisiana anchor cumene-to-phenol capacity along the Gulf Coast petrochemical belt, feeding bisphenol A demand from Michigan and Ohio automotive glazing manufacturers. EPA Clean Air Act Title V permitting and OSHA permissible exposure limits for phenol vapor shape capital deployment timelines at expansion sites. Houston and Baton Rouge integrated complexes leverage refinery-grade benzene and propylene access to sustain margin resilience against feedstock volatility.
Canada
Ontario's polycarbonate compounding sector in Windsor and Toronto corridors draws phenol derivatives for automotive lightweighting programs serving Detroit-area OEMs. Health Canada's PMRA regulates residual impurity thresholds in phenol-based disinfectants for hospital procurement. Sarnia's chemical valley hosts specialty resin production with direct pipeline links to US Great Lakes distribution networks.
Mexico
Nuevo León and Tijuana industrial zones absorb phenolic resins and bisphenol A for nearshored automotive and electronics assembly operations. Mexico's federal environmental regulator SEMARNAT enforces air emission standards at border-region chemical processing facilities. Monterrey's manufacturing corridor is consolidating direct supply relationships with Gulf Coast phenol producers to bypass merchant distributor markups.
North America Phenol Market Key Industry Players
Concentration sits with integrated petrochemical conglomerates operating Gulf Coast cumene-phenol-acetone complexes. The competitive structure tiers between backward-integrated majors with captive benzene supply and mid-scale merchant producers dependent on spot feedstock markets. Three archetypes dominate: refinery-integrated operators, standalone oxidation specialists, and diversified chemical conglomerates with resin downstream positions. Capacity expansion cycles and long-term offtake contracting with automotive tier-one suppliers represent the primary competitive vectors reshaping supply relationships.
Within the integrated operator tier, INEOS Phenol and Dow Inc. exemplify Gulf Coast concentration through cumene-to-derivatives chain control. Shell Chemicals occupies a position spanning refinery integration and merchant market supply. AdvanSix Inc. represents the mid-scale specialist archetype with Northeast US production positioning.
| Leading Market Players |
|---|
| INEOS Phenol |
| Shell Chemicals |
| Dow Inc. |
| Formosa Chemicals & Fibre Corporation |
| Mitsui Chemicals Inc. |
| ALTIVIA |
| AdvanSix Inc. |
| SI Group |
| Honeywell International Inc. |
| Others |
Cost & Logistics Intelligence
Forty-five-day cumene inventory cycles at Gulf Coast phenol complexes translate directly into contract pricing leverage for backward-integrated operators. This lead-time band concentrates margin capture among Texas and Louisiana producers with captive benzene supply, while merchant buyers absorb feedstock volatility through indexed pricing clauses.
Pricing Analysis
Configured-to-order pricing for pharmaceutical-grade liquid phenol commands substantial premiums over standard industrial bisphenol A contracts. Contract-based long-term offtake structures dominate volume transactions, with price differentiation driven by purity certification tiers and geographic delivery cost to automotive corridors. Cost compression in commodity bisphenol A is intensifying because acetone co-product netbacks are weakening in oversupplied solvent markets. Tier-one automotive suppliers exhibit lowest price sensitivity due to just-in-time technical service requirements, while adhesive formulators show highest sensitivity to benzene-linked feedstock movements.
Supply Chain Analysis
Inventory positioning at thirty-to-sixty-day coverage levels reflects just-in-time pressures from polycarbonate compounders in Michigan and Ohio. Supply concentrates in the United States, specifically Texas and Louisiana, with secondary sourcing from Ontario's Sarnia chemical valley. Raw material dependencies center on refinery-grade benzene, polymer-grade propylene, and cumene oxidation catalysts. Single-source vulnerability runs through Gulf Coast steam cracker operating rates, which transmit directly into benzene cost instability. Distribution runs through direct producer relationships for automotive volumes, with regional distributors serving mid-scale coating and adhesive accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American phenol demand is accelerating through automotive lightweighting mandates and EPA compliance layering that favors scaled operators. This high-growth disruption rests on NHTSA fuel economy standards pulling polycarbonate penetration faster than legacy metal substitution cycles.
For Market Incumbents: Consolidate backward integration into refinery-grade propylene and benzene supplies to defend against merchant feedstock volatility. Expand closed-loop process capacity at existing Gulf Coast sites before EPA New Source Review timelines extend competitor expansion cycles by additional months. Lock in ten-to-fifteen-year direct offtake agreements with polycarbonate resin manufacturers in Detroit and Windsor corridors to preempt distributor disintermediation.
For New Entrants and Emerging Players: Differentiate on bio-based feedstock pathways to capture Department of Energy funding and sustainability premiums from automotive OEMs with Scope 3 reduction targets. Target pharmaceutical-grade liquid phenol synthesis in New Jersey and Pennsylvania corridors where FDA drug master file documentation creates qualification barriers for commodity producers. Pursue toll manufacturing partnerships with established Gulf Coast oxidation specialists rather than greenfield capacity builds.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because acetone co-product economics are compressing standalone oxidation margins and forcing merchant producers toward distressed valuations. Acquisition targets should emphasize mid-scale specialists with Northeast US positioning and resin downstream integration. Watch acetone offtake spreads in methyl methacrylate synthesis as the inflection indicator for capacity rationalization timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive benzene supply from Texas refinery streams insulates margin against spot volatility. |
| Capacity Expansion | Gulf Coast brownfield additions leverage existing OSHA-compliant infrastructure for faster permitting. |
| Long-term Supply Agreement | Direct polycarbonate producer contracts displace spot market exposure in Michigan automotive corridors. |
| Green Manufacturing Transition | Lignin-derived phenol pilot programs attract IRA funding for renewable chemical qualification. |
| Joint Venture | Monterrey manufacturing partnerships bypass distributor markups in Mexico nearshoring zones. |
Research Approach
A standing panel of phenol plant managers, polycarbonate procurement leads at Tier 1 automotive suppliers, Gulf Coast distribution channel partners, and EPA regulatory affairs directors provided ongoing calibration across the study period. Primary interviews combined with secondary validation against American Chemistry Council production surveys, SEC 10-K filings from integrated petrochemical conglomerates, customs and trade flow databases, and OSHA enforcement records. Bottom-up capacity modeling and top-down demand segmentation triangulated volume estimates.
Consistency checks validated outputs against external benchmarks including refinery operating rate correlations and automotive production forecasts. The analytical framework segmented across product purity grades, end-use industries, regional production hubs, and customer procurement archetypes throughout the forecast period. CAGRs derived from regression analysis of historical capacity utilization against polycarbonate demand elasticities, incorporating benzene-propylene spread dynamics and acetone market absorption rates as industry-specific inputs.
Forecasts assume regulatory continuity in EPA Clean Air Act implementation and OSHA permissible exposure limit enforcement; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Oxo Chemicals Market
Organic Chemicals
Europe Cycloalkanes Market
Organic Chemicals
High Purity Metal Organics Market
Organic Chemicals
N-Hexyl Chloride Market
Organic Chemicals
Dioctyl Phthalate Market
Organic Chemicals
Anisole Derivatives Market
Organic Chemicals
Isophthalic Acid Market
Organic Chemicals
North America Biphenyl Market
Organic Chemicals
Acetylacetone Market
Organic Chemicals
Chlorocyclopentane Market
Organic Chemicals
Cyclohexanone Market
Organic Chemicals
Organocatalyst Market
Organic Chemicals
US Humate Market
Organic Chemicals
Global Glycolic Acid Market
Organic Chemicals
Global Carboxylic Acid Market
Organic Chemicals
Cycloalkanes Market