
 Ocular Sealants and Glues Market | 2026-2036
Ocular Sealants and Glues Market Size, Share, and Industry Trends Forecast 2026-2036
Ocular Sealants and Glues Market Analytics
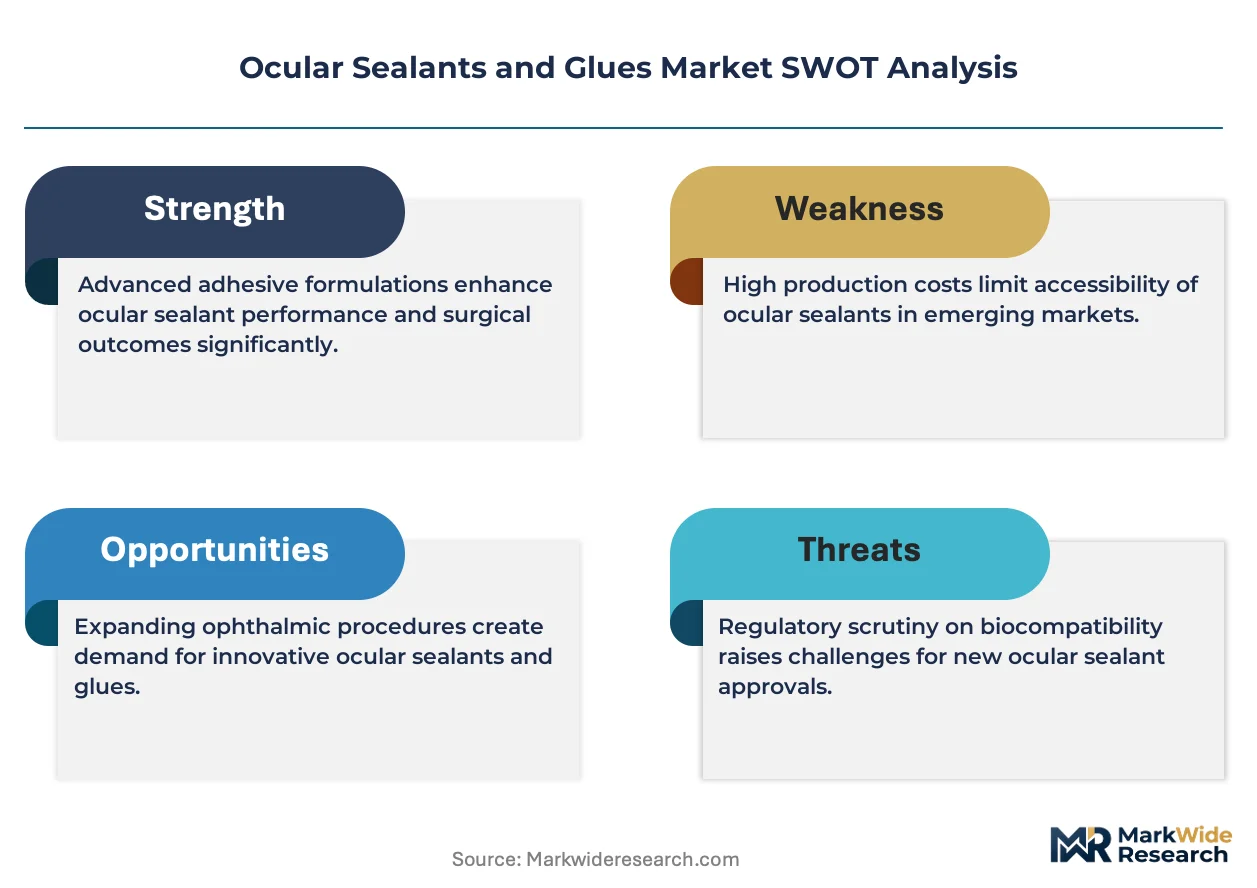
Fibrin-based formulations is rebalancing cost structures against synthetic cyanoacrylate alternatives in anterior segment procedures. Johnson & Johnson leverages its surgical suture heritage to dominate hospital formulary access. Baxter International anchors its position through plasma-derived fibrin sealant manufacturing scale. Ocular Therapeutix specializes in sustained-release hydrogel platforms that extend beyond immediate wound closure.
Ocular sealants and glues comprise biocompatible adhesive formulations designed to achieve hemostasis and tissue approximation in ophthalmic surgery, typically achieving tensile strengths between 0.1 and 0.5 N/cm² depending on polymer composition. These products serve to replace or supplement sutures in corneal, conjunctival, and scleral wounds where needle penetration risks additional tissue trauma. Biodegradable segments command premium positioning due to their elimination of removal procedures, while synthetic formulations compete on cost in high-volume cataract settings. Application demand clusters around corneal repair and cataract surgery where reimbursement pathways are most established, leaving vitreoretinal applications as the emerging margin pool.
FDA 510(k) clearance pathways and the EU Medical Device Regulation shape product development timelines and clinical evidence requirements for market entry. ISO 10993 biocompatibility testing and Japan's PMDA pharmaceutical affairs standards further segment approval complexity across major jurisdictions. Stakeholders must monitor evolving reimbursement codes for sealant-assisted procedures as these determine hospital purchasing thresholds and ambulatory surgery center adoption curves.
Market Dynamics
Synthetic cyanoacrylate formulations are compressing procedure costs in high-volume cataract settings, forcing fibrin-based alternatives to defend margin through biodegradability claims and extended-release functionality.
Growth Catalysts
- EU MDR biocompatibility mandates:Stricter ISO 10993 testing requirements are accelerating hospital formulary upgrades toward certified sealant products with documented safety profiles.
- Ambulatory surgery center expansion:United States outpatient facilities are standardizing sealant-assisted wound closure protocols to reduce suture-related complication rates and accelerate patient throughput.
- Hydrogel sustained-release platforms:Extended-duration therapeutic delivery beyond immediate closure is opening reimbursement pathways previously reserved for pharmaceutical interventions.
Market Restraints
- Human plasma supply concentration:Fibrin sealant manufacturers depend on concentrated North American and European blood plasma collection networks, creating raw material vulnerability.
- Technical limitation in tensile strength:Current biodegradable formulations achieve 0.1-0.3 N/cm² versus 0.5 N/cm² for synthetic alternatives, restricting use in high-tension scleral wounds.
- Substitution threat from advanced sutures:Barbed and antimicrobial-coated suture technologies are reclaiming share in cost-sensitive anterior segment procedures.
Strategic Opportunities
- Vitreoretinal surgery penetration:Underdeveloped sealant use in posterior segment procedures presents margin expansion potential as instrument miniaturization enables precise application.
- Japan PMDA fast-track pathways:Expedited review frameworks for regenerative medical products are shortening time-to-market for novel biologic sealant formulations.
- Direct-to-ambulatory distribution:Bypassing hospital centralized purchasing through specialized ophthalmic supply cooperatives is capturing independent surgery center volume.
Industry Challenges
- Biocompatibility certification timelines:ISO 10993-5 cytotoxicity and ISO 10993-10 sensitization testing protocols extend product development cycles by 18-24 months.
- Integration complexity with phacoemulsification workflows:Sealant application steps must synchronize with existing cataract surgical choreography without extending operating room time.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ocular Sealants and Glues Market |
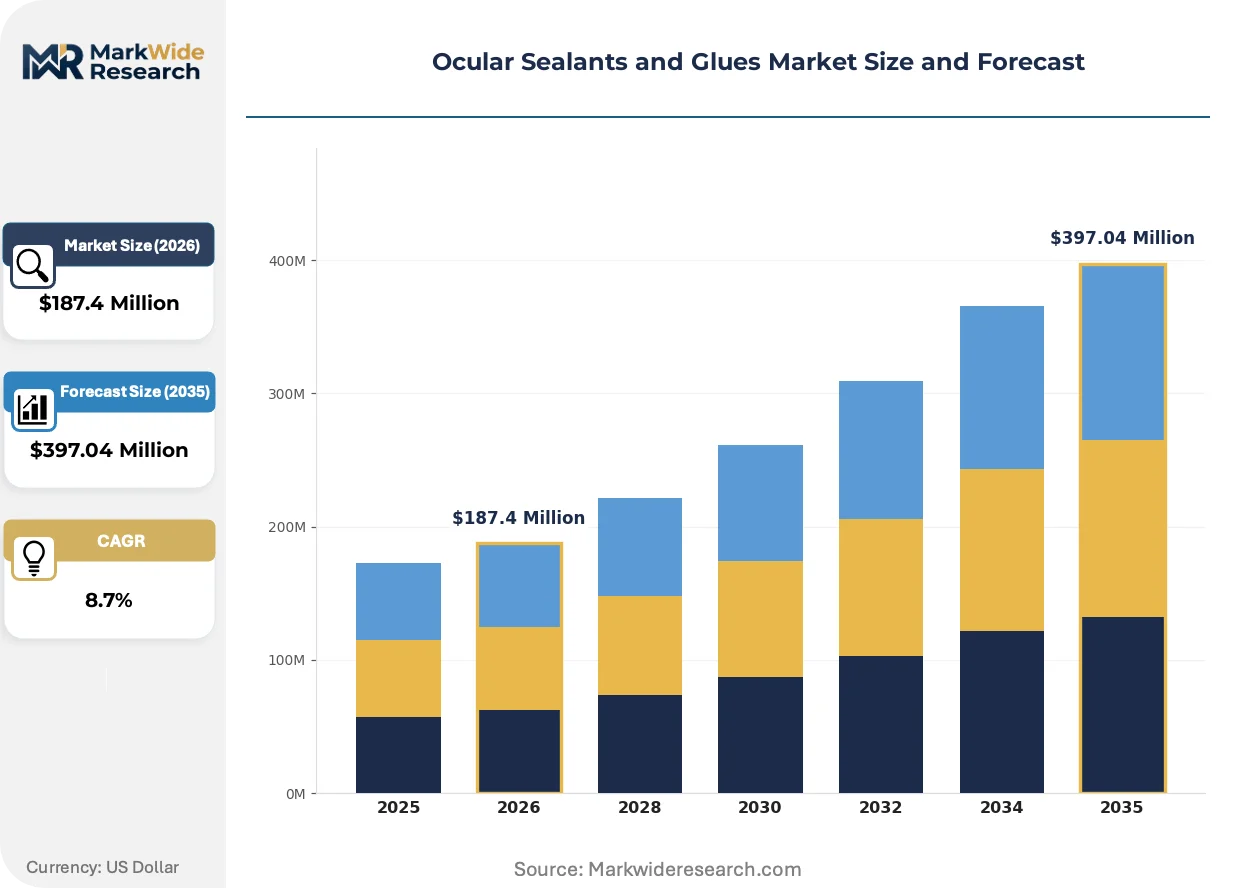
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biodegradable, Non-biodegradable, Synthetic, Natural Application: Corneal Repair, Vitreoretinal Surgery, Glaucoma Surgery, Cataract Surgery Delivery Mode: Topical, Injectable, Surgical Adhesives, Coating End User: Hospitals, Ambulatory Surgery Centers, Ophthalmology Clinics, Research Labs |
| Companies Covered | Ocular Therapeutix, Johnson & Johnson, B. Braun Melsungen AG, Cohera Medical, CryoLife, Baxter International, Reliance Life Sciences, CSL Behring, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ocular Sealants and Glues Market Evolving Landscape
Photocrosslinkable hydrogel technologies are reshaping intraoperative handling characteristics, while regulatory convergence around biocompatibility standards is compressing regional approval fragmentation.
Photocrosslinkable polyethylene glycol-based sealants are decentralizing surgical workflow control by enabling on-demand gelation under surgeon-directed LED illumination. Ambulatory surgery centers in Germany and Japan are adopting these systems to eliminate the mixing and setting time variability of traditional fibrin products. This technology is decentralizing procedure scheduling flexibility, allowing same-day case volume adjustments without sealant waste from pre-mixed kit expiration.
EU Medical Device Regulation Annex I general safety and performance requirements are mandating clinical evidence upgrades for legacy sealant products seeking recertification. Manufacturers must now submit post-market surveillance data and periodic safety update reports that exceed previous Medical Device Directive obligations. Synthetic cyanoacrylate products with longer commercial histories face the steepest compliance burden, creating temporary market access gaps that biodegradable alternatives are exploiting.
Surgeon preference is consolidating around single-use, pre-filled applicator formats that eliminate multi-step preparation and reduce nursing staff training burden. Hospital purchasing committees in the United States are embedding this format requirement into standard bid specifications, displacing traditional dual-syringe mixing systems. This specification-driven selection is most visible in integrated delivery networks where standardization across multiple ambulatory sites overrides individual surgeon brand loyalty.
Ocular Sealants and Glues Market Segmentation
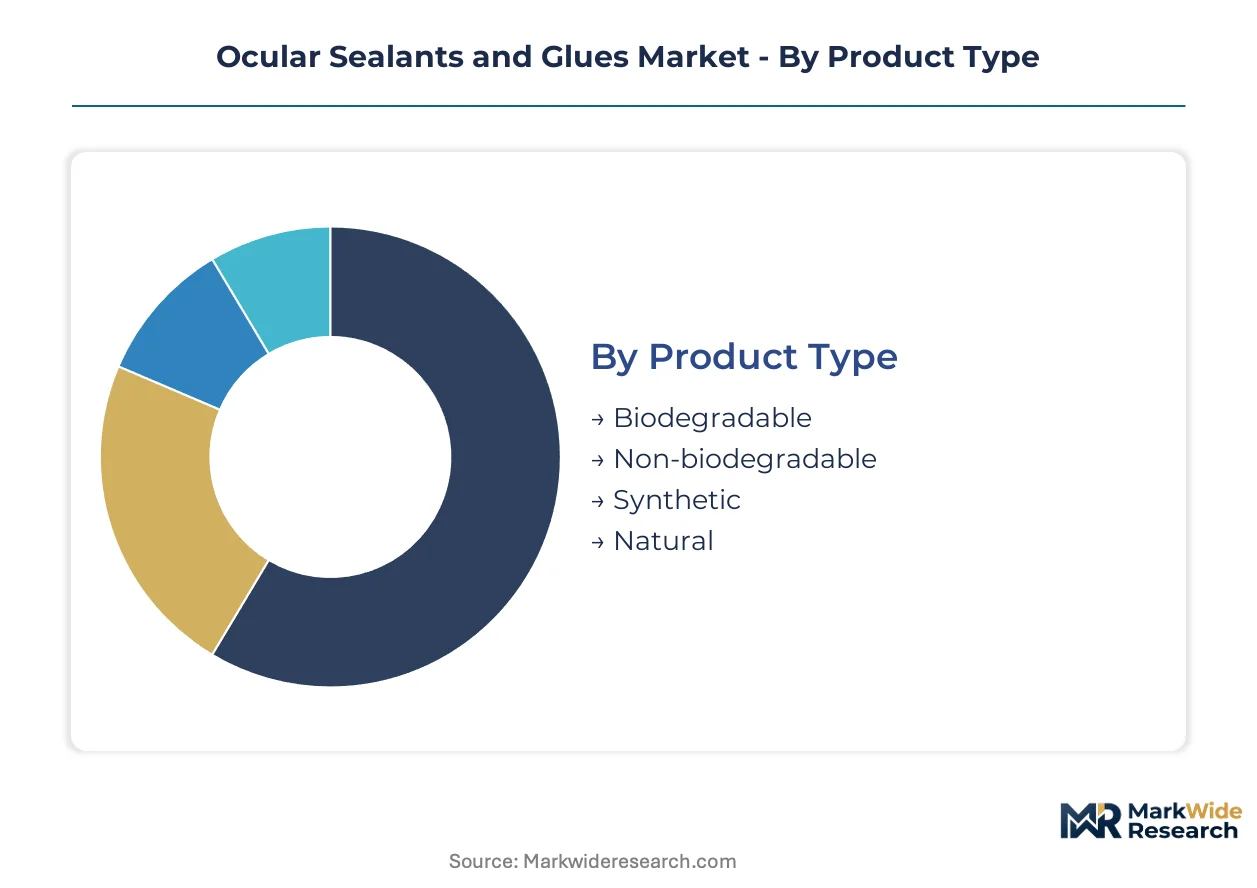
Ocular sealant segmentation reveals divergent commercial logics across material science maturity and procedural integration depth. Product type and application splits expose where biodegradable premiums command formulary access versus where synthetic cost compression dominates procurement decisions.
Product Type:
Biodegradable formulations embed into multi-step wound management protocols requiring material elimination without retrieval procedures, while non-biodegradable alternatives serve as permanent structural anchors in specific anatomical repairs.
- Biodegradable:Polymer matrices engineered for hydrolytic or enzymatic breakdown eliminate suture removal visits in corneal and conjunctival applications. Demand clusters in United States ambulatory surgery centers where reimbursement bundles reward reduced follow-up burden.
- Synthetic:Cyanoacrylate and polyethylene glycol formulations deliver tensile strength exceeding 0.4 N/cm² for immediate wound stability. High-volume cataract settings in Germany and Japan standardize these products for cost-controlled anterior segment procedures.
- Non-biodegradable:Permanent acrylic adhesives retain structural integrity for scleral buckle fixation and prosthetic integration. Selection criteria prioritize chemical inertness over absorption kinetics.
- Natural:Fibrin and albumin-derived sealants leverage autologous or allogeneic protein coagulation cascades. Plasma supply constraints in North American collection networks restrict manufacturing scale.
Volume placements concentrate in synthetic formulations; the faster expansion belongs to biodegradable platforms.
Application:
Procedure-specific anatomical constraints dictate sealant selection across anterior and posterior segment interventions, with reimbursement pathway maturity determining commercial prioritization.
- Cataract Surgery:Clear corneal incision closure drives the highest absolute unit consumption as phacoemulsification volumes expand in outpatient settings. Synthetic cyanoacrylate products dominate this segment through sub-60-second application protocols.
- Corneal Repair:Penetrating keratoplasty and lamellar procedures require optical clarity preservation alongside adhesive strength. Biodegradable hydrogel platforms gain preference in United States academic medical centers for Descemet membrane attachment.
- Vitreoretinal Surgery:Sclerotomy closure and retinal detachment repair present unmet needs for posterior segment-compatible formulations. Instrument miniaturization enables precise subretinal application.
- Glaucoma Surgery:Trabeculectomy and tube shunt procedures utilize sealants for bleb modulation and wound leak prevention. Anti-fibrotic drug compatibility influences material selection.
Revenue concentration sits with cataract applications; vitreoretinal surgery demonstrates the steepest expansion trajectory as instrumentation advances.
Delivery Mode:
Application mechanics separate intraoperative workflow integration from postoperative therapeutic extension, with format selection impacting nursing staff training and inventory management.
- Surgical Adhesives:Pre-mixed or dual-syringe systems deliver immediate polymerization for intraoperative hemostasis. Standardization across hospital formulary committees in the United States favors single-use applicator formats.
- Injectable:Subconjunctival and intracameral deposition enables targeted delivery to posterior segment structures. Precision requirements limit adoption to specialized vitreoretinal practices.
- Topical:Postoperative surface application supports epithelial wound healing and barrier function restoration. Patient self-administration protocols expand addressable settings beyond operating rooms.
- Coating:Device and implant surface modification provides sustained-release pharmacological activity alongside mechanical adhesion. Integration with intraocular lens and glaucoma drainage device manufacturing creates captive demand channels.
Procurement volume tilts toward surgical adhesives; coating applications gain share fastest through device OEM partnerships.
End User:
Facility type determines purchasing authority structure, with centralized hospital procurement contrasting against ambulatory site autonomy in product selection.
- Hospitals:Integrated delivery networks leverage volume aggregation for formulary standardization across multiple surgical service lines. Value analysis committees evaluate sealant alternatives against suture complication cost models.
- Ambulatory Surgery Centers:Independent outpatient facilities prioritize rapid patient throughput and same-day discharge protocols. Direct-to-facility distribution bypasses hospital supply chain markups.
- Ophthalmology Clinics:Office-based settings utilize topical sealant formulations for minor procedural applications and postoperative care extension. Reimbursement coding for clinic-administered sealants remains less established than facility-based alternatives.
- Research Labs:Preclinical and clinical investigation sites drive early-stage formulation testing and surgeon training. Academic medical centers in Japan and Germany anchor regenerative sealant development programs.
Unit consumption clusters in hospital systems; ambulatory surgery centers demonstrate the most rapid volume acceleration as site-of-service migration continues.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States, Germany, and Japan concentrate the majority of ocular sealant procurement as these nations upgrade ophthalmic surgical infrastructure. Hospital formulary committees in these markets prioritize biocompatibility certifications and single-use applicator formats. Regulatory pathways in each jurisdiction shape product development timelines and market entry strategies.
United States
FDA 510(k) clearance pathways govern product entry, with ISO 10993 biocompatibility testing extending development cycles by 18-24 months. Ambulatory surgery centers in Texas and Florida standardize sealant-assisted wound closure to accelerate patient throughput. The Southeast surgical corridor from Atlanta to Miami anchors high-volume cataract settings where synthetic cyanoacrylate products dominate procurement.
Germany
EU Medical Device Regulation Annex I mandates upgraded clinical evidence for legacy sealant recertification. Photocrosslinkable hydrogel systems gain preference in Bavarian and Baden-Württemberg academic centers for their on-demand gelation capabilities. The Rhine-Ruhr metropolitan cluster hosts integrated delivery networks that aggregate purchasing across multiple outpatient facilities.
Japan
PMDA fast-track pathways for regenerative medical products compress time-to-market for novel biologic formulations. Tokyo and Osaka anchor surgeon training programs for posterior segment sealant applications. The Kanto region's instrument miniaturization advances enable precise subretinal delivery that expands vitreoretinal surgery penetration.
United Kingdom
MHRA post-Brexit regulatory alignment with EU MDR standards creates transitional certification complexity for sealant manufacturers. London and Manchester ophthalmic centers drive demand for biodegradable hydrogel platforms in corneal repair procedures. The Midlands manufacturing belt supplies pre-filled applicator components to European device assemblers.
Switzerland
Swissmedic certification requirements emphasize documented safety profiles for plasma-derived fibrin sealants. Basel and Zurich host research collaborations between surgical device developers and academic medical centers. The country's pharmaceutical manufacturing heritage supports precision formulation capabilities for sustained-release ocular platforms.
Ocular Sealants and Glues Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with hospital formulary access determining procurement outcomes more than raw technical specifications. The vendor base organizes around three archetypes: diversified surgical conglomerates with suture heritage, plasma-derived biologics specialists, and sustained-release platform innovators. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms seek to secure plasma supply chains and accelerate regulatory submissions.
Among diversified surgical conglomerates, Johnson & Johnson and Baxter International occupy positions anchored by manufacturing scale and hospital distribution networks. Ocular Therapeutix exemplifies the sustained-release specialist archetype, with its hydrogel platform development extending beyond immediate wound closure into therapeutic delivery. B. Braun Melsungen AG represents European-based surgical supply integration, while CSL Behring and CryoLife sit within the plasma-derived biologics tier where raw material sourcing concentration creates structural vulnerability.
| Leading Market Players |
|---|
| Ocular Therapeutix |
| Johnson & Johnson |
| B. Braun Melsungen AG |
| Cohera Medical |
| CryoLife |
| Baxter International |
| Reliance Life Sciences |
| CSL Behring |
| Medtronic |
| Others |
Value Network & Pricing Analysis
Hospital formulary committees in the United States demanding single-use pre-filled applicator formats are forcing manufacturers to retool filling and sterilization lines, compressing margins on legacy dual-syringe systems while elevating pricing power for certified biodegradable alternatives.
Pricing Analysis
Volume placements cluster in synthetic cyanoacrylate products where per-unit transactional pricing dominates high-volume cataract settings; premium-mid-economy pricing differentiation separates ISO 10993-certified biodegradable hydrogels from uncertified alternatives. Price differentiation hinges on biocompatibility certification tier and volume scale commitments through integrated delivery network contracts. Cost compression in synthetic tiers is intensifying because ambulatory surgery centers are standardizing sub-60-second application protocols. Independent outpatient facilities exhibit highest price sensitivity; academic medical centers purchasing for corneal repair demonstrate lowest sensitivity due to optical clarity requirements.
Supply Chain Analysis
Specialized polymer chemists and sterile manufacturing technicians in Germany, Switzerland, and the eastern United States constrain capacity expansion for photocrosslinkable hydrogel production. Raw material sourcing draws from North American and European plasma collection networks for fibrin sealants, Japanese precision polymer suppliers for PEG-based formulations, and German chemical manufacturers for cyanoacrylate monomers. Single-source vulnerability concentrates in plasma-derived inputs where blood collection network disruptions propagate immediately to finished goods availability. Distribution runs through hospital supply chain markups for integrated delivery networks and direct-to-facility channels for independent ambulatory surgery centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Human plasma supply concentration in North American and European collection networks creates a structural capacity bottleneck that props pricing for fibrin-based sealants and incentivizes synthetic formulation substitution.
For Market Incumbents: Deploy hospital formulary lock-in through GPO contract extensions to defend against barbed suture reclamation in anterior segment procedures. Prioritize backward integration into plasma collection networks or captive polymer synthesis capacity to secure raw material availability against supply disruption. Accelerate ISO 10993-5 and ISO 10993-10 certification investments to exploit EU MDR recertification gaps facing legacy synthetic competitors. For New Entrants and Emerging Players: Enter via vitreoretinal surgery penetration where instrument miniaturization enables precise subretinal application and reimbursement pathways remain underdeveloped. Target Japan's Kanto region for PMDA fast-track regenerative medical product qualification, leveraging expedited review frameworks to compress time-to-market. Pursue direct-to-ambulatory distribution through ophthalmic supply cooperatives to bypass hospital centralized purchasing and capture independent surgery center volume. For Investors and Strategic Acquirers: The window for entry favors sustained-release platform specialists with hydrogel therapeutic delivery capabilities beyond immediate wound closure. Long-term viability centers on regenerative medicine convergence where sealant functionality merges with pharmaceutical intervention. Watch FDA 510(k) clearance velocity for photocrosslinkable systems as the inflection indicator for workflow disruption adoption curves.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Supply Network Expansion | CSL Behring and CryoLife anchoring North American collection capacity secures fibrin sealant manufacturing scale. |
| EU MDR Recertification Investment | Baxter International upgrading clinical evidence packages exploits temporary market access gaps for biodegradable alternatives. |
| Photocrosslinkable Hydrogel Development | Ocular Therapeutix LED-activated gelation platforms decentralize surgical workflow control for ambulatory settings. |
| Direct-to-Ambulatory Distribution | Johnson & Johnson bypassing hospital supply chains captures independent surgery center volume in Texas and Florida. |
| Vitreoretinal Application Training | Tokyo and Osaka academic centers building surgeon competency expands posterior segment addressable market. |
Research Methodology
Document review covered FDA 510(k) clearance databases, EU MDR Annex I technical documentation, and ISO 10993 biocompatibility testing protocols, complemented by interviews with hospital purchasing committee members, ambulatory surgery center administrators, ophthalmic surgeons, GPO contracts managers, and biomedical engineers. Secondary validation drew from CMS Medicare reimbursement coding databases, hospital procurement records, and PMDA pharmaceutical affairs submissions. Bottom-up unit demand modeling triangulated against top-down market sizing across product type, application, delivery mode, and end user segments.
Segment-level value outputs across the analysis window reflect procedure volume projections, reimbursement pathway maturity, and material science adoption curves. The analytical framework modeled biodegradable versus synthetic formulation splits, anterior versus posterior segment penetration rates, and hospital versus ambulatory site-of-service migration. CAGRs derived from logistic diffusion curves for technology substitution and price elasticity estimates for procurement tier sensitivity. Industry-specific inputs included phacoemulsification volume trajectories, plasma collection network capacity constraints, and instrument miniaturization advancement timelines.
Revisions become necessary when EU MDR enforcement intensity shifts, FDA biocompatibility testing requirements expand, or plasma collection network disruptions materialize beyond modeled scenarios. Forecasts reflect documented assumptions regarding reimbursement code stability and surgeon training program expansion rates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
South America Electronics Adhesives Market
Adhesives & Sealants
United Kingdom Adhesives Market
Adhesives & Sealants
Low VOC Adhesive Market
Adhesives & Sealants
Electric Vehicle Adhesives and Sealants Market
Adhesives & Sealants
Elastic Bonding Adhesive and Sealant Market
Adhesives & Sealants
Asia-Pacific Cyanoacrylate Adhesives Market
Adhesives & Sealants
South America Polyurethane (PU) Adhesives Market
Adhesives & Sealants
UV Cured Adhesives Market
Adhesives & Sealants
Foam Adhesive Market
Adhesives & Sealants
Europe Cyanoacrylate Adhesives Market
Adhesives & Sealants
Hot Melt Adhesives Market
Adhesives & Sealants
Dental Impression Tray Adhesives Market
Adhesives & Sealants
Conductive Glue Market
Adhesives & Sealants
Canada Sealants Market
Adhesives & Sealants
Middle East and Africa Flock Adhesives Market
Adhesives & Sealants
Fibrin Glue Market