
 Adhesives and Sealants Distribution Market | 2026-2036
Adhesives and Sealants Distribution Market Size, Share, and Industry Trends Forecast 2026-2036
Adhesives and Sealants Distribution Market Outlook
REACH is rebalancing the cost-of-entry calculus for distributors serving European industrial accounts, forcing inventory segmentation between compliant and legacy formulations. Hisco leverages its technical service infrastructure to guide customers through substance authorization workflows. Fastenal anchors its position through embedded vending and on-site inventory programs at manufacturing facilities. Biesterfeld AG specializes in engineered material distribution, sustaining margin pools through application-specific technical support rather than commodity volume.
Adhesives and sealants distribution encompasses the procurement, warehousing, formulation blending, technical consultation, and last-mile logistics of bonding and sealing chemistries, typically involving products with viscosity ranges from 100 to 500,000 centipoise and cure mechanisms spanning moisture, thermal, UV, or anaerobic activation. The primary commercial purpose is to reduce customer working capital requirements while ensuring specification compliance and just-in-time availability for production lines. Epoxy and polyurethane product types command the deepest technical support requirements and correspondingly higher service margins, while cyanoacrylate segments compete primarily on availability velocity and packaging flexibility. Wholesale channels still dominate tonnage flows to industrial end users, though direct sales relationships with automotive and aerospace OEMs capture the most stable contract volumes and longest planning horizons.
EPA VOC regulations in the United States, REACH in Europe, and China's GB standards collectively determine which formulations distributors may legally stock and transport across jurisdictions. These frameworks shape demand by disqualifying certain solvent-based chemistries and accelerating water-borne and hot-melt alternatives in regulated applications. Distributors must monitor evolving substance restriction timelines and pre-register alternative suppliers before portfolio gaps emerge.
Market Dynamics
REACH substance authorization timelines and EPA VOC threshold revisions are forcing distributors to reconfigure inventory portfolios ahead of regulatory deadlines, compressing the window for legacy formulation clearance and accelerating supplier pre-qualification cycles.
Growth Catalysts
- Construction sector bonding demand:Commercial and residential buildouts in Germany and the United States are absorbing structural adhesive volumes for curtain wall systems and prefabricated concrete connections.
- REACH compliance services:Technical consultation on substance authorization workflows creates attach revenue streams for distributors serving European industrial accounts.
- Automotive OEM supply chain embedding:Just-in-time delivery requirements from vehicle manufacturers in Stuttgart and Detroit lock in long-term distribution contracts with penalty clauses for stockouts.
Market Restraints
- Petrochemical feedstock volatility:Epoxy resin and isocyanate price swings compress service margins when distributors cannot pass through cost spikes under fixed-price contracts.
- Specialty chemical supply concentration:German and Belgian producers control high-performance polyurethane precursor supply, exposing distributors to allocation risk during plant turnarounds.
- Solvent-based formulation disqualification:EPA VOC thresholds and REACH restrictions on aromatic compounds eliminate legacy product lines before water-borne alternatives achieve equivalent cure speeds.
Strategic Opportunities
- India industrial corridor penetration:PLI scheme incentives for domestic manufacturing are creating first-mover openings for distributors establishing local blending and technical service capabilities.
- UV-cure adhesive convergence:Electronics miniaturization and medical device assembly are intersecting to create specification overlap that single-source distributors can capture.
- On-site inventory programs:Vending and vendor-managed inventory installations at manufacturing facilities reduce customer working capital while locking out competitor access.
Industry Challenges
- Formulation chemist scarcity:Distributors struggle to recruit technical staff capable of translating customer substrate requirements into cure-cycle specifications across epoxy, polyurethane, and silicone chemistries.
- Dual registration burden:Maintaining parallel REACH and EPA-compliant product portfolios doubles documentation overhead without proportional revenue expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adhesives and Sealants Distribution Market |
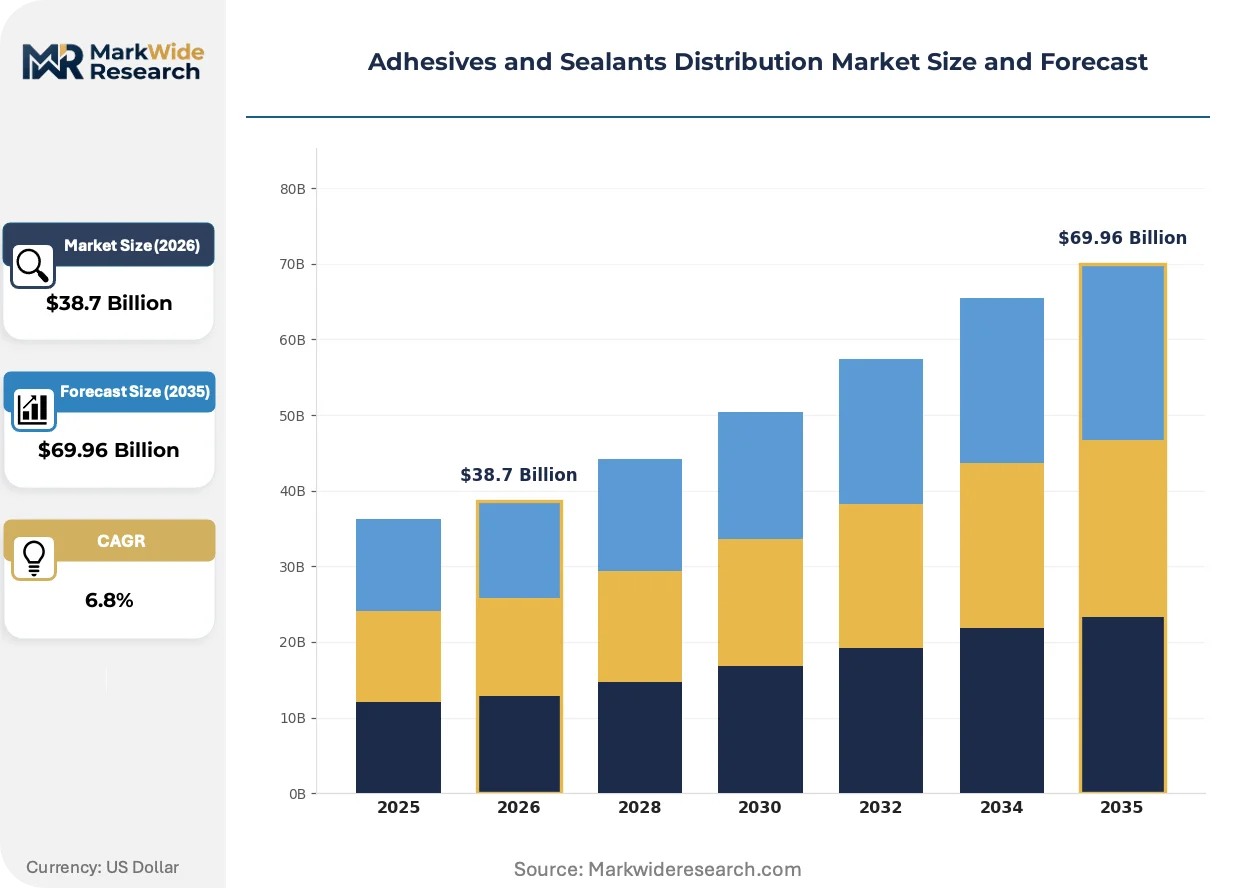
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cyanoacrylate, Epoxy, Silicone, Polyurethane Distribution Channel: Wholesale, Retail, Online, Direct Sales End User: Construction, Automotive, Aerospace, Electronics Application: Flooring, Packaging, Automotive Assembly, Electrical Insulation |
| Companies Covered | Hisco, Fastenal, Krayden Inc., Ellsworth, Biesterfeld AG, BC Adhesives, Grainger, Ter Group, Rudolph Bros & Co, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adhesives and Sealants Distribution Market Strategic Shifts
Digital inventory tracking and predictive replenishment algorithms are reshaping how distributors manage working capital and customer service levels across geographically dispersed production facilities.
Hot-melt reactive polyurethane adhesive technology is consolidating specification preference in automotive interior assembly and flexible packaging lamination. Tier-one suppliers in Germany and the United States are specifying these systems for bond-line durability under thermal cycling. The technology is consolidating market position previously held by solvent-borne alternatives that face regulatory phase-out timelines.
EPA VOC threshold reductions under the Clean Air Act are disqualifying solvent-based sealants from architectural coating applications. Industrial end-users in California and the Northeast corridor face the most compressed compliance deadlines. Water-borne and silyl-modified polymer alternatives are capturing specification share in commercial construction bidding documents.
Buyer consolidation among automotive and aerospace OEMs is compressing distributor negotiation leverage and extending payment terms. Tier-two distributors serving secondary suppliers in Ohio and Baden-Württemberg face margin compression as procurement functions centralize at headquarters level. Technical service differentiation rather than price remains the viable defense against disintermediation.
Adhesives and Sealants Distribution Market Segmentation
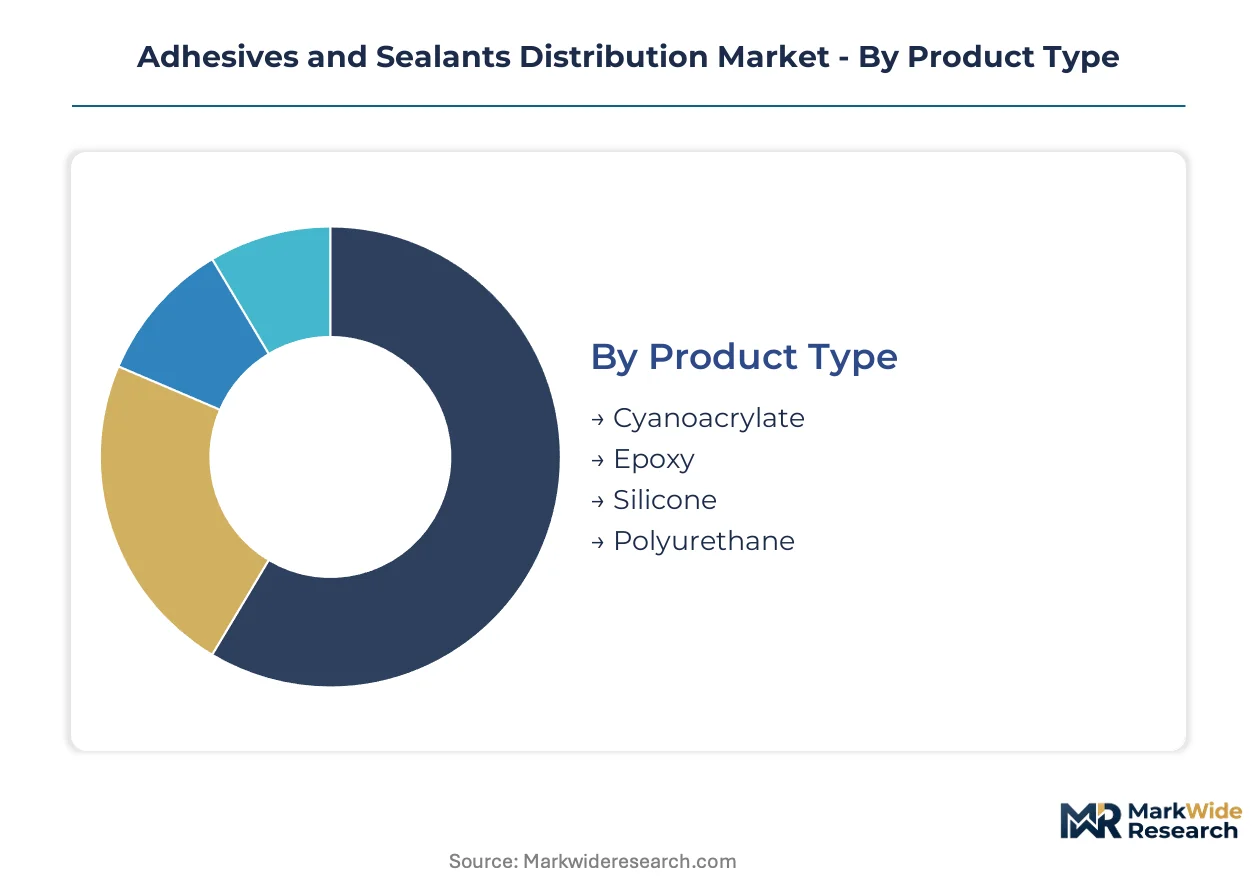
Segmentation in adhesives and sealants distribution reflects how technical complexity, regulatory burden, and customer procurement patterns fragment service requirements. Distributors configure inventory depth, technical staffing, and logistics infrastructure differently across each dimension.
Product Type:
Thermoset chemistries span the customization arc from instant-bonding commodity grades to engineered systems requiring substrate-specific cure protocols.
- Epoxy:Two-part thermoset systems with viscosity ranges from 5,000 to 500,000 centipoise dominate structural bonding in wind turbine blade manufacturing across Germany and Denmark. REACH substance authorization burdens concentrate here due to bisphenol-A and amine hardener restrictions.
- Polyurethane:Reactive systems cure through moisture or thermal activation, commanding premium service margins in Stuttgart automotive OEM supply chains where bond-line durability under thermal cycling is specified.
- Silicone:Room-temperature vulcanizing formulations serve high-temperature electrical insulation in aerospace wire harness assembly.
- Cyanoacrylate:Instant adhesives compete on packaging flexibility and availability velocity for electronics assembly lines.
Most installed capacity flows through Epoxy. Expansion is steepest in Polyurethane.
Distribution Channel:
Channel economics separate high-touch technical consultation from transactional availability, with working capital intensity scaling inversely with customer proximity.
- Wholesale:Ton-volume flows to industrial MRO accounts sustain distributor margins through consolidated procurement and predictable demand patterns in Ohio manufacturing corridors.
- Direct Sales:Long-term contracts with automotive and aerospace OEMs in Detroit and Toulouse capture stable volumes but demand dedicated technical service infrastructure and penalty-clause compliance systems.
- Retail:Small-format packaging serves contractor and DIY demand through building supply merchants.
- Online:Digital procurement portals capture specification-grade repeat orders from mid-tier manufacturers seeking reduced search friction.
Wholesale channels anchor volume throughput. Direct Sales channels are expanding most quickly as OEM procurement centralizes.
End User:
End-use concentration determines whether distributors compete on formulation expertise or logistics reliability, with regulatory exposure varying sharply by sector.
- Automotive:Just-in-time delivery requirements from Stuttgart and Detroit assembly plants lock in embedded inventory programs with penalty structures for stockouts.
- Construction:Commercial buildouts in Germany and the United States absorb structural adhesive volumes for curtain wall systems and prefabricated concrete connections.
- Aerospace:FAA and EASA certification requirements for flame-retardant formulations create specification stickiness and long supplier qualification timelines.
- Electronics:Miniaturization trends in medical device and semiconductor assembly drive demand for UV-cure systems with sub-millimeter precision.
Construction absorbs the highest tonnage. Electronics represents the fastest-growing trajectory.
Application:
Application-specific performance requirements fragment distributor technical service capabilities across cure speed, environmental resistance, and substrate compatibility dimensions.
- Automotive Assembly:Hot-melt reactive polyurethane systems specified for interior trim bonding face compressed EPA VOC compliance deadlines in California and Northeast corridor manufacturing.
- Electrical Insulation:Silicone and epoxy formulations serve high-voltage transformer and motor winding applications with dielectric strength specifications.
- Flooring:Moisture-cure polyurethane adhesives install resilient and wood flooring systems in commercial construction bidding.
- Packaging:Hot-melt adhesives for flexible lamination compete on melt viscosity stability and food-contact compliance.
Automotive Assembly commands the deepest technical support requirements. Packaging offers the most standardized procurement patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered industrial-scale adhesive formulation in the post-war period, establishing distribution networks that now span automotive supply chains across three continents. The sector's geographic footprint reflects both historical chemical manufacturing concentration and contemporary regulatory divergence.
United States
Commercial construction in Texas and Florida absorbs structural adhesive volumes for hurricane-resistant building envelopes. EPA VOC threshold reductions under the Clean Air Act compress compliance timelines for solvent-based sealant distributors serving California and Northeast corridor markets. Detroit automotive OEMs embed vendor-managed inventory programs with penalty clauses for production line stockouts.
Germany
Stuttgart and Munich automotive clusters sustain the deepest technical service requirements for polyurethane and epoxy distribution. REACH substance authorization workflows for bisphenol-A and amine hardeners elevate documentation burdens for distributors serving industrial accounts. Baden-Württemberg manufacturing corridors concentrate procurement volume for hot-melt reactive systems specified for interior trim bonding.
China
Yangtze River Delta electronics assembly lines drive specification-grade demand for UV-cure adhesives with sub-millimeter precision. GB standards and dual carbon goals accelerate water-borne formulation preference in regulated applications. Pearl River Delta packaging manufacturers specify hot-melt systems for flexible lamination with food-contact compliance.
India
PLI scheme incentives for domestic manufacturing create first-mover openings for distributors establishing local blending capabilities in Maharashtra and Gujarat. BIS certification requirements fragment product portfolios compared to European or North American equivalents. Tamil Nadu automotive corridors absorb imported polyurethane precursor volumes despite domestic capacity expansion.
Japan
Osaka and Nagoya precision manufacturing clusters demand silicone formulations for high-temperature electrical insulation in aerospace wire harness assembly. METI efficiency standards shape procurement specifications for industrial adhesive applications. Kanto region electronics miniaturization trends intersect with medical device assembly requirements to create specification overlap.
Adhesives and Sealants Distribution Market Competitive Environment
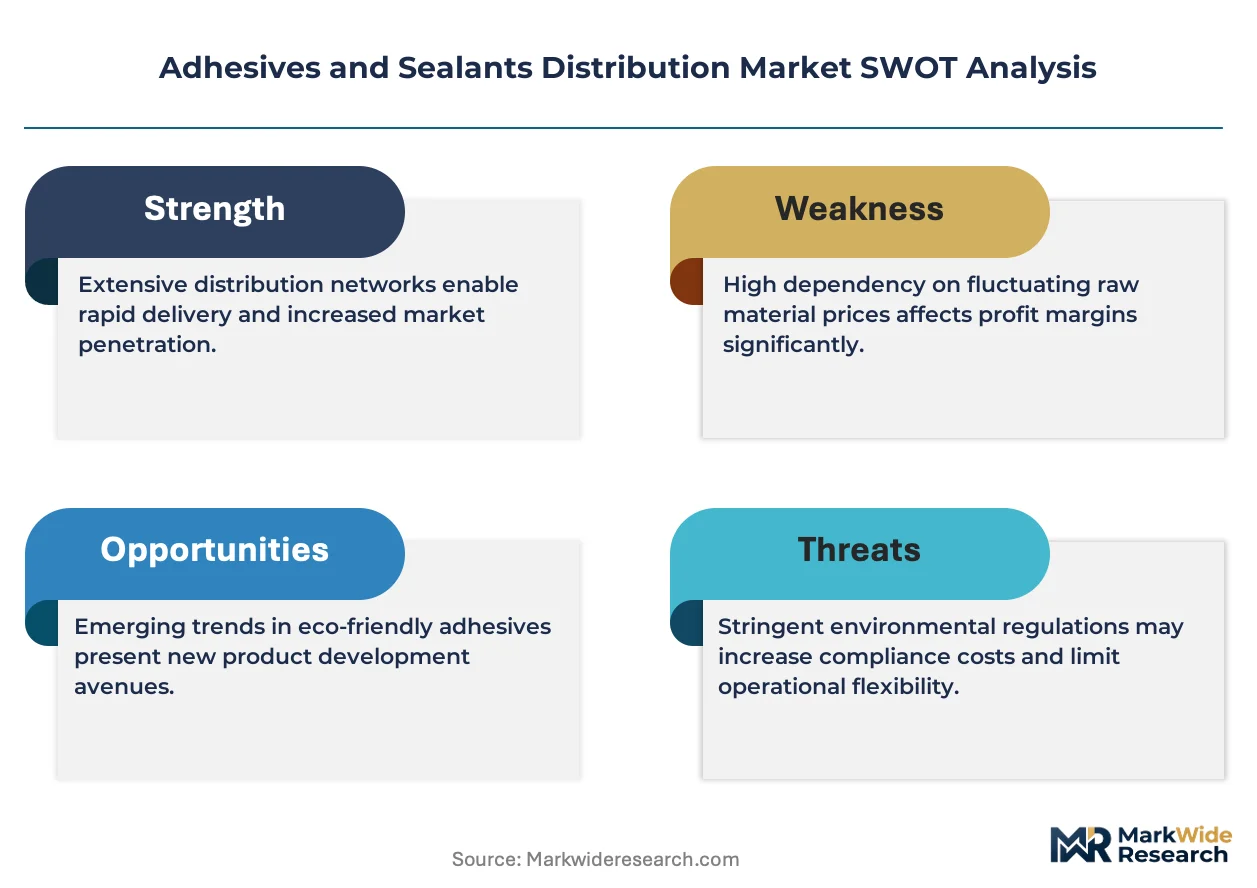
The competitive structure tilts toward technical-service-intensive distributors over pure logistics players. Concentration remains moderate, with global industrial distributors anchoring volume throughput alongside regional specialists capturing premium-margin segments. Three archetypes dominate: embedded inventory program operators, formulation-blending technical consultants, and commodity-scale wholesale consolidators. M&A activity concentrates on regional specialty distributors with established OEM qualification timelines, while organic expansion focuses on local blending capacity in high-growth industrial corridors.
Among North American industrial distributors, Hisco and Fastenal occupy positions emphasizing technical consultation and embedded vending infrastructure respectively. Biesterfeld AG represents the European specialist archetype, sustaining margin pools through application-specific support rather than commodity volume. These three exemplify how geographic origin and organizational structure shape competitive positioning within a market where regulatory fluency and substrate-specific expertise determine customer retention.
| Leading Market Players |
|---|
| Hisco |
| Fastenal |
| Krayden Inc. |
| Ellsworth |
| Biesterfeld AG |
| BC Adhesives |
| Grainger |
| Ter Group |
| Rudolph Bros & Co |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up wholesale specialists anchor pricing discipline through consolidated procurement leverage across Ohio and Baden-Württemberg manufacturing corridors, while family-owned regional distributors defend margin pools via embedded technical service contracts that resist commoditization pressure from automotive OEM procurement centralization.
Pricing Analysis
Contract-based long-term offtake agreements with penalty clauses for stockouts dominate automotive and aerospace procurement, separating specification-grade epoxy and polyurethane systems from commodity cyanoacrylate spot purchases. Price differentiation rests on REACH compliance certification tier and application-specific formulation support rather than raw material grade alone. Cost compression in solvent-based legacy portfolios is intensifying as EPA VOC thresholds disqualify architectural sealant formulations before water-borne alternatives achieve equivalent cure speeds. Tier-two distributors serving secondary suppliers in Ohio manufacturing corridors face the steepest price sensitivity, while Stuttgart OEM supply chains absorb premium service margins for thermal-cycling-qualified polyurethane systems.
Supply Chain Analysis
Dual-sourcing mandates from Detroit and Stuttgart automotive OEMs force distributors to pre-qualify parallel REACH and EPA-compliant suppliers before portfolio gaps emerge from substance authorization timelines. Raw material supply concentrates in Germany, Belgium, and China, with bisphenol-A epoxy resins and isocyanate precursors drawing from petrochemical feedstocks vulnerable to allocation risk during plant turnarounds. Single-source vulnerability in high-performance polyurethane precursor supply exposes distributors to margin compression when fixed-price contracts cannot pass through feedstock volatility. Distribution runs through wholesale channels for tonnage flows to industrial MRO accounts, while direct sales relationships with automotive OEMs capture the most stable contract volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The adhesives and sealants distribution market functions as a stable compounder, with regulatory compliance burdens creating persistent attach revenue streams for technical service infrastructure across European and North American industrial accounts.
For Market Incumbents: To counter automotive OEM procurement centralization, anchor customer relationships through vendor-managed inventory installations with embedded vending infrastructure at manufacturing facilities, and deepen application-specific formulation support capabilities that resist price-based disintermediation from tier-one wholesale consolidators. For New Entrants and Emerging Players: Digital procurement portals targeting mid-tier electronics manufacturers in the Yangtze River Delta offer the most penetrable white-space entry, with UV-cure adhesive specifications for medical device assembly providing a defensible niche before scaling into automotive supply chain qualification timelines. For Investors and Strategic Acquirers: Industrial distributors with established technical service infrastructure are the most active acquirer in this space, seeking regional specialists with completed OEM qualification timelines in Stuttgart or Detroit corridors. The signal to watch is REACH substance authorization deadline acceleration, which would compress legacy portfolio clearance windows and elevate compliant-formulation distributor valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Local Blending | Maharashtra and Gujarat PLI incentives reward captive formulation capacity with reduced import duty exposure. |
| REACH Compliance Service Expansion | Substance authorization workflow consultation creates attach revenue from Baden-Württemberg industrial accounts. |
| Long-term Supply Agreement with Automotive OEMs | Penalty-clause contracts with Detroit assembly plants lock in decade-spanning revenue predictability. |
| Joint Venture for UV-cure Technology Access | Osaka precision manufacturing clusters demand sub-millimeter cure precision for aerospace wire harness applications. |
| Green Manufacturing Transition Certification | EPA VOC threshold compliance qualifies distributors for California and Northeast corridor commercial construction bidding. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with adhesive formulation chemists, automotive OEM procurement leads, distribution channel partners, and plant engineers at Ohio and Baden-Württemberg manufacturing facilities with secondary validation through customs trade data, ACC and Cefic industry reports, SEC 10-K filings from listed distributors, and REACH substance authorization databases. Bottom-up demand modeling across end-use segments triangulated against top-down market sizing from production capacity and trade flow analysis.
Historical reference periods anchored volume and value trajectories across the analysis window, with segmentation modeling spanning product chemistry tier, end-use industry concentration, distribution channel format, and regional regulatory cluster. CAGRs derived from regression analysis of procurement volume trends and formulation substitution patterns, incorporating petrochemical feedstock price elasticity and automotive production cycle correlation as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for hot-melt reactive polyurethane displacement of solvent-borne systems would alter the outlook for distributor margin pool distribution. Deviation in EPA VOC threshold enforcement timing or REACH substance authorization acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Hybrid Silane-Terminated Polymer Adhesives for EV Battery Pack Assembly Market
Adhesives & Sealants
Indonesia Adhesives Market
Adhesives & Sealants
Mirror Adhesive Market
Adhesives & Sealants
Butyl Adhesive Market
Adhesives & Sealants
Europe Adhesives Market
Adhesives & Sealants
South America Adhesives Market
Adhesives & Sealants
Global Stone and Tile Adhesives and Sealants Market
Adhesives & Sealants
Global Isononyl Acrylate Market
Adhesives & Sealants
Dispersion Adhesives Market
Adhesives & Sealants
Asia-Pacific Adhesives and Sealants Market
Adhesives & Sealants
Flock Adhesives Market
Adhesives & Sealants
India Tile Adhesive Market
Adhesives & Sealants
US Pressure Sensitive Adhesives Market
Adhesives & Sealants
Polyurethane (PU) Adhesives in Electronics Market
Adhesives & Sealants
Global Dimer Acid Market
Adhesives & Sealants
Global Footwear Adhesives Market