
 Air Fryer Market | 2026-2036
Air Fryer Market Size, Share, and Industry Trends Forecast 2026-2036
Air Fryer Market Intelligence
App-based recipe subscription services bundled with hardware purchases is restructuring how manufacturers monetize the appliance lifecycle. Groupe SEB leverages its connected appliance ecosystem to sustain recurring engagement beyond the initial sale. SharkNinja anchors its growth through aggressive digital channel control and direct-to-consumer positioning. Philips differentiates on air circulation technology leadership and premium positioning in European and Asian markets.
An air fryer is a countertop convection appliance that circulates superheated air at temperatures typically reaching 200°C to 400°F through a compact cooking chamber, using minimal or no oil to produce crisped food surfaces. Its primary commercial purpose centers on delivering fried-texture outputs with reduced fat content for health-oriented consumers. Countertop air fryers occupy the dominant volume position due to lower price points and kitchen space efficiency, while multipurpose air fryers represent the fastest-expanding category as consumers prioritize multi-function appliances that combine pressure cooking, roasting, and dehydrating capabilities. The 3-5 quart capacity band captures the deepest margin pool by balancing family-size utility with countertop footprint constraints.
The US Consumer Product Safety Commission and the FDA's food-contact substance regulations shape material safety requirements for non-stick coatings and heating element enclosures. The EU's Ecodesign Directive and REACH chemical standards enforce energy-efficiency thresholds and restrict perfluorinated compounds in coating formulations, directly influencing R&D allocation for export-oriented manufacturers. China's GB standards and SAMR product safety certifications govern access to the world's largest appliance production base. Stakeholders must monitor evolving chemical disclosure requirements and energy-labeling expansions as regulatory divergence between jurisdictions intensifies compliance complexity.
Market Dynamics
The air fryer market is experiencing structural pressure from multipurpose appliance convergence, as consumers demand single devices that replace multiple kitchen tools while regulatory chemical restrictions force coating reformulation across export supply chains.
Growth Catalysts
- EU Ecodesign Directive:Energy-efficiency labeling mandates accelerate R&D investment in optimized heating element designs and drive premium product positioning across German and UK retail channels.
- Health-conscious suburban households:Demand for reduced-fat cooking methods expands the addressable base beyond traditional frying-equipment owners into wellness-oriented kitchen renovation projects.
- Digital recipe ecosystems:App-based content services bundled with hardware purchases create recurring revenue streams and extend customer lifetime value beyond initial appliance sales.
Market Restraints
- Perfluorinated compound restrictions:REACH chemical standards in Europe and evolving FDA food-contact substance regulations limit coating formulation options and extend product development cycles.
- Guangdong province manufacturing concentration:Heavy reliance on a single production cluster for heating element and plastic enclosure supply creates vulnerability to logistics disruptions and tariff exposure.
- Countertop space scarcity:Urban kitchen footprint limitations in Japan and dense European housing constrain adoption of larger-capacity units despite family-size utility demand.
Strategic Opportunities
- Direct-to-consumer channel expansion:Bypassing traditional retail markups through owned digital platforms enables margin capture and first-party data accumulation for personalization.
- Pressure-cooking convergence:Multi-function appliances combining air frying with pressure cooking and dehydrating capabilities command price premiums and reduce competitive substitutability.
- India BIS certification pathway:Formalizing compliance with Bureau of Indian Standards unlocks access to a large underpenetrated market with rising middle-class appliance demand.
Industry Challenges
- Cross-jurisdictional compliance staffing:Divergent chemical disclosure requirements between EPA, ECHA, and SAMR regulatory frameworks demand specialized regulatory affairs expertise that mid-tier manufacturers struggle to retain.
- Heating element thermal testing capacity:Certification backlog at third-party laboratories for GB standards and CE marking creates product launch delays and inventory carrying costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Fryer Market |
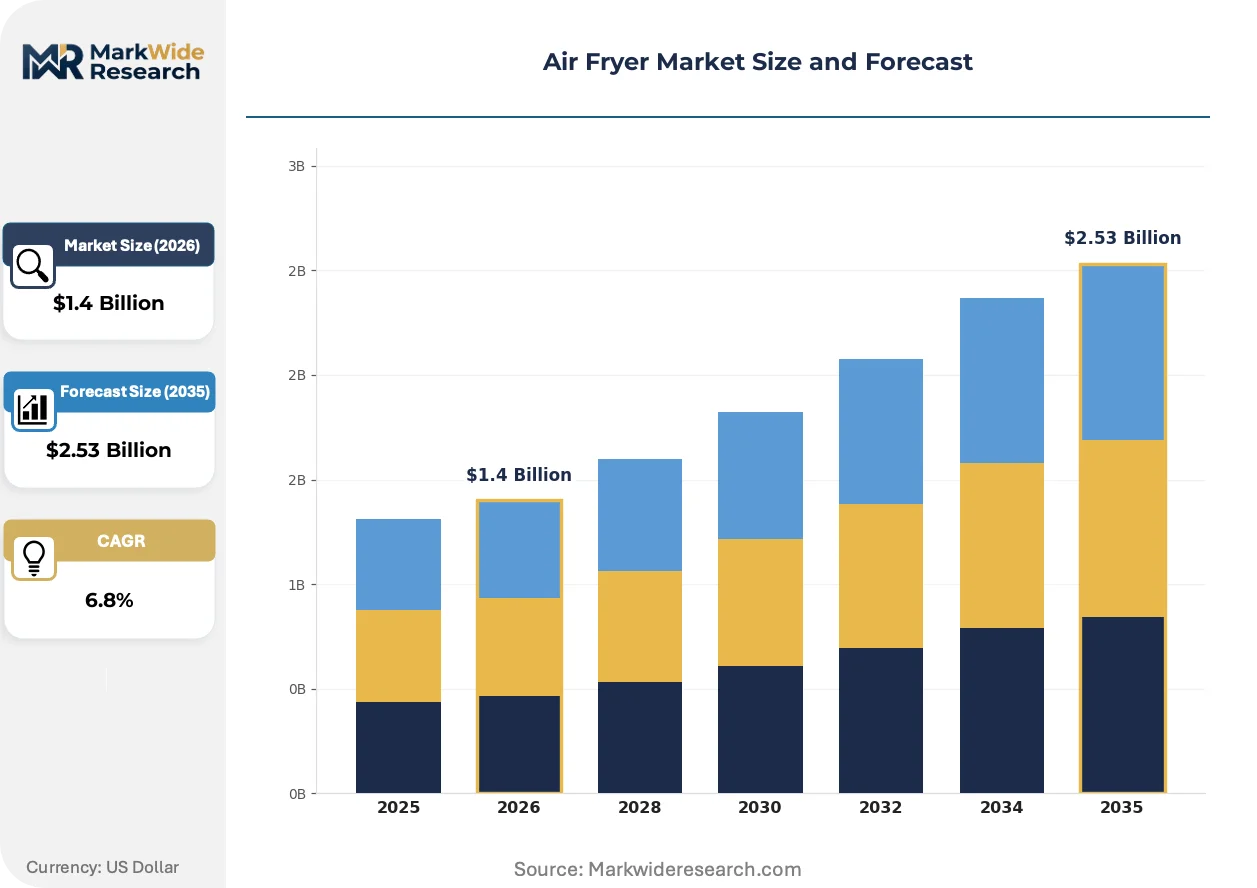
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop Air Fryers, Oven Air Fryers, Multipurpose Air Fryers, Mini Air Fryers Capacity: 1-2 Quarts, 2-3 Quarts, 3-5 Quarts, 5+ Quarts Sales Channel: Online Retail, Specialty Stores, Department Stores, Discount Retailers Brand: Ninja, Philips, Instant Pot, Cosori |
| Companies Covered | Groupe SEB, De’ Longhi Group, Philips, Panasonic Holdings Corporation, Instant Brands, SharkNinja, Electrolux Group, Midea Group, Breville, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Fryer Market Strategic Shifts & Innovations
Air fryer innovation is pivoting toward intelligent cooking systems and material safety advancement, with manufacturers competing on connectivity integration and coating chemistry rather than pure thermal performance specifications.
Dual heating technology—combining upper and lower radiant elements with optimized airflow—is converging with pressure sensor arrays to enable automatic moisture detection and cooking cycle adjustment. Premium kitchen appliance buyers in Germany and Japan are adopting these converged systems at accelerating rates. This convergence is compressing the feature gap between dedicated air fryers and full-size convection ovens, forcing countertop appliance specialists to defend positioning through software differentiation rather than hardware specifications alone.
REACH restrictions on perfluorinated compounds in non-stick coatings are compelling reformulation toward ceramic and sol-gel alternatives across export-oriented manufacturing. The industrial consequence is elevated raw material costs and extended supplier qualification timelines for coating vendors serving European markets. Small-appliance brands with established European distribution are responding fastest, leveraging existing ECHA registration relationships to accelerate compliant product transitions ahead of enforcement deadlines.
Subscription-based recipe content is displacing static user manuals as the primary post-purchase engagement mechanism. Direct-to-consumer brands are bundling hardware with annual content access, while traditional retail-dependent manufacturers face channel conflict when attempting similar pivots. This behavioral shift is most visible in US suburban markets, where digital-native cooking communities drive discovery and appliance purchase decisions through social platform recommendations rather than in-store demonstration.
Air Fryer Market Segmentation
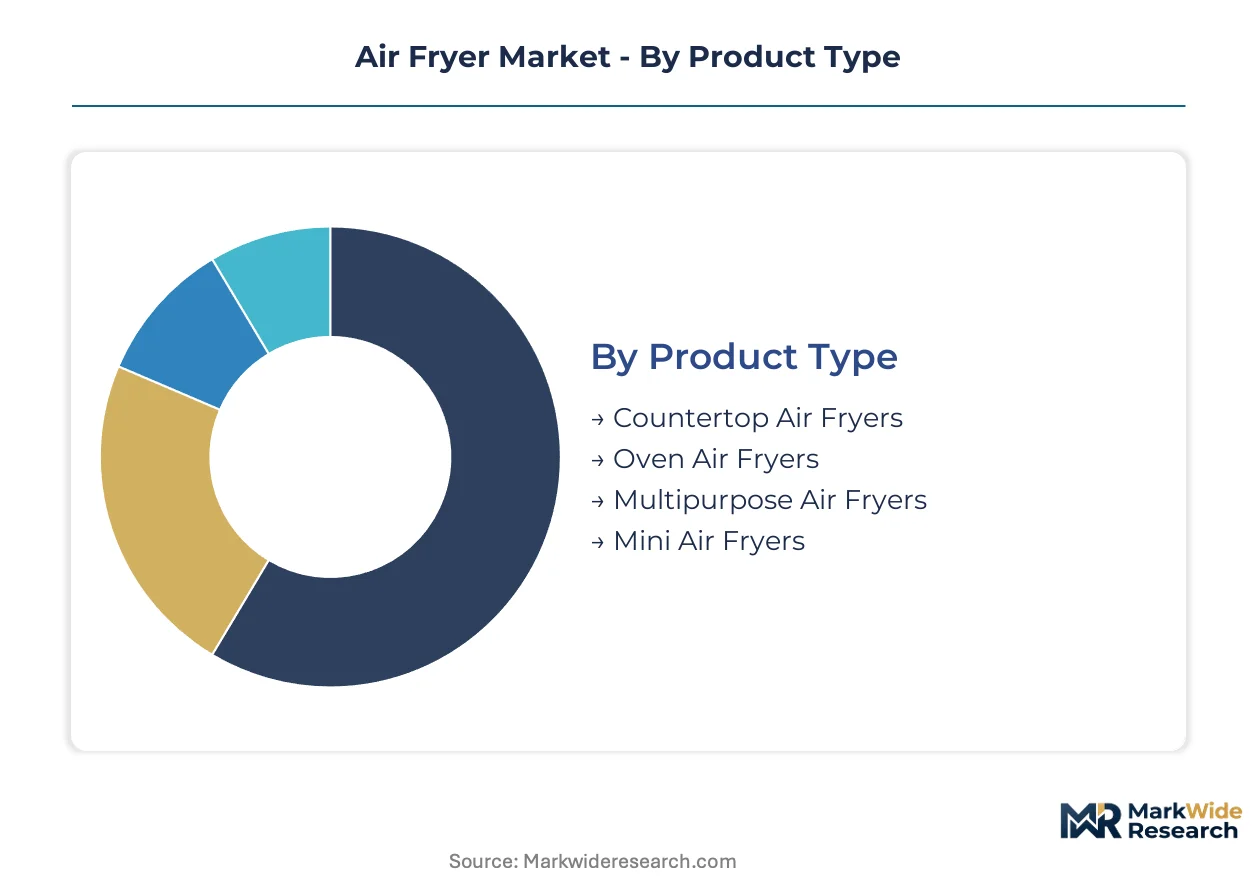
Air fryer manufacturers structure portfolios across four distinct dimensions. Product format determines kitchen placement and use-case flexibility. Capacity sizing balances household scale against countertop constraints. Channel strategy shapes margin capture and customer data ownership. Brand positioning reflects technology differentiation and geographic heritage.
Product Type:
Buyer priorities diverge between space-constrained urban households seeking single-function simplicity and suburban families demanding multi-appliance consolidation.
- Countertop Air Fryers:Compact convection units with dedicated frying chambers dominate unit volumes through accessible price positioning and minimal kitchen footprint requirements. Demand concentrates in German and UK retail channels where energy-efficiency labeling drives replacement cycles.
- Multipurpose Air Fryers:Converged appliances integrating pressure cooking, roasting, and dehydrating functions command price premiums and reduce competitive substitutability through functional stacking. Suburban North American households prioritize these systems during kitchen renovation projects.
- Oven Air Fryers:Full-size convection ovens with integrated air frying modes compete for appliance budget allocation against dedicated countertop units.
- Mini Air Fryers:Sub-2-quart personal units target single-person households and secondary cooking applications.
Countertop air fryers lead volumes today; multipurpose air fryers are gaining share fastest.
Capacity:
Pricing stratifies across volume tiers that align with household composition and meal preparation scale.
- 3-5 Quarts:The mid-capacity band captures the deepest margin pool by balancing family-size utility with countertop footprint constraints. This segment anchors product development investment for manufacturers serving Japanese and dense European urban markets.
- 1-2 Quarts:Personal-scale units address single-person households and constrained Japanese kitchen configurations where METI energy-labeling standards influence purchase decisions.
- 2-3 Quarts:Compact family units serve two-to-three person households seeking primary cooking appliance functionality.
- 5+ Quarts:Large-capacity systems target multi-generational households and batch cooking applications.
The 3-5 quart segment generates the highest absolute margins; 1-2 quart units show the steepest expansion trajectory in Asia-Pacific urban centers.
Sales Channel:
Margin structure and customer relationship depth vary sharply between owned digital platforms and third-party retail intermediation.
- Online Retail:E-commerce platforms enable direct-to-consumer margin capture and first-party data accumulation for personalization. SharkNinja anchors growth through aggressive digital channel control in US suburban markets.
- Specialty Stores:Kitchenware boutiques and appliance showrooms provide demonstration environment for premium positioning and technology education.
- Department Stores:Traditional retail footprints maintain brand visibility but compress margins through markup requirements and inventory risk transfer.
- Discount Retailers:Value-oriented mass merchants drive volume penetration among price-sensitive first-time buyers.
Online retail leads transaction volumes today; specialty stores are expanding most quickly in European premium segments.
Brand:
Heritage and technology positioning separate established appliance conglomerates from digital-native challengers.
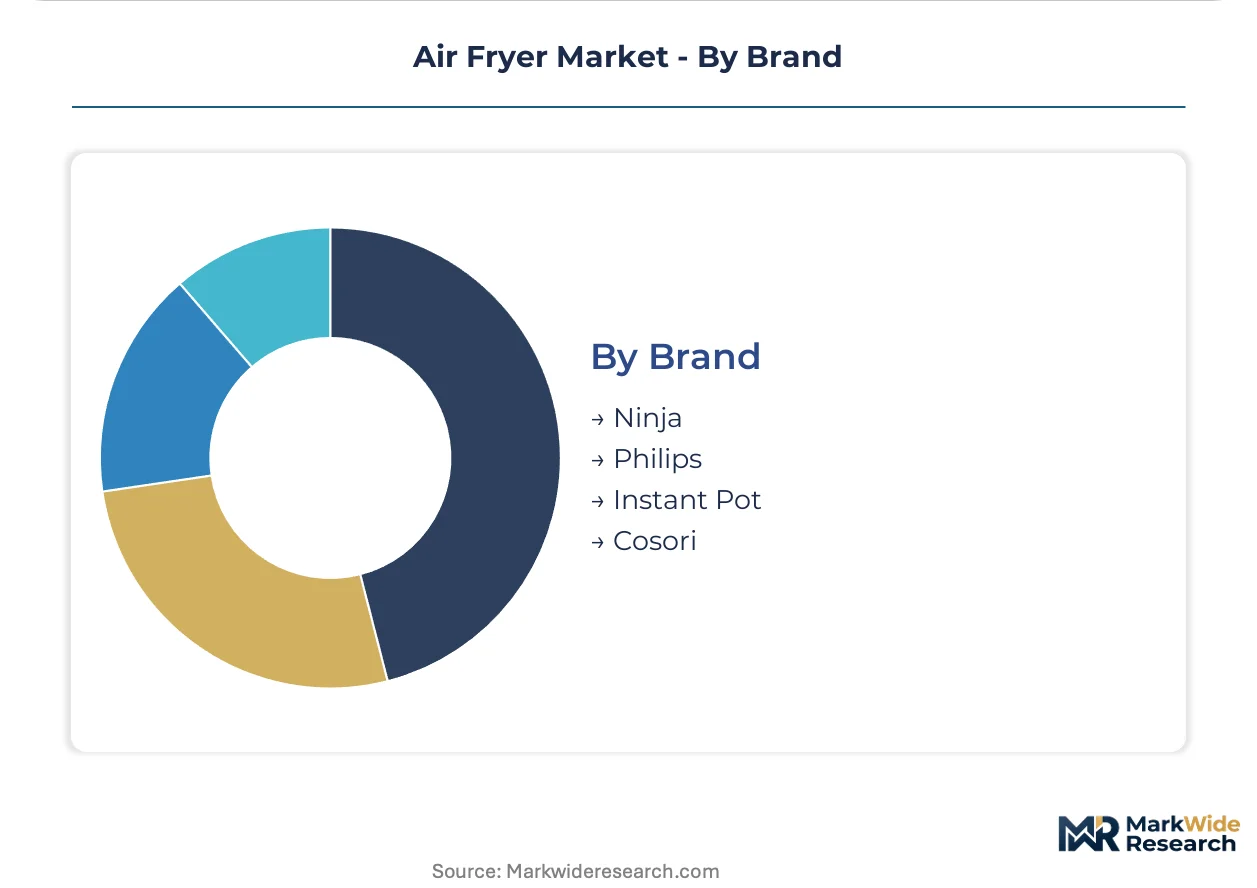
- Ninja:SharkNinja's aggressive digital channel control and direct-to-consumer positioning drives rapid share accumulation in North American markets.
- Philips:Air circulation technology leadership and premium positioning in European and Asian markets sustains margin advantage through specification differentiation.
- Instant Pot:Pressure-cooking brand extension leverages existing customer base for multi-function appliance convergence.
- Cosori:Value-oriented positioning targets price-sensitive segments through e-commerce channel optimization.
Ninja leads volume momentum today; Philips maintains the strongest premium positioning in regulated European markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States suburban households prioritize multipurpose functionality while Japanese consumers favor compact energy-efficient units, revealing divergent regional preferences that shape manufacturer portfolio allocation.
United States
Health-conscious suburban families drive replacement cycles toward multi-function appliances combining air frying with pressure cooking and dehydrating capabilities. The FDA's food-contact substance regulations govern non-stick coating formulations for products sold through domestic retail channels. Manufacturing supply chains concentrate in Guangdong province for heating element production, though final assembly increasingly shifts to Mexico to manage tariff exposure.
Germany
Energy-efficiency labeling under the EU Ecodesign Directive accelerates consumer upgrade cycles toward optimized heating element designs. REACH chemical standards restrict perfluorinated compounds in coating formulations, compelling reformulation toward ceramic alternatives. Retail demand concentrates in metropolitan regions including Berlin, Munich, and Hamburg where kitchen renovation projects favor premium positioning.
Japan
METI energy-labeling standards influence purchase decisions for compact 1-2 quart units suited to dense urban kitchen configurations. The country's national consumer safety regulator enforces strict electrical appliance standards for heating element enclosures and thermal cutoff mechanisms. Osaka-based appliance distributors anchor procurement networks serving Kansai region households with space-constrained cooking environments.
United Kingdom
Post-pandemic kitchen renovation activity sustains demand for mid-capacity 3-5 quart units balancing family utility with countertop constraints. The country's product safety regulator enforces CE marking requirements for electrical safety and energy consumption disclosure. Greater London retail channels prioritize connected appliances with app-based recipe integration, diverging from northern England's price-sensitive mass merchant preferences.
India
Rising middle-class appliance demand in metropolitan centers creates expansion opportunities for formal BIS-certified products. The Bureau of Indian Standards governs electrical safety and performance testing for imported and domestically manufactured units. Maharashtra and Karnataka states concentrate early adoption among urban professional households, with Delhi-NCR emerging as a distribution hub for northern regional markets.
Air Fryer Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with premium positioning concentrated among heritage appliance conglomerates while value-tier supply flows through original equipment manufacturing arrangements. The vendor base organizes around three strategic archetypes: digital-native direct-to-consumer challengers, established European technology leaders, and diversified Asian conglomerates with captive manufacturing. Competitive dynamics center on M&A activity targeting connected appliance capabilities and vertical integration into heating element supply.
Within the heritage technology tier, Groupe SEB and De' Longhi Group exemplify European appliance conglomerates leveraging established distribution relationships and regulatory compliance expertise. Philips occupies a position emphasizing air circulation specification leadership in premium European and Asian markets. Among diversified manufacturers, Midea Group represents Chinese conglomerate scale advantages in component sourcing and export manufacturing capacity. SharkNinja anchors the direct-to-consumer archetype through aggressive digital channel control and first-party data accumulation in North American markets.
| Leading Market Players |
|---|
| Groupe SEB |
| De' Longhi Group |
| Philips |
| Panasonic Holdings Corporation |
| Instant Brands |
| SharkNinja |
| Electrolux Group |
| Midea Group |
| Breville |
| Others |
Cost & Logistics Intelligence
Premium-mid-economy pricing differentiation separates connected appliance ecosystems from commodity countertop units, with this tiering manifesting in both margin capture strategies and sourcing configurations across Guangdong-based manufacturing and European distribution hubs. REACH-compliant coating reformulation and METI energy-labeling investments concentrate in premium supply chains, while value-tier production optimizes for BIS certification pathways and discount retail channel economics.
Pricing Analysis
Capacity additions in Mexico and Vietnam are reshaping price floors for North American-bound inventory as manufacturers diversify beyond Guangdong province to manage tariff exposure. Three-tier pricing structure across premium, standard, and economy levels reflects divergence in connectivity bundling and coating chemistry compliance, with Philips and Groupe SEB commanding brand premiums through ECHA-registered formulations. Cost compression in the economy tier intensifies because Cosori and similar challengers optimize e-commerce channel economics without recipe subscription attach rates. First-time buyers in discount retail channels exhibit highest price sensitivity, while connected appliance subscribers in German metropolitan markets demonstrate lowest elasticity.
Supply Chain Analysis
Freight cost volatility between Asia-Pacific production bases and European distribution centers is elevating landed cost uncertainty for coating vendors and heating element suppliers. Manufacturing concentrates in China, Mexico, and Vietnam, with component sourcing drawing from Malaysian semiconductor packaging for control systems and Japanese thermal cutoff mechanisms. Raw material dependencies center on aluminum alloy enclosures, ceramic coating precursors, and copper heating elements. Single-source vulnerability persists in Guangdong province for radiant element production. Distribution runs through direct-to-consumer platforms, kitchenware specialty retailers, and mass merchant channels with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on two vectors: coating chemistry cost-down through sol-gel formulation scale-up, and premium-tier shift toward pressure-cooking convergence with recurring content revenue attach.
For Market Incumbents: Anchor defensive positioning through backward integration into heating element supply and accelerated ECHA registration relationships that lock in REACH-compliant coating vendor qualification ahead of enforcement deadlines. Philips and Groupe SEB should prioritize pressure sensor array R&D to defend against Instant Pot's multi-function appliance convergence threat. Channel control through owned digital platforms represents the critical margin capture lever against SharkNinja's direct-to-consumer data accumulation. For New Entrants and Emerging Players: Begin with BIS-certified product development targeting Maharashtra and Karnataka metropolitan centers, where underpenetrated middle-class appliance demand meets limited heritage brand distribution. The most penetrable white-space sits in compact 1-2 quart energy-efficient units for Japanese urban kitchens, where METI labeling requirements filter out unqualified challengers. A recipe-content-first go-to-market angle bypasses retail channel conflict that constrains traditional manufacturers. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier manufacturers lack specialized regulatory affairs expertise for cross-jurisdictional compliance staffing across EPA, ECHA, and SAMR frameworks. Long-term viability favors targets with established ECHA registration relationships and European distribution infrastructure that accelerates compliant product transitions. The signal to watch is certification backlog duration at third-party laboratories for GB standards and CE marking, which indicates capacity constraints that favor integrated testing capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Pressure-Cooking Convergence | Multi-function appliances command price premiums and reduce substitutability in North American suburban markets. |
| Direct-to-Consumer Channel Expansion | Owned digital platforms enable margin capture and first-party data accumulation for personalization beyond retail intermediation. |
| REACH-Compliant Coating Reformulation | Ceramic and sol-gel alternatives to perfluorinated compounds secure European market access ahead of enforcement deadlines. |
| India BIS Certification Pathway | Formal compliance with Bureau of Indian Standards unlocks access to rising middle-class appliance demand in metropolitan centers. |
| Recipe Subscription Ecosystem Bundling | App-based content services extend customer lifetime value beyond initial hardware sales in US suburban markets. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with product development executives at heritage appliance conglomerates, regulatory affairs leads managing ECHA and SAMR compliance, category buyers at German and UK retail channels, and coating vendor technical directors with secondary validation. Secondary sources included EU Ecodesign Directive implementation reports, REACH restriction updates from ECHA, FDA food-contact substance guidance, METI energy-labeling standards documentation, and customs records tracking heating element and enclosure trade flows. Bottom-up unit economics modeling triangulated against top-down market sizing across capacity tiers and regional demand clusters.
Segment-weighting approaches distributed value and volume across product format, capacity sizing, channel strategy, and brand positioning dimensions, with additional granularity for connectivity integration levels and coating chemistry compliance tiers. CAGRs were derived from installed base replacement cycles, household formation patterns, and regulatory upgrade mandates rather than extrapolation of historical growth rates. Industry-specific forecast inputs incorporated METI energy-labeling influence on Japanese compact unit demand and EU Ecodesign Directive acceleration of German replacement cycles.
Several conditions sit outside the modeled scope, including geopolitical disruption to Guangdong province manufacturing, abrupt REACH enforcement timeline acceleration, and tariff rate modifications affecting Mexico assembly economics. Forecasts reflect assumptions about regulatory stability and coating vendor qualification timelines that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
United States Smokeless Indoor Grills Market
Food Service
United States Full Service Restaurants Market
Food Service
Chained Consumer Foodservice Market
Food Service
Food Service Disposables Market
Food Service
Instant Grocery Market
Food Service
Commercial Beverage Dispenser Market
Food Service
Self-Heating Hot Pot Market
Food Service
Electric Tiffin Market
Food Service
Malaysia Food Service Market
Food Service
Latin America Inflight Catering Market
Food Service
Catering Food Warmers Market
Food Service
Singapore Food Service Market
Food Service
Foodservice Coffee Market
Food Service
Pasteurized Eggs Market
Food Service
Supermarkets Market
Food Service
Europe Pizza Oven Market