
 China Energy- Drinks Market | 2026-2036
China Energy- Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
China Energy- Drinks Market Outlook
The capital-intensity divergence between bottling network scale and brand marketing spend is bifurcating competitive outcomes in China's energy-drink sector. Red Bull GmbH leverages its global formula licensing system to sustain premium positioning in high-traffic convenience channels. Eastroc Beverage Group anchors its position through deep distribution into third- and fourth-tier city kiosks. Hangzhou Wahaha Group competes on manufacturing scale, operating some of the largest beverage production complexes in Zhejiang province.
China energy-drinks comprise non-alcoholic beverages formulated with caffeine, taurine, B-vitamins, and adaptogenic compounds, typically delivering 80-150mg caffeine per serving to enhance alertness and reduce perceived fatigue. These formulations serve commercial purposes ranging from athletic performance support to cognitive endurance during extended work shifts. Carbonated variants occupy the mature volume base, while functional and natural segments capture expanding margin pools as health-conscious consumers scrutinize ingredient panels. The athlete and busy-professional end-user categories are pulling innovation toward lower-sugar, plant-derived energy matrices. Cans dominate packaging due to chill-retention and single-serve portability, though powder sachets are gaining traction in gym and travel contexts.
SAMR enforces GB standards on caffeine limits and additive disclosures, while NMPA oversight on functional claims restricts how brands communicate health benefits. These frameworks compel reformulation investments and lengthen new-product approval timelines. Online retail channels are reshaping access patterns, bypassing traditional supermarket gatekeepers. Stakeholders must monitor regulatory clarifications on energy-drink classification versus sports-nutrition boundaries to anticipate compliance cost shifts.
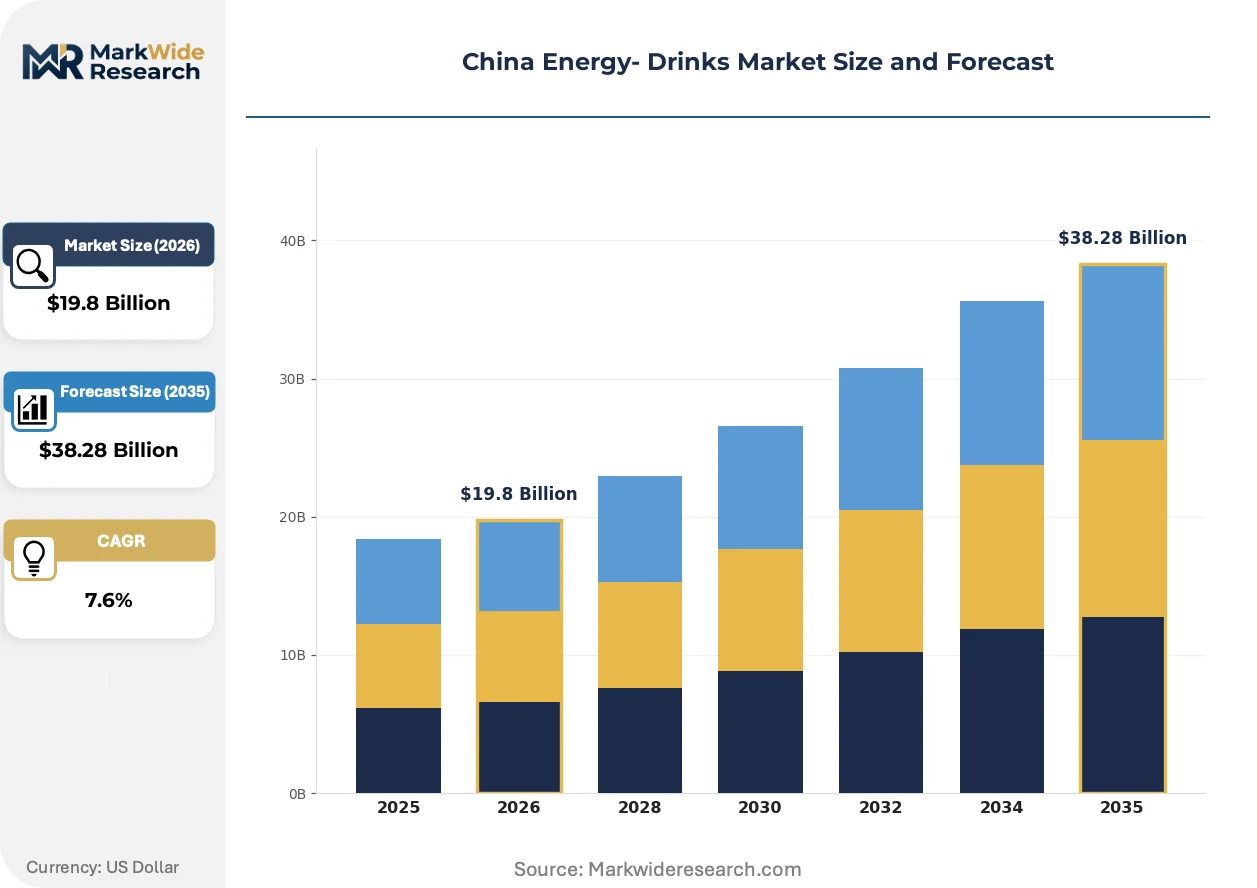
Market Dynamics
Urban work-hour extension in Shanghai and Shenzhen is compressing consumption occasions toward portable, single-serve formats that bypass traditional retail gatekeepers. SAMR's tightening GB standards on caffeine disclosure and additive transparency are forcing simultaneous reformulation investments across the competitive set.
Growth Catalysts
- Extended work-hour normalization:Professionals in tier-one cities now consume energy drinks during commutes and late shifts, expanding daily consumption windows beyond traditional sports and gaming occasions.
- GB standard clarity:SAMR's codified caffeine limits and labeling mandates reduce regulatory ambiguity, accelerating new-product approval timelines for compliant formulations.
- Convenience channel densification:Kiosk and unmanned retail networks in third-tier cities extend physical access to consumers previously underserved by supermarket distribution.
Market Restraints
- Taurine and caffeine input concentration:Specialty ingredient supply clusters in Southeast Asia create single-source vulnerability for domestic formulators.
- SAMR claim restriction friction:NMPA oversight on functional health benefits prevents direct communication of adaptogenic effects, compressing marketing differentiation space.
- Natural coffee substitution:Specialty café chains in Beijing and Guangzhou capture alertness-seeking consumers through premium single-origin positioning.
Strategic Opportunities
- Fourth-tier city whitespace:Sichuan and Henan provinces show penetration gaps where local kiosk networks lack premium functional variants.
- Plant-derived matrix convergence:Ginseng and rhodiola extracts combined with microencapsulated caffeine enable clean-label positioning without synthetic additive reliance.
- Gym channel powder sachet innovation:Fitness centers in Chengdu and Wuhan bypass traditional retail entirely through direct locker and vending placement.
Industry Challenges
- Formulation chemist scarcity:Cross-functional expertise spanning food science, regulatory compliance, and sensory optimization commands premium compensation in Shanghai and Hangzhou talent markets.
- Dual certification timeline compression:SAMR food-additive approval combined with NMPA functional-claim review extends product-launch cycles beyond competitor response windows.
- Legacy canning line retrofit costs:Aseptic powder-filling equipment for sachet formats demands capital outlays that strain mid-tier manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Energy- Drinks Market |
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $38.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbonated, Non-Carbonated, Functional, Natural End User: Athletes, Students, Busy Professionals, Health Enthusiasts Packaging Type: Cans, Bottles, Powder Sachets, Multipacks Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Shops |
| Companies Covered | The Coca-Cola Company, Hangzhou Wahaha Group Co Ltd, Eastroc Beverage Group Co., Ltd., Otsuka Pharmaceutical, Taisho Pharmaceutical California Inc, Red Bull GmbH, PepsiCo, Inc., Jianlibao Group, Monster Beverage Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Energy- Drinks Market Strategic Shifts
Ingredient sourcing transparency and format portability are compressing traditional category boundaries between energy drinks, functional waters, and sports nutrition. Formulators now compete on matrix complexity rather than caffeine dosage alone.
Microencapsulation technology for sustained-release caffeine is fragmenting consumption occasion segmentation. Athletes and shift workers adopt single products that deliver multi-hour alertness curves without repeated dosing. This capability is compressing the historical divide between immediate-effect energy drinks and extended-duration sports nutrition.
SAMR's draft guidelines on energy-drink versus sports-nutrition classification are forcing portfolio restructuring. Brands must choose between food-beverage regulatory pathways or health-product registration with stricter clinical substantiation requirements. Tier-one distributors are responding by creating separate merchandising sets that prevent cross-category confusion at point of sale.
Subscription-based replenishment through e-commerce platforms is displacing supermarket impulse purchasing among white-collar consumers in Beijing and Shenzhen. Tmall and JD.com locker networks enable workplace delivery that bypasses convenience store markup. This channel shift is most visible among technology sector employees who prioritize time efficiency over physical browsing.
China Energy- Drinks Market Segmentation
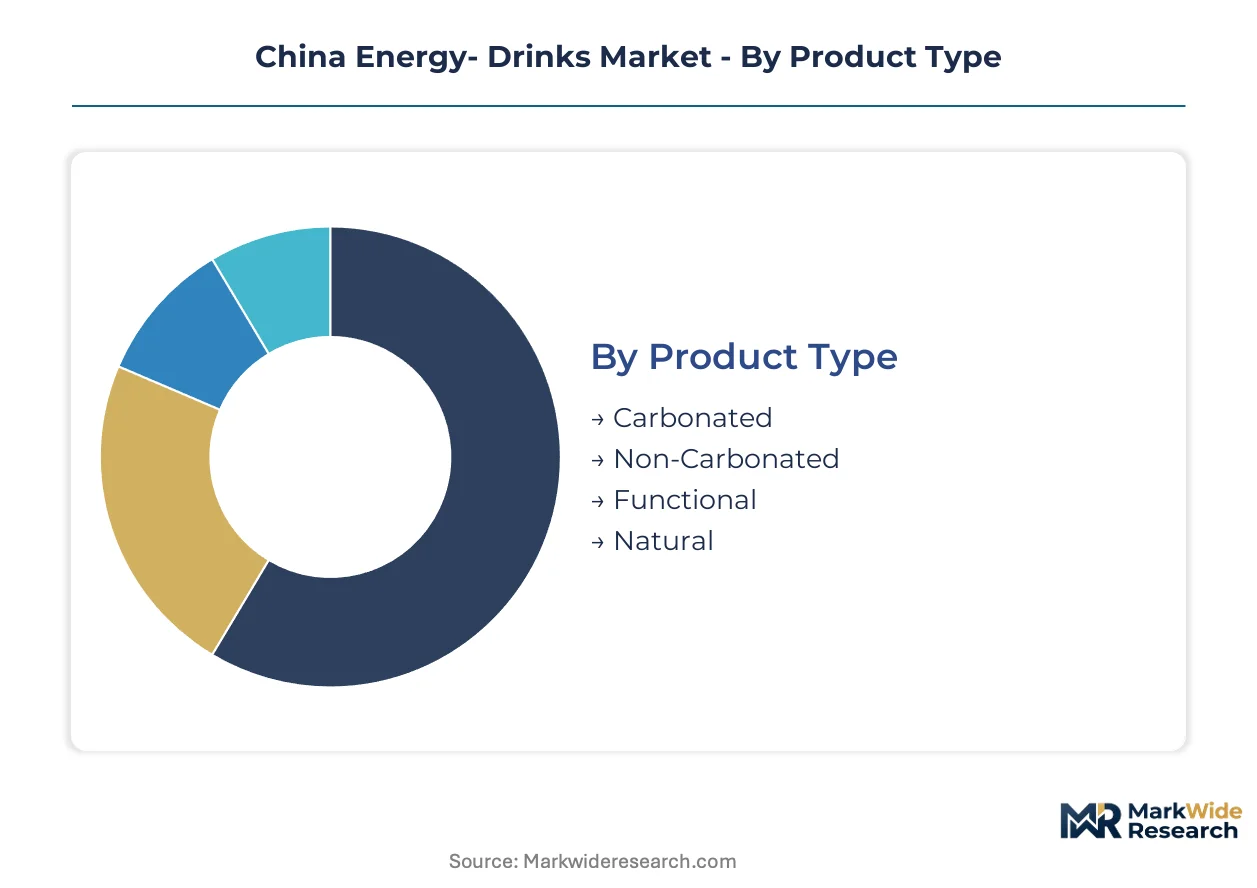
Segmentation in China's energy-drink market reveals how SAMR's dual regulatory pathways—food-beverage versus health-product classification—create divergent compliance burdens across product formats. Manufacturers must align formulation choices with distribution channel requirements to avoid approval delays.
Product Type:
GB standards on caffeine disclosure and additive transparency differentiate compliance obligations across formulation categories, with synthetic versus plant-derived matrices facing distinct SAMR review timelines.
- Carbonated:These formulations combine dissolved carbon dioxide with standard caffeine-taurine matrices at 80-150mg caffeine per serving. Demand concentrates in Shanghai and Shenzhen convenience channels where chill-retention drives impulse purchasing among commuters facing extended work shifts. SAMR's labeling mandates for sugar content have forced reformulation toward reduced-calorie variants.
- Functional:Enhanced matrices incorporate B-vitamins, adaptogens, and amino acid complexes beyond baseline stimulant profiles. Health Enthusiasts in Beijing and Guangzhou pull adoption toward clinically substantiated claims, though NMPA oversight restricts direct communication of adaptogenic effects. This segment climbs the fastest as ingredient transparency becomes a purchase determinant.
- Non-Carbonated:Still formulations prioritize rapid consumption without gastric discomfort during athletic activity. Gym channels in Chengdu and Wuhan stock these for pre-workout consumption.
- Natural:Plant-derived caffeine from green tea and yerba mate combined with ginseng extracts. Clean-label positioning attracts premium positioning in specialty shops.
Established volume favors Carbonated; emerging adoption favors Functional.
End User:
Consumption occasion fragmentation across professional, athletic, and academic contexts drives format and channel preferences, with urban work cultures normalizing energy-drink use outside traditional sports settings.
- Busy Professionals:White-collar workers in tier-one cities consume during commutes and late shifts, expanding daily consumption windows beyond traditional occasions. Tmall and JD.com locker networks enable workplace delivery that bypasses convenience store markup. Technology sector employees prioritize time efficiency over physical browsing.
- Athletes:Gym and competitive sports contexts demand sustained-release formulations with electrolyte co-factors. Fitness centers in Chengdu and Wuhan deploy powder sachets through direct locker and vending placement, bypassing traditional retail entirely.
- Students:Academic examination periods concentrate demand in lower-price-tier carbonated variants through campus convenience networks.
- Health Enthusiasts:Ingredient panel scrutiny drives preference for natural matrices with transparent sourcing documentation. Specialty café substitution poses competitive pressure in Beijing and Guangzhou.
Volume concentration rests with Busy Professionals; steepest expansion trajectory appears among Athletes adopting gym-channel powder formats.
Packaging Type:
Single-serve portability versus bulk economics shapes manufacturer capital allocation, with aseptic powder-filling equipment demanding balance sheet strain for mid-tier producers.
- Cans:Aluminum containers dominate due to superior chill-retention and single-serve portability. Kiosk networks in third- and fourth-tier cities rely on this format for ambient storage compatibility.
- Powder Sachets:Microencapsulated caffeine enables precise dosing control and travel-friendly logistics. Gym channel innovation in Chengdu and Wuhan demonstrates format versatility outside traditional retail gatekeepers.
- Bottles:PET and glass variants accommodate larger serving sizes for extended consumption occasions. Supermarket placement favors this format for home-stockpiling behavior.
- Multipacks:Bundled units capture price-sensitive volume in warehouse club and online retail channels. E-commerce subscription models displace impulse purchasing among white-collar consumers.
Cans retain channel dominance; Powder Sachets gain share fastest through fitness center direct placement.
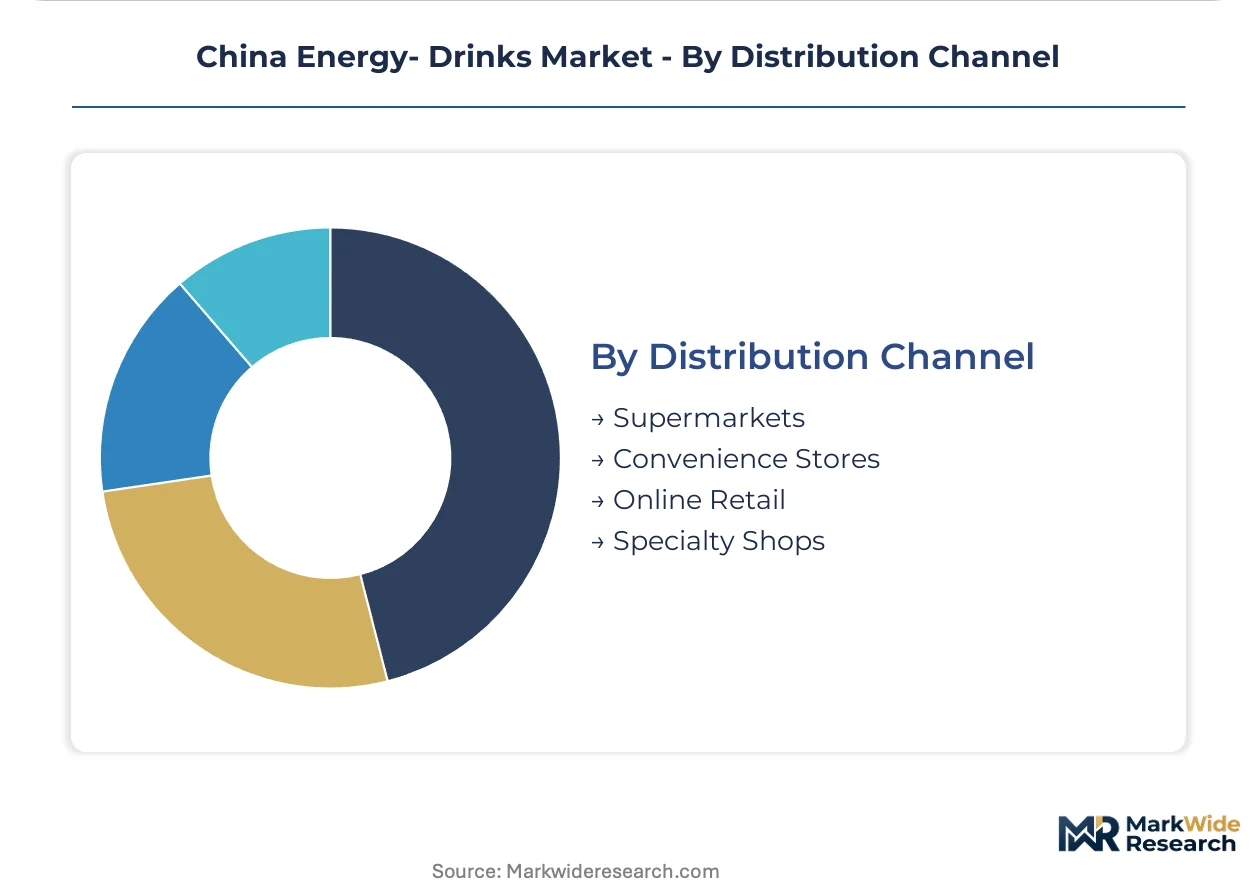
Distribution Channel:
Physical retail densification versus digital replenishment models create parallel access architectures, with unmanned retail networks extending penetration into previously underserved geographies.
- Convenience Stores:High-traffic urban locations in Shanghai and Shenzhen sustain premium functional variant placement. Extended operating hours align with professional consumption occasion expansion.
- Online Retail:Tmall and JD.com platforms enable subscription-based replenishment that displaces supermarket impulse purchasing. Locker networks bypass last-mile delivery friction for workplace consumption.
- Supermarkets:Traditional gatekeepers face share erosion as digital channels capture white-collar replenishment behavior. Still relevant for multipack and family-size purchasing.
- Specialty Shops:Curated assortments of natural and functional variants serve Health Enthusiasts seeking ingredient transparency. Beijing and Guangzhou clusters show highest channel development.
Convenience Stores anchor physical volume; Online Retail expands most quickly through subscription mechanics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium functional variants command pricing power in Shanghai and Shenzhen that outstrips fourth-tier city benchmarks by substantial margins. SAMR's GB standards apply uniformly, yet enforcement intensity and consumer sophistication create divergent commercial outcomes across China's urban hierarchy.
Shanghai
Extended work-hour normalization among finance and technology professionals compresses consumption toward portable, single-serve formats during commutes and late shifts. SAMR's labeling mandates for sugar content and caffeine disclosure force continuous reformulation investments from brands seeking shelf placement in high-traffic convenience channels. Lujiazui and Zhangjiang Hi-Tech Park clusters concentrate demand for sustained-release formulations that align with multi-hour alertness requirements.
Shenzhen
Technology sector employees prioritize time efficiency, driving subscription-based replenishment through Tmall and JD.com locker networks that bypass traditional retail gatekeepers. MIIT oversight on cross-border e-commerce platforms shapes import formulation accessibility for premium international brands. Nanshan and Longgang districts anchor consumption density, with unmanned retail networks extending penetration into manufacturing corridors.
Beijing
Health Enthusiasts scrutinize ingredient panels, pulling adoption toward natural matrices with transparent sourcing documentation despite NMPA restrictions on direct adaptogenic claims. Dual carbon goals under MEE influence packaging material specifications and recycling infrastructure investments. Zhongguancun and Yizhuang clusters demonstrate highest specialty shop channel development for curated functional assortments.
Chengdu
Fitness center direct placement of powder sachets bypasses traditional retail entirely, with gym channels in High-Tech Zone and Tianfu New Area deploying microencapsulated caffeine formats through locker and vending systems. Western China expansion strategies target this sub-region for whitespace penetration before saturation reaches eastern benchmarks.
Guangzhou
Specialty café substitution poses competitive pressure as premium single-origin coffee captures alertness-seeking consumers in Tianhe and Haizhu districts. GB standards on food additive transparency accelerate clean-label positioning investments from formulators seeking differentiation against beverage alternatives. Pearl River Delta logistics infrastructure enables rapid distribution refresh cycles for fast-moving variants.
China Energy- Drinks Market Competitive Environment
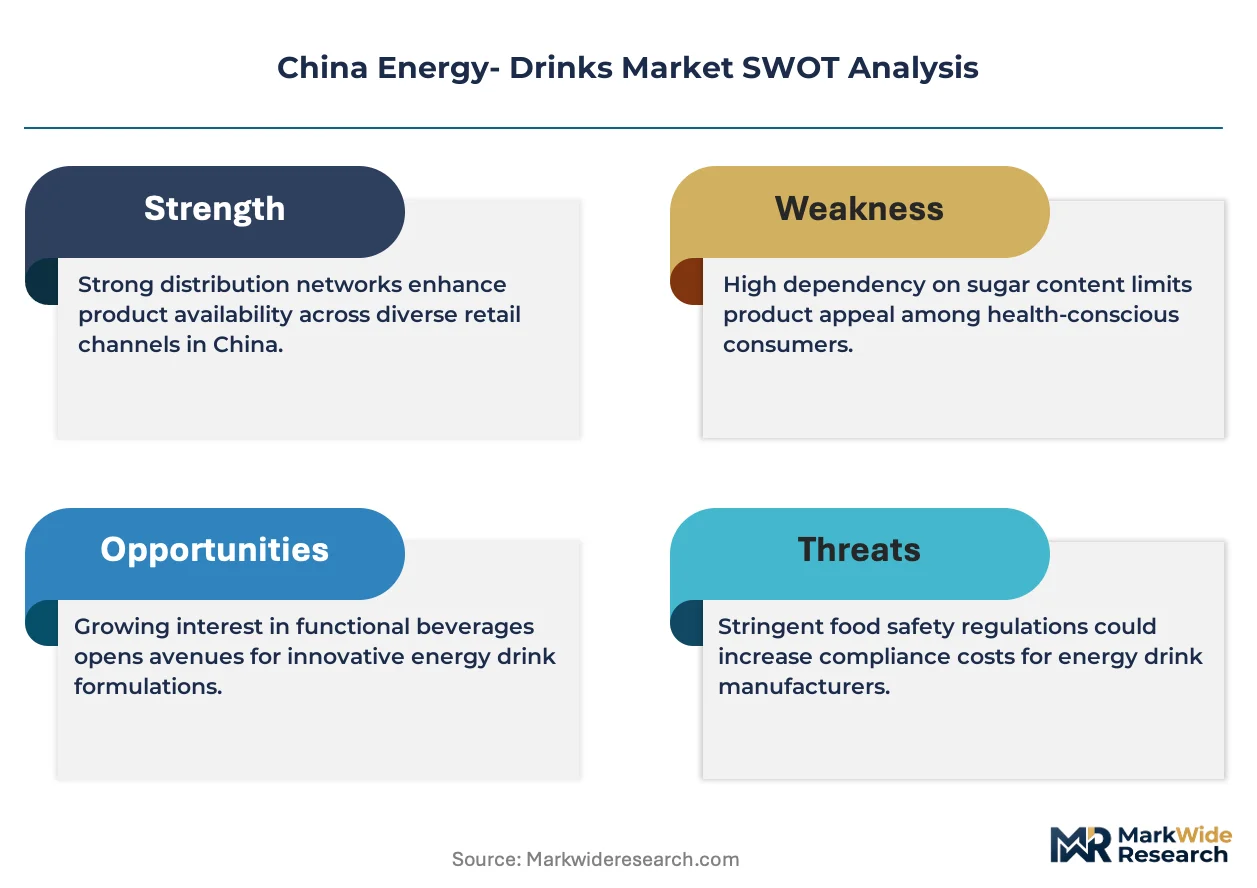
Concentration sits with diversified beverage conglomerates and specialized energy-drink pure-plays. The competitive set spans three tiers: multinational licensors leveraging global formula systems, domestic manufacturing scale leaders, and regional distribution specialists. Strategic moves center on portfolio diversification into functional and natural segments, plus backward integration into captive ingredient supply.
Among multinational pure-plays, Red Bull GmbH and Monster Beverage Corporation exemplify formula licensing and brand marketing archetypes. Domestic scale leaders include Hangzhou Wahaha Group Co Ltd and Eastroc Beverage Group Co., Ltd., representing manufacturing footprint and deep distribution competencies respectively. The Coca-Cola Company and PepsiCo, Inc. occupy diversified beverage conglomerate positions, while Otsuka Pharmaceutical and Taisho Pharmaceutical California Inc represent pharmaceutical-origin entrants with clinical substantiation capabilities.
| Leading Market Players |
|---|
| The Coca-Cola Company |
| Hangzhou Wahaha Group Co Ltd |
| Eastroc Beverage Group Co., Ltd. |
| Otsuka Pharmaceutical |
| Taisho Pharmaceutical California Inc |
| Red Bull GmbH |
| PepsiCo, Inc. |
| Jianlibao Group |
| Monster Beverage Corporation |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts for taurine and caffeine concentrate lock in supply access and price visibility for domestic formulators navigating SAMR's tightening GB standards on additive transparency. These arrangements insulate manufacturers from Southeast Asian input volatility while compressing margin flexibility for mid-tier producers lacking procurement scale.
Pricing Analysis
The customization-premium spread between standard carbonated variants and functional formulations with adaptogenic matrices widens as health-conscious consumers in Beijing and Shanghai reward ingredient transparency. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade under NMPA functional-claim pathways and volume scale through e-commerce subscription mechanics. Pricing pressure stems from specialty café substitution in Guangzhou and Shenzhen, where single-origin coffee captures alertness-seeking professionals. Students and price-sensitive consumers in campus networks exhibit highest price elasticity, while Health Enthusiasts tolerate premium positioning for clinically substantiated formulations.
Supply Chain Analysis
The Strait of Malacca transit corridor for taurine and specialty caffeine extracts from Indonesia and Vietnam creates logistics vulnerability for Chinese formulators dependent on just-in-time ingredient flows. Raw material procurement draws from Southeast Asian chemical processing clusters, domestic B-vitamin synthesis facilities in Zhejiang, and imported adaptogenic botanicals from Korea and Japan. Single-source concentration in Indonesian taurine production exposes manufacturers to tariff friction and maritime disruption. Distribution runs through tiered wholesale networks: deep distribution into third- and fourth-tier city kiosks for mass-market variants, direct-to-locker e-commerce fulfillment for white-collar professionals, and gym-channel vending placement for powder sachet formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as specialty café chains and plant-based functional waters capture alertness occasions previously owned by carbonated energy drinks. The priority is retaining professional consumers through format innovation and clean-label repositioning.
For Market Incumbents: Consolidate formulation chemist talent in Shanghai and Hangzhou through competitive compensation packages that counter scarcity-driven turnover. Deepen backward integration into captive caffeine and taurine supply through strategic partnerships with Southeast Asian processors, reducing exposure to single-source vulnerability. Defend against natural coffee substitution by accelerating microencapsulated sustained-release product launches that replicate multi-hour alertness curves without repeated dosing.
For New Entrants and Emerging Players: Differentiate on plant-derived matrix positioning using ginseng and rhodiola extracts that enable clean-label claims without synthetic additive reliance. Target fourth-tier city whitespace in Sichuan and Henan provinces where kiosk networks lack premium functional variants and incumbent distribution remains shallow. Pursue gym-channel direct placement in Chengdu and Wuhan fitness centers, bypassing traditional retail gatekeepers entirely through locker and vending system partnerships.
For Investors and Strategic Acquirers: The market sits at a regulatory consolidation phase that favors manufacturers with dual SAMR-NMPA certification capabilities and established e-commerce subscription infrastructure. Long-term viability hinges on portfolio diversification into functional and natural segments as GB standards commoditize baseline carbonated variants. Monitor SAMR draft guidelines on energy-drink versus sports-nutrition classification as the inflection signal: regulatory pathway clarity will determine which formulation investments capture margin expansion versus compliance cost traps.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Ingredient Supply | Reduces single-source vulnerability for taurine and caffeine concentrates from Southeast Asian clusters. |
| Microencapsulated Sustained-Release Formulation Launch | Compresses consumption occasion segmentation between immediate-effect drinks and extended-duration sports nutrition. |
| Gym-Channel Direct Placement Expansion | Bypasses traditional retail gatekeepers through locker and vending deployment in Chengdu and Wuhan fitness centers. |
| Clean-Label Natural Matrix Repositioning | Enables premium positioning under tightening SAMR GB standards on additive transparency and disclosure. |
| E-Commerce Subscription Infrastructure Buildout | Captures white-collar replenishment behavior through Tmall and JD.com locker networks in Beijing and Shenzhen. |
Study Parameters
Desk research of regulatory filing databases, customs trade records, and beverage industry association reports preceded structured interviews with SAMR compliance officers, formulation chemists at domestic manufacturers, convenience store category buyers, and gym channel operators. Primary fieldwork captured operational constraints on reformulation timelines, distribution economics across tiered cities, and consumer occasion fragmentation. Secondary validation drew from NMPA functional-claim registries, GB standard documentation, and e-commerce platform transaction data. Bottom-up segment sizing triangulated against top-down market envelope estimates.
Variance decomposition across product type, end-user occasion, packaging format, and distribution channel dimensions anchored the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate blending weighted by base-year value shares. Modeled inputs incorporated urban work-hour extension trajectories in tier-one cities, SAMR regulatory clarification timelines, and specialty café penetration rates as demand-side displacement factors.
Material uncertainties — SAMR classification rulings, NMPA functional-claim enforcement intensity, and Southeast Asian input supply disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory pathway stability and consumer substitution elasticity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Zero Proof Spirit Market
Non-Alcoholic Beverages
Fermented Non Dairy Non Alcoholic Beverages Market
Non-Alcoholic Beverages
Hydrogen Water Pitcher Market
Non-Alcoholic Beverages
Probiotic Soda Market
Non-Alcoholic Beverages
US NFC Lemon Juice Market
Non-Alcoholic Beverages
Europe Energy Drink Market
Non-Alcoholic Beverages
Non-Alcoholic Spirits Market
Non-Alcoholic Beverages
Carbonated Ready-To-Drink Tea Market
Non-Alcoholic Beverages
Europe Non-Alcoholic Wine and Beer Market
Non-Alcoholic Beverages
Global RTD Tea Drinks Market
Non-Alcoholic Beverages
North America Soy Beverages Market
Non-Alcoholic Beverages
United Arab Emirates Bottled Water Market
Non-Alcoholic Beverages
Bubble Tea Market
Non-Alcoholic Beverages
Non-Alcoholic Wine and Beer Market
Non-Alcoholic Beverages
Energy Drinks Market
Non-Alcoholic Beverages
Gulf Cooperation Council (GCC) Bottled Water Market