
 Europe Smokeless Indoor Grills Market | 2026-2036
Europe Smokeless Indoor Grills Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Smokeless Indoor Grills Market Insights
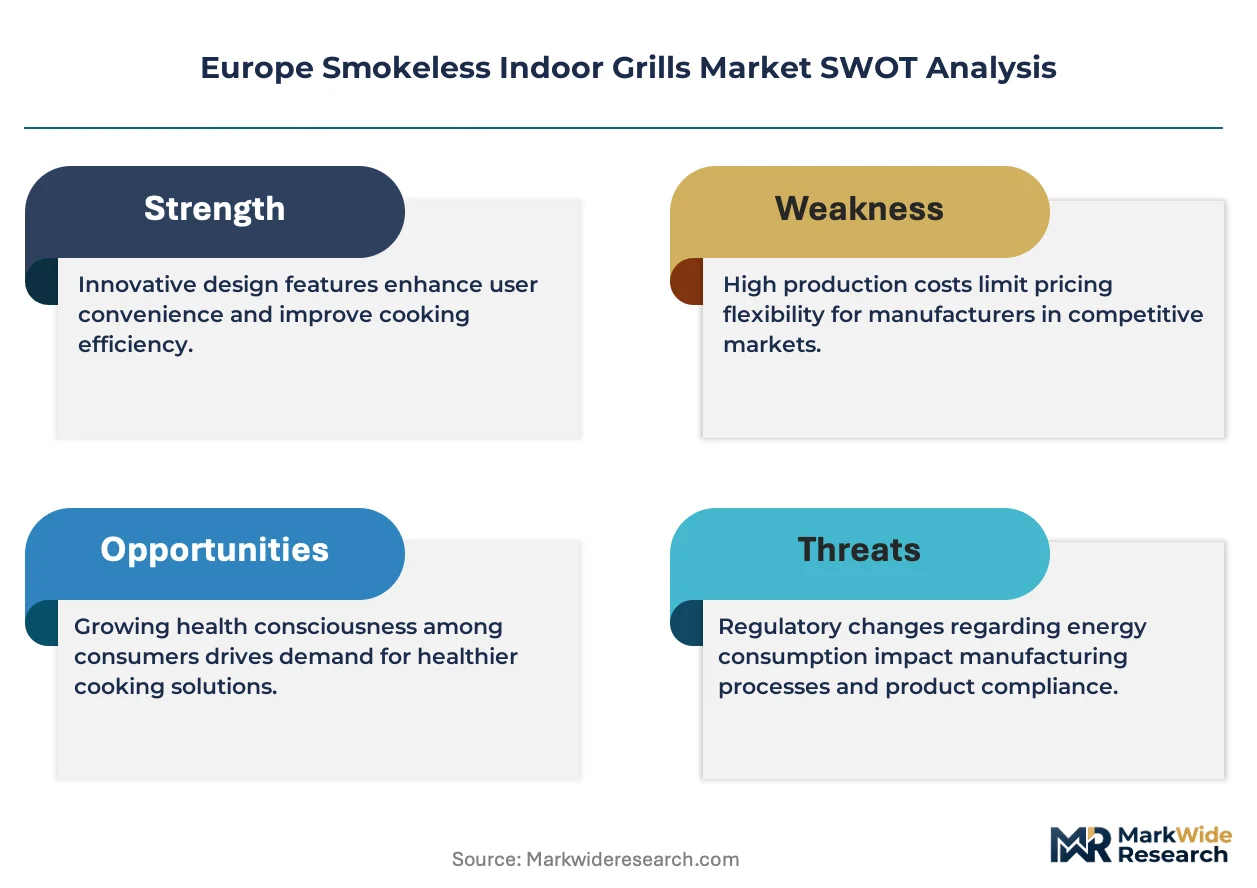
The gap between premium and commodity tiers in Europe smokeless indoor grills is broadening as ceramic-plate infrared models command three-to-four times the price of basic non-stick electric units. Philips leverages its appliance R&D footprint in the Netherlands to sustain technology leadership in precision temperature control systems. Groupe SEB anchors its competitive position through deep wholesale relationships with French and Benelux department store networks. Ninja Kitchen differentiates via direct-to-consumer online retail channels that bypass traditional European kitchenware distributors.
Smokeless indoor grills are electrically powered cooking appliances that use infrared radiation, closed-loop airflow, or water-trap grease management to reduce particulate and vapor emissions below detectable thresholds in enclosed residential or commercial kitchens. European units typically operate at 1,500–2,200 watts with cooking surfaces ranging from 1,200 to 2,400 square centimeters, designed to satisfy Ecodesign Directive standby power limits. Electric grills occupy the largest installed base due to lower price points and universal voltage compatibility across EU member states. Infrared grills represent the fastest-expanding category as chefs and home cooks pursue sear performance without ventilation infrastructure. Hybrid grills combining electric and infrared elements are capturing margin-rich positioning in specialty retail channels.
CE marking under the Low Voltage Directive and Ecodesign framework governs electrical safety and energy efficiency for all units sold in EU territory, while REACH restricts hazardous substances in non-stick coatings and ceramic components. France's national energy regulator enforces stricter standby consumption thresholds than baseline EU requirements, tilting procurement toward premium certified models. Germany's Federal Institute for Risk Assessment evaluates grill surface coatings for food-contact migration limits. Buyers and manufacturers must monitor evolving Ecodesign implementing measures that will likely expand to cover operational energy consumption, not just standby power.
Market Dynamics
Urban apartment densification across Western European capitals is compressing available kitchen space and eliminating outdoor cooking options, forcing appliance manufacturers to miniaturize infrared heating elements while maintaining sear temperatures above 230°C.
Growth Catalysts
- Ecodesign standby power limits:Stricter EU thresholds are filtering out inefficient legacy models and redirecting procurement toward certified premium units with sub-1-watt standby consumption.
- Ceramic infrared plate technology:French and German culinary enthusiasts are adopting high-heat radiant cooking for steak searing without ventilation infrastructure.
- Benelux metropolitan clusters:Amsterdam and Brussels apartment dwellers are driving compact electric grill penetration in 45-square-meter kitchens.
Market Restraints
- Stainless steel input volatility:Nickel price swings are compressing margins on premium housing and cooking surface components sourced from Nordic mills.
- REACH coating compliance:Migration testing for PTFE alternatives is extending product development cycles by 8-14 months for non-stick surface iterations.
- Induction cooktop substitution:Built-in radiant hobs with grill plates are capturing space-constrained kitchen renovations in Scandinavian markets.
Strategic Opportunities
- Spanish secondary cities:Valencia and Seville rental markets remain underpenetrated for compact electric grills relative to Madrid and Barcelona saturation.
- Direct-to-consumer channels:Ninja Kitchen's bypass model is demonstrating margin capture potential outside traditional department store networks.
- EU Green Deal appliance incentives:National rebate programs for A-rated electric cooking equipment are tilting replacement cycles toward certified smokeless models.
Industry Challenges
- Thermal engineer scarcity:Infrared emitter design expertise is concentrating in Eindhoven and Stuttgart industrial clusters, constraining R&D scaling.
- CE marking timeline compression:Notified body backlogs for Low Voltage Directive certification are delaying product launches by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Smokeless Indoor Grills Market |
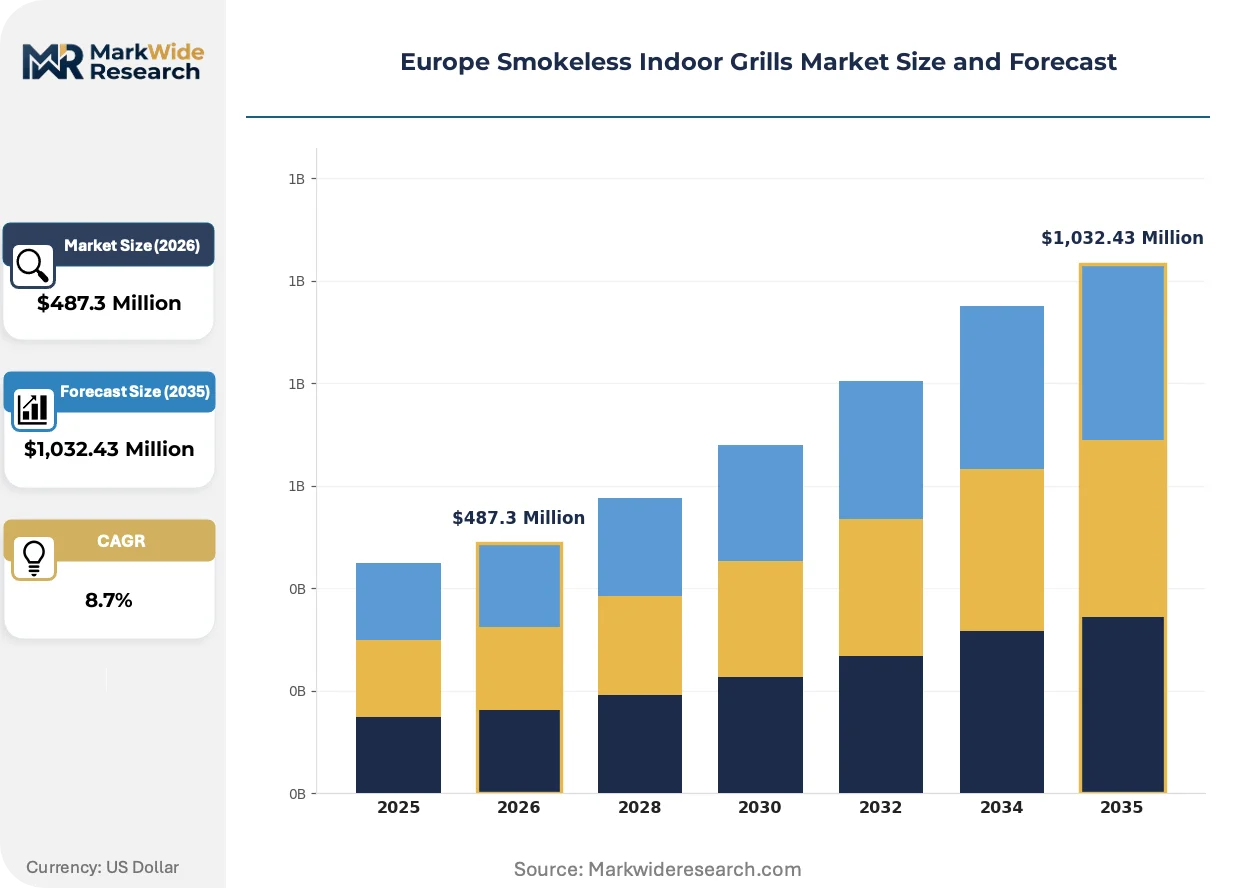
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Grills, Infrared Grills, Non-Stick Grills, Hybrid Grills End User: Households, Restaurants, Food Trucks, Catering Services Material: Stainless Steel, Aluminum, Ceramic, Cast Iron Distribution Channel: Online Retail, Specialty Stores, Department Stores, Wholesale Suppliers |
| Companies Covered | Shinpo Co, Coleman, Philips, De'Longhi, Groupe SEB, Ninja Kitchen, Midea, Hamilton Beach, Power XL, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Smokeless Indoor Grills Market Trends and Innovations
Heating architecture is fragmenting into interchangeable component systems that let manufacturers swap infrared emitters, electric coils, and hybrid configurations within shared chassis platforms.
Smart temperature control firmware is modularizing across Philips and Groupe SEB product lines, enabling precision probe integration and app-based recipe programming that apartment chefs in Berlin and Paris are adopting twice as fast as analog dial interfaces. This flexibility is compressing SKU proliferation costs while allowing regional customization for voltage and safety standards.
France's national energy regulator has tightened standby consumption thresholds beyond baseline EU Ecodesign requirements, forcing importers to retest inventory and accelerating phase-out of non-compliant stock in Galeries Lafayette and BHV Marais channels. Premium certified models are capturing shelf space previously occupied by entry-tier alternatives.
Specialty kitchen retailers are unbundling after-sales service from hardware margins, shifting warranty extensions and cleaning kit subscriptions to recurring revenue models. This pattern is most visible in German markets where WMF and Zwilling flagship stores in Munich and Hamburg are piloting membership programs for appliance maintenance.
Europe Smokeless Indoor Grills Market Segmentation
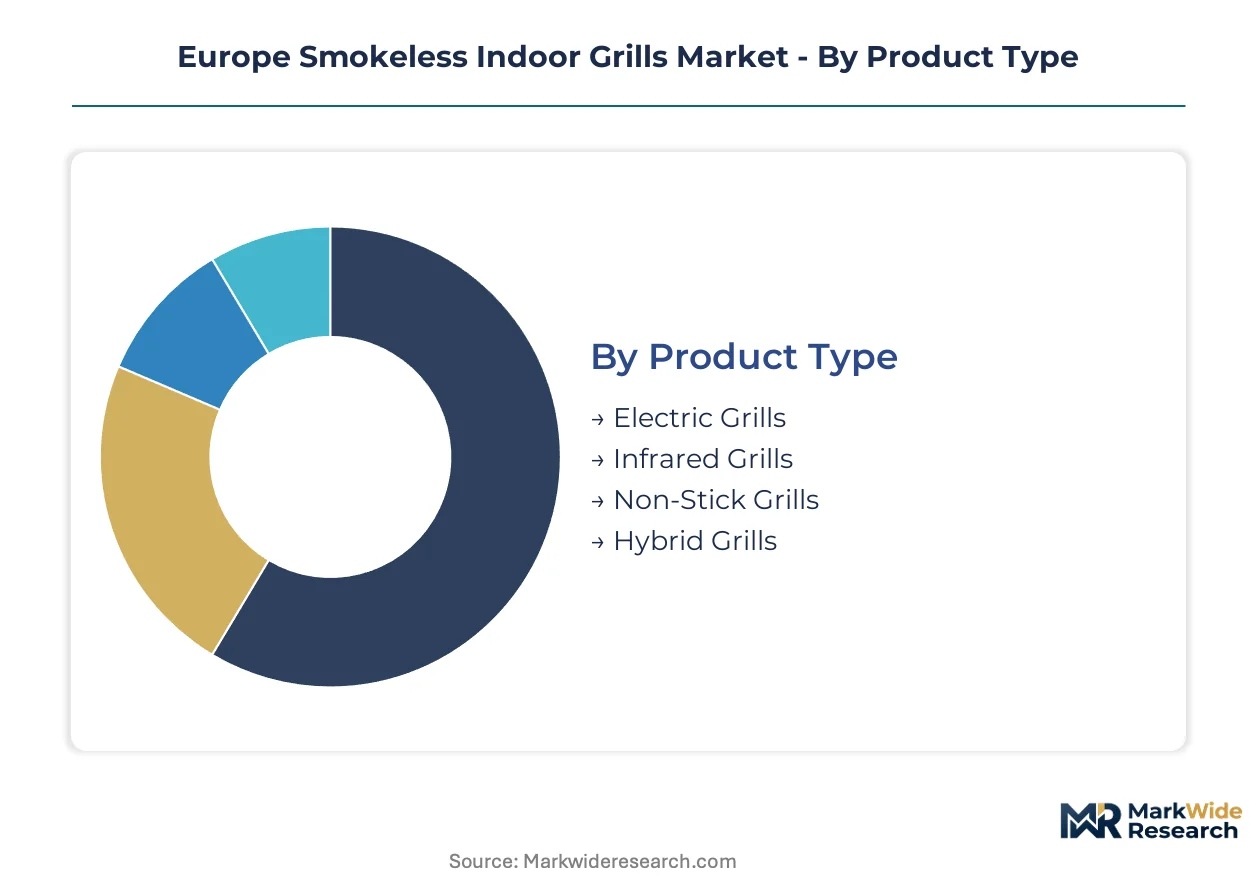
Smokeless indoor grill manufacturers configure product portfolios around four intersecting dimensions. Each dimension carries distinct margin profiles, certification requirements, and channel access rules that determine competitive positioning across European markets.
Product Type:
Production capacity concentrates in infrared and hybrid configurations, with Eindhoven and Stuttgart engineering clusters supplying precision emitter components to multiple brands.
- Electric Grills:Resistive coil elements deliver 1,500–2,200 watts through cast aluminum or steel plates. German and Benelux apartment dwellers favor these units for sub-100 euro price points and universal voltage compatibility across EU member states.
- Infrared Grills:Ceramic plate emitters generate radiant heat above 230°C for steak searing without ventilation infrastructure. French culinary enthusiasts in Paris and Lyon are expanding purchases as Ecodesign standby limits filter out inefficient legacy models.
- Non-Stick Grills:PTFE or ceramic-coated surfaces target entry-tier buyers. REACH compliance testing for coating migration limits extends development cycles for these units.
- Hybrid Grills:Combined electric coil and infrared architectures command premium positioning in specialty retail. Margin capture justifies higher BOM costs from dual heating systems.
Today's leader: Electric Grills. Tomorrow's challenger: Infrared Grills.
End User:
Cost tier stratification separates household procurement from commercial applications, with restaurants and catering services demanding certified durability ratings that households rarely require.
- Households:Urban apartment dwellers in compact kitchens drive volume. Amsterdam and Brussels 45-square-meter units create demand for miniaturized footprints with storage efficiency.
- Restaurants:Full-service kitchens require continuous-duty cycles and NSF-equivalent hygiene certifications. These buyers prioritize infrared speed over electric economy.
- Food Trucks:Mobile operators need 220V compatibility and vibration-resistant housing. Spanish operators in Valencia and Seville represent underpenetrated demand relative to Madrid saturation.
- Catering Services:Event rental fleets demand modular cleaning systems and rapid heat recovery. Volume procurement runs through wholesale supplier relationships rather than retail channels.
Households dominate unit shipments. Restaurants command average selling prices three times higher.
Material:
Volume concentration in stainless steel creates supply vulnerability to nickel price volatility from Nordic mill sourcing.
- Stainless Steel:Austenitic grades with 18/10 chromium-nickel composition dominate premium housing and cooking surfaces. German Federal Institute for Risk Assessment evaluates these materials for food-contact migration compliance.
- Aluminum:Die-cast substrates with anodized or ceramic finishes reduce weight for portable units. Cost advantages position these in entry-tier electric grill segments.
- Ceramic:Infrared emitter plates and non-stick coatings substitute for PTFE under REACH restrictions. French regulators enforce stricter consumption thresholds than baseline EU requirements.
- Cast Iron:Retained-heat cooking surfaces appeal to traditionalist segments. Weight penalties limit adoption in compact urban kitchens.
Stainless steel anchors current production. Ceramic components are climbing the fastest as coating regulations tighten.
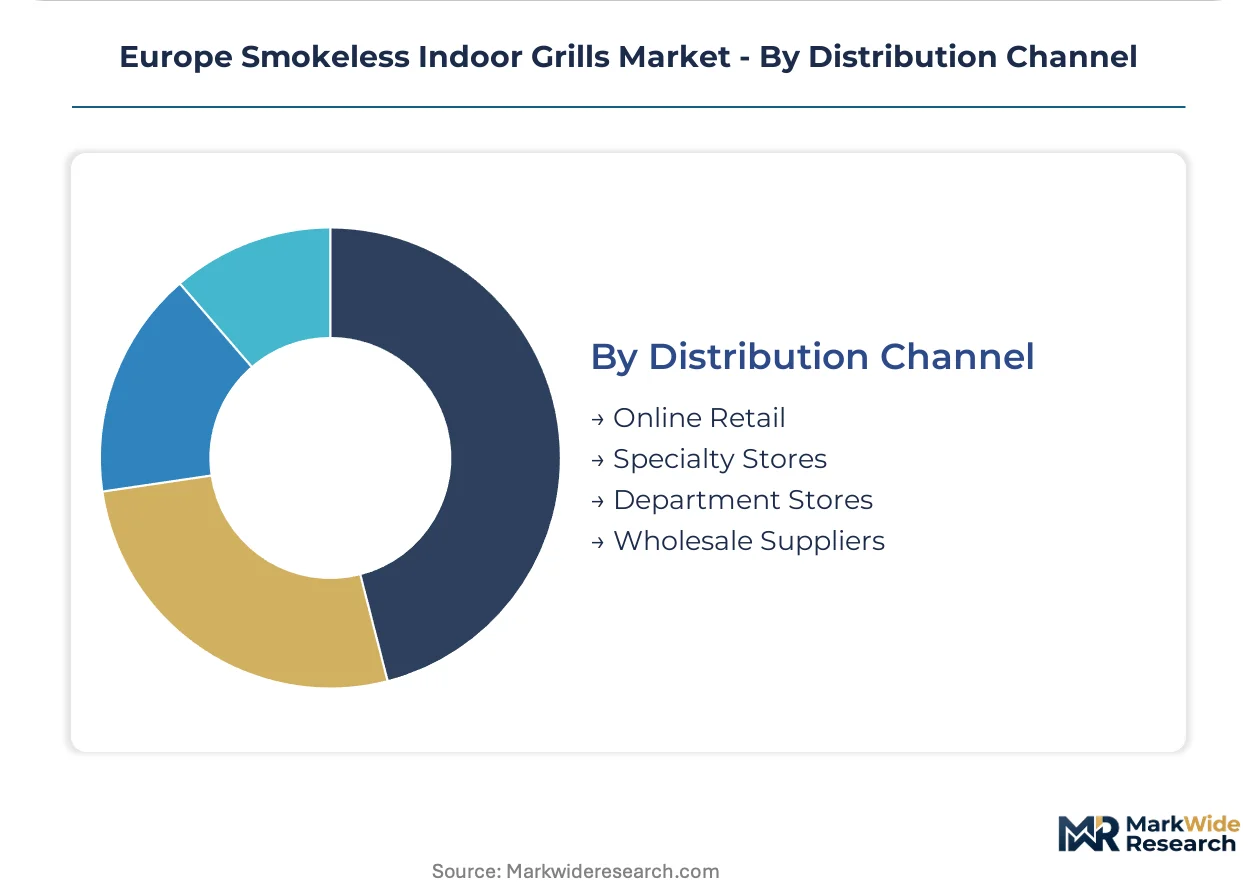
Distribution Channel:
Margin structure varies sharply by channel control, with direct-to-consumer models bypassing traditional distributor markups.
- Online Retail:Ninja Kitchen and direct brands capture full margin through proprietary storefronts. Berlin and Paris consumers adopt app-integrated smart models twice as fast as analog alternatives through these channels.
- Specialty Stores:WMF and Zwilling flagship locations in Munich and Hamburg pilot subscription maintenance programs. These outlets unbundle hardware from recurring service revenue.
- Department Stores:Galeries Lafayette and BHV Marais channels in France are reallocating shelf space toward Ecodesign-certified premium units. Non-compliant inventory faces accelerated phase-out.
- Wholesale Suppliers:Commercial kitchen distributors serve restaurant and catering procurement with volume pricing and extended warranty terms. Groupe SEB anchors competitive position through deep wholesale relationships in French and Benelux networks.
Department stores hold established position. Online retail is gaining share fastest through margin capture and smart feature integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thermal engineering talent clusters in Eindhoven and Stuttgart anchor European smokeless grill innovation, while Paris and Berlin metropolitan markets concentrate consumer demand for compact electric cooking appliances.
Germany
Berlin and Munich apartment dwellers drive demand for miniaturized infrared units with sub-1-watt standby consumption. The Federal Institute for Risk Assessment enforces strict food-contact migration limits on grill surface coatings. Stuttgart engineering clusters supply precision temperature control systems to multiple appliance brands.
France
Paris and Lyon culinary enthusiasts adopt ceramic-plate infrared models for high-heat searing without ventilation infrastructure. The national energy regulator mandates stricter standby thresholds than baseline EU Ecodesign requirements. Galeries Lafayette and BHV Marais channels in Paris reallocate shelf space toward certified premium units.
Netherlands
Amsterdam's compact 45-square-meter kitchens create demand for storage-efficient electric grills with universal voltage compatibility. CE marking under the Low Voltage Directive governs electrical safety certification for all units sold. Eindhoven's appliance R&D footprint sustains technology leadership in smart temperature control firmware.
Belgium
Brussels apartment dwellers expand purchases of compact electric units as urban densification eliminates outdoor cooking options. REACH compliance restricts hazardous substances in non-stick coatings and ceramic components. Benelux wholesale networks anchor distribution relationships for commercial and household procurement.
Spain
Valencia and Seville rental markets remain underpenetrated for compact electric grills relative to Madrid and Barcelona saturation. EU Green Deal appliance incentives tilt replacement cycles toward A-rated electric cooking equipment. Food truck operators in secondary cities demand 220V compatibility and vibration-resistant housing.
Europe Smokeless Indoor Grills Market Competitive Landscape
Top-tier vendors anchor premium positioning through technology leadership and wholesale channel control, while mid-tier specialists compete on price and direct-to-consumer access. The vendor base spans diversified appliance conglomerates, single-category specialists, and Asian manufacturing platforms. Three archetypes dominate: engineering-driven innovators with precision control systems, brand-heritage players leveraging department store relationships, and digital-native challengers bypassing traditional distribution. Competitive moves concentrate on smart feature integration and subscription-based recurring revenue models.
Among diversified appliance conglomerates, Koninklijke Philips N.V. and Groupe SEB exemplify engineering-driven and brand-heritage archetypes respectively, while SharkNinja Operating LLC occupies the digital-native challenger position. Philips leverages its Netherlands-based R&D footprint to sustain technology leadership in precision temperature control. Groupe SEB anchors competitive position through deep wholesale relationships with French and Benelux department store networks. Ninja Kitchen demonstrates margin capture potential through direct-to-consumer online retail channels that bypass traditional European kitchenware distributors.
| Leading Market Players |
|---|
| Shinpo Co |
| Coleman |
| Philips |
| De'Longhi |
| Groupe SEB |
| Ninja Kitchen |
| Midea |
| Hamilton Beach |
| Power XL |
| Others |
Pricing and Supply Chain Analysis
Urban apartment densification across Western European capitals is compressing kitchen footprints and forcing procurement toward miniaturized infrared units with sub-1-watt standby consumption, compelling manufacturers to absorb premium component costs or surrender margin on entry-tier electric coil alternatives. This demand-side specification tightening feeds directly into supply chain configuration, as Eindhoven and Stuttgart engineering clusters capture pricing power through scarce thermal design expertise while Nordic stainless steel mills transmit nickel volatility downstream.
Pricing Analysis
The bundled-vs-unbundled service split is fragmenting traditional hardware-only transactions, with German specialty retailers piloting warranty extensions and cleaning kit subscriptions as recurring revenue streams separate from upfront unit sales. Three-tier pricing structure across premium ceramic-infrared, standard electric coil, and economy non-stick levels reflects certification grade differentiation under Ecodesign standby limits and REACH coating compliance. Cost compression in entry-tier segments is intensifying because PTFE alternative migration testing extends development cycles by 8-14 months, squeezing margin on sub-100 euro units while household buyers in Amsterdam and Brussels remain most price-sensitive. Restaurant procurement commands average selling prices three times higher with minimal elasticity, prioritizing infrared speed and NSF-equivalent durability ratings over unit economics.
Supply Chain Analysis
Reverse-logistics flows for warranty returns and refurbishment are emerging as margin-recovery channels, with French and Benelux department store networks piloting trade-in programs for Ecodesign-certified upgrades. Component supply concentrates in the Netherlands for precision temperature control firmware, Germany for stainless steel housings and emitter engineering, and China for electric coil and PCB assemblies. Raw material dependencies rest on nickel-bearing austenitic grades from Nordic mills, ceramic emitter substrates, and REACH-compliant PTFE alternative coatings. Single-source vulnerability in infrared plate manufacturing concentrates in Eindhoven-Stuttgart corridors, exposing launch timelines to thermal engineer scarcity. Distribution runs through wholesale supplier relationships for commercial kitchen procurement, direct-to-consumer online channels for smart-featured household units, and flagship specialty stores for premium positioning with attached service subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through ceramic infrared technology adoption displacing basic electric coil volumes, while Ecodesign standby limits filter out inefficient legacy inventory and redirect shelf space toward certified premium tiers with superior unit economics.
For Market Incumbents: Hedge against induction cooktop substitution in Scandinavian renovations by deepening wholesale control over French and Benelux department store networks before shelf reallocation completes. Accelerate backward integration into ceramic emitter plate production to reduce dependency on Eindhoven-Stuttgart engineering clusters where thermal design talent concentrates. CE marking timeline compression from notified body backlogs presents operational risk requiring pre-submission regulatory investment to defend launch windows against 4-6 month delays.
For New Entrants and Emerging Players: Smart temperature control firmware with app-based recipe programming offers a technology-first wedge into Berlin and Paris metropolitan demand, where consumers adopt connected features twice as fast as analog interfaces. Spanish secondary cities—Valencia and Seville rental markets—present underpenetrated white space relative to Madrid and Barcelona saturation, particularly for food truck operators requiring 220V compatibility and vibration-resistant housing. Direct-to-consumer online retail bypasses traditional distributor markups and captures full margin, following the Ninja Kitchen model demonstrated in established Western European markets.
For Investors and Strategic Acquirers: Asymmetric upside sits with digital-native challengers possessing proprietary smart firmware platforms and direct channel infrastructure, positioned to compound share as household procurement shifts online. Long-term viability across the analysis window favors acquisition targets with REACH-compliant coating pipelines and Ecodesign certification momentum, avoiding stranded inventory risk from regulatory phase-outs. Monitor CE marking backlog resolution and EU Green Deal appliance incentive uptake as early signals of inventory velocity inflection and replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Firmware Platform Development | Philips and Groupe SEB modularize precision temperature control across product lines for app integration. |
| Direct-to-Consumer Channel Expansion | Ninja Kitchen demonstrates margin capture potential bypassing traditional European kitchenware distributors. |
| Ceramic Infrared Technology Transition | French culinary enthusiasts in Paris and Lyon adopt high-heat radiant cooking without ventilation infrastructure. |
| Subscription Service Unbundling | WMF and Zwilling flagship stores in Munich and Hamburg pilot membership programs for appliance maintenance. |
| EU Green Deal Certification Alignment | National rebate programs for A-rated electric cooking equipment tilt replacement cycles toward certified smokeless models. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with appliance R&D directors, category buyers at French and Benelux department stores, thermal engineering leads in Eindhoven and Stuttgart clusters, and regulatory affairs specialists navigating CE marking and REACH compliance. Secondary validation drew from Ecodesign Directive implementing measures, ECHA substance restriction databases, customs records for EU-27 electric grill imports, and national energy regulator filings in France and Germany. Bottom-up unit shipment modeling triangulated against top-down value estimates from retail audit data and wholesale distributor interviews.
Segment-weighting approaches distributed volume and value across product type dimensions—electric, infrared, hybrid configurations—end-user categories spanning household, restaurant, food truck, and catering applications, material grades from stainless steel through ceramic and aluminum, and distribution channels including online retail, specialty stores, department stores, and wholesale suppliers. CAGRs were derived from fitted growth curves calibrated to urban densification rates, Ecodesign regulatory phase-in schedules, and technology adoption patterns for smart temperature control features. Forecast inputs incorporated nickel price volatility assumptions from Nordic mill sourcing and thermal engineer supply constraints in concentrated industrial clusters.
The model holds under steady Ecodesign standby limit enforcement and REACH coating compliance timelines; deviation in notified body backlog resolution or EU Green Deal incentive program scaling would shift replacement cycle timing and premium tier penetration rates. Practitioners should monitor CE marking queue lengths and national rebate program uptake rates for early signals of inventory velocity and channel mix evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
United States Quick Service Restaurants Market
Food Service
Beverage Coaster Market
Food Service
Europe Out of Home (OOH) Delivery Market
Food Service
Full-Service Restaurants Market
Food Service
India Foodservice Market
Food Service
United States Full Service Restaurants Market
Food Service
Contract Blending Services Market
Food Service
Food Logistics Market
Food Service
North America Food Service Disposable Market
Food Service
Food and Grocery Retail Market
Food Service
Food Service Utensils Market
Food Service
Restaurant Griddle Market
Food Service
Singapore Food Service Market
Food Service
Cutting Boards Market
Food Service
United States Foodservice Market
Food Service
Light Meal Market