
 Australia Foodservice Market | 2026-2036
Australia Foodservice Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Foodservice Market Analysis
Corporate catering is unwinding share from traditional family dining as hybrid work schedules reshape weekday meal occasions. McDonald's Australia Limited leverages its drive-through infrastructure to capture commuter traffic during compressed lunch windows. Domino's Pizza Enterprises Limited anchors its position through delivery-first kitchen layouts optimized for suburban density. Guzman y Gomez differentiates with fresh-protein supply chains that support made-to-order throughput at quick-service speed.
Foodservice encompasses the commercial preparation and sale of meals and beverages outside residential settings, spanning hot-held production, cold-chain assembly, and live-cooking stations designed for immediate consumption or near-term delivery. The sector serves institutional nourishment, social occasion dining, and convenience-driven refuelling across Australian urban and regional centres. Quick Service Restaurants lead volume throughput due to standardized menus and limited-service labour models that compress ticket times. Full-Service Restaurants concentrate margin pools where wine programmes and premium proteins elevate average checks. Delivery channels within the Distribution Channel segment capture disproportionate growth as aggregator platforms expand dark-kitchen penetration into secondary suburbs.
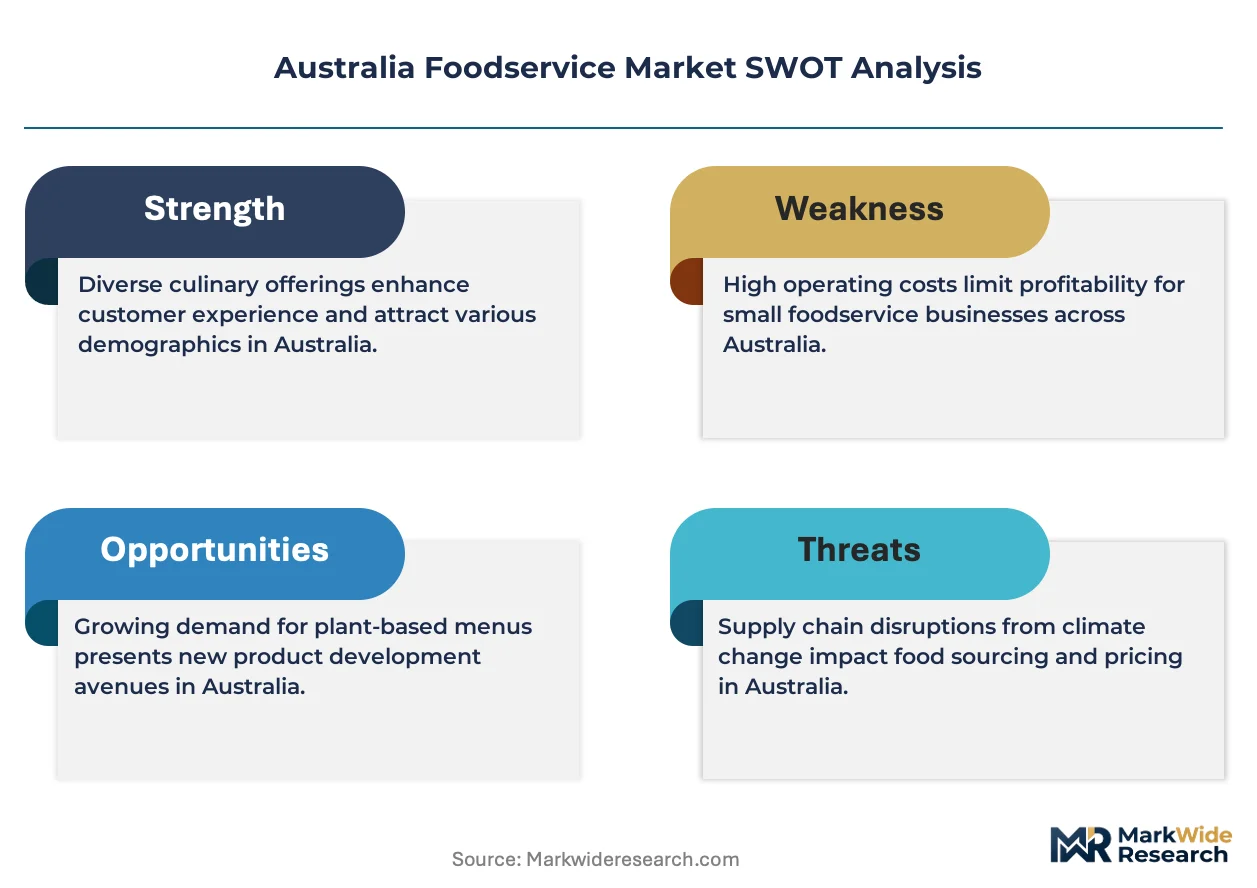
Food Standards Australia New Zealand mandates allergen declaration and nutrition labelling that elevates kitchen compliance costs while creating barriers for unverified imports. The Australian Competition and Consumer Commission scrutinises franchisor-franchisee terms, reshaping capital requirements for chain expansion. The Australian Taxation Office's fringe benefits tax treatment of staff meals influences corporate account structuring. Stakeholders must monitor regulatory calibration around gig-economy delivery worker classification, as reclassification rulings would restructure last-mile cost economics across the sector.
Market Dynamics
Hybrid work normalization has permanently altered weekday meal occasions in Australia, redirecting corporate catering spend away from traditional CBD lunch venues toward suburban delivery nodes and office park drop-off contracts.
Growth Catalysts
- Corporate catering contracts:Flexible work policies sustain demand for scheduled office meal programs across Sydney and Melbourne business districts. Employers structure fringe benefits tax arrangements through the Australian Taxation Office to subsidize staff dining.
- Aggregator platform expansion:Delivery-first kitchen layouts penetrate secondary suburbs beyond traditional restaurant footprints. Dark kitchens reduce real estate costs while maintaining proximity to residential density.
- Fresh-protein supply chains:Made-to-order throughput at quick-service speed attracts health-conscious consumers. Cold-chain integrity investments enable menu differentiation without compromising speed.
Market Restraints
- Food Standards Australia New Zealand allergen compliance:Mandatory declaration requirements elevate kitchen training costs and constrain menu engineering flexibility. Small operators face disproportionate burden from verification protocols.
- Franchisor-franchisee term scrutiny:Australian Competition and Consumer Commission intervention reshapes capital requirements for chain expansion. Disclosure obligations extend timeline to greenfield site development.
- Delivery worker classification uncertainty:Potential reclassification rulings threaten last-mile cost structures. Gig-economy labor models face regulatory pressure from employment tribunal precedents.
Strategic Opportunities
- Queensland quick-service penetration:Brisbane and Gold Coast corridors exhibit faster growth velocity than saturated southern metros. Population migration patterns support greenfield development with lower site acquisition costs.
- Drive-through infrastructure redeployment:Commuter traffic compression during compressed lunch windows favors formats with vehicle-accessible service points. Existing real estate adapts to suburban work-from-home clusters.
- Regulatory tailwind from nutrition labelling:Verified clean-label positioning commands premium positioning. Compliance investment creates barrier against unverified import competition.
Industry Challenges
- Allergen management workforce training:Cross-contamination protocols require specialized kitchen certification. Staff turnover in casual employment models erodes institutional knowledge retention.
- Legacy point-of-sale integration:Aggregator platform APIs conflict with established inventory management systems. Real-time menu synchronization demands middleware investment that compresses margin.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Foodservice Market |
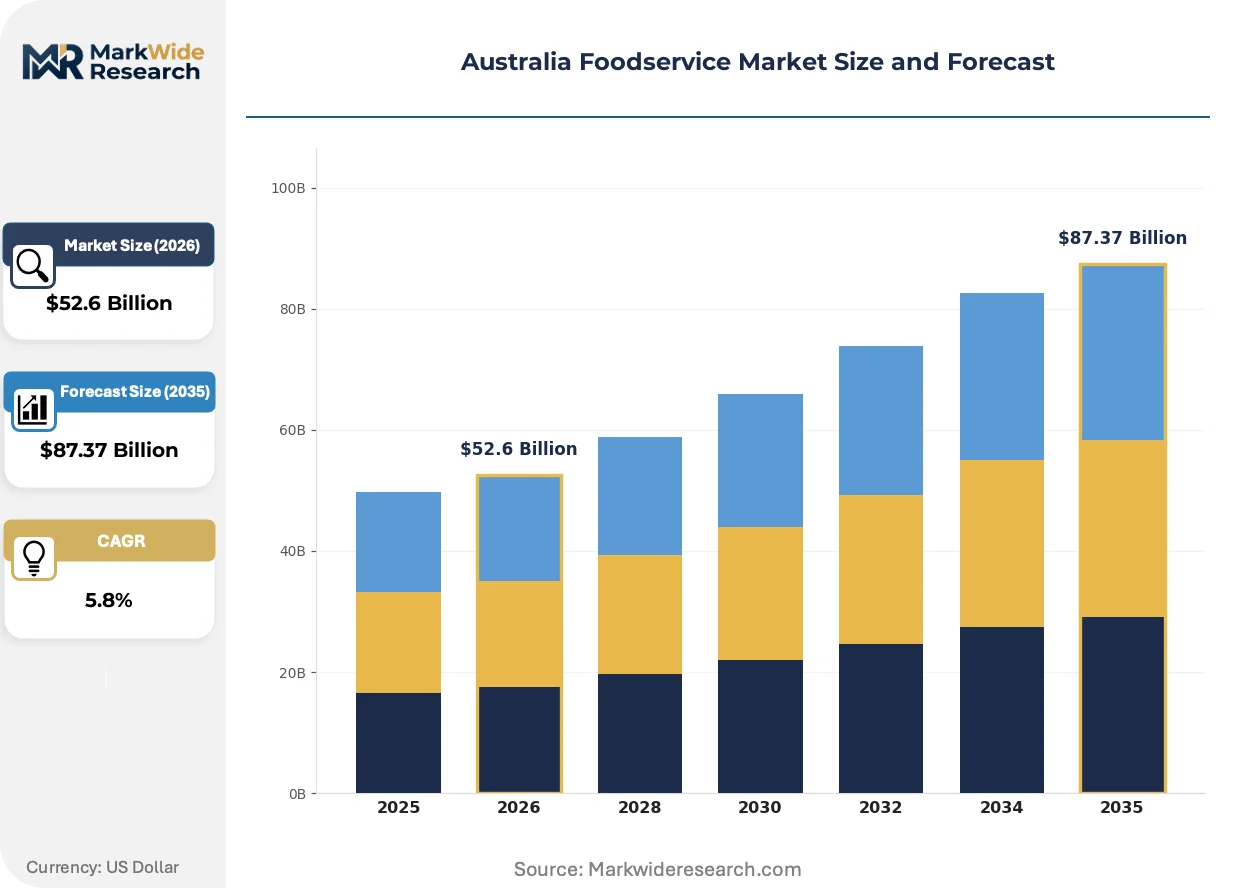
| Market Size in 2026 | $52.6 Billion |
| Market Size in 2035 | $87.37 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full-Service Restaurants, Quick Service Restaurants, Cafés, Food Trucks Menu Type: Vegetarian, Vegan, Gluten-Free, Organic Customer Type: Families, Business Professionals, Students, Tourists Distribution Channel: Dine-In, Delivery, Takeaway, Catering |
| Companies Covered | KFC, Craveable Brands, McDonald's Australia Limited, Guzman y Gomez, Yum! Brands, Inc., Domino's Pizza Enterprises Limited, Competitive Foods Australia, Zambrero Pty Ltd, Subway, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Foodservice Market Emerging Trajectories
Digital ordering infrastructure is restructuring competitive advantage around data capture and fulfillment speed rather than location premium. Technology deployment separates operators capable of dynamic menu pricing from those locked into static cost structures.
Artificial intelligence-driven demand forecasting is fragmenting inventory planning across the sector. Mid-size chains deploy machine learning models to predict hyperlocal consumption patterns within two-hour windows. Operators without predictive capability face spoilage penalties that compound during demand volatility.
Food Standards Australia New Zealand enforcement of nutrition labelling mandates is compressing reformulation timelines. Manufacturers must submit compositional data for pre-packaged components before menu rollout. Full-service restaurants with complex supplier networks face documentation burdens that quick-service standardized menus avoid.
Compressed lunch windows are displacing traditional sit-down formats in metropolitan cores. Office workers in Sydney CBD and Melbourne's Docklands prioritize speed over experience for weekday occasions. Suburban food courts and drive-through nodes capture occasion migration that permanent work-from-home patterns accelerate.
Australia Foodservice Market Segmentation
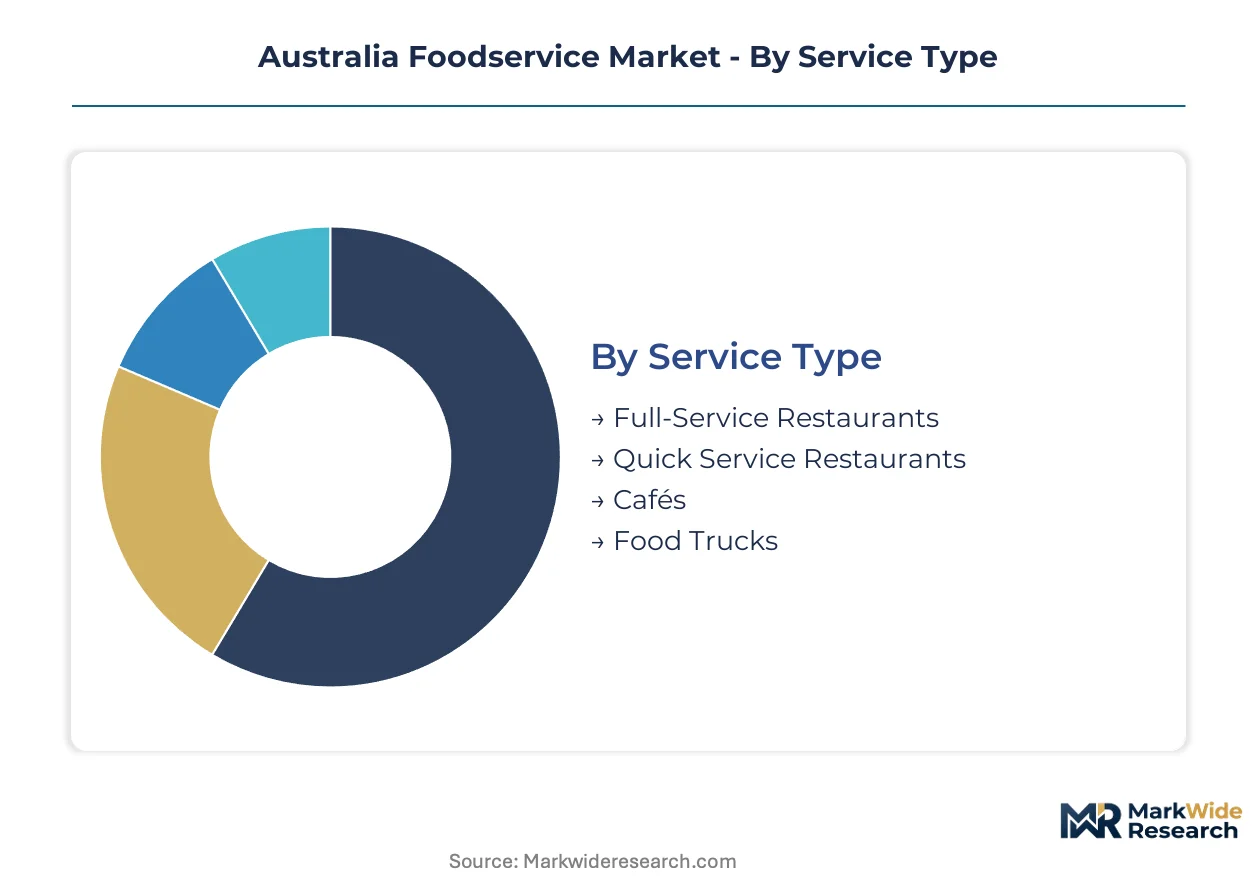
Australian foodservice operators calibrate format, menu, and channel strategies against distinct regulatory burdens and occasion-based demand clusters. Segmentation reveals where Food Standards Australia New Zealand compliance costs concentrate and where aggregator platforms restructure traditional service economics.
Service Type:
Food Standards Australia New Zealand allergen protocols apply differentially across preparation complexity tiers, elevating training overhead for live-cooking formats versus standardized assembly.
- Full-Service Restaurants:Table-service formats with wine programmes and premium protein menus command elevated average checks in Sydney and Melbourne dining precincts. Compliance documentation for complex supplier networks extends menu rollout timelines under Food Standards Australia New Zealand nutrition labelling mandates.
- Quick Service Restaurants:Limited-service labour models with standardized menus compress ticket times and simplify allergen traceability. Brisbane and Gold Coast corridors exhibit faster greenfield development velocity with lower site acquisition costs than saturated southern metros.
- Cafés:Beverage-forward daytime formats with pastry and light meal offerings capture suburban work-from-home clusters.
- Food Trucks:Mobile permits and event-based scheduling models concentrate at festivals and office park rotations.
Established volume favors Quick Service Restaurants; emerging adoption favors Food Trucks.
Menu Type:
Cost tier differentiation separates verified supply chain investments from commodity positioning.
- Vegetarian:Plant-protein menus with established supplier certification command premium positioning in metropolitan cores. Health-conscious consumers in Sydney CBD and Melbourne Docklands prioritize speed-compatible meat-free options during compressed lunch windows.
- Vegan:Elimination of all animal-derived inputs requires dedicated preparation zones and cross-contamination protocols that elevate kitchen capital requirements.
- Gluten-Free:Coeliac-safe preparation with segregated equipment addresses diagnosed dietary requirements under strict Food Standards Australia New Zealand declaration rules.
- Organic:Third-party certified ingredient sourcing creates barrier against unverified import competition.
Margin concentration sits with Gluten-Free; steepest expansion trajectory belongs to Vegan.
Customer Type:
Occasion-based demand clusters map directly to channel infrastructure requirements and location strategy.
- Families:Group-sized portions and child-friendly environments concentrate in suburban food courts and drive-through nodes. Weekend occasion migration toward experience-oriented dining sustains full-service demand in Brisbane growth corridors.
- Business Professionals:Compressed weekday lunch windows favor speed-optimized formats with digital ordering integration in Sydney and Melbourne business districts.
- Students:Price-sensitive volume demand clusters near university precincts with delivery-first kitchen penetration.
- Tourists:Seasonal demand concentration at waterfront and cultural destination precincts elevates location premium requirements.
Frequency concentration favors Business Professionals; per-visit spend elevation favors Tourists.
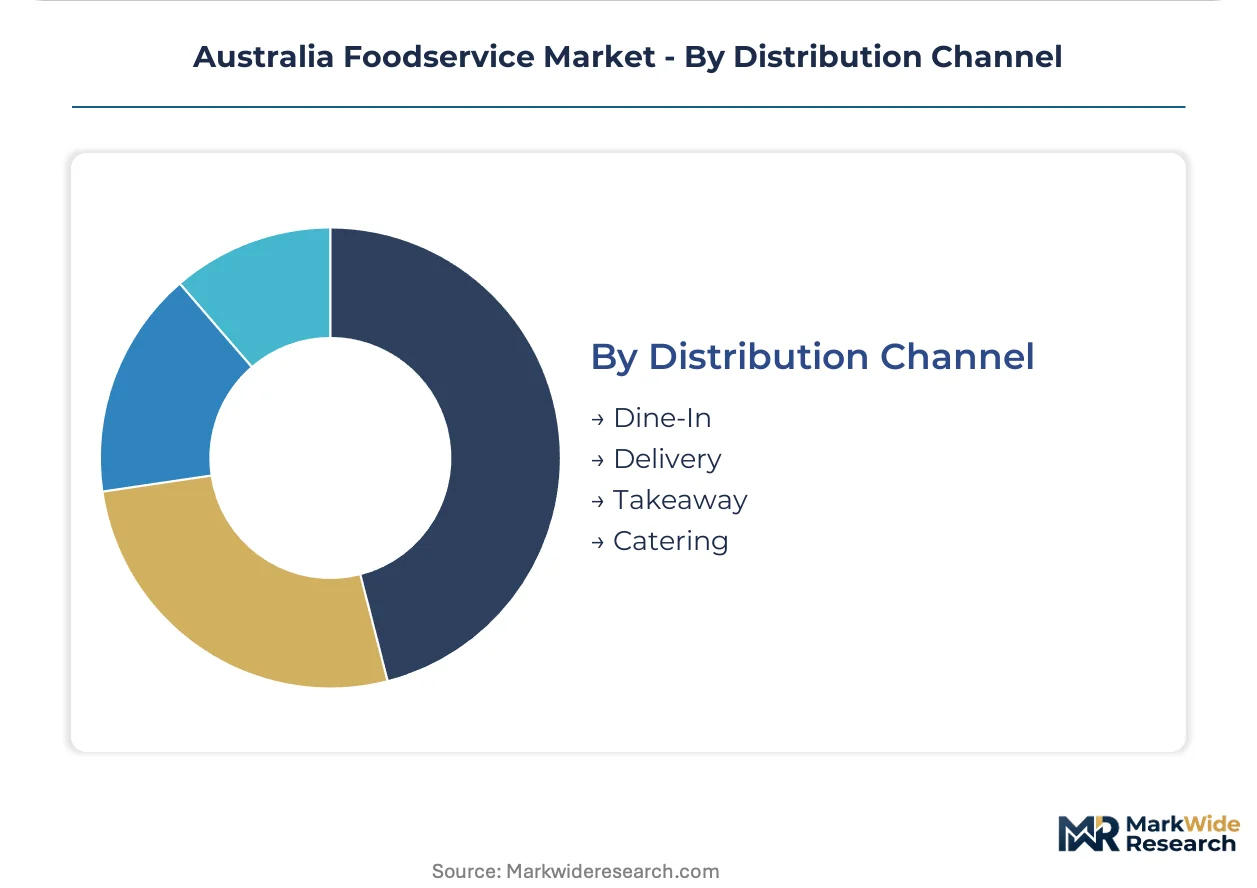
Distribution Channel:
Aggregator platform expansion is restructuring last-mile economics and real estate requirements across all formats.
- Dine-In:Experience-driven occasion formats with service labour models face permanent demand compression in CBD cores from hybrid work normalization.
- Delivery:Dark-kitchen layouts optimized for suburban density capture residential demand without location premium overhead. Machine learning demand forecasting enables dynamic menu pricing that static cost structures cannot match.
- Takeaway:Counter-service pickup formats bridge speed and cost optimization for commuter traffic patterns.
- Catering:Scheduled office meal programs and event contracts sustain corporate account structuring through Australian Taxation Office fringe benefits tax arrangements.
Asset efficiency favors Delivery; margin stability favors Catering.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Business professionals and suburban families dominate demand archetypes across Australian foodservice, with hybrid work patterns redistributing occasion concentration from CBD cores toward residential corridors. State-level regulatory variation and metropolitan density gradients shape format viability and site economics.
New South Wales
Sydney CBD lunch compression and Eastern Suburbs residential density sustain delivery-first kitchen proliferation. Food Standards Australia New Zealand allergen mandates elevate compliance costs for full-service operators in The Rocks and Surry Hills dining precincts. Western Sydney corridor expansion captures population migration with lower site acquisition costs than established eastern markets.
Victoria
Melbourne Docklands weekday traffic collapse and inner-north work-from-home clusters redirect demand toward Brunswick and Fitzroy suburban nodes. Australian Competition and Consumer Commission franchising disclosure requirements extend greenfield timelines across Greater Melbourne. Mornington Peninsula tourism concentration sustains seasonal premium dining despite metropolitan weekday softness.
Queensland
Brisbane and Gold Coast population inflows outpace southern metro saturation, supporting faster quick-service greenfield velocity. Australian Taxation Office fringe benefits tax structuring advantages corporate catering contracts in Fortitude Valley and South Brisbane office parks. Sunshine Coast corridor exhibits fastest food truck permit growth for event-based scheduling models.
Western Australia
Perth's geographic isolation sustains higher captive market pricing for established quick-service infrastructure. Mining sector fly-in-fly-out patterns concentrate institutional catering demand around airport-adjacent and resource corridor nodes. Fremantle waterfront tourism precinct maintains seasonal full-service demand distinct from metropolitan weekday patterns.
South Australia
Adelaide's lower commercial rent structure enables experimental format viability absent in Sydney or Melbourne cost environments. Barossa Valley and McLaren Vale wine tourism sustains destination dining with premium protein menus. Northern suburbs population growth supports drive-through infrastructure redeployment for commuter corridor capture.
Australia Foodservice Market Vendor Landscape
Player mix skews toward franchised quick-service networks with standardized supply chains and limited-service labor models. Scale advantages concentrate with national footprint operators capable of dark-kitchen deployment and aggregator platform integration. Three archetypes dominate: delivery-native formats with suburban density optimization, drive-through specialists leveraging commuter traffic patterns, and fresh-proposition brands with verified supply chain positioning. Competitive moves center on real estate redeployment toward vehicle-accessible formats and technology licensing for demand forecasting capability.
Among national quick-service operators, McDonald's Australia Limited, Domino's Pizza Enterprises Limited, and Guzman y Gomez occupy distinct strategic positions. McDonald's Australia Limited represents the drive-through infrastructure archetype with established suburban real estate adapted to compressed lunch windows. Domino's Pizza Enterprises Limited exemplifies delivery-first format optimization through kitchen layouts engineered for aggregator platform economics. Guzman y Gomez anchors the fresh-protein supply chain tier where made-to-order throughput supports premium positioning at quick-service speed.
| Leading Market Players |
|---|
| KFC |
| Craveable Brands |
| McDonald's Australia Limited |
| Guzman y Gomez |
| Yum! Brands, Inc. |
| Domino's Pizza Enterprises Limited |
| Competitive Foods Australia |
| Zambrero Pty Ltd |
| Subway |
| Others |
Supply Flow & Price Mechanics
Corporate catering contracts with Food Standards Australia New Zealand-mandated allergen compliance indexation lock in both protein supply access and menu pricing visibility for multi-year office meal programs across Sydney and Melbourne business districts.
Pricing Analysis
Cost-plus contracts with quarterly protein commodity indexation dominate corporate catering arrangements, insulating operators from livestock price volatility while passing through cold-chain logistics costs. Price differentiation hinges on Food Standards Australia New Zealand certification tier and suburban delivery radius compression. Cost compression in quick-service formats is intensifying because aggregator platform commission structures extract margin from suburban dark-kitchen operators. Students near university precincts exhibit highest price sensitivity; corporate accounts with Australian Taxation Office fringe benefits tax structuring show lowest sensitivity.
Supply Chain Analysis
Australia anchors beef and lamb protein production for domestic foodservice, while New Zealand supplies dairy and seafood inputs to cross-Tasman operators. Domestic produce sourcing draws from Queensland vegetable corridors and Victorian grain belts. Single-source vulnerability concentrates in imported specialty proteins facing biosecurity inspection delays. Distribution runs through national cold-chain networks with last-mile handoff to aggregator platform logistics or direct franchisee procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australian foodservice is recovering from pandemic-era occasion destruction as hybrid work normalization restores weekday corporate catering demand to cyclical highs.
For Market Incumbents: Consolidate drive-through real estate in Brisbane and Gold Coast corridors before site acquisition costs converge with southern metro levels. Lock in multi-year protein supply agreements with Queensland processors to preempt spot market exposure. Food Standards Australia New Zealand compliance investment creates defensive moats against unverified import competitors. For New Entrants and Emerging Players: Differentiate on fresh-protein supply chain transparency with made-to-order throughput at quick-service speed. Target Adelaide's lower commercial rent structure for experimental format viability absent in Sydney or Melbourne cost environments. Pursue dark-kitchen deployment in Western Sydney corridor expansion zones with direct aggregator platform API integration. For Investors and Strategic Acquirers: The market sits at a mid-cycle expansion phase that favors delivery-native formats with suburban density optimization and machine learning demand forecasting capability. Five-to-ten year viability rests on technology licensing for predictive inventory management rather than location-dependent dine-in assets. Watch for Food Standards Australia New Zealand enforcement actions against allergen non-compliance as inflection indicator for competitive shakeout.| Strategic Initiative | Industry Significance |
|---|---|
| Drive-Through Infrastructure Redeployment | McDonald's Australia Limited adapts suburban real estate to compressed lunch window commuter traffic patterns. |
| Dark-Kitchen Network Expansion | Domino's Pizza Enterprises Limited optimizes kitchen layouts for aggregator platform economics in secondary suburbs. |
| Fresh-Protein Supply Chain Verification | Guzman y Gomez commands premium positioning through made-to-order throughput at quick-service speed. |
| Machine Learning Demand Forecasting | Mid-size chains deploy predictive models to reduce spoilage penalties during demand volatility windows. |
| Food Standards Australia New Zealand Compliance Investment | Verified clean-label positioning creates barrier against unverified import competition in premium tiers. |
Methodological Framework
Desk research of Australian Bureau of Statistics foodservice turnover data, Food Standards Australia New Zealand regulatory filings, and Australian Competition and Consumer Commission franchising disclosure records preceded structured interviews with quick-service franchise operations directors, corporate catering procurement managers, aggregator platform supply chain leads, and Food Standards Australia New Zealand compliance officers. Bottom-up site-level revenue modeling triangulated against top-down state-level foodservice expenditure benchmarks.
Variance decomposition across service type, menu category, customer archetype, and distribution channel dimensions shaped analytical framework construction over the projection horizon. CAGRs derived from logistic adoption curve fitting against historical format penetration patterns. Forecast inputs incorporated hybrid work normalization velocity, Queensland population migration trajectories, and potential gig-economy delivery worker reclassification rulings.
Decision-makers should treat outputs as directional under sustained hybrid work patterns and stable Food Standards Australia New Zealand regulatory calibration; material deviation in employment tribunal precedents or protein commodity shocks would warrant model refresh. Recalibration cycles align with material shifts in aggregator platform commission structures and state-level franchising disclosure amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Aquarium Protein Skimmers Market
Food Service
United States Online Food Delivery Market
Food Service
Commercial Air Fryer Oven Market
Food Service
Commercial Deep Fryer Parts and Accessories Market
Food Service
United Kingdom Full Service Restaurants Market
Food Service
Europe Online Grocery Market
Food Service
Europe Airline Catering Services Market
Food Service
Catering Food Warmers Market
Food Service
Commercial Rice Cooker Market
Food Service
Workplace Service Market
Food Service
Saudi Arabia Inflight Catering Market
Food Service
Fast Food and Quick Service Restaurant Market
Food Service
Saudi Arabia Out of Home (OOH) Delivery Market
Food Service
US Food Service Market
Food Service
Galley Equipment Market
Food Service
Commercial Grills Market