
 Philippines Quick Service Restaurants Market | 2026-2036
Philippines Quick Service Restaurants Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Quick Service Restaurants Market Insights
Cloud-native kitchen management systems is reconfiguring how QSR chains orchestrate supply, labor, and customer data across dispersed store networks. Jollibee Foods Corporation leverages its vertically integrated commissary network to sustain cost discipline and menu consistency at scale. McDonald's anchors its Philippine footprint through real estate control and drive-thru infrastructure density. KFC differentiates via localized flavor pipelines and regional poultry sourcing partnerships.
Quick service restaurants are foodservice establishments engineered for speed, standardization, and repeatability, typically achieving order-to-handoff cycles under five minutes through modular kitchen layouts, pre-portioned ingredients, and scripted crew protocols. Their commercial purpose centers on capturing high-frequency, low-involvement meal occasions across dense urban populations. Fried chicken and burger categories dominate volume throughput due to cultural preference alignment and supply chain maturation, while delivery service models command expanding margin pools as aggregator commissions reshape unit economics. International chains and franchise outlets absorb disproportionate capital allocation, though local brands occupy defensive positions in provincial markets where heritage resonance outperforms global recognition.
The Philippine Food and Drug Administration enforces Hazard Analysis Critical Control Point standards across commissary and store-level operations, while the Department of Trade and Industry administers franchise disclosure rules that govern chain expansion transparency. Local government units layer business permit and sanitary clearance requirements that vary across city jurisdictions, creating compliance fragmentation that favors operators with dedicated regulatory affairs capacity. Stakeholders must weigh whether to build captive delivery logistics or accept aggregator dependency as the primary channel for customer acquisition.
Market Dynamics
Cloud-native kitchen management systems are compressing order-to-handoff cycles and reconfiguring labor deployment across Philippine QSR networks. These platforms integrate supply forecasting, crew scheduling, and customer analytics into unified command layers that franchise operators now treat as essential infrastructure.
Growth Catalysts
- Working Professional Demand:Dense office corridors in Metro Manila and Cebu City generate predictable high-frequency meal occasions that reward standardized speed and proximity.
- Food Safety Modernization:The Philippine Food and Drug Administration's HACCP enforcement agenda pushes chains toward centralized commissary investments that advantage scaled operators.
- Aggregator Channel Maturation:Delivery platform penetration into provincial cities extends addressable market reach without requiring greenfield store construction.
Market Restraints
- Poultry Input Volatility:Regional avian health events and feed grain price swings compress margin predictability for fried chicken specialists dependent on domestic broiler supply.
- Real Estate Concentration:Prime Metro Manila retail space scarcity elevates lease escalation risk and caps expansion velocity for drive-thru formats requiring corner visibility.
- Sanitary Clearance Fragmentation:Local government unit permit variations across city jurisdictions create compliance drag that fragments rollout timelines.
Strategic Opportunities
- Mindanao Underpenetration:Davao and Cagayan de Oro corridors offer first-mover positioning where local heritage brands retain stronger defensive moats than in Luzon.
- Cloud Kitchen Convergence:Ghost kitchen infrastructure combined with aggregator logistics enables asset-light market testing without full-service buildout.
- Provincial Franchise Disclosure:Department of Trade and Industry transparency mandates lower information asymmetry for multi-unit investors evaluating secondary city expansion.
Industry Challenges
- Kitchen Display System Integration:Legacy point-of-sale architectures resist seamless API connection to modern order management platforms, forcing middleware investments.
- Crew Retention Velocity:High-turnover service labor markets demand continuous training throughput that strains operational consistency across dispersed store networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Quick Service Restaurants Market |
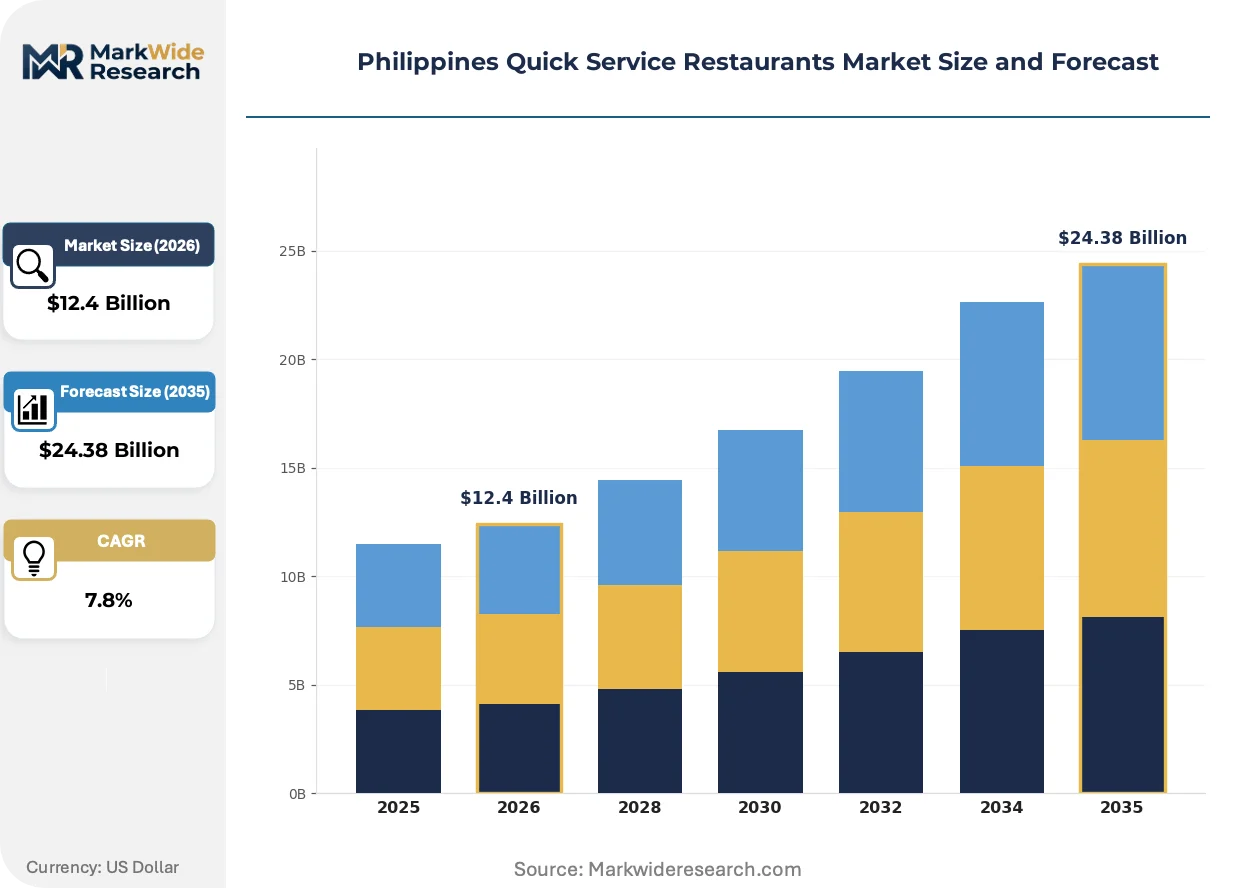
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $24.38 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Burgers, Pizza, Sandwiches, Fried Chicken Service Model: Dine-in, Drive-thru, Delivery, Takeaway Customer Type: Families, Students, Working Professionals, Travelers Brand Type: International Chains, Local Brands, Franchise Outlets, Standalone |
| Companies Covered | Jollibee Foods Corporation, McDonald's, KFC, Chowking, Mang Inasal, Shakey's Pizza Asia Ventures Inc., Pizza Hut, Burger King, Greenwich, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Quick Service Restaurants Market Trends and Innovations
Kitchen automation and regulatory digitization are converging to reshape how Philippine QSR chains orchestrate production, compliance, and customer acquisition. Three forces now dominate strategic planning.
Computer vision-based quality assurance systems are rendering obsolete manual spot-checks for product consistency and food safety documentation. Jollibee Foods Corporation and McDonald's Philippines are piloting camera arrays that monitor fryer oil degradation and holding-temperature compliance in real time. These installations compress audit labor while generating timestamped evidence trails that satisfy Philippine Food and Drug Administration inspection protocols.
The Philippine Food and Drug Administration's accelerating HACCP digitization mandate is forcing commissary operators toward blockchain-traceable ingredient logging. Large chains must now maintain electronic records linking batch codes to supplier certificates of analysis. Mid-tier franchise groups lacking dedicated regulatory technology capacity face compliance timeline compression that favors outsourced food safety auditing services.
Working professionals in Metro Manila are consolidating meal occasions around subscription-based daily value programs that displace à la carte ordering. Chains now bundle breakfast-lunch-dinner credits through mobile apps that lock in frequency while capturing payment float. This procurement consolidation is most visible in Makati and Bonifacio Global City corridors where office density supports predictable redemption velocity.
Philippines Quick Service Restaurants Market Segmentation
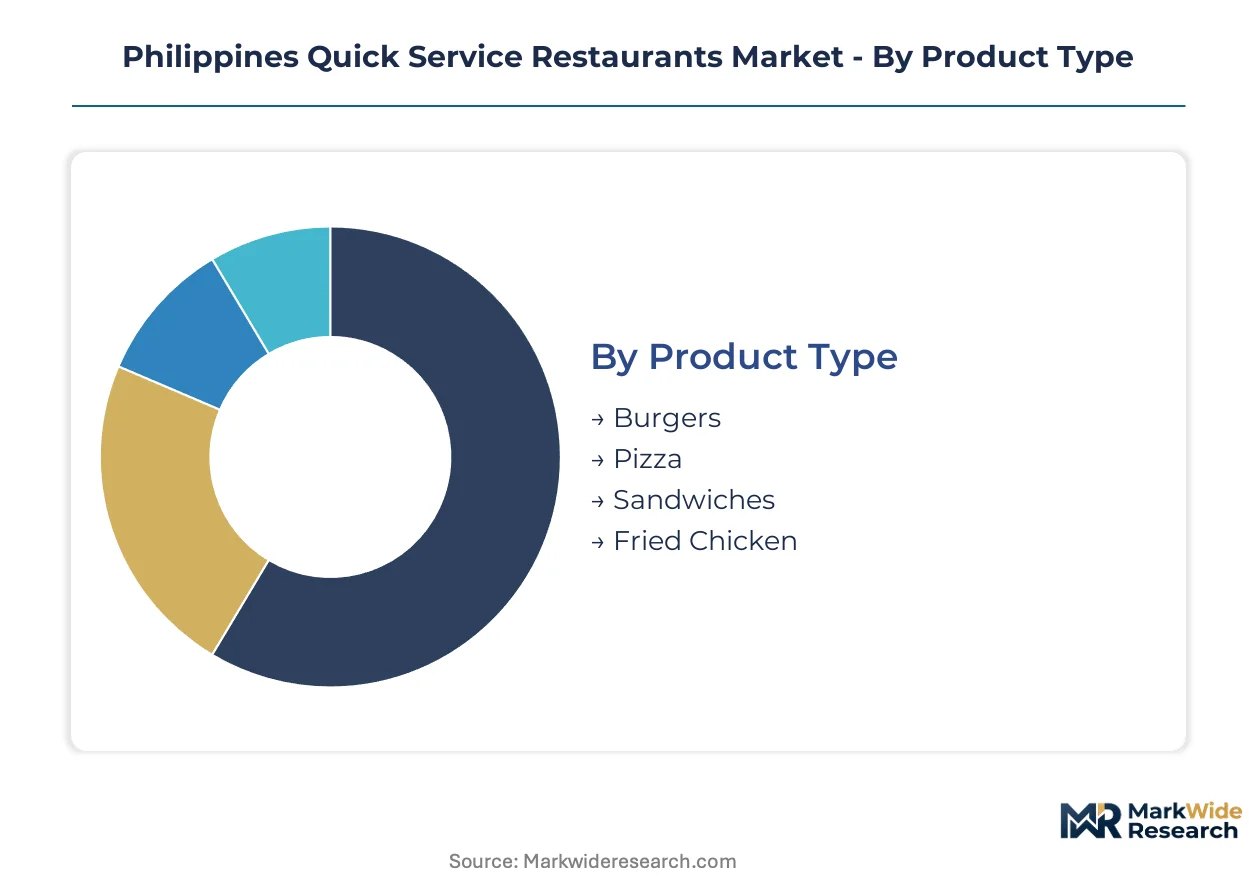
Segmentation in the Philippine QSR market reveals how consumption patterns fragment across product formats, service channels, and customer microsegments. These divisions determine capital allocation priorities and operational architecture choices for chain operators.
Product Type:
Cost tier differentiation separates mass-market staples from premium-positioned alternatives, with protein format and preparation complexity driving margin structure.
- Fried Chicken:Dominates volume throughput through standardized pressure-frying equipment and localized flavor pipelines. Working professionals in Metro Manila and Cebu City drive repeat purchase frequency during lunch corridors, though avian health events compress margin predictability.
- Burgers:Ground beef and chicken patty variants anchor value-meal engineering with modular assembly lines. Demand concentrates in drive-thru formats along EDSA and South Luzon Expressway corridors where speed-to-handoff determines market share capture.
- Pizza:Oven-intensive production requires dedicated kitchen footprints and longer order cycles. Provincial expansion faces cold-chain constraints for cheese and topping freshness.
- Sandwiches:Breakfast and snack-positioned formats with lower equipment barriers. Local bakery partnerships in Davao and Cagayan de Oro enable rapid menu localization.
Fried Chicken holds installed capacity. Burgers is rotating up the share rankings.
Service Model:
Application context determines real estate requirements and labor deployment patterns, with channel mix reshaping unit economics across urban density gradients.
- Delivery:Aggregator-dependent logistics extend addressable reach without greenfield construction. Cloud kitchen convergence in Metro Manila enables asset-light market testing.
- Drive-thru:Corner-visibility real estate commands lease premiums but captures high-frequency commuter occasions. EDSA corridor scarcity caps expansion velocity.
- Dine-in:Family and student segments sustain longer dwell times with higher ticket averages. Mall-anchored locations in Bonifacio Global City balance rent burdens with foot traffic guarantees.
- Takeaway:Minimal footprint format suited to transport hubs and hospital districts. Packaging standardization challenges multiply across humid climate conditions.
Delivery holds installed capacity. Drive-thru is climbing the fastest as infrastructure investment priorities shift.
Customer Type:
Volume concentration patterns align with daypart density and payment behavior, shaping loyalty program architecture and promotional cadence.
- Working Professionals:Subscription-based daily value programs in Makati and Bonifacio Global City lock in frequency through mobile app credits. Predictable redemption velocity supports inventory planning.
- Families:Weekend and holiday clustering drives party-size bundle engineering. Provincial markets show stronger heritage brand preference than global chain recognition.
- Students:Price-elastic demand concentrates near university districts in Quezon City and Cebu. Limited-service formats with counter-only ordering match budget constraints.
- Travelers:Transport hub and airport positioning requires extended operating hours. Menu localization demands exceed standard franchise specifications.
Working Professionals holds installed capacity. Families is gaining share fastest in provincial corridor expansion.
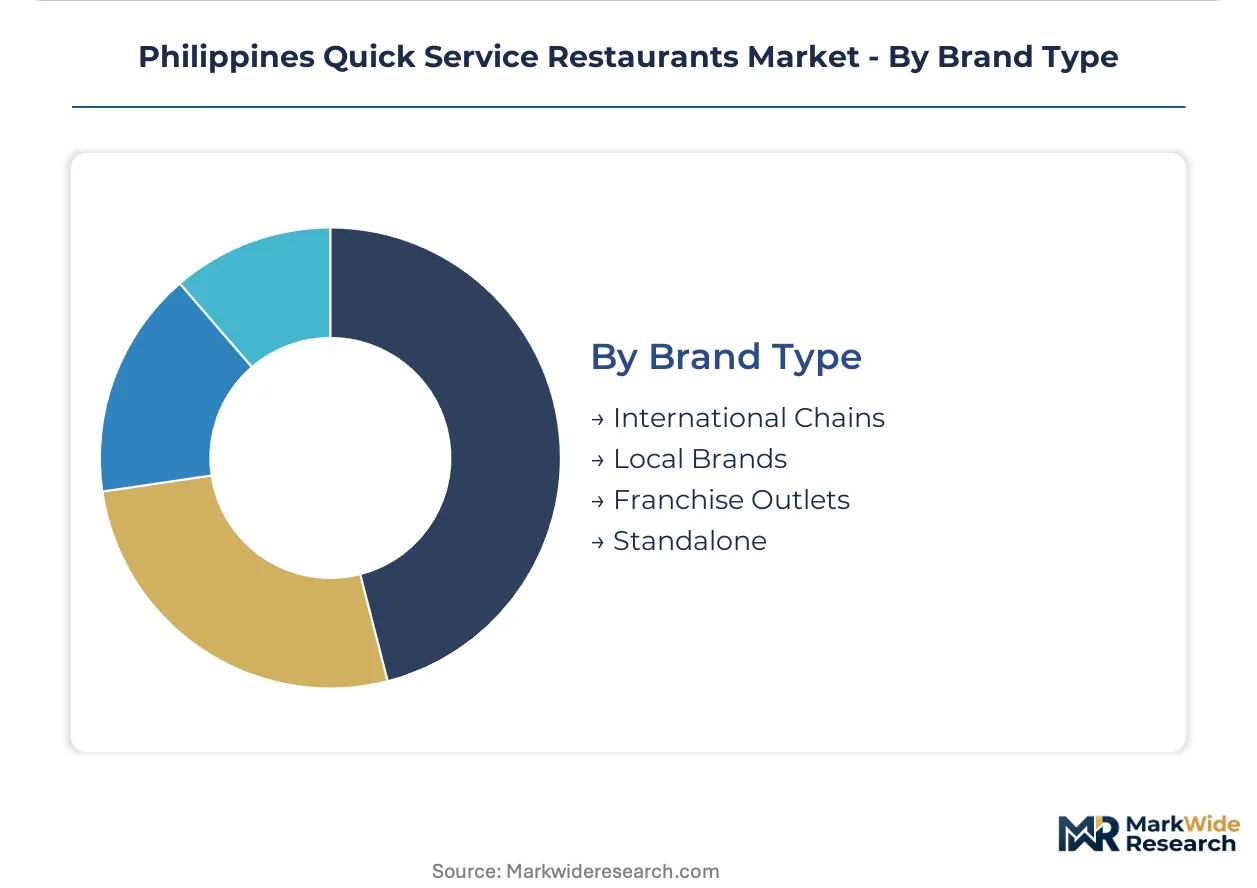
Brand Type:
Maturity and supply concentration separate scaled commissary operators from fragmented independents, with regulatory capacity determining compliance survival.
- International Chains:Real estate control and drive-thru density anchor market presence. HACCP digitization mandates favor dedicated regulatory technology investments.
- Local Brands:Heritage resonance outperforms global recognition in Mindanao and Visayas markets. Vertically integrated commissary networks sustain cost discipline.
- Franchise Outlets:Department of Trade and Industry disclosure rules lower information asymmetry for multi-unit investors. Rollout timelines fragment across local government unit permit variations.
- Standalone:Independent operators lack centralized food safety auditing capacity. Sanitary clearance compliance drag favors exit or acquisition by scaled groups.
International Chains holds installed capacity. Local Brands is rotating up the share rankings through Mindanao penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Philippines Quick Service Restaurants Market channels investment through Metro Manila into secondary urban corridors, with trade flows linking Luzon production centers to Visayas and Mindanao consumption clusters.
Metro Manila
Makati and Bonifacio Global City office densities generate concentrated working professional demand during lunch dayparts. The Philippine Food and Drug Administration's HACCP digitization mandates push commissary operators toward electronic batch tracing. Quezon City university districts sustain student-segment volume through counter-service formats.
Central Luzon
Industrial corridor expansion around Clark and Subic anchors logistics infrastructure for supply chain consolidation. The Department of Trade and Industry franchise disclosure rules lower entry barriers for multi-unit investors. Pampanga and Bulacan host processing facilities that feed Metro Manila store networks.
Visayas
Cebu City's office and tourism concentrations blend working professional and traveler demand segments. Local government unit sanitary clearance requirements vary across city jurisdictions, creating compliance fragmentation. Mactan and Iloilo corridors show growing drive-thru format penetration along expressway access points.
Mindanao
Davao and Cagayan de Oro present underpenetrated expansion corridors where local heritage brands retain defensive positioning. Regional poultry sourcing partnerships face avian health event risks that compress margin predictability. Zamboanga and General Santos show aggregator channel maturation extending reach without greenfield construction.
Southern Tagalog
Batangas and Laguna industrial zones generate manufacturing workforce demand for standardized speed and proximity. The Philippine Food and Drug Administration's food safety modernization agenda shapes operational compliance for commissary networks. Cavite corridor real estate scarcity elevates lease escalation risk for drive-thru formats.
Philippines Quick Service Restaurants Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure that concentrates around vertically integrated commissary operators and international franchise networks. Consolidation pressures favor scaled groups with dedicated regulatory affairs capacity. Two strategic archetypes dominate: heritage-rooted local brands with provincial defensive moats, and global chains with real estate control and drive-thru density. Competitive moves center on cloud kitchen convergence for asset-light testing and aggregator logistics partnerships for provincial reach extension.
Within the heritage-rooted local tier, Jollibee Foods Corporation and Chowking exemplify vertically integrated commissary operators that sustain cost discipline through captive supply networks. Among global franchise anchors, McDonald's occupies a position defined by real estate control and drive-thru infrastructure density. These three companies represent the spectrum from domestic heritage resonance to international format standardization, with each archetype commanding distinct advantages across Metro Manila density corridors versus provincial expansion zones.
| Leading Market Players |
|---|
| Jollibee Foods Corporation |
| McDonald's |
| KFC |
| Chowking |
| Mang Inasal |
| Shakey's Pizza Asia Ventures Inc. |
| Pizza Hut |
| Burger King |
| Greenwich |
| Others |
Pricing and Supply Chain Analysis
The North Luzon Expressway logistics corridor shapes cost dynamics that concentrate supply power among Metro Manila commissary operators while forcing downstream price differentiation between premium drive-thru formats and economy takeaway counters. Poultry feed grain movements through Subic and Clark anchor input cost volatility that chains must absorb or pass through menu engineering.
Pricing Analysis
Legacy point-of-sale infrastructure versus cloud-native kitchen management systems versus pilot-stage computer vision quality assurance creates a three-tier technology pricing structure across premium, standard, and economy levels. Chains with HACCP digitization investments command premium positioning through Philippine Food and Drug Administration audit readiness, while independent operators face margin compression from aggregator commission structures. Working professionals in Makati and Bonifacio Global City show lowest price sensitivity through subscription program lock-in, whereas students in Quezon City university districts drive aggressive value-meal competition.
Supply Chain Analysis
Tariff exposure between the Philippines and regional feed grain suppliers dominates supply chain risk planning for domestic broiler-dependent chains. Poultry production concentrates in Central Luzon processing zones, with equipment sourcing drawing from China and cold-chain packaging resting on Japanese supplier relationships. Regional avian health events represent the primary structural vulnerability, forcing inventory buffer strategies. Distribution runs through vertically integrated commissary networks controlled by scaled operators, with provincial reach extension increasingly dependent on aggregator logistics partnerships rather than captive delivery fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based daily value programs and aggregator channel management represent service-attach layers expanding faster than core food production, creating recurring revenue stability that hardware-centric store buildouts cannot match.
For Market Incumbents: Build regulatory technology moats through HACCP digitization investments that mid-tier franchise groups cannot replicate. Consolidate cloud kitchen infrastructure in Metro Manila to test formats before greenfield commitment. Defend against emerging ghost kitchen entrants by locking exclusive aggregator partnerships in provincial corridors. Deepen backward integration into poultry processing to buffer feed grain price swings. For New Entrants and Emerging Players: Pursue asset-light market entry through cloud kitchen convergence in Davao and Cagayan de Oro corridors where local heritage brand recognition exceeds global chain density. Target working professional subscription programs in secondary Visayas office districts with localized flavor pipelines. Leverage Department of Trade and Industry franchise disclosure transparency to attract multi-unit investors evaluating Mindanao expansion. For Investors and Strategic Acquirers: Mid-scale regional franchise groups with dedicated regulatory affairs capacity offer consolidation targets as sanitary clearance fragmentation drives exit pressure on standalone operators. Long-term viability hinges on commissary network control and aggregator channel independence. Watch for inflection signals in cloud-native kitchen management adoption rates across provincial store networks.| Strategic Initiative | Industry Significance |
|---|---|
| Commissary Network Consolidation | Captive poultry processing insulates Jollibee Foods Corporation from regional avian health margin shocks. |
| Cloud Kitchen Infrastructure Deployment | Ghost kitchen convergence enables McDonald's asset-light format testing without prime real estate commitment. |
| HACCP Digitization Investment | Electronic batch tracing satisfies Philippine Food and Drug Administration mandates while compressing audit labor. |
| Aggregator Logistics Partnership | Third-party delivery extension into Mindanao secondary cities bypasses greenfield construction timelines. |
| Subscription Program Engineering | Mobile app credit bundling locks working professional frequency in Makati and Bonifacio Global City corridors. |
Research Methodology
Operator-level perspectives from commissary operations directors, franchise development officers, aggregator platform account managers, and local government unit permit administrators anchored the qualitative base. These primary inputs combined with secondary validation from Philippine Food and Drug Administration enforcement bulletins, Department of Trade and Industry franchise disclosure filings, and customs import records for food processing equipment. Bottom-up store count modeling and top-down consumer expenditure triangulation cross-checked volume estimates.
Scenario-bracketing around poultry input volatility and aggregator commission structure evolution shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product format, service channel, customer microsegment, and brand archetype. CAGRs derived from trend extrapolation against historical expansion velocity, with forecast inputs incorporating working professional office density projections and HACCP compliance timeline compression.
Macroeconomic conditions sit as an overlay; deviation in peso-denominated feed grain costs or regional avian health event frequency would shift the trajectory. Forecasts reflect documented assumptions about cloud kitchen adoption curves and aggregator market concentration. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Vietnam Food Service Market
Food Service
Meal Voucher Market
Food Service
Pasteurized Eggs Market
Food Service
Food Service Utensils Market
Food Service
Commercial Restaurant Rangers Market
Food Service
United Kingdom Foodservice Market
Food Service
North America Food Service Market
Food Service
Mobile Food Services Market
Food Service
Onboard Rail Catering Market
Food Service
Global Online Food Ordering Market
Food Service
Aquarium Protein Skimmers Market
Food Service
Cambodia Foodservice Market
Food Service
Chained Consumer Foodservice Market
Food Service
Beverage Vending Machine Market
Food Service
Food and Grocery Retail Market
Food Service
Clear Ice Maker Market