
 Chinese Takeout Market | 2026-2036
Chinese Takeout Market Size, Share, and Industry Trends Forecast 2026-2036
Chinese Takeout Market Outlook
Multi-source ingredient procurement is broadening across the Chinese takeout sector as operators diversify beyond traditional Asian supply corridors. Panda Express leverages centralized commissary networks to sustain menu consistency at scale across North American locations. Din Tai Fung differentiates through handmade dumpling specialization that commands premium positioning in mall and airport formats. Yum China anchors mainland China operations with integrated digital ordering infrastructure and captive last-mile logistics.
Chinese takeout denotes prepared foodservice offerings derived from Cantonese, Sichuan, and regional Chinese culinary traditions, typically characterized by wok-based cooking at 650-900°F, soy and oyster sauce-based flavor profiles, and starch-forward plating with rice or wheat noodles as substrate. Rice dishes and noodles occupy mature volume positions with established production workflows, while dumplings represent the fastest-growing product type as freezer-to-fryer automation reduces labor intensity in ghost kitchen environments. Working professionals and families concentrate margin pools through higher average order values and subscription-based meal programs, whereas students drive frequency through budget-tier positioning on campus-adjacent delivery corridors.
The FDA Food Code governs interstate food safety standards for prepared Chinese dishes, while state health departments enforce HACCP compliance in commissary and ghost kitchen facilities. Local zoning boards and municipal regulators increasingly scrutinize third-party delivery aggregation platforms for traffic congestion and commercial kitchen fire safety in converted warehouse districts. Stakeholders must monitor evolving permitting frameworks for virtual brands and assess whether backward integration into sauce manufacturing and vegetable processing strengthens margin defense against commodity volatility.
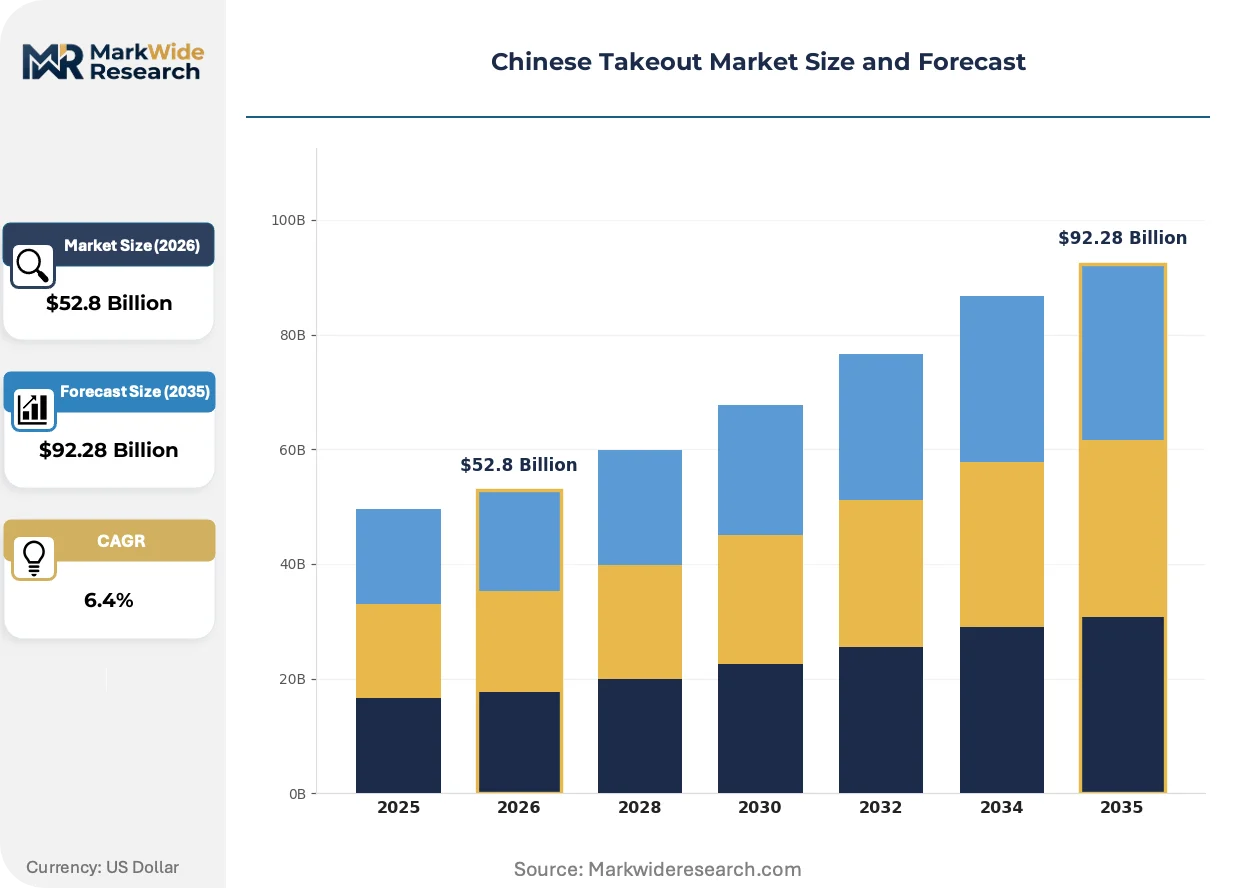
Market Dynamics
Ghost kitchen proliferation and third-party delivery platform consolidation are restructuring fixed-cost economics and customer acquisition pathways across the Chinese takeout sector, compressing traditional storefront viability while elevating virtual brand scalability.
Growth Catalysts
- Hybrid work normalization:Working professionals sustain elevated at-home lunch and dinner ordering frequency, expanding addressable demand beyond traditional office-district corridors.
- Freezer-to-fryer automation:Dumpling production robotics reduce labor intensity in commissary facilities, enabling unit economic viability for high-volume virtual brands.
- FDA Food Code harmonization:Updated interstate standards streamline multi-state operator compliance, reducing jurisdictional fragmentation for regional chains.
Market Restraints
- Soy sauce commodity volatility:Input cost swings in fermented soybean derivatives compress margin stability for sauce-dependent menu categories.
- Wok equipment supply concentration:High-BTU burner fabrication concentrates in Guangdong province foundries, exposing operators to overseas logistics disruption.
- Municipal fire code variance:Local regulators impose divergent ventilation and suppression standards on converted warehouse ghost kitchens, inflating permitting timelines.
Strategic Opportunities
- Subscription meal programs:Family-oriented weekly dinner bundles lock recurring revenue and reduce customer acquisition spend for established brands.
- Campus-adjacent micro-fulfillment:Student density corridors near state university systems offer underexploited frequency potential through budget-tier positioning.
- State-level ghost kitchen permitting:Early-adopter municipalities streamlining virtual brand licensing create first-mover advantages for compliant operators.
Industry Challenges
- Wok cooking skill scarcity:Traditional 650-900°F flame technique mastery is concentrating among aging specialist cohorts, constraining quality replication at scale.
- Third-party platform dependency:Delivery aggregator commission structures and algorithmic visibility allocation erode operator pricing autonomy and customer relationship ownership.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chinese Takeout Market |
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $92.28 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rice Dishes, Noodles, Dumplings, Stir-Fried Vegetables Customer Type: Students, Working Professionals, Families, Tourists Distribution Channel: Online Ordering, Food Delivery Apps, Walk-in, Drive-thru Price Tier: Budget, Mid-range, Premium, Gourmet |
| Companies Covered | Pick Up Stix, Din Tai Fung, Panda Express, Lao Sze Chuan, Asian Chao, Pei Wei Asian Kitchen, Manchu Wok, Yum China, P.F. Chang's, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chinese Takeout Market Strategic Shifts
Automation and regulatory adaptation are converging to reshape production economics and compliance architecture throughout the Chinese takeout value chain, with implications for labor deployment and facility configuration.
Robotic dumpling folding systems is overtaking manual production in high-volume commissary environments. Ghost kitchen operators deploying these systems achieve throughput consistency at labor costs below traditional hand-folding workflows. This compression is enabling virtual brand proliferation without commensurate headcount expansion.
State health departments are intensifying HACCP enforcement in commissary and ghost kitchen facilities, mandating documented critical control point monitoring across temperature, time, and cross-contamination vectors. Operators face elevated documentation burdens and inspection frequency. Smaller virtual brands lacking dedicated compliance personnel bear disproportionate adaptation costs.
Working professionals are consolidating ordering behavior around subscription-based family meal programs that replace daily à la carte decisions with pre-scheduled weekly deliveries. This shift displaces impulse-driven lunch orders with planned dinner occasions. Dense metropolitan corridors with high dual-income household density exhibit the fastest migration toward this model.
Chinese Takeout Market Segmentation
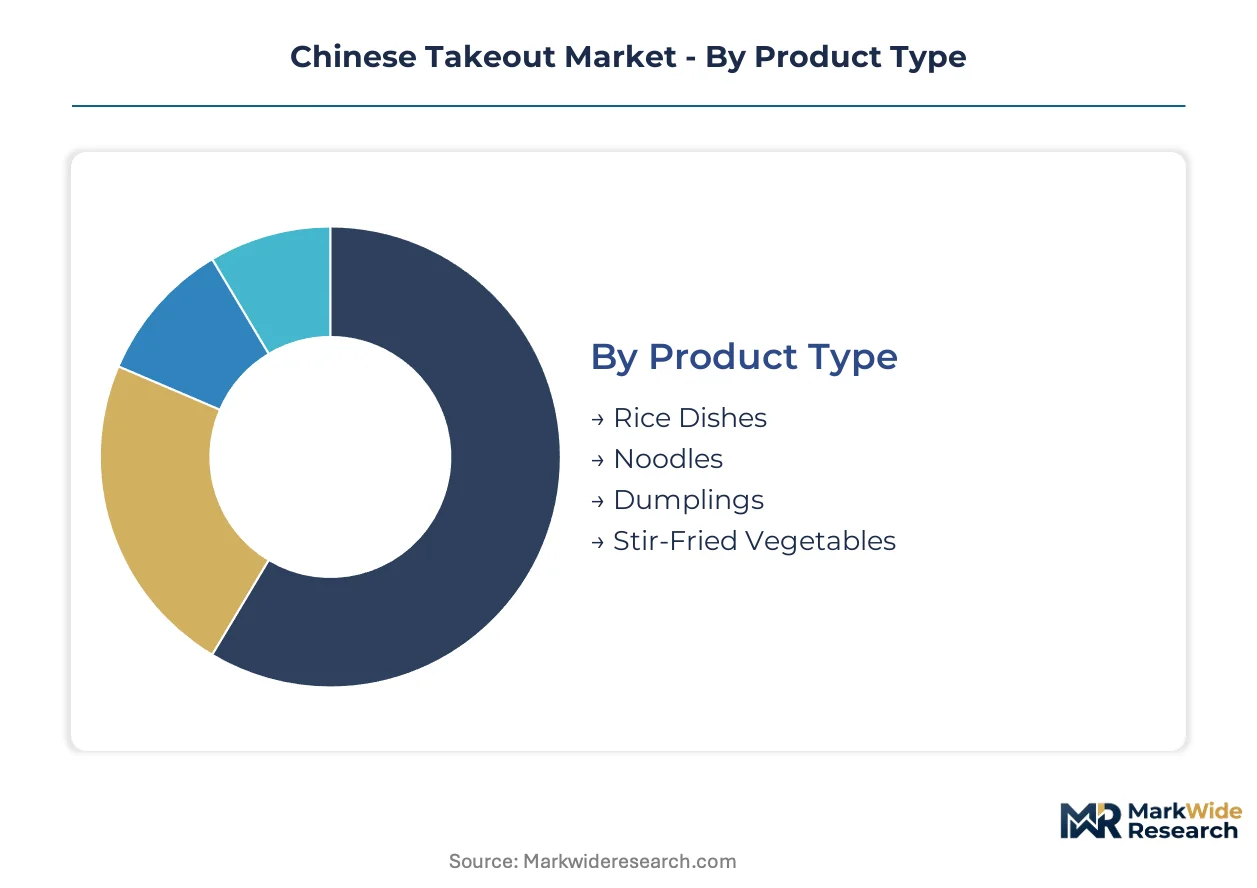
Segmentation in Chinese takeout reveals how production economics and consumption occasions fragment across distinct operational models. Understanding these divisions exposes where automation investments yield returns and which customer cohorts sustain premium pricing power.
Product Type:
Thermal intensity and labor input differentiate production workflows across menu categories, with wok-based methods at 650-900°F separating high-throughput from precision-crafted offerings.
- Rice Dishes:Soy and oyster sauce-based preparations over steamed jasmine or fried rice substrates dominate commissary output. Working professionals in dense metropolitan corridors sustain volume through combination plate efficiency and freezer-to-fryer protein integration.
- Dumplings:Hand-folded or robotically formed wheat skins encasing pork, shrimp, or vegetable fillings command premium positioning through perceived craftsmanship. Ghost kitchen automation is compressing labor costs and enabling virtual brand proliferation without commensurate headcount expansion.
- Noodles:Wheat or rice flour strands prepared through pull, cut, or extrusion methods anchor budget-tier positioning near university corridors.
- Stir-Fried Vegetables:High-heat wok blistering of bok choy, snow peas, and broccoli functions as margin-padding add-ons to protein-centric orders.
Rice dishes lead on scale; dumplings lead on momentum.
Customer Type:
Ordering frequency and average ticket size diverge sharply across life-stage and employment status, shaping loyalty program architecture and promotional cadence.
- Working Professionals:Hybrid work patterns have normalized at-home lunch and dinner ordering beyond traditional office-district corridors. Subscription-based weekly dinner bundles lock recurring revenue and reduce customer acquisition spend for operators capturing this cohort.
- Families:Multi-person households generate higher average order values through variety-seeking behavior and appetizer inclusion. Pre-scheduled delivery windows align with dual-income household coordination needs in suburban and exurban zones.
- Students:Campus-adjacent density corridors drive frequency through budget-tier positioning and late-night availability windows.
- Tourists:Airport and mall-adjacent formats capture impulse demand through visible dumpling production theater and recognized brand affiliation.
Families lead on scale; working professionals lead on momentum.
Distribution Channel:
Customer relationship ownership and margin retention vary dramatically by who controls the ordering interface and last-mile handoff.
- Online Ordering:Direct-to-consumer platforms capture first-party data and bypass aggregator commission structures. Established chains with brand recognition convert traffic most efficiently through proprietary apps.
- Food Delivery Apps:Third-party platforms concentrate demand discovery but erode pricing autonomy through algorithmic visibility allocation and fee compression. Ghost kitchen operators depend entirely on this channel for customer acquisition.
- Walk-in:Traditional storefronts sustain dine-in revenue and impulse add-on sales in high-foot-traffic urban corridors.
- Drive-thru:Limited adoption in Chinese takeout due to wok-cooked item temperature sensitivity and packaging complexity for sauced preparations.
Food delivery apps lead on scale; online ordering leads on momentum.
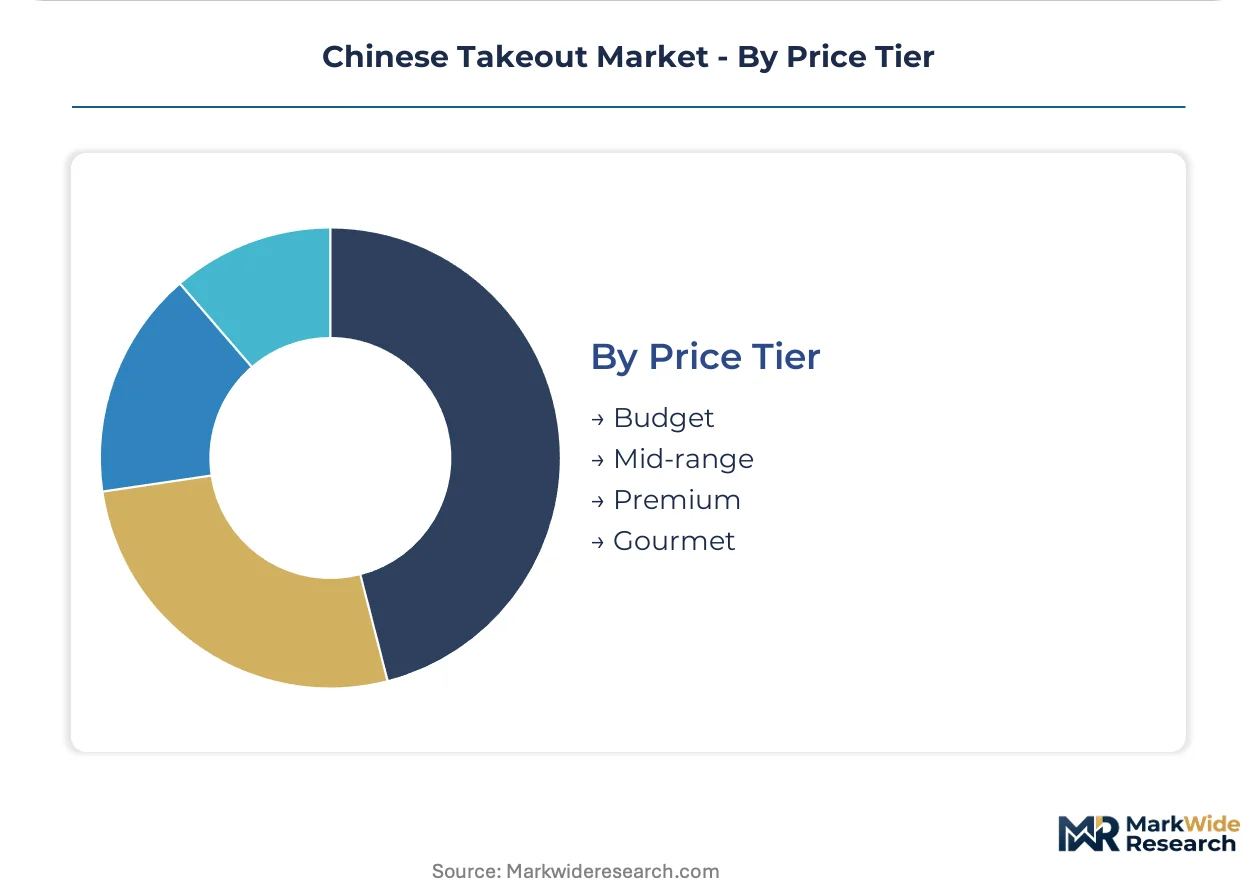
Price Tier:
Ingredient sourcing depth and labor intensity stratify positioning across accessible entry points to occasion-based splurge occasions.
- Mid-range:Commissary-produced proteins with standardized sauce profiles balance consistency and perceived value. This tier captures the bulk of working professional weeknight demand through predictable quality and portion reliability.
- Premium:Specified origin ingredients and visible preparation theater justify elevated pricing in mall and airport formats. Handmade dumpling specialization commands sustained price premiums through perceived authenticity.
- Budget:Campus-corridor operators compete on portion-per-dollar metrics with simplified menus and minimal service overhead.
- Gourmet:Limited regional cuisine specialization and chef-attributed recipes serve occasion-driven dining in destination locations.
Mid-range leads on scale; premium leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where Chinese takeout operators establish commissary and ghost kitchen infrastructure, with cost-of-compliance gaps between municipal fire codes and state health department regimes driving facility location decisions across North America and Asia-Pacific corridors.
United States
Hybrid work normalization in New York City, Los Angeles, and Chicago sustains elevated at-home ordering frequency beyond traditional office districts. The FDA Food Code governs interstate food safety standards for prepared Chinese dishes, while state health departments enforce HACCP compliance in commissary facilities. Municipal fire code variance in converted warehouse ghost kitchens inflates permitting timelines in dense metropolitan corridors.
Canada
Asian diaspora concentration in Toronto and Vancouver generates sustained demand for authentic regional cuisine formats. Health Canada and the Canadian Food Inspection Agency administer food safety protocols for prepared dishes, with provincial health authorities licensing commissary operations. Ghost kitchen proliferation in Greater Toronto Area industrial zones is compressing traditional storefront viability.
China
Integrated digital ordering infrastructure and captive last-mile logistics anchor mainland operations in tier-one cities. The State Administration for Market Regulation (SAMR) oversees food safety compliance, with local market regulators enforcing licensing for cloud kitchen facilities. Yangtze River Delta and Pearl River Delta clusters concentrate automated dumpling production robotics deployment.
United Kingdom
London's dense metropolitan corridor sustains premium positioning for visible preparation theater formats. The Food Standards Agency enforces hygiene ratings for takeout establishments, with local authority environmental health teams inspecting ghost kitchen conversions. Mall and airport-adjacent locations in Greater London capture impulse demand from business travelers.
Australia
Sydney and Melbourne's Asian diaspora populations support specialized regional cuisine offerings beyond standardized Cantonese formats. Food Standards Australia New Zealand (FSANZ) sets food safety standards, with state-level health departments licensing commercial kitchen operations. Inner-city warehouse conversions for delivery-only brands are accelerating in high-density corridors.
Chinese Takeout Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue virtual brand scalability through ghost kitchen infrastructure. The vendor base clusters around three maturity tiers: legacy chains with commissary networks, mall-format specialists emphasizing visible craftsmanship, and digital-native virtual brands leveraging third-party platform aggregation. Strategic moves concentrate on subscription program deployment and freezer-to-fryer automation investments that compress labor intensity.
Within the premium-craftsmanship tier, Din Tai Fung exemplifies handmade specialization that commands sustained price premiums in mall and airport formats. Panda Express anchors the scale-driven standardized tier with centralized commissary networks sustaining menu consistency across North American locations. Yum China occupies the integrated-digital tier, representing captive infrastructure control over ordering platforms and last-mile logistics in mainland operations.
| Leading Market Players |
|---|
| Pick Up Stix |
| Din Tai Fung |
| Panda Express |
| Lao Sze Chuan |
| Asian Chao |
| Pei Wei Asian Kitchen |
| Manchu Wok |
| Yum China |
| P.F. Chang's |
| Others |
Value Chain & Pricing Dynamics
Backward integration into sauce manufacturing anchors both supply security and margin defense for scaled Chinese takeout operators. Panda Express leverages centralized commissary networks to neutralize commodity swings in fermented soybean derivatives while sustaining pricing power through volume-tier contracts with protein suppliers.
Pricing Analysis
Aggregator commission structures compress operator pricing autonomy as third-party platforms capture 15-30% of transaction value. Three-tier pricing structure across premium, standard, and economy levels stratifies by preparation method and ingredient provenance, with handmade dumpling specialization commanding sustained premiums. Cost compression in the budget tier intensifies because campus-corridor operators compete on portion-per-dollar metrics. Students exhibit highest price sensitivity; families generating higher average order values show lowest sensitivity.
Supply Chain Analysis
Ocean freight volatility from Guangdong province foundries disrupts high-BTU wok equipment availability for North American ghost kitchen operators. Soy sauce fermentation concentrates in China and Japan; wheat flour milling for dumpling skins centers on domestic North American facilities. Single-source vulnerability in Guangdong burner fabrication exposes operators to overseas logistics disruption. Distribution runs through third-party delivery platforms for virtual brands, while established chains convert traffic through proprietary direct-ordering infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chinese takeout has matured into a late-cycle quality story as working professionals consolidate ordering behavior around subscription-based family meal programs with pre-scheduled weekly deliveries.
For Market Incumbents: Cement subscription program penetration through pre-scheduled delivery windows that lock recurring revenue and reduce customer acquisition spend. Defend against virtual brand erosion by investing in freezer-to-fryer automation that compresses labor intensity below commissary break-even thresholds for emerging entrants. Prioritize captive last-mile logistics over third-party platform dependency to reclaim customer relationship ownership.
For New Entrants and Emerging Players: Enter via campus-adjacent micro-fulfillment corridors near state university systems where budget-tier positioning and late-night availability windows exploit underexploited frequency potential. Target student density zones with simplified menus and minimal service overhead. Deploy ghost kitchen infrastructure in early-adopter municipalities streamlining virtual brand licensing to capture first-mover advantages.
For Investors and Strategic Acquirers: Consolidation pressure builds where municipal fire code variance inflates permitting timelines for converted warehouse ghost kitchens, advantaging compliant operators with established infrastructure. Long-term viability favors vertically integrated chains with backward integration into sauce manufacturing and vegetable processing. Monitor state-level ghost kitchen permitting frameworks as the signal for regulatory-arbitrage opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Freezer-to-Fryer Automation Deployment | Robotic dumpling folding reduces labor costs below hand-folding workflows in high-volume commissaries. |
| Subscription Meal Program Launch | Weekly dinner bundles lock recurring revenue from dual-income households in dense metropolitan corridors. |
| Captive Last-Mile Logistics Buildout | Proprietary delivery infrastructure bypasses aggregator commission structures and algorithmic visibility allocation. |
| State-Level Ghost Kitchen Permitting | Early compliance in streamlined municipalities creates defensive moats against delayed entrants. |
| Backward Integration into Sauce Manufacturing | In-house production of fermented soybean derivatives neutralizes commodity volatility in sauce-dependent categories. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to construct demand and supply estimates. Primary fieldwork captured perspectives from ghost kitchen operators, commissary facility managers, third-party delivery platform executives, municipal permitting officials, and supply chain procurement leads. Secondary validation drew from FDA Food Code updates, state health department HACCP enforcement records, municipal fire code variance documentation, and customs data on wok equipment imports. Bottom-up unit economics modeling triangulated against top-down market sizing across product type, customer segment, and distribution channel dimensions.
Segment-weighting approaches distributed value and volume across rice dishes, dumplings, noodles, and stir-fried vegetables, with further disaggregation by working professional, family, student, and tourist cohorts. CAGRs were derived from trend extrapolation moderated by saturation thresholds and regulatory constraint modeling. Forecast inputs incorporated hybrid work normalization patterns, freezer-to-fryer automation adoption curves, and state-level ghost kitchen permitting velocity.
Inputs from FDA enforcement records and state health department inspection databases were available through the study window; gaps in real-time ghost kitchen operator financial disclosures introduce uncertainty bands around virtual brand proliferation estimates. Forecasts reflect assumptions about sustained hybrid work patterns and automation cost curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Latin America Online Grocery Delivery Market
Food Service
Airport Quick Service Restaurants Market
Food Service
US Food Trucks Services Market
Food Service
Netherlands Food Service Market
Food Service
United States Full Service Restaurants Market
Food Service
Commercial Steam Table Market
Food Service
United States Online Food Delivery Market
Food Service
US Restaurant Point of Sale Solution Market
Food Service
Snack Subscription Box Service Market
Food Service
Commercial Charbroiler Market
Food Service
Takeout Dinner Market
Food Service
India Foodservice Market
Food Service
Commercial Griddle Market
Food Service
Pizza Oven Market
Food Service
Quick-Service Restaurants Market
Food Service
Commercial Rice Cooker Market