
 Cutting Boards Market | 2026-2036
Cutting Boards Market Size, Share, and Industry Trends Forecast 2026-2036
Cutting Boards Market Analysis
Market Overview
Aftermarket replacement cycles in commercial foodservice operations are reshaping volume flows across the cutting boards supply base. John Boos leverages its butcher-block heritage and American hardwood sourcing to anchor premium positioning in professional kitchens. Epicurean competes through proprietary paper-based composite technology that sustains dishwasher-safe durability claims. OXO differentiates via ergonomic grip engineering and broad retail channel control across North American mass merchants.
Product & Technology Landscape
Cutting boards are rigid food-preparation surfaces engineered from wood end-grain assemblies, bamboo lamination, high-density polyethylene, or tempered glass, with thickness typically ranging from 0.5 to 4 inches to absorb blade impact and protect knife edges. Wood and bamboo segments retain margin concentration in artisanal and sustainability-positioned channels, while plastic dominates volume through NSF-certified commercial procurement and healthcare kitchen compliance. Professional chef and catering end-user categories represent the fastest-growing demand pool as ghost kitchen expansion and centralized commissary operations multiply across urban foodservice clusters.
Regulatory Environment & Outlook
FDA food-contact notification requirements govern polymer migration limits in plastic cutting boards sold in the United States, while NSF International Standard 2 establishes equipment sanitation protocols for commercial kitchen certification. The EU REACH regulation restricts certain wood treatment chemicals in bamboo and hardwood imports entering European ports. Stakeholders must monitor evolving state-level plastic bans and compostability mandates that are fragmenting material approval pathways across jurisdictions.
Market Dynamics
Commercial foodservice operators are compressing replacement cycles for cutting surfaces as ghost kitchen proliferation and centralized commissary operations multiply across urban corridors, forcing suppliers to recalibrate inventory velocity and material certification pipelines.
Growth Catalysts
- FDA Food-Contact Notification:Polymer migration limits for polyethylene boards are tightening material specifications, accelerating NSF-certified procurement in hospital and school kitchens across the United States.
- Ghost Kitchen Infrastructure:Delivery-optimized commissaries in Texas and California corridors are generating concentrated demand for high-durability polyethylene and composite surfaces rated for industrial dishwasher cycles.
- End-Grain Hardwood Assemblies:Professional chef preferences for blade-preserving surfaces are sustaining artisanal wood segment margins despite longer replacement intervals.
Market Restraints
- Hardwood Input Volatility:American black walnut and maple price swings are compressing margins for butcher-block manufacturers dependent on domestic sustainable forestry certification.
- EU REACH Chemical Restrictions:Wood treatment compound limitations at European ports are fragmenting import approval pathways for bamboo and tropical hardwood laminates.
- Tempered Glass Substitution:Non-porous glass surfaces are capturing hygiene-sensitive healthcare segments despite inferior knife-edge preservation characteristics.
Strategic Opportunities
- Compostability Mandates:California and New York state-level single-use plastic bans are creating regulatory tailwinds for paper-based composite and bamboo fiber alternatives with certified biodegradability pathways.
- Centralized Procurement Platforms:Broadline foodservice distributors are consolidating vendor selection, creating channel consolidation opportunities for NSF-certified suppliers with national logistics coverage.
- Ergonomic Grip Engineering:Integration of thermoplastic elastomer handles with high-density polyethylene cores is opening differentiation space in institutional procurement specifications.
Industry Challenges
- NSF Standard 2 Certification Timelines:Commercial kitchen equipment sanitation protocols require 90-120 day laboratory validation cycles, delaying new material introductions.
- Cross-Contamination Training Gaps:Color-coded HACCP systems depend on consistent frontline implementation that institutional buyers struggle to enforce across multi-site operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cutting Boards Market |
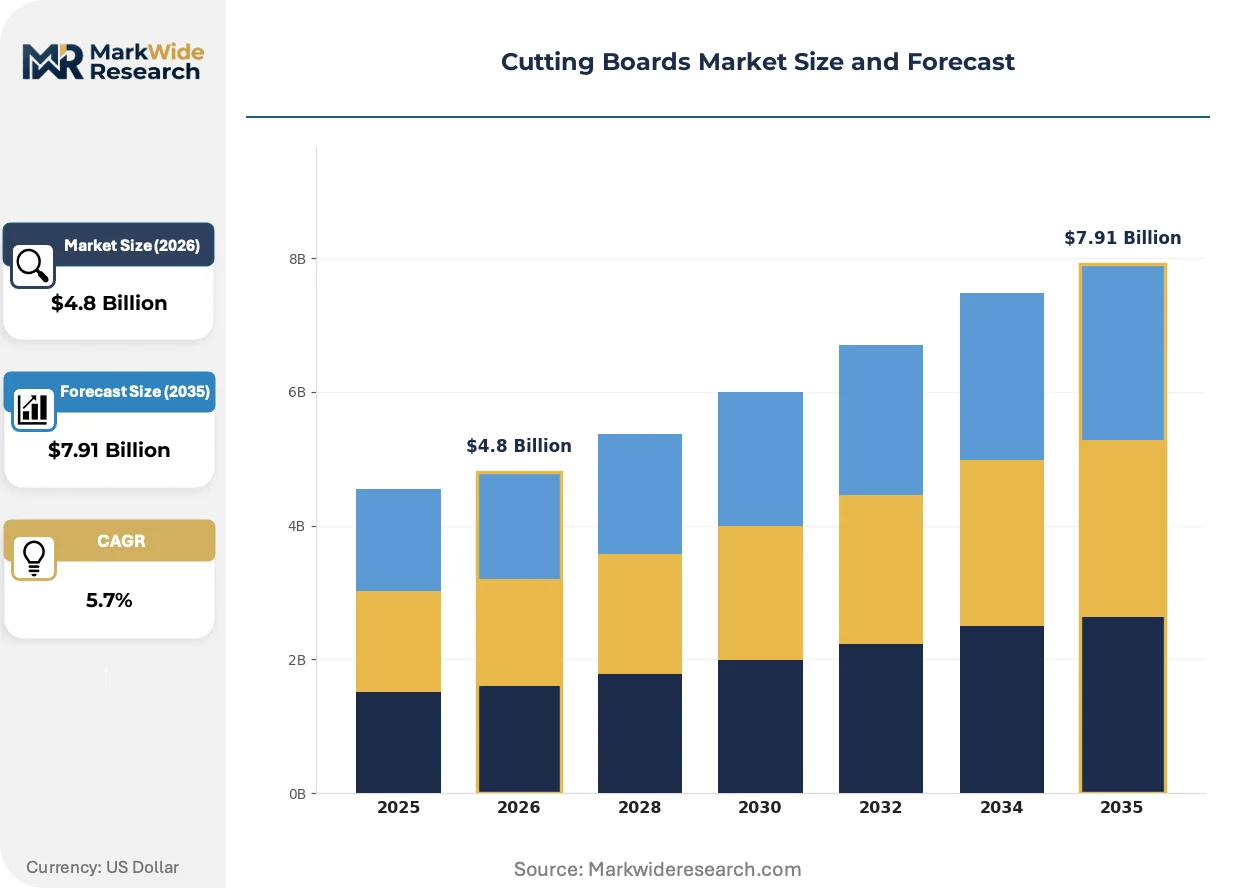
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Wood, Bamboo, Plastic, Glass Shape: Rectangular, Round, Square, Oval Size: Small, Medium, Large, Extra Large End User: Household, Commercial, Professional Chefs, Catering Services |
| Companies Covered | Sonder LA, Epicurean, John Boos, Tupperware, OXO, Grizzly Blocks, Ironwood Gourmet, Bamboo Classic Board, SoulFino, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cutting Boards Market Emerging Trajectories
Material science advances and regulatory fragmentation are converging to reshape competitive positioning across wood, polymer, and composite cutting surface categories. Suppliers must now engineer for divergent certification requirements while maintaining cost structures viable for both retail and institutional channels.
Antimicrobial additive integration into high-density polyethylene substrates is rendering obsolete untreated plastic boards in healthcare and commercial foodservice procurement specifications. Hospital cafeterias and nursing facility kitchens in the United States are mandating silver-ion or triclosan-embedded surfaces in new equipment contracts. This technology compression is forcing legacy polyethylene extruders to reformulate compounds or exit medical-adjacent segments entirely.
EU REACH Annex XVII restrictions on formaldehyde-releasing agents in bamboo lamination adhesives are triggering supply chain reconfigurations for Asian manufacturers serving European ports. German and French import inspectors are rejecting shipments with non-compliant phenol-resin bonding layers. European distributors are pivoting toward European-sourced beechwood alternatives or paper-based composites with certified adhesive systems.
Chef-owned independent restaurants are unbundling after-sales service expectations from cutting board procurement, treating surfaces as disposable consumables rather than capital equipment. This behavioral shift favors lower-unit-cost polyethylene and bamboo options over premium end-grain hardwood assemblies in metropolitan culinary corridors. Brooklyn and Austin operator clusters exemplify this velocity-over-longevity preference pattern.
Cutting Boards Market Segmentation
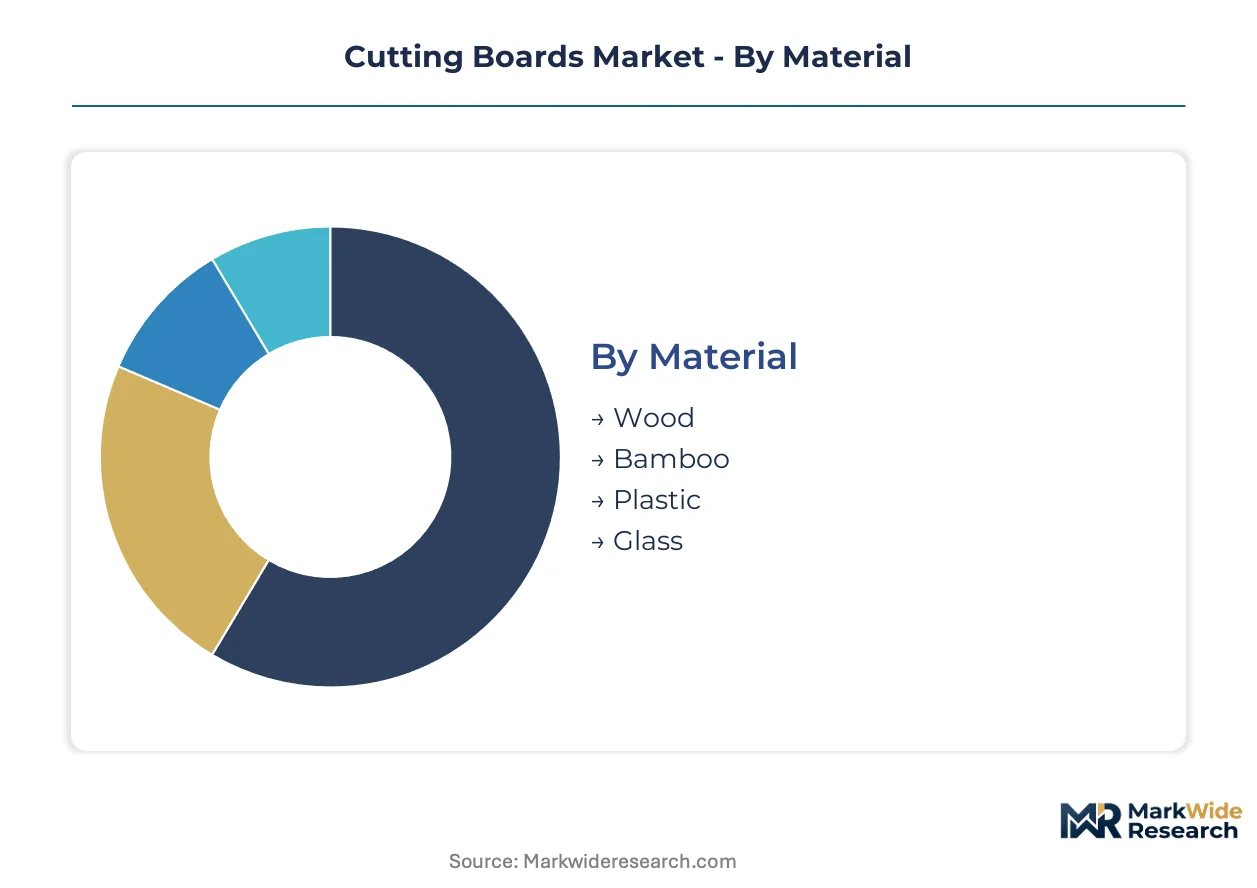
Material composition dictates certification pathways and replacement economics across cutting board procurement channels. Shape and size specifications diverge sharply between institutional foodservice contracts and retail consumer preferences. End-user category determines durability requirements and price elasticity thresholds.
Material:
Mature extrusion technologies dominate volume production while emerging composite formulations capture sustainability premiums.
- Wood:End-grain maple and black walnut assemblies absorb blade impact through cellular fiber orientation. Professional kitchens in Texas and California corridors specify NSF-certified hardwood for blade preservation despite longer replacement cycles.
- Plastic:High-density polyethylene substrates integrate silver-ion antimicrobial additives for healthcare compliance. Hospital and school cafeterias across the United States mandate FDA food-contact certified polymer surfaces rated for industrial dishwasher cycles.
- Bamboo:Laminated grass-fiber composites offer rapid-renewable positioning for sustainability-oriented procurement.
- Glass:Tempered silica surfaces serve hygiene-critical healthcare segments despite inferior knife-edge preservation characteristics.
Plastic retains volume leadership; bamboo holds the steepest expansion curve.
Shape:
Geometric specifications align with workspace constraints and storage efficiency requirements across deployment environments.
- Rectangular:Linear edge geometry maximizes usable cutting surface per linear foot of counter space. Ghost kitchen commissaries in urban corridors specify standardized rectangular formats for modular workstation configuration.
- Round:Radial symmetry facilitates rotational cutting techniques and corner-free sanitation protocols. Catering operators prefer circular boards for buffet presentation aesthetics and centralized ingredient access.
- Square:Equal-edge dimensions suit compact residential kitchens with constrained counter depth.
- Oval:Elongated curvature provides directional cutting flow for artisanal butcher-block applications.
Rectangular formats dominate commercial procurement specifications; round configurations gain share in mobile catering equipment.
Size:
Surface area requirements scale with batch volume and protein throughput across end-use categories.
- Large:Exceeding 18 inches in primary dimension, these surfaces accommodate whole-animal butchery and high-volume vegetable prep. Centralized commissary operations in California specify large-format polyethylene for production line efficiency.
- Extra Large:Surfaces exceeding 24 inches serve dedicated butcher stations and institutional protein processing. Texas meat-processing facilities specify extra-large end-grain maple for commercial slaughterhouse compliance.
- Small:Under 12-inch dimensions target residential quick-prep tasks and limited counter spaces.
- Medium:12-18 inch range balances portability with functional surface area for household cooking.
Large formats command commercial procurement volume; extra-large surfaces expand most quickly in centralized food production.
End User:
Operational intensity and capital depreciation policies differentiate procurement behavior across customer categories.
- Commercial:Foodservice operators prioritize NSF certification and standardized replacement schedules over unit longevity. Ghost kitchen infrastructure across Austin and Brooklyn corridors treats cutting surfaces as consumable inventory rather than capital equipment.
- Professional Chefs:Independent restaurant owners specify end-grain hardwood for blade preservation and tactile feedback. Chef-owned establishments in metropolitan culinary clusters unbundle after-sales service expectations from procurement decisions.
- Household:Residential purchasers balance aesthetic preferences with dishwasher compatibility and storage constraints.
- Catering Services:Mobile food operators demand lightweight durability and rapid sanitation turnaround for event-based deployment.
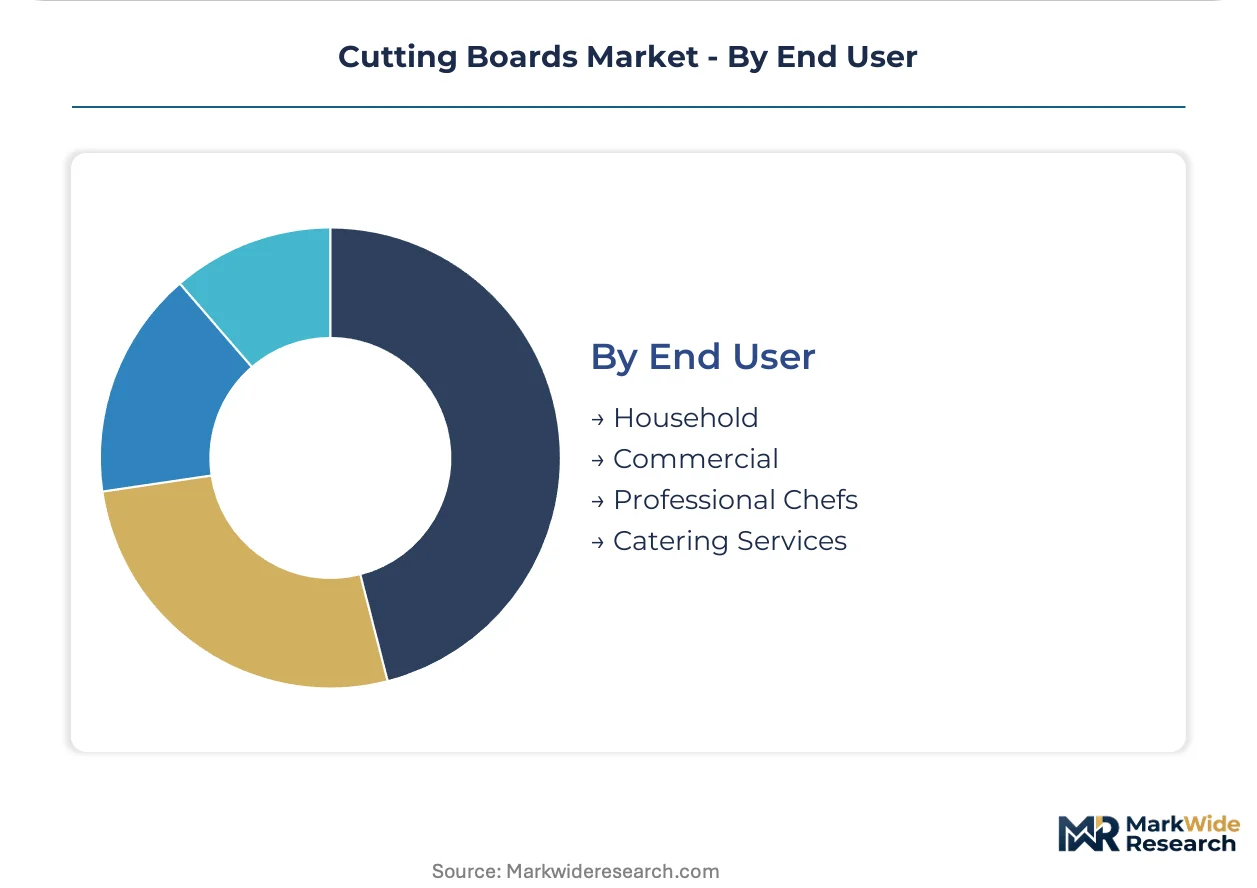
Commercial end users drive aggregate volume; professional chef segments sustain premium pricing tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: North American operators prioritize NSF-certified polymer durability for high-velocity replacement cycles, while European procurement emphasizes REACH-compliant adhesive systems in renewable-material laminates.
United States
Ghost kitchen proliferation across Texas and California corridors drives concentrated demand for industrial-dishwasher-rated polyethylene surfaces. FDA food-contact notification requirements tighten polymer migration specifications for hospital and school cafeteria procurement. Austin and Brooklyn operator clusters exemplify velocity-over-longevity consumption patterns favoring lower-unit-cost options.
Germany
Commercial foodservice distributors consolidate vendor selection around NSF-certified suppliers with EU-wide logistics coverage. ECHA REACH Annex XVII restrictions on formaldehyde-releasing agents in bamboo lamination adhesives trigger supply chain reconfigurations. German import inspectors reject non-compliant phenol-resin bonding layers at Hamburg and Bremen ports.
France
Chef-owned independent restaurants in Paris and Lyon metropolitan areas unbundle after-sales service expectations from cutting surface procurement. French national food safety regulations align with EU REACH chemical restrictions on wood treatment compounds. Catering operators in Provence-Alpes-Côte d'Azur prefer circular boards for buffet presentation aesthetics.
China
Manufacturing capacity concentrates in Yangtze River Delta and Pearl River Delta zones for bamboo fiber composite export production. GB standards govern food-contact surface specifications for domestic hospitality procurement. Zhejiang and Fujian province factories pivot toward European-sourced adhesive systems to satisfy REACH compliance for EU-bound shipments.
Japan
Professional chef segments in Tokyo and Osaka sustain premium positioning for end-grain hardwood assemblies despite longer replacement intervals. METI industrial standards influence commercial kitchen equipment sanitation protocols. Kansai region culinary clusters demonstrate persistent preference for blade-preserving wood surfaces over polymer alternatives.
Cutting Boards Market Vendor Landscape
Capability concentration sits with artisanal hardwood specialists; scale advantage sits with polymer extruders and mass-market distributors. The vendor base separates into three functional tiers: heritage-positioned wood fabricators, composite technology developers, and ergonomic retail-format suppliers. Dominant competitive moves include strategic partnerships with broadline foodservice distributors and portfolio diversification into antimicrobial-embedded substrate formulations.
Within the heritage-positioned tier, John Boos exemplifies American hardwood sourcing integration, while Epicurean occupies a position in proprietary paper-based composite technology. Among ergonomic retail-format specialists, OXO anchors mass-merchant channel control through grip-engineering differentiation. These three entities represent divergent archetype strategies: domestic supply-chain anchoring, material-science innovation, and retail-format ergonomics respectively.
| Leading Market Players |
|---|
| Sonder LA |
| Epicurean |
| John Boos |
| Tupperware |
| OXO |
| Grizzly Blocks |
| Ironwood Gourmet |
| Bamboo Classic Board |
| SoulFino |
| Others |
Supply Flow & Price Mechanics
Port of Long Beach container rates shape cost structures across polyethylene cutting board imports from Asian manufacturing zones, compressing margins for distributors serving Texas ghost kitchen corridors while amplifying price spreads between NSF-certified premium tiers and uncertified economy alternatives.
Pricing Analysis
Contract-based long-term offtake agreements dominate institutional procurement, with broadline foodservice distributors locking in volume commitments for antimicrobial-embedded polyethylene boards. Price differentiation separates NSF-certified surfaces with silver-ion additives from standard HDPE alternatives, with certification grade and volume scale as primary tiering mechanisms. Pricing pressure stems from hardwood input volatility in American black walnut and maple markets. Hospital and school cafeteria buyers exhibit lowest price sensitivity due to compliance mandates, while independent restaurant operators in Austin and Brooklyn corridors demonstrate highest elasticity, treating boards as consumable inventory.
Supply Chain Analysis
American black walnut and maple feedstock draws from domestic sustainable forestry certification programs in the Great Lakes and Appalachian regions. Raw material dependencies center on phenol-resin adhesives for bamboo lamination, high-density polyethylene resin from Gulf Coast petrochemical complexes, and silver-ion antimicrobial compounds. Single-source vulnerability concentrates in Asian bamboo fiber composite manufacturing serving European REACH compliance requirements. Distribution runs through broadline foodservice distributors with national logistics coverage for institutional accounts, supplemented by direct-to-restaurant channels for chef-owned independents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
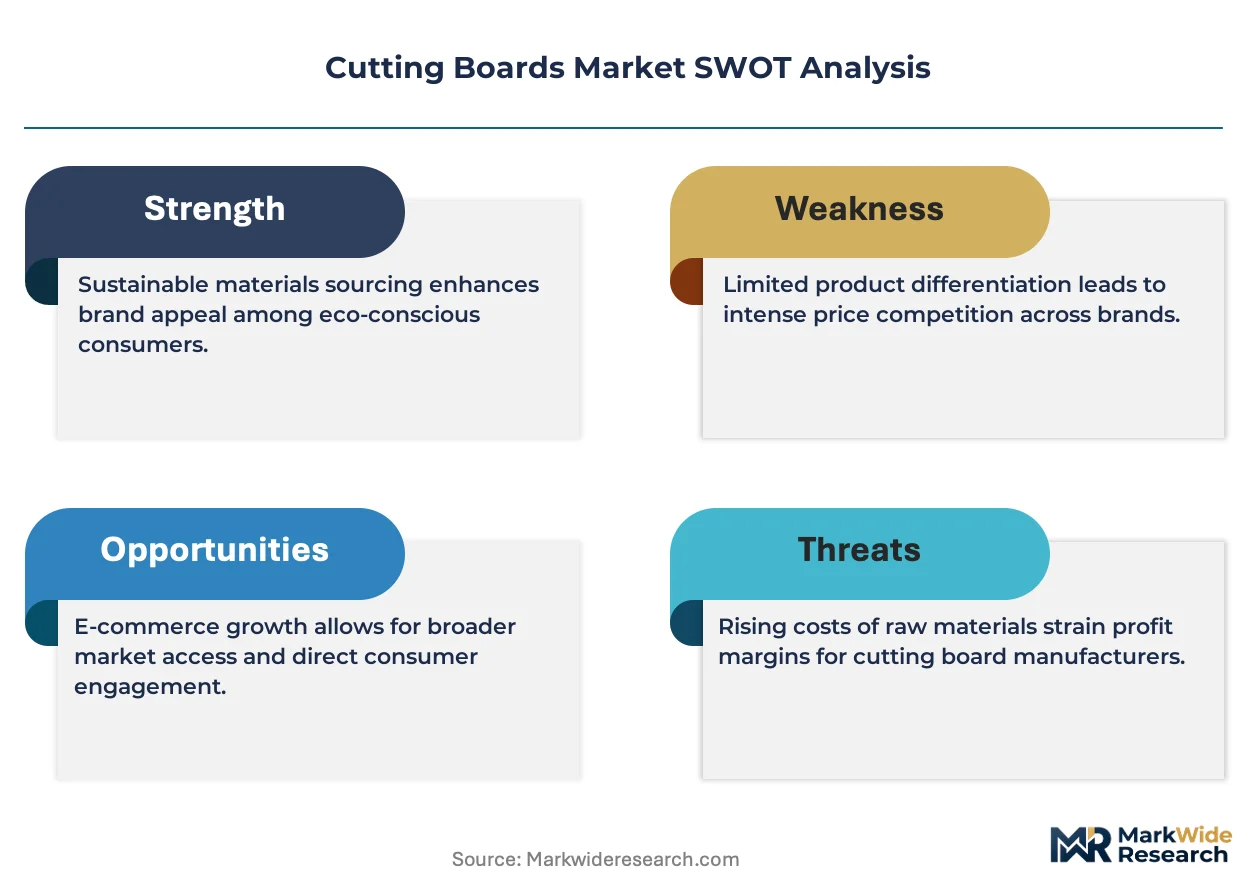
Tempered glass surfaces threaten substitution in hygiene-critical healthcare segments, forcing incumbent suppliers to defend material relevance through certification depth and blade-preservation engineering.
For Market Incumbents: Pre-empt glass substitution in hospital cafeterias by deepening NSF Standard 2 certification portfolios and integrating ergonomic thermoplastic elastomer handles into HDPE cores. Anchor supply security through backward integration into American hardwood forestry certification or captive adhesive formulation for bamboo composites. Ghost kitchen velocity-over-longevity preferences demand inventory flexibility rather than longevity claims. For New Entrants and Emerging Players: Paper-based composite white space in California and New York compostability mandate corridors represents the most penetrable entry point for certified biodegradable alternatives. Mid-tier commercial foodservice operators in secondary urban corridors lack dedicated supplier relationships. Pursue direct procurement platform partnerships with regional broadline distributors rather than national logistics investments. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified kitchen equipment conglomerates with underoptimized cutting board divisions lacking antimicrobial formulation capabilities. Long-term viability hinges on material science differentiation rather than brand heritage accumulation. Watch FDA polymer migration limit tightening timelines as inflection signals for compound reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Formulation Investment | Silver-ion embedding renders untreated HDPE obsolete in hospital cafeteria contracts. |
| NSF Certification Acceleration | Ninety-day laboratory validation cycles delay new material introductions without pre-positioning. |
| REACH-Compliant Adhesive Sourcing | European port rejections of phenol-resin bonding layers force supply chain reconfiguration. |
| Ergonomic Handle Integration | Thermoplastic elastomer grips differentiate institutional procurement specifications. |
| Ghost Kitchen Channel Partnership | Velocity-over-longevity consumption patterns favor consumable-inventory positioning. |
Methodological Framework
Operator-level perspectives from commercial kitchen equipment buyers, NSF certification laboratory directors, broadline foodservice distributor procurement managers, and bamboo composite manufacturing plant managers anchored the qualitative base. Secondary validation drew from FDA food-contact notification filings, NSF International Standard 2 equipment sanitation protocols, ECHA REACH Annex XVII restriction updates, and customs import inspection records at Hamburg and Long Beach ports. Bottom-up volume estimates triangulated against top-down market sizing across material, shape, size, and end-user segmentation dimensions.
Scenario-bracketing framed the analytical approach across the projection horizon, with material substitution curves and regulatory compliance timelines as primary sensitivity inputs. Segmentation modeling captured wood end-grain assemblies, polyethylene substrates, bamboo laminates, and tempered glass surfaces alongside commercial, professional chef, household, and catering end-user categories. CAGRs derived from replacement cycle compression rates in ghost kitchen infrastructure and antimicrobial mandate diffusion patterns across healthcare foodservice procurement.
Practitioners should monitor FDA polymer migration limit revisions, EU REACH adhesive restriction expansions, and state-level compostability mandate adoptions for early signals requiring forecast adjustment. Cross-checking against broadline distributor inventory turnover data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Europe Online Grocery Delivery Market
Food Service
Beverage Vending Machine Market
Food Service
Indonesia Foodservice Market
Food Service
South Africa Fast Food Market
Food Service
Commercial Deep Fryer Parts and Accessories Market
Food Service
Egypt Food Service Market
Food Service
Europe Smokeless Indoor Grills Market
Food Service
GCC Biodegradable Food Service Disposables Market
Food Service
Restaurant Glassware Market
Food Service
Europe Cloud Kitchen Market
Food Service
North America Cafes & Bars Market
Food Service
Bar Refrigeration Market
Food Service
Commercial Cutlery Market
Food Service
United States Smokeless Indoor Grills Market
Food Service
Commercial Air Fryer Oven Market
Food Service
India Quick Service Restaurant Market