
 Microbial Food Ingredients Market | 2026-2036
Microbial Food Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Microbial Food Ingredients Market Analysis
Subscription-based strain characterization services is decoupling microbial ingredient sales from traditional bulk supply contracts. DSM leverages its culture collection breadth to sustain long-term R&D partnerships with dairy processors across Northern Europe. BASF competes through backward integration into fermentation feedstock supply, while Novozymes anchors its position through proprietary enzyme expression platforms.
Microbial food ingredients comprise viable or inactivated microorganisms, their metabolites, and enzymatic extracts used to modify food matrices through fermentation, biotransformation, or direct supplementation, typically requiring controlled pH between 4.5 and 7.0 and temperatures of 30°C to 42°C for optimal metabolic activity. These inputs serve primarily to enhance shelf stability, nutritional density, and sensory profiles in processed foods. Probiotics command the deepest margin pools due to clinical substantiation requirements and strain-specific intellectual property, while enzymes represent the highest-volume category driven by cost reduction in baked goods and beverage processing. Organic acids are gaining fastest in meat preservation applications as processors reformulate around reduced synthetic additive labels.
EFSA maintains stringent Qualified Presumption of Safety assessments for novel microbial strains entering European food chains, while the FDA GRAS notification pathway shapes U.S. market entry timelines for fermentation-derived ingredients. China's SAMR enforces national food safety standards under GB codes that classify microbial additives by permitted strain lists and maximum usage levels. Stakeholders must monitor evolving strain patent expiries and regulatory divergence between jurisdictions to optimize product registration sequencing and manufacturing location decisions.
Market Dynamics
Clean-label fermentation is restructuring supply relationships as dairy processors bypass commodity traders to contract directly with strain developers for proprietary culture access.
Growth Catalysts
- EFSA Qualified Presumption of Safety pathway:Harmonized safety assessments for microbial strains reduce redundant toxicology studies across EU member states, accelerating cross-border ingredient approvals.
- Precision fermentation infrastructure:Contract manufacturing organizations in Denmark and the Netherlands now offer dedicated food-grade bioreactor capacity, lowering capital barriers for novel ingredient commercialization.
- Plant-based dairy analogues:Formulators require microbial-derived flavor precursors and texture-modifying enzymes to replicate fermented dairy sensory profiles without animal inputs.
Market Restraints
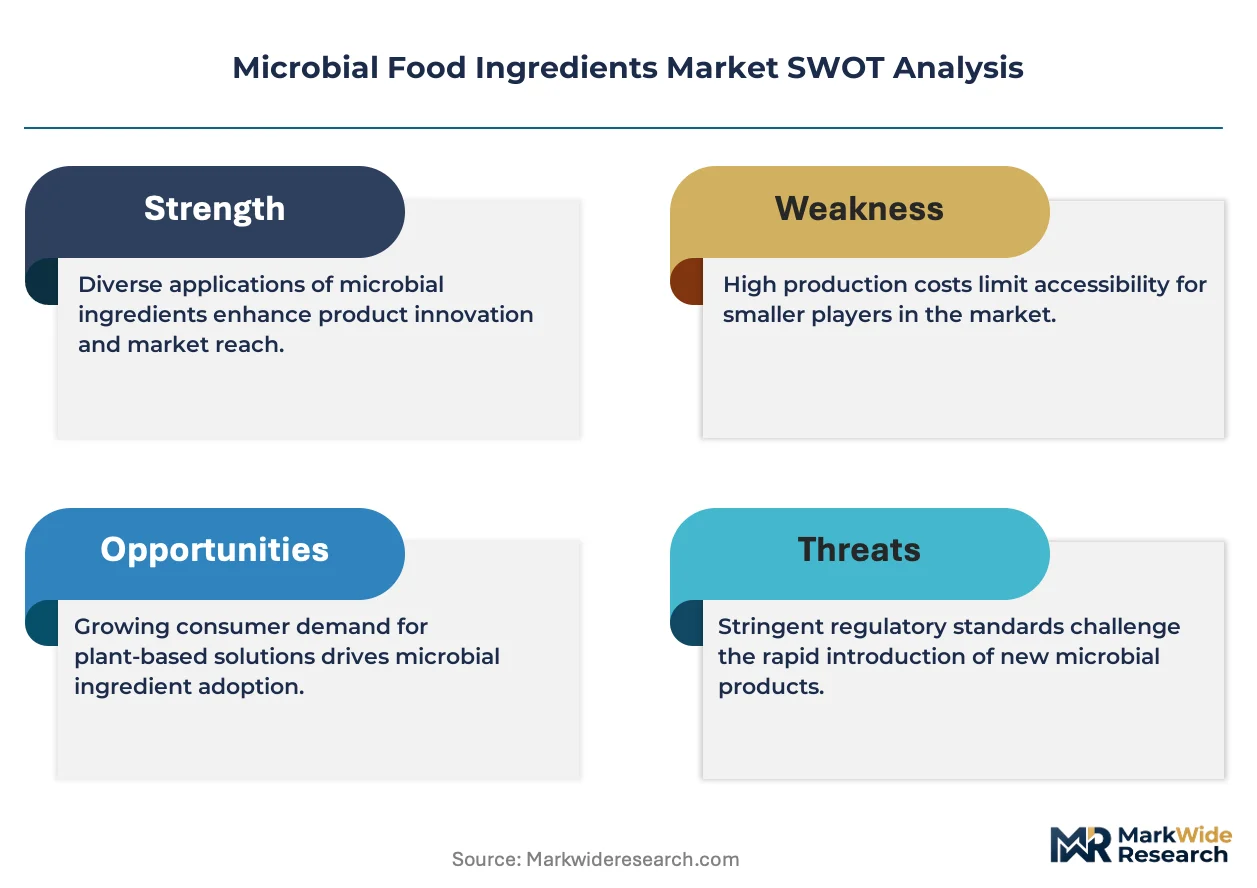
- Feedstock price volatility:Corn-derived dextrose and soy peptone costs fluctuate with agricultural commodity cycles, compressing fermentation margins during input spikes.
- Strain bank concentration:Three public culture collections in Germany, Japan, and the United States control access to 60% of documented food-grade microorganisms, creating licensing bottlenecks.
- Thermal stability limitations:Most probiotic strains lose viability above 55°C, restricting incorporation into UHT-processed beverages and retort-pouched meals.
Strategic Opportunities
- South Korean functional food regulations:MFDS recognition of postbiotics as a distinct category creates a regulatory sandbox for heat-killed microbial ingredients with substantiated health claims.
- Cellular agriculture feed applications:Fermentation-derived amino acid and vitamin premixes address cultivated meat producers' need for animal-free growth media components.
- Direct-to-manufacturer digital platforms:Strain-matching algorithms connect food formulators with specialized culture suppliers, disintermediating traditional ingredient distributors.
Industry Challenges
- PhD-level fermentation scientists:Industrial microbiology programs have contracted across Western European universities, narrowing the talent pipeline for scale-up operations.
- Multi-jurisdictional dossier preparation:Separate GRAS notifications for FDA, novel food applications for EFSA, and strain-specific registrations for China's SAMR demand redundant safety documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microbial Food Ingredients Market |
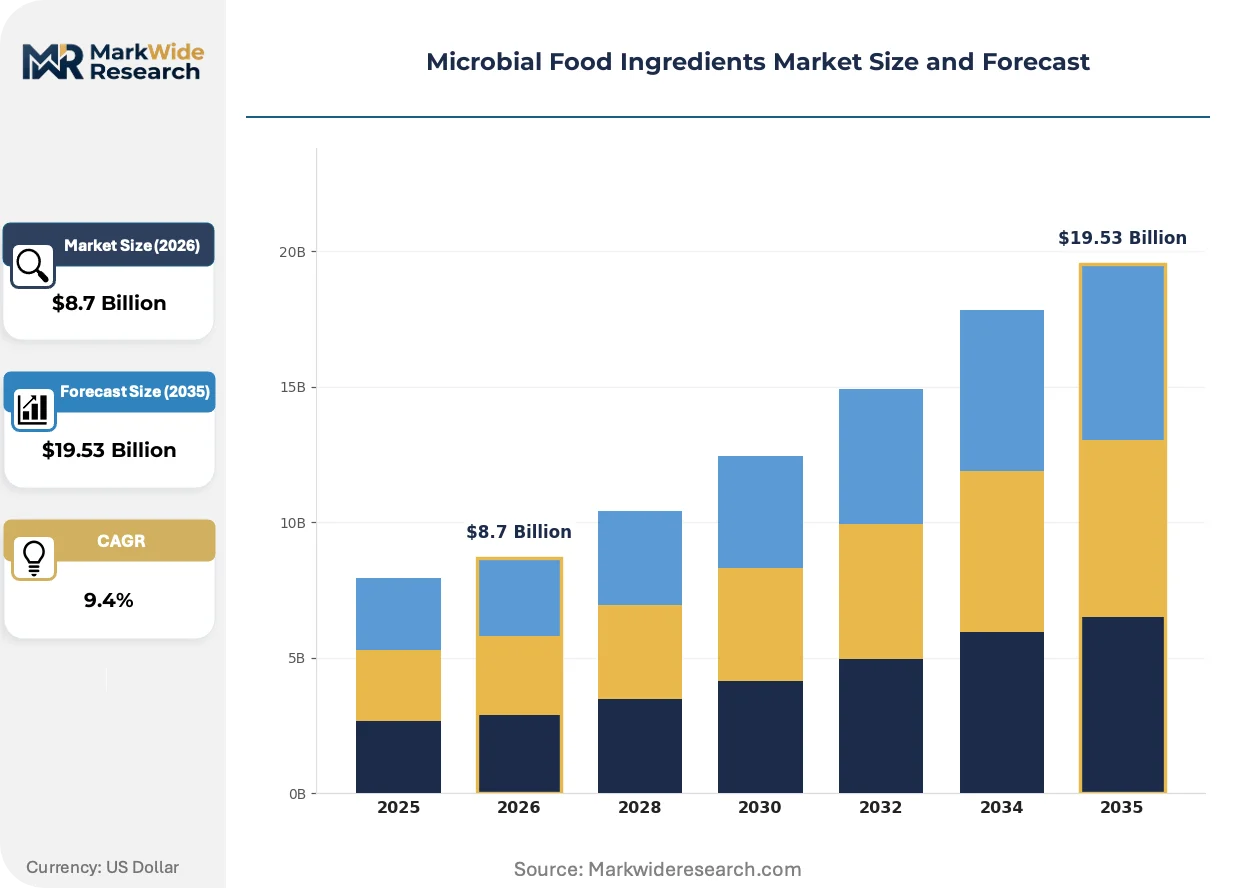
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probiotics, Enzymes, Amino Acids, Organic Acids Application: Dairy Products, Baked Goods, Meat Products, Beverages End User: Food Manufacturers, Beverage Producers, Restaurants, Home Cooks Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Lallemand, Evonik Industries, Ginkgo Bioworks, DSM, BASF, Novozymes, Cargill, Archer Daniels Midland, Adisseo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microbial Food Ingredients Market Emerging Trajectories
Bioprocess intensification and regulatory category creation are redrawing competitive boundaries between commodity enzyme suppliers and high-value probiotic developers.
Continuous fermentation with cell retention is overtaking traditional batch processing in amino acid production. Chinese lysine manufacturers have retrofitted 80% of installed capacity since 2022. This operational shift is compressing capital intensity per kilogram of output and widening margin spreads for integrated producers.
EU Green Deal packaging mandates are forcing reformulation timelines. The F-Gas Regulation phase-down of hydrofluorocarbon refrigerants raises cooling costs for fermentation facilities, particularly affecting thermotolerant strain production. Northern European processors are responding with ammonia-based refrigeration retrofits and geothermal integration.
Subscription characterization services are fragmenting procurement patterns. Dairy cooperatives in Wisconsin and Bavaria now lease strain performance data rather than purchasing bulk cultures outright. This model shift concentrates buyer power with technology platforms and defers manufacturing investment to specialized fermentation houses.
Microbial Food Ingredients Market Segmentation
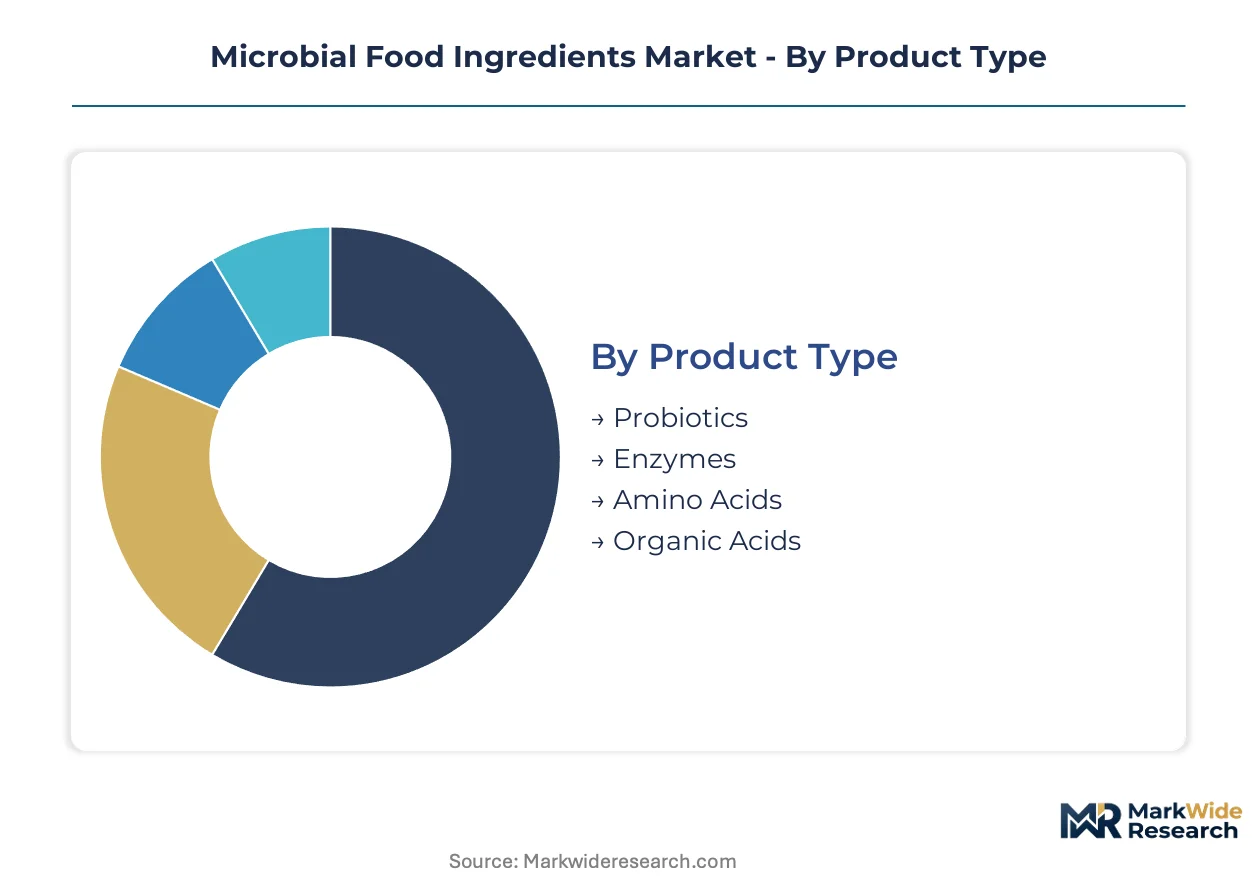
Microbial food ingredients exhibit divergent margin profiles and technical specifications across product categories, forcing procurement teams to balance functional performance against regulatory substantiation costs. Application-specific formulation requirements further fragment sourcing strategies, as thermostability demands in beverage processing clash with viability preservation needs in dairy fermentation.
Product Type:
Strain specificity and intellectual property protection intensity vary dramatically across microbial ingredient technologies, creating tiered investment barriers for market entrants.
- Probiotics:Live or heat-killed microbial strains delivering substantiated health benefits through gut microbiome modulation. Clinical trial requirements and strain-specific patents concentrate value capture with culture collection licensors in Germany and Japan. EFSA Qualified Presumption of Safety assessments impose documentation burdens that favor incumbent developers with established dossier libraries.
- Enzymes:Protein catalysts derived from bacterial or fungal fermentation, standardized by activity units per gram. Cost reduction imperatives in baked goods and beverage processing drive procurement volume, with amylases and proteases dominating industrial contracts. Novozymes and DSM anchor supply through proprietary expression platforms.
- Amino Acids:Fermentation-derived building blocks for protein fortification and flavor enhancement. Chinese and Indian manufacturers absorb disproportionate capacity additions, leveraging continuous fermentation retrofits to compress unit economics.
- Organic Acids:Metabolites including lactic acid and citric acid for pH modulation and preservation. Meat processors reformulating around reduced synthetic additive labels are pulling fastest volume expansion in this category.
Mature deployment sits with Enzymes. Newer deployment is concentrated in Organic Acids.
Application:
Processing temperature regimes and shelf stability requirements dictate strain selection criteria across food manufacturing verticals.
- Dairy Products:Fermentation cultures for yogurt, cheese, and kefir production requiring precise acidification curves and texture development. Clean-label momentum is restructuring supply relationships as processors contract directly with strain developers for proprietary culture access, bypassing commodity traders.
- Baked Goods:Enzymatic improvers for dough conditioning, crumb structure optimization, and shelf-life extension. Amylases and xylanases represent highest-volume procurement categories, with cost-per-ton processed driving supplier selection.
- Meat Products:Bioprotective cultures and organic acids for pathogen inhibition and color retention. Reformulation timelines are accelerating as processors respond to EU Green Deal packaging mandates and synthetic additive reduction commitments.
- Beverages:Probiotic fortification and enzymatic clarification for juices, kombucha, and functional drinks. Thermal stability limitations restrict viable strain incorporation into UHT-processed products, creating demand for heat-killed postbiotic alternatives.
Volume concentration favors Dairy Products. Steepest expansion trajectory is emerging in Meat Products.
End User:
Technical sophistication and regulatory exposure determine service intensity requirements across customer tiers.
- Food Manufacturers:Industrial-scale processors with dedicated quality assurance and regulatory affairs functions. These buyers negotiate multi-year supply agreements with embedded strain performance guarantees and documentation packages for EFSA, FDA, or SAMR submissions.
- Beverage Producers:Formulators requiring microbial-derived flavor precursors and texture-modifying enzymes, particularly for plant-based dairy analogues. Precision fermentation infrastructure in Denmark and the Netherlands supports novel ingredient commercialization for this segment.
- Restaurants:Foodservice operators sourcing fermented bases and specialized cultures for in-house production. Direct-to-manufacturer digital platforms are disintermediating traditional distributors through strain-matching algorithms.
- Home Cooks:Retail consumers purchasing starter cultures and fermentation kits. Online retail channels dominate this fragmented, price-sensitive segment with minimal technical support requirements.
Contract sophistication peaks with Food Manufacturers. Digital disintermediation is penetrating Restaurants fastest.
Distribution Channel:
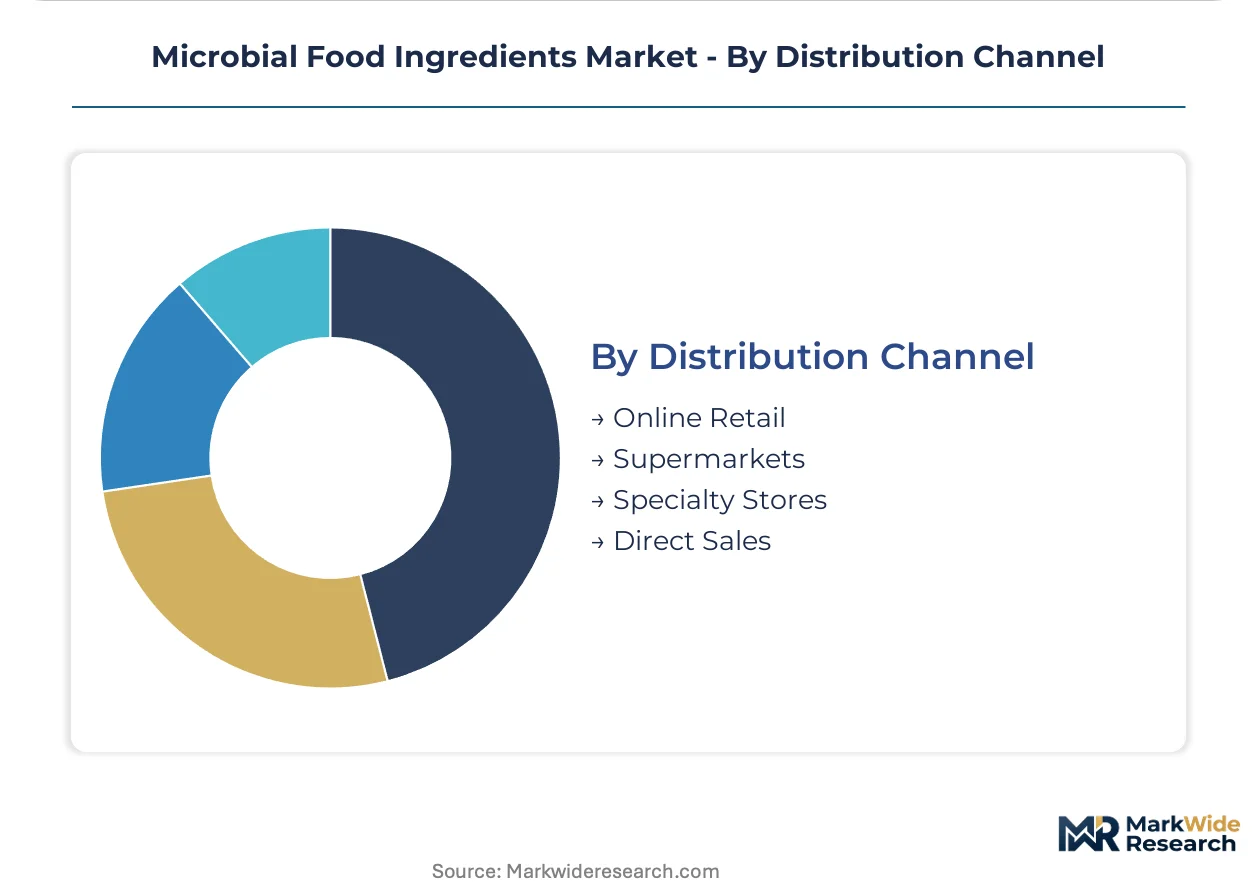
Supply chain configuration determines documentation integrity and cold chain maintenance capabilities.
- Online Retail:E-commerce platforms serving home cooks and small-scale fermenters with ambient-stable products. Subscription-based strain characterization services are fragmenting procurement patterns, concentrating buyer power with technology platforms.
- Supermarkets:Mass retail chains stocking consumer-facing probiotic supplements and fermentation starters. Shelf placement negotiations favor brands with clinical substantiation and recognizable strain designations.
- Specialty Stores:Boutique retailers targeting artisanal food producers and fermentation enthusiasts. Technical consultation and starter culture freshness drive loyalty in this service-intensive channel.
- Direct Sales:Manufacturer-to-processor relationships for bulk enzymes, amino acids, and proprietary cultures. Clean-label fermentation is accelerating direct contracting as dairy processors seek exclusive strain access.
Margin capture concentrates in Direct Sales. Channel expansion is climbing the fastest in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China and India absorb disproportionate capacity additions in amino acid fermentation, while European strain developers face lengthening EFSA approval timelines. North American dairy processors are contracting directly with culture suppliers, bypassing traditional distribution channels.
China
Continuous fermentation retrofits have upgraded 80% of installed lysine capacity since 2022. SAMR enforces GB standards that classify microbial additives by permitted strain lists and maximum usage levels. Yangtze River Delta manufacturers leverage state-backed precision fermentation infrastructure to compress unit economics for amino acid exports.
United States
Dairy cooperatives in Wisconsin now lease strain performance data through subscription platforms rather than purchasing bulk cultures. FDA GRAS notification pathways shape market entry timelines for fermentation-derived ingredients. Greater Boston hosts contract manufacturing organizations offering dedicated food-grade bioreactor capacity for novel ingredient commercialization.
Germany
EFSA Qualified Presumption of Safety assessments impose documentation burdens that favor incumbent developers with established dossier libraries. EU Green Deal packaging mandates and F-Gas Regulation phase-downs are forcing ammonia-based refrigeration retrofits in fermentation facilities. Bavarian processors are integrating geothermal systems to offset rising cooling costs for thermotolerant strain production.
India
FSSAI regulations govern microbial food additive approvals through strain-specific safety evaluations. Gujarat and Maharashtra absorb disproportionate capacity additions in amino acid fermentation, leveraging feedstock proximity to agricultural commodity belts. Indian manufacturers are retrofitting batch processing lines with continuous fermentation systems to match Chinese unit economics.
South Korea
MFDS recognition of postbiotics as a distinct category creates a regulatory sandbox for heat-killed microbial ingredients with substantiated health claims. Seoul Capital Area formulators require microbial-derived flavor precursors for plant-based dairy analogues. Domestic fermentation houses are expanding contract manufacturing capacity to serve functional food exporters targeting Japanese and Southeast Asian markets.
Microbial Food Ingredients Market Vendor Landscape
Top-tier vendors anchor proprietary strain collections and expression platforms, while mid-tier players compete on fermentation scale and feedstock integration. The market structure concentrates around three strategic archetypes: culture collection licensors with deep strain banks, integrated chemical conglomerates with backward feedstock control, and specialized enzyme developers with proprietary biotransformation technologies. Dominant competitive moves include direct-to-manufacturer digital platform launches and precision fermentation infrastructure partnerships.
Among European-based developers, DSM leverages its culture collection breadth to sustain long-term R&D partnerships, while BASF competes through backward integration into fermentation feedstock supply. Novozymes anchors the specialized enzyme tier through proprietary expression platforms. These three exemplify the tiered competitive structure where strain intellectual property, feedstock control, and bioprocess expertise define distinct positioning vectors.
| Leading Market Players |
|---|
| Lallemand |
| Evonik Industries |
| Ginkgo Bioworks |
| DSM |
| BASF |
| Novozymes |
| Cargill |
| Archer Daniels Midland |
| Adisseo |
| Others |
Supply Flow & Price Mechanics
EU Green Deal packaging mandates and F-Gas Regulation phase-downs gate qualified supply for thermotolerant strain production, restricting premium-tier pricing access to processors with ammonia-based refrigeration retrofits and geothermal integration in Northern Europe.
Pricing Analysis
Margin tightening in commodity enzyme tiers reflects continuous fermentation retrofits by Chinese lysine manufacturers compressing unit economics. Three-tier pricing structure across premium, standard, and economy levels separates strain-specific probiotic cultures from bulk enzymatic improvers and commodity organic acids. Pricing pressure stems from corn-derived dextrose and soy peptone cost volatility feeding through fermentation margins. Food manufacturers with multi-year supply agreements show lowest price sensitivity; home cooks through online retail channels exhibit highest.
Supply Chain Analysis
PhD-level fermentation scientist shortages across Western European universities constrain scale-up operations in Denmark, the Netherlands, and Germany. Supply concentrates in China and India for amino acid fermentation, with Germany and Japan anchoring culture collection licensing. Raw material dependencies center on agricultural feedstocks—corn dextrose, soy peptone, and yeast extract—plus specialized bioreactor components. Single-source vulnerability sits with three public culture collections controlling 60% of documented food-grade microorganisms. Distribution runs through direct sales for bulk industrial contracts, with digital platforms fragmenting procurement for smaller processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where feedstock control and strain intellectual property determine margin capture. Players are pursuing backward integration into fermentation feedstock supply as the decisive upstream lever.
For Market Incumbents: Lock in exclusive strain access through long-term R&D partnerships with dairy cooperatives in Wisconsin and Bavaria, while securing ammonia-based refrigeration capacity ahead of F-Gas Regulation enforcement. Patent expiries on established probiotic strains threaten margin pools; prioritize dossier libraries for EFSA Qualified Presumption of Safety assessments to extend regulatory moats. For New Entrants and Emerging Players: MFDS recognition of postbiotics as a distinct category in South Korea opens a window for heat-killed microbial ingredients with substantiated health claims, bypassing thermal stability limitations that restrict viable probiotic incorporation. Target plant-based dairy analogue formulators in Seoul Capital Area requiring microbial-derived flavor precursors. Lead with subscription-based strain characterization services to disintermediate traditional ingredient distributors. For Investors and Strategic Acquirers: Precision fermentation infrastructure partnerships in Greater Boston and the Yangtze River Delta are the leading indicator that contract manufacturing capacity is consolidating before novel ingredient commercialization scales. Five-to-ten year viability favors platforms combining strain-matching algorithms with captive bioreactor networks. Watch for direct-to-manufacturer digital platform launches as the inflection signal for distributor disintermediation accelerating.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | BASF's captive corn dextrose sourcing insulates margin compression from agricultural commodity cycles. |
| Precision Fermentation Infrastructure Partnership | Contract manufacturing organizations in Denmark lower capital barriers for novel strain commercialization. |
| Direct-to-Manufacturer Digital Platform Launch | Strain-matching algorithms disintermediate traditional distributors and concentrate buyer power with technology platforms. |
| Regulatory Dossier Library Investment | Established EFSA Qualified Presumption of Safety assessments create incumbent moats against novel strain entrants. |
| Geothermal Refrigeration Retrofit | Bavarian processors offset F-Gas Regulation cooling cost spikes for thermotolerant strain production. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with fermentation scientists at culture collection licensors, procurement leads at dairy processors, regulatory affairs directors navigating EFSA and FDA pathways, and plant managers operating continuous fermentation retrofits. FDA GRAS notifications, EFSA novel food applications, SAMR GB standard filings, and fermentation industry association reports provided validation layers. Bottom-up strain-level production estimates triangulated against top-down ingredient category demand assessments.
Reconciliation of volume and value data streams across the projection horizon employed segmentation by product type—probiotics, enzymes, amino acids, organic acids—crossed with application verticals and end-user technical sophistication tiers. CAGRs derived from fitted growth curves incorporating regulatory approval timeline assumptions, capacity expansion announcements, and substitution elasticity between microbial and synthetic additives. Industry-specific inputs included strain patent expiry schedules and precision fermentation infrastructure buildout trajectories.
The model assumes a particular technology adoption path; alternative pathways for continuous fermentation with cell retention would alter the outlook if Chinese manufacturers accelerate retrofit timelines beyond baseline assumptions. Forecasts reflect documented assumptions regarding EFSA evaluation duration, feedstock price normalization, and thermotolerant strain development progress. Material deviation in regulatory approval timelines, agricultural commodity spikes, or culture collection licensing terms warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Avocado Oil Market
Ingredients
South America Insoluble Dietary Fibers Market
Ingredients
North America Vegetable Oils Market
Ingredients
Potato Peel Powder Market
Ingredients
Dried Fruit Ingredients Market
Ingredients
Native Whey Protein Ingredients Market
Ingredients
Mung Bean Starch Market
Ingredients
Global Dry Yeast Market
Ingredients
Siraitia Grosvenorii Extract Market
Ingredients
Europe Malt Ingredient Market
Ingredients
Astragalus Root Extract Market
Ingredients
Hydrolyzed Egg Market
Ingredients
Europe Gelatin Market
Ingredients
Coconut Flour Market
Ingredients
Egg Free Premix Market
Ingredients
Global Autolyzed Yeast Extract Market