
 Asia Pacific Freeze Dried Product Market | 2026-2036
Asia Pacific Freeze Dried Product Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Freeze Dried Product Market Insights
Aftermarket service revenue for freeze-dried processing equipment is fragmenting as original manufacturers lose exclusivity on spare parts and technical support. Fujian Lixing Foods Co. Ltd. leverages backward integration into raw fruit sourcing to secure supply continuity across Fujian province. Ajinomoto Co. Inc. anchors its position through R&D intensity in umami-enhanced freeze-dried formulations for instant applications. Asahi Group Holdings Ltd. competes via brand strength in beverage-adjacent freeze-dried ingredients distributed through Japanese convenience retail.
Freeze-dried products undergo sublimation dehydration at pressures below 611 pascals and shelf temperatures typically ranging from -50°C to -80°C, preserving cellular structure and rehydration capacity for commercial food manufacturing. The fruits segment leads value generation due to premium pricing in retail and food service channels across Thailand and Australia. Vacuum packs dominate packaging type selection where oxygen transmission rates below 0.1 cc/m²/day extend shelf life for export-bound products. Online distribution channels register the fastest structural expansion as direct-to-consumer brands in South Korea and Japan bypass traditional wholesale layers.
Japan's Ministry of Health, Labour and Welfare enforces food additive and labeling standards that constrain imported freeze-dried ingredients without domestic certification. Australia's FSANZ mandates nutritional disclosure protocols that shape pouch-format retail packaging specifications. China's SAMR intensifies facility inspection frequency for freeze-dried meat operations following revised food safety implementation rules. Stakeholders must monitor regulatory divergence between harmonized ASEAN standards and country-specific import protocols when allocating regional production capacity.
Market Dynamics
Southeast Asian freeze-dried fruit exporters are consolidating processing capacity to meet European retail shelf-space requirements, while Japan's JIS packaging norms and China's SAMR facility inspections force dual-track certification investments across regional supply chains.
Growth Catalysts
- Japan's Ministry of Health, Labour and Welfare certification:Domestic labeling standards for imported freeze-dried ingredients create captive demand for certified regional suppliers.
- Military and emergency preparedness procurement:Institutional buyers across Japan, Australia, and South Korea anchor volume contracts for long-shelf-life nutrition products.
- Direct-to-consumer online channels:South Korean and Japanese brands bypass wholesale layers, compressing distribution costs and expanding addressable consumer bases.
Market Restraints
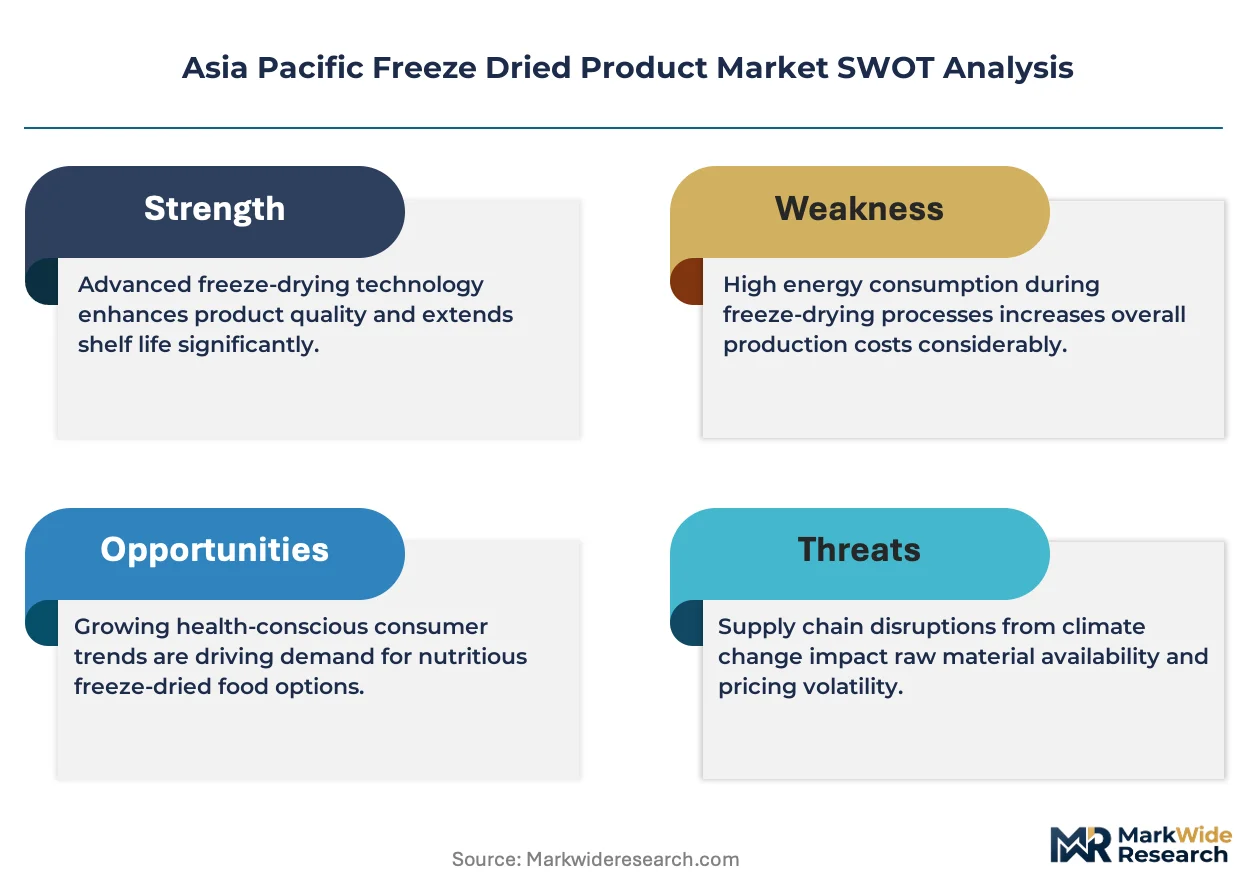
- Energy-intensive sublimation processing:Shelf temperatures at -50°C to -80°C and vacuum pressures below 611 pascals drive electricity costs that constrain margin expansion.
- Raw fruit supply concentration in Fujian province:Backward integration by dominant processors limits independent supplier access to premium cultivars.
- China's SAMR meat facility inspection intensity:Revised food safety implementation rules extend compliance timelines and raise capital requirements for freeze-dried protein operations.
Strategic Opportunities
- Vietnam and Indonesia capacity expansion:Greenfield freeze-drying investments target European and North American export channels with lower labor and land costs than established Northeast Asian bases.
- Umami-enhanced instant formulations:R&D intensity in savory flavor profiles opens food service and ready-meal applications beyond traditional sweet fruit segments.
- ASEAN harmonized standards adoption:Regulatory convergence reduces certification duplication for multi-country distribution, favoring centralized regional production hubs.
Industry Challenges
- Aftermarket service fragmentation:Original equipment manufacturers lose exclusivity on spare parts and technical support, eroding installed-base revenue predictability.
- Dual certification burden:Divergence between harmonized ASEAN standards and country-specific import protocols forces redundant testing and documentation for cross-border shipments.
- Vacuum packaging oxygen transmission specification:Rates below 0.1 cc/m²/day require specialized film suppliers with limited regional availability, constraining export-bound production scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Freeze Dried Product Market |
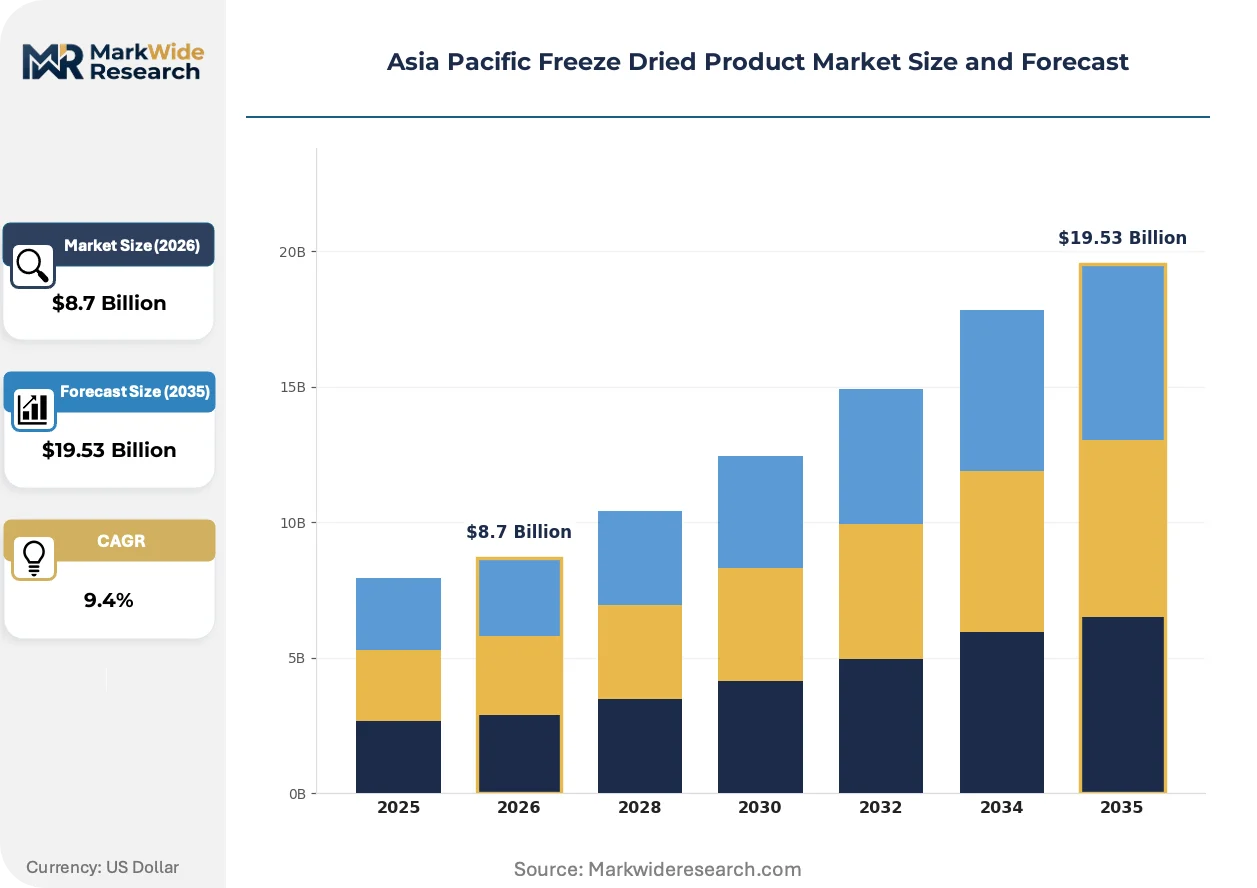
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meat, Fruits, Vegetables, Herbs End User: Food Service, Retail, Institutional, Direct-to-Consumer Packaging Type: Vacuum Packs, Sachets, Cans, Pouches Distribution Channel: Online, Supermarkets, Specialty Stores, Convenience Stores |
| Companies Covered | Fujian Lixing Foods Co. Ltd., Campers Pantry Pty Ltd., Ajinomoto Co. Inc., 3 Seasons Fruit Industry Co. Ltd., The Forager Food Co., Asahi Group Holdings Ltd., Nagatanien Holdings Co. Ltd., Totally Pure Fruits Pty Ltd., Nestle S.A., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Freeze Dried Product Market Trends and Innovations
Freeze-dried processing technology is migrating from batch-based sublimation systems toward continuous microwave-assisted drying, altering capital deployment patterns and facility footprints across the Asia Pacific region.
Continuous microwave-assisted drying is migrating from pilot-scale demonstrations to commercial installations in Thailand and Vietnam. Food service manufacturers seeking faster rehydration times are adopting hybrid thermal systems that reduce cycle duration by 40 percent. This technology migration is compressing the payback period for new capacity investments, redirecting capital from traditional tray-based lyophilizers toward integrated processing lines.
China's SAMR has intensified facility inspection frequency for freeze-dried meat operations under revised food safety implementation rules. The industrial consequence is a bifurcation between certified export-grade facilities and domestic-only processors. Vietnam-based meat drying operations are most affected, responding by segregating production lines and pursuing parallel Japan JIS certification to maintain multi-market access.
Convenience retail buyers in Japan are consolidating supplier relationships around beverage-adjacent freeze-dried ingredient portfolios. Direct sourcing agreements are replacing layered distributor networks, compressing margin pools for intermediaries. This consolidation is most visible in Tokyo and Osaka metropolitan convenience store chains, where private-label freeze-dried coffee and tea ingredients now command preferred shelf positioning.
Asia Pacific Freeze Dried Product Market Segmentation
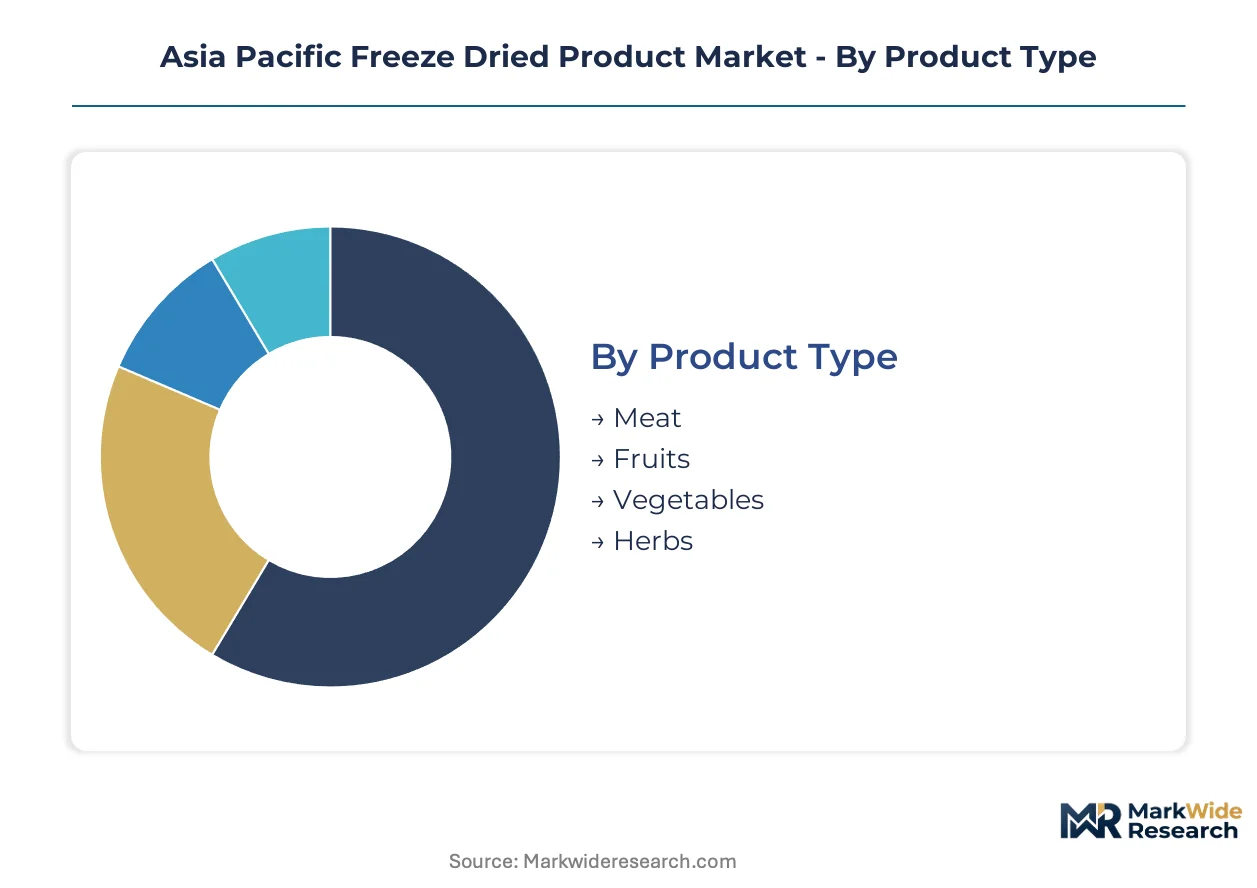
Freeze-dried product segmentation in Asia Pacific reflects divergent shelf-life requirements and channel economics. Military procurement cycles run 18-24 months while direct-to-consumer brands turn inventory in 45-60 days, creating fundamentally different working capital profiles across segments.
Product Type:
Cycle times vary dramatically: fruits and vegetables compress from harvest to finished goods in 72 hours during peak season, while meat and herb processing extends across multi-week sanitation and certification protocols.
- Fruits:Cellular structure preservation through sublimation at -50°C to -80°C enables premium rehydration performance in food service applications. Thailand and Australia concentrate retail and food service demand where premium pricing supports energy-intensive processing economics.
- Meat:China's SAMR intensifies facility inspection frequency under revised food safety implementation rules, bifurcating certified export-grade facilities from domestic-only processors. Vietnam-based operations segregate production lines and pursue parallel Japan JIS certification to maintain multi-market access.
- Vegetables:Shorter dehydration cycles than meat but require blanching pre-treatment that adds processing stages and water treatment compliance costs.
- Herbs:Low bulk density and volatile oil sensitivity constrain throughput per lyophilizer cycle, limiting viable scale to specialty processors with dedicated botanical expertise.
Fruits dominate installed base across Northeast Asian retail channels. Meat is where expansion concentrates as military and emergency preparedness procurement anchors volume contracts in Japan, Australia, and South Korea.
End User:
Cost tier stratification separates capital-intensive institutional buyers from margin-compressed retail intermediaries and asset-light direct-to-consumer brands.
- Institutional:Military and emergency preparedness buyers in Japan, Australia, and South Korea negotiate multi-year volume contracts with stringent shelf-life specifications. Procurement cycles extend 18-24 months but deliver predictable capacity utilization for certified suppliers.
- Direct-to-Consumer:South Korean and Japanese brands bypass traditional wholesale layers, compressing distribution costs by 15-25 percentage points versus retail-channel equivalents. Customer acquisition costs concentrate in digital marketing rather than slotting fees.
- Food Service:Manufacturers seeking faster rehydration times drive adoption of hybrid thermal systems that reduce cycle duration by 40 percent.
- Retail:Convenience store chains in Tokyo and Osaka metropolitan areas consolidate supplier relationships around beverage-adjacent freeze-dried ingredient portfolios.
Institutional buyers anchor capacity planning for certified processors. Direct-to-Consumer channels are gaining share fastest as digital-native brands scale customer acquisition.
Packaging Type:
Application requirements dictate barrier specification intensity, with export-bound products demanding specialized film suppliers with limited regional availability.
- Vacuum Packs:Oxygen transmission rates below 0.1 cc/m²/day extend shelf life for European and North American export channels. Specialized co-extruded film suppliers concentrate in Japan and South Korea, constraining scaling for Vietnam and Indonesia-based processors.
- Pouches:Australia's FSANZ mandates nutritional disclosure protocols that shape pouch-format retail packaging specifications, forcing label redesigns for cross-border shipments.
- Sachets:Single-serve formats dominate direct-to-consumer trial packs and convenience retail impulse purchases.
- Cans:Military specification packaging for long-duration emergency stockpiles requires seam integrity testing protocols that extend production lead times.
Vacuum packs dominate export-grade production. Pouches represent the fastest-climbing format as retail channel consolidation favors shelf-ready presentation.
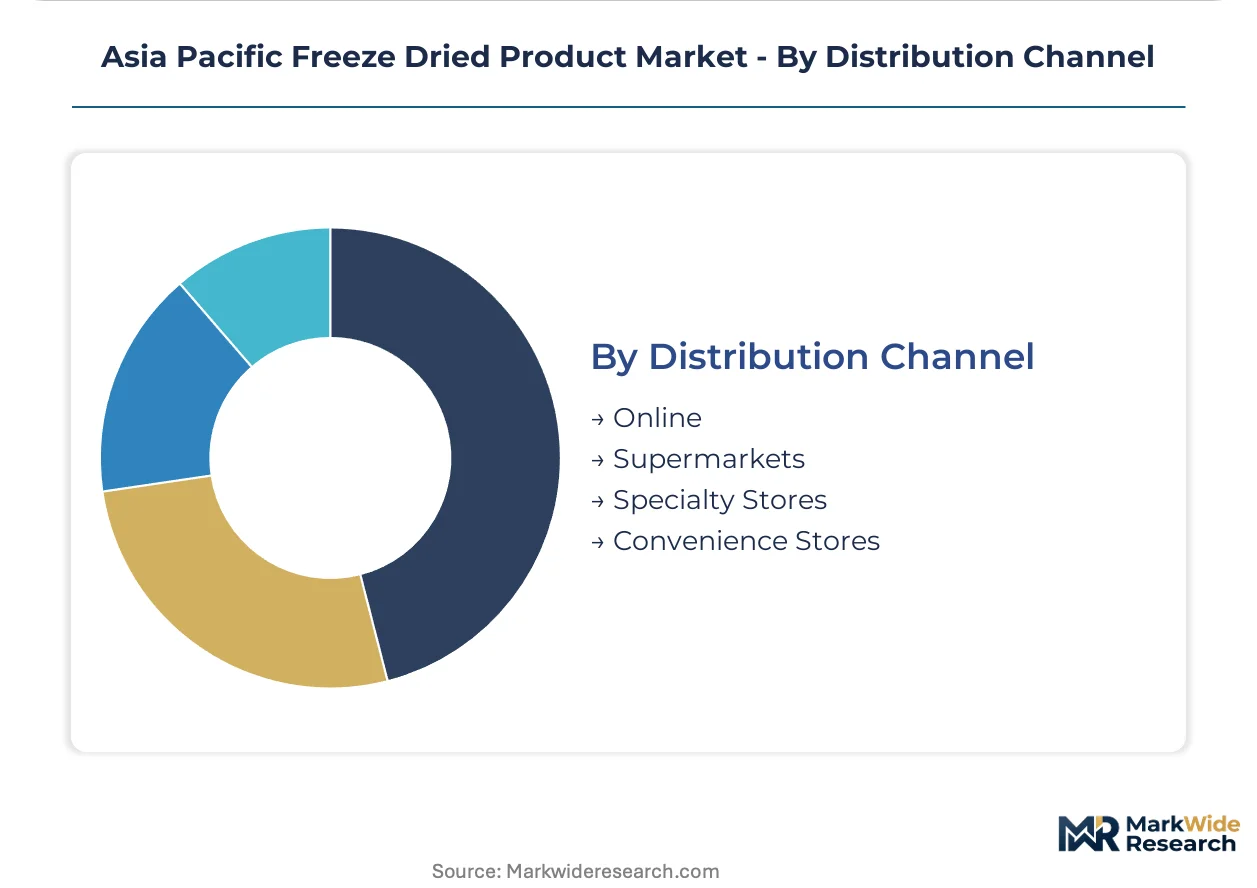
Distribution Channel:
Geographic concentration of digital infrastructure separates online-native markets from traditional retail-dependent segments.
- Online:South Korean and Japanese direct-to-consumer brands leverage last-mile density and mobile payment penetration to compress delivery windows to 24-48 hours. Customer data feedback loops enable rapid flavor and format iteration.
- Convenience Stores:Tokyo and Osaka metropolitan chains consolidate supplier relationships, replacing layered distributor networks with direct sourcing agreements that compress margin pools for intermediaries.
- Supermarkets:Thailand and Australia concentrate premium fruit segment placement with dedicated freeze-dried sections.
- Specialty Stores:Health and wellness positioning supports premium pricing for organic-certified and single-origin product lines.
Convenience stores anchor beverage-adjacent ingredient volumes. Online channels are expanding most quickly as digital infrastructure penetration deepens across Southeast Asian urban centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Freeze-dried processing capacity clusters across Northeast Asian industrial corridors and Southeast Asian export zones, with regulatory divergence between Japan's JIS certification requirements and China's SAMR meat facility inspections forcing dual-track compliance investments.
Japan
Military procurement contracts and convenience retail consolidation anchor demand for long-shelf-life nutrition products. The Ministry of Health, Labour and Welfare enforces additive and labeling standards that constrain imported ingredients without domestic certification. Tokyo and Osaka metropolitan chains now consolidate supplier relationships around beverage-adjacent ingredient portfolios.
China
Domestic food safety implementation rules intensify facility inspection frequency for freeze-dried meat operations under SAMR oversight. SAMR standards reshape product certification requirements for export-bound production. Fujian province concentrates raw fruit sourcing and backward integration by dominant processors.
South Korea
Direct-to-consumer brands leverage mobile payment penetration and last-mile density to compress delivery windows. Military and emergency preparedness procurement anchors institutional volume contracts. Seoul-based digital-native brands bypass traditional wholesale layers, expanding addressable consumer bases through online channels.
Australia
FSANZ nutritional disclosure protocols shape pouch-format retail packaging specifications for cross-border shipments. Military procurement cycles run 18-24 months with stringent shelf-life specifications. Queensland and New South Wales concentrate premium fruit segment placement in dedicated retail sections.
Vietnam
Greenfield freeze-drying investments target European and North American export channels with lower labor and land costs than Northeast Asian bases. Meat drying operations segregate production lines to pursue parallel Japan JIS certification. Ho Chi Minh City industrial zones attract capacity expansion for export-grade vacuum-pack production.
Asia Pacific Freeze Dried Product Market Competitive Landscape
Vertically integrated fruit processors and diversified food conglomerates split the market between captive supply chains and brand-driven distribution networks. Consolidation pressures concentrate around certification-holding facilities capable of multi-market access. Three archetypes dominate: backward-integrated raw material controllers, R&D-intensive formulation specialists, and brand-leveraged convenience retail suppliers. Competitive moves center on dual-certification capacity expansion and direct sourcing agreement consolidation with metropolitan retail chains.
Among Japanese diversified food groups, Ajinomoto Co. Inc. and Asahi Group Holdings Ltd. occupy positions anchored by R&D intensity and convenience retail brand strength respectively. Fujian Lixing Foods Co. Ltd. exemplifies the backward-integrated archetype through upstream control over Fujian province raw fruit sourcing. Campers Pantry Pty Ltd. represents Australian-based specialty positioning in outdoor and emergency preparedness segments.
| Leading Market Players |
|---|
| Fujian Lixing Foods Co. Ltd. |
| Campers Pantry Pty Ltd. |
| Ajinomoto Co. Inc. |
| 3 Seasons Fruit Industry Co. Ltd. |
| The Forager Food Co. |
| Asahi Group Holdings Ltd. |
| Nagatanien Holdings Co. Ltd. |
| Totally Pure Fruits Pty Ltd. |
| Nestle S.A. |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Vietnam-based freeze-drying facilities is compressing spot pricing for export-grade fruit products while simultaneously forcing Japanese and South Korean processors to defend premium positioning through certification bundling and extended shelf-life guarantees.
Pricing Analysis
Aftermarket service revenue for spare parts and technical support drives lifetime value capture for equipment suppliers, though original manufacturer exclusivity is eroding. Pricing stratifies across JIS-certified premium tiers, SAMR-compliant standard tiers, and domestic-only economy tiers. Cost compression in the standard tier is intensifying because Vietnamese contract manufacturers are absorbing margin pressure to secure European retail shelf-space commitments. Direct-to-consumer brands in South Korea exhibit the lowest price sensitivity due to compressed distribution layers, while Southeast Asian export processors face acute sensitivity to vacuum packaging film costs.
Supply Chain Analysis
Contract manufacturing capacity concentrates among Fujian Lixing Foods Co. Ltd., Vietnam-based greenfield operators in Ho Chi Minh City industrial zones, and Thai hybrid thermal system adopters. Raw material supply draws from Fujian province fruit cultivars, Australian meat processing inputs, and Indonesian herb sourcing corridors. Single-source vulnerability in specialized co-extruded vacuum film suppliers based in Japan and South Korea threatens export scaling for Vietnam and Indonesia processors. Distribution runs through direct sourcing agreements with Tokyo and Osaka metropolitan convenience chains, bypassing traditional wholesale layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous microwave-assisted drying technology is disrupting batch-based sublimation economics, compressing capital payback periods and redirecting investment toward integrated processing lines across Thailand and Vietnam.
For Market Incumbents: Pre-empt capacity obsolescence by retrofitting existing lyophilizer installations with hybrid thermal modules that reduce cycle duration. Secure dual JIS and SAMR certification for Vietnam and Indonesia facilities before regulatory divergence hardens into permanent trade barriers. Anchor institutional procurement relationships through multi-year military and emergency preparedness contracts with 18-24 month renewal cycles.
For New Entrants and Emerging Players: Pursue white-space opportunities in umami-enhanced savory formulations for food service and ready-meal applications, where R&D intensity barriers remain lower than established sweet fruit segments. Target Vietnam and Indonesia for greenfield capacity with lower labor and land costs than Northeast Asian bases. Enter through direct-to-consumer online channels in South Korea, leveraging mobile payment penetration and last-mile density to compress customer acquisition costs into digital marketing spend.
For Investors and Strategic Acquirers: Long-term, this sits as a certification-arbitrage play because regulatory divergence between harmonized ASEAN standards and country-specific import protocols creates persistent margin premiums for dual-certified facilities. Acquisition targets should concentrate on Vietnam-based processors with parallel Japan JIS certification and segregated production lines for export-grade meat operations. Monitor SAMR facility inspection frequency and JIS packaging norm revisions as inflection indicators for compliance cost trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | Parallel JIS and SAMR compliance unlocks multi-market access for Vietnam-based meat processors. |
| Hybrid Thermal System Adoption | Continuous microwave-assisted drying reduces cycle duration by 40 percent in Thai commercial installations. |
| Direct Sourcing Consolidation | Tokyo and Osaka convenience chains are replacing layered distributor networks with preferred supplier agreements. |
| Backward Integration into Raw Fruit | Fujian province sourcing control secures supply continuity for dominant processors during peak harvest windows. |
| Online Channel Expansion | South Korean digital-native brands bypass wholesale layers to expand addressable consumer bases through mobile payment penetration. |
Research Methodology
The analysis maps freeze-dried fruits, vegetables, meat, and herbs segments, each validated through production facility managers, retail category buyers at Japanese convenience chains, military procurement officers, and vacuum packaging film suppliers. Primary interviews with these stakeholders combined with secondary validation from customs export records, SAMR food safety implementation filings, JIS standard revision notices, and ASEAN harmonization protocol documents. Bottom-up capacity installation tracking and top-down trade flow analysis provide triangulation across the Asia Pacific region.
Assumptions held fixed include SAMR inspection intensity trajectories, JIS packaging norm stability, and Southeast Asian labor cost differentials versus Northeast Asian bases. Variables tested include continuous microwave-assisted drying adoption rates, direct-to-consumer channel penetration in South Korea and Japan, and European retail shelf-space allocation for Southeast Asian fruit exports. CAGRs derive from segmented volume projections across product type, end user, packaging format, and distribution channel dimensions. Forecast inputs incorporate energy cost sensitivity for sublimation processing and vacuum film supplier concentration constraints.
Sensitivities concentrate around SAMR regulatory enforcement intensity, JIS certification timeline extensions, and European import protocol revisions for freeze-dried fruit products. Forecasts reflect documented assumptions regarding technology migration pace and channel shift velocity. Quarterly review of military procurement contract awards, greenfield capacity announcements in Vietnam and Indonesia, and vacuum packaging film supplier expansion plans is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Asia-Pacific Frozen Yogurt Market
Processed and Frozen Foods
Germany Frozen Snack Market
Processed and Frozen Foods
Freeze Dried Fruit Extract Market
Processed and Frozen Foods
Indonesia Frozen Food Market
Processed and Frozen Foods
Canned Vegetables Market
Processed and Frozen Foods
Kimchi Market
Processed and Frozen Foods
North America Frozen Finger Chips Market
Processed and Frozen Foods
Europe Frozen Desserts Market
Processed and Frozen Foods
Dry Mix Base for Frozen Desserts Market
Processed and Frozen Foods
Europe Freeze-Dried Products Market
Processed and Frozen Foods
Taiyaki Ice Cream Market
Processed and Frozen Foods
Chocolate Ice Cream Market
Processed and Frozen Foods
Frozen Processed Food Market
Processed and Frozen Foods
Freeze Dried Vegetables Market
Processed and Frozen Foods
Bangladesh Frozen Food Market
Processed and Frozen Foods
Frozen Shrimp Market