
 Global Online Food Delivery Services Market | 2026-2036
Global Online Food Delivery Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Online Food Delivery Services Market Foresight
Corporate client concentration is pivoting toward enterprise catering contracts as hybrid work schedules reshape office meal programs. DoorDash leverages its logistics infrastructure to serve Fortune 500 campus contracts, while Meituan anchors urban Chinese markets through superapp integration of food, grocery, and local services. Delivery Hero competes across fragmented European and Latin American markets through localized brand portfolios rather than unified global identity.
Online food delivery services constitute digitally intermediated platforms connecting food preparers with consumers through algorithmic order matching, real-time GPS tracking, and dynamic surge pricing mechanisms. These systems rely on mobile-native architectures, cloud-based kitchen management software, and last-mile routing optimization to coordinate millions of daily transactions across heterogeneous restaurant networks. Restaurant aggregators occupy the largest value pool by capturing commission fees from high-frequency independent operators with limited digital capability, while subscription-based services are generating recurring revenue streams through membership programs that reduce per-order delivery costs for habitual users. Platform type segmentation reveals mobile applications dominating transaction volume, though smart device integration through connected car and home systems represents an emerging interface category.
FDA food safety guidelines, EU GDPR data protection frameworks, and China's SAMR antitrust oversight collectively shape operational compliance burdens across major markets. India's FSSAI licensing requirements impose hygiene certification standards on cloud kitchen operators, while the EU AI Act begins constraining algorithmic pricing and rider dispatch systems. Stakeholders must monitor regulatory divergence between data localization mandates and cross-border platform interoperability standards.
Market Dynamics
Hybrid work normalization is fragmenting demand patterns across enterprise catering contracts, forcing platform operators to rebuild logistics networks around intermittent office occupancy rather than predictable downtown density.
Growth Catalysts
- Superapp bundling:Urban Indian consumers are consolidating food, grocery, and mobility services within single-platform ecosystems, reducing customer acquisition costs through cross-service data integration.
- EU Green Deal packaging mandates:Compulsory shifts toward compostable containers and reusable delivery systems are creating premium service tiers that capture sustainability-conscious urban households.
- Cloud kitchen proliferation:FSSAI-licensed delivery-only facilities are expanding kitchen capacity without real estate constraints in dense Indian metros.
Market Restraints
- Rider classification litigation:European labor courts are reclassifying gig workers as employees, inflating unit economics across Berlin, Madrid, and Paris operations.
- Input cost volatility:Petroleum-linked delivery fees fluctuate with crude price swings, compressing margins on low-ticket orders in fuel-importing economies.
- Algorithmic pricing constraints:EU AI Act provisions are limiting dynamic surge mechanisms, capping revenue optimization during peak demand windows.
Strategic Opportunities
- Corporate catering white space:Fortune 500 hybrid work programs in the United States present underpenetrated contract catering volumes requiring dedicated campus logistics infrastructure.
- Smart home integration:Voice-activated ordering through connected kitchen appliances and in-vehicle systems is opening frictionless transaction channels beyond mobile applications.
- Reusable packaging subsidies:EU member state incentive programs for returnable container systems are creating cost-advantaged circular delivery models.
Industry Challenges
- Data localization compliance:India's proposed data protection framework requires server infrastructure migration, imposing capital intensity on foreign platform operators.
- Cross-border payment fragmentation:Divergent digital wallet standards between India, China, and European markets complicate unified payment architecture deployment.
- Antitrust enforcement divergence:SAMR, FTC, and European Commission investigations into platform fees are forcing jurisdiction-specific pricing structures that erode operational leverage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Online Food Delivery Services Market |
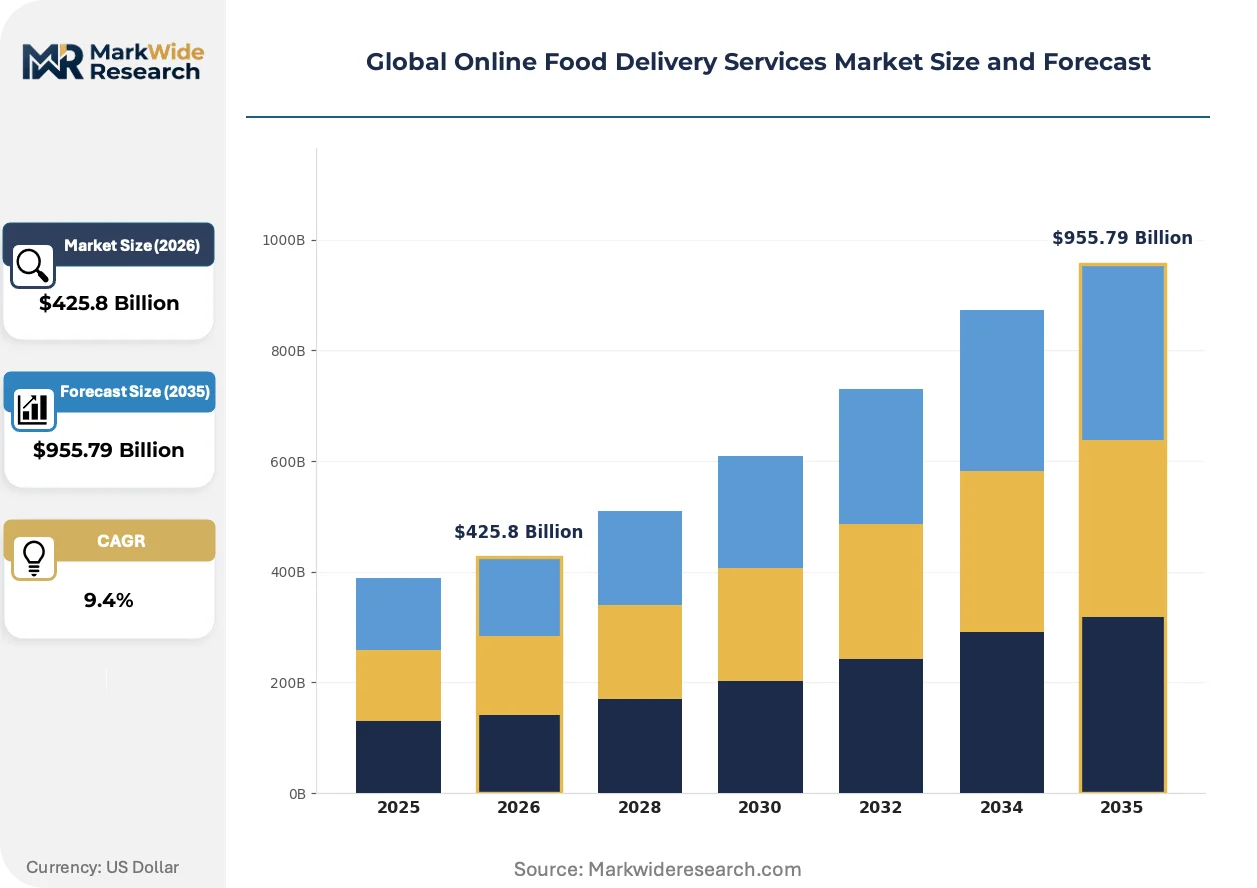
| Market Size in 2026 | $425.8 Billion |
| Market Size in 2035 | $955.79 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Restaurant Aggregators, Standalone Delivery, Hybrid Models, Subscription-based Services, Meal Kits Platform Type: Mobile Application, Website Portal, Social Media Integration, Smart Device Integration, Voice-enabled Ordering Customer Type: Individual Consumers, Corporate Clients, Event Planners, Educational Institutions, Healthcare Facilities Payment Method: Credit/Debit Cards, Digital Wallets, Cash on Delivery, Bank Transfers, Buy Now Pay Later |
| Companies Covered | DoorDash, Uber Eats, Delivery Hero, Zomato, Grab Holdings, Just Eat Takeaway, Meituan, Deliveroo, Swiggy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Online Food Delivery Services Market Shifts & Advancements
Artificial intelligence is penetrating dispatch and demand forecasting systems, compressing delivery windows while regulatory pressure on algorithmic decision-making intensifies across major jurisdictions.
Machine learning route optimization is absorbing real-time traffic, weather, and kitchen preparation data to synchronize rider arrival with order completion. Enterprise clients with campus contracts are demanding sub-25-minute guarantees that legacy heuristic dispatch systems cannot fulfill. This compression is absorbing mid-market aggregators into specialized logistics partnerships or proprietary fleet investments.
EU AI Act algorithmic transparency requirements are forcing disclosure of rider dispatch logic and surge pricing parameters. Platform operators must now maintain auditable decision trails for automated systems affecting worker income. Cloud kitchen operators in Germany and France are restructuring pricing engines to demonstrate non-discriminatory geographic coverage before national regulators.
Subscription membership models are displacing per-transaction purchasing among habitual users in dense urban corridors. Monthly fee structures bundle reduced delivery charges with priority restaurant access, locking in predictable revenue streams. This shift concentrates most visible in Indian superapp ecosystems where food delivery anchors multi-service retention strategies.
Global Online Food Delivery Services Market Segmentation
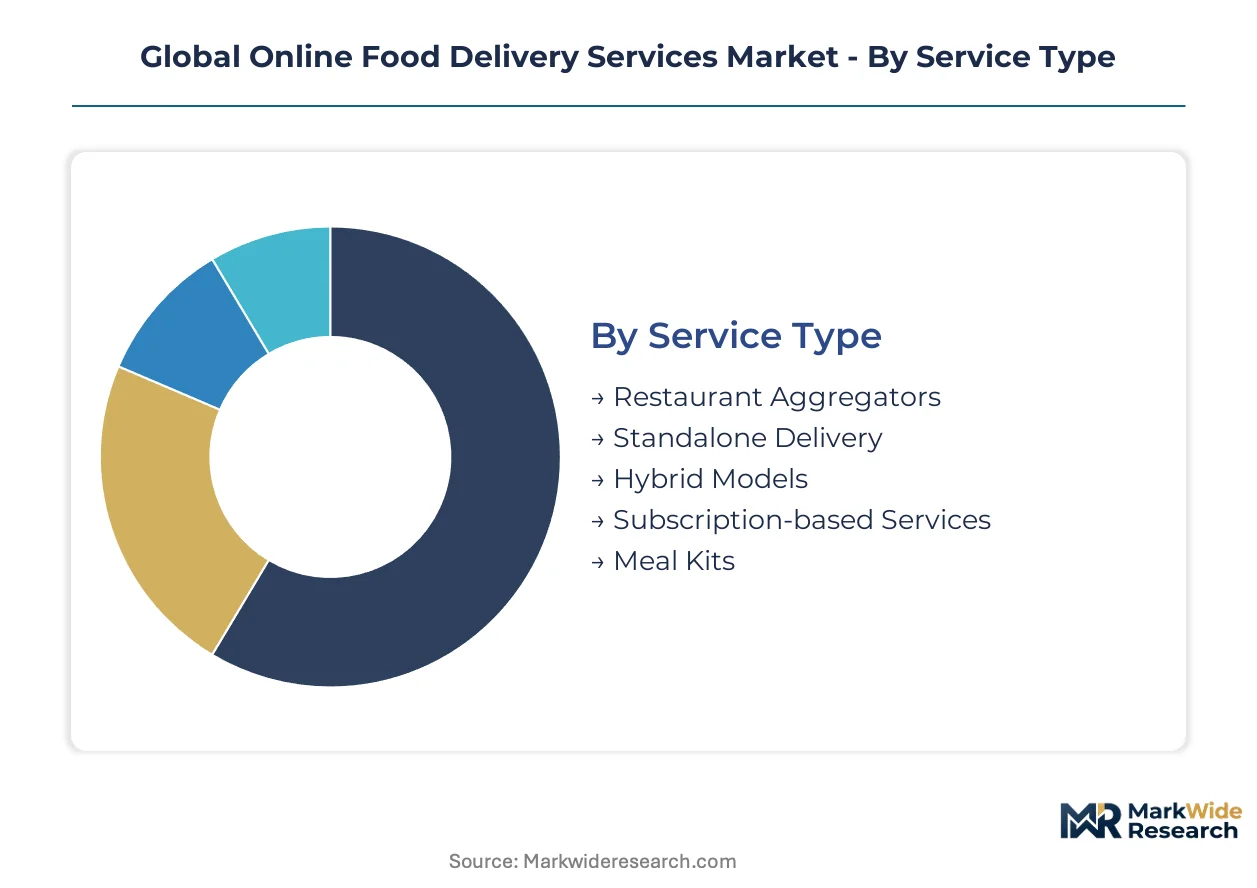
Segmentation reveals how capital deployment varies across service architectures and interface technologies. Platform operators allocate resources differently between logistics-heavy fulfillment models and software-centric aggregation plays.
Service Type:
Capital intensity peaks in segments requiring proprietary fleet infrastructure and kitchen real estate.
- Restaurant Aggregators:Asset-light platforms match independent restaurants with consumers through algorithmic order routing. Commission-based revenue concentrates in dense Indian and Chinese urban corridors where restaurant digitalization lags consumer smartphone penetration.
- Standalone Delivery:Proprietary logistics networks require substantial vehicle fleet investment and rider workforce scaling. European labor reclassification rulings in Germany, Spain, and France are inflating unit economics for operators maintaining dedicated delivery personnel.
- Hybrid Models:Blend third-party restaurant access with captive kitchen capacity, demanding selective real estate commitments.
- Subscription-based Services:Recurring revenue structures reduce per-order customer acquisition costs through membership lock-in.
- Meal Kits:Pre-portioned ingredient logistics require cold-chain fulfillment infrastructure and inventory forecasting systems.
Most installed capacity flows through Restaurant Aggregators. Expansion is steepest in Subscription-based Services.
Platform Type:
Interface development costs scale with hardware integration complexity and ecosystem partnership requirements.
- Mobile Application:Native iOS and Android architectures dominate transaction volume through GPS-enabled location services and push notification engagement. Indian superapp ecosystems bundle food delivery with grocery and mobility within single mobile interfaces, amortizing development costs across service verticals.
- Smart Device Integration:Connected car dashboards and smart home appliances enable frictionless reordering through embedded APIs. Automotive OEM partnerships with German and Japanese manufacturers are opening in-vehicle transaction channels beyond handheld screens.
- Website Portal:Browser-based ordering retains corporate catering procurement workflows requiring desktop invoice management.
- Social Media Integration:In-app purchasing through content platforms reduces discovery friction for impulse-driven meal decisions.
- Voice-enabled Ordering:Natural language processing integration demands ongoing AI training investment for accent and dialect coverage.
Mobile Application captures the dominant transaction share. Smart Device Integration is climbing the fastest as automotive and appliance OEMs open APIs.
Customer Type:
Sales cycle length and contract value vary sharply between individual and institutional procurement patterns.
- Individual Consumers:High-frequency, low-ticket transactions drive volume economics through habit formation and loyalty program retention. Urban Indian and Chinese middle-class density supports superapp cross-selling between food, grocery, and transport services.
- Corporate Clients:Enterprise catering contracts with Fortune 500 hybrid work programs require dedicated campus logistics infrastructure and sub-25-minute delivery guarantees. DoorDash has built specialized fulfillment networks for intermittent office occupancy patterns across US metropolitan areas.
- Event Planners:Large-batch scheduling demands temporary kitchen capacity scaling and coordinated timing precision.
- Educational Institutions:Semester-long contracts with student dining programs require allergen compliance and nutritional disclosure systems.
- Healthcare Facilities:Patient meal delivery imposes FDA food safety guidelines and temperature-controlled transport protocols.
Individual Consumers generate the highest transaction velocity. Corporate Clients are gaining share fastest as hybrid work normalizes across enterprise accounts.
Payment Method:
Integration costs reflect regional financial infrastructure fragmentation and regulatory compliance burdens.
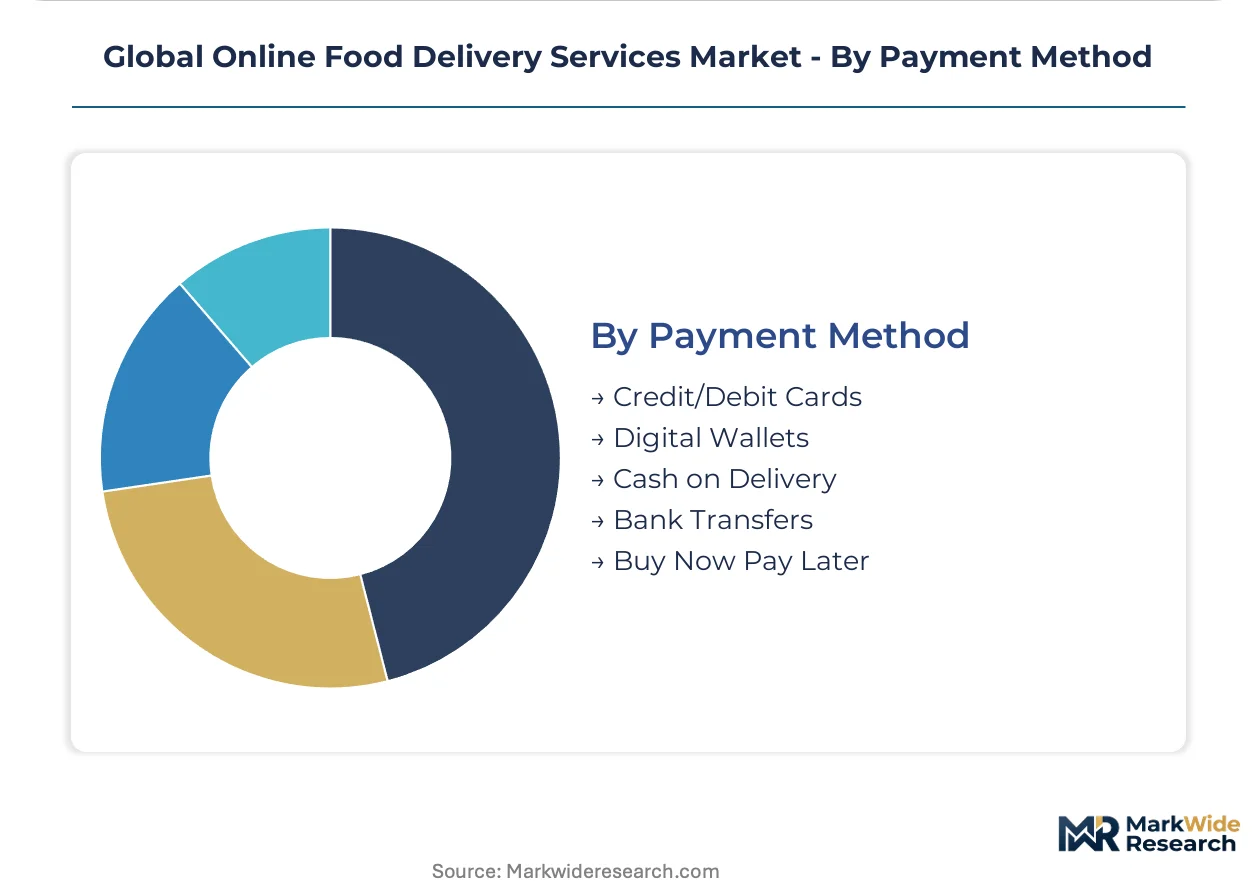
- Digital Wallets:Closed-loop payment ecosystems dominate in India through UPI infrastructure and in China via Alipay and WeChat Pay. Cross-border platform operators face data localization requirements under India's proposed data protection framework, forcing server infrastructure migration for transaction processing.
- Credit/Debit Cards:Interchange fee structures vary across European, US, and Asian markets, requiring jurisdiction-specific pricing optimization.
- Cash on Delivery:Remains prevalent in underbanked segments and markets with low card penetration.
- Bank Transfers:Direct account debiting appeals to corporate procurement departments requiring audit trails.
- Buy Now Pay Later:Embedded credit products require lending license compliance and consumer protection disclosures.
Digital Wallets process the dominant transaction volume. Buy Now Pay Later is expanding most quickly among younger demographic cohorts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's superapp ecosystems bundle food delivery with grocery and mobility services, while Germany's EU Green Deal compliance costs reshape platform economics through reusable packaging mandates and rider reclassification rulings.
United States
Fortune 500 hybrid work programs are fragmenting demand patterns across intermittent office occupancy, forcing dedicated campus logistics infrastructure. FDA food safety guidelines impose temperature-controlled transport protocols on healthcare and corporate catering contracts. DoorDash has built specialized fulfillment networks across metropolitan areas to serve intermittent downtown density.
China
Urban middle-class density and smartphone penetration anchor superapp integration of food, grocery, and local services. SAMR antitrust oversight constrains platform fee structures and merchant exclusivity arrangements. Meituan anchors demand concentration through algorithmic order matching and real-time GPS tracking across dense urban corridors.
Germany
EU AI Act provisions are limiting dynamic surge pricing mechanisms and forcing auditable decision trails for automated dispatch systems. ECHA chemical safety standards and EU Green Deal packaging directives mandate compostable containers and reusable delivery systems. Berlin and Munich operations face inflated unit economics from labor court reclassifications of gig workers as employees.
India
FSSAI licensing requirements impose hygiene certification standards on cloud kitchen operators expanding kitchen capacity without real estate constraints. The proposed data protection framework requires server infrastructure migration, imposing capital intensity on foreign platform operators. Mumbai and Bangalore superapp ecosystems reduce customer acquisition costs through cross-service data integration between food, grocery, and transport verticals.
Brazil
Underbanked segments sustain cash-on-delivery prevalence alongside digital wallet expansion through PIX infrastructure. ANVISA food safety regulations govern temperature-controlled transport for prepared meal logistics. São Paulo and Rio de Janeiro concentrate platform operator investment in last-mile routing optimization and cloud kitchen proliferation.
Global Online Food Delivery Services Market Competitive Landscape
US-based platforms anchor one tier; European specialists hold fragmented market positions across localized brand portfolios. The vendor base splits between logistics-heavy proprietary fleet operators and asset-light algorithmic aggregators. Three archetypes dominate: superapp ecosystems bundling multiple services, restaurant aggregators capturing commission fees from independent operators, and subscription-based platforms generating recurring revenue through membership lock-in. Dominant competitive moves include geographic expansion through acquisition and technology licensing for dispatch optimization.
Among US-based operators, DoorDash and Uber Eats represent the logistics-intensive archetype with dedicated fleet infrastructure, while Delivery Hero exemplifies the European multi-brand portfolio strategy across fragmented markets. Meituan occupies a position within the superapp ecosystem tier, anchoring multi-service retention through cross-vertical data integration. These three companies illustrate the strategic divergence between asset-heavy fulfillment networks and software-centric aggregation plays.
| Leading Market Players |
|---|
| DoorDash |
| Uber Eats |
| Delivery Hero |
| Zomato |
| Grab Holdings |
| Just Eat Takeaway |
| Meituan |
| Deliveroo |
| Swiggy |
| Others |
Supply & Pricing Matrix
Rider wage inflation in European metros flows through to per-order delivery fees, compressing margins on economy-tier transactions while subscription premiums absorb cost escalation in habitual-user segments. Petroleum-linked fuel surcharges fluctuate with crude price swings, forcing platform operators to tier service levels around delivery speed guarantees rather than flat-rate pricing.
Pricing Analysis
Capacity additions in India's cloud kitchen corridors are reshaping price floors for aggregator commissions, squeezing independent restaurant margins while subscription-based services lock in recurring revenue through membership lock-in. Price differentiation hinges on delivery velocity tiers and FSSAI hygiene certification grades, with sustainability-conscious urban households paying premiums for EU Green Deal-compliant compostable packaging. Pricing pressure stems from SAMR and EU AI Act constraints on algorithmic surge mechanisms, capping peak-window revenue optimization. Individual consumers in dense urban corridors exhibit highest price sensitivity, while Fortune 500 corporate catering contracts demonstrate lowest sensitivity due to dedicated campus logistics requirements.
Supply Chain Analysis
Reusable container return flows through EU member state incentive programs are creating circular logistics networks that reverse last-mile distribution patterns. Kitchen equipment manufacturing concentrates in China, Germany, and Italy, while cold-chain packaging materials draw from South Korean and Japanese specialty chemical suppliers. Supply chain risk centers on single-source vulnerability for GPS-enabled dispatch hardware amid semiconductor allocation constraints. Distribution runs through cloud kitchen clusters in Mumbai, São Paulo, and Berlin, with rider fleet scaling determining effective coverage radius.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in online food delivery rests on subscription membership penetration and cloud kitchen density economics, with automation in dispatch systems compressing per-order fulfillment costs. Premium-tier shifts toward corporate catering and sustainability-certified services are capturing price-inelastic demand segments.
For Market Incumbents: To counter SAMR and EU AI Act algorithmic pricing constraints, incumbents should deepen proprietary fleet infrastructure in Fortune 500 campus corridors and secure FSSAI cloud kitchen certifications ahead of capacity expansion. Channel control through superapp data integration anchors multi-service retention against disaggregation threats. For New Entrants and Emerging Players: Smart home appliance APIs offer frictionless entry points beyond saturated mobile application markets, with voice-enabled ordering through connected kitchen devices representing the most penetrable interface layer. Corporate catering white space in hybrid work programs presents underexploited contract volumes requiring sub-25-minute guarantee capabilities. For Investors and Strategic Acquirers: Roll-up economics work for regional restaurant aggregators because EU labor reclassification rulings are forcing smaller operators toward exit, consolidating commission-based revenue pools. Long-term viability hinges on subscription membership attach rates as the inflection indicator; practitioners should monitor cross-service retention metrics and cloud kitchen utilization rates for early signals.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Kitchen Capacity Expansion | FSSAI-licensed delivery-only facilities bypass real estate constraints in dense Indian metros. |
| Superapp Service Integration | Cross-vertical bundling reduces customer acquisition costs through shared data infrastructure. |
| Corporate Catering Infrastructure | Dedicated campus logistics capture Fortune 500 hybrid work program contract volumes. |
| Reusable Packaging Systems | EU member state subsidies create cost-advantaged circular delivery models. |
| Smart Device API Partnerships | Automotive OEM integrations open frictionless transaction channels beyond mobile screens. |
Research Methodology
Multiple input streams — executive interviews with platform operations directors, regulatory affairs specialists at cloud kitchen operators, and corporate procurement managers — were reconciled against customs data on kitchen equipment imports, FSSAI licensing databases, and EU AI Act implementation guidance. Secondary validation drew from SEC filings of listed aggregators, UPI transaction volume reports, and automotive OEM partnership announcements. Bottom-up cloud kitchen capacity estimates and top-down addressable urban household projections were triangulated.
Data-stream reconciliation across service type, platform interface, and customer archetype dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from modeled subscription penetration curves and corporate catering contract velocity. Forecast inputs incorporated EU Green Deal packaging mandate compliance costs and SAMR antitrust fee-structure constraints.
Labor reclassification rulings, petroleum price volatility, and data localization enforcement are the dominant revision risks to modeled unit economics. Forecasts reflect assumptions on rider workforce scaling and cloud kitchen utilization thresholds. Practitioners should monitor regulatory enforcement intensity and crude price movements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Healthy Takeout Market
Food Service
A La Carte Market
Food Service
Saudi Arabia Foodservice Market
Food Service
India Online Grocery Market
Food Service
Instant Noodle Vending Machine Market
Food Service
Supermarkets Market
Food Service
Europe Food Cold Chain Logistics Market
Food Service
Fast Food Market
Food Service
Saudi Arabia Pizza Restaurants Market
Food Service
Commercial Ice Dispenser Market
Food Service
Sandwich Toasters Market
Food Service
Germany Foodservice Market
Food Service
Takeout Dinner Market
Food Service
Turkey Retail Bubble Tea Kits Market
Food Service
Latin America Inflight Catering Market
Food Service
Commercial Beverage Dispenser Market