
 India Retail Bubble Tea Kits Market | 2026-2036
India Retail Bubble Tea Kits Market Size, Share, and Industry Trends Forecast 2026-2036
India Retail Bubble Tea Kits Market Insights
Online retail distribution is narrowing as the primary growth vector for India retail bubble tea kits, with quick-commerce platforms and direct-to-consumer storefronts capturing urban households seeking convenience. Frozen Bottle leverages its established cold-beverage infrastructure to anchor kit visibility in Tier-1 cities. The Tea Planet competes through flavor innovation and localized sourcing. Boba Bhai Pvt Ltd dominates the Mumbai-Bengaluru corridor with hyperlocal delivery partnerships.
India retail bubble tea kits comprise pre-portioned tapioca pearls, tea bases, syrups, and preparation accessories designed for domestic kitchen assembly, typically requiring boiling water and five to ten minutes of active preparation time. The product serves consumers seeking café-style beverage experiences without outlet dependency. Milk tea kits occupy the largest volume share due to familiarity with masala chai palates, while fruit kits represent the fastest-growing category as tropical flavor profiles gain traction among younger buyers. Specialty stores and online retail together capture the most attractive margin pools by combining experiential sampling with subscription-based repeat purchases.
FSSAI labeling mandates and state-level food safety inspections shape product formulation and packaging transparency requirements for all market participants. BIS certification for food-grade plastics influences straw and cup accessory sourcing decisions among kit assemblers. Stakeholders must monitor evolving e-commerce regulations under the Consumer Protection Act and emerging plastic-waste rules in Maharashtra and Karnataka that could reshape disposable component strategies.
Market Dynamics
Quick-commerce platforms and direct-to-consumer storefronts are compressing traditional retail margins while FSSAI labeling mandates force reformulation investments across kit assemblers. This dual pressure from distribution transformation and regulatory compliance defines current competitive positioning.
Growth Catalysts
- FSSAI food safety norms:Mandatory labeling transparency is accelerating premium kit adoption as consumers trust certified domestic assembly over unregulated imports.
- Mumbai-Bengaluru corridor concentration:Metro density and premium grocery retail expansion in Maharashtra and Karnataka create concentrated consumption zones with established cold-chain infrastructure.
- Quick-commerce logistics:Swiggy Instamart and Zepto delivery networks are collapsing the time-to-preparation gap for impulse-driven kit purchases.
Market Restraints
- Tapioca pearl import dependency:Cassava starch supply concentrates in Southeast Asian processing facilities, exposing assemblers to shipping cost volatility and currency fluctuation.
- BIS food-grade plastic certification:Straw and cup accessory sourcing faces extended approval timelines that delay product launches by 8-12 weeks.
- Masala chai substitution:Established tea preparation rituals in Tier-2 and Tier-3 cities limit kit penetration where café-style beverage habits remain underdeveloped.
Strategic Opportunities
- Telangana and Tamil Nadu expansion:Hyderabad and Chennai metro networks lack dedicated bubble tea kit distribution, presenting first-mover advantages for quick-commerce partnerships.
- Subscription-based repeat purchases:Monthly flavor curation models lock in customer lifetime value while reducing customer acquisition costs for direct-to-consumer brands.
- PLI scheme for food processing:Central government production-linked incentives could offset domestic tapioca pearl manufacturing investments currently uneconomical at small scale.
Industry Challenges
- Cold-chain integration complexity:Maintaining frozen pearl integrity through last-mile delivery requires temperature-controlled partnerships that quick-commerce platforms struggle to guarantee consistently.
- Flavor formulation talent scarcity:Food technologists with expertise in tropical fruit syrup stabilization and tea base extraction command premium salaries that strain emerging kit assemblers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Retail Bubble Tea Kits Market |
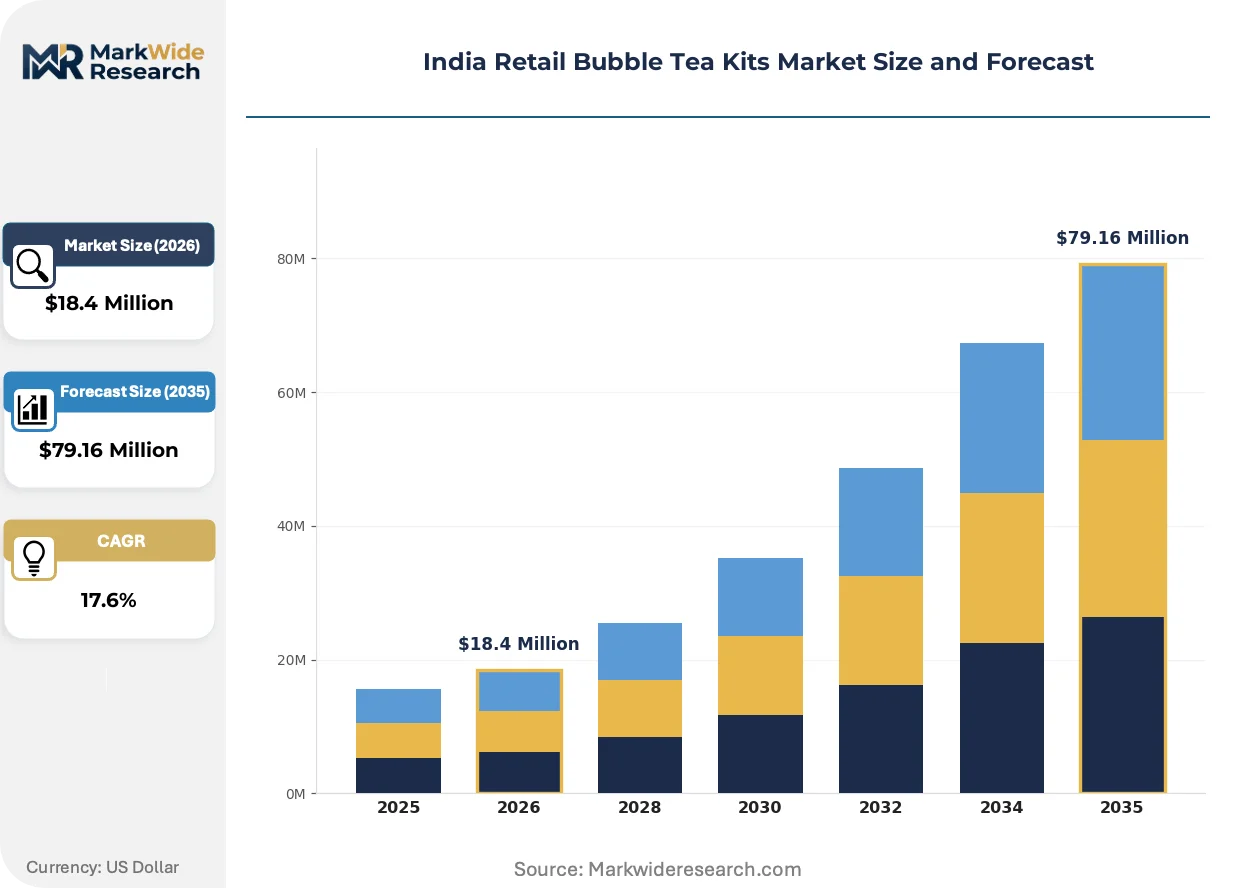
| Market Size in 2026 | $18.4 Million |
| Market Size in 2035 | $79.16 Million |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Classic Kits, Fruit Kits, Milk Tea Kits, Foam Kits Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Convenience Stores Customer Type: Millennials, Families, Students, Professionals Price Tier: Value, Mid-range, Premium, Luxury |
| Companies Covered | Frozen Bottle, The Tea Planet, Bubble Tea House Company, Chatime, Gong Cha Global Limited, Bubble Tea Supply Inc, Easy Boba, Ten Ren's Tea Time, Boba Bhai Pvt Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Retail Bubble Tea Kits Market Trends and Innovations
Domestic kitchen assembly is shifting from novelty to habitual consumption as younger buyers reject outlet dependency. Three converging forces—packaging technology, regulatory transparency mandates, and channel fragmentation—are redefining how kits reach Indian households.
Modified atmosphere packaging for tapioca pearls is collapsing the shelf-life gap between frozen and room-temperature storage. Tier-1 urban households are adopting these extended-life kits for unplanned consumption. This technology is collapsing the inventory risk that previously constrained retail shelf placement for perishable components.
FSSAI's evolving labeling mandates now require granular disclosure of artificial sweetener content and preservative thresholds. Kit assemblers reformulating for clean-label positioning gain preferential placement in premium grocery retail. Maharashtra and Karnataka state-level food safety inspections are driving consolidation among smaller unbranded competitors unable to absorb compliance costs.
Swiggy Instamart and Zepto shoppers now expect 10-minute delivery windows for beverage kits previously planned as weekly grocery purchases. Quick-commerce platforms are disintermediating traditional kirana stores and modern trade for impulse-driven kit sales. This behavior shift concentrates most visibly in Mumbai and Bengaluru where metro density supports viable unit economics for rapid fulfillment.
India Retail Bubble Tea Kits Market Segmentation
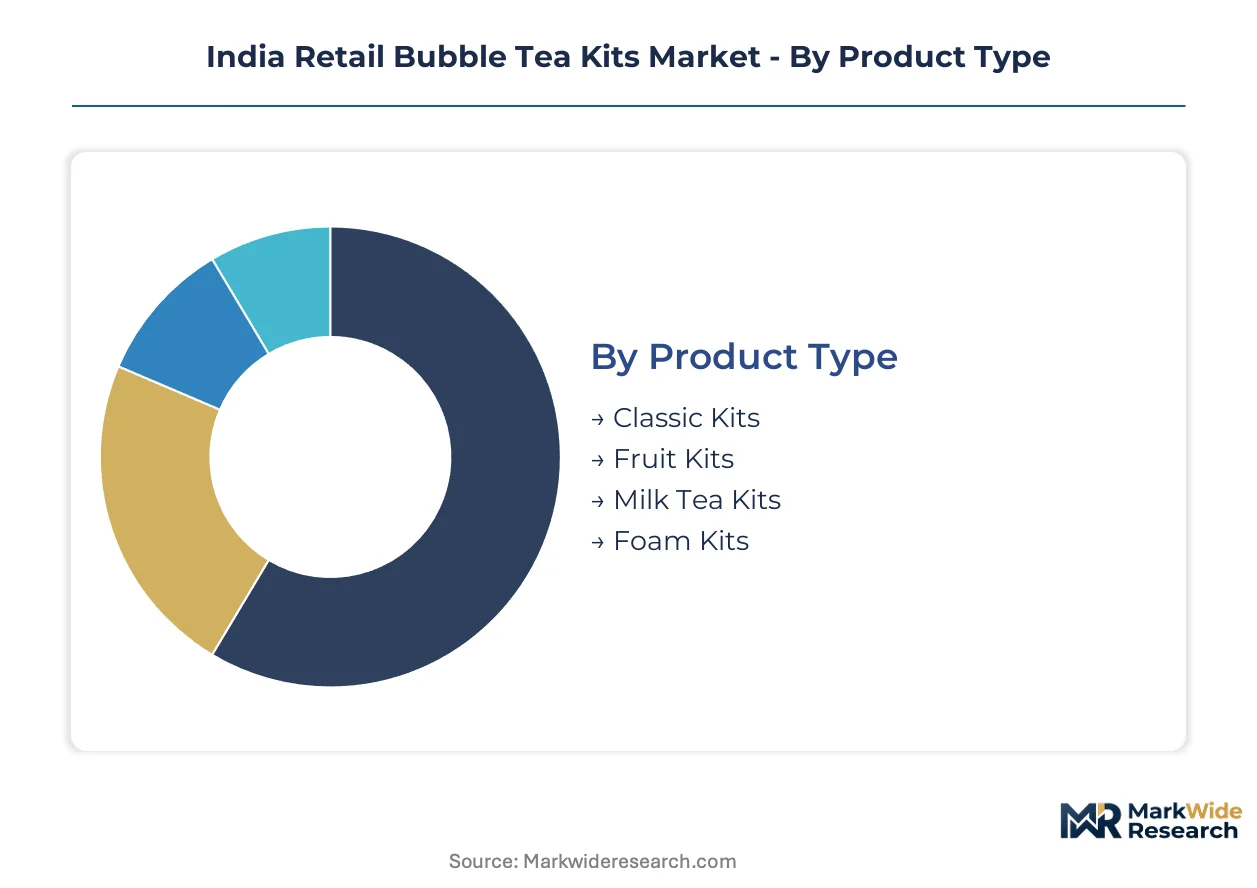
Segmentation in the India retail bubble tea kits market reveals distinct consumption velocities across product formats and buyer profiles. Understanding these turnover patterns enables assemblers to align inventory depth with actual consumption cadence rather than treating all segments uniformly.
Product Type:
Cycle times vary dramatically across kit formats, with perishable components and flavor novelty driving replenishment frequency differences of 3-5x between fastest and slowest-turning categories.
- Milk Tea Kits:These kits combine black tea bases with non-dairy creamer sachets and pre-sweetened tapioca pearls calibrated for masala chai-adjacent palates. Demand concentrates in Mumbai and Bengaluru apartment clusters where working professionals replicate café routines during evening wind-down hours.
- Fruit Kits:Tropical flavor profiles—mango, passionfruit, lychee—dominate these assemblies with stabilized syrup pouches and color-matched pearl variants. Younger buyers in Hyderabad and Chennai metro corridors are driving the steepest expansion trajectory as these kits displace conventional juice preparations.
- Classic Kits:Traditional Taiwanese-style formulations with unflavored pearls and raw sugar syrups serve purist consumers seeking authenticity.
- Foam Kits:Cheese foam and salted cream topping sachets add preparation complexity for experience-seeking households.
Milk tea kits dominate installed base. Fruit kits are where expansion concentrates.
Distribution Channel:
Margin capture and customer acquisition economics diverge sharply across channels, with digital-native routes commanding 2-3x the lifetime value of physical retail despite higher front-end logistics costs.
- Online Retail:Direct-to-consumer storefronts and quick-commerce platforms collapse delivery windows to under 30 minutes for impulse purchases. Swiggy Instamart and Zepto partnerships in Maharashtra and Karnataka generate the highest repeat rates through subscription bundling.
- Specialty Stores:Experiential retail formats in Bengaluru's Indiranagar and Mumbai's Bandra West combine sampling stations with flavor customization counters. Premium positioning here supports 40-60% gross margins through assisted selling.
- Supermarkets:Modern trade chains in Tier-1 cities provide shelf visibility for trial purchases but struggle with pearl inventory turnover.
- Convenience Stores:Kirana penetration remains minimal due to cold-chain requirements and low basket compatibility.
Online retail dominates installed base. Specialty stores are where expansion concentrates.
Customer Type:
Preparation time tolerance and flavor experimentation appetite create distinct service requirements across demographic cohorts.
- Millennials:Urban millennials aged 28-38 treat kit assembly as social ritual, purchasing multi-flavor variety packs for weekend entertaining. Instagram-worthy presentation drives premium tier willingness.
- Students:Hostel-dwelling university populations in Pune and Bengaluru prioritize single-serve sachet formats with minimal equipment requirements.
- Families:Households with children favor larger-format kits with simplified preparation instructions and allergen-transparent labeling mandated by FSSAI disclosure rules.
- Professionals:Time-constrained corporate workers in Mumbai's BKC and Bengaluru's Whitefield favor 10-minute preparation guarantees with pre-portioned components.
Millennials dominate installed base. Students are where expansion concentrates.
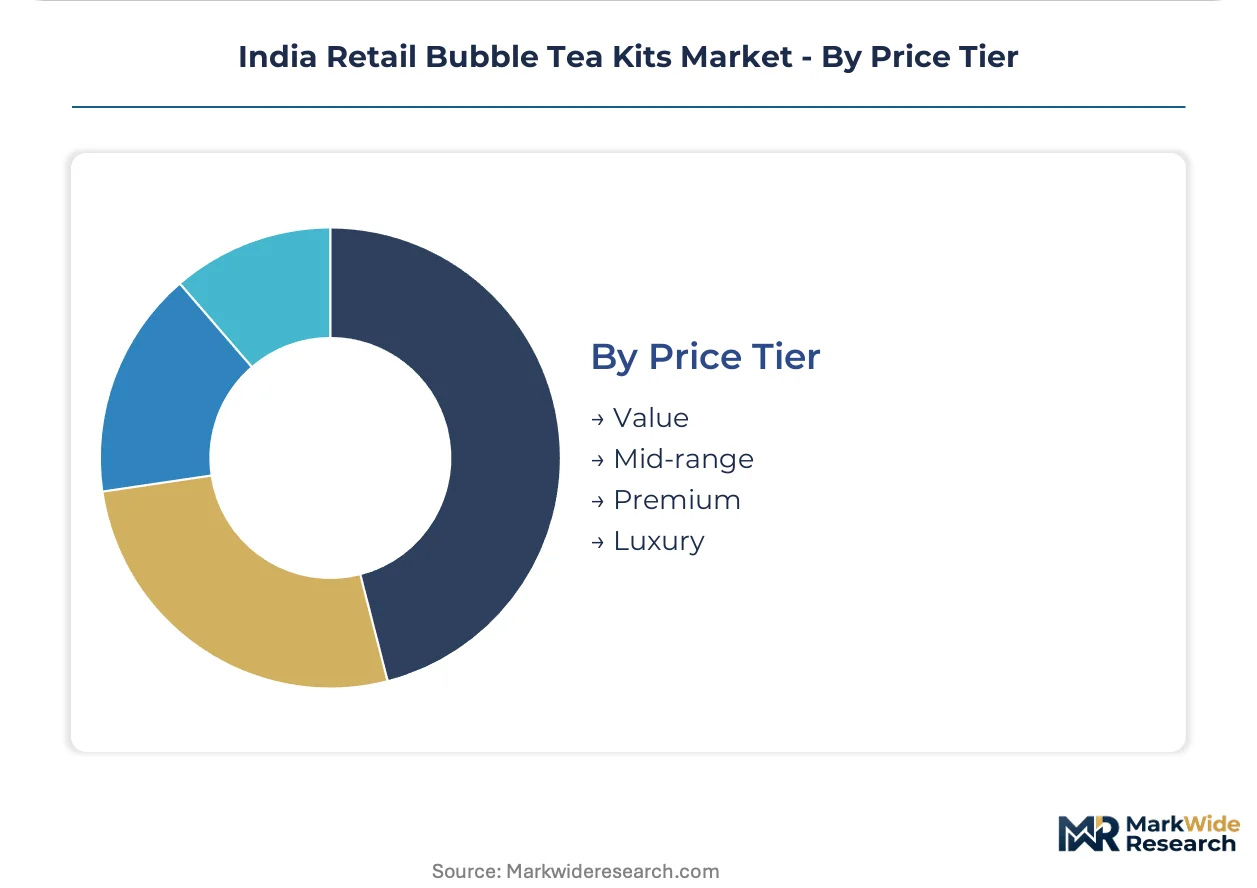
Price Tier:
Raw material sourcing transparency and certification depth create four distinct value propositions with minimal crossover purchasing between adjacent tiers.
- Premium:Organic tea bases, natural fruit extracts, and BIS-certified food-grade accessories command shelf space in Nature's Basket and Foodhall formats. Clean-label positioning aligns with FSSAI's evolving artificial sweetener disclosure mandates.
- Mid-range:Standardized flavor portfolios with conventional stabilizers serve the bulk of quick-commerce volume through Swiggy Instamart and Blinkit partnerships.
- Value:Price-optimized kits with synthetic flavoring and basic polyethylene straws penetrate Tier-2 cities through local kirana networks with limited cold-chain investment.
- Luxury:Limited-edition collaborations with regional tea estates and imported Taiwanese pearl variants target gift-giving occasions in Delhi NCR and Mumbai luxury retail.
Mid-range dominates installed base. Premium is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FSSAI labeling mandates and Maharashtra's enforcement infrastructure anchor kit demand concentration in western India, with state-level food safety inspections driving consolidation among compliant assemblers.
Maharashtra
Mumbai's apartment density and premium grocery retail expansion generate concentrated consumption zones for milk tea kits. FSSAI's artificial sweetener disclosure rules force reformulation investments among local assemblers. Bandra West and Lower Parel clusters host experiential sampling formats that lock in repeat purchases through subscription bundling.
Karnataka
Bengaluru's tech corridor professionals favor ten-minute preparation guarantees with pre-portioned components. BIS food-grade plastic certification delays product launches by 8-12 weeks for straw and cup accessory sourcing. Indiranagar and Whitefield retail clusters combine assisted selling with flavor customization counters capturing 40-60% gross margins.
Telangana
Hyderabad metro networks lack dedicated bubble tea kit distribution, presenting first-mover advantages for quick-commerce partnerships. PLI scheme for food processing could offset domestic tapioca pearl manufacturing investments currently uneconomical at small scale. Hitech City and Gachibowli corporate corridors show emerging demand for single-serve sachet formats.
Tamil Nadu
Chennai's younger buyers drive steepest expansion trajectory for tropical fruit kits displacing conventional juice preparations. State-level food safety inspections under FSSAI norms reshape disposable component strategies for local assemblers. T. Nagar and Anna Nagar retail clusters remain underpenetrated for experiential kit formats.
Delhi-NCR
Gift-giving occasions in luxury retail segments attract limited-edition collaborations with regional tea estates. DGFT import regulations expose assemblers to shipping cost volatility for cassava starch supply concentrated in Southeast Asian processing facilities. South Delhi and Gurgaon premium grocery formats show nascent adoption of clean-label positioning.
India Retail Bubble Tea Kits Market Competitive Landscape
Established beverage infrastructure players and direct-to-consumer specialists split the market between physical retail anchoring and digital-native acquisition. Three strategic archetypes dominate: cold-beverage chain extenders leveraging existing store networks, flavor innovation laboratories emphasizing localized sourcing, and hyperlocal delivery integrators collapsing fulfillment windows. Dominant competitive moves include quick-commerce platform partnerships and FSSAI compliance-driven portfolio consolidation.
Among cold-beverage infrastructure extenders, Frozen Bottle occupies a position exemplifying Tier-1 city visibility through established retail footprints. The Tea Planet sits within the flavor innovation tier, representing archetypal competition through product differentiation. Boba Bhai Pvt Ltd anchors the hyperlocal delivery integrator segment, exemplifying Mumbai-Bengaluru corridor concentration through platform partnerships.
| Leading Market Players |
|---|
| Frozen Bottle |
| The Tea Planet |
| Bubble Tea House Company |
| Chatime |
| Gong Cha Global Limited |
| Bubble Tea Supply Inc |
| Easy Boba |
| Ten Ren's Tea Time |
| Boba Bhai Pvt Ltd |
| Others |
Pricing and Supply Chain Analysis
Southeast Asian cassava starch processing hubs in Thailand and Vietnam anchor pearl production costs, transmitting currency volatility directly into Indian assembler margins through import-heavy input structures. This geographic tethering constrains pricing autonomy for domestic kit brands while quick-commerce platform commissions compress retail markups.
Pricing Analysis
Mumbai-Bengaluru price spreads of 15-20 percent reflect quick-commerce density differentials and cold-chain fulfillment costs. Three-tier pricing structure across premium, standard, and economy levels separates BIS-certified accessory bundles from basic polyethylene variants, with certification grade and volume scale as primary differentiation drivers. Cost compression in value tiers is intensifying because of synthetic flavoring oversupply. Students in hostel clusters show highest price sensitivity; luxury gift segments show least.
Supply Chain Analysis
Extended payment terms from Thai tapioca processors strain working capital for emerging assemblers lacking supply-chain finance facilities. Geographic supply concentration centers on Thailand, Vietnam, and Taiwan for cassava starch extraction, flavor syrup stabilization, and modified atmosphere packaging films. Raw material dependencies include tapioca pearls, tropical fruit concentrates, and food-grade plastic straws. Single-source vulnerability for frozen pearl shipments through Mumbai and Chennai ports threatens inventory continuity. Distribution runs through quick-commerce dark stores and direct-to-consumer fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India retail bubble tea kits sit in early-cycle expansion, with Telangana and Tamil Nadu metro penetration running at one-third of Maharashtra levels and substantial headroom remaining.
For Market Incumbents: Entrench position through backward integration into domestic pearl manufacturing utilizing PLI scheme incentives, while securing exclusive quick-commerce slotting fees in Bengaluru and Mumbai. Frozen Bottle and Boba Bhai Pvt Ltd face emerging threat from direct-to-consumer subscription specialists; FSSAI compliance investment creates channel control lever against unbranded competitors. For New Entrants and Emerging Players: Establish a beachhead in Hyderabad and Chennai through Zepto and Swiggy Instamart partnerships before incumbent exclusivity agreements harden. Telangana's Hitech City corridor presents most penetrable geography; single-serve sachet formats for student hostel populations offer clearest go-to-market angle with minimal cold-chain infrastructure. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors flavor innovation laboratories with proprietary syrup stabilization capabilities over pure-play distribution integrators. Five-to-ten year viability hinges on clean-label formulation moats and subscription retention mechanics. Acquisition target archetype: direct-to-consumer brands with monthly curation models and FSSAI-certified manufacturing. Signal to watch: PLI scheme uptake rates for domestic tapioca processing investments.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Pearl Manufacturing Investment | PLI scheme offsets currently uneconomical small-scale tapioca processing in Telangana and Tamil Nadu. |
| Quick-Commerce Exclusive Partnership | Zepto and Swiggy Instamart slotting guarantees lock in Mumbai-Bengaluru corridor visibility against competitors. |
| Clean-Label Reformulation Program | FSSAI artificial sweetener disclosure mandates reward early movers with premium grocery retail placement. |
| Subscription Curation Model Launch | Monthly flavor bundles reduce customer acquisition costs and extend lifetime value for direct-to-consumer brands. |
| Modified Atmosphere Packaging Adoption | Extended pearl shelf-life collapses inventory risk for kirana and modern trade retail expansion. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FSSAI compliance filings, quick-commerce platform merchant data, and BIS certification records. Primary interviews engaged kit assembler operations heads, quick-commerce category managers, and premium grocery retail buyers. Secondary validation drew from customs import records for cassava starch, state-level food safety inspection reports, and PLI scheme disclosure documents. Bottom-up demand modeling triangulated against top-down market sizing.
Forecast inputs span product type segmentation across milk tea, fruit, classic, and foam kits; distribution channel dynamics through online retail, specialty stores, supermarkets, and convenience networks; and customer type cohorts including millennials, students, families, and professionals. CAGRs derived from adoption curve analysis and penetration rate trajectories across metro corridors. Industry-specific inputs include quick-commerce delivery density maps and cold-chain infrastructure expansion timelines.
Sensitivities concentrate around FSSAI regulatory evolution, cassava starch import tariff adjustments, and quick-commerce platform commission restructuring. Forecasts reflect documented assumptions regarding urban household beverage habit formation and e-commerce logistics scaling. Macroeconomic contraction, state-level plastic-waste rule tightening, or tapioca pearl supply disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Oman Food Service Market
Food Service
Europe Food Away from Home Market
Food Service
Galley Equipment Market
Food Service
Global Online Food Delivery Services Market
Food Service
Commercial Beverage Dispenser Market
Food Service
Portable Buffet and Drop-In Ranges Market
Food Service
Europe Out of Home (OOH) Delivery Market
Food Service
Supermarkets Market
Food Service
Europe Food Service Market
Food Service
North America Food Service Disposable Market
Food Service
Saudi Arabia Pizza Restaurants Market
Food Service
Meal Voucher Market
Food Service
Asia-Pacific Cloud Kitchen Market
Food Service
China Inflight Catering Market
Food Service
Latin America Online Grocery Market
Food Service
Food Service Utensils Market