
 Germany Foodservice Market | 2026-2036
Germany Foodservice Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Foodservice Market Foresight
Healthcare facility catering is hardening as the dominant end-use vertical within German foodservice procurement. McDonald's Corporation leverages its drive-thru infrastructure to anchor suburban traffic nodes. Edeka Group sustains captive wholesale distribution through vertical control over retail-adjacent catering contracts. SSP Group PLC competes aggressively in transportation hub concessions across Deutsche Bahn corridors.
Germany foodservice encompasses the preparation, delivery, and commercial distribution of meals outside residential kitchens, spanning hot-held service lines, cold-chain logistics, and just-in-time production systems calibrated to HACCP temperature protocols. The sector's primary commercial purpose centers on feeding concentrated populations—workers, patients, travelers, students—at scale with standardized quality and traceable ingredient provenance. Quick Service Restaurants dominate volume throughput while Catering Services capture margin concentration through long-term institutional contracts. Delivery platforms within Product Offering are displacing dine-in traffic in urban cores, though Drive-Thru retains defensive strength in automotive-centric regions.
The EU Green Deal packaging standards, Germany's national organic labeling framework under BLL guidelines, and municipal waste reduction ordinances in Berlin and Munich collectively elevate compliance costs for single-use serviceware while redirecting procurement toward reusable systems. KBA food transport safety protocols and local health authority inspections under the Infektionsschutzgesetz enforce cold-chain documentation that shapes distributor qualification criteria. Stakeholders must monitor how the EU AI Act's forthcoming transparency requirements intersect with automated kitchen equipment deployments and dynamic pricing algorithms across franchise networks.
Market Dynamics
EU Green Deal packaging mandates are forcing German foodservice operators to reengineer procurement workflows around reusable serviceware systems and certified organic sourcing protocols under BLL guidelines.
Growth Catalysts
- Healthcare facility catering demand:German hospital complexes and eldercare campuses are consolidating meal contracts under long-term procurement frameworks that favor large-scale caterers with HACCP certification.
- EU Green Deal packaging standards:These mandates accelerate investment in reusable container logistics and closed-loop washing infrastructure across Berlin and Munich metropolitan zones.
- Technology campus expansion:Corporate catering contracts for R&D facilities in Hamburg and Stuttgart are hardening as anchor tenants for contract foodservice volume.
Market Restraints
- Input cost volatility:Organic protein and certified vegetable prices fluctuate under Germany's national organic labeling framework, compressing margin predictability for mid-tier operators.
- Supply concentration risk:Cold-chain logistics capacity concentrates among KBA-certified transport operators in Bavaria and Baden-Württemberg, creating bottleneck exposure.
- Regulatory friction:Municipal waste reduction ordinances in Berlin and Munich impose conflicting compliance timelines with federal BLL organic benchmarks.
Strategic Opportunities
- Underpenetrated rural corridors:Drive-thru infrastructure remains sparse across Mecklenburg-Vorpommern and Saxony-Anhalt, offering first-mover positioning for QSR chains with automotive-centric formats.
- Regulatory tailwind:Germany's Infektionsschutzgesetz inspection protocols favor operators with automated temperature documentation, creating competitive separation for digitized kitchens.
- Channel innovation:Ghost kitchen clusters in Frankfurt and Cologne industrial zones enable multi-brand delivery aggregation without prime real estate exposure.
Industry Challenges
- Cold-chain documentation complexity:KBA food transport safety protocols require real-time traceability systems that strain legacy ERP infrastructure at mid-sized distributors.
- Workforce certification gaps:HACCP-trained kitchen managers remain scarce in eastern German states, delaying contract ramp-ups for new healthcare and education accounts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Foodservice Market |
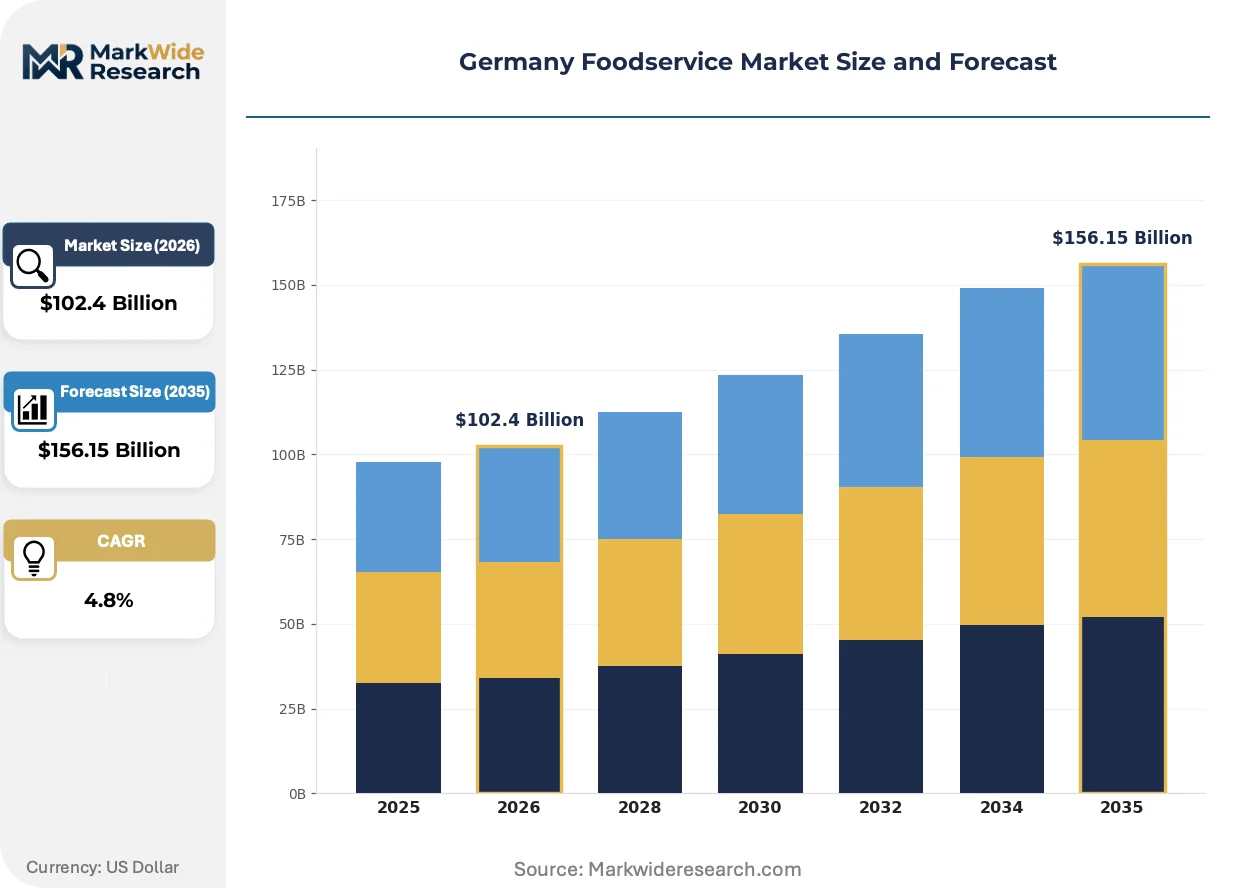
| Market Size in 2026 | $102.4 Billion |
| Market Size in 2035 | $156.15 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Quick Service Restaurants, Cafeterias, Catering Services, Vending Services, Food Trucks End User: Corporate Offices, Educational Institutions, Healthcare Facilities, Transportation Hubs, Leisure Venues Product Offering: Dine-In, Takeaway, Delivery, Drive-Thru, Buffet Distribution Channel: Direct Sales, Wholesale Distributors, Online Platforms, Retail Chains, Franchise Networks |
| Companies Covered | Burger King Deutschland GmbH, Coop Gruppe Genossenchaft, McDonald's Corporation, QSR Platform Holding SCA, Doctor's Associates Inc., AmRest Holdings SE, Edeka Group, SSP Group PLC, Yum! Brands Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Foodservice Market Shifts & Advancements
Automation and sustainability protocols are compressing traditional kitchen footprints while rerouting demand through digital ordering channels and centralized production nodes.
Cloud-based kitchen management software is decentralizing production coordination across multi-site catering operations. Large contract caterers serving Deutsche Bahn corridors and technology campuses are adopting these platforms to synchronize just-in-time meal assembly with real-time demand signals. This decentralizing architecture reduces buffer inventory requirements while tightening compliance documentation for KBA cold-chain audits.
EU AI Act transparency requirements are reshaping automated equipment procurement decisions. Foodservice operators deploying dynamic pricing algorithms and robotic cooking lines must now document decision logic for franchise network deployments. German metropolitan operators in Berlin and Munich are front-loading compliance investments to preempt enforcement timelines.
Corporate procurement departments are consolidating vendor panels around ESG-certified suppliers. Long-term catering contracts for healthcare complexes and automotive manufacturing campuses now embed BLL organic benchmarks and reusable packaging quotas as mandatory award criteria. This consolidation pressure favors operators with captive supply chain control over ingredient provenance and waste stream management.
Germany Foodservice Market Segmentation
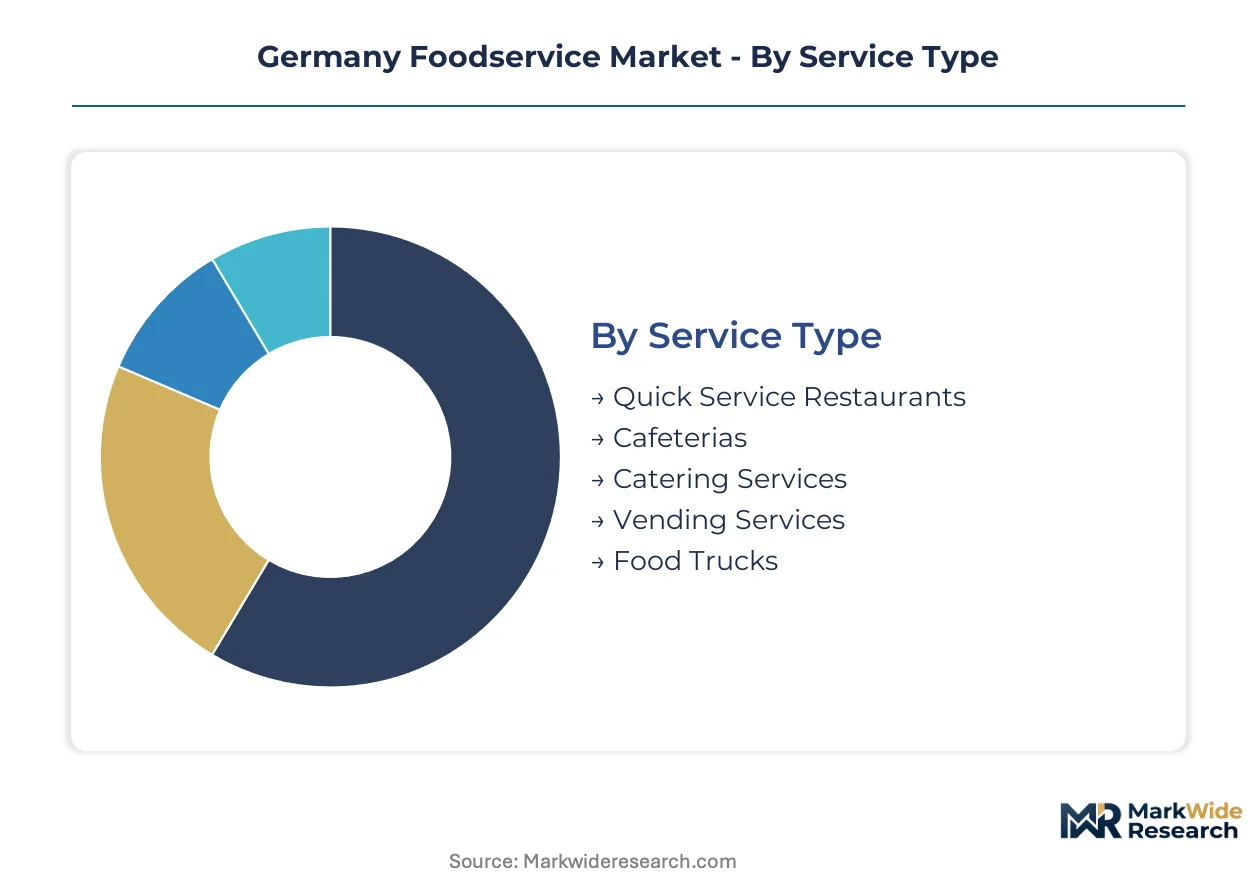
German foodservice procurement patterns diverge sharply between standardized high-volume formats and customized contract catering. Segment boundaries blur as ghost kitchens and delivery platforms reconfigure traditional service type definitions.
Service Type:
Customization intensity ranges from rigidly standardized QSR production lines to bespoke catering menus negotiated per contract.
- Quick Service Restaurants:High-throughput assembly lines dominate suburban traffic corridors with drive-thru anchoring. Berlin and Munich metropolitan zones concentrate volume where automotive access shapes site selection.
- Catering Services:Long-term institutional contracts for healthcare complexes and technology campuses command margin premiums through menu customization and HACCP certification requirements. Procurement departments embed BLL organic benchmarks and reusable packaging quotas as mandatory award criteria.
- Cafeterias:Self-service lines in corporate and educational settings balance speed with limited menu rotation.
- Vending Services:Automated retail formats serve transportation hubs and manufacturing floors with refrigerated fresh-food cabinets displacing traditional snack machines.
- Food Trucks:Mobile kitchens cluster around urban event circuits and construction sites with seasonal demand fluctuations.
Leading the category by volume: Quick Service Restaurants. Expanding most quickly: Catering Services.
End User:
Contract duration and menu complexity separate transient consumer traffic from multi-year institutional procurement frameworks.
- Healthcare Facilities:Hospital complexes and eldercare campuses consolidate meal contracts under procurement frameworks favoring large-scale caterers with KBA cold-chain documentation. HACCP-trained kitchen managers remain scarce in eastern German states, constraining contract ramp-ups.
- Corporate Offices:Technology campuses in Hamburg and Stuttgart harden as anchor tenants for contract foodservice volume with R&D facilities demanding extended service hours.
- Educational Institutions:University canteens and school meal programs operate under municipal procurement rules with cost-per-meal caps.
- Transportation Hubs:Deutsche Bahn corridors and airport terminals concentrate concession opportunities where SSP Group PLC competes aggressively.
- Leisure Venues:Stadiums and entertainment complexes demand surge-capacity production for event-driven traffic spikes.
Dominating procurement value: Healthcare Facilities. Steepest expansion trajectory: Corporate Offices.
Product Offering:
Channel economics favor formats minimizing real estate exposure while maximizing order frequency.
- Delivery:Platform-mediated ordering displaces dine-in traffic in urban cores through ghost kitchen clusters in Frankfurt and Cologne industrial zones enabling multi-brand aggregation.
- Drive-Thru:Automotive-centric formats retain defensive strength in suburban and rural corridors where Mecklenburg-Vorpommern and Saxony-Anhalt remain underpenetrated.
- Dine-In:Traditional restaurant floor service faces compression from digital channel migration.
- Takeaway:Counter pickup bridges convenience and cost control for urban workers.
- Buffet:Self-service lines persist in institutional settings though EU Green Deal packaging mandates pressure disposable serviceware models.
Commanding current volume: Dine-In. Gaining share fastest: Delivery.
Distribution Channel:
Control over cold-chain logistics separates integrated operators from distributor-dependent competitors.
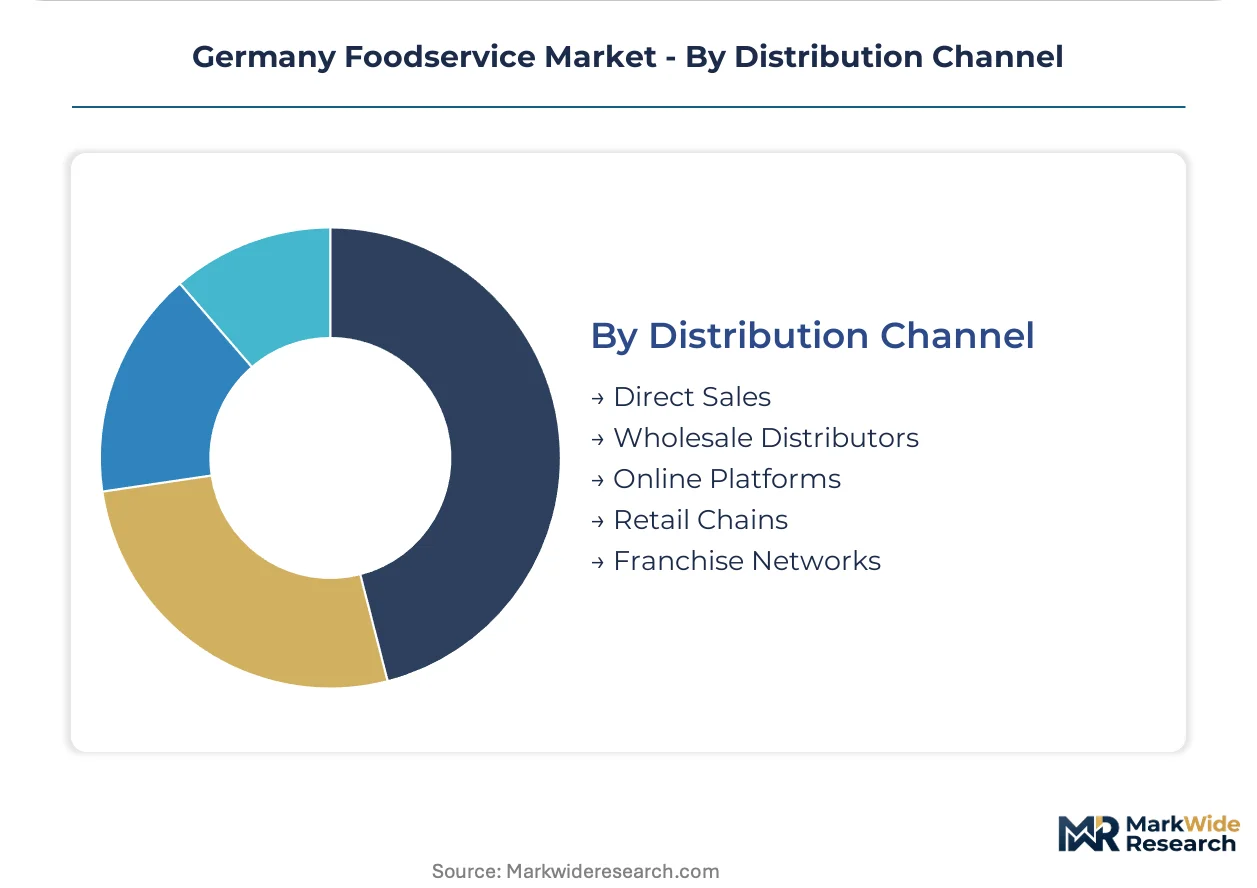
- Franchise Networks:Standardized operating procedures and pooled procurement leverage drive-thru infrastructure across suburban nodes. McDonald's Corporation anchors this channel with captive supply chain protocols.
- Wholesale Distributors:Edeka Group sustains captive distribution through vertical control over retail-adjacent catering contracts with KBA-certified transport capacity concentrating in Bavaria and Baden-Württemberg.
- Direct Sales:Large contract caterers bypass intermediaries for healthcare and corporate accounts.
- Online Platforms:Aggregator-mediated ordering reshapes customer acquisition economics.
- Retail Chains:Supermarket-adjacent foodservice captures convenience-oriented traffic.
Controlling maximum throughput: Franchise Networks. Climbing the fastest: Online Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones and technology parks across German federal states concentrate foodservice procurement through long-term institutional contracts. KBA-certified cold-chain logistics cluster in southern manufacturing corridors. Municipal organic sourcing mandates in major metros reshape distributor qualification criteria.
Bavaria
Automotive manufacturing campuses and semiconductor fabrication facilities drive corporate catering volume around Munich and Ingolstadt. The state's Infektionsschutzgesetz enforcement protocols favor operators with digitized HACCP documentation. KBA-certified transport operators concentrate in Bavaria, creating cold-chain capacity advantages for healthcare facility contractors.
North Rhine-Westphalia
Chemical industry complexes and logistics hubs in Cologne and Düsseldorf generate sustained demand for industrial canteen services. EU Green Deal packaging mandates intersect with municipal waste ordinances in these cities, elevating reusable serviceware requirements. Ghost kitchen clusters in Frankfurt industrial zones enable multi-brand delivery aggregation without prime real estate exposure.
Baden-Württemberg
Engineering headquarters and R&D facilities in Stuttgart anchor technology campus catering contracts. The state's organic labeling enforcement under BLL guidelines exceeds federal baselines, compressing margin predictability for mid-tier operators. Precision manufacturing corridors around Karlsruhe and Mannheim sustain round-the-clock meal service demand.
Berlin-Brandenburg
Startup ecosystems and government administrative centers concentrate contract foodservice procurement in the capital region. Municipal waste reduction timelines in Berlin conflict with federal organic certification schedules, creating compliance friction. Healthcare complexes in Potsdam consolidate meal contracts under procurement frameworks requiring KBA cold-chain documentation.
Hamburg
Port logistics operations and maritime industry headquarters sustain industrial catering volume across the metropolitan zone. Transportation hub concessions at Hamburg Airport and Deutsche Bahn terminals attract competitive bidding from concession specialists. The city's organic sourcing benchmarks under BLL guidelines redirect procurement toward certified suppliers with captive waste management systems.
Germany Foodservice Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with quick-service chains dominating volume throughput while institutional caterers capture margin concentration. The market exhibits tiered consolidation: global franchisors anchor suburban traffic nodes, regional wholesalers control captive distribution, and specialized contract caterers serve healthcare and corporate accounts. Three archetypes define competitive positioning: drive-thru infrastructure operators, vertically integrated wholesale distributors, and HACCP-certified institutional specialists. Capacity expansion and strategic partnerships represent the dominant competitive moves, particularly around cold-chain logistics and automated kitchen deployments.
Among global franchisors, McDonald's Corporation and Yum! Brands Inc. exemplify scale-driven infrastructure operators with standardized procurement protocols. Edeka Group occupies a position within the wholesale distribution archetype, leveraging retail-adjacent vertical control. SSP Group PLC represents the transportation hub concession specialist, competing across Deutsche Bahn corridors and airport terminals.
| Leading Market Players |
|---|
| Burger King Deutschland GmbH |
| Coop Gruppe Genossenchaft |
| McDonald's Corporation |
| QSR Platform Holding SCA |
| Doctor's Associates Inc. |
| AmRest Holdings SE |
| Edeka Group |
| SSP Group PLC |
| Yum! Brands Inc. |
| Others |
Supply & Pricing Matrix
Healthcare procurement departments and corporate campus facilities anchor pricing power through multi-year catering contracts that embed BLL organic benchmarks and reusable packaging quotas as mandatory award criteria. This buyer concentration forces tiered pricing stratification across premium certified-organic tiers, standard HACCP-compliant tiers, and economy conventional-sourcing tiers.
Pricing Analysis
Short lead-time premiums apply to just-in-time meal assembly for healthcare complexes and technology campuses where KBA cold-chain documentation must synchronize with real-time demand signals. Price differentiation separates BLL-certified organic tiers from conventional sourcing tiers, with volume scale discounts hardening for institutional accounts above defined meal thresholds. Cost compression in mid-tier conventional sourcing is intensifying because organic protein and certified vegetable prices fluctuate under Germany's national organic labeling framework. Healthcare facility procurement departments exhibit lowest price sensitivity due to embedded ESG mandates, while educational institutions under municipal cost-per-meal caps show highest sensitivity.
Supply Chain Analysis
Organic vegetable and certified protein supply rests on Dutch greenhouse operations, Spanish field agriculture, and domestic Bavarian farming cooperatives under BLL guidelines. Cold-chain logistics capacity concentrates among KBA-certified transport operators in Bavaria and Baden-Württemberg, creating single-source vulnerability for eastern German states. Distribution runs through Edeka Group's captive wholesale networks for retail-adjacent catering contracts, while direct sales dominate large healthcare and corporate accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German foodservice is transitioning from disposable serviceware systems to reusable container logistics and automated kitchen documentation, with cloud-based kitchen management software replacing legacy ERP infrastructure for multi-site catering coordination.
For Market Incumbents: Cement defensive positioning by deepening backward integration into captive organic sourcing networks and KBA-certified cold-chain transport capacity. Prioritize digitized HACCP documentation investments to exploit Infektionsschutzgesetz inspection protocols that favor automated temperature tracking. Channel control through franchise network standardization remains essential against delivery platform displacement.
For New Entrants and Emerging Players: Capture first-mover positioning in underpenetrated rural corridors across Mecklenburg-Vorpommern and Saxony-Anhalt where drive-thru infrastructure remains sparse. Ghost kitchen clusters in Frankfurt and Cologne industrial zones offer lowest real estate exposure for multi-brand delivery aggregation. A go-to-market angle targeting automotive-centric QSR formats in eastern states bypasses incumbent metropolitan saturation.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier contract caterers with HACCP certification gaps in eastern German states where workforce scarcity delays contract ramp-ups. Long-term viability over the mid-window hinges on ESG-certified supplier consolidation around captive waste management and organic provenance control. The signal to watch is municipal waste reduction ordinance acceleration in Berlin and Munich that elevates reusable system investment requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Reusable Container Logistics Investment | EU Green Deal packaging mandates in Berlin and Munich elevate compliance costs for single-use serviceware. |
| Automated Kitchen Documentation Deployment | Infektionsschutzgesetz protocols favor digitized HACCP systems for competitive separation in healthcare contracts. |
| Ghost Kitchen Cluster Expansion | Industrial zones in Frankfurt and Cologne enable multi-brand delivery aggregation without prime real estate exposure. |
| Backward Integration into Organic Sourcing | BLL organic benchmarks embedded in corporate procurement panels favor captive supply chain control. |
| KBA-Certified Cold-Chain Capacity Addition | Transport safety protocols concentrate among Bavaria and Baden-Württemberg operators, creating bottleneck exposure. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with contract catering procurement directors, HACCP certification auditors, KBA transport operators, ghost kitchen facility managers, and corporate campus foodservice coordinators. Secondary sources included BLL organic labeling framework documentation, EU Green Deal packaging mandate texts, Infektionsschutzgesetz enforcement protocols, KBA food transport safety guidelines, and municipal waste reduction ordinances from Berlin and Munich. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Granularity-level modeling deployed service type, end user vertical, product offering channel, and distribution channel as core segmentation dimensions, with BLL certification tier and KBA cold-chain compliance status as industry-specific overlay variables. CAGRs were derived through trend extrapolation calibrated to documented contract award values and facility expansion announcements across the analysis window. Forecast inputs incorporated technology campus buildout pipelines, healthcare facility consolidation timelines, and EU AI Act transparency requirement implementation trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to organic input price volatility, municipal-federal regulatory friction, and workforce certification gap resolution in eastern states. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Latin America Inflight Catering Market
Food Service
GCC Online Grocery Market
Food Service
Global Online Food Delivery Services Market
Food Service
Germany Smokeless Indoor Grills Market
Food Service
Snack Subscription Box Service Market
Food Service
Food Service Utensils Market
Food Service
Asia-Pacific Food Away from Home Market
Food Service
Commercial Ice Dispenser Market
Food Service
Self-Heating Hot Pot Market
Food Service
Breakfast Takeout Market
Food Service
Haute Cuisine Market
Food Service
Commercial Pizza Oven Market
Food Service
UK Smokeless Indoor Grills Market
Food Service
Saudi Arabia Cloud Kitchen Market
Food Service
Instant Noodle Vending Machine Market
Food Service
Asia Pacific Airline Catering Services Market