
 Europe Food Away from Home Market | 2026-2036
Europe Food Away from Home Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Food Away from Home Market Analytics
The capability gap between capital-heavy full-service operators and lean fast-casual formats is bifurcating competitive returns across the European landscape. Nestlé S.A. leverages its frozen-to-table infrastructure to anchor institutional supply contracts in France and the United Kingdom. Dr. Oetker GmbH competes through specialized pizza and bakery platforms that dominate German-speaking markets. Greencore Group plc controls chilled ready-meal production for British retail and foodservice crossover channels.
Food away from home encompasses all prepared meals and beverages consumed outside domestic kitchens, spanning from quick-service counters to full-service dining rooms with standardized food safety protocols and temperature-controlled supply chains. The category serves commercial, institutional, and leisure consumption occasions across European cities. Full-service restaurants still capture the largest margin pools in Southern Europe, while fast casual is expanding fastest among time-constrained urban professionals in Nordic capitals. The budget tier remains structurally mature in Eastern European markets, whereas premium positioning concentrates around Michelin-recognized clusters in Paris, London, and Milan.
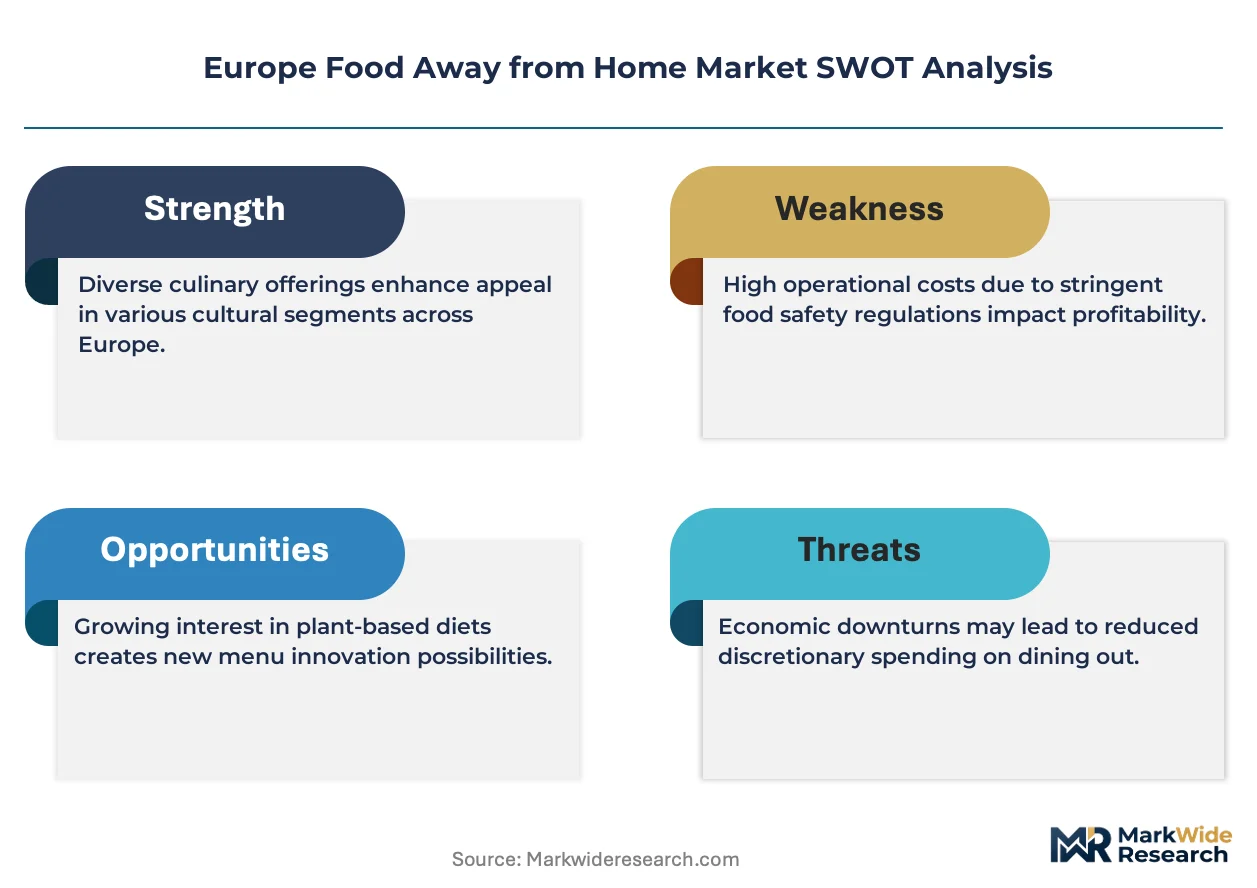
EFSA nutritional labeling mandates and REACH chemical safety standards govern ingredient sourcing and menu transparency across EU member states, pushing operators toward cleaner label portfolios. The F-Gas Regulation constrains refrigeration choices in commercial kitchens, redirecting capital toward climate-friendly equipment retrofits. Stakeholders must monitor how CSRD disclosure requirements will force supply chain visibility investments before the next regulatory enforcement cycle tightens.
Market Dynamics
EU Green Deal supply chain mandates are forcing foodservice operators to reconfigure sourcing networks and cold-chain infrastructure across member states. The F-Gas Regulation accelerates equipment replacement cycles while REACH compliance raises ingredient documentation burdens. These pressures favor operators with capital reserves to absorb retrofit costs and audit investments.
Growth Catalysts
- Corporate catering contracts:Office parks across Germany and the Netherlands are consolidating meal provision under single-vendor arrangements. These contracts demand scalable production and temperature-controlled logistics.
- EFSA nutritional labeling mandates:Menu transparency requirements push operators toward cleaner label portfolios. Reformulation investments create differentiation among health-positioned brands.
- Urban gastronomy corridors:Berlin, Copenhagen, and Amsterdam concentrate demand from time-constrained professionals. High foot-traffic zones justify premium positioning and experimental formats.
Market Restraints
- Energy cost volatility:Commercial kitchen refrigeration and HVAC consume disproportionate operating budgets. The F-Gas Regulation constrains equipment choices while electricity tariffs squeeze margin recovery.
- Ingredient supply concentration:Frozen protein and specialty produce flows through Rotterdam and Hamburg port clusters. Disruption at these nodes propagates through cross-border distribution networks.
- Substitution by in-house corporate dining:Large employers in Nordic markets are building captive kitchen facilities. These captive operations capture volume that previously flowed to external caterers.
Strategic Opportunities
- Poland and Romania underpenetration:Eastern European markets retain fragmented independent operators. Branded fast-casual formats can establish scale before consolidation accelerates.
- CSRD disclosure tailwinds:Supply chain visibility investments become mandatory for large corporate clients. Operators with traceable sourcing gain preferred-vendor status in RFP processes.
- Cloud kitchen convergence with logistics tech:Dark kitchens paired with algorithmic delivery routing compress last-mile costs. Paris and London host the densest experiments in this model.
Industry Challenges
- Refrigeration technician scarcity:Climate-friendly equipment retrofits require specialized installation and maintenance skills. Training pipelines lag behind F-Gas Regulation enforcement timelines.
- Legacy ERP integration:Farm-to-fork traceability demands real-time data exchange with upstream suppliers. Many mid-tier operators operate on siloed systems that resist API connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Food Away from Home Market |
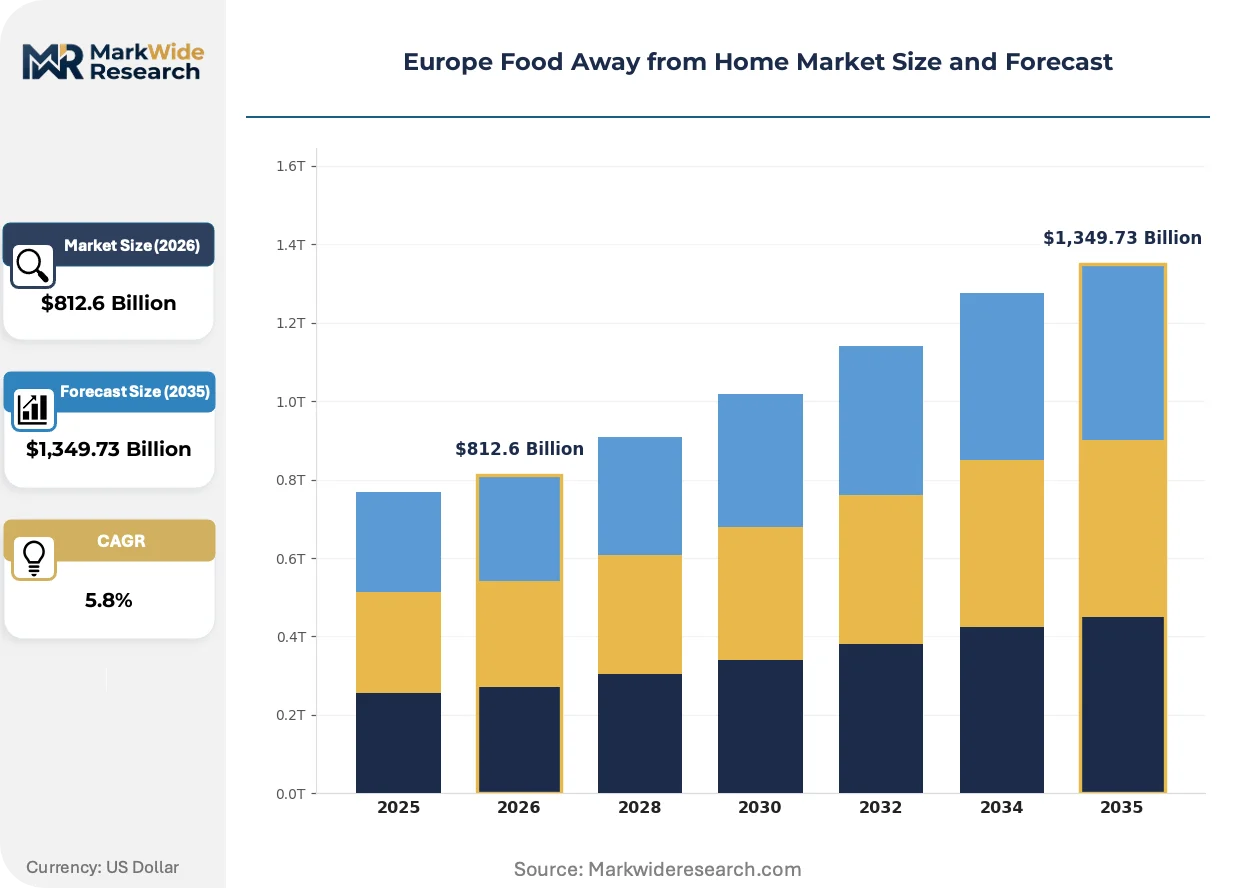
| Market Size in 2026 | $812.6 Billion |
| Market Size in 2035 | $1,349.73 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full-Service Restaurants, Fast Casual, Cafés, Food Trucks Customer Type: Families, Business Professionals, Tourists, Students Meal Type: Breakfast, Lunch, Dinner, Snacks Price Tier: Premium, Mid-Range, Budget, Value |
| Companies Covered | Nomad Foods Ltd., Nestlé S.A., Dr. Oetker GmbH, Unilever PLC, Orkla ASA, Kerry Group plc, Fjordland AS, Saarioinen Oy, Greencore Group plc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Food Away from Home Market Evolving Landscape
Automation and regulatory compliance technologies are compressing operational models across European foodservice. Operators are deploying capital toward equipment that simultaneously reduces labor exposure and satisfies tightening environmental standards. The competitive gap widens between technology-adopted chains and traditional independents.
Connected kitchen equipment is miniaturizing sensor arrays and control systems into compact form factors suitable for small-footprint urban locations. Fast-casual chains in Stockholm and Helsinki are piloting these units to monitor HACCP compliance remotely. The technology is miniaturizing quality assurance overhead, allowing lean teams to operate multiple micro-kitchens without proportional management hires.
CSRD disclosure requirements are mandating granular supply chain emissions reporting from large foodservice buyers. Operators must now document Scope 3 footprints from agricultural inputs through final delivery. British and German institutional caterers face the earliest compliance deadlines, driving accelerated supplier audits and contract renegotiations.
Subscription meal programs are displacing transactional ordering among urban professional segments. Copenhagen and Amsterdam host the densest adoption of weekly pre-paid lunch plans. Corporate HR departments increasingly subsidize these arrangements as retention tools, redirecting volume from traditional pay-per-visit counters toward contracted providers with predictable fulfillment obligations.
Europe Food Away from Home Market Segmentation
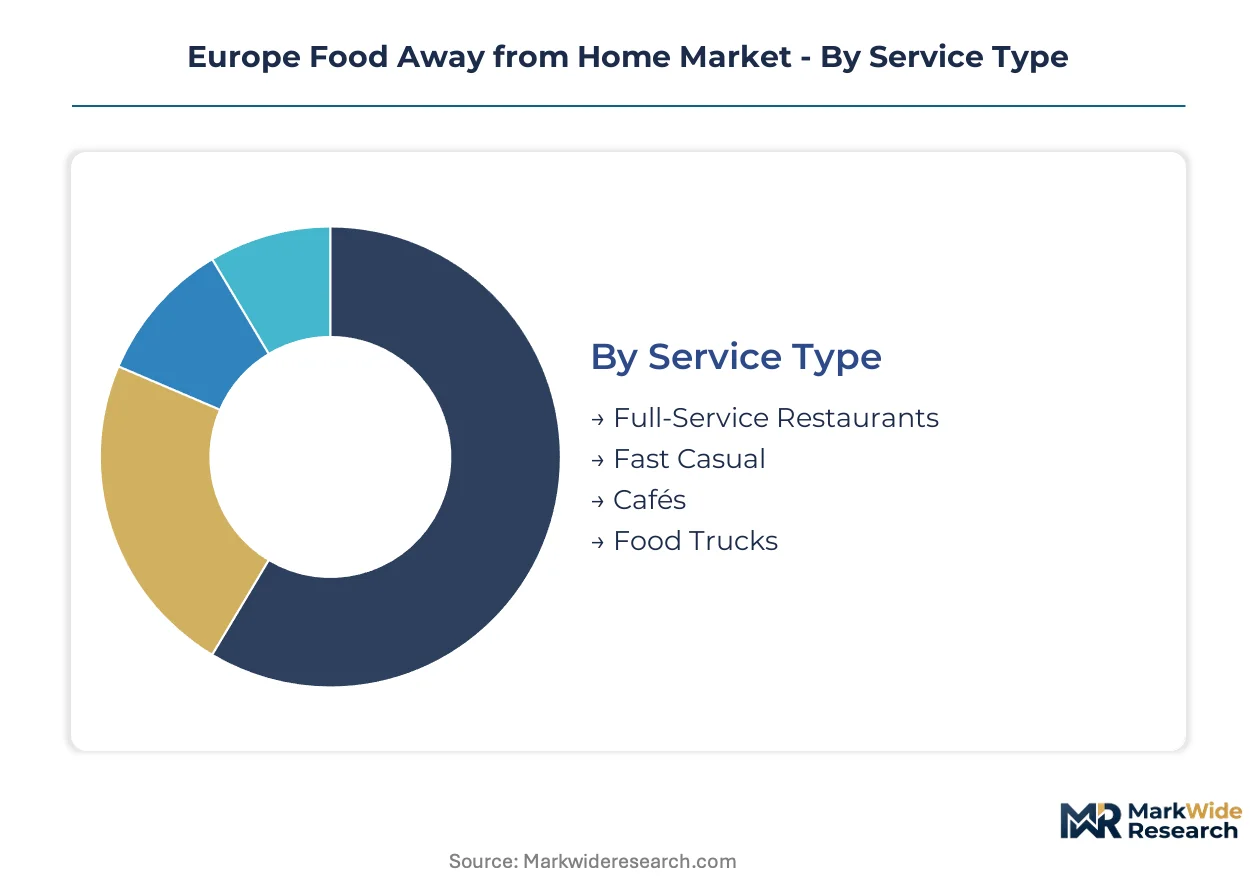
Service format, customer occasion, and price positioning create distinct operational requirements for European food away from home operators. Each segment demands specialized supply chain configurations, labor models, and regulatory compliance strategies that determine competitive viability.
Service Type:
EFSA nutritional labeling mandates and F-Gas refrigeration standards apply differentially across formats based on kitchen complexity and service velocity.
- Full-Service Restaurants:Table service with extended dwell times and multi-course menu structures requires dedicated HACCP stations and climate-controlled wine storage. Southern European markets in Italy and Spain concentrate demand here, though labor cost inflation constrains expansion.
- Fast Casual:Counter service with customizable assembly-line production dominates Berlin, Copenhagen, and Amsterdam urban corridors. EFSA transparency requirements favor operators with clean-label supply chains and visible ingredient sourcing.
- Cafés:Beverage-forward formats with limited hot food menus occupy high-rent streetfront locations. French and Italian café culture sustains premium positioning despite compressed margins.
- Food Trucks:Mobile units with compact equipment footprints exploit event licensing and temporary permits. Regulatory fragmentation across German Länder and French departments complicates cross-border operations.
Established volume favors Full-Service Restaurants; emerging adoption favors Fast Casual.
Customer Type:
Procurement patterns diverge sharply between contracted institutional accounts and discretionary individual spenders.
- Families:Multi-generational dining occasions prioritize portion scalability and child-friendly menu options. Weekend demand concentrates in suburban retail parks across Germany and the Netherlands.
- Business Professionals:Time-constrained weekday lunch occasions drive subscription meal program adoption in London and Paris financial districts. Corporate HR subsidies redirect volume toward contracted providers.
- Tourists:Seasonal demand spikes in Mediterranean coastal zones and Alpine ski corridors. Operators depend on multilingual staff and extended seasonal hours.
- Students:Price-sensitive volume concentrates near university campuses in Warsaw, Budapest, and Prague. Budget tier operators compete on proximity and meal deal bundling.
Contracted corporate channels favor Business Professionals; discretionary spend recovery favors Tourists.
Meal Type:
Daypart economics determine equipment utilization rates and labor scheduling intensity across European operations.
- Breakfast:Coffee-centric occasions with rapid throughput requirements dominate Nordic commuter rail stations and airport terminals. Grab-and-go formats capture share from traditional sit-down service.
- Lunch:The highest-volume daypart for urban professional segments drives cloud kitchen specialization in Paris and London. Algorithmic delivery routing compresses last-mile fulfillment windows.
- Dinner:Full-service formats capture margin premiums through beverage attachment and extended table turns. Mediterranean markets sustain later dining hours than Northern European counterparts.
- Snacks:Between-meal occasions support bakery and confectionery specialists in Belgian and Austrian high streets. Portion-controlled offerings align with EFSA nutritional labeling trends.
Operational scale favors Lunch; margin expansion favors Dinner.
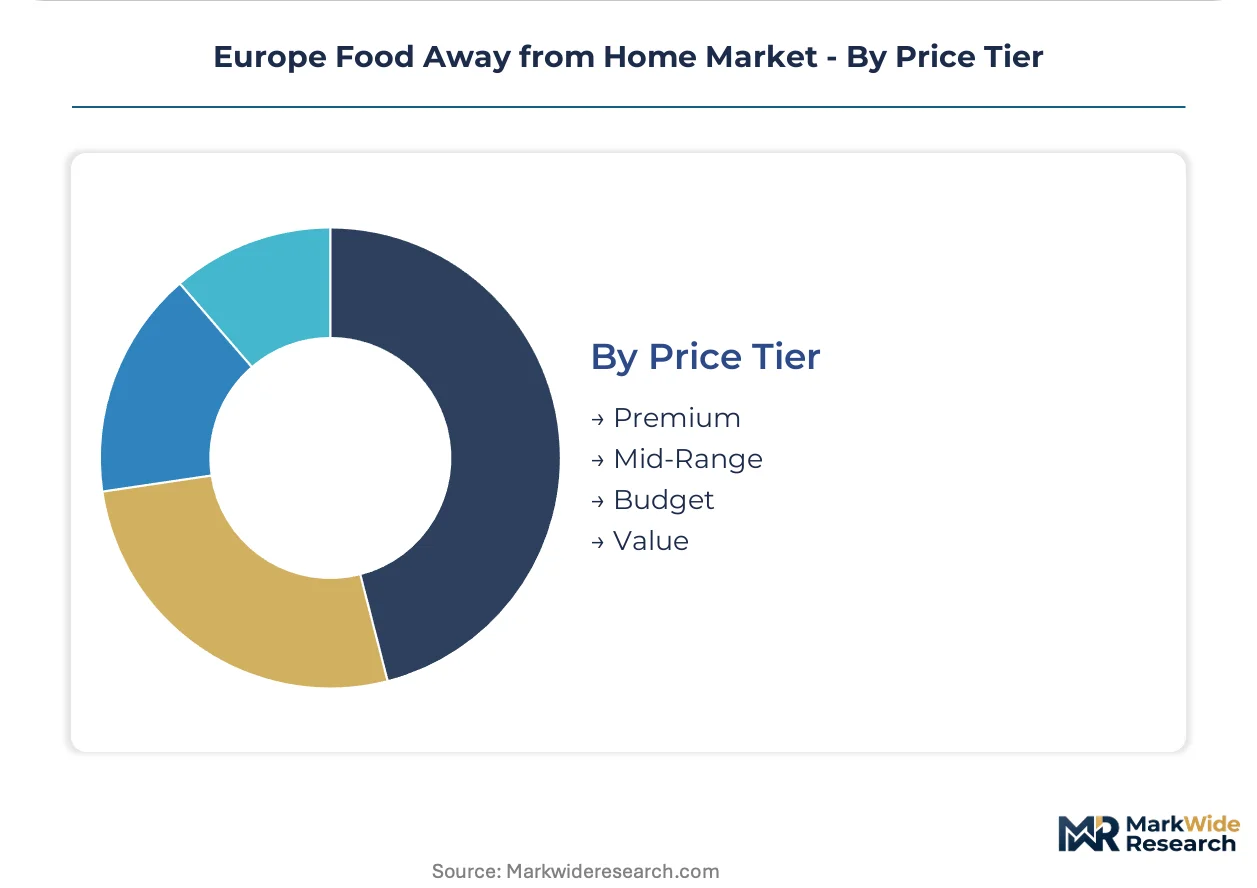
Price Tier:
REACH compliance costs and CSRD disclosure investments stratify competitive access across price positioning levels.
- Premium:Michelin-recognized clusters in Paris, London, and Milan concentrate supply relationships with artisan producers. Traceable sourcing and chef pedigree justify price multiples.
- Mid-Range:Branded fast-casual chains with standardized formats target urban professionals in Stockholm and Helsinki. Clean-label reformulation investments differentiate against budget alternatives.
- Budget:Eastern European markets retain fragmented independent operators with limited capital for regulatory retrofit. Price competition intensifies around meal deal bundling.
- Value:Limited-service formats with minimized labor exposure operate in transport hubs and retail parks. Equipment automation reduces per-unit cost structures.
Regulatory compliance investment favors Premium; volume scalability favors Mid-Range.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across European markets. German and Dutch corporate buyers negotiate volume contracts with limited price tolerance, while Italian and Spanish consumers retain stronger discretionary attachment to full-service dining experiences.
Germany
Urban gastronomy corridors in Berlin and Hamburg concentrate fast-casual expansion targeting time-constrained professionals. The F-Gas Regulation accelerates commercial kitchen equipment replacement cycles across federal states. Bavaria's office parks near Munich and Stuttgart drive consolidated corporate catering contracts under single-vendor arrangements.
United Kingdom
London's financial districts host dense subscription meal program adoption subsidized by corporate HR departments. CSRD disclosure requirements force institutional caterers to document Scope 3 emissions from agricultural inputs. Greencore Group plc anchors chilled ready-meal production for British retail and foodservice crossover channels.
France
Michelin-recognized clusters in Paris sustain premium positioning through traceable artisan supply relationships. EFSA nutritional labeling mandates push operators toward cleaner label portfolios and menu transparency. Lyon and Bordeaux concentrate full-service restaurant margin pools despite labor cost inflation pressures.
Italy
Southern European dining culture sustains extended table turns and beverage attachment in full-service formats. REACH compliance raises ingredient documentation burdens for imported specialty produce. Milan and Rome host experimental fast-casual formats competing against traditional trattoria density.
Netherlands
Amsterdam's high foot-traffic zones justify premium positioning among experimental foodservice formats. The EU Green Deal reshapes supply chain sourcing requirements for out-of-home operators. Rotterdam's port cluster handles frozen protein flows that propagate through cross-border distribution networks.
Europe Food Away from Home Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the European food away from home landscape. Capital-heavy full-service operators and lean fast-casual formats are bifurcating competitive returns. Three archetypes dominate: multinational packaged food suppliers with frozen-to-table infrastructure, specialized regional bakery and pizza platforms, and chilled ready-meal producers controlling retail-foodservice crossover channels. Dominant competitive moves include supply chain visibility investments for CSRD compliance and cloud kitchen convergence with algorithmic delivery routing.
Among packaged food suppliers with European headquarters, Nestlé S.A. and Dr. Oetker GmbH occupy distinct positioning. Nestlé S.A. represents the capital-reserved archetype capable of absorbing retrofit costs and audit investments across France and the United Kingdom. Dr. Oetker GmbH exemplifies specialized platform concentration within German-speaking markets. Greencore Group plc anchors the chilled production segment for British institutional supply relationships.
| Leading Market Players |
|---|
| Nomad Foods Ltd. |
| Nestlé S.A. |
| Dr. Oetker GmbH |
| Unilever PLC |
| Orkla ASA |
| Kerry Group plc |
| Fjordland AS |
| Saarioinen Oy |
| Greencore Group plc |
| Others |
Value Network & Pricing Analysis
Centralized frozen-protein processing at Rotterdam and Hamburg port clusters compresses per-unit cost structures while establishing hard price floors for cross-border distribution. Scale advantages in temperature-controlled logistics reward operators with dedicated cold-chain assets, forcing smaller competitors toward narrow geographic niches or contract manufacturing arrangements.
Pricing Analysis
Corporate catering contracts with extended service agreements anchor lifetime value across European office parks. Three-tier pricing structure across premium, standard, and economy levels separates Michelin-recognized Paris clusters from mid-range fast-casual formats and Eastern European budget independents. Price differentiation rests on EFSA compliance documentation and CSRD-ready supply chain visibility. Cost compression in the budget tier intensifies because REACH ingredient documentation burdens fall disproportionately on capital-constrained operators. Student segments near Warsaw and Prague campuses exhibit highest price sensitivity; premium clusters in London and Milan show least elasticity.
Supply Chain Analysis
Netherlands and Germany anchor frozen-protein consolidation and chilled ready-meal production for British and French institutional channels. Poland and Romania host fragmented independent operators with limited retrofit capacity. Raw material flows draw from North Sea fishing quotas, Ukrainian grain corridors, and Iberian specialty produce. Single-source vulnerability concentrates at Rotterdam port clusters where disruption propagates through cross-border networks. Distribution runs through temperature-controlled logistics partnerships serving urban gastronomy corridors and corporate catering contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud kitchen convergence with algorithmic delivery routing is reconfiguring platform economics across European foodservice. Interoperability between subscription meal programs and corporate HR benefit systems is consolidating volume under contracted providers with predictable fulfillment infrastructure.
For Market Incumbents: Shield institutional supply relationships by accelerating CSRD-compliant supply chain visibility investments before enforcement cycles tighten. Absorb F-Gas Regulation retrofit costs to lock out capital-constrained competitors. Vertical integration into frozen-to-table infrastructure anchors multi-year corporate catering contracts across German office parks.
For New Entrants and Emerging Players: CE marking fast-track for connected kitchen equipment opens white-space in Stockholm and Helsinki micro-kitchen deployments. Eastern European fast-casual formats in Warsaw and Budapest offer lowest competitive density. Target algorithmic delivery routing partnerships to compress last-mile costs against established logistics networks.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among operators with corporate subscription meal programs and multi-site catering contracts. Long-term viability favors chilled ready-meal producers controlling retail-foodservice crossover channels. Acquisition focus: mid-tier operators with traceable sourcing infrastructure and API-ready ERP systems. Monitor CSRD disclosure deadlines as inflection indicator for preferred-vendor consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Supply Chain Visibility Investment | CSRD-compliant traceability secures preferred-vendor status in British and German institutional RFPs. |
| Cloud Kitchen Convergence | Dark kitchen density in Paris and London pairs with algorithmic routing to compress fulfillment costs. |
| Clean-Label Reformulation | EFSA nutritional transparency mandates push operators toward documented ingredient sourcing portfolios. |
| Corporate Subscription Programs | HR-subsidized weekly lunch plans displace transactional ordering in Copenhagen and Amsterdam corridors. |
| Climate-Friendly Equipment Retrofit | F-Gas Regulation compliance redirects capital toward refrigeration replacement cycles across federal states. |
Research Methodology
The analysis maps full-service restaurants, fast-casual formats, cafés, and food trucks, each validated through foodservice operations directors, procurement leads at institutional caterers, supply chain managers at frozen-protein distributors, and regulatory compliance officers. Primary interviews with cloud kitchen operators and corporate HR benefits administrators cross-check volume assumptions. Secondary validation draws from EFSA guidance documents, EU Green Deal implementation timelines, customs records through Rotterdam and Hamburg ports, and SEC filings of listed foodservice operators. Bottom-up site-level capacity estimates triangulate against top-down market sizing.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models service format, customer occasion, meal type, and price tier dimensions alongside regulatory compliance intensity as segmentation drivers. CAGRs derive from historical trajectory analysis adjusted for enforcement timelines of F-Gas Regulation and CSRD disclosure requirements. Forecast inputs include corporate catering contract renewal rates and cloud kitchen deployment densities in urban corridors.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal implementation or prolonged energy cost volatility would require recalibration. Forecasts reflect assumptions about regulatory enforcement pacing and cold-chain infrastructure investment cycles. Recalibration cycles align with material shifts in EFSA mandate scope and corporate sustainability disclosure deadlines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Smart Food Logistics Market
Food Service
United Kingdom Quick Service Restaurant Market
Food Service
Food Contract Manufacturing Market
Food Service
Europe Food Cold Chain Logistics Market
Food Service
Catering Food Warmers Market
Food Service
Global Food Platform-To-Consumer Delivery Market
Food Service
United States Food Truck Market
Food Service
North America Online Food Delivery Market
Food Service
Saudi Arabia Pizza Restaurants Market
Food Service
A La Carte Market
Food Service
Latin America Biodegradable Food Service Disposables Market
Food Service
Asia Pacific Airline Catering Services Market
Food Service
Instant Grocery Market
Food Service
United Arab Emirates Foodservice Market
Food Service
Asia-Pacific Halal Food and Beverage Market
Food Service
Cambodia Foodservice Market