
 Global Dark Store Market | 2026-2036
Global Dark Store Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dark Store Market Analysis
The gap between premium automated dark stores and commodity manual-pick operations is broadening as capital requirements diverge sharply. Amazon.com, Inc. leverages its robotics ecosystem to sustain fulfillment speed advantages in dense urban corridors. Swiggy anchors its competitive position through hyperlocal warehouse placement that dominates 10-minute delivery windows in Indian megacities. Zepto differentiates by controlling real estate selection algorithms that optimize last-mile radius coverage.
A dark store is a dedicated fulfillment-only warehouse optimized for online order picking rather than customer foot traffic, typically operating within 3,000–10,000 square feet with temperature-controlled zones for fresh and frozen categories. These facilities rely on automated storage and retrieval systems to achieve order cycle times under three minutes from click to dispatch. Grocery product types command the largest operational footprint due to cold-chain complexity and frequent replenishment cycles. Same-day delivery services generate the highest customer retention rates among service types, while AI-powered analytics represents the fastest-growing technology segment as operators deploy predictive demand forecasting to reduce stockout penalties.
The US Department of Transportation and the EU F-Gas Regulation shape cold-chain infrastructure standards that dictate refrigeration equipment choices in dark store construction. India's FSSAI mandates separate handling protocols for perishable inventory that influence warehouse layout and staffing models. China's SAMR enforces food traceability requirements that drive blockchain-integrated inventory management adoption. Stakeholders must monitor evolving last-mile emission regulations as municipalities across Germany, France, and the United Kingdom impose delivery vehicle restrictions that could force fleet electrification timelines and reshape site selection criteria.
Market Dynamics
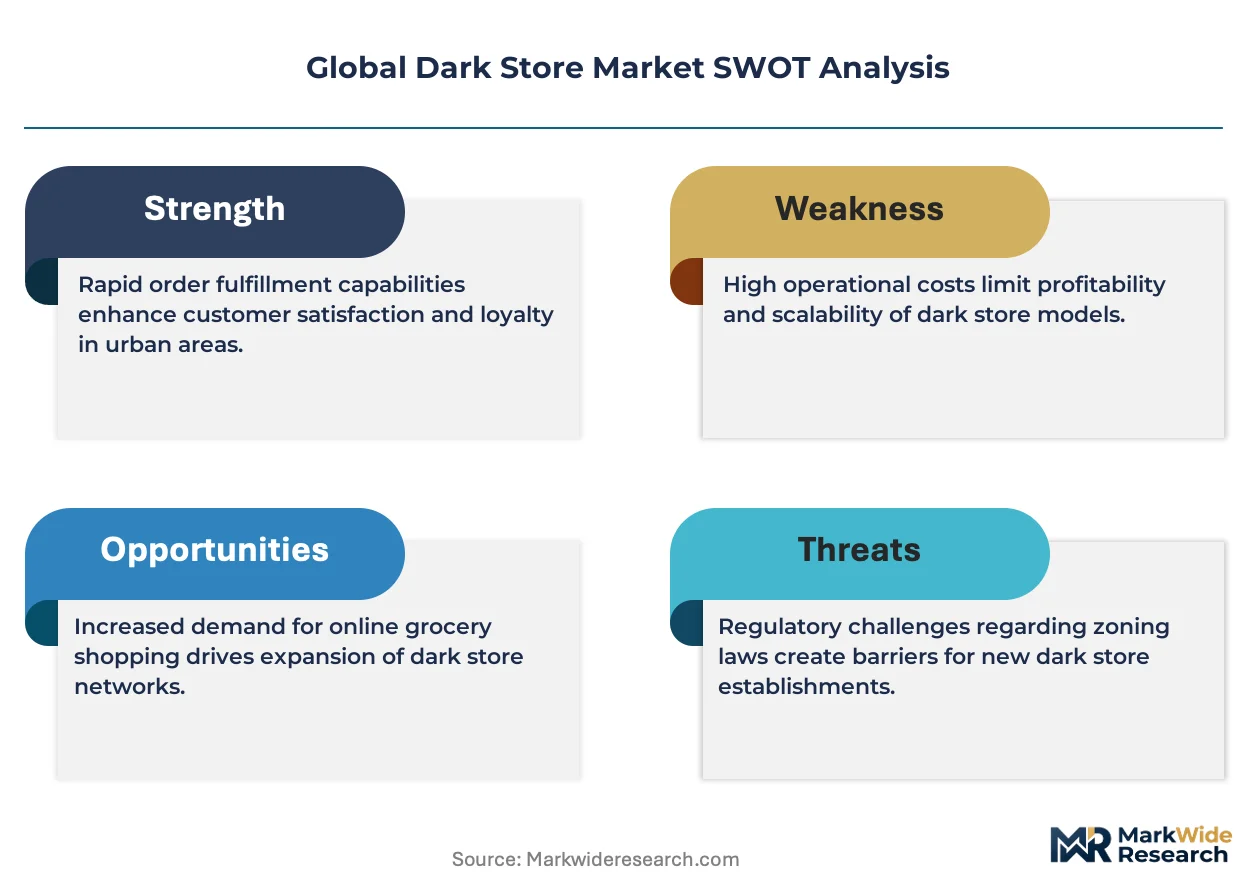
Capital intensity bifurcation between robotic and manual dark stores is compressing mid-tier operator margins while AI-powered demand forecasting rewrites inventory turnover benchmarks across fulfillment networks.
Growth Catalysts
- EU F-Gas Regulation:Stringent refrigerant phase-down mandates accelerate cold-chain equipment replacement cycles, forcing warehouse operators toward energy-efficient automation retrofits that reduce per-unit fulfillment costs.
- Urban last-mile density:Metropolitan clusters in India, Germany, and Brazil concentrate online grocery demand within sub-5-kilometer radii, enabling micro-fulfillment economics that sustain sub-30-minute delivery promises.
- Automated storage and retrieval systems:ASRS deployment in temperature-controlled zones compresses order cycle times from click to dispatch, directly supporting same-day customer retention premiums.
Market Restraints
- Refrigeration equipment cost volatility:Copper and aluminum input price swings strain cold-chain infrastructure budgets, particularly for operators building multi-zone temperature facilities.
- Real estate supply concentration:Suitable urban infill sites within last-mile radii cluster in Tier-1 Indian cities and select German metropolitan zones, inflating lease premiums for competitors outside incumbent networks.
- Technical limitation:Frozen category picking automation remains mechanically constrained, requiring hybrid human-robot staffing models that dilute labor efficiency gains achieved in ambient zones.
Strategic Opportunities
- Brazilian secondary cities:São Paulo and Rio de Janeiro anchor current quick-commerce density while Belo Horizonte and Curitiba present underpenetrated expansion corridors with rising middle-class online grocery penetration.
- Blockchain-integrated inventory management:China's SAMR food traceability requirements demonstrate regulatory tailwinds that reward operators deploying immutable supply-chain ledgers for perishable provenance verification.
- Dark kitchens convergence:Shared urban fulfillment infrastructure combining grocery micro-fulfillment with prepared meal assembly creates channel innovation opportunities in dense Asian and European corridors.
Industry Challenges
- Cold-chain technician scarcity:Certified refrigeration maintenance specialists command wage premiums that inflate operating expenditures, particularly for operators scaling multi-site networks across divergent climate zones.
- Legacy WMS integration friction:Warehouse management system migration from conventional distribution software to AI-native platforms demands extended implementation timelines and specialized systems integrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dark Store Market |
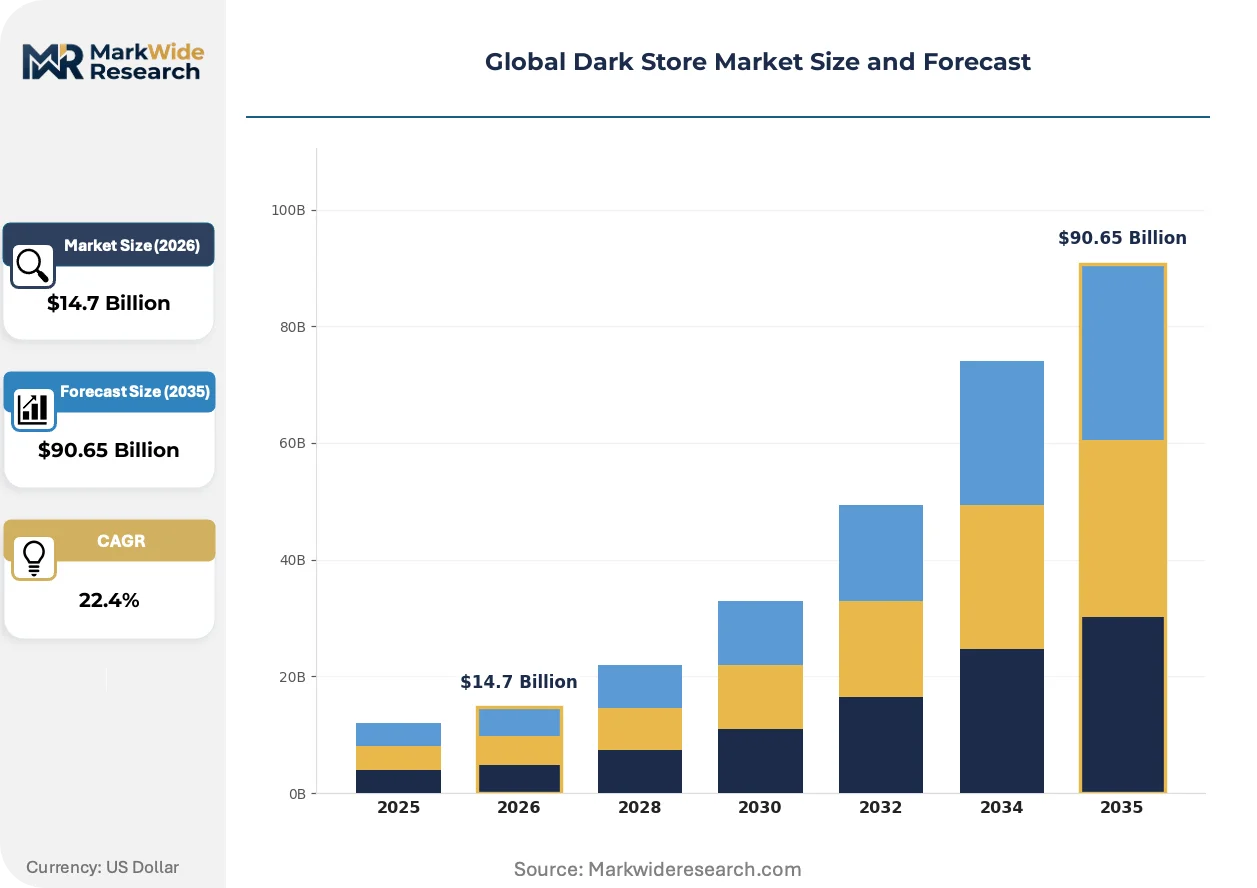
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $90.65 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grocery, Electronics, Apparel, Household Items Service Type: Same-Day Delivery, Next-Day Delivery, Click & Collect, Subscription Customer Type: Retailers, Wholesalers, E-commerce Platforms, Restaurants Technology: Inventory Management, Order Fulfillment, Delivery Tracking, AI-Powered Analytics |
| Companies Covered | Amazon.com, Inc., Walmart, Inc., Swiggy, Instacart, Flipkart, Auchan, Target Corporation, Grab, Zepto, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dark Store Market Emerging Trajectories
Robotic fulfillment architectures are converging with predictive analytics to compress order cycle economics, while regulatory pressure on cold-chain emissions and shifting urban consumption patterns reshape site selection and service design.
Autonomous mobile robots equipped with vision-based item recognition are converging with machine learning-driven path optimization to enable single-picker throughput rates previously requiring three manual associates. Grocery operators in Japan and South Korea deploy these systems most aggressively, achieving sub-90-second pick times for ambient SKUs. The structural consequence is converging with labor cost arbitrage to displace manual-pick economics in metropolitan zones above 500,000 population.
The EU F-Gas Regulation's hydrofluorocarbon phase-down timeline is forcing refrigeration equipment replacement decisions that favor CO2 transcritical systems over conventional HFC architectures. Industrial consequence includes 15-25% energy consumption reductions but requires specialized engineering capabilities scarce outside Northern European supplier networks. Frozen grocery categories face the steepest compliance cost escalation, driving consolidation toward operators with captive technical expertise.
Subscription-based grocery replenishment models are displacing transactional same-day purchasing among dual-income households in US coastal metros and London commuter zones. Traditional impulse-driven basket building yields to algorithmic reorder cycles that concentrate demand predictability with platform operators. This behavioral pivot is most visible in fresh produce and dairy categories where consumption patterns exhibit lowest variance week-to-week.
Global Dark Store Market Segmentation
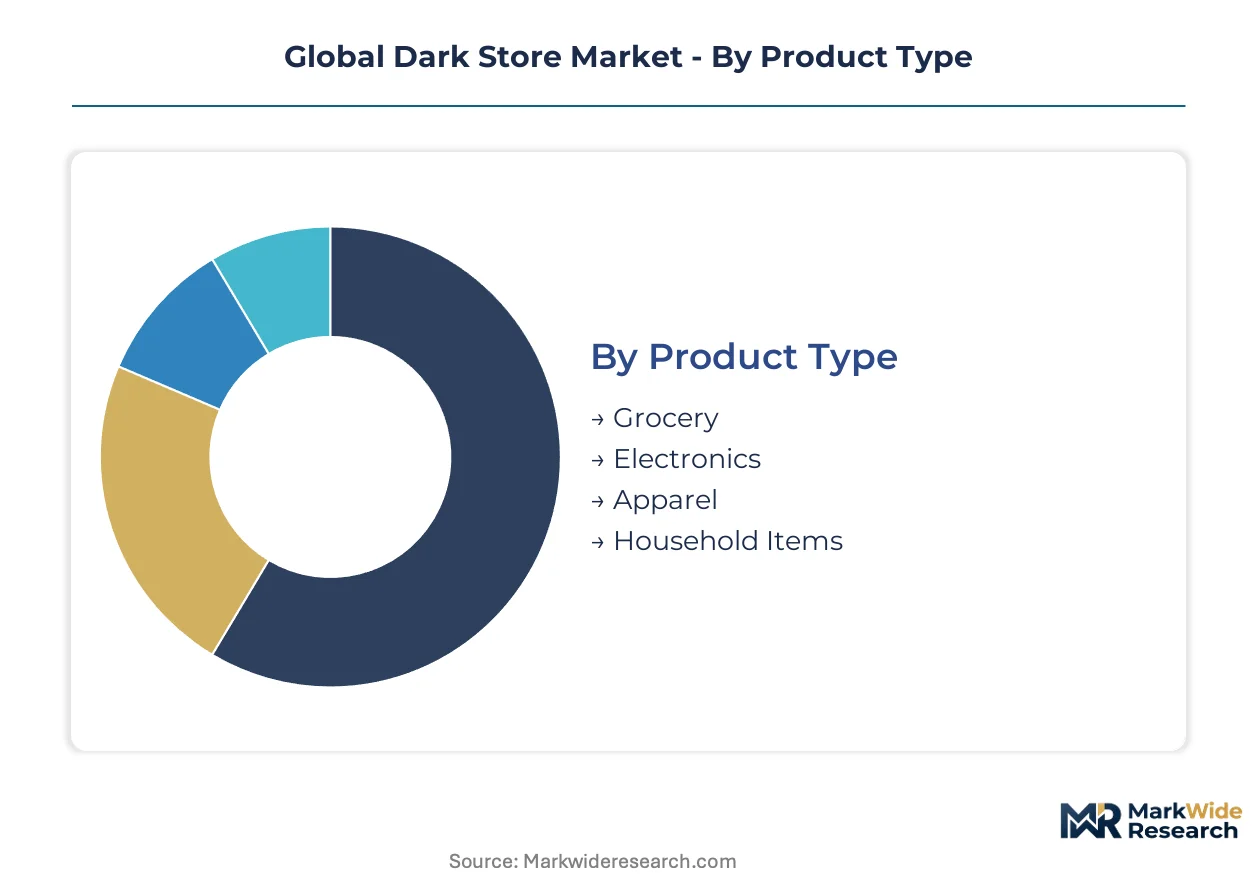
Dark store operators configure fulfillment infrastructure around product handling requirements and delivery velocity promises. Segmentation reveals how capital allocation, automation intensity, and site selection criteria diverge across operational models.
Product Type:
Buyers prioritize temperature control complexity and replenishment frequency when selecting fulfillment partners.
- Grocery:Cold-chain infrastructure dominates facility design with multi-zone refrigeration for fresh, chilled, and frozen categories. Indian quick-commerce platforms concentrate demand here, driven by FSSAI handling mandates and urban consumer expectations for sub-30-minute delivery of perishables.
- Electronics:High-value, low-velocity SKUs require secure storage and anti-static handling protocols. Demand clusters in German and Japanese metropolitan corridors where same-day replacement expectations for consumer devices justify premium fulfillment positioning.
- Apparel:Seasonal inventory turnover and size-variant complexity shape warehouse layout around returns processing capabilities. Compact urban footprints in São Paulo and London prioritize rapid exchange handling over deep storage.
- Household Items:Bulky, low-margin categories favor automated storage density over speed. Brazilian secondary cities show rising penetration as middle-class online purchasing expands beyond grocery into replenishment goods.
Grocery leads on scale; AI-powered analytics adoption in electronics leads on momentum.
Service Type:
Delivery velocity commitments determine automation investment thresholds and network density requirements.
- Same-Day Delivery:Sub-3-hour fulfillment windows mandate hyperlocal warehouse placement within 5-kilometer radii of demand clusters. Indian operators deploy dense networks in Mumbai, Bangalore, and Delhi NCR to capture retention premiums from time-sensitive urban consumers.
- Next-Day Delivery:Relaxed velocity permits larger catchment areas and lower real estate costs. European markets favor this model for non-perishable categories where EU F-Gas refrigeration compliance costs discourage rapid expansion of cold-chain micro-fulfillment.
- Click & Collect:Hybrid fulfillment integrates dark store picking with designated pickup points. German retailers leverage this to bypass last-mile emission restrictions in Berlin, Hamburg, and Munich city centers.
- Subscription:Algorithmic replenishment cycles concentrate demand predictability with platform operators. US coastal metros and London commuter zones show behavioral pivot toward automated reordering in fresh produce and dairy categories.
Same-day delivery leads on scale; subscription models lead on momentum.
Customer Type:
End-user operational models dictate warehouse configuration from picking protocols to integration requirements.
- Retailers:Traditional grocers retrofit existing distribution assets or build dedicated urban fulfillment nodes. Indian supermarket chains face competitive pressure from quick-commerce specialists, accelerating captive dark store deployment.
- Wholesalers:Bulk-breaking and case-pick automation dominate facility design. Brazilian foodservice distributors expand into quick-commerce fulfillment as restaurant delivery platforms demand consolidated sourcing.
- E-commerce Platforms:Pure-play operators optimize for single-item pick velocity and returns absorption. Amazon leverages robotics ecosystems in dense US and European urban corridors to sustain speed advantages.
- Restaurants:Dark kitchen convergence creates shared infrastructure demand in Asian and European corridors. Combined grocery and prepared meal assembly requires flexible temperature zones and cross-category contamination controls.
E-commerce platforms lead on scale; restaurants lead on momentum.
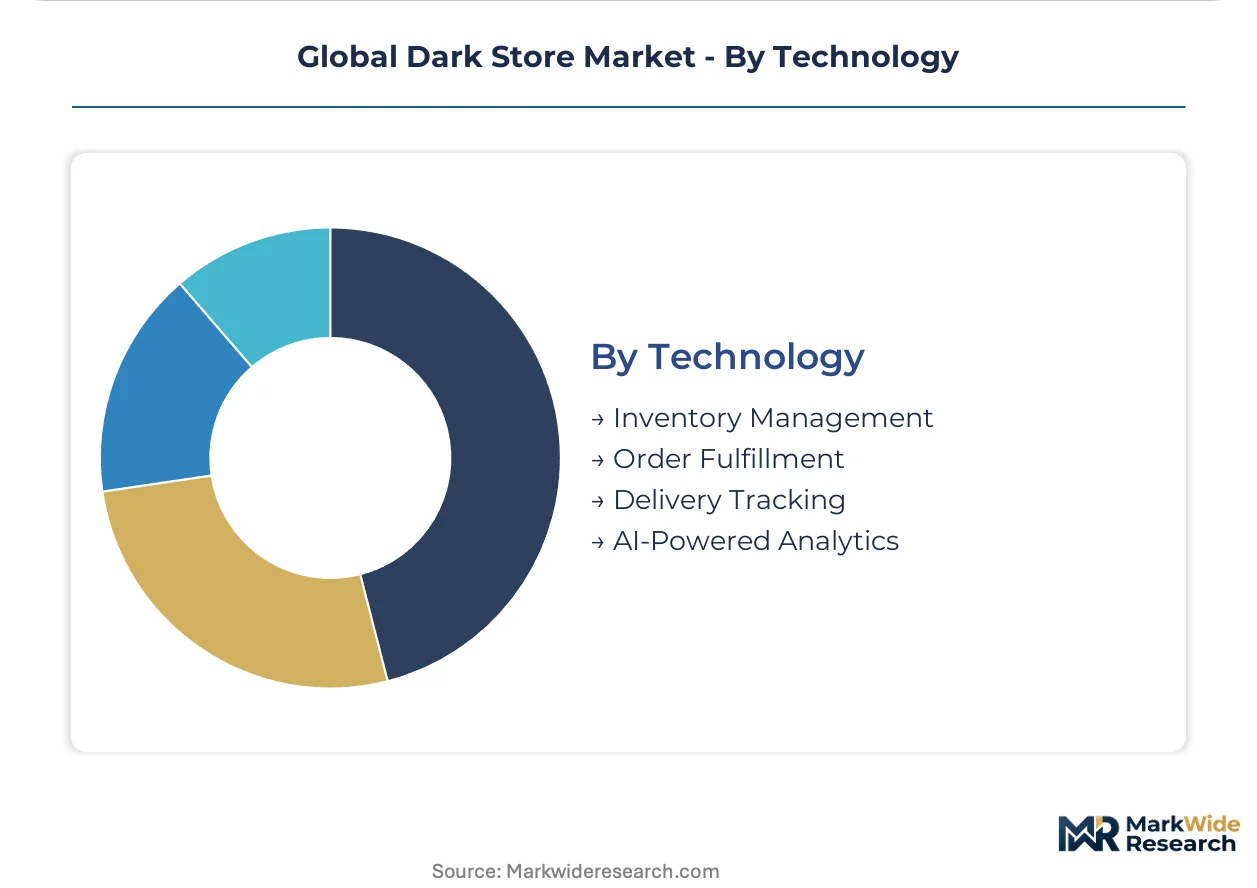
Technology:
Automation sophistication separates premium operators from commodity fulfillment providers.
- Inventory Management:Real-time stock visibility across distributed networks enables demand pooling and safety stock reduction. Chinese operators deploy blockchain-integrated systems to satisfy SAMR food traceability requirements for perishable provenance.
- Order Fulfillment:Automated storage and retrieval systems compress cycle times from click to dispatch. Japanese and South Korean grocery operators achieve sub-90-second pick times for ambient SKUs through vision-based robotic recognition.
- Delivery Tracking:Last-mile visibility platforms integrate with municipal emission monitoring in Germany, France, and the United Kingdom. Fleet electrification timelines reshape site selection to accommodate charging infrastructure.
- AI-Powered Analytics:Predictive demand forecasting reduces stockout penalties and optimizes replenishment timing. This segment expands most quickly as operators deploy machine learning across multi-site networks to rewrite inventory turnover benchmarks.
Inventory management leads on scale; AI-powered analytics leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified refrigeration technicians and robotics engineers concentrate in Northern European and East Asian industrial corridors, anchoring the technical workforce for automated cold-chain fulfillment infrastructure.
United States
Urban last-mile density in New York, Chicago, and Los Angeles drives micro-fulfillment network expansion for sub-30-minute grocery delivery. EPA refrigerant management regulations under Section 608 constrain equipment choices for multi-zone temperature facilities. Amazon operates robotics-intensive dark stores in dense coastal metros to sustain speed advantages against regional grocers.
Germany
EU F-Gas Regulation hydrofluorocarbon phase-down mandates accelerate cold-chain equipment replacement toward CO2 transcritical systems. Berlin, Hamburg, and Munich impose last-mile emission restrictions that reshape fleet electrification timelines and site selection criteria. Auchan and incumbent retailers deploy click-and-collect hybrid models to bypass city-center delivery constraints.
India
FSSAI perishable handling protocols and urban consumer expectations for 10-minute delivery concentrate quick-commerce investment in Mumbai, Bangalore, and Delhi NCR. Swiggy and Zepto operate dense networks of compact fulfillment centers optimized for hyperlocal radius coverage. The PLI scheme for cold-chain infrastructure subsidizes automation adoption among domestic operators.
China
SAMR food traceability requirements drive blockchain-integrated inventory management adoption for perishable provenance verification. Yangtze River Delta and Pearl River Delta clusters concentrate demand for same-day grocery fulfillment among middle-class households. JD.com and Alibaba leverage captive logistics networks to dominate urban micro-fulfillment economics.
Brazil
Rising middle-class online grocery penetration in São Paulo and Rio de Janeiro anchors current quick-commerce density while Belo Horizonte and Curitiba present expansion corridors. ANVISA sanitary surveillance requirements for perishable handling influence warehouse layout and staffing models. Foodservice distributors retrofit bulk-breaking capabilities to serve restaurant delivery platforms demanding consolidated sourcing.
Global Dark Store Market Vendor Landscape
Top-tier vendors anchor automated fulfillment ecosystems, while mid-tier operators compete on hyperlocal real estate placement and manual-pick efficiency. The market structure bifurcates between capital-intensive robotics deployments and lean micro-fulfillment networks optimized for emerging-market labor economics. Three archetypes dominate: technology-integrated retailers with captive logistics, pure-play quick-commerce platforms with dense urban footprints, and foodservice distributors pivoting into grocery fulfillment. Competitive moves concentrate on strategic partnerships for last-mile coverage and vertical integration into cold-chain equipment maintenance capabilities.
Within the technology-integrated retailer archetype, Amazon.com, Inc. and Walmart, Inc. occupy positions defined by robotics ecosystem control and nationwide distribution backbone leverage. Among pure-play quick-commerce specialists, Swiggy and Zepto exemplify the hyperlocal warehouse placement model that dominates 10-minute delivery windows in Indian megacities. These named entities represent contrasting strategic bets on automation intensity versus real estate density as the primary competitive lever.
| Leading Market Players |
|---|
| Amazon.com, Inc. |
| Walmart, Inc. |
| Swiggy |
| Instacart |
| Flipkart |
| Auchan |
| Target Corporation |
| Grab |
| Zepto |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up quick-commerce specialists in India and Brazil anchor supply-side consolidation while exerting pricing discipline through captive real estate networks and volume-based equipment procurement.
Pricing Analysis
Bundled fulfillment services combining automated picking with last-mile delivery command premiums over unbundled warehouse-only contracts. Three-tier pricing structure across premium robotics-enabled, standard semi-automated, and economy manual-pick levels reflects automation intensity and cold-chain complexity. Pricing pressure stems from copper and aluminum volatility in refrigeration equipment, compressing margins for mid-tier operators building multi-zone facilities. E-commerce platforms exhibit lowest price sensitivity due to retention premiums from sub-30-minute delivery promises, while independent grocers face acute cost pressure in lease-inflated Tier-1 Indian corridors.
Supply Chain Analysis
Dual-sourcing requirements for ASRS components and refrigeration systems mandate multi-supplier qualification across German, Japanese, and South Korean engineering networks. Equipment procurement draws from Northern European CO2 transcritical specialists, East Asian robotics integrators, and Indian cold-chain fabricators. Copper and aluminum price volatility creates commodity exposure for operators scaling temperature-controlled infrastructure. Distribution runs through direct OEM relationships for large-format deployments and regional integrators for compact urban sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in dark store operations rests on AI-driven demand forecasting compression of safety stock carrying costs and premium-tier automation retrofitting in dense metropolitan corridors.
For Market Incumbents: To counter pure-play quick-commerce density in Indian megacities, legacy retailers must accelerate captive micro-fulfillment deployment in Mumbai and Delhi NCR while securing backward integration into cold-chain maintenance capabilities to offset technician wage premiums. For New Entrants and Emerging Players: Capture underpenetrated Brazilian secondary cities Belo Horizonte and Curitiba through hybrid grocery-foodservice fulfillment models, leveraging ANVISA compliance expertise as a go-to-market wedge against multinational platforms lacking local regulatory navigation. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier manual-pick operators facing automation retrofit pressure, offering consolidation plays for private-equity sponsors with captive technical capabilities. Long-term viability favors robotics-integrated networks with proven sub-90-second pick economics. Watch ASRS deployment velocity in Japanese and South Korean grocery corridors as the inflection signal for automation ROI validation.| Strategic Initiative | Industry Significance |
|---|---|
| ASRS Retrofit Deployment | CO2 transcritical refrigeration integration with EU F-Gas compliance reduces energy costs for German operators. |
| Hyperlocal Real Estate Acquisition | Zepto's algorithmic site selection in Bangalore demonstrates radius-optimized fulfillment economics. |
| Blockchain Inventory Integration | SAMR traceability requirements in China reward immutable perishable provenance verification systems. |
| Dark Kitchen Convergence | Shared urban infrastructure in London and Singapore combines grocery picking with prepared meal assembly. |
| AI Demand Forecasting Platform | Predictive analytics adoption rewrites inventory turnover benchmarks across Swiggy's distributed network. |
Methodological Framework
Bottom-up fulfillment center deployment modeling reconciled against top-down cold-chain equipment shipment tracking forms the analytical core. Primary interviews with dark store operations directors, refrigeration equipment procurement leads, last-mile logistics planners, and municipal zoning officials combined with secondary validation from customs import records, FSSAI facility registration databases, EU F-Gas equipment certification filings, and SEC 10-K supply chain disclosures. Triangulation across stakeholder inputs and trade data ensures demand-supply reconciliation.
Input-output matrices map automation intensity, temperature zone requirements, and delivery velocity commitments to capital expenditure and operating cost structures across the projection horizon. Segmentation dimensions include product type handling complexity, service tier velocity promises, customer archetype integration requirements, and technology sophistication levels. CAGRs derive from equipment installation run-rates, real estate lease commencement tracking, and quick-commerce order density proxies in monitored metropolitan clusters.
Regulatory enforcement variance, commodity price swings, and automation technology adoption curves are the dominant revision risks. Deviation in EU F-Gas phase-down timelines or Indian PLI scheme disbursement rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Food Truck Services Market
Food Service
Turkey Retail Bubble Tea Kits Market
Food Service
Europe Inflight Catering Market
Food Service
Stirrers Market
Food Service
Smart Food Logistics Market
Food Service
Restaurant Griddle Market
Food Service
Oman Food Service Market
Food Service
Europe Airline Catering Services Market
Food Service
India Foodservice Market
Food Service
Charbroiler Market
Food Service
Instant Grocery Market
Food Service
Peer-To-Peer Dining Market
Food Service
Germany Smokeless Indoor Grills Market
Food Service
Retail Bubble Tea Kits Market
Food Service
Asia Pacific Food Platform-To-Consumer Delivery Market
Food Service
Netherlands Food Service Market