
 Popcorn Making Cart Market | 2026-2036
Popcorn Making Cart Market Size, Share, and Industry Trends Forecast 2026-2036
Popcorn Making Cart Market Analytics
Single-source component procurement is restructuring into multi-source strategies across the popcorn making cart supply base. Gold Medal Products Co. leverages captive die-stamping capacity to control kettle and frame costs. Cretors & Co. anchors its position through century-old brand equity in cinema and stadium channels. Paragon International, Inc. specializes in compact electric cart designs for regional carnival operators.
A popcorn making cart is a mobile or stationary food-service appliance comprising a heated popping chamber, oil reservoir, and dispensing enclosure, typically fabricated from 304-grade stainless steel for food-contact compliance and thermal retention. The unit serves concession operators by enabling on-demand batch production in high-foot-traffic environments. Electric carts dominate volume shipments due to consistent output and reduced labor intensity versus manual crank models. Commercial-grade configurations command premium positioning through NSF certification and higher wattage elements, while home carts occupy a price-sensitive tier with smaller kettle capacities and simplified controls. Mobile installation types are gaining preference in sports venues and temporary event setups where floor-plan flexibility matters.
FDA food-contact surface regulations and NSF International equipment sanitation standards govern product legibility across the United States, while EU CE marking and EFSA material safety assessments condition market access for European-bound exports. These frameworks elevate compliance costs for smaller fabricators but also create qualification barriers that favor established suppliers with in-house testing laboratories. Stakeholders must monitor evolving state-level energy efficiency mandates for commercial kitchen equipment, as these could trigger redesign cycles for electric heating systems before the forecast midpoint.
Market Dynamics
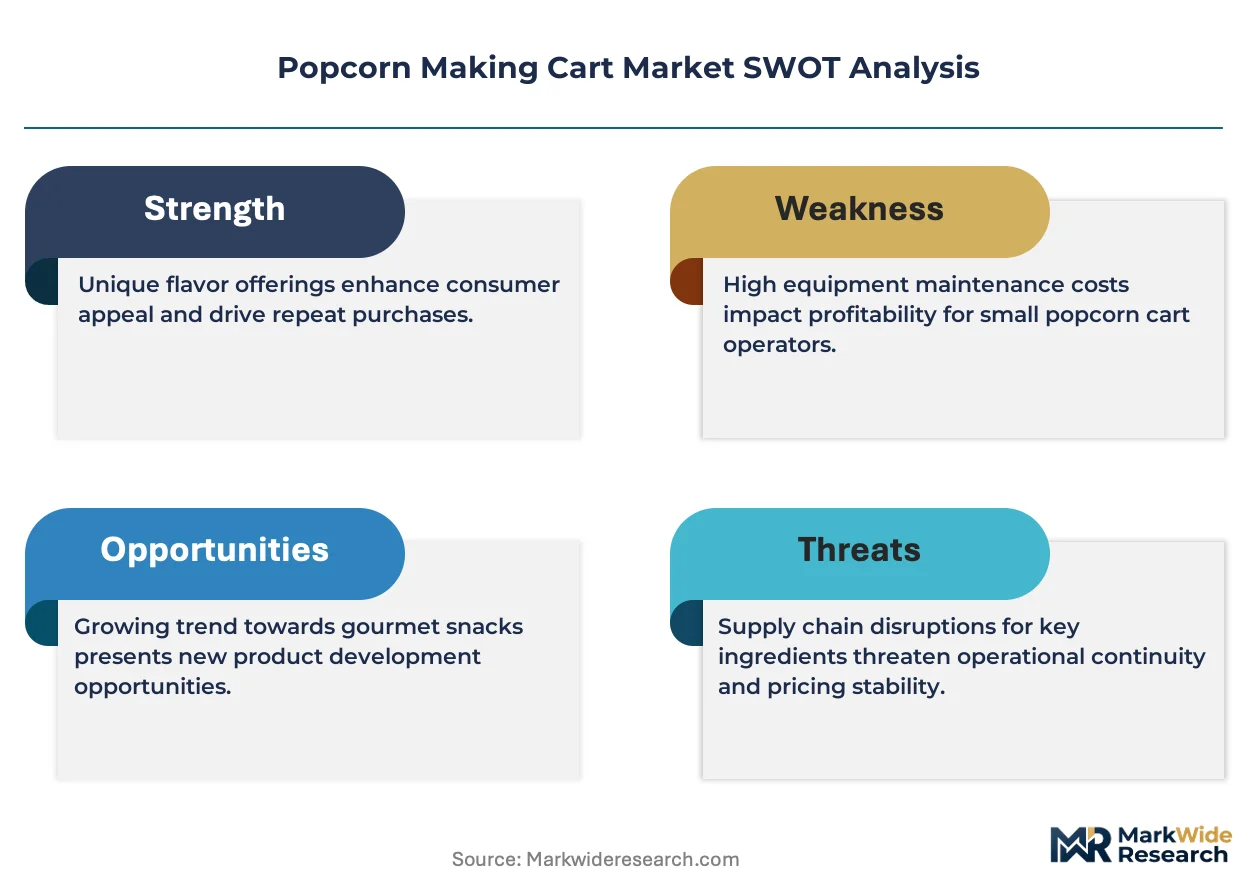
Stainless steel food-contact compliance under FDA and EU frameworks is restructuring manufacturing economics across the popcorn making cart supply base, forcing fabricators to absorb elevated testing costs or exit export channels entirely.
Growth Catalysts
- India's street-food modernization programs:Urban municipal authorities are replacing informal vendors with certified equipment, creating procurement pipelines for NSF-compliant electric carts.
- Southeast Asian cinema expansion:Multiplex operators in Thailand and Vietnam are enlarging concession footprints to diversify revenue beyond ticket sales.
- Electric heating element advancement:Higher-wattage commercial configurations reduce batch-to-batch variability, cutting labor intensity for high-volume stadium operators.
Market Restraints
- 304-grade stainless steel price volatility:Nickel content fluctuations compress fabricator margins on export-bound units.
- Supply concentration in Indian component clusters:Dependence on Pune and Ahmedabad-based metalworking districts creates disruption exposure during monsoon logistics.
- Manual crank model substitution threat:Low-cost mechanical units persist in rural Indian and African informal markets, capping premium electric cart penetration.
Strategic Opportunities
- India's underserved Tier-2 cities:Multiplex construction in Lucknow, Indore, and Kochi outpaces equipment supplier presence.
- CE marking regulatory tailwind:EFSA material safety assessments create qualification barriers that favor established fabricators with in-house testing laboratories.
- Solar-electric hybrid convergence:Battery-assisted heating systems enable deployment at off-grid festival sites and temporary sporting events.
Industry Challenges
- NSF certification timeline compression:Third-party laboratory backlogs extend product launch cycles by four to six months.
- Welding technician scarcity:304-grade food-contact seam certification requires specialized skill sets concentrated in legacy manufacturing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Popcorn Making Cart Market |
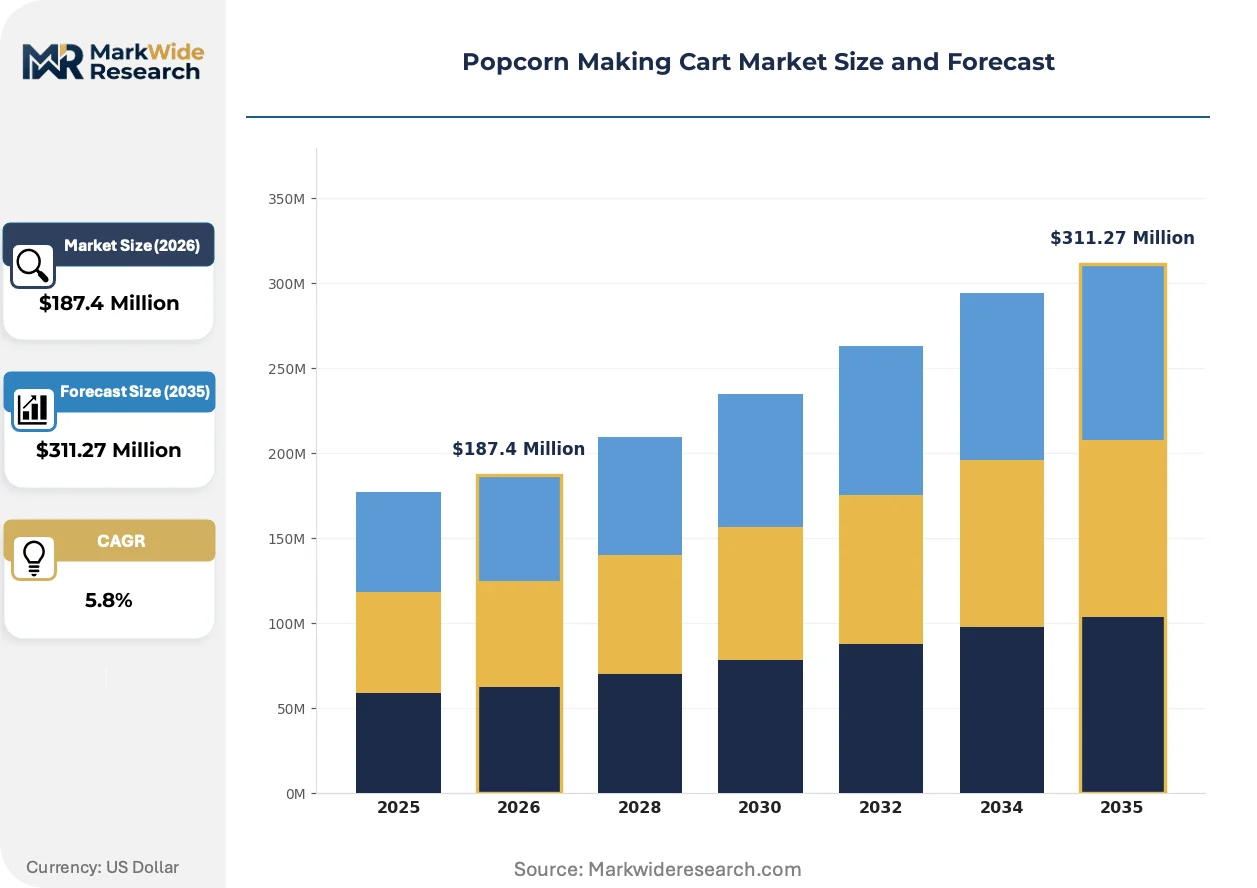
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Carts, Manual Carts, Commercial Carts, Home Carts End User: Concession Stands, Movie Theaters, Sports Venues, Home Users Installation: Mobile, Stationary, Built-in, Removable Distribution Channel: Online Retail, Direct Sales, Wholesalers, Third-Party Vendors |
| Companies Covered | Gold Medal Products Co., Cretors & Co., Paragon International, Inc., Great Northern Popcorn Company, Nostalgia Products LLC, Benchmark USA, Inc., Snappy Popcorn Co., Funtime Popcorn Machines, West Bend Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Popcorn Making Cart Market Evolving Landscape
Equipment design is pivoting toward modularity and energy efficiency as operators face mounting pressure to reduce operating costs and comply with tightening sanitation mandates across multiple jurisdictions.
Infrared radiant heating technology is consolidating control over premium commercial segments. Stadium concessionaires and cinema chains are adopting these systems for faster recovery between batches. The technology is consolidating supplier tiers by rendering lower-wattage conventional elements obsolete in certified commercial applications.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant transitions in enclosed dispensing systems. Manufacturers must redesign cooling circuits to accommodate lower-global-warming-potential alternatives. European-bound export configurations bear the highest redesign burden, with fabricators absorbing prototype validation costs ahead of compliance deadlines.
Buyers are unbundling after-sales service from initial equipment purchases. Regional carnival operators and event rental companies now source maintenance contracts through third-party kitchen equipment servicers rather than original manufacturers. This pattern is most visible in India's fragmented rental market, where asset utilization rates dictate total cost-of-ownership calculations.
Popcorn Making Cart Market Segmentation
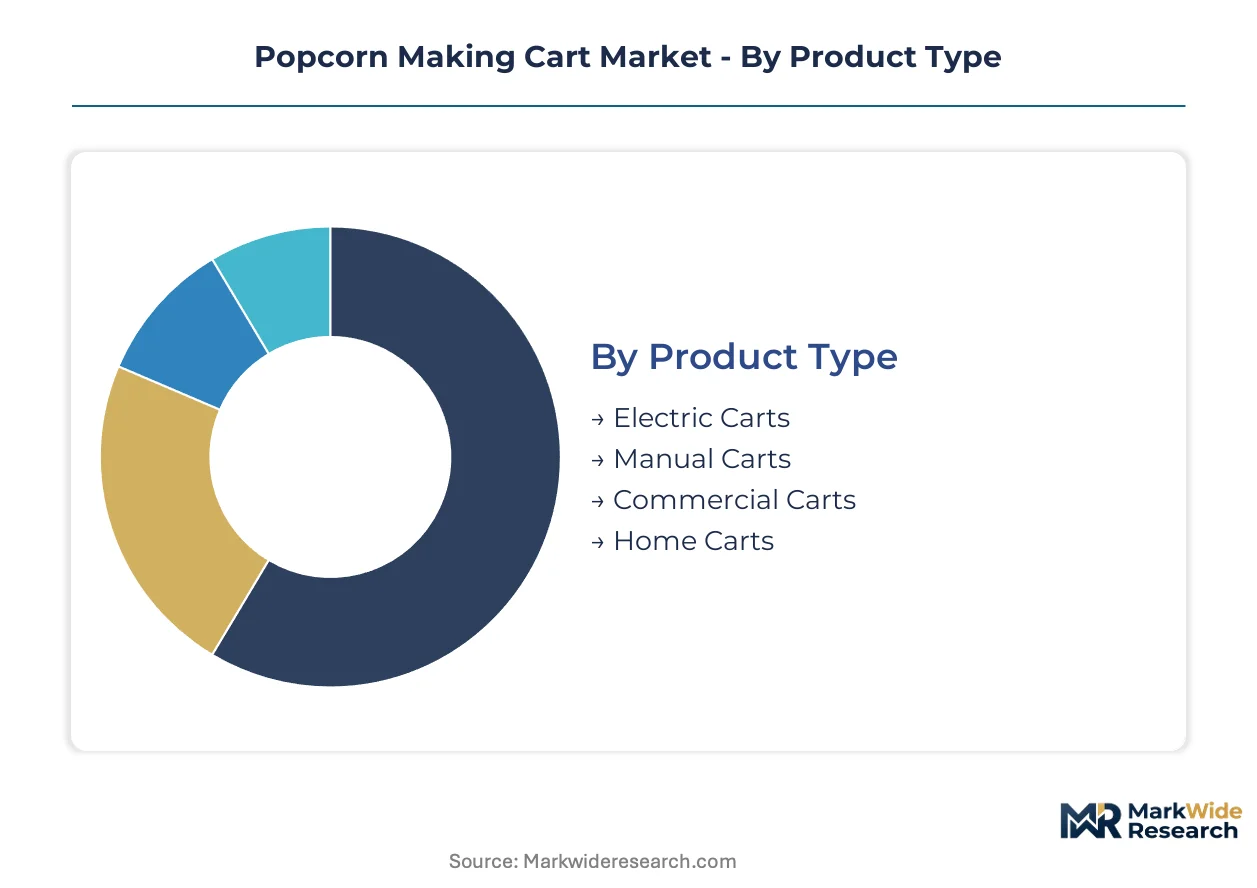
Popcorn making cart procurement patterns diverge sharply across operator scale and venue permanence. Equipment specifications, compliance requirements, and financing mechanisms reshape demand within each segment cluster.
Product Type:
Buyers in this category separate by operational intensity and certification requirements rather than purchase price alone.
- Electric Carts:Configurations deploy 1500-3000 watt heating elements with thermostatic batch control and NSF-certified 304-grade contact surfaces. Demand concentrates in Thailand and Vietnam multiplex chains where labor cost reduction drives concession automation. Stadium operators favor these units for throughput consistency during intermission rushes.
- Commercial Carts:Heavy-gauge stainless construction supports continuous-duty cycles exceeding eight hours with integrated oil filtration and automated stirring mechanisms. India's street-food modernization programs mandate FSSAI-compliant equipment, directing municipal procurement toward this tier.
- Manual Carts:Hand-crank agitation systems with direct-flame or solid-fuel heating occupy informal vendor economics. These units persist in rural Indian and African markets where electricity access remains unreliable.
- Home Carts:Compact countertop designs with 4-8 ounce kettle capacities and simplified thermal controls target residential entertainment use. Online retail channels dominate this price-sensitive tier.
Volume sits with Electric Carts; growth tilts toward Commercial Carts.
End User:
Revenue per square foot and asset utilization rates determine equipment specification intensity across buyer types.
- Movie Theaters:Multiplex operators specify infrared radiant recovery systems and enclosed dispensing with climate control. Southeast Asian cinema chains in Bangkok and Ho Chi Minh City are expanding concession footprints to offset declining ticket yield.
- Sports Venues:Stadium concessionaires demand rapid batch turnaround with modular cart configurations for floor-plan flexibility. Mobile installation types dominate this channel.
- Concession Stands:Independent operators prioritize total cost-of-ownership with third-party maintenance contracts replacing manufacturer service agreements. India's fragmented rental market exhibits this pattern most visibly.
- Home Users:Occasional-use buyers emphasize storage footprint and aesthetic integration over throughput specifications.
Revenue concentrates with Movie Theaters; Sports Venues are expanding most quickly.
Installation:
Permanence of venue infrastructure and floor-plan flexibility requirements segment buyer preferences.
- Mobile:Castor-mounted frames with quick-disconnect electrical and ventilation interfaces enable repositioning within venues. Festival operators and temporary sporting events in India drive demand for battery-assisted hybrid variants.
- Stationary:Fixed-position units with hard-plumbed extraction and dedicated electrical service anchor permanent concession builds. Cinema chains prefer this configuration for brand consistency.
- Built-in:Architecturally integrated enclosures with custom millwork surround standardized popping mechanisms. Premium multiplex developments in Tier-2 Indian cities specify this tier.
- Removable:Drop-in modules allowing seasonal deployment or equipment rotation within multi-use spaces.
Deployment favors Mobile units; Built-in configurations are climbing the fastest.
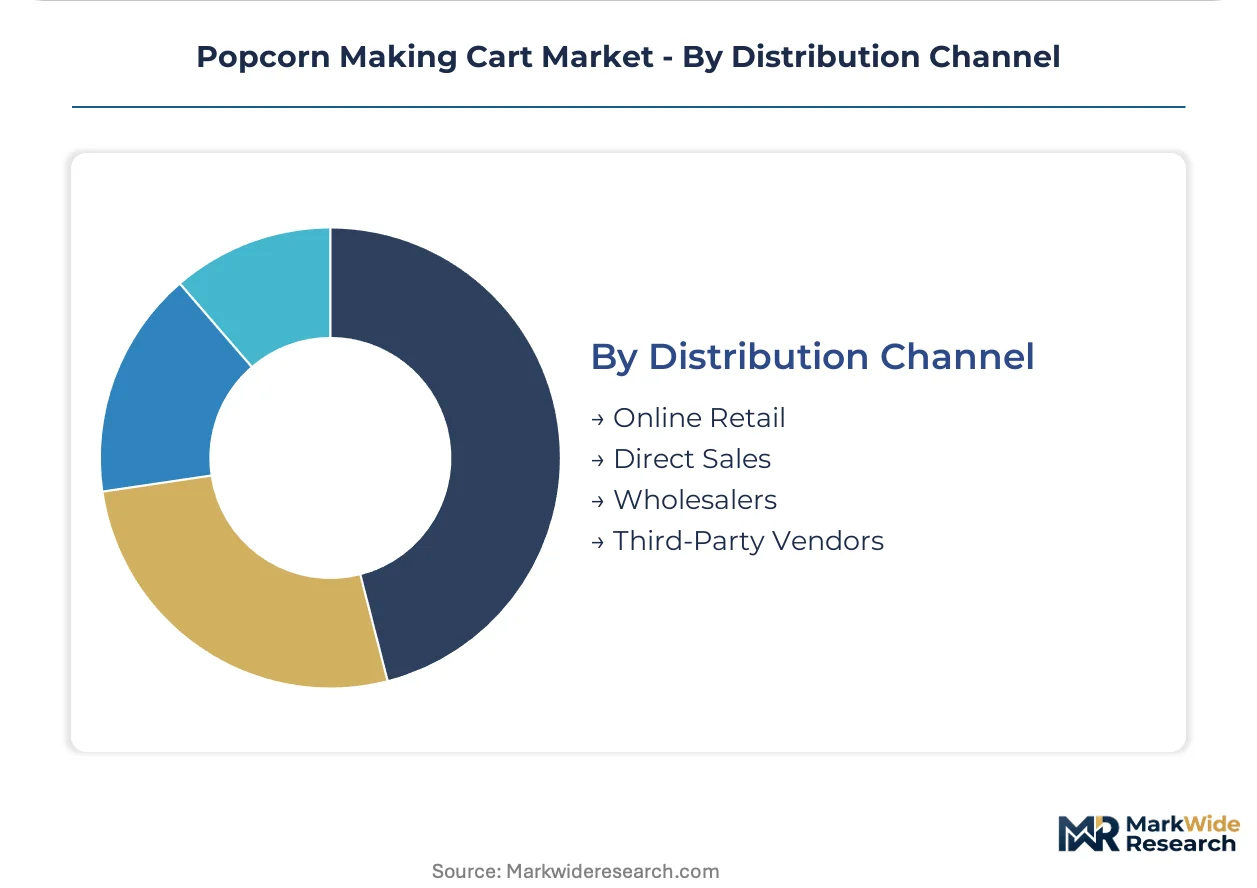
Distribution Channel:
Buyer sophistication and after-sales service requirements determine channel selection patterns.
- Direct Sales:Manufacturer field teams configure NSF-certified systems for cinema chain rollouts with bundled installation and training. Gold Medal Products Co. leverages captive die-stamping capacity to control delivered cost in this channel.
- Online Retail:E-commerce platforms aggregate home cart demand with standardized shipping configurations and return policies. Price transparency compresses margins for smaller fabricators.
- Wholesalers:Regional distributors stock electric and manual units for independent concession operators with credit terms and local service networks.
- Third-Party Vendors:Event rental companies and kitchen equipment servicers source refurbished or secondary-market units for asset-light operators.
Transaction volume flows through Direct Sales; Online Retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nickel ore availability and stainless steel rolling capacity anchor the geographic footprint. Fabrication clusters concentrate near metalworking districts with established food-equipment export infrastructure. Regulatory divergence between FDA and CE marking frameworks shapes supplier qualification requirements.
United States
Multiplex concession automation and stadium renovation cycles drive replacement demand for NSF-certified electric configurations. FDA food-contact surface regulations and NSF International equipment sanitation standards govern product legibility. Cincinnati and Chicago metalworking districts host established fabricators with in-house testing laboratories serving cinema chain rollouts.
India
Urban multiplex construction in Lucknow, Indore, and Kochi accelerates procurement pipelines for FSSAI-compliant equipment. Street-food modernization programs mandate certified electric carts replacing informal vendor setups. Pune and Ahmedabad-based metalworking clusters supply component subassemblies, though monsoon logistics create seasonal disruption exposure.
Germany
EU F-Gas Regulation phase-down schedules force redesign cycles for enclosed dispensing systems with climate control. CE marking and EFSA material safety assessments condition market access, elevating compliance costs for smaller fabricators. Bavarian industrial equipment manufacturers anchor premium-tier supply for European cinema chains.
Thailand
Multiplex operators in Bangkok enlarge concession footprints to diversify revenue beyond ticket yield. Local content requirements and municipal vendor certification programs structure procurement. Eastern Economic Corridor manufacturing zones attract component assembly operations serving Southeast Asian distribution networks.
Vietnam
Ho Chi Minh City cinema chains expand concession automation alongside new multiplex developments. BIS-equivalent equipment safety assessments govern import clearance for electric heating configurations. Northern industrial provinces around Hanoi concentrate metal fabrication subcontracting for regional equipment assemblers.
Popcorn Making Cart Market Competitive Landscape
Capacity expansion dominates the current landscape as established fabricators add captive die-stamping and testing infrastructure. The supplier base stratifies into three tiers: heritage brands with century-old cinema channel relationships, mid-scale specialists with regional carnival focus, and price-competitive assemblers serving informal markets. Competitive positioning hardens around NSF certification speed, stainless steel sourcing relationships, and aftermarket service network density. Fabricators defend margin position through backward integration into kettle production and multi-source component strategies.
Within the heritage-brand tier, Gold Medal Products Co. and Cretors & Co. occupy positions defined by long-standing cinema and stadium channel presence. Paragon International, Inc. exemplifies the specialist archetype with compact electric configurations. Chinese and Indian Co., Ltd. structures populate the volume-driven segment with price-accessible manual and electric units. Geographic origin visible in company naming—Zhengzhou, Ahmedabad, Mumbai—signals cluster proximity to metalworking districts. GmbH and AG suffixes indicate European-based fabricators bearing CE marking compliance burdens. The "Others" category captures fragmented regional assemblers without export certification capacity.
| Leading Market Players |
|---|
| Gold Medal Products Co. |
| Cretors & Co. |
| Paragon International, Inc. |
| Great Northern Popcorn Company |
| Nostalgia Products LLC |
| Benchmark USA, Inc. |
| Snappy Popcorn Co. |
| Funtime Popcorn Machines |
| West Bend Company |
| Others |
Value Network & Pricing Analysis
Nickel price volatility on the London Metal Exchange cascades through 304-grade stainless steel procurement into three distinct pricing tiers across the popcorn making cart supply base. Fabricators absorbing elevated alloy costs compress margins on economy-grade manual units while passing through premiums on NSF-certified electric configurations to cinema chain buyers.
Pricing Analysis
Warranty and after-sales service unbundling is restructuring buyer economics across the popcorn making cart market. Three-tier pricing structure across premium, standard, and economy levels separates NSF-certified commercial electric carts with bundled installation from stripped-down manual units sold through wholesale channels. Price differentiation hinges on certification grade and geographic delivery cost, with Indian municipal procurement mandating FSSAI compliance that elevates standard-tier pricing. Cost compression in the economy segment is intensifying because Chinese and Indian assemblers compete on spot stainless steel purchases. Home users exhibit highest price sensitivity, while multiplex operators in Thailand and Vietnam demonstrate lowest sensitivity due to revenue-per-square-foot calculations.
Supply Chain Analysis
NSF and CE marking qualification gates concentrate supply chain control among fabricators with in-house testing laboratories in the United States, Germany, and India. Component sourcing draws from Pune and Ahmedabad metalworking clusters for kettle subassemblies, nickel-bearing stainless steel from Indonesian and Philippine ore processing, and electric heating elements from Chinese ceramics manufacturers. Single-source vulnerability in monsoon-exposed Indian logistics corridors creates seasonal disruption exposure for export-bound units. Distribution runs through direct sales teams for cinema chain rollouts, regional wholesalers for independent concession operators, and e-commerce platforms for home cart segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around certification-capable fabricators as FDA and EU compliance costs force sub-scale assemblers toward exit or captive acquisition.
For Market Incumbents: Extend captive die-stamping capacity into kettle production to defend margin position against nickel price volatility. Acquire distressed NSF certification pipelines from failing regional fabricators in India's Tier-2 cities. Backward integration into 304-grade stainless sourcing relationships anchors cost control against LME nickel swings. For New Entrants and Emerging Players: The mid-tier price gap between Gold Medal Products Co. premium positioning and Ahmedabad-based manual assemblers creates entry space for FSSAI-certified electric carts. Target India's underserved Lucknow and Indore multiplex construction pipelines with rapid NSF certification turnaround. Deploy third-party maintenance bundling to match incumbent service networks without capital-heavy field infrastructure. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale specialists with dormant CE marking capacity in Bavarian industrial zones. Long-term viability rests on regulatory qualification moats widening through EU F-Gas redesign burdens and FDA testing backlogs. Watch NSF certification laboratory queue lengths as inflection indicator for supplier tier consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kettle Production | Captive die-stamping at Gold Medal Products Co. insulates margin from nickel volatility. |
| NSF Certification Fast-Track Investment | In-house testing laboratories compress four-to-six month third-party backlogs for cinema rollouts. |
| Multi-Source Component Strategy | Diversification beyond Pune and Ahmedabad clusters reduces monsoon logistics exposure. |
| Solar-Electric Hybrid Development | Battery-assisted heating opens off-grid festival and temporary sporting event deployment. |
| Third-Party Maintenance Partnership | Unbundled service contracts align with Indian rental market asset utilization economics. |
Research Methodology
Document review covered trade customs data, NSF International certification registries, and EU F-Gas Regulation implementation notices, complemented by interviews with cinema concession procurement directors, stainless steel fabricator operations managers, and municipal street-food modernization officers. Secondary validation drew from FDA food-contact surface guidance documents, EFSA material safety assessments, and Indian FSSAI equipment compliance circulars. Bottom-up unit shipment estimates from component suppliers triangulated against top-down venue construction pipelines across the analysis window.
Segmented volume and value trajectories emerged from modeling across product type, installation permanence, end-user scale, and geographic regulatory cluster dimensions. CAGRs derived from curve-fitting historical procurement cycles against multiplex construction permits and municipal vendor certification mandates. Forecast inputs incorporated nickel price band scenarios, monsoon logistics disruption frequencies, and infrared heating element adoption curves in stadium channels.
Inputs from NSF laboratory certification queues and Indian municipal procurement databases were available through the study window; gaps in real-time stainless steel inventory positions at Pune fabricators introduce uncertainty bands around cost pass-through assumptions. Forecasts reflect documented assumptions on certification timeline compression and alloy price volatility persistence. A model refresh is warranted upon material change in EU F-Gas refrigerant phase-down schedules or FDA state-level energy efficiency mandate expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Latin America Online Grocery Delivery Market
Food Service
Global Virtual Restaurant and Ghost Kitchens Market
Food Service
Europe Food Service Market
Food Service
Hyperlocal Grocery Delivery Market
Food Service
Electric Tiffin Market
Food Service
India Quick Service Restaurant Market
Food Service
Philippines Foodservice Market
Food Service
Cambodia Foodservice Market
Food Service
Europe Barbeque Grill Market
Food Service
Onboard Rail Catering Market
Food Service
Stirrers Market
Food Service
Europe Pizza Oven Market
Food Service
Commercial Pizza Oven Market
Food Service
Beverage Vending Machine Market
Food Service
Brazil Foodservice Market
Food Service
Meal Kit Delivery Services Market