
 Frying Shortening Market | 2026-2036
Frying Shortening Market Size, Share, and Industry Trends Forecast 2026-2036
Frying Shortening Market Foresight
Southeast Asian palm oil processing capacity is hardening as the dominant upstream supply base for frying shortening feedstock. Cargill Incorporated leverages its integrated oilseed crush and refining footprint across multiple continents to secure cost-advantaged supply chains. Wilmar International Limited anchors its position through deep vertical control of palm oil origination, refining, and distribution into foodservice channels. Bunge Global SA competes on oilseed processing scale and geographic diversification of its edible oils portfolio.
Frying shortening comprises refined, partially hydrogenated or interesterified fats engineered for thermal stability, with smoke points typically exceeding 230°C and oxidative stability indices tailored for repeated frying cycles in commercial food preparation. Palm oil-based shortening dominates volume production due to its natural semi-solid crystalline structure and competitive cost position, while soybean oil-based variants gain traction in North American formulations responding to sustainability sourcing pressures. Snack manufacturing commands premium formulations with extended fry life, whereas quick service restaurants prioritize bulk packaging economics and consistent performance across distributed kitchen networks.
The U.S. FDA enforces zero grams trans fat labeling thresholds that compel reformulation away from partial hydrogenation, while Indonesia's BIS-equivalent national standards govern palm olein quality grades for export markets. The EU F-Gas Regulation and REACH chemical safety frameworks indirectly constrain processing aid chemistries used in interesterification catalyst systems. Stakeholders must monitor evolving national dietary fat policies and oleochemical feedstock certification schemes to anticipate reformulation costs and sourcing geography shifts.
Market Dynamics
The U.S. FDA's trans fat labeling mandates and Indonesia's export-grade palm olein standards are forcing simultaneous reformulation across multiple continents, compressing product development cycles and redrawing sourcing maps.
Growth Catalysts
- Quick service restaurant procurement:Chains are standardizing on high-oleic frying shortenings to extend oil life and cut kitchen operational costs.
- REACH chemical safety frameworks:EU processing aid restrictions are accelerating interesterified fat adoption as a technically compliant pathway.
- Southeast Asian palm clusters:Indonesia and Malaysia's integrated refining infrastructure supplies feedstock at scale to regional manufacturers.
Market Restraints
- Crude palm oil price volatility:Weather-driven supply swings in Malaysian estates transmit directly into shortening cost structures.
- Single-origin concentration risk:Over 80 percent of global palm oil origination sits within Indonesia-Malaysia processing corridors.
- Partial hydrogenation technical ceiling:Trans fat thresholds render legacy catalyst systems non-viable for new product development.
Strategic Opportunities
- Indian foodservice penetration:Organized QSR expansion in tier-two cities creates first-mover positioning for packaged shortening suppliers.
- Interesterification-palm olein convergence:Blending enzymatic restructuring with natural semi-solid feedstock unlocks clean-label positioning.
- Brazilian biofuel policy spillover:Soybean oil diversion to biodiesel mandates is forcing snack manufacturers toward alternative frying fat sourcing.
Industry Challenges
- Oil stability technician scarcity:Formulation chemists with combined lipid chemistry and thermal oxidation expertise command premium compensation.
- Multi-jurisdiction certification lag:Simultaneous FDA, EFSA, and BIS-equivalent approvals extend new product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frying Shortening Market |
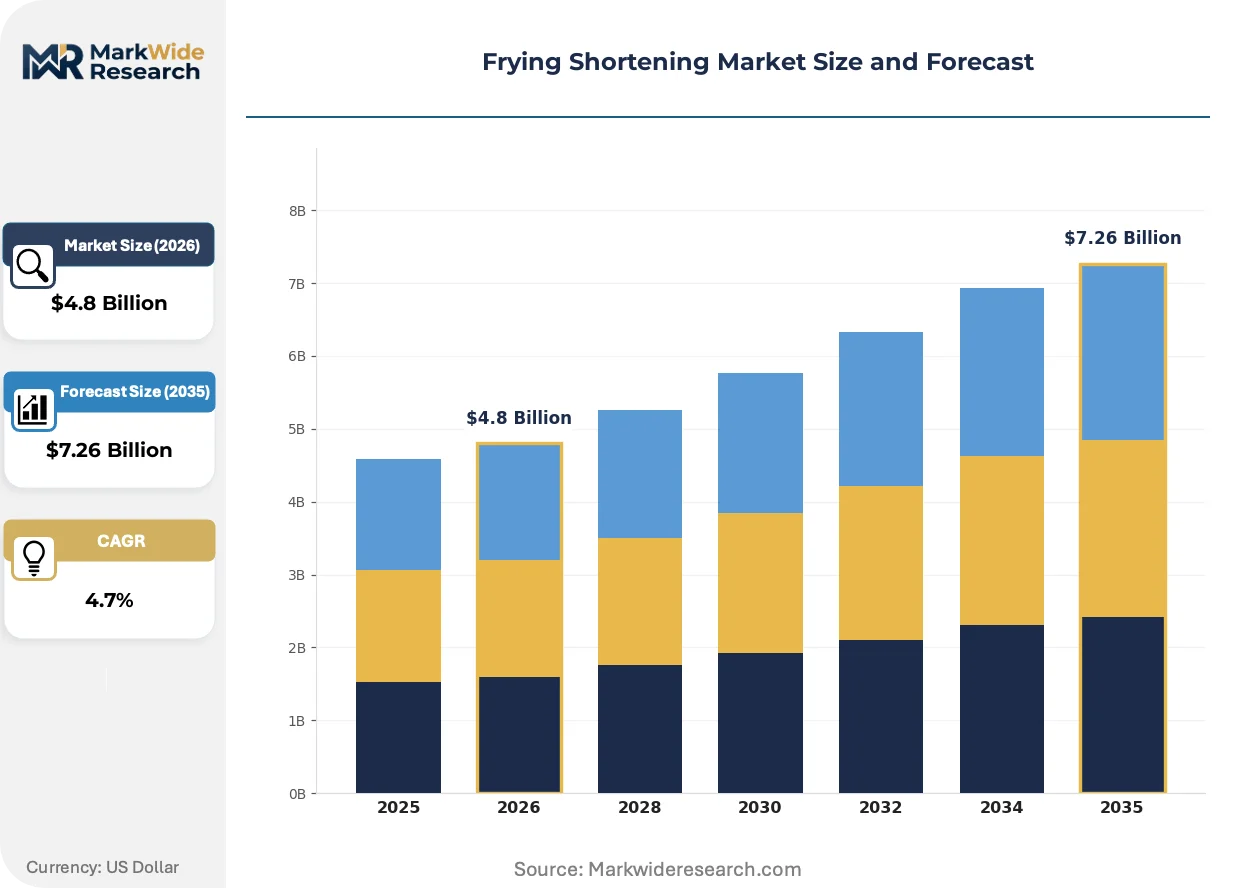
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.26 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetable Oil-Based, Animal Fat-Based, Blend Shortening, Palm Oil-Based, Soybean Oil-Based Application: Restaurant Cooking, Food Processing, Commercial Kitchens, Snack Manufacturing, Catering Services End User Type: Quick Service Restaurants, Foodservice Distributors, Institutional Food Providers, Bakery Chains, Culinary Schools Packaging Type: Cartons, Plastic Tubs, Metal Cans, Bulk Containers, Sachets |
| Companies Covered | AAK AB, Fuji Oil Co. Ltd., Cargill Incorporated, Palsgaard AS, Conagra Brands, Archer Daniels Midland Company, Wilmar International Limited, Ventura Foods, Bunge Global SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frying Shortening Market Shifts & Advancements
Enzymatic interesterification and high-oleic seed breeding are converging to eliminate trans fats while preserving the crystalline structure that commercial fryers require for consistent performance.
Enzymatic interesterification systems are electrifying the technical pathway for trans fat elimination in premium frying shortenings. North American snack manufacturers are adopting these catalyst platforms at accelerated pilot-to-production scales. The technology is electrifying margin compression across legacy partial hydrogenation equipment bases as capital redeploys toward bioreactor infrastructure.
EU F-Gas Regulation constraints on fluorinated processing aids are reshaping catalyst selection in European interesterification facilities. Industrial consequence includes forced migration toward lipase-based enzymatic systems with higher feedstock flexibility. Snack manufacturing lines in Germany and the Netherlands are absorbing reformulation costs fastest, with palm-sunflower blends displacing hydrogenated soybean stocks.
Foodservice distributors are consolidating shortening procurement into annual volume contracts with technical service attachments. Independent restaurant operators are losing negotiating leverage as broadline distributors bundle frying fats with equipment maintenance programs. This consolidation is most visible in U.S. metropolitan markets where Sysco and US Foods route density enables just-in-time bulk delivery with oil quality monitoring.
Frying Shortening Market Segmentation
Frying shortening procurement cycles track equipment replacement timelines in commercial kitchens, with reformulation mandates from FDA and EFSA compressing product upgrade windows. Segment boundaries shift as enzymatic interesterification displaces legacy hydrogenation infrastructure across food manufacturing and foodservice channels.
Product Type:
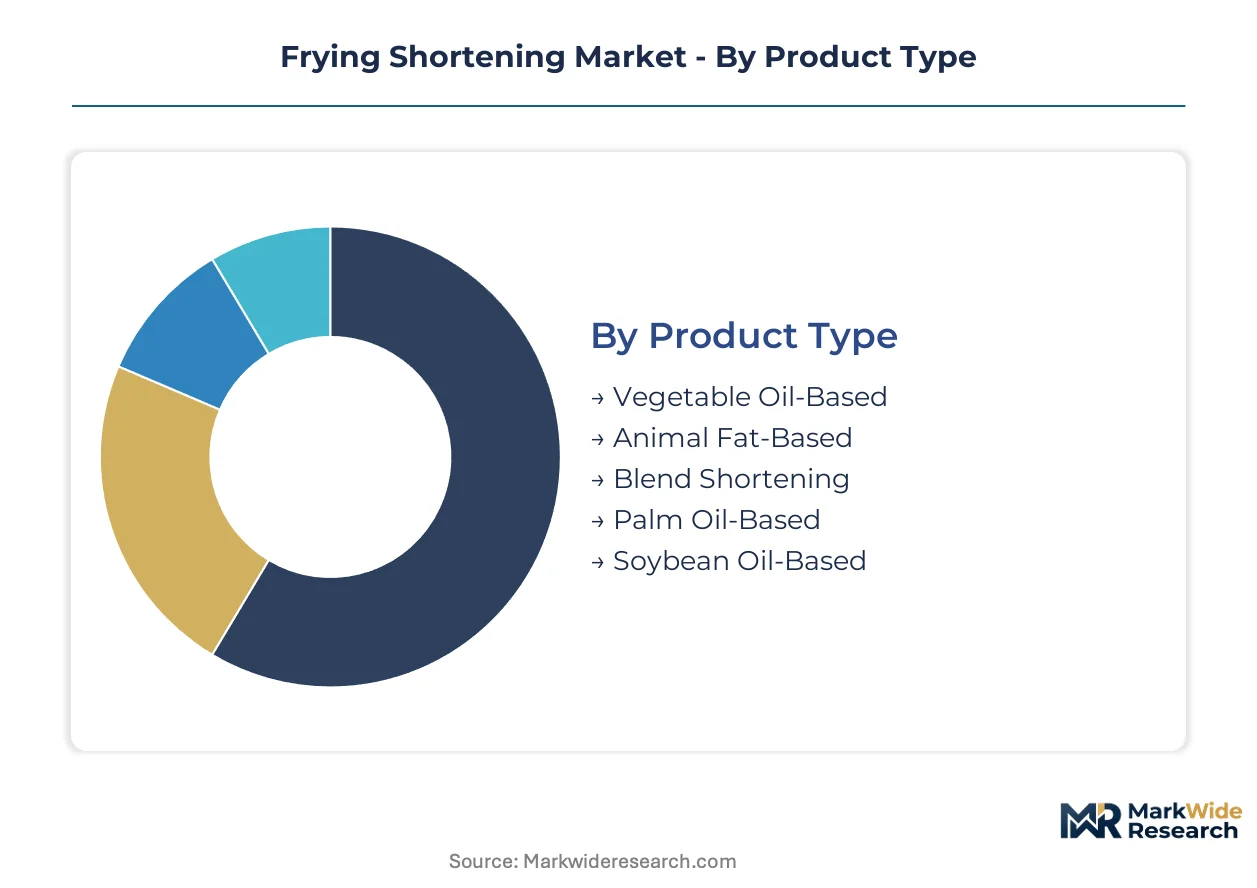
Reformulation cycles for trans fat compliance are accelerating replacement demand across all product categories, with thermal stability specifications now dictating procurement decisions.
- Vegetable Oil-Based:Refined, bleached, and deodorized oil stocks interesterified or blended to achieve target solid fat indices and smoke points above 230°C. North American snack manufacturers are migrating toward high-oleic sunflower and canola bases to satisfy clean-label positioning while maintaining fry life performance.
- Palm Oil-Based:Natural beta-prime crystalline structure delivers inherent solidity without hydrogenation, with Indonesian and Malaysian refining clusters supplying olein and stearin fractions at scale. Quick service restaurants in Southeast Asia specify this category for bulk procurement economics and oxidative stability across extended frying cycles.
- Animal Fat-Based:Rendered tallow and lard fractions retain niche positioning in traditional bakery applications and specific regional cuisines.
- Blend Shortening:Interesterified or physically mixed systems combining palm, soybean, and tropical oils to optimize cost-performance ratios.
- Soybean Oil-Based:High-oleic breeding programs and enzymatic restructuring are expanding application scope beyond biodiesel feedstock diversion.
Palm Oil-Based sits at the top of the volume ranking, with Soybean Oil-Based climbing the fastest.
Application:
Volume concentration patterns trace foodservice channel density, with centralized procurement in chain operations reshaping demand distribution across preparation environments.
- Snack Manufacturing:Continuous fryer operations demand shortenings with extended fry life indices and minimal foam generation during high-temperature processing. German and Dutch manufacturers are absorbing premium costs for enzymatic interesterification to satisfy EU F-Gas Regulation constraints on fluorinated processing aids.
- Quick Service Restaurants:Distributed kitchen networks require consistent performance across variable equipment ages and temperature control precision. Chains are standardizing on high-oleic formulations with technical service attachments from distributors like Sysco and US Foods.
- Restaurant Cooking:Independent operators face procurement consolidation pressure as broadline distributors bundle shortening with equipment maintenance programs.
- Food Processing:Industrial-scale bakeries and prepared food manufacturers specify shortening by solid fat content and plasticity ranges.
- Commercial Kitchens:Institutional cafeterias and hospitality operations prioritize bulk packaging economics over formulation sophistication.
- Catering Services:Mobile and event-based food preparation drives demand for portable packaging formats with extended ambient stability.
Snack Manufacturing commands the highest formulation premiums, with Quick Service Restaurants expanding volume share most rapidly.
End User Type:
Procurement authority is consolidating into fewer decision-makers, with technical specification influence shifting from kitchen operators to supply chain and quality assurance functions.
- Quick Service Restaurants:Corporate procurement teams negotiate annual volume contracts with embedded technical service for oil quality monitoring and fryer management protocols. Chains with route density in U.S. metropolitan markets leverage just-in-time bulk delivery to minimize inventory carrying costs.
- Foodservice Distributors:Broadline operators are capturing margin by bundling shortening procurement with equipment maintenance and oil filtration services.
- Institutional Food Providers:Hospital, school, and corporate cafeteria systems specify by nutritional profile compliance and cost per frying cycle.
- Bakery Chains:Central commissaries demand consistent crystallization behavior for laminated dough applications.
- Culinary Schools:Training institutions represent specification influence rather than volume, with curriculum choices shaping future chef preferences.
Foodservice Distributors are consolidating decision authority fastest, with Quick Service Restaurants maintaining the largest absolute procurement volumes.
Packaging Type:
Packaging selection correlates with user scale and kitchen infrastructure, with bulk systems penetrating deepest in chain operations and cartons retaining position in fragmented independent segments.
- Bulk Containers:Stainless steel totes and flexitank systems deliver 1,000+ liter quantities to central commissaries and high-volume fryer banks. U.S. metropolitan QSR clusters with distributor route density achieve lowest per-unit costs through this format.
- Plastic Tubs:10-20 liter polyethylene containers balance handling convenience with cost efficiency for mid-scale independent restaurants.
- Metal Cans:Traditional tinplate packaging retains position in specialty and export markets requiring extended shelf stability.
- Cartons:Paperboard with polyethylene liners serves small independent operators and retail channel distribution.
- Sachets:Single-portion foil pouches address airline catering, military rations, and emergency foodservice applications.
Bulk Containers dominate volume throughput, with Plastic Tubs gaining penetration in tier-two city foodservice expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between trans fat enforcement regimes is redirecting production investment toward jurisdictions with stable compliance costs. Southeast Asian palm oil clusters capture reformulation-driven demand as North American and European manufacturers absorb higher catalyst and certification expenses.
United States
Quick service restaurant chains drive procurement of high-oleic frying shortenings to extend oil life across distributed kitchen networks. The FDA maintains zero grams trans fat labeling thresholds that compel continuous reformulation away from partial hydrogenation. Chicago and Dallas metropolitan clusters concentrate distributor route density for just-in-time bulk shortening delivery with embedded technical service.
Indonesia
Integrated palm oil processing infrastructure supplies olein and stearin fractions at scale to regional frying shortening manufacturers. BIS-equivalent national standards govern palm olein quality grades for export markets, creating certification friction for non-compliant feedstock. Medan and Surabaya refining corridors anchor downstream shortening production capacity serving foodservice channels across Southeast Asia.
Germany
Snack manufacturers absorb premium costs for enzymatic interesterification to satisfy EU F-Gas Regulation constraints on fluorinated processing aids. EFSA dietary fat evaluations influence reformulation specifications for industrial bakery and prepared food applications. The Rhine-Ruhr industrial corridor hosts interesterification facilities blending palm-sunflower stocks for continental European distribution.
India
Organized quick service restaurant expansion in tier-two cities creates procurement opportunities for packaged shortening suppliers with technical service capabilities. FSSAI nutritional labeling requirements and import tariff structures on refined palm oil reshape cost-performance calculations for domestic formulators. Mumbai and Delhi-NCR foodservice distribution hubs concentrate decision authority for national chain procurement.
Brazil
Soybean oil diversion to biodiesel mandates under national biofuel policy frameworks is forcing snack manufacturers toward alternative frying fat sourcing. ANVISA food additive regulations govern interesterification catalyst approvals, extending product development timelines. São Paulo state oilseed processing complexes face feedstock competition from renewable diesel offtake agreements.
Frying Shortening Market Competitive Landscape
Southeast Asian producers anchor one tier through captive palm oil supply; North American and European specialists hold position through enzymatic processing capabilities and technical service bundling. Market structure reflects dual concentration: upstream origination clusters in Indonesia-Malaysia corridors, and downstream formulation expertise in jurisdictions with stringent trans fat enforcement. Three archetypes dominate: integrated agribusiness conglomerates with refining-to-distribution control; regional oilseed processors with geographic diversification; and specialty lipid formulators with enzymatic restructuring capabilities. Competitive moves center on backward integration into oleochemical feedstock and strategic partnerships with foodservice distributors for route-dense just-in-time delivery.
Among integrated agribusiness conglomerates, Wilmar International Limited and Cargill Incorporated exemplify archetypes of vertical control spanning origination through foodservice channel distribution. Bunge Global SA occupies a position representing oilseed processing scale across multiple continents. These entities anchor competitive dynamics through upstream supply security and downstream procurement consolidation with quick service restaurant chains.
| Leading Market Players |
|---|
| AAK AB |
| Fuji Oil Co. Ltd. |
| Cargill Incorporated |
| Palsgaard AS |
| Conagra Brands |
| Archer Daniels Midland Company |
| Wilmar International Limited |
| Ventura Foods |
| Bunge Global SA |
| Others |
Supply & Pricing Matrix
Quick service restaurant procurement standardization on high-oleic formulations is compressing supplier margins and forcing feedstock diversification across palm and oilseed processors. FDA trans fat mandates and EU F-Gas Regulation compliance costs are layering certification premiums onto base shortening prices, with cost pass-through varying by distributor scale and route density.
Pricing Analysis
Distributor margin capture dominates pricing architecture in metropolitan U.S. foodservice corridors, where Sysco and US Foods bundle technical service with bulk shortening contracts. Three-tier pricing structure across premium enzymatic interesterification, standard palm-olein blends, and economy hydrogenated legacy stocks reflects formulation complexity and certification grade. Cost compression in standard-tier products is intensifying because Indonesian palm olein export tariffs and Malaysian weather-driven supply swings transmit directly into feedstock costs. Independent restaurant operators exhibit highest price sensitivity, while national QSR chains absorb premiums for embedded fryer management protocols and oil quality monitoring.
Supply Chain Analysis
Single-source vulnerability sits with Indonesian and Malaysian palm oil origination corridors, which supply over four-fifths of global feedstock for frying shortening production. Crude palm oil, high-oleic soybean oil, and enzymatic catalyst systems constitute the critical input triad, with Brazilian soybean oil increasingly diverted to biodiesel mandates under ANVISA frameworks. Commodity price volatility in Malaysian estates and tariff exposure on refined palm olein imports into India represent persistent structural risks. Distribution runs through broadline foodservice operators consolidating shortening procurement with equipment maintenance and filtration services in U.S. and European metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Frying shortening functions as a stable compounder anchored by irreversible regulatory mandates that perpetuate reformulation demand across food manufacturing and foodservice channels.
For Market Incumbents: Extend technical service bundling into predictive fryer management systems that lock in annual volume contracts with quick service restaurant chains. Deepen backward integration into Indonesian palm olein origination to offset Malaysian supply volatility and secure cost-advantaged feedstock positions against emerging enzymatic specialists. Certification investment in simultaneous FDA, EFSA, and BIS-equivalent approvals compresses competitor launch timelines and reinforces distributor exclusivity arrangements. For New Entrants and Emerging Players: Tier-two city foodservice distributors in India represent the most penetrable buyer archetype, with organized QSR expansion outpacing packaged shortening supplier technical capabilities. Specialty lipid formulators with enzymatic restructuring expertise can capture premium positioning in German and Dutch snack manufacturing lines facing EU F-Gas Regulation catalyst constraints. A go-to-market angle anchored in clean-label palm-sunflower blend formulations with embedded oil stability monitoring addresses unmet technical service gaps. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale enzymatic interesterification specialists possessing lipase-based catalyst platforms and established BIS-equivalent certification pathways. Long-term viability over a five-to-ten-year horizon rests on regulatory divergence persisting between trans fat enforcement regimes, with acquisition targets commanding premium valuations for multi-jurisdiction approval capabilities. The signal to watch is Brazilian biofuel policy spillover accelerating soybean oil diversion and forcing snack manufacturer sourcing shifts toward palm-based alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Palm Olein Origination | Captive supply from Indonesian refining corridors insulates margin compression from Malaysian weather-driven volatility. |
| Enzymatic Interesterification Capacity Expansion | Lipase-based bioreactor deployment satisfies FDA trans fat thresholds while displacing legacy hydrogenation equipment bases. |
| Technical Service Bundling with Distributors | Embedded fryer management protocols lock in annual volume contracts with Sysco and US Foods route-dense networks. |
| Multi-Jurisdiction Certification Investment | Simultaneous FDA, EFSA, and BIS-equivalent approvals extend competitor product launch timelines and reinforce exclusivity. |
| High-Oleic Seed Breeding Partnerships | North American sunflower and canola varietal development expands clean-label formulation scope beyond palm dependency. |
Research Methodology
Coverage spans the United States, Indonesia, Germany, India, and Brazil, with primary inputs from each jurisdiction triangulated against secondary validation. Interviews with quick service restaurant procurement directors, broadline foodservice distributor category managers, palm oil refinery operations heads, snack manufacturing R&D directors, and enzymatic catalyst technology suppliers informed demand-side and supply-side dynamics. Secondary sources include FDA trans fat labeling guidance documents, EFSA dietary fat evaluations, Indonesian BIS-equivalent export standards, FSSAI nutritional labeling requirements, and ANVISA food additive regulations, cross-referenced with customs trade data on crude palm oil and refined olein movements. Bottom-up volume modeling by product type and application segment was reconciled with top-down market sizing across the analysis window.
Granularity-level modeling tracked vegetable oil-based, palm oil-based, animal fat-based, blend, and soybean oil-based product categories against snack manufacturing, quick service restaurant, restaurant cooking, food processing, commercial kitchen, and catering service applications. End user type segmentation captured quick service restaurants, foodservice distributors, institutional food providers, bakery chains, and culinary schools with associated packaging format preferences. CAGRs were derived from segment-level volume trajectories adjusted for regulatory reformulation cycle timing and equipment replacement patterns in commercial fryer installations. Industry-specific forecast inputs incorporated high-oleic seed breeding program adoption rates and enzymatic interesterification capacity buildout timelines.
Underlying measurement precision varies by segment; quick service restaurant and snack manufacturing applications carry tighter precision than fragmented independent restaurant and catering channels due to consolidated procurement visibility. Forecasts reflect assumptions on regulatory enforcement continuity, palm oil supply chain stability, and enzymatic catalyst cost curves that could shift materially with Indonesian export policy changes or breakthroughs in chemical interesterification efficiency. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Canada Food Flavor and Enhancer Market
Food Enhancers and Additives
United States Water Enhancer Market
Food Enhancers and Additives
Food Raising Agents Market
Food Enhancers and Additives
France Water Enhancer Market
Food Enhancers and Additives
Water Enhancer Market
Food Enhancers and Additives
Europe Water Enhancer Market
Food Enhancers and Additives
Liquid Smoke Market
Food Enhancers and Additives
Global Citrus Aurantium Extract Market
Food Enhancers and Additives
Trans-Resveratrol Market
Food Enhancers and Additives
Crumb Softener Market
Food Enhancers and Additives
United Kingdom Water Enhancer Market
Food Enhancers and Additives
Isomalt Market
Food Enhancers and Additives
Isoprenol Market
Food Enhancers and Additives
Emulsifier Enhancers Market
Food Enhancers and Additives
Feed Palatability Enhancers and Modifiers Market
Food Enhancers and Additives
United Kingdom Interesterified Fats Market