
 Neodymium [Nd-Fe-B] Magnet Market | 2026-2036
Neodymium [Nd-Fe-B] Magnet Market Size, Share, and Industry Trends Forecast 2026-2036
Neodymium [Nd-Fe-B] Magnet Market Outlook
Automotive OEM consolidation in electric drivetrain procurement is realigning magnet demand toward fewer, larger contracts. Proterial leverages integrated rare earth sourcing from mine to magnet to secure long-term supply commitments. Shin-Etsu Chemical anchors high-volume sintered magnet production for Japanese and European automotive programs. VACUUMSCHMELZE differentiates through specialized grades serving aerospace and medical device specifications.
Neodymium [Nd-Fe-B] magnets consist of an Nd₂Fe₁₄B tetragonal crystal structure produced through powder metallurgy sintering or polymer-bonded compaction, delivering maximum energy products exceeding 50 MGOe for compact, high-torque applications. Sintered magnets dominate volume due to superior magnetic performance in automotive traction motors, while bonded magnets occupy cost-sensitive consumer electronics where complex geometries outweigh peak flux density. Metallic magnets retain niche industrial equipment roles where thermal stability exceeds raw magnetic strength priorities.
China's MIIT governs rare earth mining quotas and export licensing, directly constraining global Nd-Fe-B feedstock availability. REACH and RoHS in Europe impose substance restrictions and supply chain disclosure requirements that elevate compliance costs for magnet importers. Stakeholders must monitor regulatory fragmentation between China's export controls and Western circular-economy mandates as they reshape sourcing strategies and recycling investments.
Market Dynamics
Automotive OEMs are consolidating electric drivetrain procurement into multi-year magnet supply agreements, compressing supplier bases and forcing magnet manufacturers to secure captive rare earth processing capacity.
Growth Catalysts
- Dual carbon goals:China's MIIT production quotas and carbon-neutral mandates are accelerating domestic Nd-Fe-B capacity expansion for EV traction motors.
- EV powertrain electrification:Sintered Nd-Fe-B magnets are displacing ferrite in automotive traction motors due to torque density requirements in 800V architectures.
- Inner Mongolia processing clusters:Concentrated rare earth separation and alloying infrastructure in Baotou reduces feedstock transit costs for magnet manufacturers.
Market Restraints
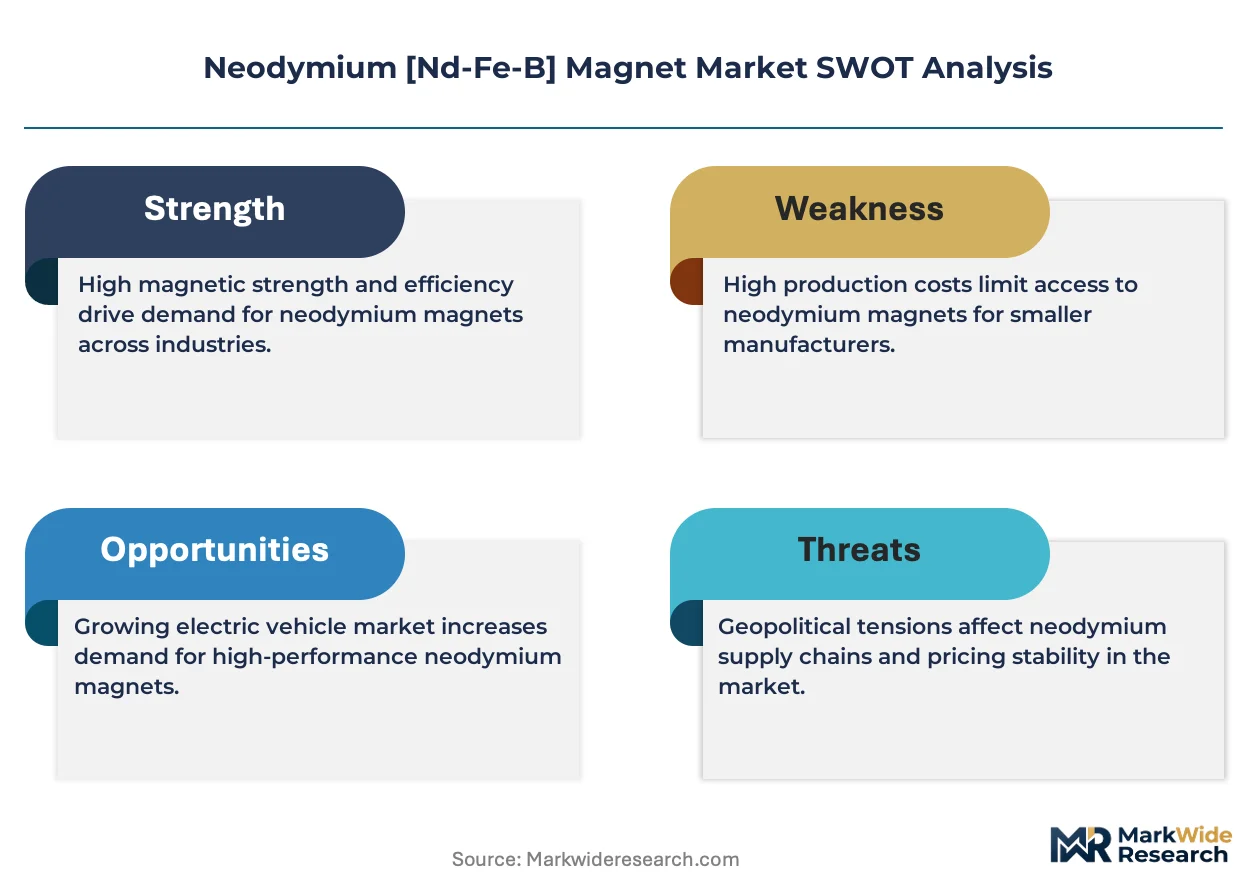
- Neodymium price volatility:Spot market dysprosium and terbium pricing swings of 40-60% annually compress magnet fabricator margins.
- China supply concentration:85% of global rare earth oxide separation occurs in Chinese state-controlled facilities, creating single-source vulnerability.
- Heavy rare earth dependency:High-temperature automotive grades require terbium and dysprosium additions that face export licensing delays.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for domestic EV manufacturing are attracting magnet assemblers to Gujarat and Tamil Nadu.
- Wind turbine direct-drive generators:10+ MW offshore turbines are adopting Nd-Fe-B excitation instead of geared doubly-fed induction systems.
- EU Critical Raw Materials Act:Mandatory recycling content quotas and strategic stockpile mandates are funding European rare earth magnet recycling infrastructure.
Industry Challenges
- Magnet alloy metallurgist scarcity:Powder compaction and grain boundary diffusion expertise concentrates in aging workforces at Japanese and Chinese producers.
- REACH substance disclosure:Full supply chain cobalt and heavy rare earth provenance documentation extends European customer onboarding by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neodymium [Nd-Fe-B] Magnet Market |
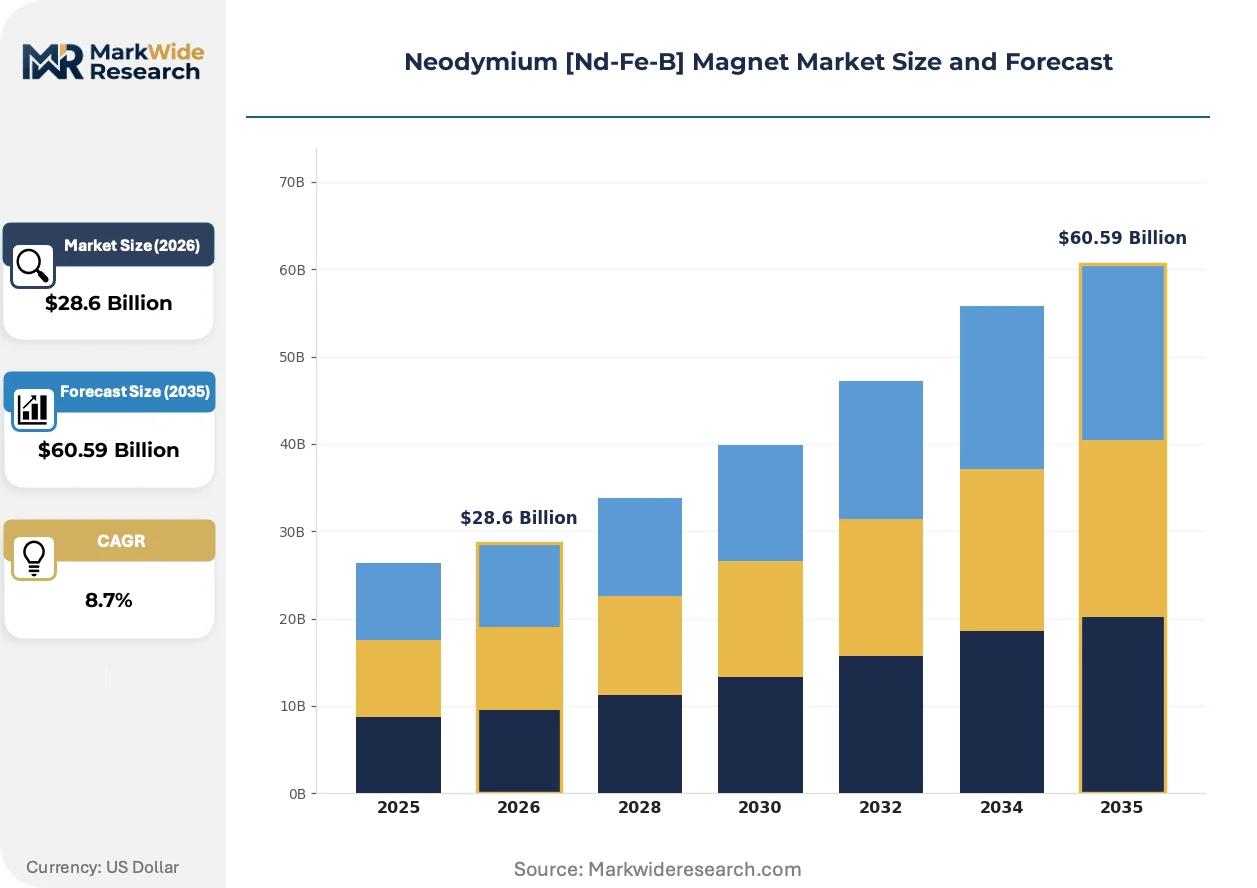
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bonded Magnets, Sintered Magnets, Injection Molding Magnets, Metallic Magnets Application: Consumer Electronics, Automotive, Renewable Energy, Industrial Equipment End User: Manufacturers, OEMs, Research Institutions, Hobbyists Distribution Channel: Online Stores, Distributors, Wholesale Suppliers, Retail Outlets |
| Companies Covered | Proterial, MP Materials, Arnold Magnetic Technologies, Electron Energy Corporation, Integrated Magnetics, Shin-Etsu Chemical, VACUUMSCHMELZE, K&J Magnetics, TDK Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neodymium [Nd-Fe-B] Magnet Market Strategic Shifts
Magnet manufacturing is splitting between high-performance sintered grades for automotive traction and cost-optimized bonded formulations for auxiliary motors, with recycling technology bridging both streams.
Grain boundary diffusion (GBD) technology is modularizing magnet design by enabling heavy rare earth concentration at grain surfaces rather than uniform alloying. Automotive motor designers at European OEMs are adopting GBD-enhanced magnets to reduce terbium consumption by 30-50% while maintaining 180°C operating limits. This diffusion process is modularizing supply chains, allowing magnet fabricators to source standard Nd-Fe-B substrates and apply heavy rare earth coatings in-house.
REACH substance restrictions are forcing magnet importers to document full rare earth provenance through supply chain due diligence. ECHA's SCIP database mandates disclosure of neodymium and dysprosium in automotive components exceeding 0.1% concentration. European tier-one motor suppliers are responding by qualifying Malaysian and Australian rare earth feedstocks to reduce China-origin dependency in compliance filings.
Automotive OEMs are compressing magnet qualification cycles from 36 months to 18 months to match EV platform launch velocities. Tier-one motor suppliers are disintermediating spot-market traders and signing direct offtake agreements with magnet fabricators holding MIIT-allocated rare earth quotas. This concentration is most visible in Germany, where BMW and Volkswagen have consolidated magnet procurement through single-source contracts with Japanese and Chinese producers holding captive separation capacity.
Neodymium [Nd-Fe-B] Magnet Market Segmentation
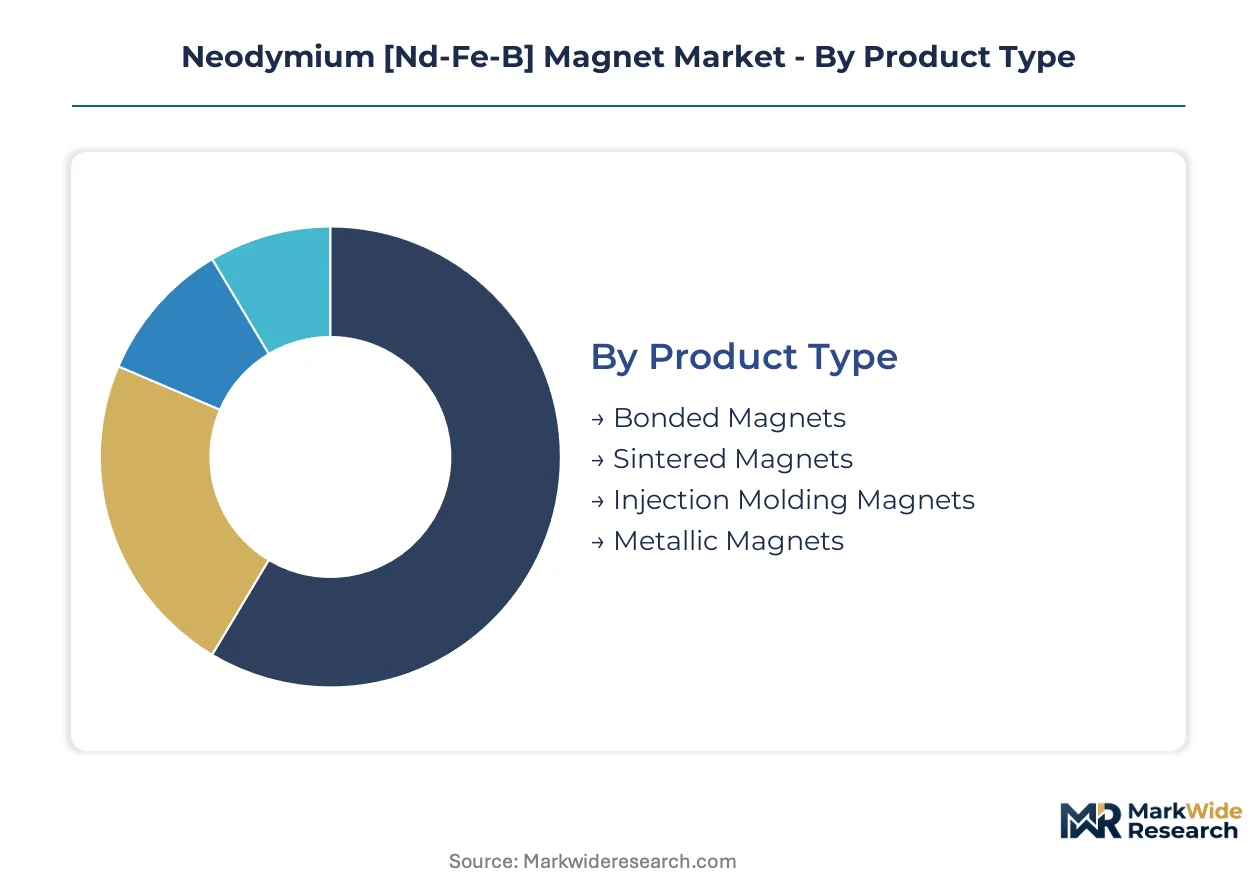
Neodymium magnet procurement splits along performance-grade boundaries, with automotive traction motors demanding sintered formulations while consumer electronics tolerates bonded alternatives. Specification-driven segmentation dictates pricing power, supply chain length, and heavy rare earth exposure across each tier.
Product Type:
Magnetic performance and thermal tolerance separate the product hierarchy, with manufacturing process complexity determining cost structure and end-use eligibility.
- Sintered Magnets:Powder metallurgy compaction followed by high-temperature sintering produces Nd₂Fe₁₄B tetragonal crystals exceeding 50 MGOe energy product. Automotive OEMs in Germany and Japan specify these grades for 800V traction motors where torque density requirements exclude all alternatives.
- Bonded Magnets:Polymer-bonded Nd-Fe-B powder enables complex geometries through compression or injection molding, sacrificing 30-40% magnetic strength for dimensional flexibility. Chinese consumer electronics assemblers in Shenzhen and Dongguan dominate procurement volumes for smartphone vibration motors and laptop hinge assemblies.
- Injection Molding Magnets:Thermoplastic bonding allows net-shape manufacturing with tolerances reaching ±0.05mm for miniature sensor applications. Medical device manufacturers specify these for implantable drug delivery systems where biocompatible encapsulation is mandatory.
- Metallic Magnets:Cast and wrought alloys retain coercivity above 200°C without heavy rare earth additions, serving industrial servo motors in steel mills and oil drilling equipment where thermal cycling resistance outweighs peak flux density.
Sintered magnets lead on scale; bonded magnets lead on momentum.
Application:
End-use concentration determines rare earth procurement strategy, with volume buyers securing MIIT-allocated quotas and spot-market exposure concentrated in fragmented segments.
- Automotive:Traction motor and steering assist applications consume high-coercivity grades with dysprosium and terbium additions. European OEMs have consolidated procurement through direct offtake agreements with Japanese and Chinese producers holding captive separation capacity.
- Consumer Electronics:Miniature speakers, hard disk drives, and vibration motors utilize bonded and sintered grades in sub-gram quantities. Assembly in Vietnam and Malaysia is displacing Chinese manufacturing for tariff-sensitive US-bound products.
- Renewable Energy:Direct-drive wind turbine generators above 5MW rating specify large-block sintered magnets with grain boundary diffusion enhancement. Offshore installations in the North Sea and Taiwan Strait are expanding most quickly.
- Industrial Equipment:Servo motors, magnetic separators, and lifting systems employ standard grades with less stringent temperature coefficients. Replacement demand cycles through distributors rather than direct OEM contracts.
Automotive commands pricing power; renewable energy shows steepest expansion trajectory.
End User:
Procurement sophistication varies sharply across buyer categories, with volume concentration enabling backward integration and fragmented demand accepting distributor markups.
- OEMs:Automotive and wind turbine original equipment manufacturers negotiate multi-year supply agreements with MIIT-quota holders. BMW and Volkswagen have compressed supplier bases to single-source contracts with captive rare earth processors.
- Manufacturers:Tier-two motor and component fabricators purchase through authorized distributors with 8-14 week lead times. REACH compliance documentation requirements from ECHA extend European onboarding cycles substantially.
- Research Institutions:University and national laboratory procurement operates through small-batch specialty suppliers serving prototyping and materials science programs.
- Hobbyists:Retail and online channels serve maker communities with standardized N35-N52 grade discs and blocks, priced by magnetic energy product tier.
OEMs lead on contract scale; manufacturers lead on transaction velocity.
Distribution Channel:
Channel selection reflects order size, technical support requirements, and geographic proximity to magnet fabrication clusters.
- Distributors:Authorized regional distributors maintain bonded inventory for automotive tier-one suppliers requiring JIT delivery to motor assembly plants. VACUUMSCHMELZE and Shin-Etsu channel European demand through Frankfurt and Amsterdam logistics hubs.
- Wholesale Suppliers:Volume buyers of standard grades access Baotou and Ningbo producers through bulk procurement offices, bypassing distributor margins on container-quantity orders.
- Online Stores:Alibaba and specialty magnet retailers serve prototype builders and maintenance-repair-operations demand with catalog-specified grades and 48-hour fulfillment.
- Retail Outlets:Physical hobby and electronics stores stock consumer-grade products for immediate pickup, representing minimal revenue concentration.
Distributors lead on value capture; wholesale suppliers lead on volume throughput.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands rare earth separation capacity while Germany consolidates magnet procurement through direct automotive OEM contracts, creating divergent sourcing models across major demand centers.
China
MIIT production quotas govern feedstock allocation for Nd-Fe-B magnet fabrication serving domestic EV manufacturers. Dual carbon goals accelerate capacity expansion in Inner Mongolia processing clusters. Baotou's integrated rare earth separation and alloying infrastructure reduces transit costs for magnet producers supplying BYD and CATL supply chains.
Germany
BMW and Volkswagen have compressed magnet supplier bases to single-source contracts for 800V traction motor programs. REACH substance disclosure requirements through ECHA extend onboarding cycles for non-European feedstock sources. Frankfurt logistics hubs channel Shin-Etsu and VACUUMSCHMELZE distribution to motor assembly plants in Bavaria and Baden-Württemberg.
Japan
METI strategic stockpile mandates secure heavy rare earth reserves for high-coercivity automotive grades. Grain boundary diffusion expertise concentrates in aging workforces at established producers. Nagoya and Osaka industrial corridors host precision magnet fabrication for Toyota and Honda electric drivetrain programs.
United States
IRA domestic content bonuses incentivize magnet assembly reshoring for qualifying EV tax credits. MP Materials operates the only integrated rare earth mine-to-magnet facility outside China. California and Texas processing investments aim to reduce dependency on Chinese state-controlled separation capacity.
India
PLI scheme production-linked incentives attract magnet assemblers to Gujarat and Tamil Nadu EV manufacturing corridors. BIS standards compliance requirements shape import specifications for automotive-grade products. Chennai and Ahmedabad industrial zones concentrate motor fabrication for domestic two-wheeler and passenger vehicle electrification.
Neodymium [Nd-Fe-B] Magnet Market Competitive Environment
Chinese producers anchor volume-tier supply through MIIT-allocated quota holders; Japanese and European specialists hold premium-grade positions for automotive qualification programs. Market structure consolidates around three archetypes: integrated rare earth-to-magnet operators, sintered-grade specialists with captive separation, and bonded-magnet fabricators serving consumer electronics. Dominant competitive moves include backward integration into rare earth mining and multi-year direct offtake agreements with automotive OEMs.
Among integrated operators, Proterial exemplifies mine-to-magnet supply chain control. MP Materials represents North American reshoring efforts through domestic separation and alloying investments. Shin-Etsu Chemical occupies a position as a volume-scale sintered magnet supplier holding Japanese and European automotive qualifications.
| Leading Market Players |
|---|
| Proterial |
| MP Materials |
| Arnold Magnetic Technologies |
| Electron Energy Corporation |
| Integrated Magnetics |
| Shin-Etsu Chemical |
| VACUUMSCHMELZE |
| K&J Magnetics |
| TDK Corporation |
| Others |
Value Chain & Pricing Dynamics
Grain boundary diffusion technology is displacing conventional heavy rare earth alloying, simultaneously compressing terbium and dysprosium consumption per magnet and shifting cost advantage toward fabricators with in-house diffusion capability rather than uniform-alloy substrate suppliers.
Pricing Analysis
Capacity additions in Inner Mongolia are reshaping price floors for standard Nd-Fe-B substrates as Baotou's integrated separation-alloying clusters reduce feedstock transit costs. Contract-based long-term offtake agreements dominate automotive procurement, with price differentiation resting on MIIT quota verification and grain boundary diffusion certification. Cost compression in bonded magnet tiers is intensifying because Vietnamese and Malaysian assembly plants compete on labor arbitrage for consumer electronics demand. Tier-two motor manufacturers exhibit highest price sensitivity due to spot-market rare earth exposure, while OEMs with captive separation contracts show lowest sensitivity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from BMW, Volkswagen, and Toyota, bypassing distributor tiers for sintered automotive grades. Geographic supply concentration centers on China, Japan, and Germany, with rare earth oxide separation overwhelmingly anchored in Chinese state-controlled facilities. Magnet fabrication draws from neodymium-praseodymium alloy, dysprosium-terbium heavy rare earth additions, and cobalt-free grain boundary compositions. Single-source vulnerability pervades the chain because 85% of global rare earth separation occurs in Chinese MIIT-governed facilities, creating tariff and export licensing exposure. Distribution runs through authorized regional hubs in Frankfurt, Amsterdam, and Nagoya for just-in-time motor assembly feeds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Nd-Fe-B magnet market compounds steadily as EV powertrain electrification locks in structural demand growth across automotive OEM procurement cycles.
For Market Incumbents: Lock in multi-year offtake agreements with MIIT-allocated quota holders before competitor consolidation exhausts available feedstock commitments. Deepen backward integration into rare earth separation or secure joint venture positions in Baotou processing clusters to defend against emerging Australian and Malaysian feedstock competitors. Prioritize grain boundary diffusion R&D investment to maintain cost advantage as heavy rare earth prices swing. For New Entrants and Emerging Players: Capture India PLI scheme incentives by establishing magnet assembly operations in Gujarat and Tamil Nadu corridors ahead of domestic EV manufacturing scale-up. Target wind turbine direct-drive generator segments in European North Sea markets where REACH compliance documentation requirements deter low-cost Chinese imports. Pursue qualification partnerships with European tier-one motor suppliers to bypass 18-month OEM onboarding cycles. For Investors and Strategic Acquirers: Valuations sit cheapest among bonded magnet fabricators serving consumer electronics, where pricing pressure from Vietnamese assembly competition has compressed multiples relative to automotive-grade sintered specialists. Long-term viability favors integrated mine-to-magnet operators with captive heavy rare earth access across the 5-10 year projection horizon. Watch MIIT export licensing delays for terbium and dysprosium as the inflection signal for Western rare earth reshoring economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Separation | Captive feedstock access secures MIIT quota allocation for automotive contract eligibility. |
| Grain Boundary Diffusion Technology Deployment | In-house heavy rare earth coating capability reduces terbium consumption by 30-50% for 180°C grades. |
| Long-term Supply Agreement with Automotive OEMs | Single-source contracts with BMW and Volkswagen compress competitor access to 800V traction motor programs. |
| Joint Venture in Inner Mongolia Processing Cluster | Baotou integration lowers transit costs and aligns with China's dual carbon capacity expansion mandates. |
| REACH Compliance Documentation Investment | ECHA SCIP database readiness accelerates European tier-one supplier onboarding by 8-14 months. |
Study Parameters
Direct dialogue with magnet fabrication plant managers, automotive OEM procurement directors, rare earth separation engineers, and REACH compliance officers grounded qualitative findings in operational reality. Secondary validation drew from MIIT production quota announcements, ECHA substance restriction updates, SEC filings of listed rare earth operators, and customs trade data for neodymium alloy flows. Bottom-up and top-down triangulation cross-checked magnet volume estimates against EV production forecasts and wind turbine installation pipelines.
Bottom-up modeling aggregated segment-level demand from automotive traction motor specifications, consumer electronics bill-of-materials, and renewable energy generator ratings across the projection horizon. Top-down constraints applied GDP-industrial production elasticities and rare earth mining capacity ceilings. Segmentation dimensions included product type (sintered, bonded, injection-molded, metallic), application (automotive, consumer electronics, renewable energy, industrial), and performance grade coercivity tiers. CAGRs derived from fitted growth curves against historical Nd-Fe-B shipment data and EV penetration scenarios.
Underlying measurement precision varies by segment; automotive OEM contract volumes carry tighter precision than hobbyist retail channel estimates due to disclosure requirements. Forecasts reflect assumptions regarding MIIT quota continuity, heavy rare earth export licensing timeliness, and grain boundary diffusion adoption curves in European automotive programs. Periodic stress-testing of base assumptions is recommended against regulatory fragmentation between Chinese export controls and Western circular-economy mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
Japan Neodymium Iron Boron Magnet Market
Magnetic Materials
Copper Magnet Wire Market
Magnetic Materials
Global Soft Magnetic Materials Market
Magnetic Materials
Plastic Bonded Magnet Market
Magnetic Materials
Global Neodymium Magnet Market
Magnetic Materials
Europe Copper Magnetic Wire Market
Magnetic Materials
Global Soft Magnetic Alloys Market
Magnetic Materials
Magnetorheological Fluid Market
Magnetic Materials
Nanocrystalline Soft Magnetic Material Market
Magnetic Materials
Magnetic Material Magnetization and Testing Equipment Market
Magnetic Materials
Reduced Iron Powder Market
Magnetic Materials
North America Magnet Market
Magnetic Materials
Middle East and Africa Magnet Wire Market
Magnetic Materials
Magnet Wire Market
Magnetic Materials
Amorphous Soft Magnetic Materials Market
Magnetic Materials
Sintered Soft Magnetic Material Market