
 Carbonyl Iron Powder Market | 2026-2036
Carbonyl Iron Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Carbonyl Iron Powder Market Analysis
Direct sales channels for specialty metal powders is rewriting how carbonyl iron powder reaches end users, with producers bypassing traditional traders to secure long-term supply agreements. BASF leverages its integrated chemical production network to control feedstock quality from iron pentacarbonyl through finished powder. Höganäs AB anchors its position through deep relationships with European automotive and powder metallurgy customers. JFE Steel Corporation competes on manufacturing scale, operating dedicated carbonyl iron facilities that serve Asian electronics and steel markets.
Carbonyl iron powder consists of highly pure iron particles produced through thermal decomposition of iron pentacarbonyl, typically achieving purity levels above 99.5% with particle sizes ranging from 1 to 10 micrometers and distinctive onion-skin layered morphology. The material serves primarily as a core component in electromagnetic interference shielding, radio-frequency absorption, and precision powder metallurgy applications where high permeability and consistent magnetic properties prove essential. Micronized powder dominates volume shipments due to its ubiquity in EMI suppression coatings and ferrite manufacturing, while coated powder commands premium positioning through enhanced oxidation resistance demanded by aerospace specifications. Granulated powder sustains growth in steel alloying applications where flowability and bulk density reduce handling losses. Flaked powder occupies narrower specialty niches in magnetic fluid seals and targeted absorber formulations.
REACH registration requirements in Europe and China's GB standards under SAMR oversight constrain import access and mandate full substance documentation for carbonyl iron powder formulations. The U.S. EPA and OSHA frameworks govern workplace exposure limits and environmental release reporting for iron pentacarbonyl precursor handling, elevating compliance costs for North American production. Stakeholders must monitor evolving EU F-Gas Regulation linkages to industrial gas processes and track China's dual carbon goals for energy-intensive thermal decomposition operations. Forward decisions hinge on securing qualified precursor supply and validating powder grades against tightening electromagnetic compatibility certifications across multiple jurisdictions.
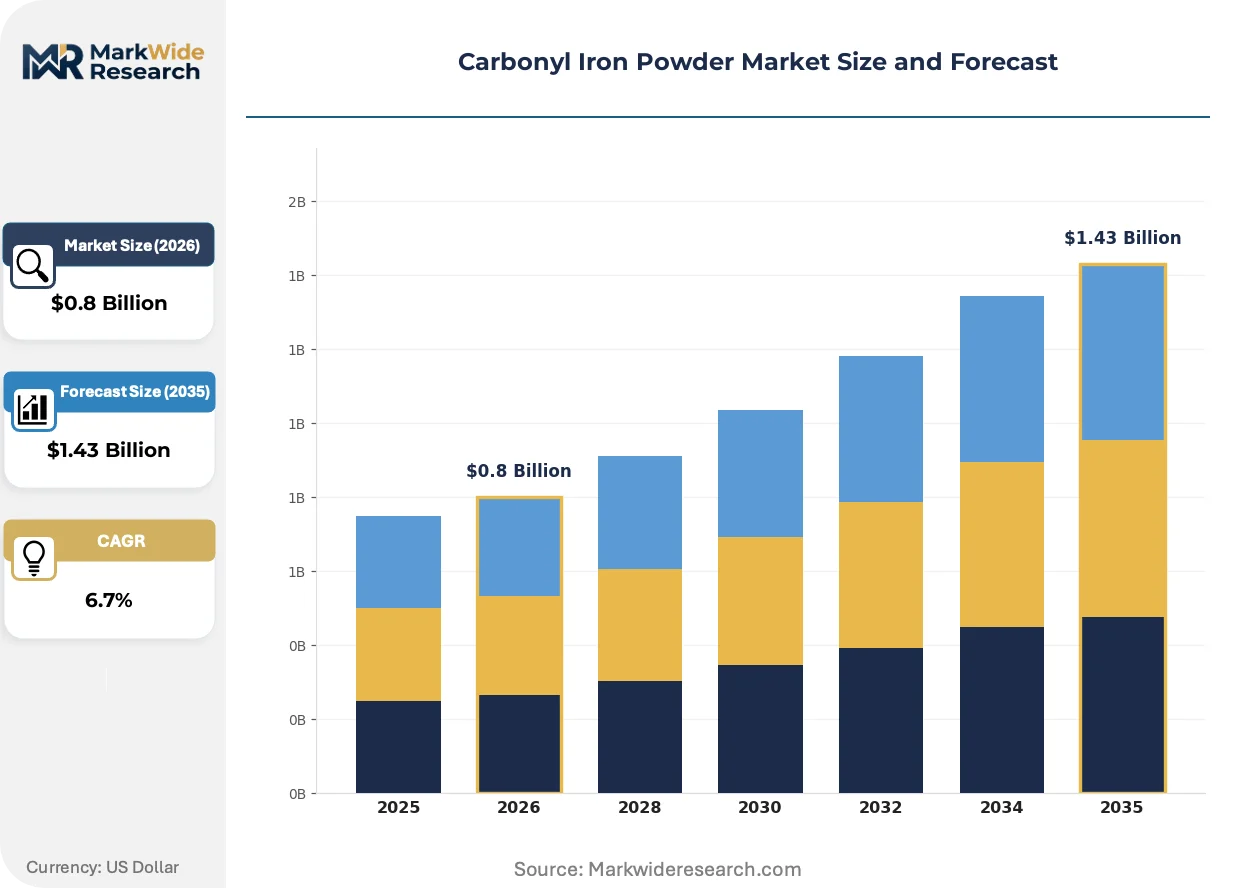
Market Dynamics
Electronics manufacturers in Germany and China are compressing supplier margins through consolidated procurement of high-purity carbonyl iron powder for electromagnetic shielding applications, forcing producers to demonstrate traceable compliance across REACH and GB standards simultaneously.
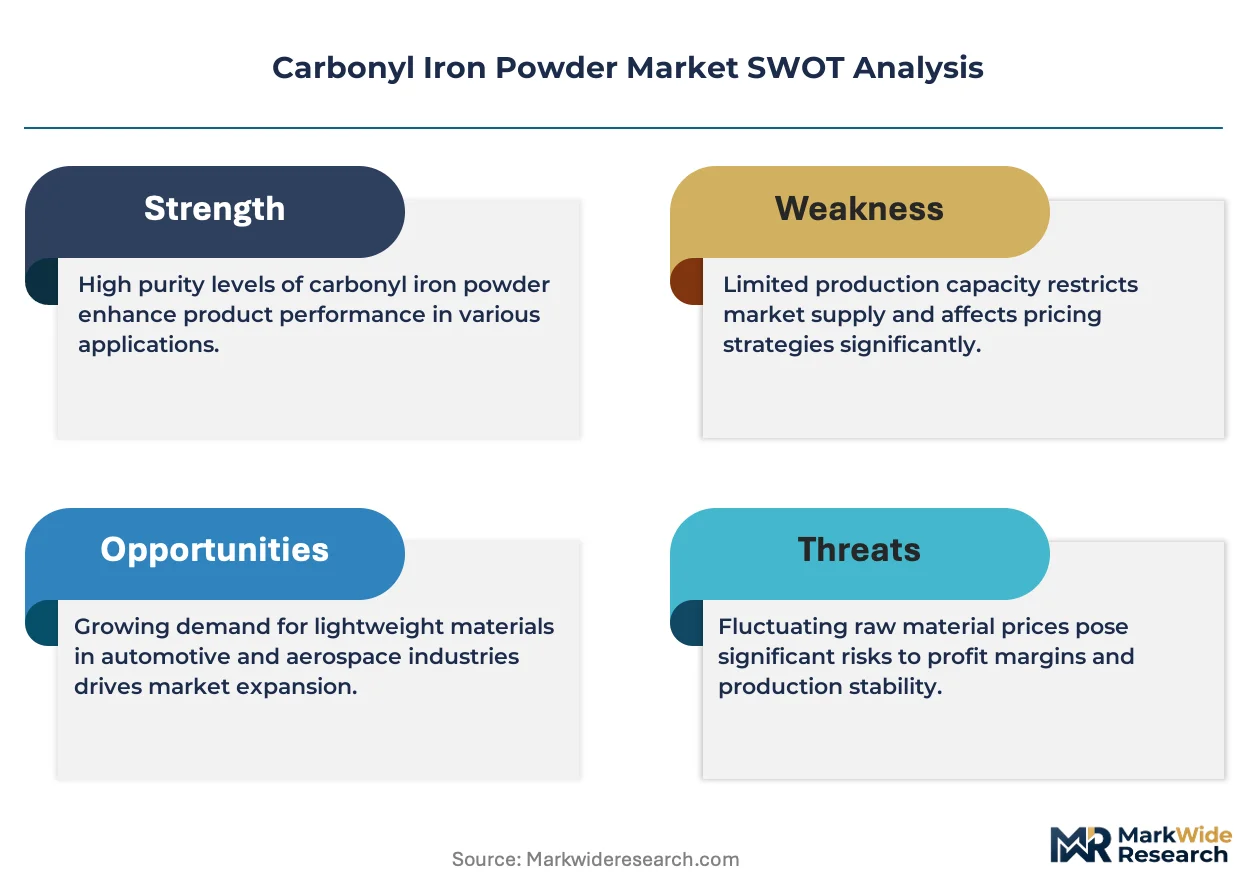
Growth Catalysts
- EMI suppression mandates:FCC and CE marking requirements for electromagnetic compatibility in automotive electronics and 5G infrastructure are expanding addressable demand for high-permeability core materials.
- China:SAMR's evolving GB standards under dual carbon goals are accelerating domestic substitution of imported specialty powders in precision powder metallurgy applications.
- Thermal decomposition efficiency gains:Advanced reactor designs are reducing energy intensity per kilogram of iron pentacarbonyl processed, improving unit economics for micronized powder output.
Market Restraints
- Iron pentacarbonyl supply concentration:Precursor production clusters in select industrial zones create vulnerability to feedstock disruption and price volatility.
- REACH documentation burden:Full substance registration requirements for imported formulations impose fixed compliance costs that disadvantage smaller volume entrants.
- Ferrite composite substitution:Manganese-zinc and nickel-zinc ferrites are capturing share in lower-frequency absorption applications where permeability requirements moderate.
Strategic Opportunities
- India:PLI scheme incentives for domestic electronics manufacturing are creating qualified demand for EMI shielding materials in smartphone and telecom equipment production.
- Aerospace specification powders:Oxidation-resistant coated grades command premium positioning in satellite and avionics applications where outgassing limits apply.
- Direct long-term supply agreements:Producers are bypassing traditional distributor networks to secure multi-year contracts with German automotive tier-1 suppliers.
Industry Challenges
- Electromagnetic compatibility certification timelines:Validation against tightening IEC and customer-specific standards extends qualification cycles for new powder grades.
- Process safety expertise:Thermal decomposition operations require specialized handling of toxic iron pentacarbonyl feedstock, constraining workforce availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbonyl Iron Powder Market |
| Market Size in 2026 | $0.8 Billion |
| Market Size in 2035 | $1.43 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Micronized Powder, Granulated Powder, Flaked Powder, Coated Powder Application: Electromagnetic Devices, Steel Production, Chemical Catalysts, Magnetic Materials End User: Automotive Components, Electronics Manufacturers, Aerospace Industry, Construction Sector Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | BASF, Höganäs AB, JFE Steel Corporation, CNPC Powder, Jiangsu Tianyi Ultra-fine Metal Powder, Jinchuan Group, DAIDO STEEL, Sintez-CIP, Rio Tinto Metal Powders, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbonyl Iron Powder Market Emerging Trajectories
Carbonyl iron powder production is experiencing simultaneous pressure from energy transition mandates and precision manufacturing requirements, reshaping how producers configure thermal decomposition capacity and customer qualification protocols.
Sub-micron particle engineering is collapsing the performance gap between carbonyl iron and engineered ferrites in high-frequency absorber applications. Defense contractors and satellite manufacturers in the US and Europe are qualifying these grades for stealth and thermal management systems. The technology is collapsing traditional material selection hierarchies that previously reserved carbonyl iron for sub-GHz frequencies.
REACH registration deadlines under ECHA oversight are forcing reformulation transparency across European supply chains. Importers must now disclose full substance composition and impurity profiles, elevating documentation costs. Specialty powder distributors serving German automotive customers are responding by consolidating supplier panels to reduce audit burden.
Buyer consolidation among electronics contract manufacturers is compressing supplier negotiation cycles and unbundling technical service from material supply. Direct material qualification by Foxconn and BYD Electronics procurement teams is displacing traditional distributor-led specification support. This pattern is most visible in Shenzhen and Dongguan manufacturing clusters where volume concentration enables arm's-length purchasing terms.
Carbonyl Iron Powder Market Segmentation
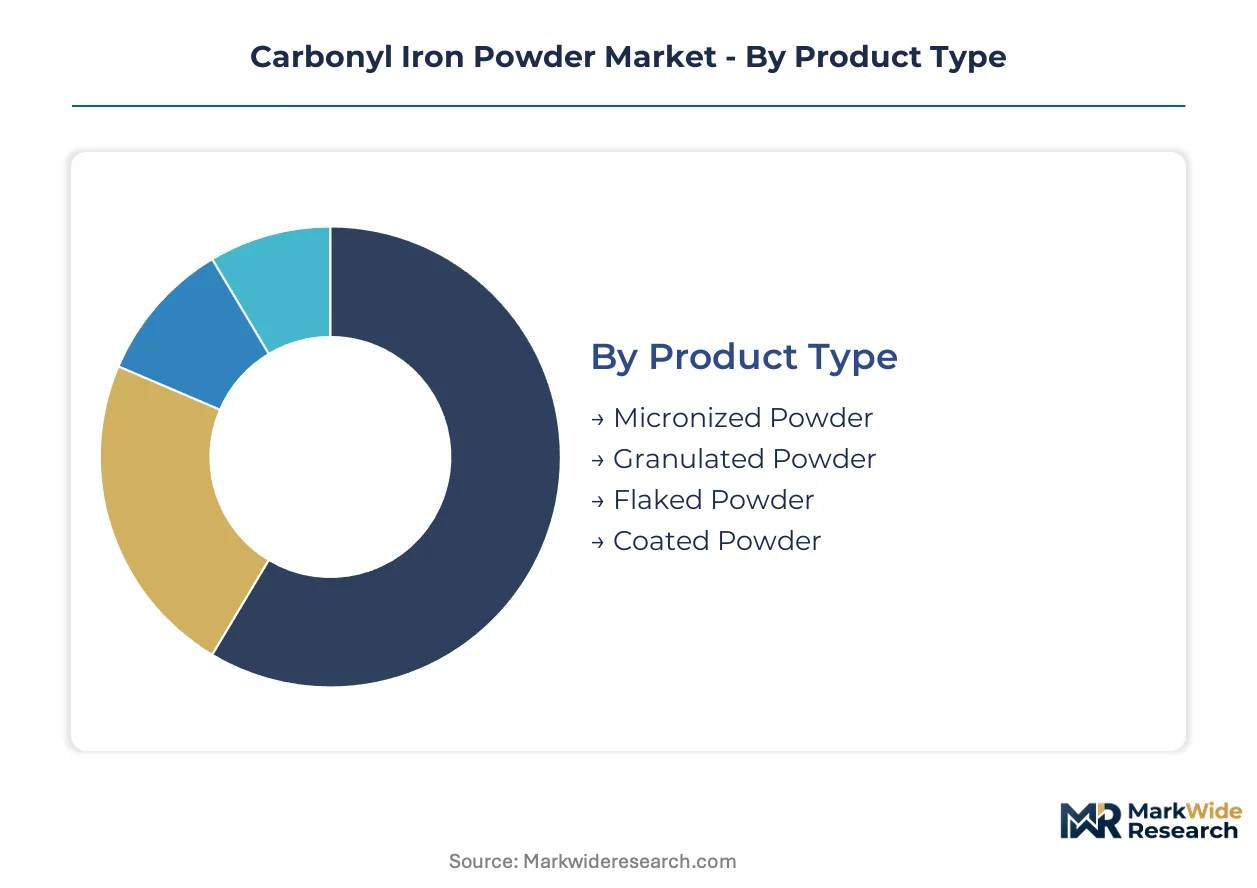
Carbonyl iron powder markets fragment across technical specifications, application requirements, and procurement patterns. Each segment carries distinct qualification cycles, margin structures, and supply chain configurations that reshape competitive positioning.
Product Type:
Micronized powder turns inventory fastest due to standardized EMI suppression grades, while coated powder sits longest awaiting aerospace qualification. Granulated and flaked varieties occupy intermediate velocity positions tied to steel mill offtake and specialty magnetic fluid orders.
- Micronized Powder:Particles range from 1 to 10 micrometers with onion-skin layered morphology and purity above 99.5%. Demand concentrates in German automotive supply chains and Shenzhen electronics clusters where FCC and CE marking compliance drives specification rigidity.
- Coated Powder:Surface-treated grades incorporate oxidation-resistant layers for extended thermal stability. Aerospace manufacturers in Germany and satellite builders in the US qualify these materials against outgassing limits, extending validation timelines but securing premium positioning.
- Granulated Powder:Engineered for flowability and bulk density in steel alloying applications. JFE Steel Corporation and European powder metallurgy customers favor this form for reduced handling losses during continuous casting operations.
- Flaked Powder:Flattened particle geometry serves magnetic fluid seals and targeted absorber formulations. Niche demand from defense contractors and precision instrument makers sustains limited production runs.
Micronized powder dominates installed base. Coated powder is where expansion concentrates.
Application:
Cost tier stratification separates commodity steel alloying from certified electromagnetic components. Steel production absorbs volume at compressed margins while electromagnetic devices capture value through technical service bundling.
- Electromagnetic Devices:High-permeability cores for EMI shielding, RF absorption, and inductor assemblies. Electronics manufacturers in Germany and China compress supplier margins through consolidated procurement of REACH and GB-compliant grades.
- Steel Production:Alloying additive for precision powder metallurgy and specialty steel grades. German automotive supply chains and East Asian steel mills drive offtake where thermal decomposition efficiency gains improve unit economics.
- Chemical Catalysts:Iron pentacarbonyl-derived purity supports Fischer-Tropsch and hydrogenation processes. Petrochemical clusters in China and Germany maintain steady demand despite ferrite substitution pressure in adjacent segments.
- Magnetic Materials:Ferrite manufacturing feedstock and bonded magnet formulations. Manganese-zinc and nickel-zinc ferrites are capturing share in lower-frequency absorption where permeability requirements moderate.
Steel production anchors volume throughput. Electromagnetic devices are climbing the fastest.
End User:
Customer type determines contract structure — automotive tier-1 suppliers demand multi-year direct agreements while construction buyers accept spot market terms.
- Electronics Manufacturers:Foxconn and BYD Electronics procurement teams in Shenzhen and Dongguan clusters are displacing distributor-led specification support. Direct material qualification compresses negotiation cycles and unbundles technical service from material supply.
- Automotive Components:German tier-1 suppliers anchor European demand through deep relationships with Höganäs AB and BASF. Long-term supply agreements bypass traditional trader networks to secure feedstock traceability.
- Aerospace Industry:Satellite and avionics applications impose oxidation resistance and outgassing compliance. US defense contractors and European satellite manufacturers qualify sub-micron grades for stealth and thermal management systems.
- Construction Sector:Magnetic shielding for infrastructure and industrial equipment represents price-sensitive demand. Wholesaler and distributor channels serve fragmented regional buyers with limited specification complexity.
Electronics manufacturers dominate order frequency. Aerospace is where margin expansion concentrates.
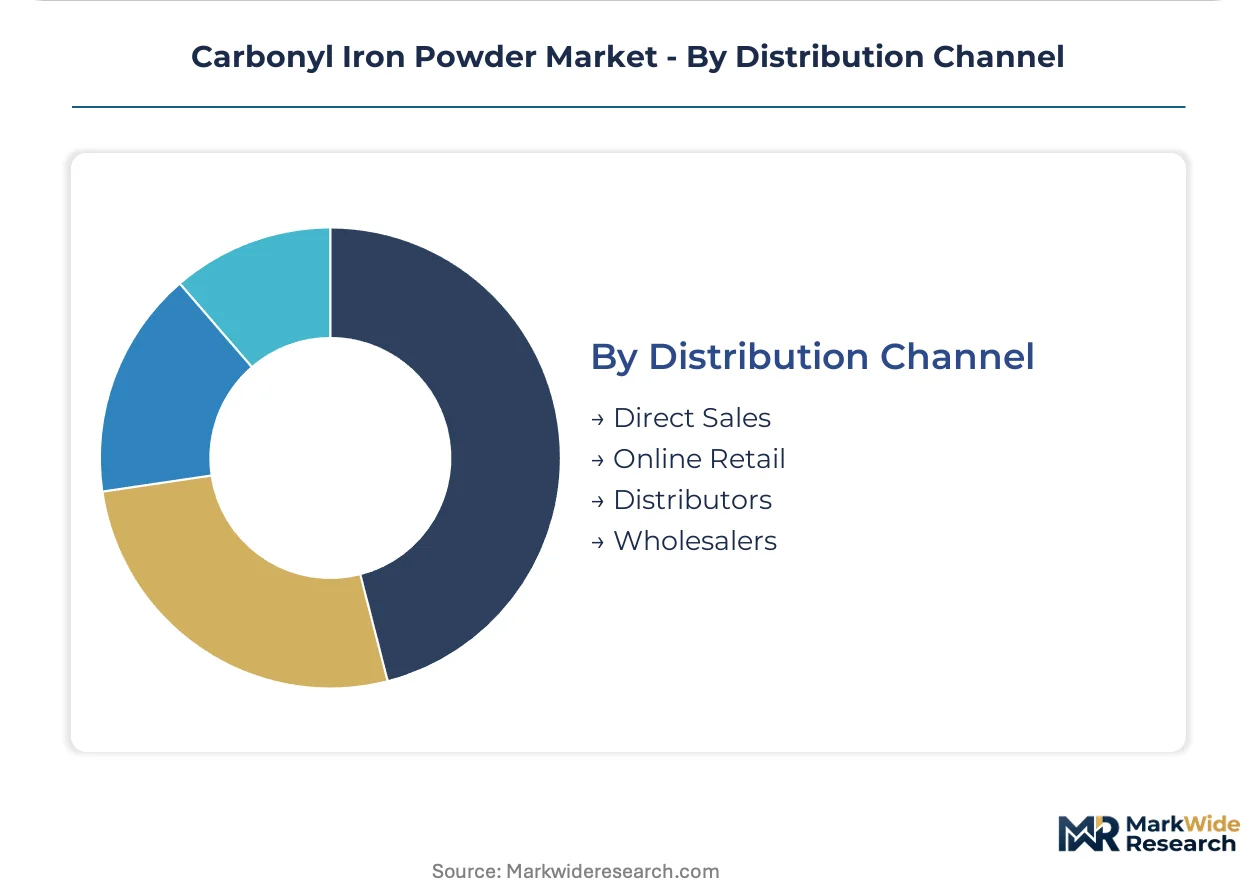
Distribution Channel:
Supply concentration varies sharply — direct sales lock in qualified automotive and electronics accounts while distributors serve residual construction and spot chemical markets.
- Direct Sales:Producers bypass traditional traders to secure multi-year agreements with German automotive tier-1 suppliers and Asian electronics contract manufacturers. BASF leverages integrated chemical production networks to control feedstock quality from iron pentacarbonyl through finished powder.
- Distributors:Specialty powder distributors serving German automotive customers consolidate supplier panels to reduce REACH audit burden. Regional stocking points support construction and smaller chemical catalyst accounts.
- Online Retail:Limited to standardized micronized grades for research quantities and maintenance-repair-operations procurement. Specification support remains minimal compared to direct technical service channels.
- Wholesalers:Bulk handling of granulated powder for steel mill customers where flowability and bulk density specifications are well-established. Price transparency compresses margins but sustains volume throughput.
Direct sales dominate qualified demand. Distributors are where residual volume concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive supply chains command premium pricing for REACH-compliant carbonyl iron powder grades, while Chinese electronics clusters extract volume discounts through consolidated procurement of GB-standard materials. This pricing-power asymmetry reshapes where producers allocate thermal decomposition capacity.
Germany
Automotive tier-1 suppliers in Baden-Württemberg and Bavaria anchor European demand for high-permeability electromagnetic core materials. ECHA's REACH registration requirements impose full substance documentation burdens on imported formulations, elevating compliance costs. Stuttgart and Munich manufacturing clusters drive direct long-term supply agreements that bypass traditional distributor networks.
China
Shenzhen and Dongguan electronics contract manufacturers compress supplier margins through arm's-length procurement of EMI shielding grades. SAMR's evolving GB standards under dual carbon goals accelerate domestic substitution of imported specialty powders. Yangtze River Delta steel mills sustain granulated powder offtake for continuous casting operations.
United States
Defense contractors and satellite manufacturers in California and Texas qualify sub-micron grades for stealth and thermal management applications. EPA and OSHA frameworks govern workplace exposure limits for iron pentacarbonyl precursor handling, elevating production costs. Aerospace clusters in Southern California drive premium pricing for oxidation-resistant coated specifications.
Japan
Precision powder metallurgy customers in Nagoya and Osaka sustain demand for consistent magnetic properties in ferrite manufacturing. METI oversight of industrial chemical processes shapes thermal decomposition facility permitting. Chubu region automotive suppliers maintain deep relationships with integrated steel producers for alloy-grade powder offtake.
India
PLI scheme incentives for domestic electronics manufacturing create qualified demand for EMI shielding materials in smartphone production. BIS certification requirements for imported metal powders constrain supplier access pending standard harmonization. Maharashtra and Karnataka manufacturing clusters attract contract manufacturers relocating from China.
Carbonyl Iron Powder Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream where precursor control and thermal decomposition expertise determine margin capture. The vendor base concentrates around integrated chemical producers, dedicated powder metallurgy houses, and steel-linked operations. Three archetypes dominate: backward-integrated chemical conglomerates controlling iron pentacarbonyl feedstock; specialized powder metallurgy firms with deep automotive relationships; and steel producers leveraging captive carbonyl iron capacity. Capacity expansion and direct supply agreement penetration represent the dominant competitive moves.
Among the integrated chemical producers, BASF anchors the European supply position through its Ludwigshafen production network. Höganäs AB exemplifies the specialized powder metallurgy archetype with concentrated relationships in German automotive supply chains. JFE Steel Corporation represents steel-linked operations with dedicated carbonyl iron facilities serving Asian electronics markets. These three occupy distinct competitive positions without direct overlap in customer qualification protocols or geographic account control.
| Leading Market Players |
|---|
| BASF |
| Höganäs AB |
| JFE Steel Corporation |
| CNPC Powder |
| Jiangsu Tianyi Ultra-fine Metal Powder |
| Jinchuan Group |
| DAIDO STEEL |
| Sintez-CIP |
| Rio Tinto Metal Powders |
| Others |
Supply Flow & Price Mechanics
Iron pentacarbonyl production clusters in Germany and China concentrate precursor supply, anchoring margin capture downstream at specialized powder metallurgy houses and integrated chemical producers. This upstream geography directly shapes where pricing power accumulates across micronized and coated powder grades.
Pricing Analysis
Configured-to-order pricing for aerospace-grade coated powder commands substantial premiums over standard micronized grades for EMI suppression. Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered formulations from spot-market imports and unqualified research quantities. Price differentiation rests on certification grade and volume scale, with Foxconn procurement teams extracting discounts through consolidated offtake. Cost compression in standard grades is intensifying because buyer consolidation among electronics contract manufacturers compresses negotiation cycles.
Supply Chain Analysis
Export-control regimes governing dual-use magnetic materials constrain flows of sub-micron grades to defense contractors. Supply concentrates in Germany, China, and Japan, with thermal decomposition capacity tethered to iron pentacarbonyl feedstock from Ludwigshafen and Yangtze River Delta chemical parks. Raw material dependencies include iron pentacarbonyl precursor, high-purity carbon monoxide, and specialized reactor ceramics. Single-source vulnerability around qualified precursor supply creates structural risk. Distribution runs through direct long-term agreements for automotive and electronics accounts, with distributors serving residual construction markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ferrite composite substitution threatens carbonyl iron powder incumbents in lower-frequency absorption applications, forcing defensive positioning around high-permeability niches where engineered ferrites cannot match performance.
For Market Incumbents: Insulate core margins through backward integration into iron pentacarbonyl precursor production and accelerated qualification of sub-micron grades for satellite applications. BASF's Ludwigshafen network demonstrates how feedstock control secures supply continuity. Lock in multi-year direct agreements with German automotive tier-1 suppliers before distributor consolidation accelerates.
For New Entrants and Emerging Players: Establish a beachhead in India's PLI-supported electronics manufacturing corridor, where EMI shielding demand outpaces qualified domestic supply. Target Maharashtra and Karnataka clusters with BIS-pre-certified grades to bypass harmonization delays. Lead with technical service bundling that Foxconn and BYD Electronics procurement teams have displaced from incumbent distributors.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized powder metallurgy houses with deep automotive relationships and captive thermal decomposition expertise. Long-term viability hinges on differentiation from commodity steel-linked operations. Watch for SAMR acceleration of domestic substitution timelines as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | BASF's Ludwigshafen network controls iron pentacarbonyl quality from feedstock through finished powder. |
| Sub-micron Grade Qualification | Defense contractors in California and Texas validate grades for stealth applications beyond traditional frequency limits. |
| Direct Long-term Supply Agreements | Höganäs AB secures multi-year contracts with Baden-Württemberg automotive suppliers bypassing distributor networks. |
| India PLI Corridor Entry | Maharashtra and Karnataka clusters attract contract manufacturers relocating from China with qualified EMI material demand. |
| REACH Registration Consolidation | Specialty powder distributors reduce audit burden by consolidating supplier panels to ECHA-compliant producers. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interviews with thermal decomposition plant managers, procurement leads at German automotive tier-1 suppliers, EMI materials engineers at Shenzhen electronics clusters, and specialty powder distributors serving European aerospace accounts. Secondary validation drew from ECHA REACH registration databases, SAMR GB standard evolution notices, SEC filings of integrated chemical producers, and customs trade data for iron pentacarbonyl flows. Bottom-up capacity modeling and top-down demand triangulation were cross-referenced against EIA energy intensity benchmarks for thermal decomposition operations.
Calibration against historical price spreads between micronized and coated grades informed elasticity assumptions across the projection horizon. Segmentation dimensions modeled include product type tier, application end-use, end-user industry vertical, and distribution channel structure. CAGRs were derived from installed base erosion rates and substitution elasticity parameters. Forecast inputs incorporated SAMR dual carbon policy implementation pace and ECHA F-Gas Regulation linkage effects on industrial gas processes.
Sensitivities concentrate around iron pentacarbonyl supply disruption, REACH documentation burden escalation, and ferrite substitution acceleration in sub-GHz applications. Forecasts reflect assumptions about regulatory harmonization timelines and energy transition cost pass-through. Material shifts in SAMR domestic substitution mandates or ECHA substance restriction expansions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
Sintered Magnet Market
Magnetic Materials
Magnetic Alloys Market
Magnetic Materials
Global Iron Powder Market
Magnetic Materials
Japan Neodymium Iron Boron Magnet Market
Magnetic Materials
Amorphous Soft Magnetic Materials Market
Magnetic Materials
Global Soft Magnetic Alloys Market
Magnetic Materials
High Performance Magnet Market
Magnetic Materials
Global Non Grain-Oriented Electrical Steel Market
Magnetic Materials
Neodymium [Nd-Fe-B] Magnet Market
Magnetic Materials
Iron Oxide Market
Magnetic Materials
Cobalt Oxide Market
Magnetic Materials
Neodymium-Iron-Boron Magnet Market
Magnetic Materials
Global Permanent Magnet Market
Magnetic Materials
Soft Ferrite Core Market
Magnetic Materials
Gadolinium Market
Magnetic Materials
Flux Field Directional Material Market