
 Neodymium-Iron-Boron Magnet Market | 2026-2036
Neodymium-Iron-Boron Magnet Market Size, Share, and Industry Trends Forecast 2026-2036
Neodymium-Iron-Boron Magnet Market Intelligence
ISO/TS 16949 automotive quality certification is reorganizing supplier eligibility for NdFeB magnet vendors serving drivetrain programs. Hitachi Metals sustains integrated control from rare earth refining through finished magnet production in Japan. Ningbo Yunsheng leverages China's processing scale to dominate bonded magnet exports. VACUUMSCHMELZE specializes in thin-film and high-temperature grades for aerospace generators.
Neodymium-iron-boron magnets consist of an Nd2Fe14B tetragonal crystalline structure with typical energy products of 30-52 MGOe, produced through powder metallurgy sintering or polymer-bonded compression molding to deliver the strongest permanent magnetic field per unit volume commercially available. Sintered magnets occupy the highest value tier in automotive traction motors where operating temperatures exceed 150°C, while bonded magnets serve cost-sensitive sensor and consumer electronics applications with complex geometries. Motors applications command the largest volume pull from EV platforms, with generators expanding fastest in offshore wind turbine direct-drive architectures.
REACH restrictions on heavy metal content and RoHS substance limits shape material composition requirements for NdFeB magnets sold across Europe, while China's MIIT rare earth production quotas constrain upstream neodymium supply. The US Department of Commerce export controls on advanced magnet manufacturing equipment add licensing friction for new capacity builds. Stakeholders must monitor feedstock quota announcements and certification timelines to secure qualified supply positions ahead of automotive platform lock-ins.
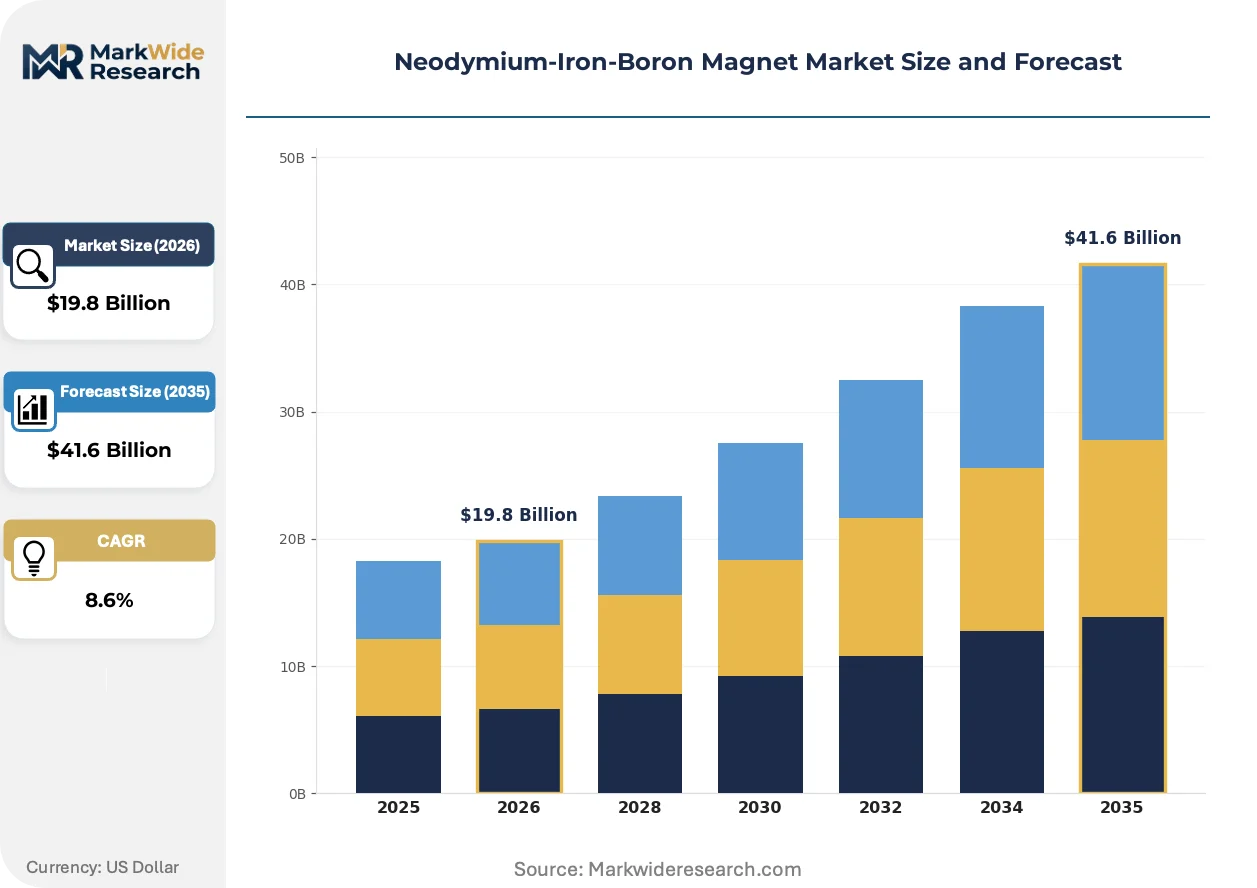
Market Dynamics
China's MIIT rare earth processing quotas are tightening feedstock flows into magnet fabrication clusters, forcing automotive OEMs to secure qualified supply positions before platform lock-ins crystallize.
Growth Catalysts
- Automotive electrification mandates:EU CO2 fleet targets and US IRA clean vehicle credits are accelerating permanent magnet procurement for EV traction motors.
- Offshore wind scale-up:Direct-drive generator architectures in North Sea and East Asian wind farms require high-temperature-grade NdFeB magnets.
- ISO/TS 16949 certification requirements:Automotive quality standards are filtering supplier eligibility, concentrating orders among qualified vendors.
Market Restraints
- Neodymium supply concentration:Over 80% of rare earth oxide refining occurs in Chinese processing facilities under quota control.
- Heavy rare earth dependency:Dysprosium and terbium additions for high-temperature grades face concentrated supply geography.
- REACH substance restrictions:ECHA scrutiny on heavy metal content creates compliance friction for European-bound magnet shipments.
Strategic Opportunities
- Recycling feedstock development:End-of-life magnet recovery from hard disk drives and industrial motors offers alternative neodymium sourcing.
- Thin-film deposition techniques:VACUUMSCHMELZE-style high-temperature coatings enable aerospace generator applications.
- India PLI scheme for advanced chemistry cells:Downstream battery and motor manufacturing incentives create magnet demand anchor points.
Industry Challenges
- ISO/TS 16949 certification timelines:Automotive qualification cycles span 18-24 months, delaying new supplier entry.
- US Department of Commerce export controls:Licensing requirements for advanced magnet manufacturing equipment constrain greenfield capacity builds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neodymium-Iron-Boron Magnet Market |
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $41.6 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bonded Magnets, Sintered Magnets, Composite Magnets, Extruded Magnets End User: Automotive, Aerospace, Electronics, Renewable Energy Application: Motors, Generators, Magnetic Separators, Sensors Shape: Disc, Block, Ring, Cylinder |
| Companies Covered | Shin-Etsu Chemical Co., Ltd., Hitachi Metals, Ltd., Ningbo Yunsheng High-Tech Magnetics Co., Ltd., TDK Corporation, VACUUMSCHMELZE GmbH & Co. KG, Magnequench International Inc., Arnold Magnetic Technologies, Sumitomo Corporation, Jingci Material Science Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neodymium-Iron-Boron Magnet Market Strategic Shifts & Innovations
Magnet performance requirements are diverging across temperature grades and corrosion resistance specifications as end-use applications fragment between automotive traction, wind generators, and precision sensors.
Grain boundary diffusion (GBD) technology is displacing conventional sintering for heavy rare earth conservation. Toyota and Hyundai Motor Group drivetrain engineers specify GBD-treated magnets for 180°C operating environments. This process is displacing traditional alloying methods that required higher dysprosium loading.
REACH Annex XVII restrictions on nickel release and RoHS substance limits are reshaping coating specifications for European-bound magnets. ECHA enforcement is pushing Japanese and Chinese suppliers toward epoxy and parylene barrier layers. Automotive sensor applications in Germany face the tightest compliance verification.
Buyer consolidation among tier-one automotive suppliers is compressing magnet procurement cycles. Bosch, Denso, and Nidec are consolidating supplier panels from 8-10 vendors to 3-4 qualified partners. Japan and South Korea exhibit the most pronounced supplier rationalization.
Neodymium-Iron-Boron Magnet Market Segmentation
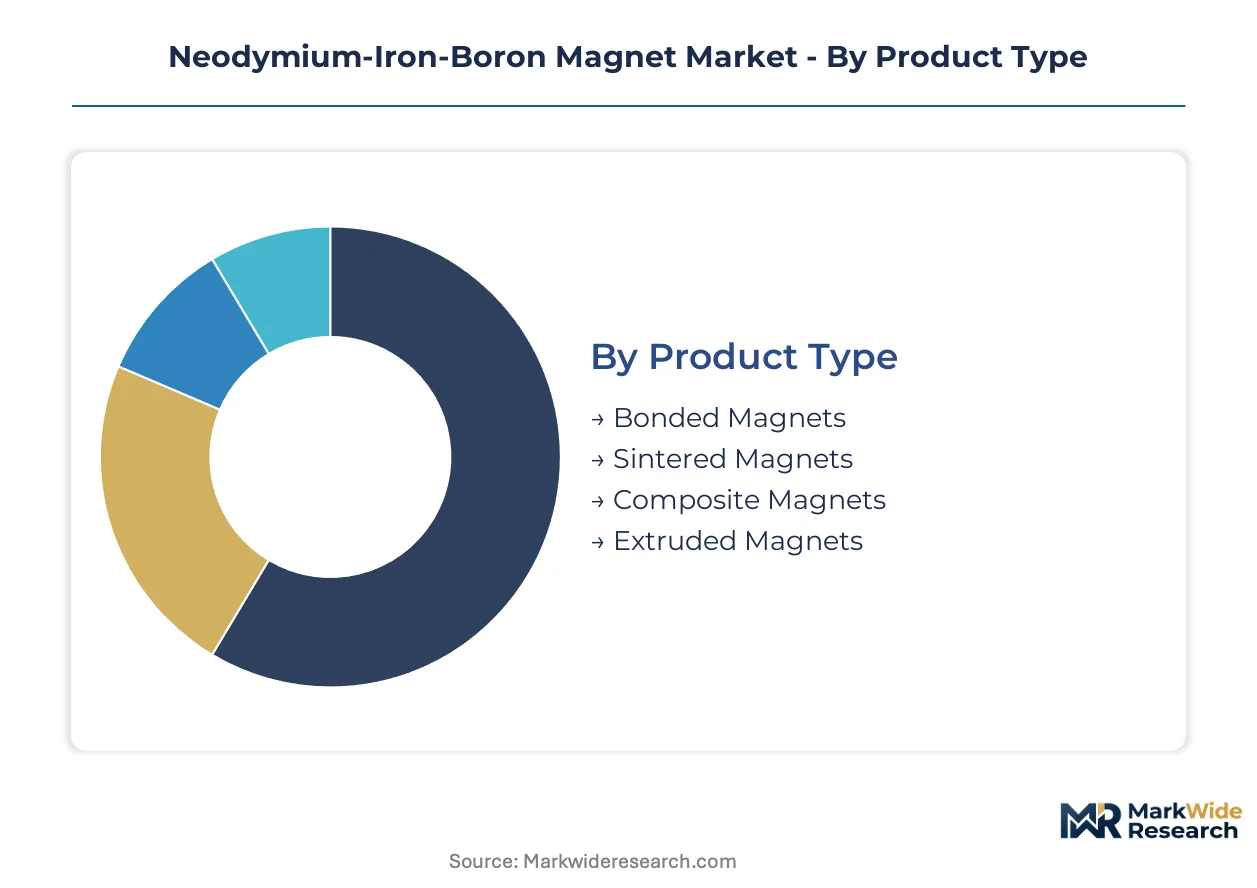
NdFeB magnet specifications diverge sharply across temperature tolerance, corrosion resistance, and dimensional precision requirements. Each segmentation axis reflects distinct margin structures and qualification barriers that reshape supplier competitiveness.
Product Type:
Sintered magnets command the deepest margin pools due to automotive traction motor qualification requirements and heavy rare earth alloying premiums.
- Sintered Magnets:Produced through powder metallurgy pressing and high-temperature sintering of Nd2Fe14B alloy, these deliver energy products of 30-52 MGOe with thermal stability up to 200°C. Automotive OEMs in Germany and Japan specify sintered grades for EV traction motors where ISO/TS 16949 certification gates supplier eligibility. Dysprosium and terbium additions for high-temperature performance concentrate value capture among integrated rare earth processors.
- Bonded Magnets:Polymer matrix compression molding enables complex geometries with dimensional tolerances of ±0.05mm, though energy products peak at 12 MGOe. Ningbo fabrication clusters serve cost-sensitive sensor applications in South Korean consumer electronics supply chains. The isotropic powder feedstock avoids heavy rare earth dependencies that constrain sintered supply.
- Composite Magnets:Hybrid structures combining NdFeB with ferrite or SmCo phases balance cost and performance in industrial automation actuators.
- Extruded Magnets:Continuous profile forming suits linear motor applications and magnetic conveyor systems with moderate field strength requirements.
The dominant share belongs to Sintered Magnets, while Bonded Magnets is closing the gap fastest.
End User:
Procurement scale and technical specification stringency concentrate value differently across customer categories, with automotive programs imposing the steepest qualification barriers.
- Automotive:Traction motor and steering assist applications demand 150-180°C operating grades with 20-year corrosion resistance. Toyota, Hyundai, and Bosch procurement panels consolidate orders among 3-4 qualified suppliers per region. ECHA REACH compliance and MIIT rare earth quotas jointly constrain qualified supply availability.
- Renewable Energy:Direct-drive wind generators in North Sea and East Asian offshore farms require segmented ring magnets with grain boundary diffusion treatment. Vestas and Siemens Gamesa specifications favor suppliers with captive heavy rare earth processing.
- Electronics:Hard disk drive voice coil motors and smartphone haptic actuators prioritize miniaturization and thin-film coating consistency.
- Aerospace:VACUUMSCHMELZE and specialized Japanese suppliers serve generator applications with extreme temperature cycling and radiation hardness requirements.
Automotive captures the largest volume allocation, though Renewable Energy is expanding most quickly.
Application:
Functional performance requirements and replacement cycle dynamics fragment the application landscape across rotating machinery and static field systems.
- Motors:Brushless DC and permanent magnet synchronous motor architectures dominate EV drivetrain and industrial servo applications. Operating temperature gradients from 80°C in HVAC compressors to 180°C in automotive traction systems drive grade stratification. Grain boundary diffusion technology is displacing conventional alloying for heavy rare earth conservation.
- Generators:Direct-drive offshore wind turbines eliminate gearbox maintenance through large-diameter ring magnet arrays. Rare earth supply concentration and ECHA substance scrutiny shape procurement risk assessments.
- Sensors:Position, speed, and current sensing applications in automotive and industrial automation prioritize dimensional precision and temperature coefficient stability.
- Magnetic Separators:Food processing and mining beneficiation operations utilize high-field gradient drum and belt configurations with epoxy-coated block magnets.
Motors holds the dominant position, while Generators shows the steepest expansion trajectory.
Shape:
Manufacturing process compatibility and magnetic circuit design constraints determine shape selection across motor topologies and sensor configurations.
- Block:Rectangular profiles suit linear motor assemblies and magnetic separator arrays with straightforward pole orientation requirements.
- Disc:Axially magnetized cylinders serve speaker drivers, magnetic couplings, and holding applications with planar field distribution needs.
- Ring:Radial and diametrical magnetization patterns enable voice coil motors, magnetic bearings, and sensor encoders with rotational symmetry.
- Cylinder:Rod and tube geometries fit solenoid-style actuators and probe-based measurement instruments.
Block shapes dominate industrial volume, while Ring configurations are gaining share fastest in precision motor applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clean vehicle tax credits under the US Inflation Reduction Act and EU CO2 fleet mandates are redirecting magnet procurement toward qualified supply chains. Automotive OEMs in Germany, Japan, and South Korea are accelerating platform lock-ins ahead of tightening rare earth quotas.
China
MIIT processing quotas constrain neodymium oxide flows into Ningbo and Ganzhou fabrication clusters. The dual carbon goals framework imposes emissions caps on sintering furnaces. Tianjin and Baotou rare earth refining complexes supply captive feedstock to vertically integrated magnet producers.
Japan
Hitachi Metals and TDK procurement panels specify grain boundary diffusion grades for 180°C automotive traction applications. METI supply chain resilience programs subsidize heavy rare earth stockpiling. Chiba and Aichi prefectures concentrate thin-film coating specialists serving aerospace generator programs.
Germany
Bosch and Siemens Gamesa procurement teams enforce REACH Annex XVII compliance on nickel release and RoHS substance limits. KBA automotive certification gates supplier eligibility for EV drivetrain programs. Bavaria and Baden-Württemberg host precision magnet machining clusters for industrial servo motors.
United States
Department of Commerce export controls on advanced magnet manufacturing equipment constrain greenfield capacity builds. IRA clean vehicle assembly requirements favor North American magnet sourcing for tax credit eligibility. California and Michigan anchor EV powertrain engineering centers specifying sintered grades.
South Korea
Hyundai Motor Group and LG Magna e-Powertrain consolidate supplier panels to 3-4 qualified vendors per platform. MFDS chemical substance registration creates compliance friction for imported magnet coatings. Busan-Ulsan industrial corridors concentrate bonded magnet fabrication for consumer electronics sensors.
Neodymium-Iron-Boron Magnet Market Key Industry Players
Player mix skews toward integrated rare earth processors and specialized coating specialists. Market structure concentrates among Japanese and Chinese fabricators with captive upstream control, while European and North American vendors occupy niche high-temperature and thin-film segments. Two strategic archetypes dominate: vertically integrated refiners-to-magnet producers, and technology specialists licensing grain boundary diffusion processes. Competitive moves center on capacity expansion in Southeast Asian tax-advantaged zones and strategic partnerships with automotive tier-one suppliers.
Within the integrated processor tier, Shin-Etsu Chemical Co., Ltd. and Hitachi Metals, Ltd. exemplify upstream-to-downstream control from rare earth refining through finished magnet production. Ningbo Yunsheng High-Tech Magnetics Co., Ltd. represents scale-driven bonded magnet fabrication serving cost-sensitive sensor applications. These three anchors illustrate the geographic bifurcation between Japanese quality-certification dominance and Chinese processing scale.
| Leading Market Players |
|---|
| Shin-Etsu Chemical Co., Ltd. |
| Hitachi Metals, Ltd. |
| Ningbo Yunsheng High-Tech Magnetics Co., Ltd. |
| TDK Corporation |
| VACUUMSCHMELZE GmbH & Co. KG |
| Magnequench International Inc. |
| Arnold Magnetic Technologies |
| Sumitomo Corporation |
| Jingci Material Science Co., Ltd. |
| Others |
Cost & Logistics Intelligence
ISO/TS 16949 automotive quality certification gates supplier eligibility while simultaneously stratifying price tiers across qualified and unqualified magnet vendors serving EV drivetrain programs.
Pricing Analysis
Certification level creates the primary spread between automotive-grade sintered magnets and industrial sensor grades. Three-tier pricing structure separates ISO/TS 16949-certified traction motor magnets from standard industrial grades and economy bonded variants. Cost compression in economy bonded tiers is intensifying because Ningbo fabrication clusters compete on volume scale. Automotive OEMs exhibit the lowest price sensitivity due to platform lock-in requirements, while consumer electronics sensor buyers drive hardest bargain negotiations.
Supply Chain Analysis
Strategic stockpiling of heavy rare earth oxides dominates inventory strategy among Japanese integrated producers facing MIIT quota uncertainty. Raw material supply draws from Chinese rare earth refining complexes, Malaysian light rare earth separation facilities, and Australian hard rock concentrate shipments. Dysprosium and terbium dependencies create single-source vulnerability concentrated in Chinese heavy rare earth processing. Distribution runs through tier-one automotive supplier consolidation panels and direct wind turbine OEM procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive electrification mandates are disrupting permanent magnet procurement patterns, with EU CO2 fleet targets and US IRA clean vehicle credits creating inflection demand for qualified supply positions.
For Market Incumbents: Consolidate supplier panel positions ahead of automotive platform lock-ins by securing captive heavy rare earth processing capacity and accelerating grain boundary diffusion technology adoption. Defend against emerging Chinese bonded magnet specialists by deepening ISO/TS 16949 certification coverage across Southeast Asian expansion zones.
For New Entrants and Emerging Players: Lead with recycling feedstock development targeting end-of-life hard disk drive recovery and industrial motor magnet harvesting as alternative neodymium sourcing. Penetrate the aerospace generator segment where VACUUMSCHMELZE-style thin-film coating expertise commands premium positioning and qualification barriers remain surmountable for specialized entrants.
For Investors and Strategic Acquirers: US Department of Commerce export controls on advanced magnet manufacturing equipment reshapes the acquisition landscape toward Southeast Asian tax-advantaged fabrication assets. Target integrated processors with captive rare earth refining through finished magnet production capability. Watch MIIT quota announcement timing as the critical signal for feedstock cost inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Grain Boundary Diffusion Technology Licensing | Toyota and Hyundai specifications are displacing conventional heavy rare earth alloying methods. |
| Heavy Rare Earth Stockpiling Programs | METI subsidies enable Japanese producers to buffer against MIIT quota volatility. |
| Southeast Asian Capacity Expansion | Tax-advantaged zones attract magnet fabrication serving IRA-compliant North American automotive demand. |
| End-of-Life Magnet Recovery Infrastructure | Hard disk drive and industrial motor harvesting offers alternative neodymium feedstock sourcing. |
| Thin-Film Coating Specialization | ECHA REACH nickel release restrictions push epoxy and parylene barrier layer adoption. |
Research Approach
The analysis maps sintered magnet, bonded magnet, and composite magnet sub-sectors, each validated through procurement directors at tier-one automotive suppliers, wind turbine OEM sourcing managers, rare earth processing executives, and aerospace generator program engineers. Primary interview findings cross-checked against customs trade data, SEC filings from listed magnet producers, MIIT quota announcements, and ECHA REACH substance restriction updates. Bottom-up segment sizing triangulated with top-down end-use demand modeling across EV traction motor, direct-drive wind generator, and precision sensor applications.
Consistency checks validated volume and value outputs against IHS Markit vehicle production databases, wind turbine installation tracking, and regional rare earth oxide trade flows. Segmentation dimensions modeled include magnet type, operating temperature grade, corrosion resistance specification, end-use industry, and regional production cluster. CAGRs derived from elasticity analysis linking automotive electrification penetration rates and wind energy capacity additions to magnet content per unit assumptions.
Underlying assumptions cover MIIT quota enforcement continuity, ISO/TS 16949 certification timeline stability, and ECHA substance restriction implementation pace, with deviation risk concentrated in rare earth export policy shifts and automotive platform specification changes. Revision becomes warranted when heavy rare earth oxide spot price volatility crosses threshold levels triggering substitution technology acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
North America Samarium Cobalt Magnets Market
Magnetic Materials
Global Soft Magnetic Materials Market
Magnetic Materials
Sintered Soft Magnetic Material Market
Magnetic Materials
North America Magnet Wire Market
Magnetic Materials
Sintered Magnet Market
Magnetic Materials
Nanocrystalline Soft Magnetic Material Market
Magnetic Materials
Global Bonded Magnet Market
Magnetic Materials
Magnet Market
Magnetic Materials
Samarium Cobalt Magnets Market
Magnetic Materials
Ferroboron Market
Magnetic Materials
Global Non-Oriented Electrical Steel Market
Magnetic Materials
Magnetic Plastics Market
Magnetic Materials
Magnetite Nanoparticles Market
Magnetic Materials
Ferrite Magnet Market
Magnetic Materials
Magnetorheological Fluid Market
Magnetic Materials
Magnetic Materials Market